
 India Collagen Market | 2026-2036
India Collagen Market Size, Share, and Industry Trends Forecast 2026-2036
India Collagen Market Foresight
Marine collagen sourced from fish scales and skin is recalibrating product economics across India's collagen landscape by offering superior bioavailability at competitive extraction costs. Titan Biotech Ltd leverages its bovine-derived collagen expertise to dominate pharmaceutical-grade supply chains. Nitta Gelatin India Limited anchors the food and beverage segment through its gelatin manufacturing scale. Athos Collagen Pvt. Ltd. specializes in porcine and marine variants for cosmetic applications.
Collagen is a fibrous structural protein comprising glycine, proline, and hydroxyproline amino acids, extracted through acid or enzymatic hydrolysis of animal connective tissues, and functions primarily as a gelling, stabilizing, and texturizing agent across food, pharmaceutical, and personal care formulations. Hydrolyzed collagen leads the product type landscape due to its solubility and absorption profile in nutraceutical applications. Marine collagen represents the fastest-growing source category, driven by halal-certification advantages and sustainability positioning in export markets. Nutritional supplements command the highest margin pool within end-use segments as direct-to-consumer brands proliferate.
The Food Safety and Standards Authority of India (FSSAI) governs collagen labeling and health claims, while the Central Drugs Standard Control Organization (CDSCO) regulates pharmaceutical-grade collagen used in wound care and surgical applications, collectively elevating compliance costs for new entrants. Bureau of Indian Standards (BIS) certification requirements for collagen peptides used in food products further shape market access dynamics. Stakeholders must monitor evolving FSSAI standards on novel collagen sources and evaluate backward integration into raw material supply chains to secure cost advantages as demand intensifies.
Market Dynamics
FSSAI's tightened labeling mandates for collagen-based nutritional supplements are forcing manufacturers toward cleaner formulations and transparent sourcing disclosures, compressing margins for non-compliant players while rewarding early adopters of certification-heavy supply chains.
Growth Catalysts
- Halal-certified marine collagen:Fish-scale extraction methods are unlocking export access to Middle Eastern and Southeast Asian markets where religious certification governs procurement decisions.
- Protein-enriched diet shift:Urban Indian consumers in Maharashtra and Gujarat are integrating collagen peptides into daily nutrition regimens, expanding the addressable base beyond clinical applications.
- PLI scheme incentives:India's production-linked incentive framework for pharmaceuticals is subsidizing capital equipment for collagen peptide manufacturing, lowering entry barriers for domestic producers.
Market Restraints
- Bovine raw material volatility:Tallow and hide prices fluctuate with monsoon-driven cattle availability, squeezing cost predictability for pharmaceutical-grade collagen producers.
- CDSCO compliance burden:Pharmaceutical-grade collagen for wound care applications faces extended approval timelines, delaying product launches by 18-24 months versus food-grade alternatives.
- Plant-based protein substitution:Pea and rice protein isolates are capturing share in mass-market nutritional supplements where collagen's functional advantages matter less than price.
Strategic Opportunities
- Kerala and Tamil Nadu marine clusters:Underutilized fish processing infrastructure along India's southwestern coast offers captive raw material access for scale marine collagen operations.
- Cosmeceutical topical formulations:Dermatology clinics in Mumbai and Delhi are prescribing collagen-infused serums, creating a high-margin channel distinct from commodity nutraceuticals.
- BIS certification harmonization:Pending alignment of food-grade collagen peptide standards with Codex Alimentarius would streamline export documentation for Indian manufacturers.
Industry Challenges
- Enzymatic hydrolysis expertise gap:Few Indian chemical engineers possess specialized training in controlled collagen denaturation, forcing reliance on imported process technology.
- Multi-regulator navigation:Simultaneous FSSAI, CDSCO, and BIS compliance for cross-category collagen products demands dedicated regulatory affairs teams that mid-tier players struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Collagen Market |
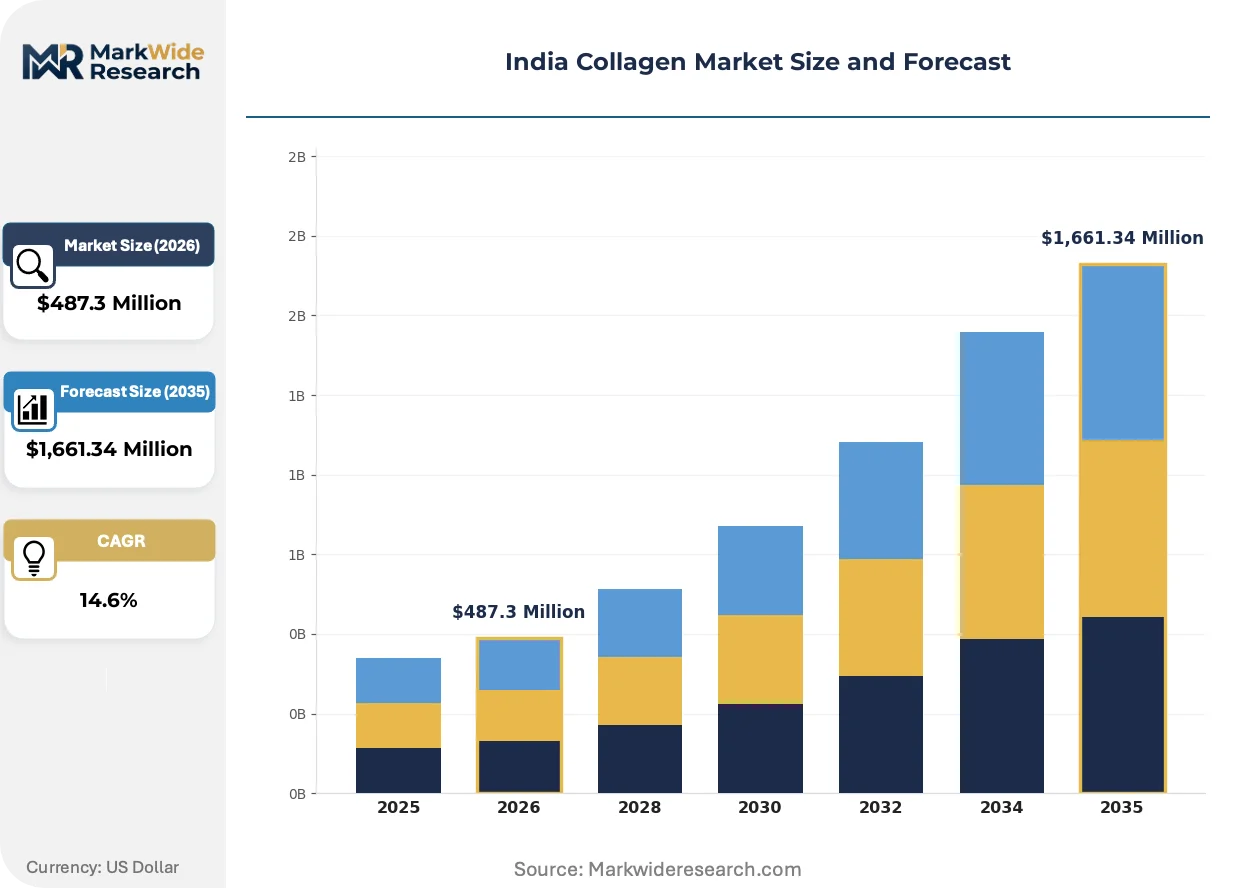
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Gelatin, Collagen Peptides, Collagen Cream End Use: Healthcare, Cosmetics, Food & Beverage, Nutritional Supplements Source: Bovine, Porcine, Marine, Poultry Distribution Channel: Online, Offline, Supermarkets, Pharmacies |
| Companies Covered | Titan Biotech Ltd, Athos Collagen Pvt. Ltd., Nitta Gelatin India Limited, Bioxent Health and Nutrition Pvt. Ltd, Cologenesis Healthcare Pvt Ltd, Gelita AG, Jellice Group, Holista CollTech Ltd, Rousselot (Darling Ingredients), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Collagen Market Shifts & Advancements
Marine extraction technologies and direct-to-consumer channel proliferation are compressing traditional gelatin supply chains while elevating bioavailability as the primary purchase criterion among urban Indian buyers.
Precision enzymatic hydrolysis is rewriting cost structures for fish-scale collagen processors by enabling selective peptide chain cleavage at ambient temperatures, eliminating energy-intensive acid-bath steps. Nutraceutical contract manufacturers in Hyderabad and Bangalore are adopting these systems to serve direct-to-consumer brands demanding smaller batch flexibility. The technology is compressing minimum viable scale thresholds, allowing regional players to challenge Nitta Gelatin's volume dominance in food applications.
FSSAI's pending framework for novel collagen sources including insect and microbial fermentation-derived proteins is forcing reformulation roadmaps across the supplier base. Manufacturers must pre-substitute labeling claims and establish traceability documentation before formal rule publication. Nutritional supplement exporters targeting Gulf Cooperation Council markets are most exposed, as dual FSSAI and halal certification requirements compound compliance complexity.
Subscription-based replenishment models are displacing pharmacy and supermarket bulk purchasing among metropolitan collagen consumers. Direct-to-consumer brands leverage WhatsApp commerce and influencer-driven education to capture recurring revenue from fitness enthusiasts and dermatology patients. This behavioral pivot concentrates most visibly in Mumbai and Delhi, where same-day delivery infrastructure supports just-in-time nutrition purchasing patterns previously reserved for pharmaceuticals.
India Collagen Market Segmentation
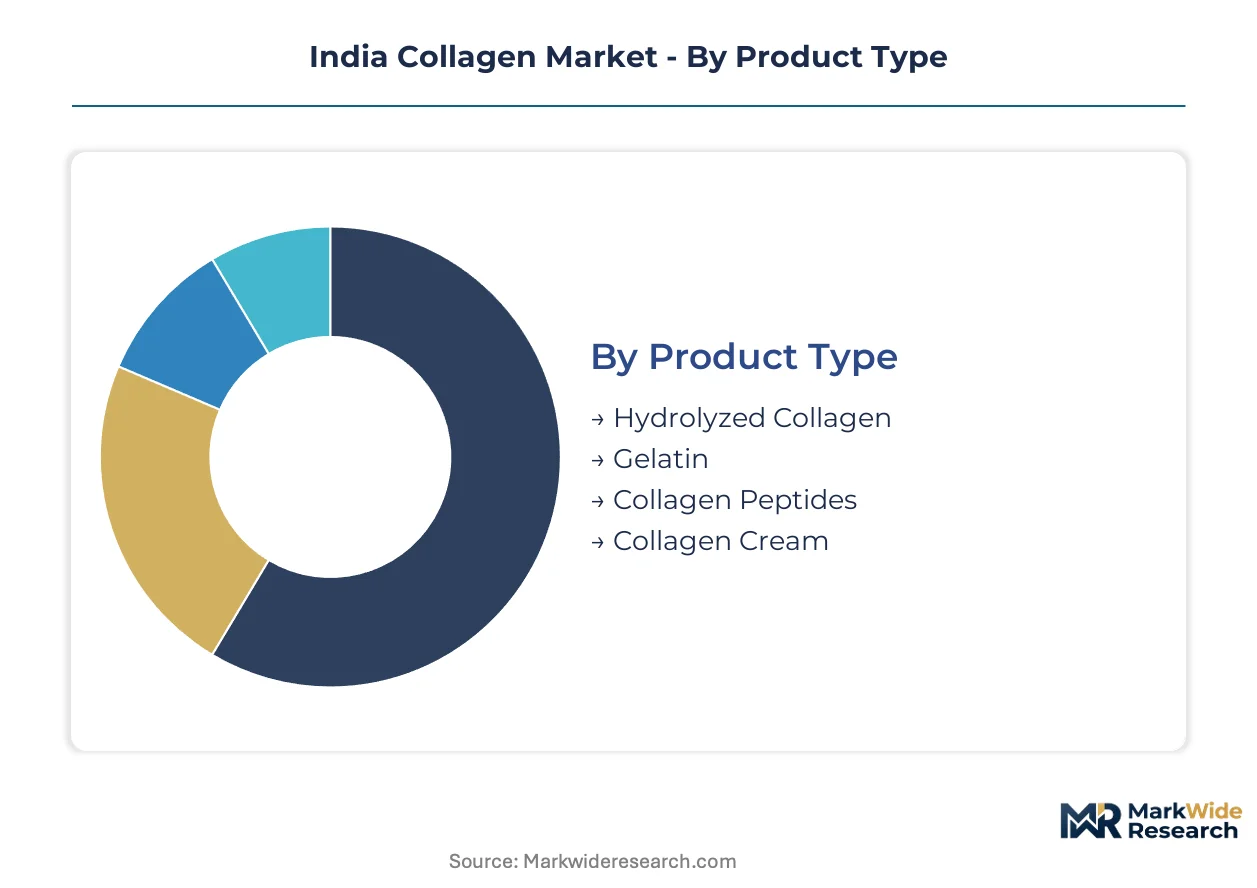
India's collagen market fragments across extraction methods, purity grades, and delivery formats that determine regulatory pathway and margin structure. Each segment carries distinct FSSAI and CDSCO compliance burdens that reshape competitive positioning.
Product Type:
Hydrolyzed collagen operates as a standalone nutritional input, while gelatin remains embedded within food manufacturing systems as a functional ingredient.
- Hydrolyzed Collagen:Enzymatically cleaved peptides with molecular weight below 10 kDa enable rapid intestinal absorption. Nutritional supplement brands in Mumbai and Delhi prioritize this format for direct-to-consumer positioning, though enzymatic hydrolysis equipment costs compress margins for small-batch producers.
- Gelatin:Partially hydrolyzed collagen with gelling strength measured in Bloom values dominates confectionery and pharmaceutical capsule applications. Nitta Gelatin India's manufacturing scale in Gujarat anchors supply for domestic food manufacturers, with BIS certification requirements filtering out informal competitors.
- Collagen Peptides:Standardized peptide chains for clinical nutrition and sports recovery applications.
- Collagen Cream:Topical formulations for dermatology and cosmetic use with CDSCO cosmetic registration requirements.
Gelatin leads volumes today; hydrolyzed collagen is gaining share fastest.
End Use:
Cost tier stratification separates premium clinical applications from mass-market nutrition positioning.
- Nutritional Supplements:Direct-to-consumer powders and capsules command the highest margin pool as urban consumers in Maharashtra integrate daily collagen regimens. FSSAI's tightened labeling mandates are forcing reformulation investments that favor organized players with dedicated regulatory affairs capacity.
- Healthcare:Pharmaceutical-grade collagen for wound dressings and surgical hemostats faces CDSCO approval timelines stretching 18-24 months. Titan Biotech Ltd's bovine-derived supply chain dominates this segment, with hospital procurement committees prioritizing documented traceability.
- Cosmetics:Serum and topical formulations for dermatology clinics in Mumbai and Delhi.
- Food & Beverage:Gelatin and hydrolyzed collagen as functional ingredients in processed foods.
Nutritional supplements lead volumes today; healthcare applications are expanding most quickly.
Source:
Geographic concentration of raw material supply chains determines cost predictability and certification access.
- Marine:Fish-scale and skin extraction from Kerala and Tamil Nadu processing clusters offers halal-certification advantages for Middle Eastern export markets. Precision enzymatic hydrolysis at ambient temperatures is eliminating energy-intensive acid-bath steps, compressing minimum viable scale thresholds for regional challengers.
- Bovine:Hide and tallow-derived collagen anchors pharmaceutical-grade supply chains. Monsoon-driven cattle availability fluctuations in Maharashtra and Gujarat create raw material price volatility that squeezes cost forecasting for wound care manufacturers.
- Porcine:Skin and bone extraction for cosmetic and food applications with limited religious market access.
- Poultry:Emerging cartilage and skin sourcing for niche nutritional applications.
Bovine sources lead volumes today; marine extraction is climbing the fastest.
Distribution Channel:
Customer type fragmentation separates recurring subscription purchasers from transactional retail buyers.
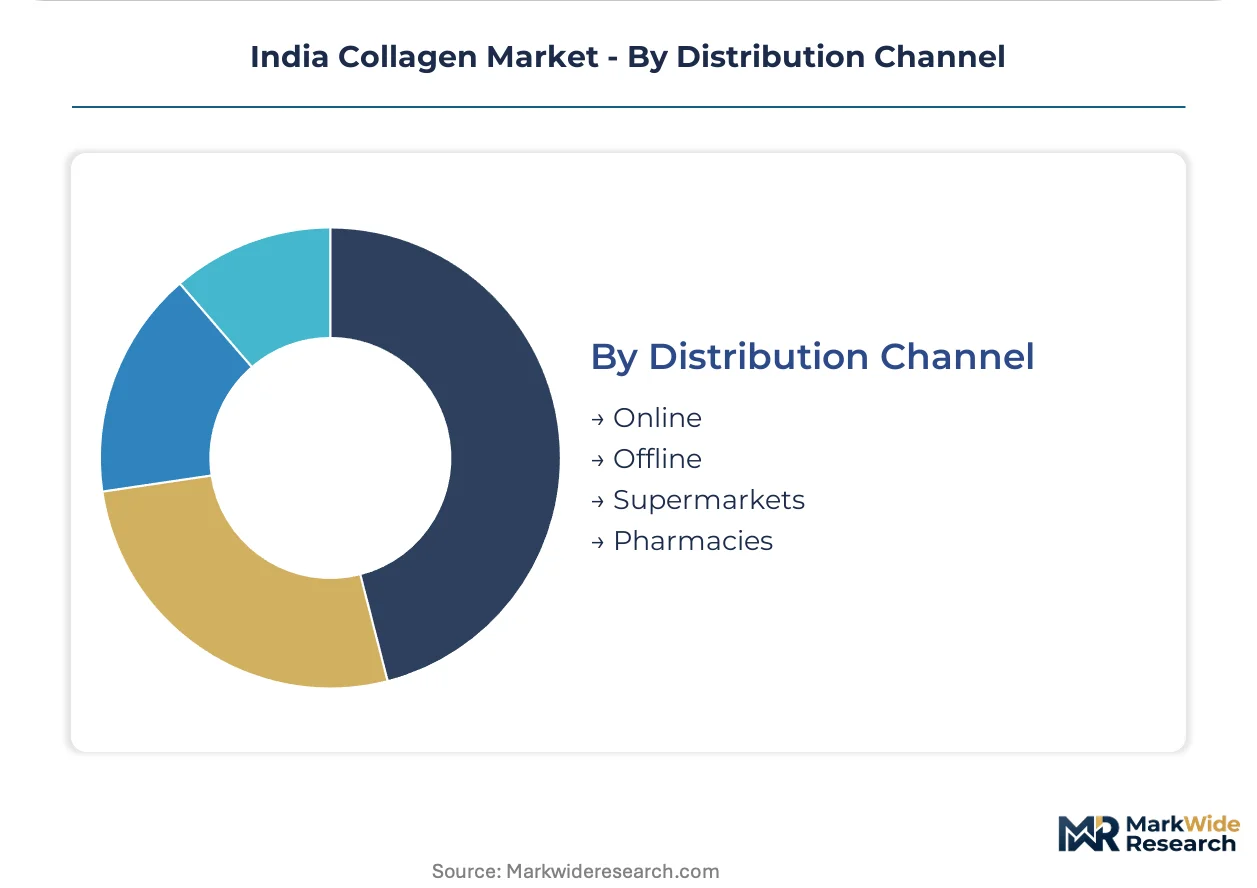
- Online:Direct-to-consumer brands leverage WhatsApp commerce and influencer education to capture subscription revenue from fitness enthusiasts. Same-day delivery infrastructure in Mumbai and Delhi supports just-in-time purchasing patterns previously reserved for pharmaceuticals.
- Pharmacies:Clinical-grade collagen peptides and wound care products with pharmacist recommendation dependency.
- Offline:Traditional retail and distributor networks for bulk food manufacturing procurement.
- Supermarkets:Mass-market nutritional supplements and cosmetic creams for impulse purchasing.
Pharmacies lead volumes today; online channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's pharmaceutical and nutraceutical manufacturing corridors anchor India's collagen production capacity, with Mumbai-Pune belt concentration driving raw material procurement patterns and export logistics infrastructure.
Maharashtra
Pharmaceutical-grade collagen demand from Mumbai's hospital procurement networks and Pune's contract research organizations is accelerating bovine-derived peptide consumption. FSSAI's Mumbai zonal office enforces tightened labeling mandates for nutritional supplements distributed through Maharashtra's pharmacy chains. The Bhiwandi-Nashik industrial corridor hosts enzymatic hydrolysis facilities serving direct-to-consumer brands with same-day delivery reach into Mumbai metropolitan consumers.
Gujarat
Gelatin manufacturing for confectionery and pharmaceutical capsule applications concentrates in Anand and Vadodara districts, leveraging tallow supply chains from local cattle processing. CDSCO's zonal headquarters in Ahmedabad expedites pharmaceutical-grade collagen approvals for wound care manufacturers targeting hospital networks. The Dahej special economic zone attracts marine collagen processors seeking halal-certification infrastructure for Middle Eastern export markets.
Kerala
Fish-scale and skin raw material availability from Kochi-Alappuzha processing clusters is repositioning Kerala as India's marine collagen sourcing hub. The state's fisheries department coordinates traceability documentation required for FSSAI novel source frameworks. Thiruvananthapuram's biotech park hosts precision enzymatic hydrolysis pilots eliminating acid-bath extraction costs for regional challengers.
Tamil Nadu
Underutilized seafood processing infrastructure along the Nagapattinam-Tuticorin coastline offers captive raw material access for scale marine collagen operations. The Tamil Nadu Industrial Development Corporation promotes backward integration into fish waste valorization through subsidized cold chain investments. Chennai's port infrastructure supports containerized collagen peptide exports to Southeast Asian markets demanding halal certification.
Karnataka
Nutraceutical contract manufacturers in Bangalore and Hyderabad are adopting ambient-temperature enzymatic systems to serve direct-to-consumer brands requiring smaller batch flexibility. The state's biotechnology department aligns collagen peptide standards with Codex Alimentarius pending BIS harmonization. Peenya industrial estate concentration enables just-in-time raw material sourcing for subscription-based replenishment models targeting metropolitan fitness enthusiasts.
India Collagen Market Competitive Landscape
Global majors compete with regional champions across certification-heavy supply chains, creating a tiered structure where pharmaceutical-grade producers face distinct regulatory barriers from food-grade commodity suppliers. The vendor base separates into three strategic archetypes: bovine-derived pharmaceutical specialists, marine-sourced halal exporters, and gelatin-scale food ingredient manufacturers. Dominant competitive moves include backward integration into raw material supply chains and strategic partnerships with direct-to-consumer brands for recurring revenue capture.
Among India-based specialists, Titan Biotech Ltd and Athos Collagen Pvt. Ltd. occupy positions within the pharmaceutical and cosmetic application tiers respectively, while Nitta Gelatin India Limited exemplifies the scale-driven food-grade segment. These domestic anchors compete with multinational representatives including Gelita AG and Rousselot, whose global certification portfolios serve export-oriented Indian manufacturers. The competitive dynamic centers on FSSAI compliance capacity and CDSCO approval timelines as differentiation mechanisms rather than pure manufacturing scale.
| Leading Market Players |
|---|
| Titan Biotech Ltd |
| Athos Collagen Pvt. Ltd. |
| Nitta Gelatin India Limited |
| Bioxent Health and Nutrition Pvt. Ltd |
| Cologenesis Healthcare Pvt Ltd |
| Gelita AG |
| Jellice Group |
| Holista CollTech Ltd |
| Rousselot (Darling Ingredients) |
| Others |
Supply & Pricing Matrix
FSSAI's tightened labeling mandates for nutritional supplements are forcing manufacturers toward cleaner formulations and transparent sourcing disclosures, compressing margins for non-compliant players while rewarding early adopters of certification-heavy supply chains with pricing power in premium tiers.
Pricing Analysis
Input-cost pass-through from monsoon-driven cattle availability fluctuations in Maharashtra and Gujarat squeezes cost predictability for bovine-derived pharmaceutical-grade collagen producers. Three-tier pricing structure across premium pharmaceutical-grade, standard food-grade, and economy gelatin tiers separates CDSCO-approved wound care applications from BIS-certified food ingredients and commodity confectionery inputs. Pricing pressure stems from plant-based protein substitution in mass-market nutritional supplements where pea and rice isolates undercut collagen on cost. Mass-market supplement consumers exhibit highest price sensitivity, while Mumbai and Delhi dermatology clinics prescribing collagen-infused serums show lowest sensitivity due to clinical efficacy positioning.
Supply Chain Analysis
Single-source vulnerability sits with bovine hide and tallow supply chains concentrated in Maharashtra and Gujarat, where monsoon patterns dictate raw material availability. Marine collagen draws from Kerala and Tamil Nadu fish processing clusters, while pharmaceutical-grade extraction relies on enzymatic hydrolysis equipment imported from Germany and Japan. Supply chain risk centers on regulatory restriction as FSSAI's pending novel source framework threatens reformulation costs for insect and microbial fermentation-derived proteins. Distribution runs through direct-to-consumer subscription models displacing pharmacy bulk purchasing among metropolitan fitness enthusiasts and dermatology patients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as urban Indian consumers in Maharashtra and Gujarat shift toward protein-enriched daily nutrition regimens demanding documented traceability and halal certification.
For Market Incumbents: Anchor pharmaceutical-grade positioning through CDSCO approval maintenance and backward integration into Maharashtra cattle processing networks. Defend against marine collagen challengers by securing long-term tallow supply contracts before monsoon volatility intensifies. Prioritize certification investment in dual FSSAI-halal documentation for Gulf Cooperation Council export access. For New Entrants and Emerging Players: FSSAI's pending framework for novel collagen sources in India opens a window for microbial fermentation-derived protein specialists to establish pre-compliant labeling roadmaps. Target Kerala and Tamil Nadu marine clusters where underutilized fish processing infrastructure offers captive raw material access. Pursue contract manufacturing relationships with direct-to-consumer brands in Bangalore and Hyderabad demanding smaller batch flexibility. For Investors and Strategic Acquirers: Asymmetric upside sits with precision enzymatic hydrolysis technology owners capable of ambient-temperature processing eliminating energy-intensive acid-bath steps. Long-term viability favors acquisition targets with demonstrated FSSAI regulatory affairs capacity and established traceability documentation systems. Watch for BIS certification harmonization with Codex Alimentarius as inflection indicator streamlining export documentation for Indian manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Supply | Captive tallow access in Maharashtra insulates against monsoon-driven cattle availability volatility squeezing cost forecasting. |
| Precision Enzymatic Hydrolysis Adoption | Ambient-temperature processing eliminates energy-intensive acid-bath steps, compressing minimum viable scale thresholds for regional challengers. |
| Dual FSSAI-Halal Certification Investment | Documented traceability unlocks Gulf Cooperation Council and Southeast Asian export procurement governed by religious certification. |
| Direct-to-Consumer Channel Development | WhatsApp commerce and influencer-driven education capture recurring subscription revenue from Mumbai and Delhi fitness enthusiasts. |
| Cosmeceutical Topical Formulation Expansion | Dermatology clinic prescriptions in metropolitan markets create high-margin channel distinct from commodity nutraceutical pricing pressure. |
Research Methodology
Multiple input streams — primary interviews with enzymatic hydrolysis plant managers, FSSAI regulatory affairs consultants, and Mumbai hospital procurement committees, alongside secondary validation through CDSCO approval databases, BIS certification records, and customs trade data — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Historical volume trajectories were cross-referenced against panel input from contract manufacturers and direct-to-consumer brand operators across the projection horizon. Segmentation dimensions modeled include product type, source category, end-use application, and distribution channel, with CAGRs derived from elasticity analysis against protein-enriched diet penetration rates and PLI scheme incentive uptake.
Revisions become necessary when FSSAI publishes final novel source frameworks, CDSCO extends pharmaceutical-grade approval timelines, or monsoon patterns disrupt Maharashtra and Gujarat cattle availability beyond historical variance bands. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Open Cell Foam Market
Specialty Materials
Organic Scintillators Market
Specialty Materials
UV Stabilized Films Market
Specialty Materials
Carbon Blacks for Non-Rubber Applications Market
Specialty Materials
Battery Separator Films Market
Specialty Materials
Microwave Absorbing Materials Market
Specialty Materials
Cadmium Sulfide Market
Specialty Materials
Silicone Gel Market
Specialty Materials
Rigid Polyurethane Foams Market
Specialty Materials
Solar Backsheet Films Market
Specialty Materials
Global Poly Vents Market
Specialty Materials
Global Liquid Crystal Polymer (LCP) Films and Laminates Market
Specialty Materials
Medical Injection Molded Plastics Market
Specialty Materials
Shape Memory Polymer Market
Specialty Materials
Super-Hard Material Market
Specialty Materials
Plastic Dielectric Films Market