
 Plasmid DNA Contract Manufacturing Market | 2026-2036
Plasmid DNA Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Plasmid DNA Contract Manufacturing Market Intelligence
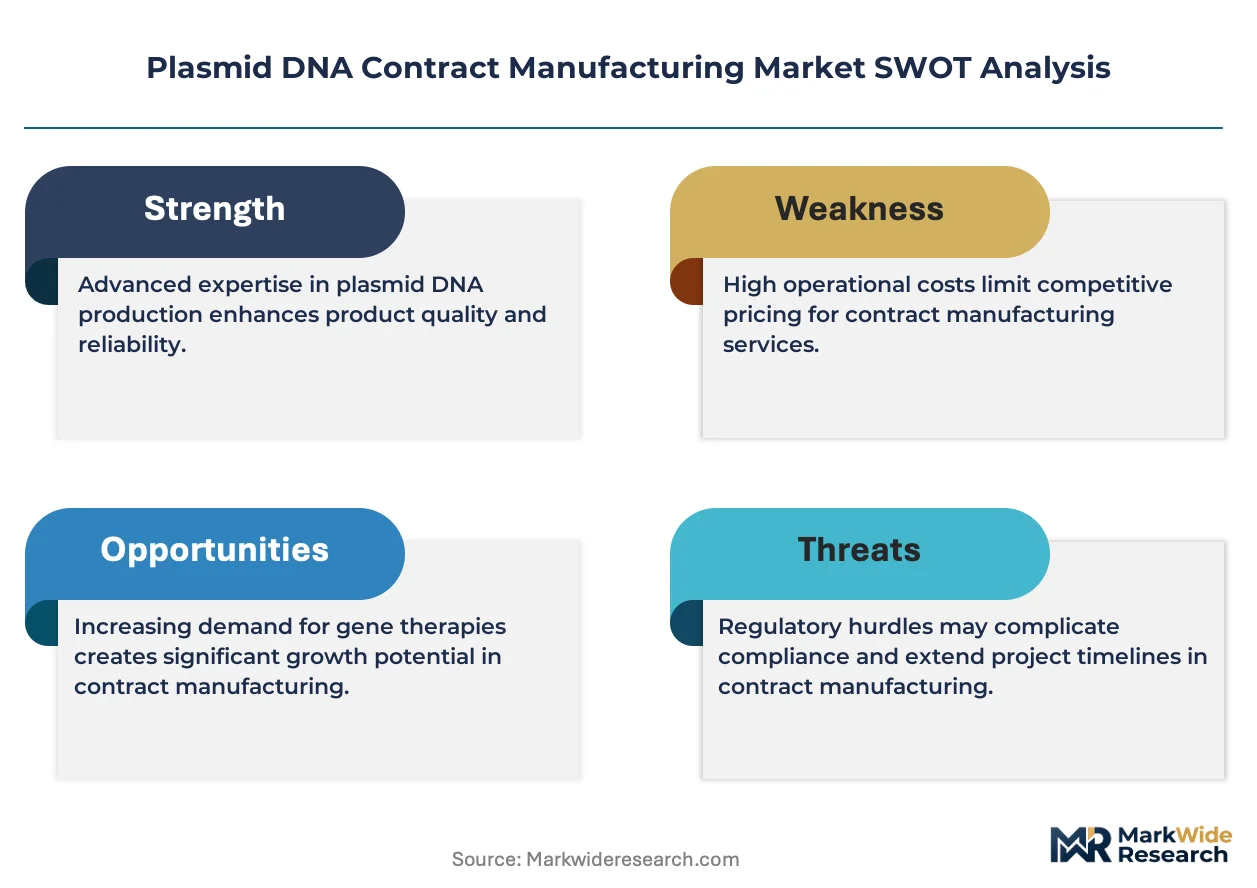
A shortage of GMP-trained molecular biologists and fermentation specialists is bifurcating the Plasmid DNA Contract Manufacturing landscape into capacity-constrained legacy sites and digitally integrated new facilities. Lonza leverages its Swiss-US manufacturing footprint to anchor high-volume gene therapy plasmid supply. Catalent Inc. competes through end-to-end plasmid-to-viral-vector integration across North American and European sites. Charles River Laboratories differentiates by extending its analytical and regulatory services alongside plasmid production.
Plasmid DNA contract manufacturing refers to the outsourced production of circular, double-stranded DNA vectors, typically 2–20 kilobases in size, propagated in bacterial hosts such as E. coli under controlled fermentation conditions, then purified through alkaline lysis and chromatography for use as genetic payloads in gene therapies, DNA vaccines, and cell engineering workflows. GMP Grade plasmid production commands the dominant value share as sponsors require ISO 5 cleanroom environments, fully documented batch records, and regulatory starting material status for downstream viral vector applications. Gene Therapy applications within the Application segment generate the fastest procurement velocity, driven by IND filings for in vivo and ex vivo programs that demand escalating plasmid quantities for transfection and transduction processes.
FDA's Chemistry, Manufacturing, and Controls guidance for gene therapy, EMA's ATMP framework, and ISO 13485 quality management standards collectively shape facility qualification timelines, release testing protocols, and cross-border shipment eligibility for plasmid products. The EU AI Act and evolving FDA inspectional approaches to continuous manufacturing are forcing CDMOs to validate real-time process analytical technology alongside traditional batch release methods. Stakeholders must monitor how regulator alignment on plasmid starting material classification affects inventory positioning and multi-site supply strategies.
Market Dynamics
The FDA's Chemistry, Manufacturing, and Controls guidance for gene therapy is compressing facility qualification timelines while simultaneously expanding batch record requirements, forcing CDMOs to choose between legacy site upgrades and greenfield digital investments.
Growth Catalysts
- EMA ATMP Framework Maturation:The European Medicines Agency's advanced therapy medicinal products classification provides regulatory clarity that accelerates IND filings for gene therapy sponsors seeking plasmid starting material status.
- mRNA Vaccine Platform Expansion:Viral vector and nucleic acid vaccine producers in Switzerland and Germany are scaling GMP plasmid procurement for transfection workflows in lipid nanoparticle manufacturing.
- Continuous Manufacturing Adoption:Real-time process analytical technology integration enables higher batch yields and reduced release testing timelines for fermentation-based plasmid production.
Market Restraints
- Fermentation Capacity Concentration:Stainless steel bioreactor availability clusters in Swiss and US coastal hubs, creating geographic chokepoints for high-volume gene therapy plasmid supply.
- Alkaline Lysis Reagent Volatility:Sodium hydroxide and proprietary resin costs fluctuate with industrial chemical supply chains, compressing margins on research-grade plasmid batches.
- Cleanroom Construction Lead Times:ISO 5 environment qualification delays average eighteen to twenty-four months, freezing sponsor pipeline commitments for new CDMO relationships.
Strategic Opportunities
- India CDMO Infrastructure Buildout:CDSCO-aligned facilities in Hyderabad and Bengaluru offer cost-advantaged GMP plasmid production for early-phase gene therapy developers seeking geographic diversification.
- Cell Engineering Workflow Integration:Plasmid supply contracts bundled with electroporation and transduction services capture value from CAR-T and iPSC program sponsors.
- EU AI Act Compliance Services:CDMOs validating algorithmic batch monitoring and predictive release systems differentiate for sponsors navigating automated manufacturing documentation requirements.
Industry Challenges
- GMP-Trained Molecular Biologist Scarcity:Fermentation specialists with documented aseptic technique and regulatory batch record experience command premium compensation, constraining workforce expansion at new facilities.
- Multi-Site Release Testing Harmonization:Sponsors operating viral vector production across US and European sites face inconsistent endotoxin and residual host cell protein acceptance criteria between FDA and EMA jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasmid DNA Contract Manufacturing Market |
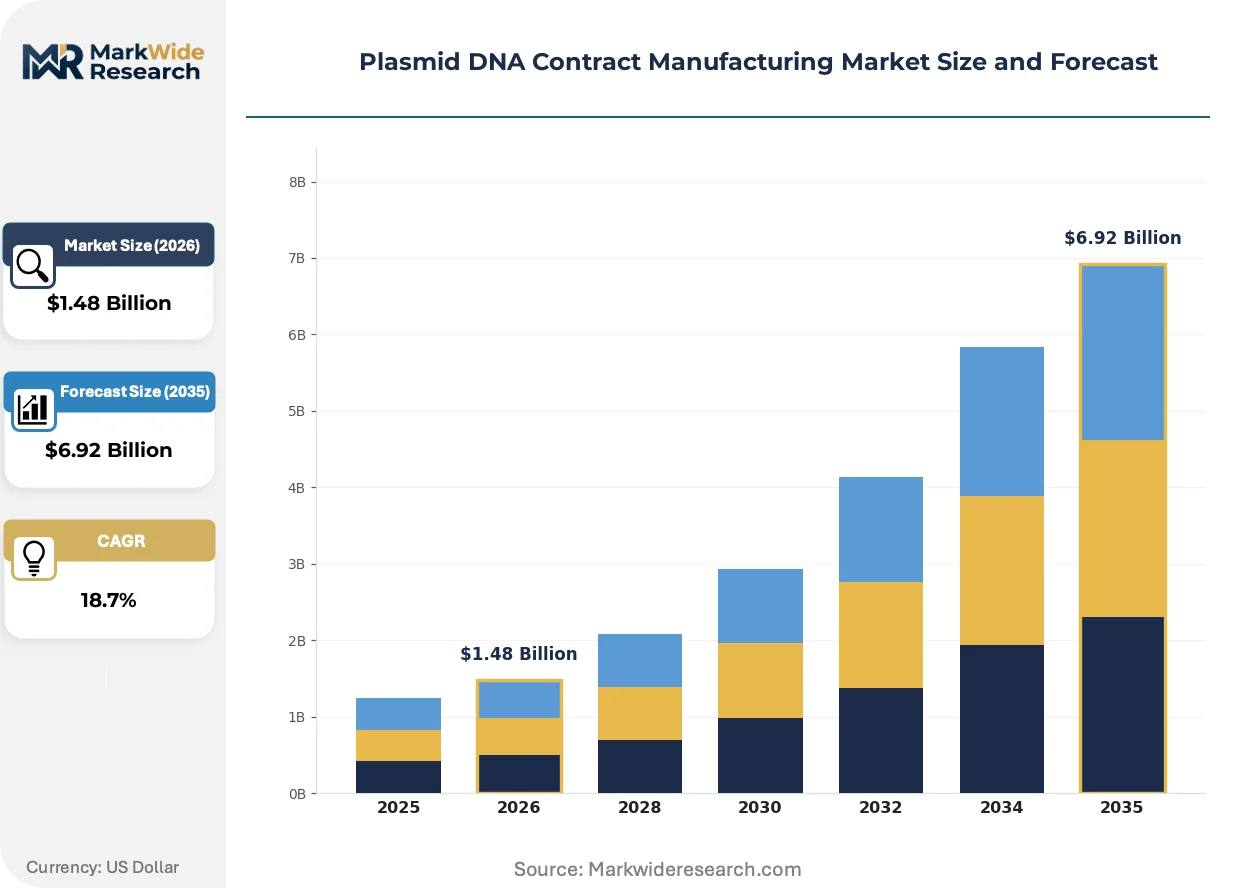
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $6.92 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clinical Grade, Research Grade, Analytical Grade, GMP Grade Application: Gene Therapy, Vaccine Development, Transgenic Research, Cell Line Development Delivery Mode: In Vivo, In Vitro, Ex Vivo, Direct Injection End User: Biotechnology Firms, Pharmaceutical Companies, Academic Institutions, Contract Research Organizations |
| Companies Covered | Lonza, Catalent Inc., Charles River Laboratories, Aldevron, VGXI, Inc., PlasmidFactory GmbH & Co. KG, Thermo Fisher Scientific Inc., BioCina, AGC Biologics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasmid DNA Contract Manufacturing Market Strategic Shifts & Innovations
Digital twin modeling and single-use bioreactor systems are compressing process development timelines while fragmenting the traditional stainless steel equipment vendor base. Three developments merit particular attention.
Single-use fermentation technology is fragmenting the installed base of stainless steel bioreactors that have dominated plasmid DNA production since the 1990s. Gene therapy sponsors with mid-scale IND requirements are adopting 50-200 liter disposable systems for rapid campaign turnover. This shift is fragmenting equipment procurement patterns and enabling modular facility designs that reduce cross-contamination risks between viral vector and plasmid production suites.
The EU AI Act's risk-based classification system for automated manufacturing processes is forcing CDMOs to revalidate legacy supervisory control and data acquisition systems. Batch record algorithms now require documented training data provenance and human oversight protocols. European gene therapy sponsors are prioritizing CDMOs with pre-validated artificial intelligence quality management systems to avoid regulatory submission delays.
Sponsor quality agreements are migrating from unit pricing to full-time equivalent staffing models for extended plasmid supply relationships. Biotechnology developers with multi-vector pipelines are locking dedicated fermentation suites and analytical teams through multi-year contracts. This pattern is most pronounced in the Boston-Cambridge and Basel-Zurich corridors where gene therapy cluster density supports captive capacity arrangements.
Plasmid DNA Contract Manufacturing Market Segmentation
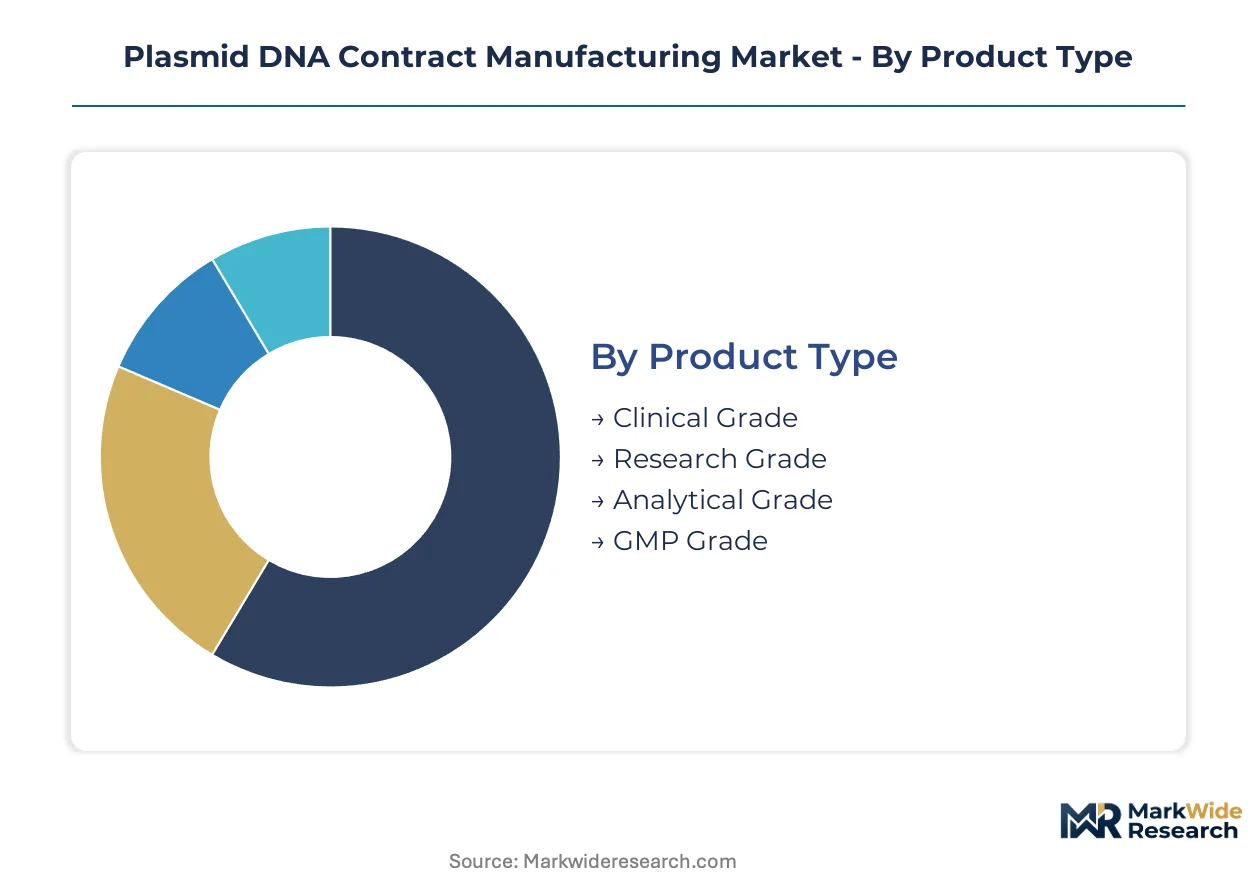
Plasmid DNA contract manufacturing segments by regulatory stringency, application complexity, and sponsor sophistication. Procurement patterns diverge sharply between early discovery workflows and commercial gene therapy supply chains.
Product Type:
GMP Grade production concentrates in Switzerland and the United States where FDA and Swissmedic inspectional frameworks anchor qualification standards. Research Grade supply disperses across domestic fermentation facilities serving local academic clusters.
- GMP Grade:Manufactured under ISO 5 cleanroom conditions with full batch documentation and regulatory starting material status for downstream viral vector applications. Gene therapy sponsors in Basel and Boston lock dedicated capacity through multi-year supply agreements.
- Research Grade:Produced under GLP guidelines without formal regulatory submission pathways. Academic institutions and early-stage biotechs in Germany and California drive procurement for transfection optimization studies.
- Clinical Grade:Bridges preclinical and Phase I requirements with partial documentation packages.
- Analytical Grade:Supports reference standard and assay development with defined purity specifications.
GMP Grade commands the established base. The steepest expansion runs through Clinical Grade as IND filings accelerate.
Application:
Cost tiers separate validated therapeutic programs from exploratory research. Gene therapy applications absorb premium pricing for endotoxin-controlled, low-residual production.
- Gene Therapy:In vivo and ex vivo programs demand escalating plasmid quantities for AAV and lentiviral vector transfection. Sponsors in the United States and Germany procure GMP-grade supply for regulatory-submission-enabling studies.
- Vaccine Development:mRNA and DNA vaccine platforms require linearized plasmid templates for in vitro transcription. Swiss CDMOs serve nucleic acid vaccine producers with dedicated fermentation suites.
- Transgenic Research:Animal model engineering and agricultural biotechnology applications.
- Cell Line Development:Stable producer cell generation for biologics manufacturing.
Vaccine Development anchors volume throughput. Gene Therapy is climbing the fastest as commercial-stage programs mature.
Delivery Mode:
Volume scale differentiates between systemic administration requiring high-dose plasmid and localized applications with modest material needs.
- In Vivo:Direct administration to patients demands pharmaceutical-grade purity with stringent endotoxin limits. Liver-directed gene therapy programs in the United States scale to gram-scale plasmid requirements per cohort.
- Ex Vivo:Cell modification outside the patient requires aseptic processing for CAR-T and iPSC workflows. German and Swiss facilities specialize in closed-system manufacturing for autologous therapies.
- In Vitro:Laboratory-scale transfection for research and process development.
- Direct Injection:Intramuscular or intratumoral delivery for DNA vaccines and immunotherapy.
Ex Vivo dominates current manufacturing commitments. In Vivo shows the steepest trajectory as in vivo gene editing advances.
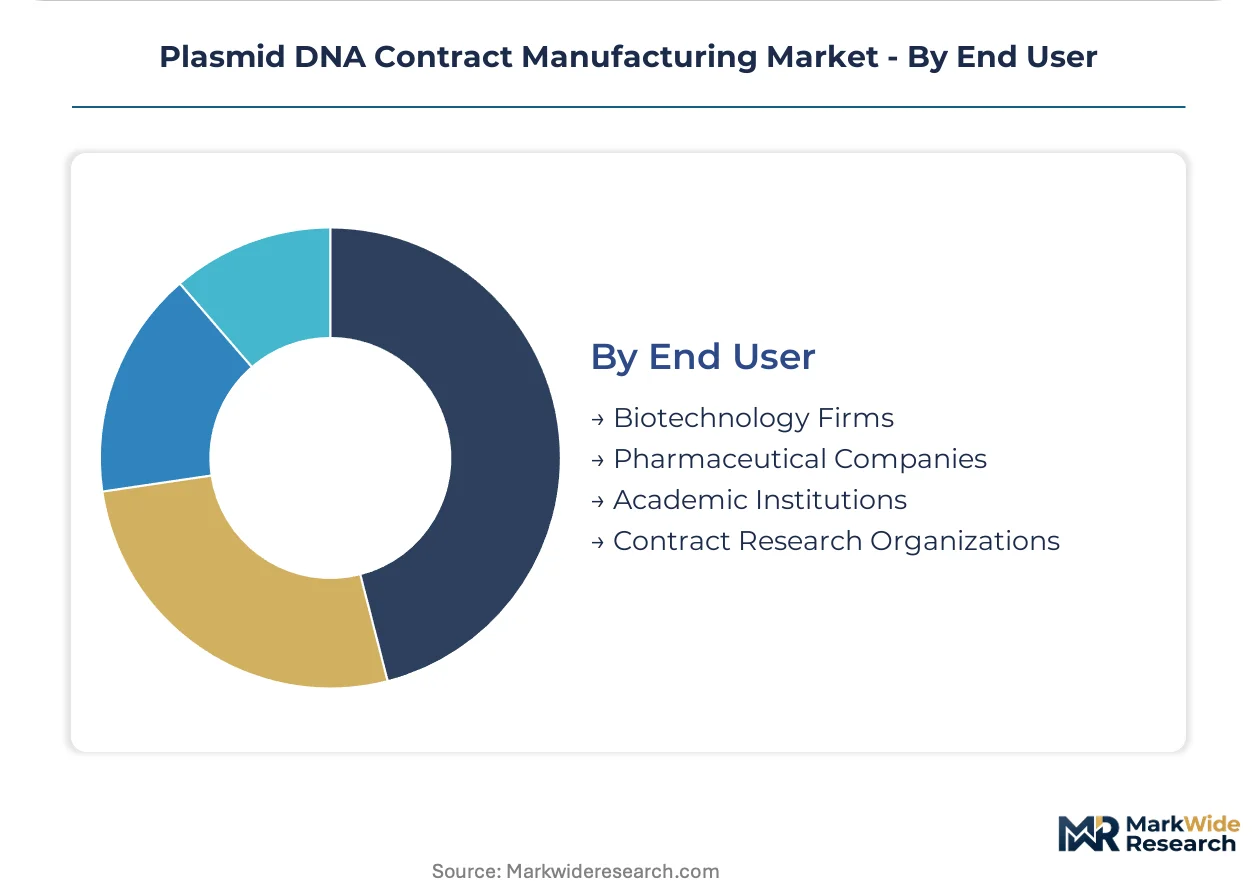
End User:
Customer type determines contract structure, with biotechnology firms seeking flexible campaign terms and pharmaceutical companies demanding captive capacity.
- Biotechnology Firms:Venture-backed gene therapy developers with multi-vector pipelines negotiate full-time equivalent staffing models. Boston-Cambridge and Basel-Zurich corridor sponsors lock dedicated analytical teams.
- Pharmaceutical Companies:Large-cap sponsors with approved products pursue backward integration into plasmid supply or secure multi-site redundancy agreements.
- Academic Institutions:Research-grade procurement for mechanistic studies and tool development.
- Contract Research Organizations:Integrated discovery-to-IND service providers bundling plasmid production with toxicology and regulatory support.
Pharmaceutical Companies command the established procurement base. Biotechnology Firms are expanding most quickly as gene therapy startup formation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Switzerland commands premium pricing for GMP-grade plasmid supply while Indian CDMOs compete on cost for research-grade batches. This asymmetry shapes procurement patterns across gene therapy development stages.
United States
FDA Chemistry, Manufacturing, and Controls guidance for gene therapy compresses facility qualification timelines while expanding batch record requirements. The Boston-Cambridge corridor anchors demand as gene therapy sponsors lock dedicated fermentation capacity through multi-year agreements. Charles River Laboratories extends analytical services alongside production from Massachusetts facilities.
Germany
EMA Advanced Therapy Medicinal Products classification accelerates IND filings for sponsors seeking plasmid starting material status. The country's national pharmaceutical regulator enforces stringent endotoxin limits for ex vivo cell engineering workflows. Heidelberg and Munich clusters specialize in closed-system manufacturing for autologous CAR-T therapies.
Switzerland
Swissmedic inspectional frameworks anchor qualification standards for commercial gene therapy supply. The EU AI Act forces CDMOs to revalidate legacy supervisory control systems for algorithmic batch monitoring. Basel-Zurich corridor sponsors prioritize partners with pre-validated artificial intelligence quality management systems.
India
CDSCO-aligned facilities in Hyderabad and Bengaluru offer cost-advantaged GMP production for early-phase developers. The country's national pharmaceutical regulator aligns with ICH guidelines for clinical-grade plasmid export eligibility. Domestic fermentation capacity serves regional vaccine producers and academic gene therapy programs.
Plasmid DNA Contract Manufacturing Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the plasmid DNA contract manufacturing landscape. Swiss and US coastal facilities dominate GMP-grade supply through stainless steel bioreactor networks and ISO 5 cleanroom infrastructure. Three archetypes define competitive positioning: integrated CDMOs with end-to-end viral vector capabilities, specialized plasmid-only producers with rapid campaign turnover, and diversified life science tools companies leveraging consumables pull-through. Capacity expansion and strategic partnerships represent the dominant competitive moves as sponsors seek multi-site redundancy.
Within the integrated CDMO tier, Lonza and Catalent Inc. exemplify archetypes spanning plasmid-to-viral-vector production across transatlantic footprints. Charles River Laboratories occupies a position emphasizing analytical and regulatory service bundling alongside fermentation supply. Among specialized producers, PlasmidFactory GmbH & Co. KG represents the European mid-scale segment focused on rapid-turnaround GMP campaigns.
| Leading Market Players |
|---|
| Lonza |
| Catalent Inc. |
| Charles River Laboratories |
| Aldevron |
| VGXI, Inc. |
| PlasmidFactory GmbH & Co. KG |
| Thermo Fisher Scientific Inc. |
| BioCina |
| AGC Biologics |
| Others |
Cost & Logistics Intelligence
Eighteen-to-twenty-four-month ISO 5 cleanroom qualification timelines concentrate pricing power with Swiss and US coastal facilities that hold validated stainless steel bioreactor networks, while gene therapy sponsors absorb premium GMP-grade costs to secure regulatory starting material status for downstream viral vector applications.
Pricing Analysis
Swiss facilities command premium pricing against Indian CDMOs that compete on cost for research-grade batches. A three-tier pricing structure across premium, standard, and economy levels stratifies by GMP certification grade, with ISO 5 cleanroom validation and FDA inspectional history driving price differentiation. Cost compression in research-grade supply intensifies as alkaline lysis reagent volatility squeezes margins on academic and early-discovery batches. Biotechnology firms with multi-vector pipelines show lowest price sensitivity through full-time equivalent staffing models, while academic institutions remain most cost-conscious.
Supply Chain Analysis
Stainless steel bioreactor availability clusters in Switzerland, Germany, and the United States, creating geographic chokepoints for high-volume gene therapy plasmid supply. Fermentation capacity draws from sodium hydroxide, proprietary chromatography resins, and E. coli host strain repositories that fluctuate with industrial chemical supply chains. Single-source vulnerability runs through Swissmedic-inspected facilities that anchor commercial gene therapy supply. Distribution runs through validated cold-chain logistics with documented batch record provenance for cross-border EMA and FDA submissions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasmid DNA contract manufacturing functions as a platform-economics inflection where CDMOs bundling electroporation and transduction services capture value from CAR-T and iPSC program sponsors seeking workflow integration rather than discrete supply transactions.
For Market Incumbents: Fortify captive capacity arrangements in the Boston-Cambridge and Basel-Zurich corridors through multi-year dedicated fermentation suite contracts that lock analytical teams. Incumbents should deepen backward integration into proprietary host strain development to differentiate against emerging Indian CDMOs building CDSCO-aligned infrastructure for cost-advantaged early-phase supply. For New Entrants and Emerging Players: CDSCO fast-track certification for Hyderabad and Bengaluru facilities offers the most penetrable entry point for early-phase gene therapy developers seeking geographic diversification from Swiss and US pricing premiums. New entrants should target research-grade procurement bundled with toxicology and regulatory support services to capture value from academic institutions and venture-backed biotechs before GMP-grade graduation. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-captive infrastructure play because FDA and EMA gene therapy framework maturation locks sponsors into validated CDMO relationships with documented batch record histories. Acquisition targets should display pre-validated artificial intelligence quality management systems for EU AI Act compliance. The signal to watch is IND filing velocity for in vivo gene editing programs that scale gram-scale plasmid requirements.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Cleanroom Qualification | Eighteen-to-twenty-four-month ISO 5 validation timelines freeze sponsor pipeline commitments for new CDMO relationships. |
| Single-Use Bioreactor Adoption | Disposable 50-200 liter systems enable rapid campaign turnover for mid-scale IND requirements in gene therapy. |
| AI Quality Management Validation | Pre-validated algorithmic batch monitoring systems differentiate CDMOs for EU AI Act compliance. |
| Cell Engineering Workflow Bundling | Plasmid supply contracts with electroporation services capture CAR-T and iPSC program value. |
| Multi-Site Redundancy Agreements | Large-cap sponsors secure transatlantic supply resilience against Swiss and US coastal capacity concentration. |
Research Approach
The analysis maps GMP-grade, clinical-grade, and research-grade production tiers, each validated through fermentation specialists, regulatory affairs leads at gene therapy sponsors, CDMO procurement managers, and quality assurance directors. Primary interviews with these stakeholders combined with secondary validation from FDA Chemistry Manufacturing and Controls guidance documents, EMA Advanced Therapy Medicinal Products classification frameworks, Swissmedic inspectional protocols, and CDSCO export eligibility guidelines. Bottom-up capacity modeling and top-down sponsor procurement pattern triangulation anchored volume and value estimates.
Consistency checks against external benchmarks validated outputs across the projection horizon. Segmentation dimensions modeled include regulatory grade tier, application complexity from gene therapy through vaccine development, delivery mode scale from in vitro through in vivo, and end-user sophistication from academic institutions through pharmaceutical companies. CAGRs derived from sponsor pipeline commitments, IND filing trajectories, and viral vector manufacturing scale-up schedules. Fermentation capacity utilization rates and cleanroom construction lead times served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained FDA and EMA gene therapy framework maturation; material deviation in regulator alignment on plasmid starting material classification would warrant model refresh. Practitioners should keep alternative scenarios live as EU AI Act enforcement timelines and continuous manufacturing adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Antibody Drug Conjugates Contract Manufacturing Market
Biotechnology Services
Mirna Tools and Services Market
Biotechnology Services
Antibodies Contract Manufacturing Market
Biotechnology Services
Global Protein Labeling Market
Biotechnology Services
Biotechnology and Pharmaceutical Services Outsourcing Market
Biotechnology Services
Global Culture Media Market
Biotechnology Services
Phycobiliproteins Market
Biotechnology Services
Global Custom Antibody Market
Biotechnology Services
Cell Culture Media Market
Biotechnology Services
Plasmid DNA Preparation Market
Biotechnology Services
Drug Discovery and Development Laboratory Services Market
Biotechnology Services
Immunoassays in R & D Market
Biotechnology Services
Feruloyl Esterase Market
Biotechnology Services
Cell Lysis and Disruption Market
Biotechnology Services
Dnases, Ligases, and RNA Polymerases Market
Biotechnology Services
Global Downstream Processing Market