
 Research-Grade Proteins Market | 2026-2036
Research-Grade Proteins Market Size, Share, and Industry Trends Forecast 2026-2036
Research-Grade Proteins Market Analytics
Specialized protein purification talent is bifurcating the competitive landscape into scale leaders and boutique specialists. Thermo Fisher Scientific leverages its end-to-end workflow integration to sustain dominant positions in high-volume recombinant protein supply. Bio-Techne Corporation anchors its competitive moat through deep catalog specialization in cytokines and growth factors. Sino Biological competes aggressively on cost-engineered mammalian expression platforms, particularly for antibody reagents.
Research-grade proteins comprise highly characterized biomolecules manufactured under controlled conditions for non-clinical investigation, typically exhibiting batch-to-batch consistency within specified purity thresholds such as SDS-PAGE verification exceeding 95 percent. These proteins enable target validation, assay development, and mechanism-of-function studies across drug discovery pipelines. Recombinant proteins command the largest value share due to their engineered specificity and scalable microbial or mammalian production, while cytokines represent the fastest-expanding category as immuno-oncology research intensifies. Academic institutions remain the most fragmented buyer segment, though pharmaceutical companies concentrate the highest per-account spending and drive premium pricing for GMP-adjacent documentation.
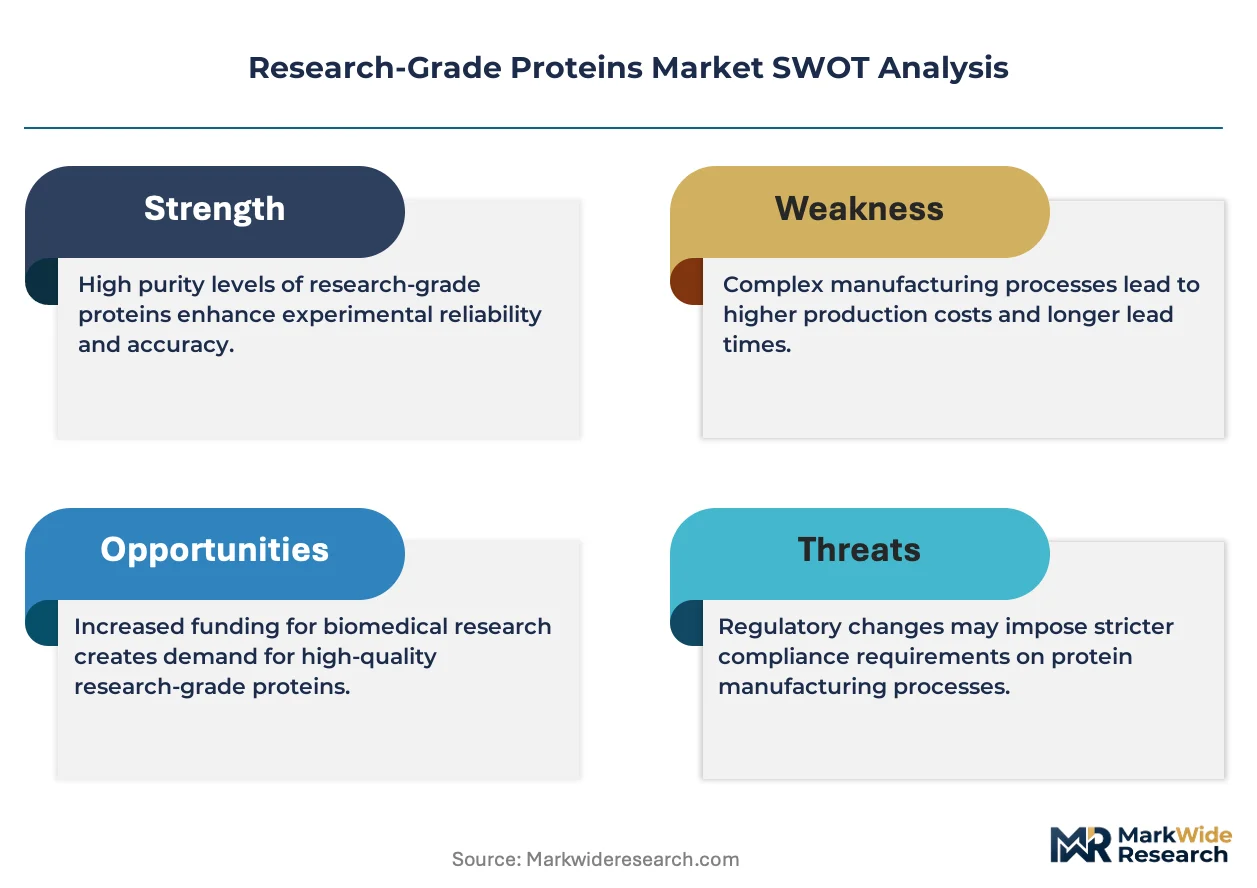
FDA oversight of ancillary materials used in cell and gene therapy development, coupled with EMA's evolving ATMP guidelines, elevates documentation burdens for suppliers seeking therapeutic-adjacent positioning. ISO 9001 and ISO 13485 certifications increasingly function as market access filters rather than competitive differentiators. China's NMPA has tightened import registration requirements for biological reagents, redirecting procurement toward domestic manufacturers with certified quality systems. Stakeholders must monitor regulatory divergence between jurisdictions to avoid qualification redundancy that erodes margin pools.
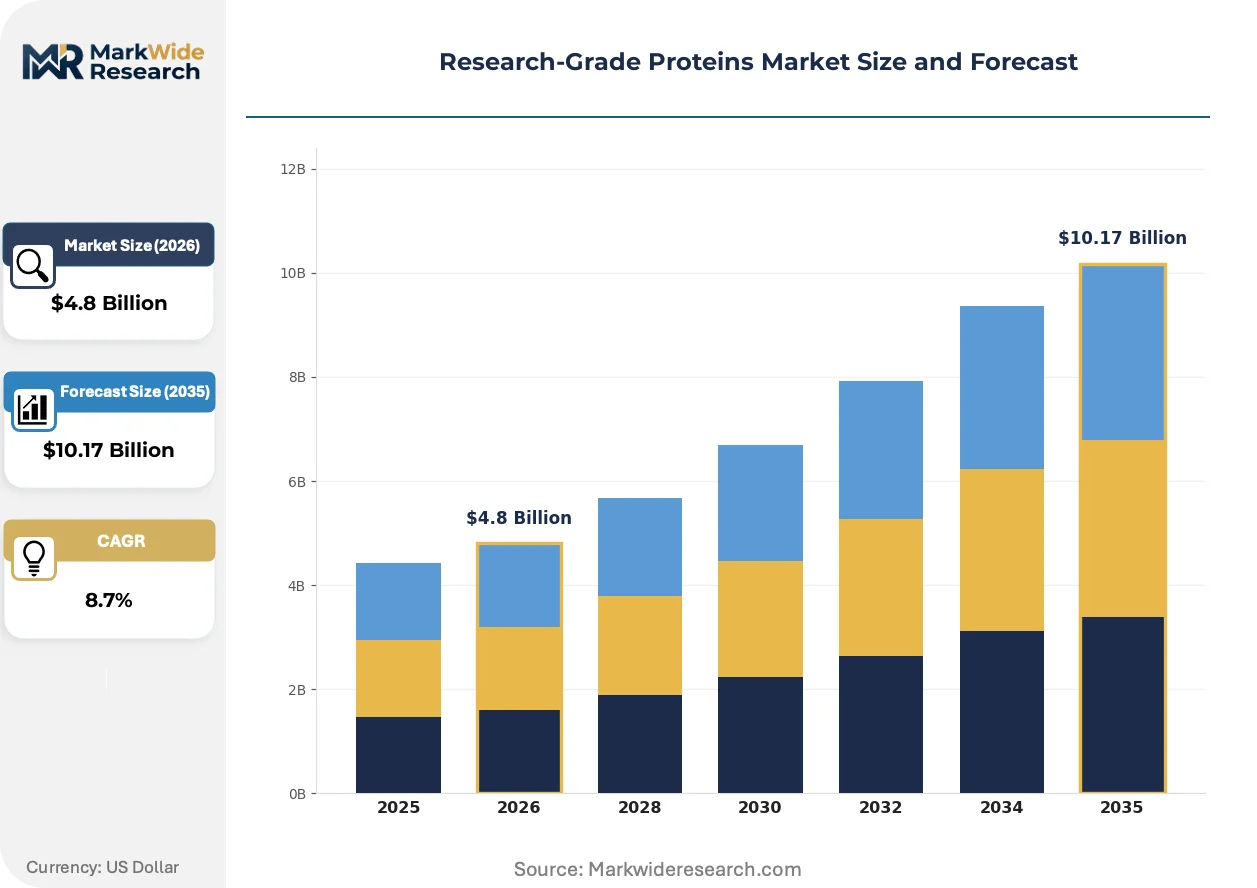
Market Dynamics
Single-use bioreactor adoption is compressing facility qualification timelines and forcing incumbent suppliers to revalidate legacy stainless-steel workflows or exit therapeutic-adjacent supply tiers entirely.
Growth Catalysts
- Cell Therapy Manufacturing Scale-Up:Biopharmaceutical companies are expanding GMP-adjacent protein procurement to support autologous and allogeneic cell therapy pipelines, creating pull-through demand for ISO 13485-certified research-grade precursors.
- FDA Ancillary Materials Guidance:The agency's evolving oversight framework for cell and gene therapy inputs is elevating documentation standards, filtering out uncertified suppliers and consolidating volume with qualified vendors.
- Continuous Processing Platforms:Perfusion-based mammalian expression systems are reducing batch-to-batch variability, enabling suppliers to meet tightened purity specifications without yield sacrifice.
Market Restraints
- Specialized Talent Scarcity:Protein purification scientists with mammalian platform expertise command premium compensation, constraining mid-tier suppliers' ability to scale technical operations.
- Chinese Import Registration Burden:NMPA's tightened biological reagent import requirements are extending qualification timelines by 12-18 months for foreign manufacturers lacking domestic manufacturing partnerships.
- Recombinant Expression Cost Structure:HEK293 and CHO cell culture media components, particularly serum-free formulations, exhibit price volatility tied to specialty chemical supply chains.
Strategic Opportunities
- India Contract Research Expansion:CDSCO's streamlined biological reagent import pathways and the country's PLI scheme for biopharma manufacturing are attracting regional distribution hub investments.
- AI-Driven Protein Engineering:Machine learning platforms for codon optimization and structure prediction are converging with automated high-throughput screening, compressing lead candidate development cycles.
- ISO 13485 Certification Arbitrage:Suppliers achieving medical device quality system alignment can access therapeutic-adjacent procurement budgets that command 40-60% pricing premiums over research-use-only tiers.
Industry Challenges
- Multi-Jurisdiction Qualification Redundancy:Divergent documentation requirements across FDA, EMA, and NMPA are forcing suppliers to maintain parallel quality systems, eroding margin pools through compliance overhead.
- Legacy Integration Friction:Biopharmaceutical buyers with entrenched LIMS and ELN infrastructures face workflow disruption when onboarding suppliers with incompatible data formats or certificate structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Research-Grade Proteins Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant Proteins, Monoclonal Antibodies, Polyclonal Antibodies, Cytokines Application: Research, Diagnostics, Therapeutics, Industrial End User: Academic Institutions, Pharmaceutical Companies, Biotechnology Firms, Research Laboratories Form: Lyophilized, Liquid, Powder, Concentrated |
| Companies Covered | Thermo Fisher Scientific, Inc., Bio-Techne Corporation, Miltenyi Biotec, GenScript, Abcam Plc, Proteintech Group, Inc., ACROBiosystems, Sino Biological, Inc., ProSpec-Tany TechnoGene Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Research-Grade Proteins Market Evolving Landscape
Automation and digitization are penetrating upstream bioprocessing, compressing development timelines while elevating the technical threshold for supplier competitiveness.
Single-use bioreactor technology is bifurcating the supplier landscape into scale leaders with disposable platform expertise and legacy stainless-steel operators facing facility write-down pressure. Cell therapy CDMOs are adopting these systems at accelerating pace to minimize cross-contamination risk in multi-product suites. This technology shift is compressing the viable supplier base by disqualifying capital-constrained competitors unable to revalidate on disposable architectures.
EMA's evolving ATMP guidelines are tightening traceability requirements for ancillary materials used in advanced therapy medicinal product development. Suppliers must now demonstrate chain-of-custody documentation from expression vector through final fill-finish, elevating record-keeping infrastructure investments. European biopharmaceutical buyers are responding by consolidating procurement with vendors holding pre-qualified ATMP material designations.
Certificate-of-analysis unbundling is emerging as a procurement pattern among large biopharmaceutical accounts, with buyers negotiating à-la-carte documentation tiers rather than accepting bundled premium pricing. Traditional distributors with fixed service-cost structures are losing share to direct-manufacturer relationships and specialized reagent marketplaces. This behavioral shift is most pronounced in the United States and Germany, where procurement functions have centralized category management authority.
Research-Grade Proteins Market Segmentation
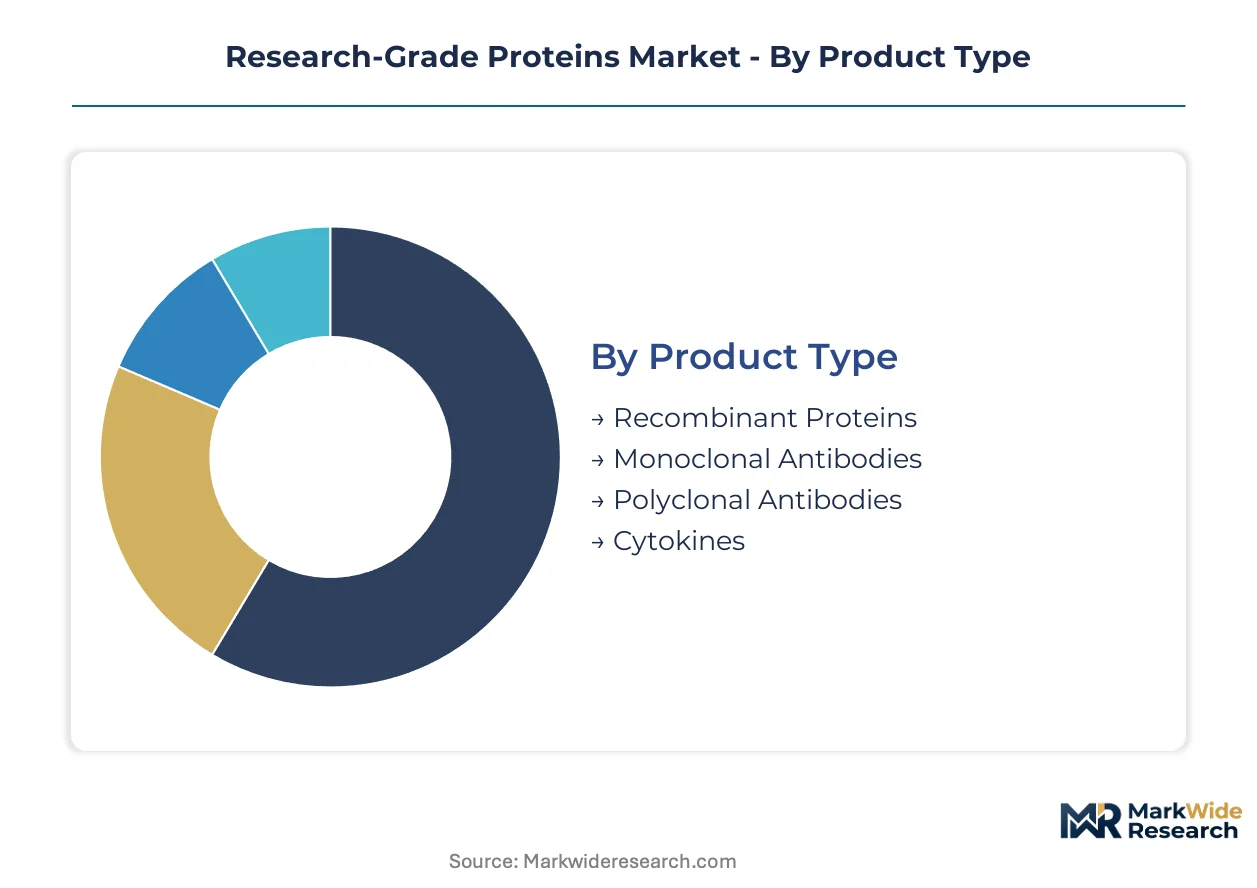
Research-grade proteins segment along four intersecting dimensions that determine procurement pathways, documentation burdens, and margin structures. Regulatory tiering across product types creates distinct qualification thresholds, while application specificity dictates purity specifications and batch-to-batch consistency requirements.
Product Type:
FDA's evolving oversight of ancillary materials for cell and gene therapy development has stratified quality system requirements across protein categories, with GMP-adjacent documentation tiers commanding substantial pricing premiums.
- Recombinant Proteins:Engineered biomolecules produced through microbial or mammalian expression systems exhibit batch-to-batch consistency exceeding 95 percent purity via SDS-PAGE verification. Demand concentrates among biopharmaceutical companies scaling autologous and allogeneic cell therapy pipelines, where ISO 13485-certified precursors pull through from research-grade into therapeutic-adjacent procurement tiers.
- Cytokines:Small signaling proteins regulating immune cell differentiation and proliferation dominate immuno-oncology target validation workflows. United States-based research institutions and German biotech clusters drive fastest expansion as CAR-T and TCR therapy programs multiply, with suppliers competing on endotoxin specification tightening below 0.1 EU per microgram.
- Monoclonal Antibodies:Highly specific immunoglobulins manufactured through hybridoma or recombinant platforms for assay development and mechanism-of-function studies.
- Polyclonal Antibodies:Heterogeneous antibody populations raised in host animals, serving lower-cost diagnostic and research applications with reduced specificity requirements.
Established volume favors recombinant proteins; emerging adoption favors cytokines.
Application:
Cost tiering separates premium documentation grades from research-use-only specifications, with therapeutic-adjacent positioning requiring 40-60 percent pricing premiums to cover quality system overhead.
- Research:Non-clinical investigation encompassing target validation, assay development, and mechanism-of-function studies constitutes the foundational demand layer. Academic institutions in the United States, Germany, and China fragment procurement across numerous small accounts, while pharmaceutical companies concentrate highest per-account spending.
- Therapeutics:Cell and gene therapy manufacturing inputs demand GMP-adjacent documentation with chain-of-custody traceability from expression vector through final fill-finish. EMA's tightening ATMP guidelines and FDA's ancillary materials framework filter procurement toward pre-qualified vendors, consolidating volume with ISO 13485-certified suppliers.
- Diagnostics:Immunoassay components for clinical and research-use detection platforms require lot-to-lot consistency but tolerate lower purity thresholds than therapeutic tiers.
- Industrial:Bioprocessing enzymes and biocatalysts for manufacturing applications prioritize yield scalability over characterization depth.
Research commands absolute volume; therapeutics commands fastest margin expansion.
End User:
Customer type determines procurement centralization, with pharmaceutical buyers consolidating category management authority while academic accounts fragment across decentralized purchasing.
- Pharmaceutical Companies:Vertically integrated drug developers and cell therapy CDMOs drive premium pricing for GMP-adjacent documentation. These buyers negotiate certificate-of-analysis unbundling and à-la-carte documentation tiers, bypassing traditional distributors for direct-manufacturer relationships.
- Biotechnology Firms:Venture-funded development-stage companies concentrate in Boston, San Francisco, and Shanghai clusters, prioritizing speed-to-clinic over cost optimization in protein procurement.
- Academic Institutions:University and government research laboratories represent the most fragmented buyer segment with decentralized purchasing authority and extended qualification timelines.
- Research Laboratories:CRO and independent testing facilities serving pharmaceutical and diagnostic clients with standardized assay protocols.
Pharmaceutical concentration favors margin; academic fragmentation favors volume scale.
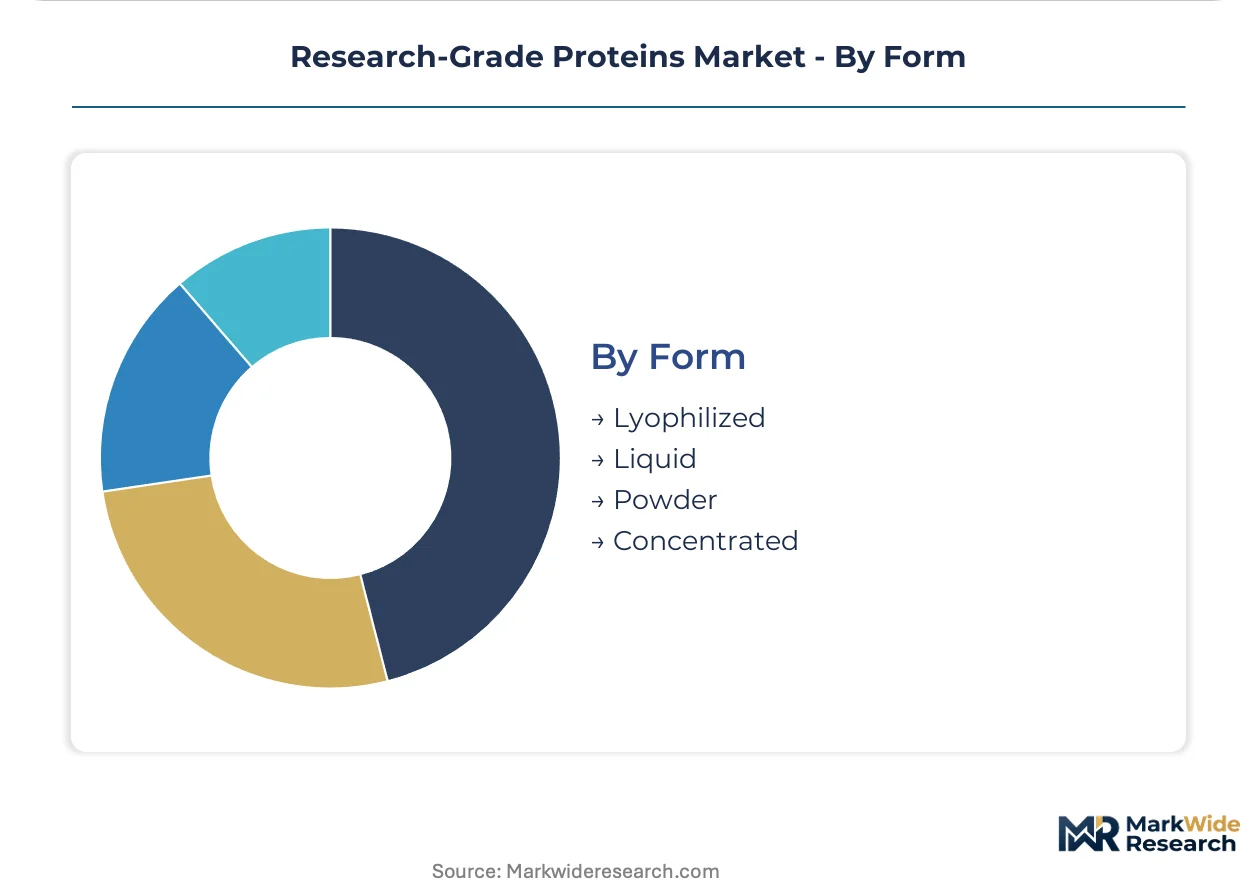
Form:
Supply chain configuration determines viable form factors, with lyophilized formats enabling ambient distribution to China and India while liquid formulations demand cold-chain infrastructure.
- Lyophilized:Freeze-dried presentations eliminate cold-chain dependency, reducing distribution cost to NMPA-regulated Chinese markets and CDSCO-monitored Indian procurement channels. Stability advantages support extended shelf life for catalog-based distribution models.
- Liquid:Ready-to-use formulations minimize reconstitution variability in high-throughput screening workflows. United States and German biopharmaceutical buyers prefer liquid formats for automated liquid handling integration, accepting cold-chain cost for operational efficiency.
- Powder:Bulk unpurified or partially processed intermediates for downstream formulation by specialized manufacturers.
- Concentrated:High-titer preparations reducing shipping volume and storage footprint for industrial-scale bioprocessing applications.
Lyophilized dominates cross-border distribution; liquid anchors premium workflow integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: United States and German buyers prioritize GMP-adjacent documentation for therapeutic pipelines, while Chinese and Indian procurement emphasizes cost-engineered catalog distribution with ambient-stable lyophilized formats.
United States
FDA's ancillary materials guidance for cell and gene therapy inputs drives biopharmaceutical companies toward ISO 13485-certified suppliers with chain-of-custody documentation. The Boston-Cambridge cluster concentrates CAR-T therapy developers scaling autologous manufacturing, pulling premium-priced research-grade precursors into GMP-adjacent procurement tiers.
Germany
EMA's tightening ATMP guidelines filter procurement toward pre-qualified vendors serving advanced therapy medicinal product development. The Munich-Heidelberg biotech corridor anchors European demand for cytokines in TCR therapy programs, with buyers negotiating certificate-of-analysis unbundling for cost optimization.
China
NMPA's tightened biological reagent import registration redirects procurement toward domestic manufacturers with certified quality systems. The Yangtze River Delta biotech hubs in Shanghai and Suzhou expand mammalian expression capacity to serve local cell therapy CDMOs, compressing foreign supplier market access timelines by 12-18 months.
India
CDSCO's streamlined import pathways and the PLI scheme for biopharma manufacturing attract regional distribution hub investments. The Hyderabad-Bengaluru corridor scales contract research operations, with procurement gravitating toward lyophilized formats that eliminate cold-chain dependency for ambient distribution.
Japan
PMDA's alignment with ICH quality guidelines elevates documentation standards for therapeutic-adjacent protein supply. The Kanto region's Tokyo-Yokohama biotech cluster concentrates regenerative medicine research, driving demand for endotoxin-specified cytokines in iPSC-derived cell therapy development.
Research-Grade Proteins Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages in end-to-end workflow integration separating high-volume recombinant protein suppliers from boutique cytokine catalog operators. The competitive terrain stratifies into three archetypes: diversified life science conglomerates with disposable bioreactor platforms, catalog-deep specialists in growth factor subsets, and cost-engineered mammalian expression houses. Consolidation pressure intensifies through M&A activity targeting ISO 13485-certified assets, while capacity expansion focuses on single-use bioreactor validation to serve cell therapy CDMO procurement.
Within the diversified conglomerate tier, Thermo Fisher Scientific anchors scale leadership through workflow integration breadth. Bio-Techne Corporation exemplifies the catalog-specialist archetype with concentrated positioning in cytokine and growth factor subsets. Sino Biological occupies the cost-engineered expression tier, competing on mammalian platform efficiency for antibody reagent supply. These three entities collectively represent the competitive vectors reshaping supplier qualification criteria across United States, German, and Chinese procurement channels.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| Bio-Techne Corporation |
| Miltenyi Biotec |
| GenScript |
| Abcam Plc |
| Proteintech Group, Inc. |
| ACROBiosystems |
| Sino Biological, Inc. |
| ProSpec-Tany TechnoGene Ltd. |
| Others |
Value Network & Pricing Analysis
Capacity utilization at ISO 13485-certified mammalian facilities concentrates pricing power among scale leaders while compressing margin pools for mid-tier suppliers unable to absorb quality system overhead. United States and German biopharmaceutical buyers negotiate certificate-of-analysis unbundling that separates GMP-adjacent documentation premiums from research-use-only base pricing, forcing suppliers to defend position through workflow integration rather than bundled service markups.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between cell therapy CDMOs and qualified protein suppliers, insulating volume commitments from spot-market volatility in HEK293 and CHO culture media inputs. Price differentiation rests on ISO 13485 certification tier and endotoxin specification stringency, with therapeutic-adjacent grades commanding substantial premiums over research-use-only equivalents. Cost compression in standard-grade recombinant proteins intensifies as Sino Biological and domestic Chinese manufacturers expand mammalian platform capacity. Academic institutions exhibit highest price sensitivity, while pharmaceutical companies prioritize batch-to-batch consistency and chain-of-custody documentation over unit cost optimization.
Supply Chain Analysis
Inventory lead times for serum-free media components extend supplier working capital cycles, particularly for foreign manufacturers navigating NMPA's 12-18 month import registration timelines in China. Manufacturing concentration clusters in the United States, Germany, and China, with the Yangtze River Delta and Boston-Cambridge corridors anchoring mammalian expression capacity. Raw material dependencies center on recombinant insulin, transferrin, and chemically defined lipid formulations sourced from specialty chemical suppliers. Single-source vulnerability in CHO cell line licensing creates qualification risk for suppliers lacking in-house expression vector development. Distribution runs through direct-manufacturer relationships for large biopharmaceutical accounts, while academic procurement fragments across specialized reagent marketplaces and traditional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic biology platforms and AI-designed protein scaffolds threaten incumbent recombinant protein suppliers with functional substitution, compelling defensive consolidation around certification assets and workflow integration capabilities.
For Market Incumbents: Consolidate ISO 13485-certified manufacturing assets to defend therapeutic-adjacent procurement tiers from emerging CDMO-backed suppliers. Acquire single-use bioreactor validation expertise to maintain qualification status with cell therapy manufacturers. Vertical integration into expression vector development reduces CHO cell line licensing vulnerability. Priority investment targets mammalian platform capacity in the Yangtze River Delta to circumvent NMPA import barriers. For New Entrants and Emerging Players: Lead with cost-engineered cytokine catalogs targeting academic institutions in India and Southeast Asia, where CDSCO's streamlined import pathways and ambient-stable lyophilized formats eliminate cold-chain infrastructure requirements. Penetrate the fragmented research-use-only segment through AI-driven codon optimization services that compress lead candidate development cycles for biotechnology firms. Go-to-market positioning emphasizes endotoxin specification tightening below 0.1 EU per microgram as a quality discriminator against established catalog suppliers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified life science conglomerates with disposable bioreactor platforms over stainless-steel legacy operators facing facility write-down pressure. Long-term viability concentrates in suppliers achieving medical device quality system alignment that accesses 40-60 percent pricing premiums. Acquisition target archetype: ISO 13485-certified mammalian expression houses with pre-qualified ATMP material designations serving European cell therapy CDMOs. Signal to watch: EMA's evolving traceability requirements accelerating procurement consolidation toward vendors with chain-of-custody infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Expansion | Opens therapeutic-adjacent procurement budgets with GMP-aligned documentation tiers. |
| Single-Use Bioreactor Validation | Qualifies suppliers for cell therapy CDMO procurement minimizing cross-contamination risk. |
| AI-Driven Protein Engineering | Compresses lead candidate development cycles through machine learning codon optimization. |
| Regional Distribution Hub Investment | Circumvents NMPA import delays through CDSCO-monitored Indian manufacturing partnerships. |
| Certificate-of-Analysis Unbundling | Responds to biopharmaceutical procurement centralization with à-la-carte documentation tiers. |
Research Methodology
The analysis maps recombinant proteins, cytokines, monoclonal antibodies, and polyclonal antibodies, each validated through protein purification scientists, regulatory affairs leads at biopharmaceutical companies, academic laboratory procurement managers, and cell therapy CDMO supply chain directors. Primary interview insights triangulate against FDA guidance documents, EMA ATMP submissions, NMPA import registration filings, and CDSCO biological reagent pathway records. Secondary validation draws from ISO certification databases, SEC 10-K disclosures, and trade customs data. Bottom-up segment sizing reconciles with top-down market boundary analysis.
Consistency checks validate volume and value outputs against external benchmarks including supplier capacity disclosures and biopharmaceutical R&D expenditure patterns. The analytical framework models product type, application tier, end-user concentration, and supply chain form factor across the projection horizon. CAGRs derive from segment-level growth rate reconciliation with macroeconomic healthcare research funding trajectories. Forecast inputs incorporate cell therapy pipeline expansion rates and regulatory documentation burden evolution.
The analysis sits within stated boundaries; outcomes outside sustained biopharmaceutical R&D funding growth or accelerated regulatory harmonization would require recalibration. Forecasts reflect assumptions regarding ISO 13485 adoption velocity and single-use bioreactor penetration timelines. Specific risks include NMPA regulatory divergence, specialty chemical supply disruption, and synthetic biology platform substitution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Global Genetically Modified (GMO) Food Market
Food Biotechnology
Papain Market
Food Biotechnology
Europe Eubiotics Market
Food Biotechnology
Biopreservation Market
Food Biotechnology
Perilla Protein Market
Food Biotechnology
Hemoglobin Feed Market
Food Biotechnology
Global GMO Testing Market
Food Biotechnology
Trypsin Market
Food Biotechnology
Prebiotics Market
Food Biotechnology
Carbohydrate Enzyme Preparation Market
Food Biotechnology
Asia Pacific Eubiotics Market
Food Biotechnology
Africa Eubiotics Market
Food Biotechnology
Chlorella Market
Food Biotechnology
Beta Lactoglobulin Protein Market
Food Biotechnology
Microalgae Market
Food Biotechnology
Genistein Market