
 Global Protein Labeling Market | 2026-2036
Global Protein Labeling Market Size, Share, and Industry Trends Forecast 2026-2036
Global Protein Labeling Market Outlook
A shift from single-source antibody supply toward multi-vendor bioconjugation strategies is decoupling procurement risk from discovery timelines. Thermo Fisher Scientific leverages its reagent-to-instrument ecosystem to control workflow standardization across customer labs. Merck KGaA anchors its position through captive production of activated dyes and crosslinkers. Danaher competes by extending its life sciences platform into automated protein analysis systems.
Protein labeling encompasses the covalent attachment of detectable tags—fluorophores, enzymes, radioisotopes, or affinity molecules—to amino acid side chains for subsequent visualization, quantification, or purification. The process typically targets lysine epsilon-amines, cysteine thiols, or N-terminal amines under controlled pH and molar excess conditions to preserve protein function. Fluorescent dyes occupy the largest product category due to their compatibility with live-cell imaging and high-throughput screening platforms. Mass spectrometry is displacing older detection modalities in quantitative proteomics workflows, while label-free technologies are gaining share where minimal sample perturbation is required.
The FDA enforces current Good Manufacturing Practice standards for diagnostic-grade labeled antibodies, while the EMA's In Vitro Diagnostic Regulation tightens performance documentation for reagents sold in Europe. China's NMPA now requires domestic registration of imported labeling kits used in clinical applications, reshaping market access for foreign suppliers. ISO 13485 certification has become a baseline qualification for vendors serving regulated end users. Stakeholders must weigh regional compliance burdens against the cost of maintaining parallel product formulations for divergent standards.
Market Dynamics
The pharmaceutical industry's pivot toward antibody-drug conjugates is compressing discovery timelines and forcing bioconjugation capabilities back into sponsor facilities, restructuring vendor relationships across the protein labeling value chain.
Growth Catalysts
- Biologics manufacturing expansion:Contract development organizations in Germany, China, and the United States are scaling GMP-grade labeling capacity to support Phase III ADC programs. This infrastructure buildout pulls through demand for activated dyes and crosslinking chemistries.
- EMA In Vitro Diagnostic Regulation:The 2022 IVDR implementation mandates performance documentation for labeled antibodies used in clinical diagnostics, creating replacement demand for validated reagent portfolios across European reference laboratories.
- Live-cell imaging workflows:CRISPR-mediated endogenous tagging is displacing overexpression systems in academic screening programs, requiring new labeling chemistries compatible with low-copy protein detection.
Market Restraints
- Specialized dye supply concentration:Activated cyanine and BODIPY fluorophores depend on captive synthesis capabilities concentrated among three European chemical suppliers, exposing procurement to single-source risk.
- Radioisotope logistics complexity:Iodine-125 and tritium labeling services face shrinking carrier networks and escalating waste disposal costs, compressing margins for legacy radiometric assay providers.
- Label-free displacement:Surface plasmon resonance and bio-layer interferometry are capturing share in kinetic characterization applications where fluorescent tags perturb binding kinetics.
Strategic Opportunities
- India biologics manufacturing:The country's PLI scheme for pharmaceuticals is attracting fill-finish investment from multinational sponsors, creating demand for localized labeling kit registration and technical support infrastructure.
- Single-domain antibody conjugation:Nanobody labeling for tissue penetration applications remains technically underserved, with few validated protocols for cysteine-engineered VHH formats.
- ISO 13485 certification gap:Mid-size reagent vendors without diagnostic-grade quality systems face exclusion from hospital procurement panels, creating acquisition targets for platform companies seeking regulated market access.
Industry Challenges
- Bioconjugation chemist scarcity:The specialized skill set spanning protein chemistry, analytical characterization, and regulatory documentation commands premium compensation, constraining capacity expansion at CDMOs.
- Legacy instrument compatibility:Automated labeling workstations must interface with decade-old HPLC and mass spectrometry infrastructure prevalent in academic core facilities, complicating workflow integration.
- Dual-use export controls:Certain heterobifunctional crosslinkers face licensing requirements under national security frameworks, delaying international shipment and complicating global study coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Protein Labeling Market |
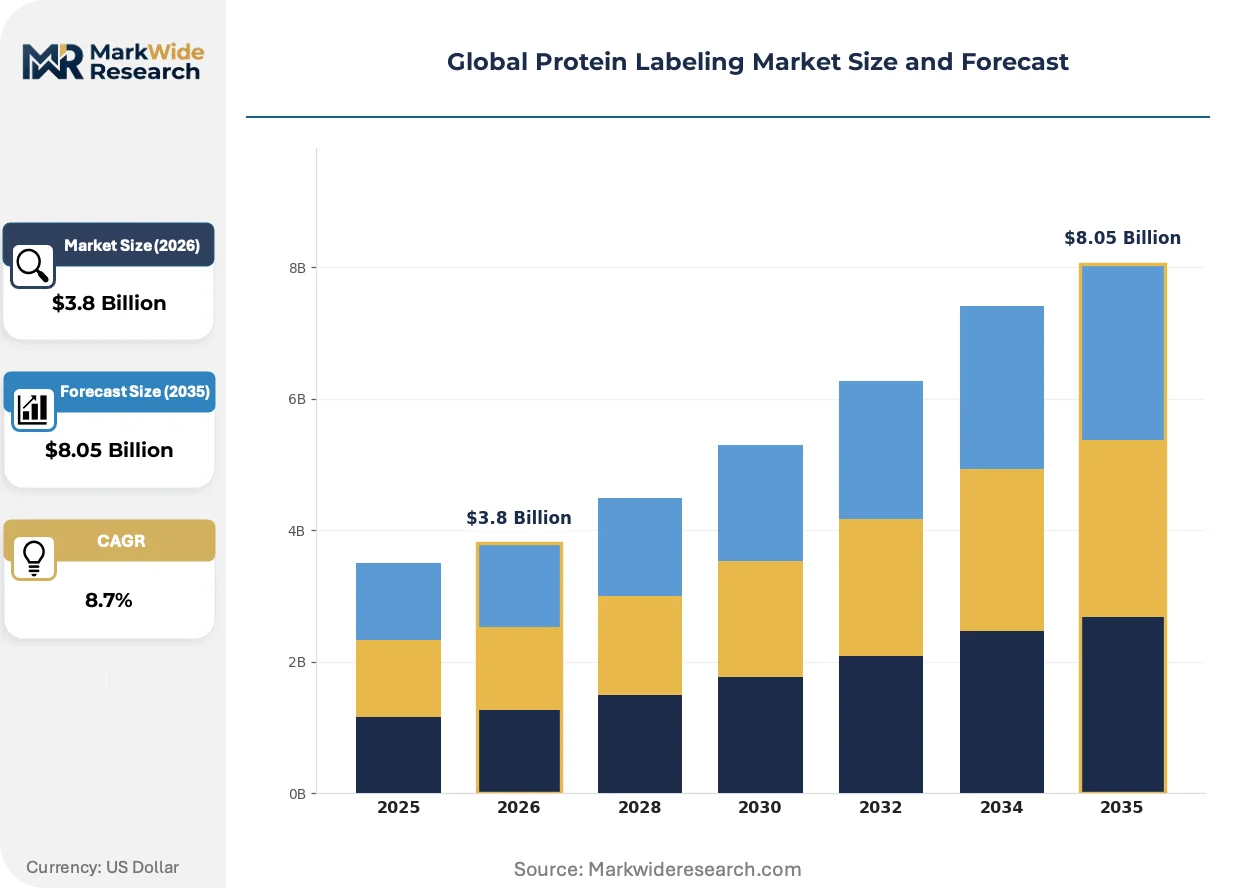
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
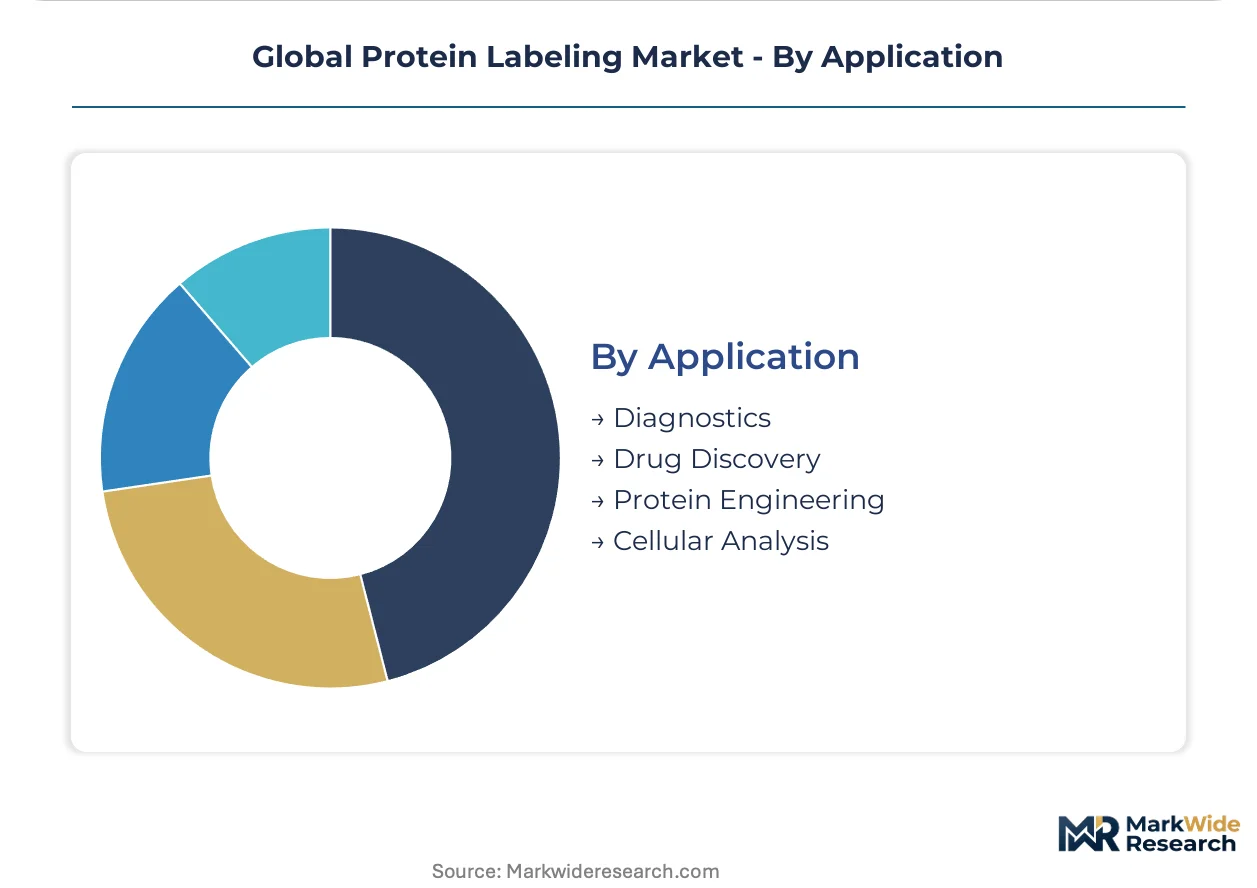
| Segmentation | Product Type: Fluorescent Dyes, Enzymes, Biotin, Isotopes Technology: Mass Spectrometry, Nuclear Magnetic Resonance, Label-Free, Western Blotting End User: Pharmaceutical Companies, Academic Research Institutions, Contract Research Organizations, Hospitals Application: Diagnostics, Drug Discovery, Protein Engineering, Cellular Analysis |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, F. Hoffmann-La Roche AG, PerkinElmer, Promega, Danaher, Bio-Rad Laboratories, New England Biolabs, LI-COR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Protein Labeling Market Strategic Shifts
Quantitative proteomics instrumentation is reshaping detection modality preferences, while regulatory documentation requirements and procurement centralization are restructuring how labeling reagents reach end users.
Site-specific conjugation via enzymatic labeling is consolidating technical preference in ADC manufacturing workflows. Contract manufacturers serving oncology sponsors are abandoning stochastic lysine conjugation for transglutaminase and sortase-mediated approaches that yield defined drug-to-antibody ratios. This shift is compressing demand for traditional N-hydroxysuccinimide ester chemistries while expanding the enzyme and engineered substrate market.
China's NMPA now requires domestic registration of imported labeling kits used in clinical applications, forcing foreign suppliers to establish local legal entities and quality representatives. The regulation fragments product portfolios as manufacturers maintain separate formulations for registered and research-use-only channels. Multinational reagent vendors are responding by acquiring Chinese distributors with established regulatory affairs capabilities.
Academic core facilities are consolidating procurement through shared services organizations that negotiate enterprise pricing across multiple institutions. This concentration shifts purchasing authority from individual principal investigators to procurement professionals who prioritize vendor interoperability and training support. The pattern is most visible in the United States, where National Institutes of Health funding pressures are accelerating shared instrumentation models.
Global Protein Labeling Market Segmentation
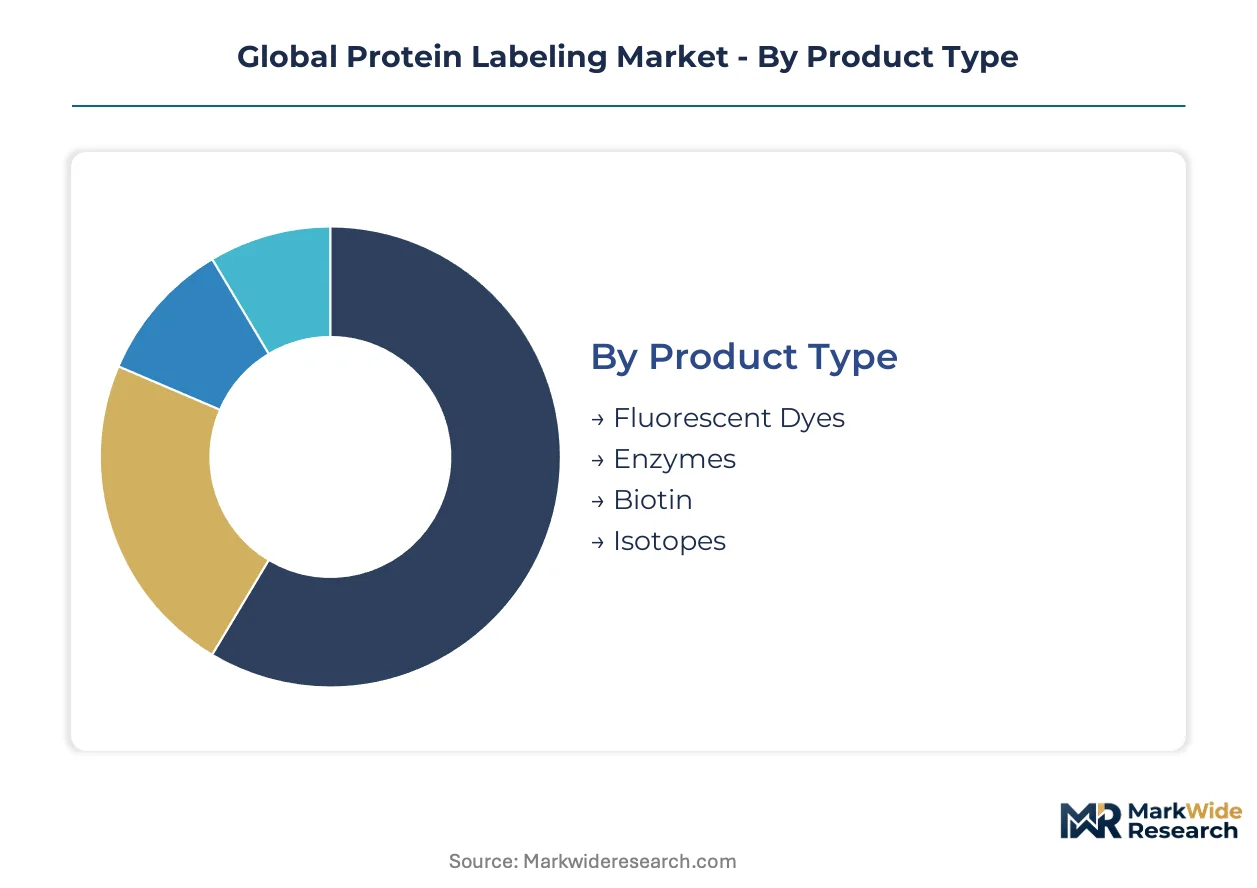
Protein labeling procurement decisions hinge on detection sensitivity requirements, regulatory compliance burdens, and integration with existing analytical infrastructure. Segment boundaries blur when pharmaceutical sponsors demand GMP-grade reagents for clinical manufacturing while academic users prioritize multiplexing flexibility.
Product Type:
Cost tier determines access to validated supply chains and technical support depth.
- Fluorescent Dyes:Cyanine, BODIPY, and Alexa Fluor variants dominate live-cell imaging and flow cytometry workflows. Demand concentrates in United States biologics manufacturing clusters where antibody-drug conjugate programs require precise drug-to-antibody ratio control.
- Enzymes:Horseradish peroxidase and alkaline phosphatase conjugates serve ELISA and chemiluminescence detection platforms. German diagnostic manufacturers anchor European procurement volumes under EMA In Vitro Diagnostic Regulation compliance requirements.
- Biotin:Streptavidin-biotin affinity systems enable signal amplification in immunohistochemistry and surface plasmon resonance assays.
- Isotopes:Iodine-125 and tritium labels face contracting carrier networks and escalating disposal costs in radiometric assay applications.
Fluorescent dyes lead on scale; enzymes lead on momentum in regulated diagnostic manufacturing.
Technology:
Application specificity drives modality selection between quantitative precision and sample preservation priorities.
- Mass Spectrometry:SILAC and iTRAQ labeling enable multiplexed quantitative proteomics with amino acid resolution. Academic core facilities in China are displacing older Western blotting workflows as instrument access expands through shared services organizations.
- Label-Free:Surface plasmon resonance and bio-layer interferometry capture kinetic characterization demand where fluorophores perturb binding equilibria. Contract research organizations favor these platforms for fragment screening campaigns.
- Nuclear Magnetic Resonance:Isotope-edited NMR structural biology requires 13C and 15N metabolic labeling in specialized expression systems.
- Western Blotting:Chemiluminescent and fluorescent secondary antibody detection persists in validation workflows despite proteomics displacement.
Mass spectrometry commands the largest installed base; label-free platforms are expanding most quickly in biopharma screening.
End User:
Customer type stratifies purchasing authority between centralized procurement and principal investigator discretion.
- Pharmaceutical Companies:In-house bioconjugation capabilities for antibody-drug conjugate manufacturing demand GMP-grade activated dyes and crosslinkers with full regulatory documentation.
- Contract Research Organizations:CDMOs in Germany, China, and the United States scale Phase III ADC labeling capacity, pulling through enzyme and site-specific conjugation chemistries.
- Academic Research Institutions:CRISPR-mediated endogenous tagging programs drive demand for low-copy detection sensitivity in shared core facilities.
- Hospitals:Clinical laboratories require ISO 13485-certified reagents under FDA diagnostic-grade standards and China's NMPA domestic registration mandates.
Pharmaceutical companies dominate value capture; contract research organizations are gaining share fastest as manufacturing outsourcing accelerates.
Application:
Maturity curves separate established diagnostic revenue from emerging therapeutic development workflows.
- Diagnostics:FDA-enforced current Good Manufacturing Practice standards and EMA IVDR performance documentation requirements create replacement demand for validated labeled antibody portfolios across reference laboratories.
- Drug Discovery:High-throughput screening and target validation workflows consume fluorescent dye libraries and automated labeling workstations.
- Protein Engineering:Site-specific conjugation via transglutaminase and sortase enzymes yields defined drug-to-antibody ratios in oncology candidate optimization.
- Cellular Analysis:Live-cell imaging and single-molecule tracking require photostable fluorophores compatible with minimal perturbation protocols.
Diagnostics anchors revenue stability; protein engineering shows the steepest expansion trajectory as ADC pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States biologics manufacturing corridor stretching from Boston to San Diego anchors global procurement of GMP-grade protein labeling reagents. Contract development organizations in Germany and China are scaling equivalent capacity to capture antibody-drug conjugate outsourcing demand. Regulatory divergence across FDA, EMA, and NMPA jurisdictions is fragmenting product formulations and compliance documentation requirements.
United States
Pharmaceutical sponsors in Massachusetts and California are building in-house bioconjugation suites to compress ADC discovery timelines. FDA diagnostic-grade current Good Manufacturing Practice standards enforce batch documentation for labeled antibodies entering clinical workflows. The San Diego-Torrey Pines cluster hosts specialized CDMOs scaling Phase III manufacturing capacity.
Germany
Contract manufacturers in Bavaria and North Rhine-Westphalia are expanding GMP-grade labeling infrastructure for European oncology programs. EMA In Vitro Diagnostic Regulation mandates performance documentation for clinical diagnostic reagents, creating replacement demand across reference laboratories. The Munich biotech corridor concentrates activated dye synthesis capabilities serving both domestic and export markets.
China
NMPA domestic registration requirements for imported clinical labeling kits are forcing foreign suppliers to establish local legal entities and quality representatives. The Suzhou and Shanghai biologics manufacturing clusters are attracting multinational fill-finish investment under the country's pharmaceutical production incentives. Domestic reagent vendors are acquiring regulatory affairs capabilities to bridge compliance gaps.
India
The pharmaceutical production-linked incentive scheme is attracting fill-finish investment from multinational sponsors into Maharashtra and Gujarat. CDSCO oversight of imported diagnostic reagents creates registration barriers that local technical support infrastructure can address. Hyderabad's vaccine manufacturing base is extending into bioconjugation capabilities for export markets.
Switzerland
Specialized chemical suppliers around Basel maintain captive synthesis capabilities for activated cyanine and BODIPY fluorophores. Swissmedic diagnostic-grade standards align with EMA frameworks while permitting earlier market access for validated reagents. The Basel-Zurich corridor serves as a procurement hub for European biopharma sponsors seeking dual-source dye supply security.
Global Protein Labeling Market Competitive Environment
Global majors compete with regional champions across regulatory documentation and technical support depth. The vendor base stratifies into three tiers: diversified life sciences platforms with reagent-to-instrument ecosystems, mid-size reagent specialists with diagnostic-grade quality systems, and regional distributors with localized regulatory affairs capabilities. Dominant competitive moves include acquisition of ISO 13485-certified mid-tier vendors for regulated market access and establishment of Chinese legal entities to satisfy NMPA domestic registration mandates.
Within the diversified platform tier, Thermo Fisher Scientific and Danaher exemplify reagent-to-instrument ecosystem strategies that standardize workflows across customer laboratories. Merck KGaA anchors the captive synthesis archetype through controlled production of activated dyes and crosslinking chemistries. These three companies occupy positions that reflect contrasting approaches to procurement risk management: workflow integration, upstream chemical supply control, and life sciences platform breadth.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| F. Hoffmann-La Roche AG |
| PerkinElmer |
| Promega |
| Danaher |
| Bio-Rad Laboratories |
| New England Biolabs |
| LI-COR |
| Others |
Value Chain & Pricing Dynamics
Activated cyanine and BODIPY fluorophore synthesis costs cascade through three distinct pricing tiers as raw material inputs from Swiss and German chemical suppliers pass through captive production networks before reaching GMP-grade antibody-drug conjugate manufacturers in the United States and China. Procurement officers at pharmaceutical sponsors face escalating pass-through pressure from concentrated dye precursor supply while academic core facilities absorb cost volatility through shared services consolidation.
Pricing Analysis
Input-cost pass-through from specialized dye precursors anchors pricing stratification across premium, standard, and economy tiers. Premium GMP-grade reagents with full FDA batch documentation command substantial markups over research-use-only formulations, while volume scale and ISO 13485 certification status drive secondary differentiation. Pricing pressure stems from bioconjugation chemist scarcity inflating contract manufacturing margins. Contract research organizations exhibit highest price sensitivity due to competitive bidding pressures, whereas pharmaceutical sponsors prioritize supply security over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with activated fluorophore synthesis capabilities concentrated in Switzerland, Germany, and select United States chemical manufacturers. The supply chain draws from cyanine dye precursors, heterobifunctional crosslinkers, and recombinant enzyme stocks as critical inputs. Dual-use export controls on certain crosslinker chemistries create regulatory friction disrupting international shipment coordination. Distribution runs through authorized distributor networks with regional regulatory affairs capabilities, particularly for NMPA-registered channels in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The protein labeling market functions as a regulatory compounder where EMA IVDR implementation and FDA diagnostic-grade enforcement generate sustained replacement demand for validated reagent portfolios across European and North American reference laboratories.
For Market Incumbents: Lock in supply security through captive synthesis of activated dyes and crosslinkers to defend against single-source concentration risk among European chemical suppliers. Extend regulatory documentation capabilities to capture IVDR-mandated performance verification workflows. Prioritize ISO 13485 certification maintenance as hospital procurement panels harden quality system requirements. For New Entrants and Emerging Players: The mid-tier price-point gap between premium GMP-grade reagents and economy research-use-only formulations offers white-space entry for validated standard-grade portfolios targeting contract research organizations. India's PLI-driven biologics manufacturing expansion presents the most penetrable geography for localized technical support infrastructure. Pursue acquisition of Chinese distributors with established NMPA registration capabilities as the primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-size reagent vendors lack diagnostic-grade quality systems yet possess proprietary conjugation chemistries or regional regulatory expertise. Long-term viability centers on platform breadth spanning reagent-to-instrument integration rather than point-product specialization. Watch for inflection where site-specific enzymatic conjugation displaces stochastic chemistries, compressing legacy NHS-ester demand.| Strategic Initiative | Industry Significance |
|---|---|
| Site-Specific Conjugation Platform Development | Transglutaminase and sortase-mediated approaches yield defined drug-to-antibody ratios for oncology sponsors. |
| NMPA Domestic Registration Establishment | Chinese legal entities with quality representatives satisfy clinical labeling kit mandates and unlock hospital procurement. |
| ISO 13485 Certification Acquisition | Diagnostic-grade quality systems secure access to regulated end users under FDA and EMA frameworks. |
| Activated Dye Captive Synthesis | Upstream control over cyanine and BODIPY fluorophores insulates against European supplier concentration risk. |
| Shared Services Organization Partnership | Academic core facility consolidation shifts purchasing authority toward enterprise pricing and vendor interoperability. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with bioconjugation chemists, regulatory affairs specialists at diagnostic manufacturers, CDMO procurement directors, and academic core facility managers with secondary validation against FDA 510(k) filings, EMA IVDR technical documentation, NMPA registration databases, and SEC disclosures from listed life sciences platforms. Bottom-up reagent volume modeling and top-down market sizing triangulated across detection modality adoption curves and end-user spending patterns.
Comparable-period anchoring tied projection assumptions to historical biologics manufacturing expansion trajectories and regulatory implementation timelines across the analysis window. Segmentation dimensions modeled include product type, detection technology, end-user category, application area, and regional regulatory cluster. CAGRs derived from instrument installation base growth, ADC pipeline progression, and validated reagent replacement cycles informed value expansion estimates.
The model assumes a particular technology adoption path; alternative pathways for label-free detection platforms or CRISPR-mediated endogenous tagging would alter the outlook for fluorescent dye demand. Forecasts reflect assumptions about regulatory enforcement consistency, bioconjugation talent availability, and crosslinker export licensing stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Antibodies Contract Manufacturing Market
Biotechnology Services
Global Cell Isolation/Cell Separation Market
Biotechnology Services
Asia-Pacific Biotechnology Market
Biotechnology Services
DNA and RNA Sample Preparation Market
Biotechnology Services
Biotech API Manufacturing Services Market
Biotechnology Services
Phycobiliproteins Market
Biotechnology Services
Global Western Blotting Market
Biotechnology Services
Global Vero Cell Media Market
Biotechnology Services
Industrial Microbiology Testing Services Market
Biotechnology Services
Cell Culture Media Market
Biotechnology Services
Cell Line Development Market
Biotechnology Services
Cell Lysis and Disruption Market
Biotechnology Services
Dnases, Ligases, and RNA Polymerases Market
Biotechnology Services
Cell Characterization Assays Kits Market
Biotechnology Services
Biologics Contract Manufacturing Market
Biotechnology Services
Europe Flow Cytometry Market