
 Global Human DNA Vaccines Market | 2026-2036
Global Human DNA Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Human DNA Vaccines Market Foresight
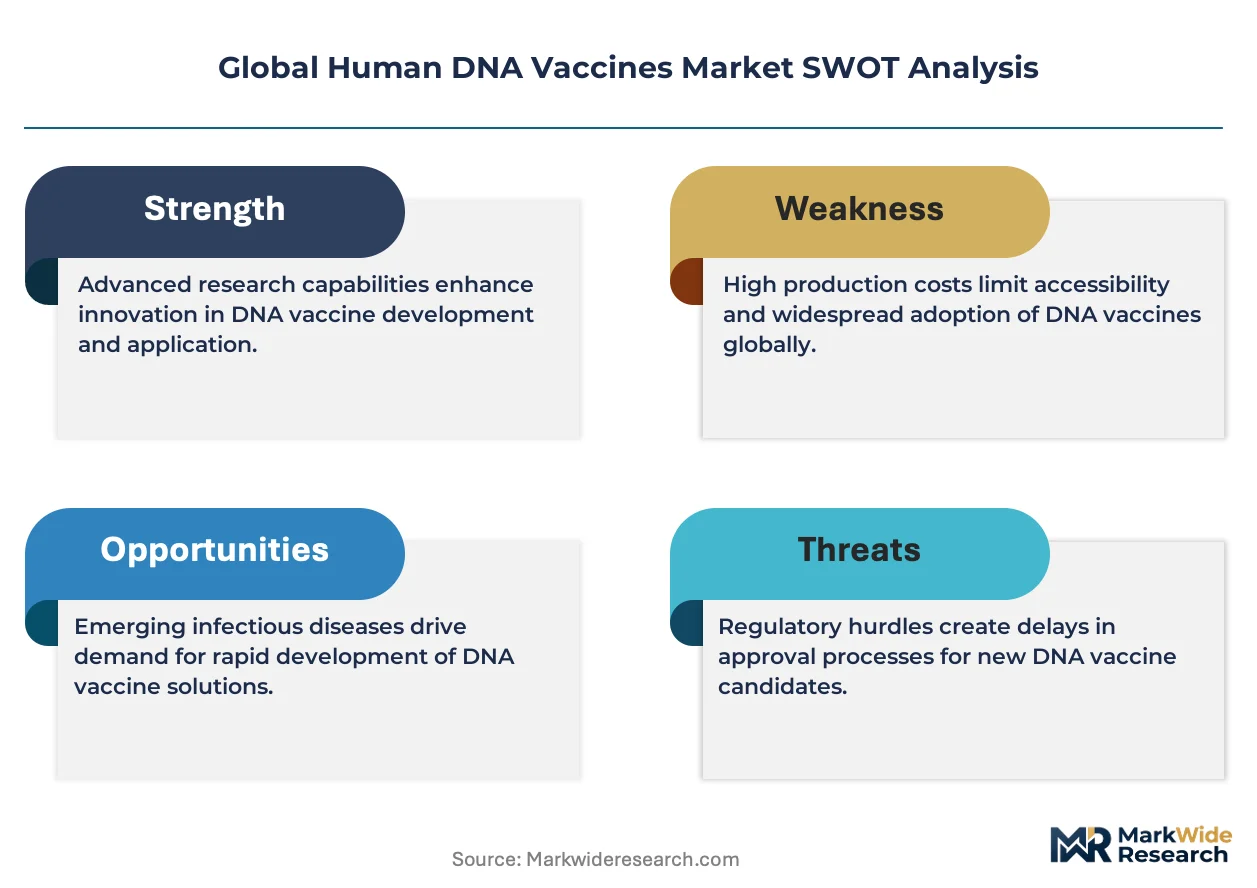
A shortage of GMP-certified nucleic acid manufacturing specialists is collapsing available production capacity across contract development organizations. Inovio Pharmaceuticals leverages proprietary electroporation devices to sustain integrated control over delivery technology. Moderna Therapeutics anchors its pipeline expansion through synthetic biology platforms optimized for rapid antigen design. Genexine Inc. dominates Asian clinical development through regional partnerships with South Korean and Chinese trial networks.
Human DNA vaccines comprise plasmid DNA encoding target antigens, formulated for intracellular expression and subsequent immune priming via major histocompatibility complex presentation, with electroporation or liposomal systems enhancing cellular uptake efficiency. Prophylactic applications currently occupy the largest addressable segment due to infectious disease preparedness mandates from government agencies and WHO pandemic frameworks. Therapeutic DNA vaccines against oncology indications represent the fastest-expanding category, driven by tumor-associated antigen personalization and combination checkpoint inhibitor protocols. Plasmid DNA technology leads manufacturing scale-up, while viral vector platforms compete in immunogenicity optimization.
FDA accelerated approval pathways and EMA adaptive licensing frameworks are reshaping clinical trial design requirements, compressing Phase I-to-approval timelines for breakthrough-designated DNA vaccines. China's NMPA has issued nucleic acid-specific GMP annexes that condition market access on domestic fill-finish capability. India's CDSCO and BIS are harmonizing import testing standards for plasmid raw materials, affecting supply qualification for regional manufacturers. Stakeholders must monitor evolving comparability protocols for biosimilar DNA vaccines as regulatory divergence between FDA and EMA quality guidelines threatens multi-region filing efficiency.
Market Dynamics
Electroporation delivery hardware is compressing development timelines by enabling intracellular plasmid uptake that chemical adjuvants cannot achieve, forcing manufacturers to secure device supply before clinical protocol finalization.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The accelerated approval pathway compresses Phase I-to-approval intervals for oncology DNA vaccines, attracting venture capital toward plasmid platform investments.
- Checkpoint inhibitor combination protocols:Therapeutic DNA vaccines encoding tumor-associated antigens are integrating with pembrolizumab and nivolumab regimens, expanding addressable patient populations beyond monotherapy limits.
- Synthetic biology platforms:Rapid antigen design capabilities are shortening response timelines for emerging infectious threats, aligning with WHO pandemic preparedness frameworks.
Market Restraints
- GMP plasmid manufacturing concentration:Contract development organizations in the United States and Germany control the majority of certified nucleic acid production capacity, creating single-source vulnerability for late-stage trials.
- Electroporation device cost structure:Proprietary delivery hardware requires capital expenditure commitments that mid-cap developers cannot absorb without partnership dilution.
- Cold-chain distribution requirements:Plasmid stability mandates complicate last-mile delivery to tropical and resource-limited regions where infectious disease burden concentrates.
Strategic Opportunities
- China's NMPA nucleic acid GMP annexes:Domestic fill-finish capability requirements are creating partnership openings for contract manufacturers establishing Chinese subsidiary operations.
- Personalized neoantigen vaccines:Tumor sequencing cost declines are enabling patient-specific plasmid design for refractory malignancies, commanding premium reimbursement.
- Needle-free delivery convergence:Microneedle patch platforms combined with electroporation are opening pediatric and needle-averse adult segments previously excluded from DNA vaccine trials.
Industry Challenges
- GMP nucleic acid specialist scarcity:Contract manufacturing organizations report 18-month backlogs for plasmid production slots due to limited regulatory-compliant workforce pipelines.
- Cross-jurisdictional comparability protocols:Divergent FDA and EMA quality guidelines for biosimilar DNA vaccines are forcing redundant stability studies that delay multi-region filings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Human DNA Vaccines Market |
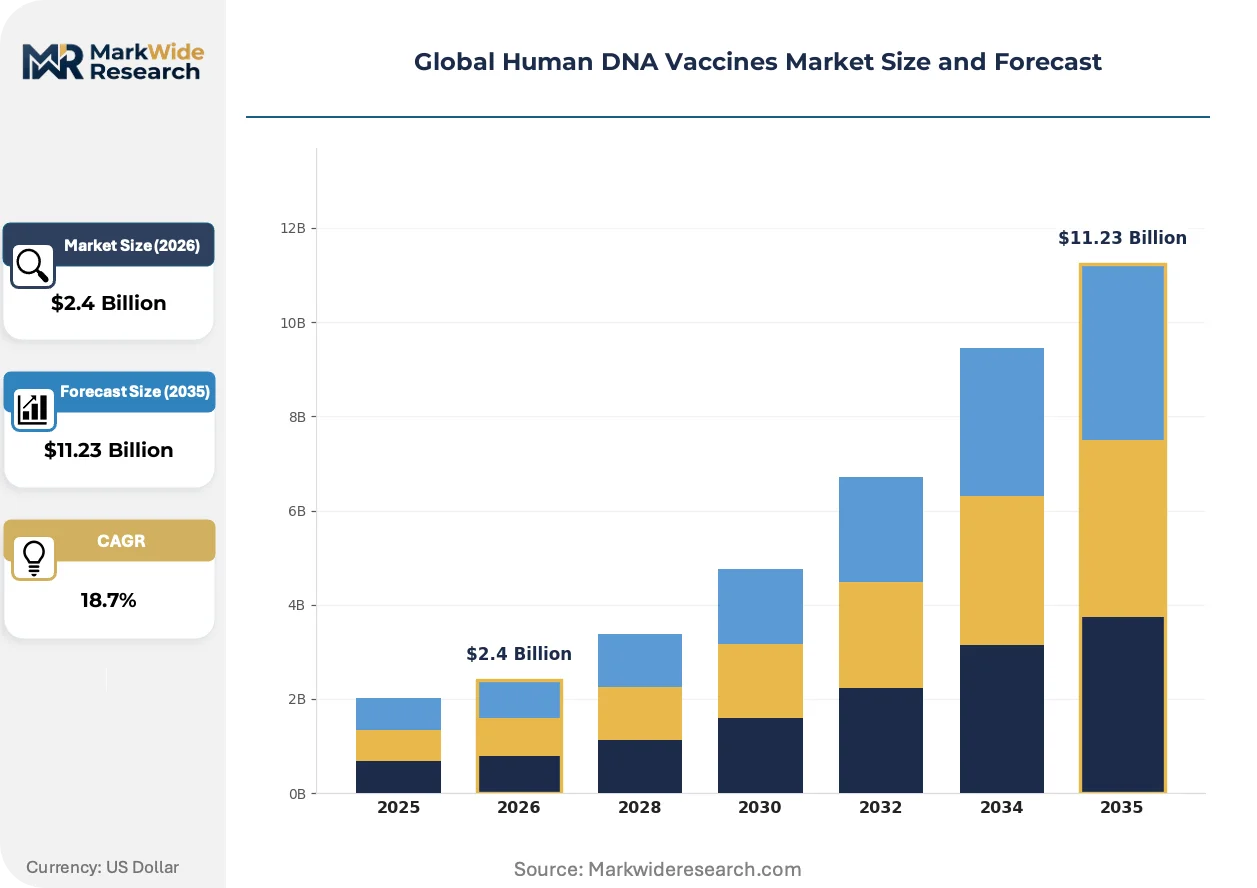
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $11.23 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Prophylactic, Therapeutic, Multivalent, Monovalent, Others Technology Platform: Plasmid DNA, Electroporation, Liposome-Based Delivery, Gene Gun, Viral Vector Application: Infectious Diseases, Oncology, Autoimmune Disorders, Allergy Treatments, Genetic Disorders End User: Research Institutes, Pharmaceutical Manufacturers, Biotechnology Firms, Healthcare Providers, Government Agencies |
| Companies Covered | Moderna Therapeutics, Inovio Pharmaceuticals, GeneOne Life Science, Zydus Cadila Healthcare, Dynavax Technologies, Genexine Inc., Shenzhen Geno-Immune Medical Institute, Applied DNA Sciences, Immunomic Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Human DNA Vaccines Market Shifts & Advancements
Delivery technology miniaturization and regulatory pathway convergence are compressing the traditional vaccine development model, while procurement patterns shift toward integrated platform ownership.
Electroporation hardware is miniaturizing from benchtop clinical devices to handheld field-deployable units. Military and pandemic response agencies are procuring portable systems for rapid-deployment vaccination campaigns. This miniaturization is collapsing the infrastructure requirements for DNA vaccine administration, enabling point-of-care delivery in remote settings previously dependent on centralized cold-chain facilities.
EMA adaptive licensing frameworks are permitting conditional approval based on surrogate immunogenicity endpoints rather than clinical outcome data. Oncology developers are leveraging this pathway to enter revenue-generating phases while confirmatory trials continue. European therapeutic vaccine sponsors are restructuring clinical programs to align with rolling review procedures, compressing regulatory submission preparation timelines.
Biopharmaceutical procurement departments are acquiring captive electroporation device supply rather than relying on third-party lessing arrangements. This shift transfers delivery risk from contract research organizations to vaccine sponsors, concentrating capital deployment in integrated platform control. United States-based developers are prioritizing device supply agreements ahead of IND-enabling toxicology studies to avoid clinical hold delays.
Global Human DNA Vaccines Market Segmentation
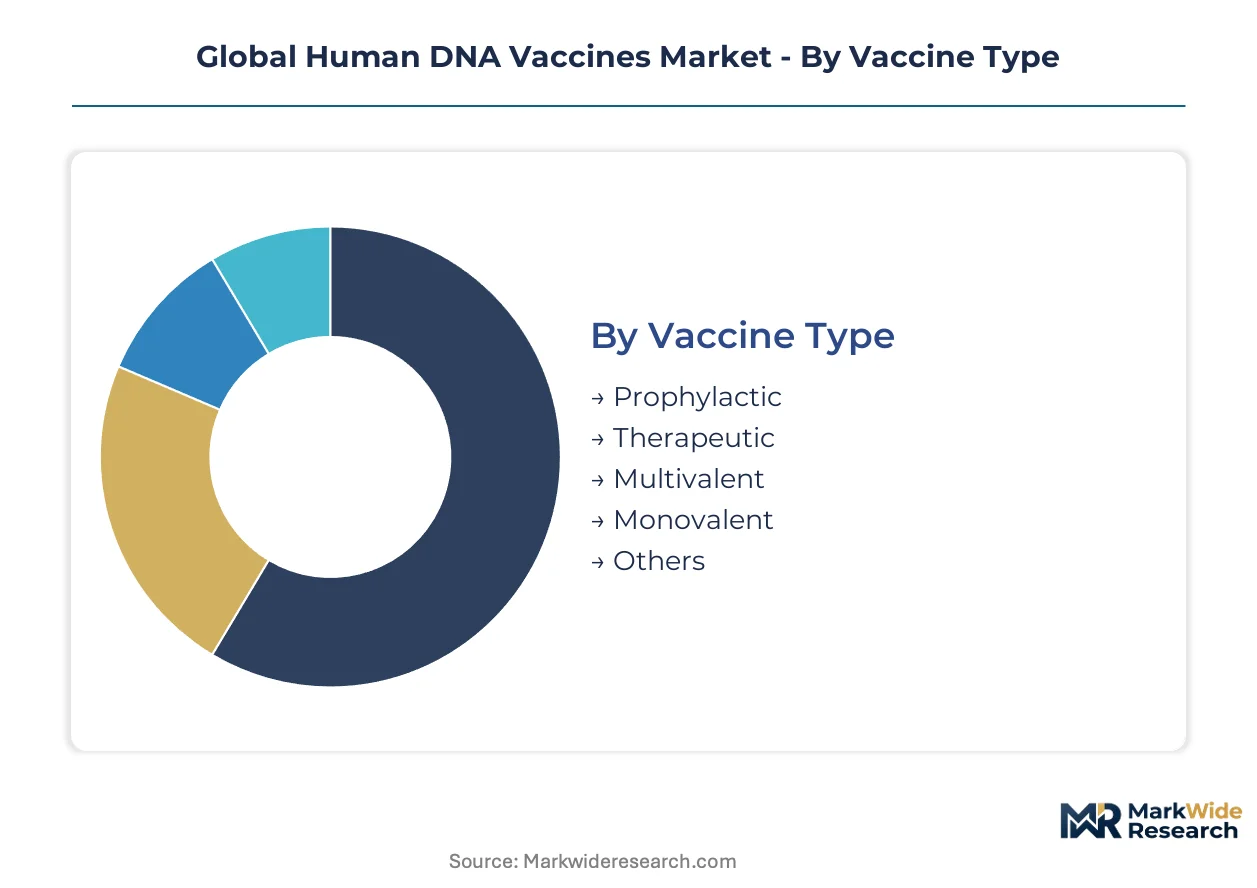
DNA vaccine segmentation reveals distinct procurement channels and development priorities across therapeutic categories. Manufacturers route prophylactic candidates through government stockpiling contracts while oncology programs target hospital infusion centers with companion diagnostic requirements.
Vaccine Type:
Prophylactic and therapeutic segments flow through divergent commercial channels, with government procurement dominating prevention and specialty pharmacy distribution governing cancer applications.
- Prophylactic:Plasmid formulations targeting infectious pathogens before exposure. Demand concentrates in United States and Chinese national stockpiling programs driven by pandemic preparedness mandates from WHO frameworks.
- Therapeutic:Antigen-encoding vaccines administered post-diagnosis to treat established disease. Oncology applications in German and South Korean academic medical centers are expanding fastest through combination checkpoint inhibitor protocols.
- Multivalent:Single-plasmid constructs encoding multiple antigens for complex pathogens.
- Monovalent:Target-specific formulations for homogenous disease threats.
- Others:Emerging formats including self-amplifying RNA-DNA hybrids.
By volume, prophylactic leads. By growth pace, therapeutic is ahead.
Technology Platform:
Platform selection determines capital intensity and partnership structure, with electroporation requiring device integration while plasmid manufacturing permits contract outsourcing.
- Plasmid DNA:Circular bacterial DNA vectors encoding target antigens under eukaryotic promoters. United States contract development organizations and German GMP facilities control production capacity, creating supply bottlenecks for Phase III programs.
- Electroporation:Pulsed electrical field delivery enhancing cellular membrane permeability. Handheld device miniaturization is opening military and remote deployment channels previously inaccessible to nucleic acid vaccines.
- Liposome-Based Delivery:Lipid nanoparticle encapsulation improving plasmid stability.
- Gene Gun:Ballistic DNA delivery via gold microparticle bombardment.
- Viral Vector:Engineered adenovirus or vaccinia carriers for enhanced immunogenicity.
Plasmid DNA commands the largest installed base. Electroporation is climbing the fastest as sponsors prioritize delivery control.
Application:
Application focus shapes regulatory strategy, with infectious disease programs leveraging FDA emergency pathways and oncology pursuing accelerated approval based on surrogate endpoints.
- Infectious Diseases:Vaccines targeting viral, bacterial, or parasitic pathogens. Chinese NMPA nucleic acid GMP annexes are conditioning market access on domestic fill-finish capability for COVID-19 and influenza candidates.
- Oncology:Tumor-associated antigen vaccines for solid malignancies. Personalized neoantigen designs in United States academic centers command premium reimbursement as sequencing costs decline.
- Autoimmune Disorders:Tolerance-inducing plasmids for rheumatoid arthritis and multiple sclerosis.
- Allergy Treatments:Desensitization protocols for environmental and food allergens.
- Genetic Disorders:Gene supplementation approaches for monogenic deficiencies.
Infectious disease holds volume leadership. Oncology shows the steepest expansion trajectory.
End User:
End-user concentration determines sales force deployment, with research institutes requiring technical support and government agencies demanding supply security guarantees.
- Research Institutes:Academic and government laboratories conducting preclinical and early-phase studies. Funding from United States NIH and German DFG is concentrating on electroporation-compatible plasmid platforms.
- Pharmaceutical Manufacturers:Large-cap sponsors integrating DNA vaccines into diversified pipelines. Vertical control over electroporation device supply is becoming a prerequisite for IND submission timing confidence.
- Biotechnology Firms:Venture-backed developers pursuing platform specialization.
- Healthcare Providers:Hospital systems administering approved therapeutic vaccines.
- Government Agencies:National stockpiling authorities and pandemic response units.
Pharmaceutical manufacturers dominate procurement value. Biotechnology firms are gaining share fastest through synthetic biology specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways and EMA adaptive licensing frameworks are compressing development timelines across the United States and European Union, while China's NMPA nucleic acid GMP annexes are conditioning market access on domestic manufacturing capability.
United States
National stockpiling programs and NIH funding concentration drive procurement of plasmid DNA platforms for infectious disease preparedness. FDA Breakthrough Therapy Designation compresses Phase I-to-approval intervals for oncology candidates. Boston and San Francisco biotech clusters host the majority of electroporation-integrated clinical trial infrastructure.
China
Domestic fill-finish capability requirements under NMPA nucleic acid GMP annexes are reshaping contract manufacturing partnerships. Government pandemic preparedness mandates align with WHO frameworks to accelerate infectious disease vaccine procurement. Shanghai and Suzhou industrial parks concentrate GMP-certified plasmid production capacity for regional supply.
Germany
EMA adaptive licensing permits conditional approval based on surrogate immunogenicity endpoints, attracting oncology therapeutic vaccine sponsors. DFG funding concentrates on electroporation-compatible academic research platforms. Heidelberg and Munich academic medical centers expand combination checkpoint inhibitor protocols with tumor-associated antigen vaccines.
South Korea
Regional clinical trial networks and MFDS regulatory harmonization support Asian market entry for DNA vaccine developers. Government biotechnology investment programs prioritize synthetic biology platform scale-up. Seoul and Songdo bioclusters coordinate multicenter oncology studies with personalized neoantigen designs.
India
CDSCO and BIS import testing standard harmonization affects plasmid raw material supply qualification for regional manufacturers. Cost-sensitive production economics attract contract development organization investment. Hyderabad and Bangalore pharmaceutical corridors build nucleic acid manufacturing workforce pipelines to address specialist scarcity.
Global Human DNA Vaccines Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with vertical control over electroporation device supply separating platform owners from dependent developers. The market structure concentrates procurement leverage among sponsors securing captive delivery hardware ahead of IND submissions. Three archetypes dominate: synthetic biology platform specialists, electroporation-integrated device owners, and contract manufacturing-dependent developers. Competitive moves center on backward integration into device supply and partnership formation to secure GMP plasmid manufacturing slots.
Within the electroporation-integrated tier, Inovio Pharmaceuticals and Moderna Therapeutics exemplify platform control strategies. Inovio Pharmaceuticals anchors device-centric positioning through proprietary delivery hardware integration. Moderna Therapeutics represents synthetic biology platform specialization optimized for rapid antigen design. Genexine Inc. occupies a position as a regional clinical development anchor through Asian trial network partnerships.
| Leading Market Players |
|---|
| Moderna Therapeutics |
| Inovio Pharmaceuticals |
| GeneOne Life Science |
| Zydus Cadila Healthcare |
| Dynavax Technologies |
| Genexine Inc. |
| Shenzhen Geno-Immune Medical Institute |
| Applied DNA Sciences |
| Immunomic Therapeutics |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between pharmaceutical sponsors and United States-based contract development organizations lock in both GMP plasmid manufacturing slots and price visibility across multi-year clinical programs. This contract structure concentrates procurement leverage among sponsors securing captive electroporation device supply before IND submission timelines harden.
Pricing Analysis
Price spreads between German GMP-certified plasmid production and Indian contract manufacturing facilities reflect quality-grade differentiation tied to FDA and EMA regulatory tiering. Three-tier pricing structure across premium, standard, and economy levels segments by certification level, volume scale, and after-sales technical support bundling. Pricing pressure stems from GMP nucleic acid specialist scarcity inflating contract manufacturing rates. Mid-cap biotechnology firms exhibit highest price sensitivity due to capital constraints, while large-cap pharmaceutical manufacturers absorb premium tiers for timeline certainty.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Shanghai port congestion elevate cold-chain distribution expenses for plasmid raw materials sourced from German and United States production hubs. Supply concentrates in the United States, Germany, and China for GMP-certified nucleic acid manufacturing capacity. Raw material dependencies include bacterial cell banks, fermentation media, and chromatography resins. Single-source vulnerability pervades late-stage clinical programs dependent on contracted plasmid slots. Distribution runs through specialized biologistics providers with temperature-validated container systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electroporation device maintenance and calibration services represent a recurring-revenue layer expanding faster than plasmid manufacturing hardware sales, creating attach-rate opportunities for platform owners.
For Market Incumbents: Shield market position through backward integration into electroporation device manufacturing and captive GMP plasmid production capacity in the United States or Germany. Emerging synthetic biology platform specialists threaten technology substitution. Certification investment in China's NMPA nucleic acid GMP annexes secures regional market access. For New Entrants and Emerging Players: FDA Breakthrough Therapy Designation fast-tracks offer regulatory pathway acceleration for oncology DNA vaccine candidates. White-space targets include personalized neoantigen therapeutics in South Korean academic medical centers and needle-free delivery platforms for pediatric segments. Go-to-market positioning through regional contract manufacturing partnerships in India bypasses capacity bottlenecks. For Investors and Strategic Acquirers: Capital is best deployed toward electroporation-integrated platform owners with captive device supply and established clinical trial infrastructure across the analysis window. Acquisition targets combine synthetic biology antigen design capabilities with GMP manufacturing relationships. Watch for inflection signals in checkpoint inhibitor combination protocol adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | EMA adaptive licensing frameworks compress Phase I-to-approval intervals for oncology candidates. |
| Manufacturing Scale-Up | GMP plasmid capacity expansion in Chinese industrial parks satisfies NMPA domestic fill-finish requirements. |
| Regulatory Approval Pathway | FDA Breakthrough Therapy Designation attracts venture capital toward plasmid platform investments. |
| Strategic Partnership | Regional trial network alliances with South Korean and Chinese investigators accelerate Asian market entry. |
| Pipeline Diversification | Personalized neoantigen programs command premium reimbursement as tumor sequencing costs decline. |
Research Methodology
Operator-level perspectives from drug development executives, regulatory affairs leads, formulary directors, and GMP manufacturing specialists anchored the qualitative base. Primary interviews combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient-flow modeling and top-down epidemiological triangulation reinforced segment sizing.
Sensitivity analysis tested forecast robustness across electroporation adoption scenarios and plasmid manufacturing capacity expansion timelines. The analytical framework modeled segmentation across vaccine type, technology platform, application, and end user throughout the forecast period. CAGRs derived from patient population growth, pricing trajectory assumptions, and penetration curve analysis. Industry-specific inputs included clinical trial enrollment velocity and regulatory approval pathway success rates.
The analysis sits within stated boundaries; outcomes outside sustained FDA and EMA accelerated approval pathway utilization or electroporation device supply chain stabilization would require recalibration. Forecasts reflect documented assumptions regarding GMP manufacturing capacity expansion, checkpoint inhibitor combination protocol adoption, and nucleic acid regulatory harmonization progress. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Hemophilia Treatment Market
Cell & Gene Therapy
Cell and Gene Therapy Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
Lentiviral Vector Contract Development and Manufacturing Organizations Market
Cell & Gene Therapy
EMEA Cancer Biological Therapy Market
Cell & Gene Therapy
Cryopreservation Cell Lines Market
Cell & Gene Therapy
Cell Regeneration Medicine Market
Cell & Gene Therapy
Global Gene Therapy Market
Cell & Gene Therapy
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market
Cell & Gene Therapy
Global Cell and Gene Therapy Market
Cell & Gene Therapy
Cell Therapy Cryopreservation and Thaw Performance Test Platforms Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market
Cell & Gene Therapy
Sandhoff Disease Therapeutics Market
Cell & Gene Therapy
Cell Reprogramming Market
Cell & Gene Therapy
Global Viral Vector Manufacturing Market
Cell & Gene Therapy
CNS Specific Antisense Oligonucleotide Market
Cell & Gene Therapy
Global Cell and Gene Therapy Manufacturing Services Market