
 Plasmid DNA Preparation Market | 2026-2036
Plasmid DNA Preparation Market Size, Share, and Industry Trends Forecast 2026-2036
Plasmid DNA Preparation Market Insights
Modular service bundling is shifting buyer choice in plasmid DNA procurement, as customers seek flexible combinations of GMP manufacturing, analytical testing, and regulatory support rather than standalone products. Charles River Laboratories leverages integrated CDMO capabilities to capture full-program contracts across gene therapy pipelines. Aldevron anchors the high-grade GMP plasmid segment through its specialized focus on nucleic acid production at clinical and commercial scale. Lonza competes with global biomanufacturing infrastructure that sustains multi-site redundancy for supply security.
Plasmid DNA preparation encompasses the isolation, purification, and quality-controlled production of circular extrachromosomal DNA vectors, typically ranging from 5 to 20 kilobases, for use in molecular cloning, transfection, and therapeutic gene delivery applications. The process employs alkaline lysis followed by chromatographic or membrane-based purification to achieve endotoxin levels below established pharmacopeial thresholds for clinical use. Among product configurations, Plasmid Purification Services command premium pricing due to GMP compliance overhead and dedicated facility requirements, while Maxiprep Kits retain stable demand from process development laboratories scaling upstream. Magnetic Bead technology is gaining traction in automated high-throughput workflows, though Alkaline Lysis remains the dominant foundational method across research and manufacturing settings.
The FDA enforces stringent CMC guidelines for plasmid DNA used as critical starting materials in gene therapy, directly elevating documentation and validation burdens for suppliers seeking IND-enabling partnerships. The EMA's ATMP framework and the EU GMP Annex 1 revisions on sterile manufacturing further condition market access for European-bound products, while ISO 13485 and ICH Q5D standards shape quality system expectations for international shipments. Stakeholders must monitor how evolving comparability protocols for plasmid master banks will reshape supplier qualification timelines and capital deployment priorities.
Market Dynamics
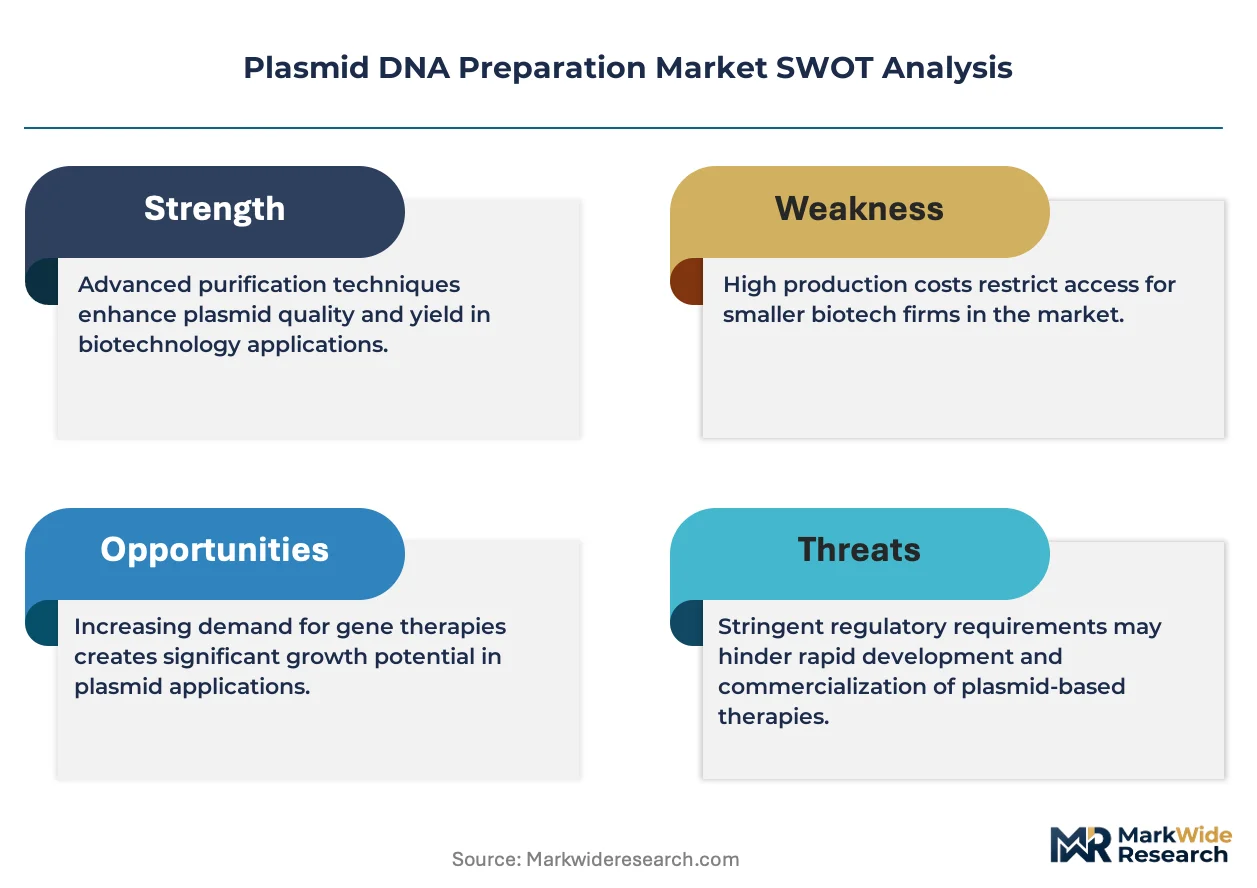
Gene therapy developers are consolidating supplier relationships as FDA CMC requirements tighten documentation burdens for plasmid master banks, compressing vendor qualification timelines and elevating capital barriers for new entrants.
Growth Catalysts
- ATMP Framework Expansion:The EMA's Advanced Therapy Medicinal Products classification is accelerating clinical trial initiations across Europe, requiring GMP-grade plasmid inputs for viral vector manufacturing.
- Alkaline Lysis Automation:Process intensification through continuous-flow alkaline lysis systems is reducing batch-to-batch variability in high-volume manufacturing settings.
- United States Clinical Concentration:The majority of Phase II and III gene therapy programs are headquartered in the United States, creating localized demand density for IND-enabling plasmid supply.
Market Restraints
- Fermentation Capacity Scarcity:Stainless steel bioreactor availability for high-cell-density E. coli culture is concentrated among a limited set of CDMOs, creating bottlenecks during campaign scheduling.
- Endotoxin Removal Costs:Chromatographic endotoxin clearance steps consume 15-25% of downstream processing costs, with resin prices subject to petrochemical feedstock volatility.
- FDA Master File Burden:Type II Drug Master File preparation and maintenance imposes six-figure annual costs on suppliers, excluding smaller research-grade providers from clinical partnerships.
Strategic Opportunities
- Japan PMDA Pathway:Japan's regenerative medicine regulatory framework offers accelerated approval timelines for gene therapies, creating demand for compliant plasmid supply as local biotechs expand manufacturing.
- mRNA Vaccine Adjacent Demand:Plasmid DNA templates for mRNA in vitro transcription are opening new revenue streams beyond viral vector applications, with process similarities enabling capacity pivoting.
- ISO 13485 Certification Gap:Medical device-grade plasmid supply for ex vivo cell engineering remains underserved, with few suppliers maintaining dual pharmaceutical-device quality systems.
Industry Challenges
- Qualified Personnel Scarcity:GMP manufacturing roles requiring combined expertise in microbial fermentation and gene therapy CMC are experiencing extended vacancy periods across CDMOs.
- Facility Qualification Timelines:Dedicated suite validation for plasmid production under EU GMP Annex 1 sterile manufacturing guidelines extends facility readiness by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasmid DNA Preparation Market |
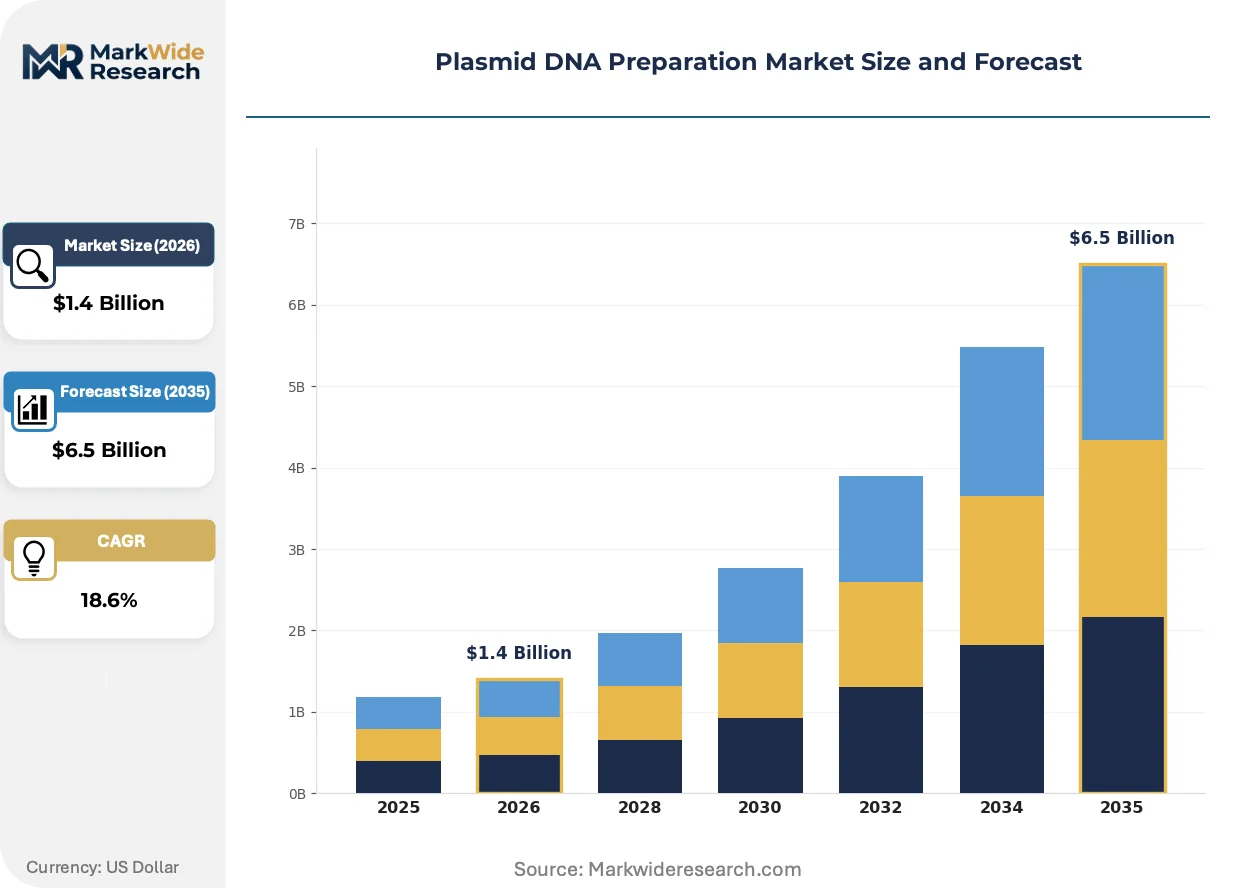
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Miniprep Kits, Maxiprep Kits, Midi Kits, Plasmid Purification Services Technology: Alkaline Lysis, Silica Membrane, Ion Exchange, Magnetic Bead Application: Gene Therapy, Vaccine Development, Research, Bioproduction End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Contract Research Organizations |
| Companies Covered | Charles River Laboratories, Aldevron, Lonza, VGXI, Inc., Catalent Inc., Thermo Fisher Scientific, Merck KGaA, PlasmidFactory GmbH & Co. KG, BioCina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasmid DNA Preparation Market Trends and Innovations
Continuous processing architectures and quality-by-design frameworks are displacing batch-wise manufacturing paradigms, compressing development timelines while elevating analytical burden on suppliers.
Magnetic bead-based plasmid purification is consolidating automated high-throughput workflows in process development laboratories. Contract manufacturers are adopting this technology to reduce manual handling errors and enable walk-away operation during screening campaigns. The shift is consolidating smaller kit-based purification providers into integrated service platforms that bundle reagent supply with analytical validation.
The FDA's evolving gene therapy CMC guidance is forcing suppliers to implement enhanced characterization protocols for plasmid topology and residual host cell DNA. Drug developers are responding by embedding quality agreements that mandate extended stability testing and forced degradation studies. Viral vector manufacturers with commercial-stage programs are most affected, renegotiating contracts to transfer analytical method validation responsibilities upstream to plasmid suppliers.
Buyer consolidation among top-tier gene therapy developers is compressing supplier switching cycles and elongating contract durations. Large pharmaceutical sponsors are mandating multi-year exclusive supply agreements with dedicated manufacturing capacity, displacing project-by-project procurement. This pattern is most visible in the United States, where three developers account for a disproportionate share of commercial-scale plasmid procurement.
Plasmid DNA Preparation Market Segmentation
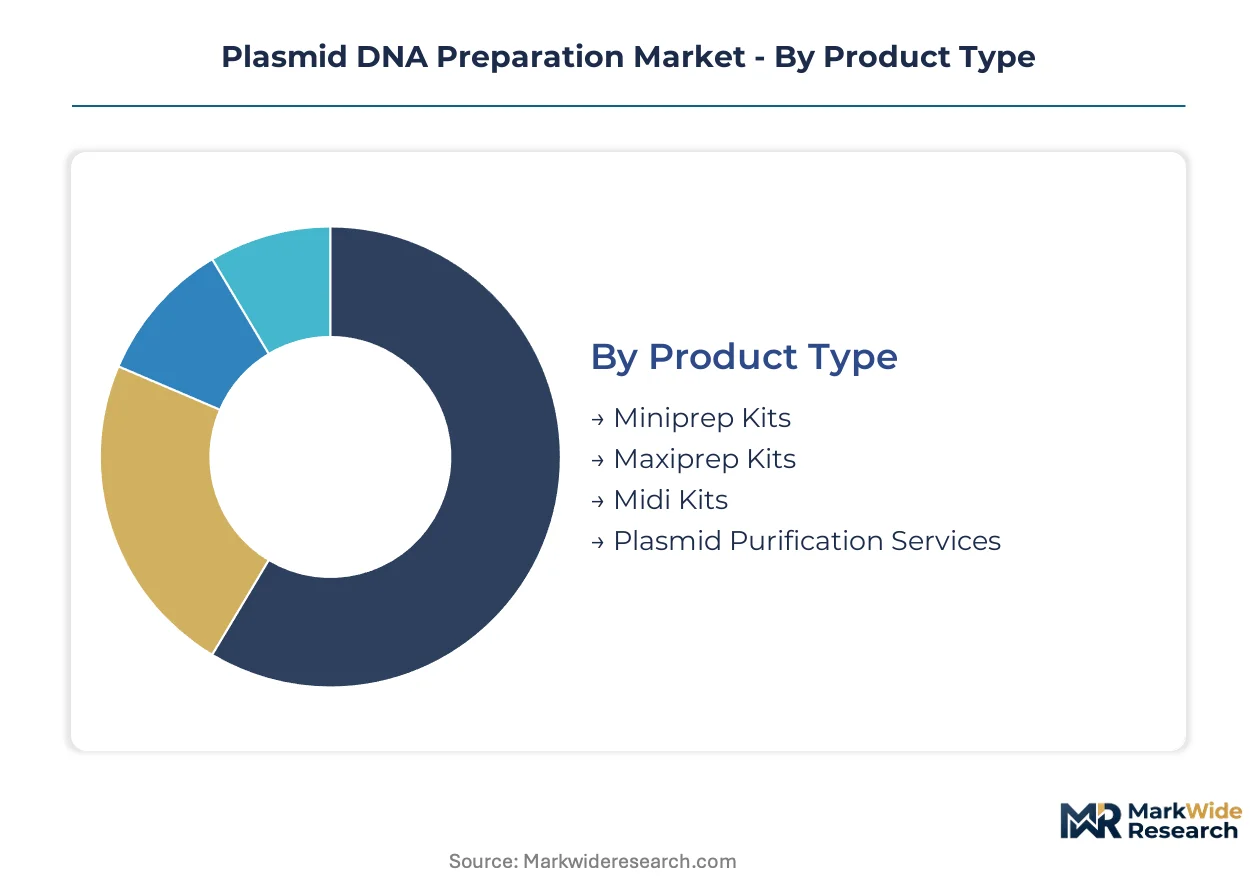
Segmentation in plasmid DNA preparation reveals how regulatory certification burdens stratify across product tiers and customer types. Suppliers must align facility investments and quality systems with the specific compliance requirements of each segment to capture contract value.
Product Type:
Certification requirements escalate sharply from research-grade kits to GMP-compliant services, with FDA Drug Master File obligations and EU GMP Annex 1 sterile manufacturing standards filtering which suppliers can serve clinical versus preclinical demand.
- Plasmid Purification Services:Dedicated facility operations producing GMP-grade material under FDA Type II Drug Master File and EMA ATMP frameworks. Gene therapy developers in the United States consolidate procurement with CDMOs holding validated sterile manufacturing suites for viral vector feedstock supply.
- Maxiprep Kits:Laboratory-scale purification systems processing 100-500mg plasmid yield per preparation. Process development groups at biotechnology firms in Massachusetts and California drive recurring demand for IND-enabling material generation.
- Miniprep Kits:Rapid isolation formats for molecular cloning verification and small-scale transfection optimization.
- Midi Kits:Intermediate throughput configurations bridging research and process development workflows.
Plasmid Purification Services sits at the top of the volume ranking, with Maxiprep Kits climbing the fastest as gene therapy pipelines expand process development capacity.
Technology:
Cost structures and automation compatibility differentiate purification approaches, with high-throughput platforms commanding premium positioning against established manual methods.
- Magnetic Bead:Automated capture systems enabling walk-away operation in 96-well and 384-well formats. Robotics integration at contract research organizations in Research Triangle Park and San Diego accelerates screening campaign throughput.
- Alkaline Lysis:Foundational chemical disruption method employing sodium hydroxide and SDS for cell lysis followed by neutralization. Global biomanufacturing infrastructure retains this method for commercial-scale production due to established validation packages.
- Silica Membrane:Spin-column formats dominating research laboratory procurement through convenience and reproducibility.
- Ion Exchange:Chromatographic resolution of plasmid isoforms and endotoxin clearance for high-purity therapeutic applications.
Alkaline Lysis retains the dominant revenue position, though Magnetic Bead is gaining share fastest among automated workflow adopters.
Application:
End-use requirements dictate plasmid topology specifications, endotoxin thresholds, and documentation depth, creating distinct supplier qualification pathways for therapeutic versus research applications.
- Gene Therapy:Supercoiled plasmid DNA as critical starting material for AAV and lentiviral vector manufacturing. FDA CMC guidance mandates extended characterization for IND submissions, concentrating procurement with suppliers holding validated master cell banks.
- Vaccine Development:DNA vaccine and mRNA template applications requiring linearized or specific topological forms. EMA's ATMP classification in Germany and the Netherlands accelerates clinical trial demand for compliant plasmid supply.
- Research:Molecular cloning, protein expression, and reporter construct applications with flexible quality specifications.
- Bioproduction:Cell line engineering and stable producer cell generation for therapeutic protein manufacturing.
Gene Therapy commands the highest unit economics, while Vaccine Development is expanding most quickly on mRNA platform proliferation.
End User:
Procurement sophistication and contract duration vary across organizational types, with pharmaceutical sponsors imposing the most stringent quality agreements and exclusivity requirements.
- Pharmaceutical Companies:Multi-year exclusive supply agreements with dedicated manufacturing capacity for commercial-stage gene therapy programs. Top-tier sponsors in the United States mandate redundant site qualification and real-time release testing protocols.
- Biotechnology Firms:Project-based procurement transitioning toward strategic partnerships as clinical milestones approach. Cambridge and South San Francisco clusters concentrate early-stage demand.
- Academic Institutions:Research-grade kit procurement through institutional purchasing agreements with limited GMP service engagement.
- Contract Research Organizations:Service bundling of plasmid preparation with downstream viral vector manufacturing for integrated client offerings.
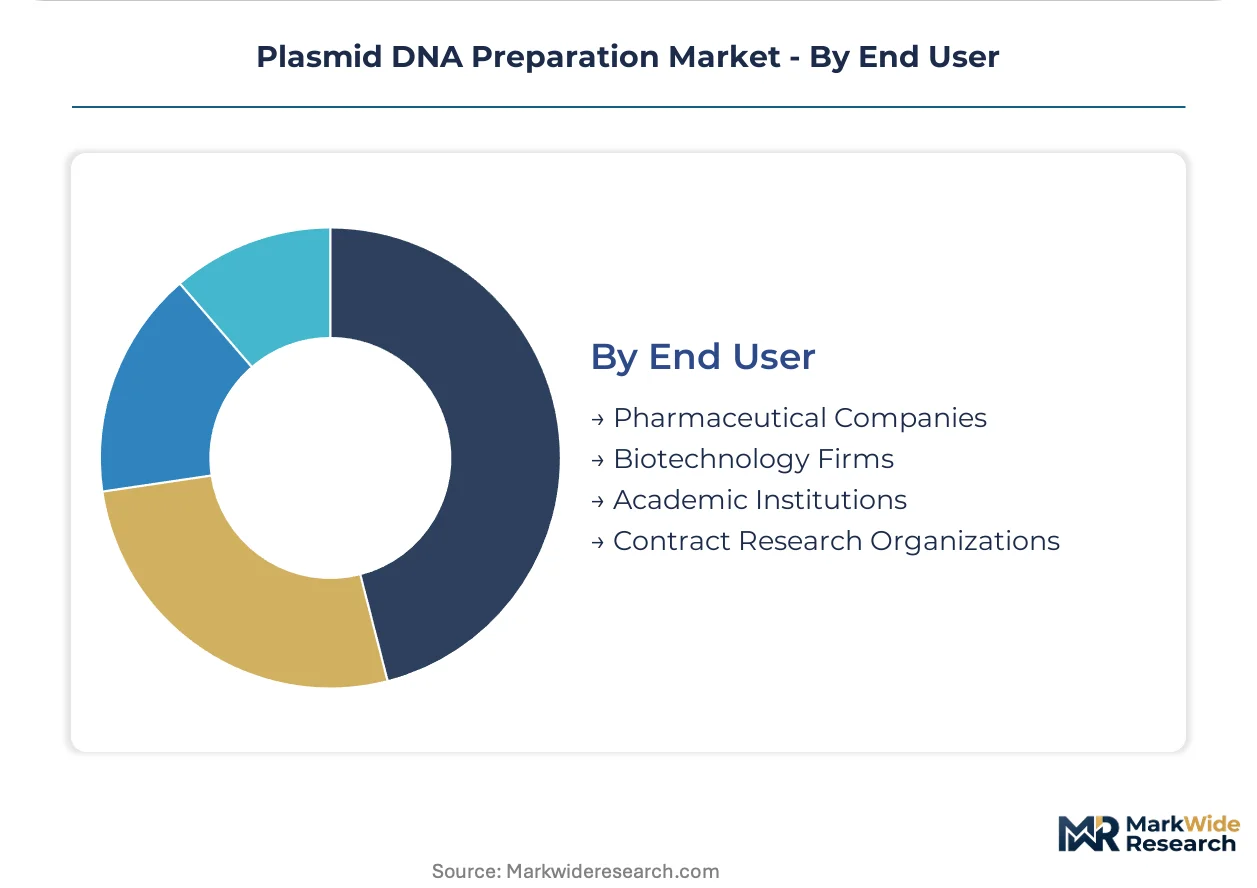
Pharmaceutical Companies anchor contract value, with Biotechnology Firms representing the steepest expansion trajectory as venture funding flows into gene therapy platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The plasmid DNA preparation industry traces its commercial origins to the San Francisco Bay Area's biotechnology corridor, where recombinant DNA techniques first scaled into industrial processes during the 1980s. This foundation established the United States as the dominant jurisdiction for gene therapy manufacturing infrastructure. Regulatory frameworks and clinical trial density now concentrate procurement across four distinct national markets.
United States
Gene therapy developers in Massachusetts and California drive the majority of IND-enabling plasmid procurement for AAV and lentiviral vector programs. FDA Type II Drug Master File requirements filter supplier participation, elevating capital barriers for clinical-grade production. The Research Triangle Park cluster in North Carolina anchors contract manufacturing capacity for commercial-scale supply.
Germany
EMA ATMP classification accelerates clinical trial initiations requiring GMP-grade plasmid inputs for viral vector manufacturing. EU GMP Annex 1 revisions on sterile manufacturing extend facility qualification timelines for suppliers seeking European market access. The Rhine-Main biotech corridor around Frankfurt concentrates process development laboratories scaling upstream workflows.
Switzerland
Swissmedic's alignment with EMA standards enables streamlined regulatory recognition for gene therapy starting materials. Basel's pharmaceutical manufacturing heritage supports integrated CDMO platforms bundling plasmid production with downstream bioprocessing. The country's dual pharmaceutical-device quality system infrastructure serves emerging ex vivo cell engineering applications.
Japan
PMDA's regenerative medicine regulatory framework offers accelerated approval timelines for gene therapies, stimulating local biotech manufacturing expansion. METI industrial policy targets domestic supply chain resilience for critical biologics inputs. The Kanto region around Tokyo concentrates venture-funded gene therapy developers transitioning from research-grade to GMP-compliant plasmid procurement.
United Kingdom
MHRA post-Brexit regulatory autonomy maintains equivalence with EMA ATMP standards for advanced therapy medicinal products. The Golden Triangle cluster spanning London, Cambridge, and Oxford houses early-stage biotechnology firms demanding flexible plasmid purification service bundling. Scottish manufacturing sites are qualifying for EU GMP recognition to preserve continental supply routes.
Plasmid DNA Preparation Market Competitive Landscape
The competitive structure tilts toward integrated contract development and manufacturing organizations with dedicated gene therapy infrastructure. Three to five established CDMOs control the majority of GMP-grade plasmid capacity, while specialized nucleic acid producers occupy premium niches. The market stratifies across full-service integrators, focused plasmid specialists, and diversified life science conglomerates. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as qualification timelines discourage customer switching.
Within the integrated CDMO tier, Charles River Laboratories exemplifies full-program contract capture across gene therapy pipelines. Aldevron occupies a specialist position in high-grade GMP plasmid production at clinical and commercial scale. Lonza represents the diversified conglomerate archetype, leveraging global biomanufacturing infrastructure to sustain multi-site redundancy for supply security.
| Leading Market Players |
|---|
| Charles River Laboratories |
| Aldevron |
| Lonza |
| VGXI, Inc. |
| Catalent Inc. |
| Thermo Fisher Scientific |
| Merck KGaA |
| PlasmidFactory GmbH & Co. KG |
| BioCina |
| Others |
Pricing and Supply Chain Analysis
Captive GMP manufacturing capacity within vertically integrated CDMOs anchors both supply security and pricing power for clinical-grade plasmid DNA, as FDA Drug Master File obligations and dedicated facility requirements create insurmountable capital barriers for non-integrated competitors. This structural configuration concentrates procurement leverage among three to five established suppliers while compressing margins for research-grade kit providers locked into transactional spot markets.
Pricing Analysis
Three-tier pricing structure across premium GMP services, mid-grade process development materials, and economy research kits stratifies the market. Price differentiation rests on certification grade—FDA Type II Drug Master File status commands substantial premiums—and volume scale, with multi-year exclusive supply agreements locking in favorable terms for pharmaceutical sponsors. Cost compression in the research-grade tier is intensifying because magnetic bead automation displaces manual kit-based workflows. Academic institutions exhibit the highest price sensitivity, while commercial-stage gene therapy developers prioritize supply security over unit cost.
Supply Chain Analysis
Qualified personnel scarcity in Massachusetts, North Carolina, and California constrains fermentation capacity expansion for high-cell-density E. coli culture. Raw material dependencies center on petrochemical-derived chromatography resins, pharmaceutical-grade reagents, and specialized plasmid backbone vectors. Single-source vulnerability pervades the stainless steel bioreactor segment, where limited CDMOs control campaign scheduling. Distribution runs through direct contractual relationships with gene therapy developers, bypassing traditional distributor networks to ensure chain-of-custody documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where gene therapy developers are consolidating procurement around suppliers with validated master cell banks and extended stability testing capabilities. The demand shift toward premium GMP specifications with real-time release testing protocols is filtering out research-grade providers.
For Market Incumbents: Hedge against capacity commoditization by embedding quality agreements that transfer analytical method validation responsibilities upstream from viral vector manufacturers. Defensive consolidation moves include qualifying redundant manufacturing sites under EU GMP Annex 1 sterile manufacturing guidelines and securing exclusive multi-year supply contracts with top-tier pharmaceutical sponsors. The threat of automated magnetic bead workflows displacing alkaline lysis in process development laboratories demands investment in continuous-flow system integration.
For New Entrants and Emerging Players: Ex vivo cell engineering developers requiring ISO 13485 medical device-grade plasmid supply represent an underserved buyer archetype with limited qualified suppliers. The most penetrable segment spans Japanese biotechs expanding manufacturing under PMDA's accelerated regenerative medicine framework. White-space targets include mRNA vaccine template production and dual pharmaceutical-device quality system certification. A go-to-market angle emphasizing walk-away automation compatibility with existing robotics infrastructure accelerates technical qualification.
For Investors and Strategic Acquirers: Consolidation pressure builds where facility qualification timelines extend 18-24 months under evolving sterile manufacturing standards, trapping customer relationships and inflating switching costs. Long-term viability across the analysis window favors CDMOs with integrated viral vector manufacturing capabilities that capture full-program contract value. Acquisition targets should display validated plasmid master banks and established FDA Type II Drug Master Files. The signal to watch is renegotiation frequency in commercial-stage gene therapy contracts, as elongated durations indicate successful supplier lock-in.
| Strategic Initiative | Industry Significance |
|---|---|
| GMP Manufacturing Scale-Up | FDA Type II Drug Master File validation enables IND-enabling partnerships with Massachusetts gene therapy developers. |
| Regulatory Certification Investment | EU GMP Annex 1 sterile manufacturing qualification preserves continental supply routes for German viral vector manufacturers. |
| Automation Technology Integration | Continuous-flow alkaline lysis systems reduce batch-to-batch variability for high-volume plasmid production campaigns. |
| Strategic Partnership Formation | Quality agreements embedding upstream analytical validation transfer capture value from viral vector CDMOs. |
| Geographic Expansion | Japan PMDA pathway alignment positions suppliers for regenerative medicine manufacturing demand in the Kanto region. |
Research Methodology
Bottom-up gene therapy pipeline modeling reconciled against top-down CDMO capacity tracking forms the analytical core of this study. Primary interviews with gene therapy development executives, regulatory affairs leads, GMP manufacturing directors, and viral vector procurement managers were cross-validated against FDA IND filings, EMA ATMP submissions, ClinicalTrials.gov records, and CDMO facility qualification disclosures. Secondary sources include SEC 10-K filings for publicly traded contract manufacturers, EU GMP inspection databases, and Japanese PMDA regenerative medicine approval trackers.
Historical trendline analysis of plasmid procurement volumes across the projection horizon established baseline growth patterns. The analytical framework segments by product type, technology platform, application, and end-user organizational structure, with additional modeling across certification grade tiers and regional regulatory clusters. CAGRs were derived from regression analysis of clinical trial initiation rates and viral vector manufacturing capacity expansion schedules. Forecast inputs incorporate gene therapy pipeline progression probabilities and mRNA vaccine platform adjacency demand.
Inputs from FDA and EMA regulatory databases were available through the study window; gaps in real-time CDMO campaign scheduling data introduce uncertainty bands around capacity utilization assumptions. Forecasts reflect documented assumptions regarding clinical trial success rates and commercial manufacturing scale-up timelines. Specific risk factors that could revise projections include FDA CMC guidance revisions on plasmid topology characterization and sudden fermentation capacity constraints from qualified personnel scarcity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Biotechnology and Pharmaceutical Services Outsourcing Market
Biotechnology Services
Plant Tissue Culture Products Market
Biotechnology Services
Custom Assays Market
Biotechnology Services
Marine Polysaccharides Fucoidan Alginate Market
Biotechnology Services
Plasma Feed Market
Biotechnology Services
Immunoassays in R & D Market
Biotechnology Services
Peptide and Oligonucleotide CDMO Market
Biotechnology Services
Feruloyl Esterase Market
Biotechnology Services
DNA and RNA Sample Preparation Market
Biotechnology Services
Bio-Services Market
Biotechnology Services
Biologics CDMO Market
Biotechnology Services
Global Downstream Processing Market
Biotechnology Services
Acetylglucosamine Market
Biotechnology Services
Cell Lysis and Disruption Market
Biotechnology Services
Mirna Tools and Services Market
Biotechnology Services
Global Alpha Galactosidase Market