
 Rocking Bioreactors Market | 2026-2036
Rocking Bioreactors Market Size, Share, and Industry Trends Forecast 2026-2036
Rocking Bioreactors Market Analytics
EMA's Annex 1 revision on sterile manufacturing is realigning capital allocation toward closed-system bioreactor designs. Sartorius AG leverages its single-use platform depth to capture upgrade cycles across European biologics facilities. Thermo Fisher Scientific anchors North American supply chains through integrated media-and-hardware bundling. Merck KGaA differentiates via membrane technology that reduces shear stress on mammalian cell lines.
Rocking bioreactors employ a platform-based agitation mechanism where a flexible bag rocks on a motorized base, typically operating at angles between 4° and 10° with rocking rates of 5–40 rpm to maintain oxygen transfer coefficients above 3 h⁻¹ in low-shear cell culture environments. Single-use bioreactors lead installed base expansion because film extractables validation now matches stainless steel cleanability assurances for clinical-phase production. Gene therapy applications represent the fastest-growing demand pool, as adeno-associated virus manufacturing requires the gentle mixing profiles that rocking motion uniquely delivers. Automated systems command premium positioning because real-time dissolved oxygen and pH feedback loops reduce batch failure rates in multi-product facilities.
FDA's process validation guidance and the EU's MDR framework jointly elevate documentation burdens for bioreactor qualification, pushing buyers toward vendors with pre-validated platform configurations. China's NMPA has aligned biologics GMP inspections with PIC/S standards, opening import pathways for European and American rocking systems. India's CDSCO is tightening clinical trial material traceability, which favors single-use bioreactors with integrated batch record automation. Stakeholders must weigh disposable supply security against stainless steel operational flexibility as regional biomanufacturing incentives reshape site selection economics.
Market Dynamics
Single-use film extractables validation now matches stainless steel cleanability assurances, eliminating a decade-long barrier to rocking bioreactor adoption in commercial-phase biologics manufacturing. This technical parity is redirecting capital from fixed infrastructure toward flexible, multi-product platforms.
Growth Catalysts
- EMA Annex 1 Revision:The sterile manufacturing directive mandates closed-system designs that rocking bioreactors uniquely satisfy through their bag-based containment architecture.
- Gene Therapy Manufacturing:Adeno-associated virus production requires the gentle mixing profiles that rocking motion delivers, creating dedicated demand from viral vector specialists.
- PIC/S Alignment in China:NMPA inspection harmonization opens import pathways for pre-validated European and American rocking systems into domestic biologics facilities.
Market Restraints
- Specialized Film Supply Concentration:Multi-layer polymer films for single-use bioreactor bags depend on a narrow supplier base concentrated in Germany and the United States.
- Stainless Steel Substitution Threat:Continuous manufacturing advances in perfusion bioreactor technology offer competing low-shear environments for established mammalian cell lines.
- Validation Documentation Burden:FDA process validation guidance and EU MDR framework jointly extend qualification timelines for new rocking platform installations.
Strategic Opportunities
- India CDSCO Traceability Mandate:Clinical trial material documentation requirements favor single-use bioreactors with integrated batch record automation systems.
- Continuous Processing Convergence:Integration of real-time dissolved oxygen and pH feedback loops with rocking platforms enables perfusion-mode operation.
- Contract Manufacturing Expansion:CDMO capacity buildouts in Singapore and South Korea seek flexible platforms for multi-product campaigns without cross-contamination risk.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Multi-product facilities require staff capable of translating platform configurations across diverse cell lines and therapeutic modalities.
- Legacy System Integration Complexity:Rocking bioreactor deployment in brownfield sites demands reconciliation with existing distributed control systems and data historians.
- Extractables Study Standardization Delays:Lack of harmonized protocols for film-leachable assessment prolongs vendor qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rocking Bioreactors Market |
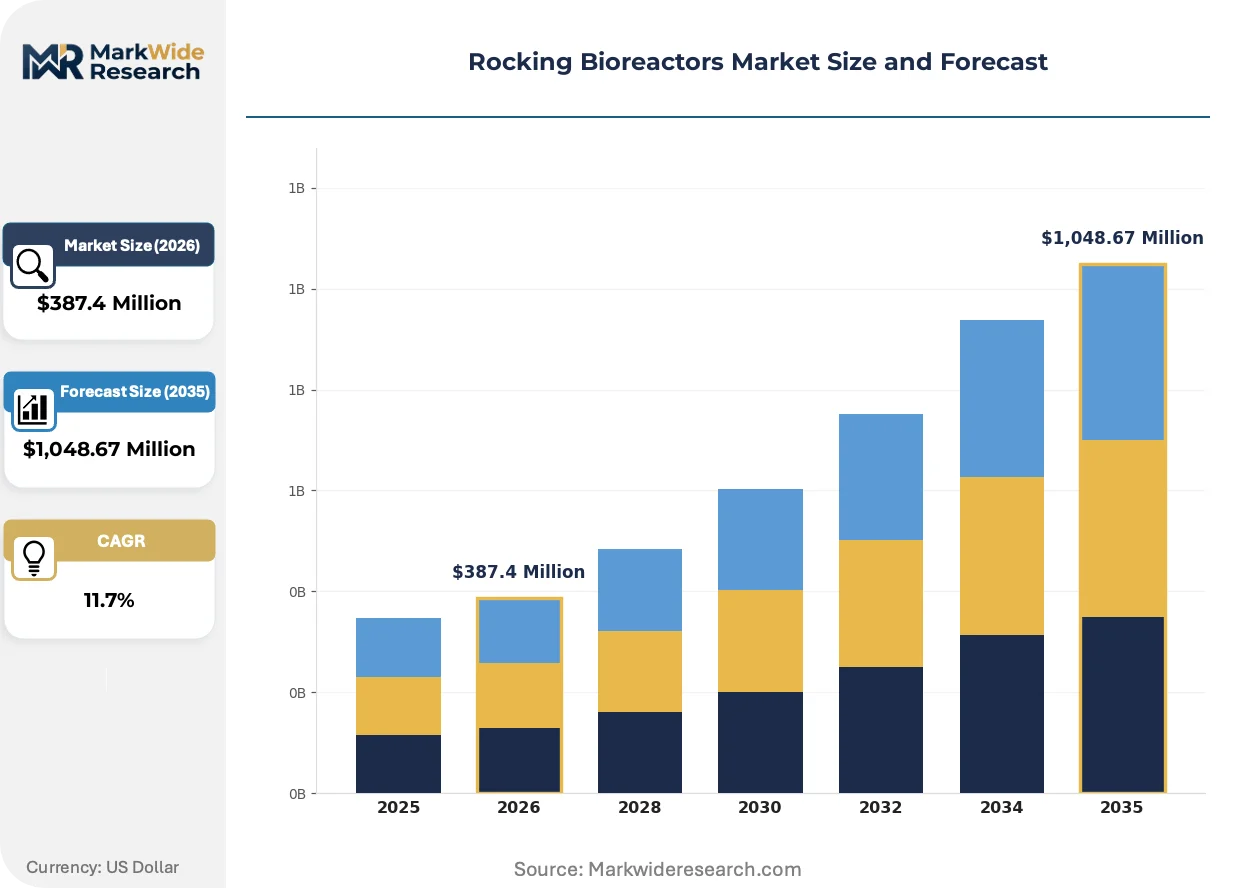
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $1,048.67 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Bioreactors, Stainless Steel Bioreactors, Glass Bioreactors, Mini Bioreactors Application: Cell Culture, Protein Production, Vaccine Development, Gene Therapy End User: Pharmaceutical Companies, Academic Institutions, Biotechnology Firms, Contract Research Organizations Technology: Automated Systems, Manual Systems, Hybrid Systems, Digital Monitoring |
| Companies Covered | Sartorius AG, Thermo Fisher Scientific Inc., Merck KGaA, Eppendorf AG, GE Healthcare, Cytiva, Applikon Biotechnology, PBS Biotech, Inc., Bioengineering AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rocking Bioreactors Market Evolving Landscape
Automation architectures are compressing batch failure rates while regulatory convergence across FDA, EMA, and NMPA is rewriting validation requirements. Demand concentration in multi-product facilities is reshaping procurement toward pre-qualified platform configurations.
Sensor-integrated rocking bioreactors are automating real-time process control through dissolved oxygen and pH feedback loops that adjust rocking angle and rate without operator intervention. Cell therapy manufacturers and viral vector specialists are adopting these systems fastest, replacing manual sampling protocols. This automation is compressing batch-to-batch variability and enabling unattended overnight operations in facilities with limited staffing.
EMA's Annex 1 revision on sterile manufacturing is mandating closed-system designs that eliminate open interventions during production. The regulation requires demonstration of containment for all aseptic operations, favoring bag-based rocking platforms over stirred-tank alternatives with mechanical seals. European biologics facilities are responding with capital allocation toward fully enclosed rocking systems with integrated sampling ports.
CDMO procurement patterns are consolidating vendor relationships around pre-validated platform configurations that reduce internal qualification burden. Multi-product facilities in the United States and Germany now specify rocking bioreactor bundles with pre-approved extractables documentation and harmonized control software. This specification compression favors suppliers with integrated media-and-hardware portfolios over component specialists.
Rocking Bioreactors Market Segmentation
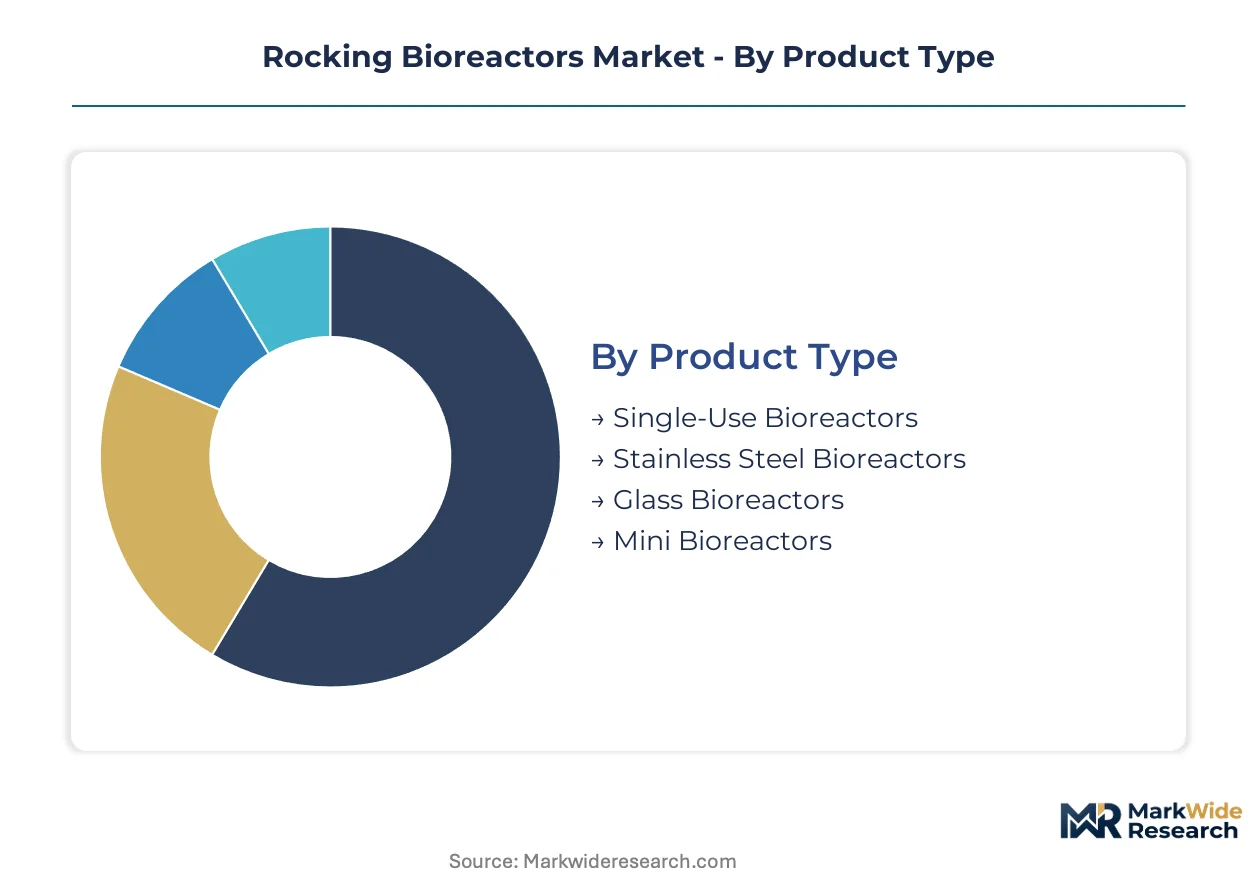
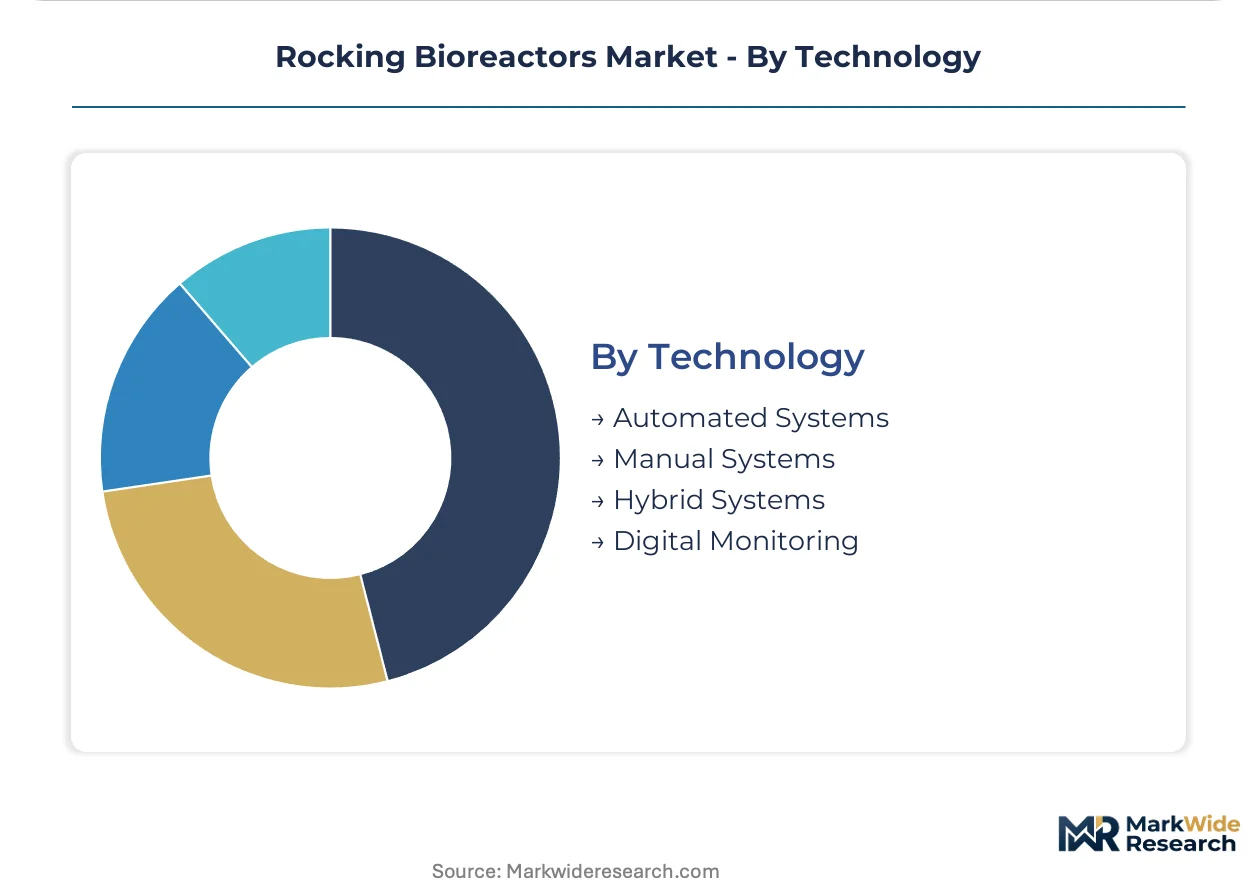
Rocking bioreactor procurement splits across material architecture, therapeutic application, and automation level. Buyers prioritize single-use film validation, gene therapy compatibility, and regulatory pre-qualification when selecting platform configurations.
Product Type:
Capital allocation decisions hinge on extractables documentation depth and multi-product flexibility requirements.
- Single-Use Bioreactors:Multi-layer polymer film construction eliminates steam-in-place cycles and enables rapid product changeover. Demand concentrates in United States and German CDMO facilities where EMA Annex 1 closed-system mandates favor bag-based containment over mechanical seals.
- Stainless Steel Bioreactors:316L electropolished vessels with jacketed temperature control support perfusion-mode operation at commercial scale. Procurement persists in established Chinese biologics plants where NMPA GMP inspections now align with PIC/S standards, validating legacy infrastructure upgrades.
- Glass Bioreactors:Borosilicate construction with magnetic drive impellers serves process development and seed train optimization. Academic laboratories in India favor these systems for CDSCO-mandated clinical trial material traceability.
- Mini Bioreactors:Sub-5 liter working volume platforms with parallel processing capability accelerate cell line screening. Biotechnology firms deploy these for early-phase gene therapy vector characterization.
Volume sits with single-use platforms; growth tilts toward mini bioreactors for cell therapy process development.
Application:
Mixing intensity requirements and shear sensitivity dictate platform selection across therapeutic modalities.
- Cell Culture:Mammalian and insect cell propagation demands oxygen transfer coefficients above 3 h⁻¹ with minimal mechanical stress. United States contract manufacturers specify rocking angles between 4° and 10° for monoclonal antibody production campaigns.
- Gene Therapy:Adeno-associated virus manufacturing requires gentle agitation to preserve viral capsid integrity. This segment is climbing the fastest as FDA-approved AAV therapies expand manufacturing capacity requirements.
- Protein Production:Recombinant protein expression in CHO and HEK293 lines leverages rocking motion for uniform nutrient distribution. German facilities prioritize automated pH control for fed-batch optimization.
- Vaccine Development:Viral seed amplification for influenza and COVID-19 platforms employs rocking bioreactors for rapid response manufacturing. China's NMPA has accelerated emergency use authorization pathways for these applications.
Revenue concentrates in cell culture; steepest expansion trajectory belongs to gene therapy vector production.
End User:
Internal qualification capabilities and campaign volume predict vendor relationship depth.
- Pharmaceutical Companies:Integrated biologics manufacturers with captive capacity specify pre-validated platform bundles to compress FDA process validation timelines. These buyers command volume pricing through multi-site standardization.
- Biotechnology Firms:Venture-backed developers of novel modalities prioritize flexibility over scale, favoring single-use rocking systems for rapid pipeline pivoting between cell and gene therapy programs.
- Contract Research Organizations:Service providers to sponsor companies require rapid protocol transferability. Indian CROs are upgrading to automated rocking platforms as CDSCO tightens batch record documentation requirements.
- Academic Institutions:Research laboratories with limited capital budgets favor manual systems for fundamental cell biology studies. These installations drive mini bioreactor demand for teaching and early-stage discovery.
Procurement volume favors pharmaceutical companies; fastest share gains belong to biotechnology firms scaling gene therapy manufacturing.
Technology:
Automation sophistication determines staffing models and batch failure risk profiles.
- Automated Systems:Real-time dissolved oxygen and pH feedback loops with programmable rocking profiles enable unattended operation. United States multi-product facilities specify these to reduce operator intervention under EMA Annex 1 containment requirements.
- Hybrid Systems:Semi-automated platforms with manual sampling and automated agitation control bridge cost and capability gaps. German mid-cap biotechs deploy these for clinical-phase material production.
- Manual Systems:Operator-dependent rocking rate and angle adjustment serves process development and educational applications. These systems dominate academic procurement in India and China.
- Digital Monitoring:Cloud-connected sensors with predictive analytics for film integrity and contamination risk represent emerging upgrade pathways. Integration complexity limits current adoption to greenfield facilities.
Installed base concentrates in manual and hybrid configurations; premium positioning shifts toward fully automated platforms with integrated batch record systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts Life Sciences Center tax incentives and Research Triangle Park credits concentrate biomanufacturing investment along the United States East Coast. Germany's BioRN cluster and Switzerland's Basel Area attract European headquarters decisions through R&D subsidies. China's Hengqin and Qianhai special zones accelerate Greater Bay Area biologics capacity buildouts.
United States
FDA process validation guidance and IRA domestic manufacturing provisions drive CDMO capacity expansion in Massachusetts and North Carolina. The Massachusetts Life Sciences Center allocates tax credits toward single-use platform installations in Greater Boston. San Francisco Bay Area biotechnology firms specify rocking bioreactors for gene therapy viral vector production.
Germany
EMA Annex 1 sterile manufacturing mandates redirect capital toward closed-system rocking platforms in Baden-Württemberg and Bavaria. The country's national pharmaceutical regulator enforces PIC/S-aligned inspection standards that validate pre-qualified European equipment. Heidelberg and Munich biotech clusters prioritize automated rocking systems for multi-product flexibility.
China
NMPA biologics GMP inspection harmonization with PIC/S standards opens import pathways for European and American rocking systems. Hengqin and Qianhai special economic zones in Guangdong Province offer tax holidays for biomanufacturing facility construction. Shanghai Zhangjiang Hi-Tech Park anchors domestic CDMO consolidation around single-use platform standardization.
India
CDSCO clinical trial material traceability mandates favor single-use bioreactors with integrated batch record automation. The country's national pharmaceutical regulator tightens documentation requirements for sponsor-supplied investigational products. Hyderabad and Bengaluru biotechnology corridors upgrade CRO infrastructure to capture contract manufacturing outflows from Western sponsors.
Switzerland
Swissmedic alignment with EMA centralized procedures accelerates rocking bioreactor qualification for export-bound biologics. Basel Area innovation incentives support technology transfer from pharmaceutical headquarters to regional CDMO partners. Zurich and Geneva clusters specialize in precision bioprocessing equipment for cell therapy manufacturing.
Rocking Bioreactors Market Competitive Landscape
United States producers anchor one tier; German specialists hold equipment validation depth. The vendor base concentrates around integrated platform suppliers and component technology providers. Three archetypes dominate: diversified life science conglomerates with bioprocessing divisions, pure-play single-use equipment specialists, and precision instrumentation firms with bioreactor adjacencies. Capacity expansion and pre-validated platform bundling constitute the dominant competitive moves.
Among diversified life science conglomerates, Sartorius AG and Thermo Fisher Scientific Inc. exemplify the integrated platform archetype through their breadth across consumables and hardware. Merck KGaA occupies a position within the membrane technology tier, representing specialization in shear-reduction approaches for sensitive cell lines. These three entities anchor competitive positioning through geographic coverage depth and regulatory pre-qualification breadth rather than point-product differentiation.
| Leading Market Players |
|---|
| Sartorius AG |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Eppendorf AG |
| GE Healthcare |
| Cytiva |
| Applikon Biotechnology |
| PBS Biotech, Inc. |
| Bioengineering AG |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap film specialists in Germany anchor multi-layer polymer supply for rocking bioreactor bags, translating captive resin formulation expertise into pricing power over CDMO procurement teams in the United States and China. This ownership concentration limits spot-market liquidity and forces buyers into long-term offtake commitments to secure extractables-validated film grades.
Pricing Analysis
Short lead-time premiums command pricing separation between spot inventory and contract-scheduled deliveries, with United States gene therapy CDMOs paying substantial markups for validated single-use bags inside twelve-week windows. Three-tier pricing structure across premium automated platforms, standard hybrid configurations, and economy manual systems reflects automation depth and pre-validation documentation breadth. Cost compression in standard-tier equipment is intensifying because Chinese domestic manufacturers are scaling film extrusion capacity under NMPA GMP alignment. Biotechnology firms with venture-backed burn rates exhibit highest price sensitivity, while pharmaceutical incumbents with captive biologics capacity prioritize qualification speed over unit economics.
Supply Chain Analysis
Direct-to-biomanufacturer channels handle hyperscale pharmaceutical demand, with Sartorius AG and Thermo Fisher Scientific operating regional distribution centers in Massachusetts and Baden-Württemberg to compress delivery timelines. Film resin supply concentrates in Germany, the United States, and Japan, with specialty fluoropolymer and polyethylene terephthalate glycol layers drawing from petrochemical feedstocks anchored in the Rhine-Ruhr corridor and Gulf Coast complexes. Single-source vulnerability pervades gamma-irradiation sterilization capacity, where limited contract facilities in Belgium and Illinois create chokepoints for bag terminal sterilization. Distribution runs through authorized distributor networks for mid-cap biotechnology accounts, with direct field service engineers supporting pharmaceutical incumbents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized film supply scarcity props pricing discipline across rocking bioreactor platforms, with qualified multi-layer polymer capacity expansion lagging demand from gene therapy viral vector manufacturing by approximately thirty-six months.
For Market Incumbents: Extend pre-validated platform bundling into Indian CRO infrastructure upgrades, capturing CDSCO-mandated batch record automation demand before domestic competitors achieve extractables documentation parity. Fortify backward integration into gamma-irradiation sterilization partnerships to neutralize single-source vulnerability in bag terminal processing. EMA Annex 1 closed-system mandates favor incumbents with existing European validation dossiers. For New Entrants and Emerging Players: Digital-channel route partnerships with cloud-based manufacturing execution system vendors offer low-friction entry into mid-cap biotechnology accounts seeking rapid platform deployment. White-space concentration sits with automated mini bioreactor configurations for cell therapy process development, where incumbent pricing leaves room for value-engineered alternatives. Target academic institutions in India and China through distributor relationships that bypass direct field service requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision instrumentation firms with bioreactor adjacencies in Switzerland and Germany, where Basel Area innovation subsidies have compressed technology transfer timelines for cell therapy equipment. Long-term viability hinges on gene therapy manufacturing capacity buildouts sustaining demand for gentle-mixing platforms. Monitor NMPA biologics GMP inspection harmonization velocity as inflection indicator for Chinese import pathway expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Validated Platform Bundling | Compresses FDA process validation timelines for multi-product pharmaceutical facilities. |
| Backward Integration into Film Resin | Secures extractables documentation control against German supplier concentration risk. |
| Gamma-Irradiation Sterilization Partnerships | Neutralizes Belgium and Illinois capacity chokepoints for single-use bag terminal processing. |
| Digital Monitoring Platform Launch | Captures greenfield facility demand for predictive film integrity analytics. |
| CDMO Capacity Expansion in Singapore | Positions for multi-product campaign flexibility without cross-contamination risk. |
Research Methodology
SEC filings, EMA regulatory submissions, and ClinicalTrials.gov protocol registrations formed the secondary backbone, cross-referenced against customs records for bioprocessing equipment imports into China and India. Primary interviews with bioprocess engineering directors, regulatory affairs leads at CDMOs, GMP inspection specialists, and single-use film procurement managers validated demand assumptions and pricing benchmarks. Bottom-up installation base modeling and top-down therapeutic modality demand aggregation were triangulated against vendor-reported platform shipments.
Historical trendline analysis across rocking bioreactor adoption curves informed projection elasticity, with segmentation dimensions spanning product architecture, therapeutic application, automation level, and end-user qualification capability. CAGRs were derived from capacity expansion announcements, regulatory approval trajectories for gene therapies, and regional biomanufacturing incentive program allocations. Forecast inputs included EMA Annex 1 implementation timelines, NMPA PIC/S alignment progress, and CDSCO traceability mandate enforcement intensity.
The model holds under sustained gene therapy pipeline advancement and regulatory convergence; deviation in stainless steel perfusion technology substitution rates or film supply disruption severity would shift trajectory. Periodic stress-testing of base assumptions against bioprocess engineering talent availability and gamma-irradiation sterilization capacity expansion is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Asia-Pacific Transfection Reagent and Equipment Market
Biotechnology Equipment
Biochemistry Analyzers Market
Biotechnology Equipment
DNA/RNA Extraction Market
Biotechnology Equipment
Lab Automation in Bioanalysis Market
Biotechnology Equipment
PCR Master Mix Market
Biotechnology Equipment
Global Large Molecule Bioanalytical Technologies Market
Biotechnology Equipment
Global Latex Agglutination Test Kits Market
Biotechnology Equipment
Cell Harvesting Systems Market
Biotechnology Equipment
RNA Isolation and Enrichment Reagent Market
Biotechnology Equipment
Biobanking Equipment Market
Biotechnology Equipment
Global Bioprocess Analyzers Market
Biotechnology Equipment
IVF Workstation Market
Biotechnology Equipment
Global Bioprocess Container Market
Biotechnology Equipment
Global Lab Automation in Protein Engineering Market
Biotechnology Equipment
Cellular Localization Kits Market
Biotechnology Equipment
Global Biological Microscope Objectives Market