
 Mirna Tools and Services Market | 2026-2036
Mirna Tools and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Mirna Tools and Services Market Outlook
ISO 13485 certification for in vitro diagnostic manufacturing is redrawing the competitive landscape for miRNA tool suppliers. Thermo Fisher Scientific leverages its end-to-end sequencing ecosystem to anchor high-throughput library preparation workflows across major cancer centers. QIAGEN sustains dominance in sample stabilization and extraction chemistry, a position built on decades of RNA quality control protocols. Illumina competes through locked-in sequencing instrument placements that generate recurring consumable revenue from miRNA profiling panels.
MiRNA tools and services encompass reagent systems, sequencing platforms, bioinformatics pipelines, and contract research services designed to isolate, quantify, and interpret microRNA molecules—small non-coding RNAs roughly 18-25 nucleotides in length that regulate gene expression post-transcriptionally. These tools serve primarily to identify disease-associated miRNA signatures for diagnostic development and therapeutic target validation in oncology and cardiovascular research. Library preparation tools occupy the largest revenue pool due to recurring consumable demand, while data analysis software represents the fastest-expanding segment as laboratories outsource computational interpretation to cloud-based bioinformatics vendors. Sequencing services retain strong growth in Asia-Pacific markets where capital constraints limit in-house platform acquisition.
FDA oversight of nucleic acid-based diagnostics under the In Vitro Diagnostics Regulation framework shapes product development timelines and clinical validation requirements for miRNA assay manufacturers. EMA's Medical Device Regulation and ISO 15189 accreditation standards for clinical laboratories further constrain market access in Europe, favoring vendors with established quality management systems. Stakeholders must monitor evolving reimbursement pathways for miRNA-based companion diagnostics, as payer acceptance will determine whether research-grade tools successfully transition into routine clinical workflows.
Market Dynamics
Single-cell miRNA profiling workflows are compressing turnaround times and forcing reagent suppliers to redesign library preparation kits for automated liquid-handling platforms.
Growth Catalysts
- NIH funding mechanisms:Sustained grant allocations to academic medical centers in the United States are accelerating procurement of next-generation sequencing infrastructure for non-coding RNA research.
- Oncology pipeline expansion:Pharmaceutical sponsors are integrating miRNA biomarker discovery into early-stage therapeutic development, creating pull-through demand for contract research services.
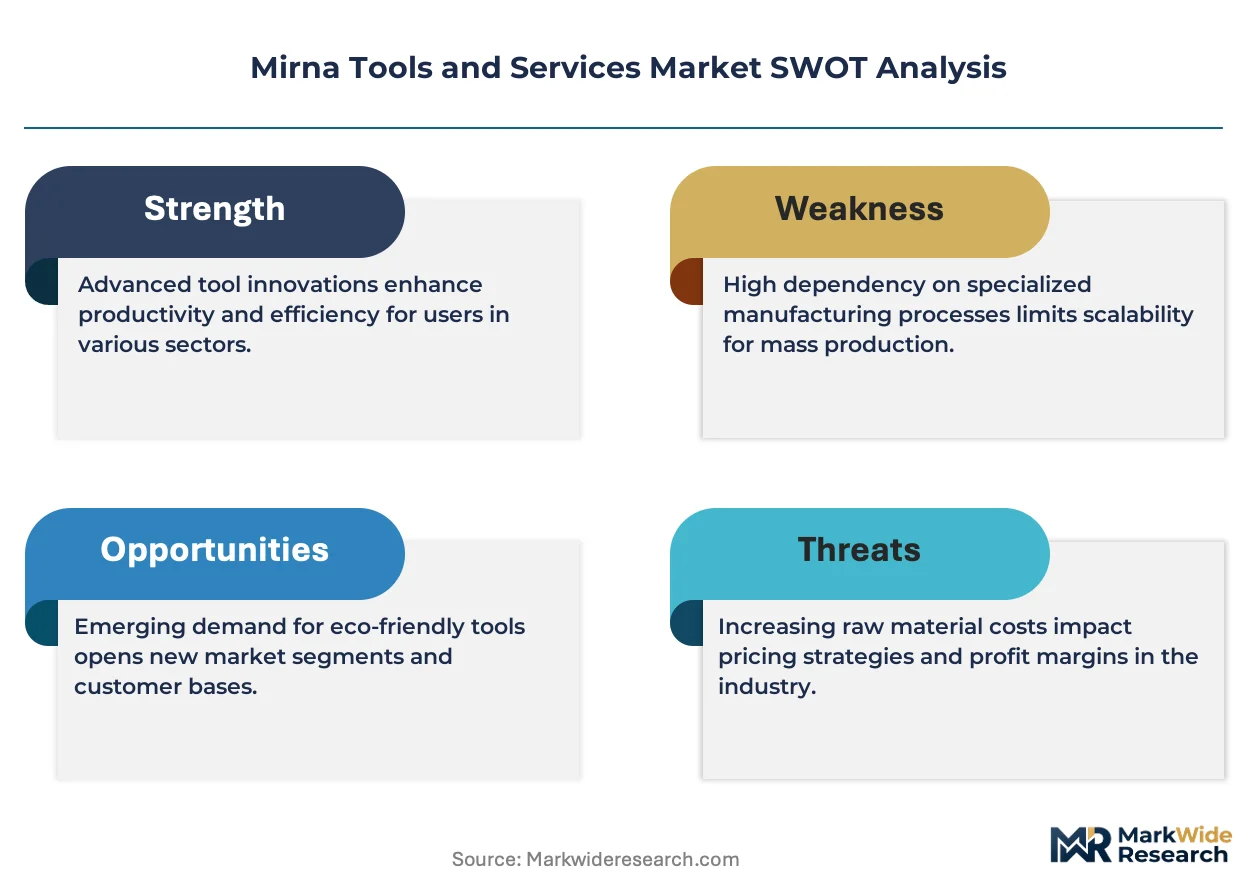
- ISO 13485 certification:Quality management mandates for in vitro diagnostic manufacturing are filtering out uncertified suppliers and concentrating purchasing power among validated vendors.
Market Restraints
- Capital intensity of sequencing platforms:High upfront instrument costs and recurring consumable commitments constrain adoption among mid-sized research institutions and emerging market laboratories.
- Regulatory friction from FDA IVD oversight:Clinical validation requirements for nucleic acid-based diagnostics extend product development timelines and increase compliance expenditure for assay manufacturers.
- Technical limitation in sample stabilization:RNA degradation during collection and transport creates reproducibility challenges that compromise downstream profiling accuracy in multi-site studies.
Strategic Opportunities
- Cloud-based bioinformatics outsourcing:Laboratories lacking computational infrastructure are migrating data interpretation to specialized vendors, expanding addressable market for analysis-as-a-service providers.
- Asia-Pacific sequencing services:Capital constraints on in-house platform acquisition in India and Southeast Asian markets are sustaining demand for centralized contract research facilities.
- Companion diagnostic reimbursement pathways:Emerging payer frameworks for miRNA-based tests in oncology create regulatory tailwind for research-grade tools transitioning into clinical workflows.
Industry Challenges
- Bioinformatics talent scarcity:Shortage of computational biologists trained in small RNA analysis pipelines limits laboratory capacity to interpret high-throughput sequencing output.
- EMA MDR compliance timelines:Extended conformity assessment procedures for in vitro diagnostics under the Medical Device Regulation delay market access for European clinical laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mirna Tools and Services Market |
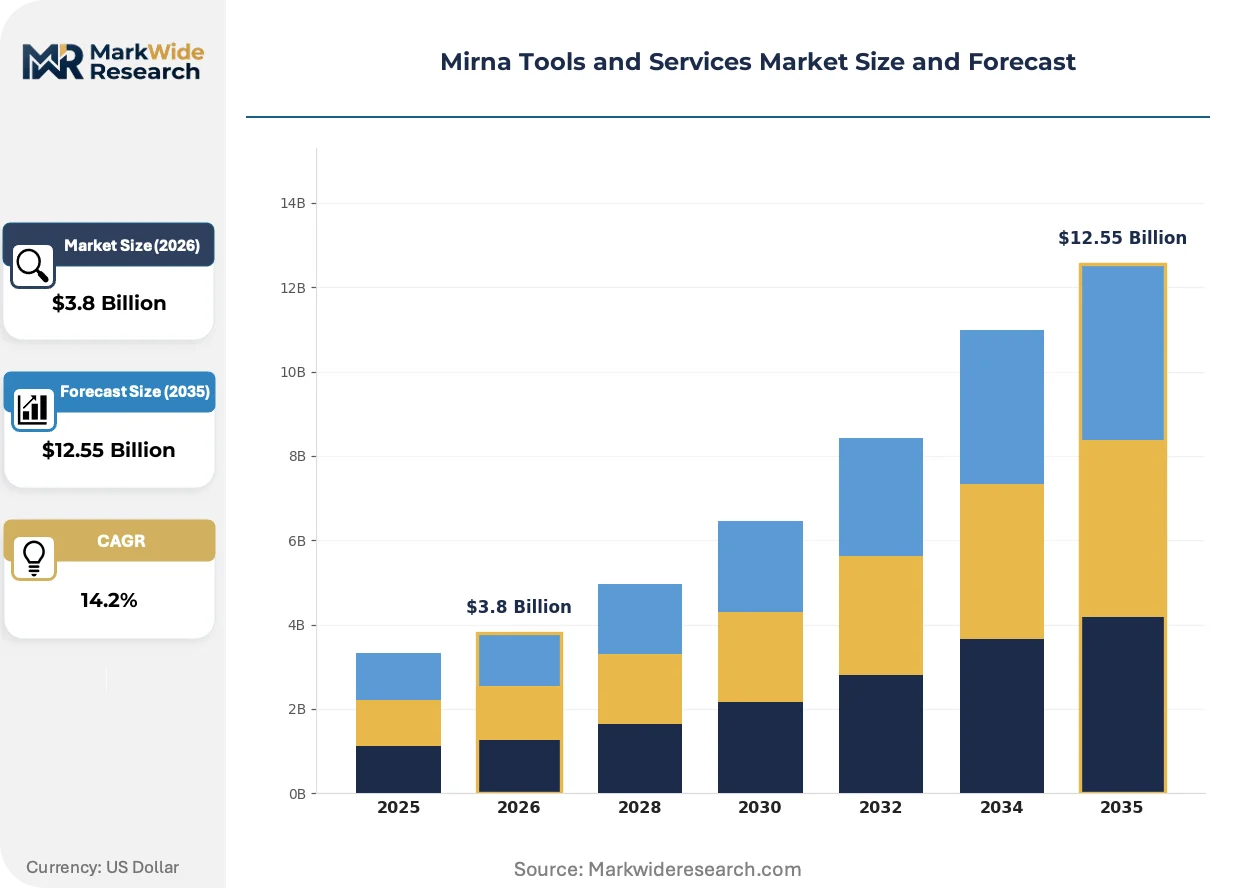
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Library Preparation Tools, Sequencing Services, Data Analysis Software, Quality Control Kits Application: Oncology Research, Drug Development, Biomarker Discovery, Genetic Testing End User: Pharmaceutical Companies, Academic Institutions, Research Laboratories, Clinical Testing Facilities Service Type: Consulting Services, Technical Support, Custom Assay Development, Training Services |
| Companies Covered | Thermo Fisher Scientific, QIAGEN, Illumina, Agilent Technologies, Bio-Rad Laboratories, Takara Bio, Revvity, Promega Corporation, Norgen Biotek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mirna Tools and Services Market Strategic Shifts
Workflow automation and regulatory harmonization are reshaping how miRNA tools transition from research-grade reagents to clinically validated diagnostics.
Digital PCR quantification methods are supplanting traditional qPCR for absolute miRNA copy number determination in liquid biopsy applications. Major cancer centers in the United States are adopting droplet-based partitioning platforms to improve sensitivity for circulating biomarker detection. This shift is compressing validation timelines for diagnostic developers seeking FDA breakthrough device designation.
EMA's In Vitro Diagnostics Regulation is mandating clinical performance studies and post-market surveillance for nucleic acid-based tests entering European markets. Manufacturers must maintain technical documentation and quality management systems that satisfy notified body scrutiny. Small reagent suppliers without established regulatory affairs functions are exiting the clinical segment to focus on research-use-only products.
Consolidated purchasing agreements are displacing fragmented procurement across individual laboratory principal investigators. Large academic medical centers and pharmaceutical sponsors are negotiating enterprise-wide sequencing consumable contracts that bundle library preparation, sequencing, and bioinformatics support. This concentration is most visible in the United States, where NIH-funded institutions leverage collective volume to extract price concessions and dedicated field service support.
Mirna Tools and Services Market Segmentation
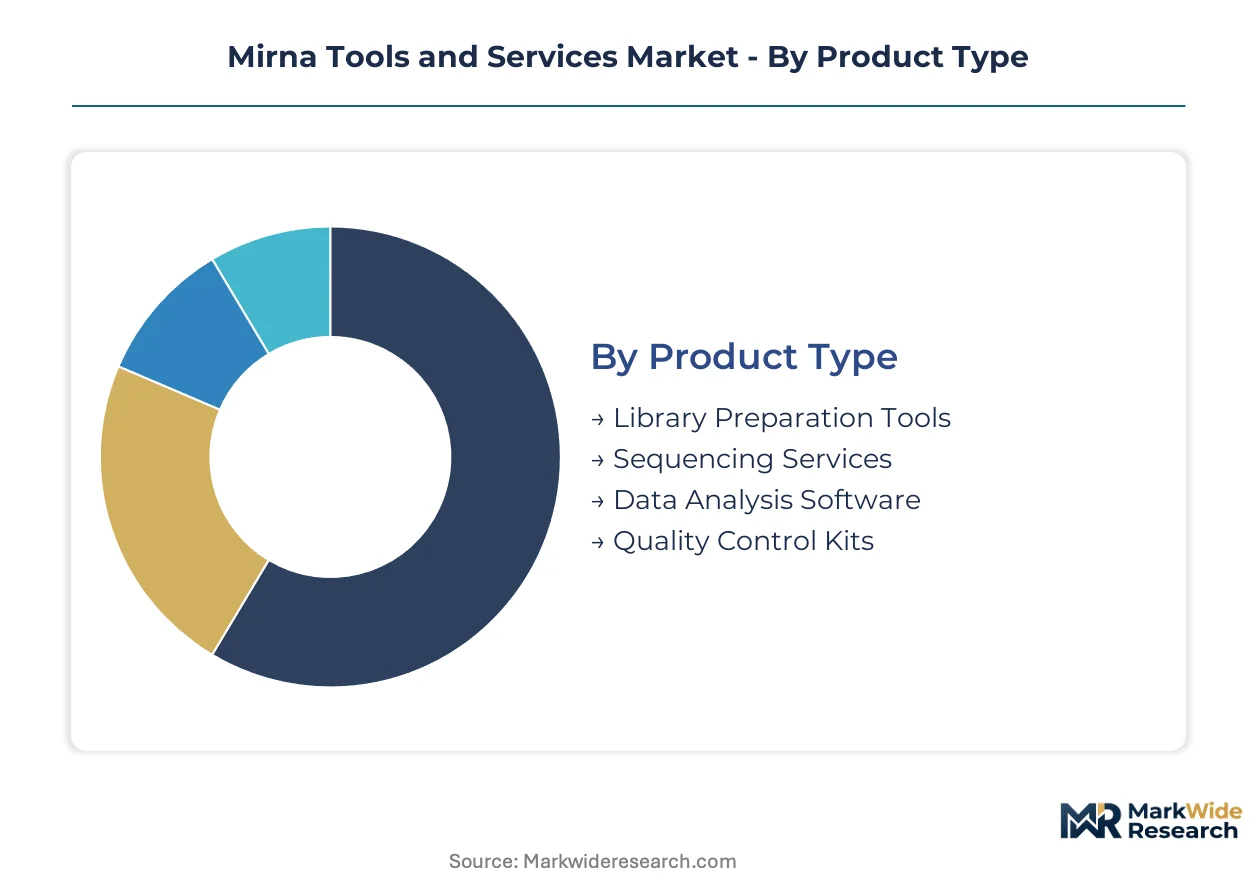
MiRNA tools and services segment across product architecture, research application, customer type, and service delivery model. Each dimension captures distinct procurement patterns and margin structures that shape vendor positioning.
Product Type:
Recurring consumable revenue concentrates in library preparation workflows, while software subscriptions are capturing expanding margin pools through cloud delivery models.
- Library Preparation Tools:Automated liquid-handling compatible kits dominate high-throughput cancer center procurement. Thermo Fisher and QIAGEN extract recurring revenue from NIH-funded institutions through bundled reagent contracts.
- Sequencing Services:Contract research organizations in Asia-Pacific markets absorb capital-constrained demand from India and Southeast Asian laboratories lacking in-house platform investment.
- Data Analysis Software:Cloud-based pipelines address bioinformatics talent scarcity in mid-sized research institutions.
- Quality Control Kits:RNA integrity assessment reagents maintain steady replacement cycles across multi-site clinical studies.
Library preparation tools hold installed capacity. Data analysis software is rotating up the share rankings.
Application:
Oncology research commands the deepest procurement budgets, though biomarker discovery is climbing fastest as pharmaceutical sponsors integrate miRNA signatures into therapeutic pipelines.
- Oncology Research:Single-cell miRNA profiling workflows at major US cancer centers drive demand for high-sensitivity detection platforms. FDA breakthrough device designation pathways accelerate validation investment from diagnostic developers.
- Biomarker Discovery:Pharmaceutical sponsors embed miRNA analysis into early-stage oncology pipelines, creating pull-through demand for end-to-end service contracts spanning isolation through computational interpretation.
- Drug Development:Target validation studies leverage circulating miRNA signatures for patient stratification.
- Genetic Testing:Inherited disease screening applications remain secondary to oncology focus.
Oncology research holds installed capacity. Biomarker discovery is rotating up the share rankings.
End User:
Pharmaceutical procurement operates on enterprise-wide sequencing contracts, while academic purchasing fragments across individual principal investigators despite NIH funding concentration.
- Pharmaceutical Companies:Large sponsors negotiate bundled agreements covering library preparation, sequencing, and bioinformatics support. Consolidated purchasing displaces fragmented procurement across therapeutic area divisions.
- Academic Institutions:NIH grant mechanisms concentrate purchasing power at major US medical centers, though individual laboratory autonomy persists in reagent selection.
- Research Laboratories:Mid-sized institutions face capital constraints on platform acquisition.
- Clinical Testing Facilities:ISO 15189 accreditation requirements filter vendor access in European markets.
Pharmaceutical companies hold installed capacity. Clinical testing facilities are rotating up the share rankings.
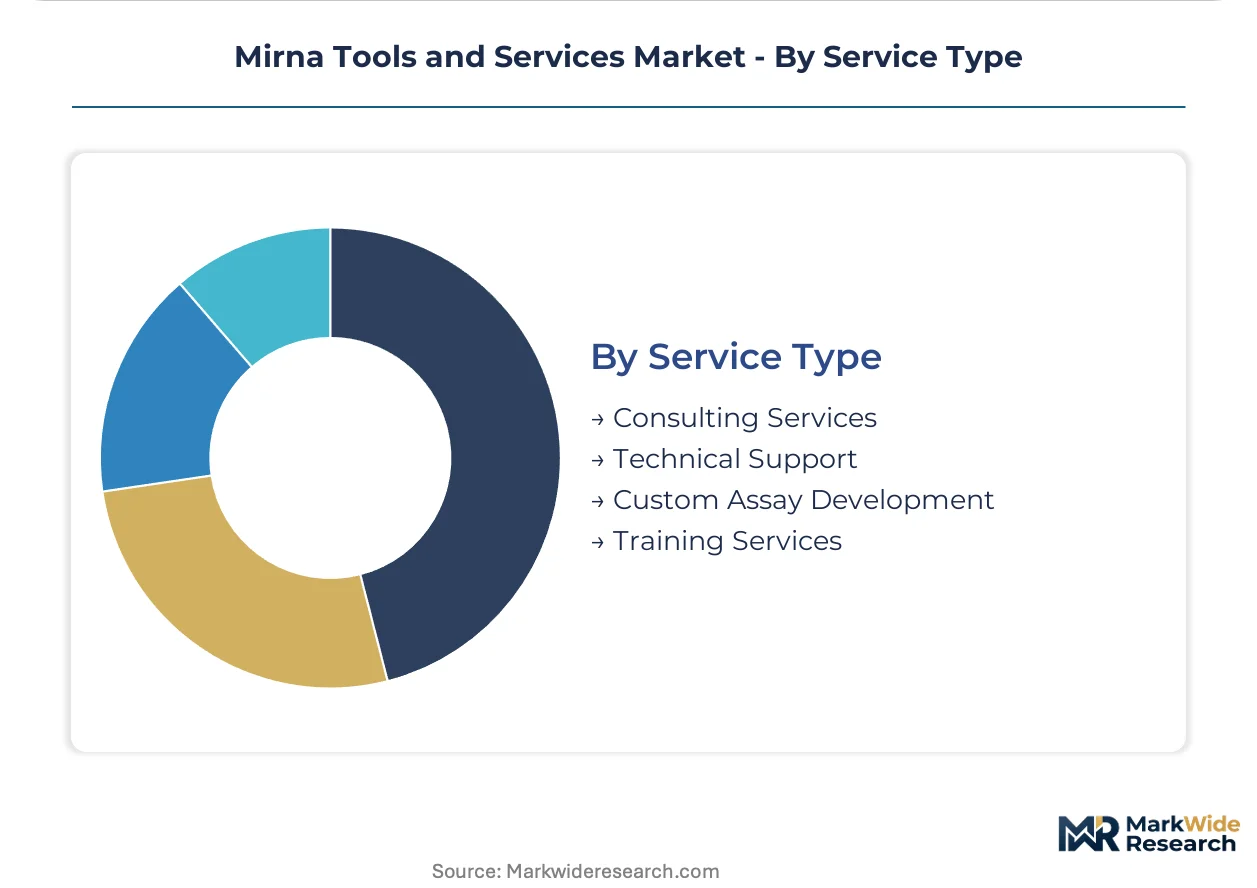
Service Type:
Custom assay development captures premium pricing from diagnostic manufacturers navigating FDA IVD validation requirements, while technical support margins compress under standardization.
- Custom Assay Development:Regulatory consulting bundled with wet-lab validation addresses FDA nucleic acid diagnostic oversight. Manufacturers without established quality management systems outsource clinical-grade assay design.
- Consulting Services:Bioinformatics pipeline architecture for laboratories lacking computational infrastructure represents the steepest expansion trajectory within service delivery.
- Technical Support:Field service contracts attach to enterprise sequencing placements.
- Training Services:Workflow education supports automated platform adoption.
Custom assay development holds installed capacity. Consulting services are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NIH-funded academic medical centers and large pharmaceutical sponsors concentrate procurement power in the United States, while European quality mandates and Asia-Pacific capital constraints create divergent demand patterns across national markets.
United States
FDA nucleic acid diagnostic oversight and NIH grant mechanisms drive consolidated purchasing at major cancer centers in Boston and San Francisco. The agency's breakthrough device designation pathway accelerates validation investment from diagnostic developers seeking clinical entry. Enterprise-wide sequencing contracts now bundle library preparation, sequencing, and bioinformatics support across Memorial Sloan Kettering and MD Anderson.
Germany
EMA Medical Device Regulation compliance timelines filter vendor access for clinical laboratories in Munich and Heidelberg. ISO 15189 accreditation standards favor established quality management systems from validated reagent suppliers. The country's national pharmaceutical regulator mandates clinical performance studies that extend conformity assessment for nucleic acid-based tests entering European markets.
China
NMPA oversight of in vitro diagnostics shapes product registration timelines for domestic and multinational manufacturers in Shanghai and Suzhou. The national medical products administration requires technical documentation and quality management system certification for clinical-grade assay market entry. Local contract research organizations absorb demand from capital-constrained mid-tier hospitals lacking in-house sequencing infrastructure.
Japan
PMDA regulatory frameworks for nucleic acid-based diagnostics influence development timelines for manufacturers targeting Tokyo and Osaka medical centers. The pharmaceutical and medical devices agency requires clinical evidence packages that align with international harmonization initiatives. Domestic reagent suppliers leverage JIS quality standards to anchor positions in academic hospital procurement.
India
CDSCO medical device rules and capital constraints on platform acquisition sustain demand for centralized sequencing services in Bangalore and Hyderabad. The central drugs standard control organization classifies nucleic acid diagnostics under risk-based regulatory categories. Contract research facilities absorb procurement from research institutions lacking capital for Illumina or Thermo Fisher instrument placements.
Mirna Tools and Services Market Competitive Environment
Player mix skews toward diversified life science conglomerates with end-to-end sequencing ecosystems, though specialized reagent chemists and cloud-native bioinformatics vendors occupy defensible niches. Market structure concentrates around three archetypes: integrated platform providers locking in consumable revenue, sample stabilization specialists extracting recurring chemistry sales, and analysis-as-a-service vendors addressing computational talent scarcity. Dominant competitive moves include enterprise-wide contract bundling that displaces fragmented laboratory procurement, and regulatory consulting services that attach to wet-lab validation for FDA IVD submissions.
Among integrated platform providers, Thermo Fisher Scientific exemplifies the end-to-end ecosystem archetype spanning library preparation through sequencing instrumentation. QIAGEN occupies a position as the sample stabilization and extraction chemistry specialist with decades of RNA quality control protocol development. Illumina anchors the sequencing instrument placement model that generates locked-in consumable demand from installed base expansion.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| QIAGEN |
| Illumina |
| Agilent Technologies |
| Bio-Rad Laboratories |
| Takara Bio |
| Revvity |
| Promega Corporation |
| Norgen Biotek |
| Others |
Value Chain & Pricing Dynamics
Digital PCR quantification methods displacing traditional qPCR for absolute miRNA copy number determination are simultaneously shifting reagent sourcing toward droplet-based partitioning platform suppliers in the United States and compressing validation economics for diagnostic developers seeking FDA breakthrough device designation.
Pricing Analysis
Cost-plus contracts with indexed raw material adjustments dominate enterprise-wide sequencing consumable agreements at NIH-funded academic medical centers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified clinical-grade reagents from research-use-only chemistry and unvalidated commodity alternatives. Cost compression in mid-tier library preparation kits is intensifying because pharmaceutical sponsors are consolidating procurement across therapeutic area divisions. Mid-sized research institutions lacking capital for in-house platform acquisition exhibit the highest price sensitivity, while large pharma sponsors prioritize regulatory consulting bundling over per-unit reagent costs.
Supply Chain Analysis
Strategic stockpiling of RNA stabilization reagents prevails among multi-site clinical studies facing degradation risks during collection and transport, while just-in-time consumable replenishment dominates high-throughput cancer centers with automated liquid-handling infrastructure. Manufacturing concentration for sequencing instrumentation rests on the United States, China, and Japan, with library preparation chemistry production anchored in Germany and Singapore. Critical dependencies include modified oligonucleotides, fluorescent dyes, and polymerase enzymes. Single-source vulnerability around Illumina instrument placements creates locked-in consumable demand that limits vendor switching. Distribution runs through direct field service teams for enterprise accounts and specialized distributors for mid-tier laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough as NIH funding allocations to non-coding RNA research reaccelerate procurement of next-generation sequencing infrastructure at major academic medical centers.
For Market Incumbents: Shield installed base revenue by embedding regulatory consulting services into wet-lab validation contracts for FDA nucleic acid diagnostic submissions. Deepen backward integration into modified oligonucleotide chemistry to reduce exposure to sole-source suppliers of critical reagent inputs. Enterprise-wide contract bundling across library preparation, sequencing, and bioinformatics support displaces fragmented laboratory procurement and raises switching costs for pharmaceutical sponsors.
For New Entrants and Emerging Players: Anchor in cloud-based bioinformatics outsourcing for mid-sized research institutions lacking computational infrastructure and trained small RNA analysts. Capital-constrained laboratories in India and Southeast Asia represent the most penetrable geography, with centralized contract research facilities absorbing demand that in-house platform acquisition cannot satisfy. A subscription-based analysis-as-a-service model bypasses capital intensity barriers that constrain traditional reagent and instrumentation sales.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized reagent chemists with established ISO 13485 quality management systems and regulatory affairs functions capable of navigating FDA IVD validation timelines. Long-term viability over a multi-year horizon hinges on successful transition from research-use-only products to clinically validated diagnostics with companion diagnostic reimbursement pathways. The signal to watch is payer acceptance frameworks for miRNA-based oncology tests, as reimbursement determination dictates whether research-grade tools achieve routine clinical workflow adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Quality management mandates filter uncertified suppliers and concentrate purchasing power among validated vendors. |
| Cloud-Based Bioinformatics Platform Launch | Specialized vendors address computational talent scarcity in mid-sized research institutions lacking infrastructure. |
| Enterprise-Wide Sequencing Contract Bundling | Consolidated purchasing agreements at Memorial Sloan Kettering and MD Anderson displace fragmented procurement. |
| Regulatory Consulting Service Expansion | FDA nucleic acid diagnostic oversight extends development timelines and creates demand for bundled validation support. |
| Asia-Pacific Contract Research Facility Buildout | Capital constraints in India and Southeast Asia sustain demand for centralized sequencing services over in-house platforms. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) submissions, EMA Medical Device Regulation technical documentation, NIH RePORTER grant databases, and ClinicalTrials.gov registry entries. Conversations with diagnostic development executives, regulatory affairs leads at IVD manufacturers, biomedical engineers at academic medical centers, and procurement managers at pharmaceutical sponsors inform demand-side dynamics. Supply-side validation draws from SEC 10-K filings of diversified life science conglomerates, ISO certification registries, and GPO contract databases. Bottom-up triangulation of reagent consumable volumes and top-down reconciliation against instrument installed base estimates ensure cross-verification.
Segmentation dimensions modeled span product architecture, research application, customer type, and service delivery model across the projection horizon. The analytical framework incorporates library preparation kit throughput rates, sequencing services capacity utilization, and software subscription renewal patterns. CAGRs derive from regression analysis of historical NIH funding allocations, pharmaceutical R&D expenditure trends, and regulatory approval pathway timelines for nucleic acid-based diagnostics. Industry-specific inputs include single-cell miRNA profiling workflow adoption curves and cloud-based bioinformatics outsourcing penetration rates among capital-constrained institutions.
Material uncertainties — NIH funding appropriation volatility, FDA nucleic acid diagnostic guidance revisions, and companion diagnostic reimbursement determinations — sit outside the modeled envelope. Forecasts reflect assumptions about sustained grant allocations and regulatory harmonization trajectories. Revision becomes warranted when payer acceptance thresholds for miRNA-based oncology tests cross critical adoption inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Marine Polysaccharides Fucoidan Alginate Market
Biotechnology Services
Biologics Contract Manufacturing Market
Biotechnology Services
Asia-Pacific Mirna Tools and Services Market
Biotechnology Services
Global Vector Control Market
Biotechnology Services
In-Vitro Fertilization Services Market
Biotechnology Services
Research Antibodies and Reagents Market
Biotechnology Services
Bio-Pharma Logistics Market
Biotechnology Services
Antibody Purification Service Market
Biotechnology Services
Europe Downstream Processing Market
Biotechnology Services
Dnases, Ligases, and RNA Polymerases Market
Biotechnology Services
GMO Testing Services Market
Biotechnology Services
Electrophoresis Market
Biotechnology Services
Global High Throughput Screening Market
Biotechnology Services
Luciferase Assay Market
Biotechnology Services
Membrane Protein Characterization Service Market
Biotechnology Services
Global Bioprocess Validation Market