
 Global Lentiviral Vectors Market | 2026-2036
Global Lentiviral Vectors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lentiviral Vectors Market Foresight
Project finance and dedicated CDMO capacity reservation agreements are reshaping competitive entry in lentiviral vector supply. Oxford Biomedica leverages proprietary LentiVector platform exclusivity to anchor UK and US gene therapy pipelines. Thermo Fisher Scientific sustains global distribution reach through integrated viral vector media and analytics portfolios. Lonza Group competes via purpose-built gene therapy manufacturing campuses in Switzerland and the United States.
Lentiviral vectors are engineered retroviral delivery systems, typically pseudotyped with vesicular stomatitis virus G glycoprotein, designed to stably integrate therapeutic genetic payloads into dividing and non-dividing mammalian cells for ex vivo and in vivo gene modification. Self-inactivating vector types dominate commercial pipelines because their deleted long terminal repeat enhancers reduce insertional oncogenesis risk and satisfy regulatory safety thresholds. Gene therapy applications command the deepest value pools, while stable packaging cell line production methods are gaining share as manufacturers seek lot-to-lot consistency beyond transient transfection batch variability.
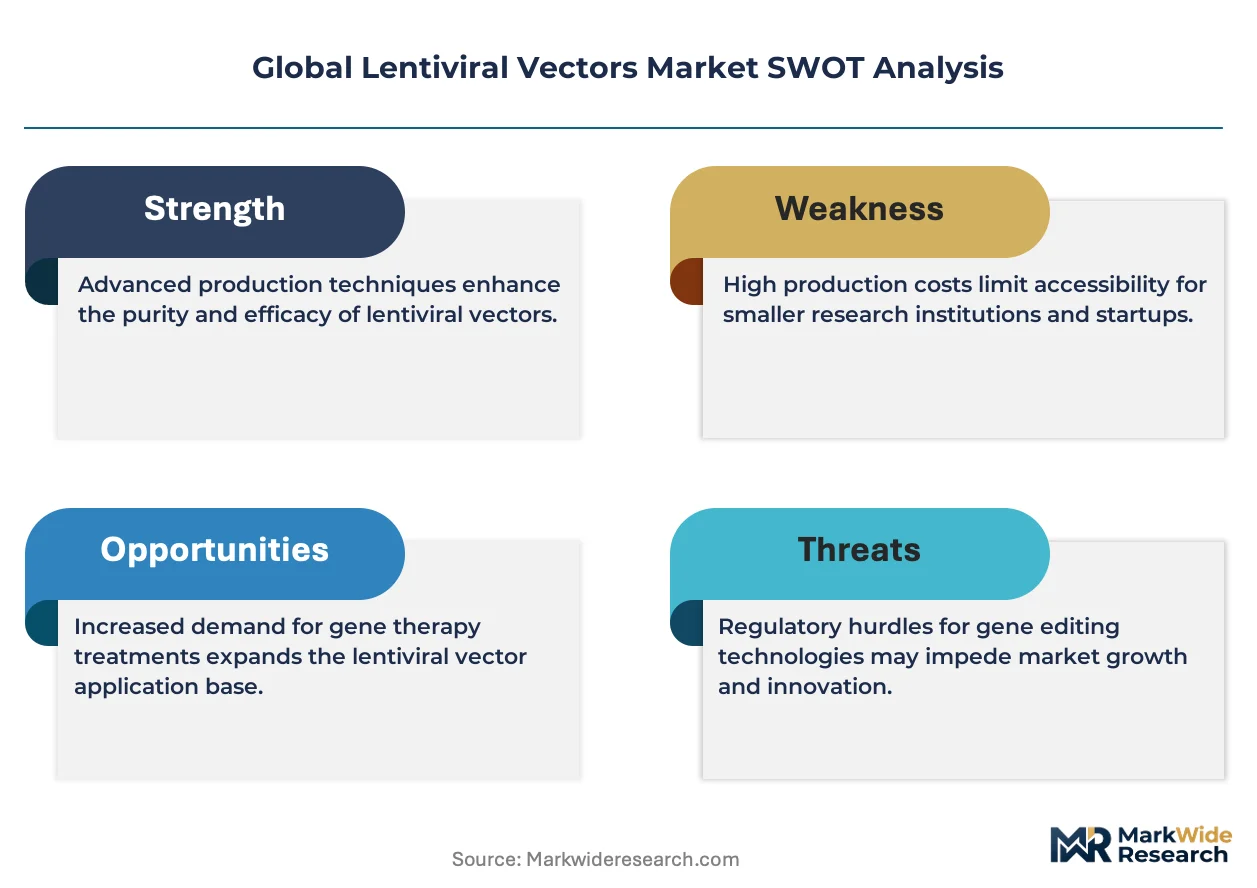
FDA's Chemistry, Manufacturing, and Controls guidance for gene therapy investigational new drugs imposes escalating purity and potency validation burdens that filter out undercapitalized vector developers. EMA's ATMP classification framework and the EU's Good Manufacturing Practice Annex 2 revisions for biological substances further constrain market access for non-compliant suppliers. Stakeholders must monitor emerging FDA guidance on replication-competent retrovirus testing thresholds and EMA parallel scientific advice pathways to anticipate compliance cost trajectories.
Market Dynamics
Stable packaging cell line production is displacing transient transfection methods as manufacturers chase lot-to-lot consistency to meet FDA and EMA potency benchmarks. This upstream process redesign is redrawing competitive entry barriers and forcing capital redeployment across vector supply chains.
Growth Catalysts
- ATMP Classification Framework:EMA's streamlined pathway accelerates commercial authorization timelines for gene therapy developers seeking European market access.
- CAR-T Cell Therapy Programs:Academic medical centers and contract manufacturers are absorbing rising clinical-grade vector volumes for patient-specific immunotherapy manufacturing.
- NIH Manufacturing Consortia:United States federal-private co-funding mechanisms are de-risking dedicated CDMO capacity buildouts for late-stage pipeline support.
Market Restraints
- Plasmid DNA Input Volatility:GMP-grade plasmid supply concentration among North American and European suppliers creates raw material bottleneck risk for transient production runs.
- Replication-Competent Retrovirus Testing Burden:FDA's tightening RCR detection thresholds impose validation cost escalation that filters undercapitalized developers from commercial pipelines.
- Allogeneic Cell Therapy Substitution:Off-the-shelf gene-edited cell platforms reduce per-patient vector dose requirements compared to autologous CAR-T manufacturing.
Strategic Opportunities
- Japan PMDA Sakigake Pathway:Conditional early approval framework attracts vector developers seeking priority review for rare disease indications with unmet need.
- In Vivo Gene Therapy Expansion:Direct CNS and ocular delivery applications bypass ex vivo cell handling infrastructure, opening new addressable patient populations.
- Continuous Bioprocessing Convergence:Integration of perfusion culture with single-use downstream purification reduces facility footprint and media consumption for vector manufacturing.
Industry Challenges
- Cell Line Development Expertise Scarcity:Qualified stable packaging cell line engineers command premium compensation, constraining talent acquisition for mid-tier CDMOs.
- Annex 2 GMP Compliance Timelines:EU biological substance manufacturing revisions require facility requalification cycles that delay batch release for European supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lentiviral Vectors Market |
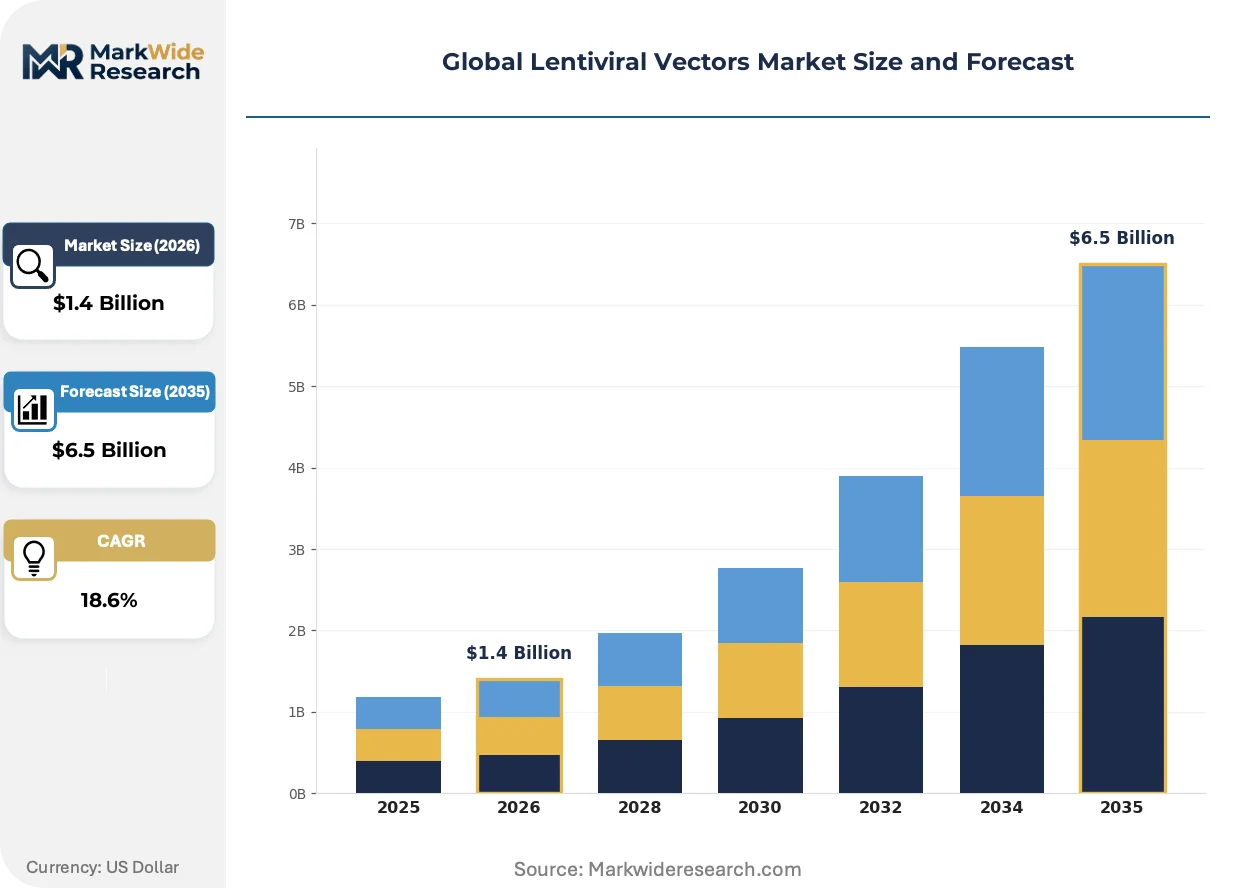
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vector Type: Self-inactivating, Integration-deficient, Pseudotyped, Third-generation, Hybrid Application: Gene Therapy, Cell Engineering, Vaccine Development, Immunotherapy, Functional Genomics End User: Biopharmaceutical Firms, Research Laboratories, Contract Development Organizations, Academic Institutes Production Method: Transient Transfection, Stable Packaging Cell Lines, Suspension Culture, Adherent Culture |
| Companies Covered | Thermo Fisher Scientific, Oxford Biomedica, Merck KGaA, Charles River Laboratories, Lonza Group, Catalent Biologics, WuXi AppTec, FinVector, Takara Bio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lentiviral Vectors Market Shifts & Advancements
Process analytical technology integration and closed-system automation are compressing batch failure rates while regulatory science advances redefine potency assay standards. Vector manufacturing is transitioning from artisanal batch production to standardized platform processes.
Inducible lentiviral packaging systems are migrating from research-grade toolkits into GMP-compliant production workflows. Gene therapy CDMOs at Switzerland's Basel cluster and Massachusetts' Kendall Square corridor are adopting these systems to reduce operator-dependent variability. The technology is migrating from small-batch academic production toward continuous manufacturing architectures that support commercial-scale patient access.
REACH registration requirements for novel viral envelope modifications are forcing European vector developers to submit extended safety dossiers for pseudotyping variants beyond VSV-G. Industrial consequence includes delayed market entry for next-generation tropism-engineered vectors. Developers targeting EU commercialization are responding by front-loading toxicology studies to parallel regulatory track timelines.
Academic medical centers are consolidating vector procurement through master service agreements with tier-one CDMOs rather than maintaining in-house transient transfection suites. This channel consolidation displaces mid-scale internal manufacturing at institutions like the University of Pennsylvania and Stanford Medicine. The shift is most visible in the United States, where NIH funding mechanisms now favor externalized GMP production over capital-intensive institutional buildouts.
Global Lentiviral Vectors Market Segmentation
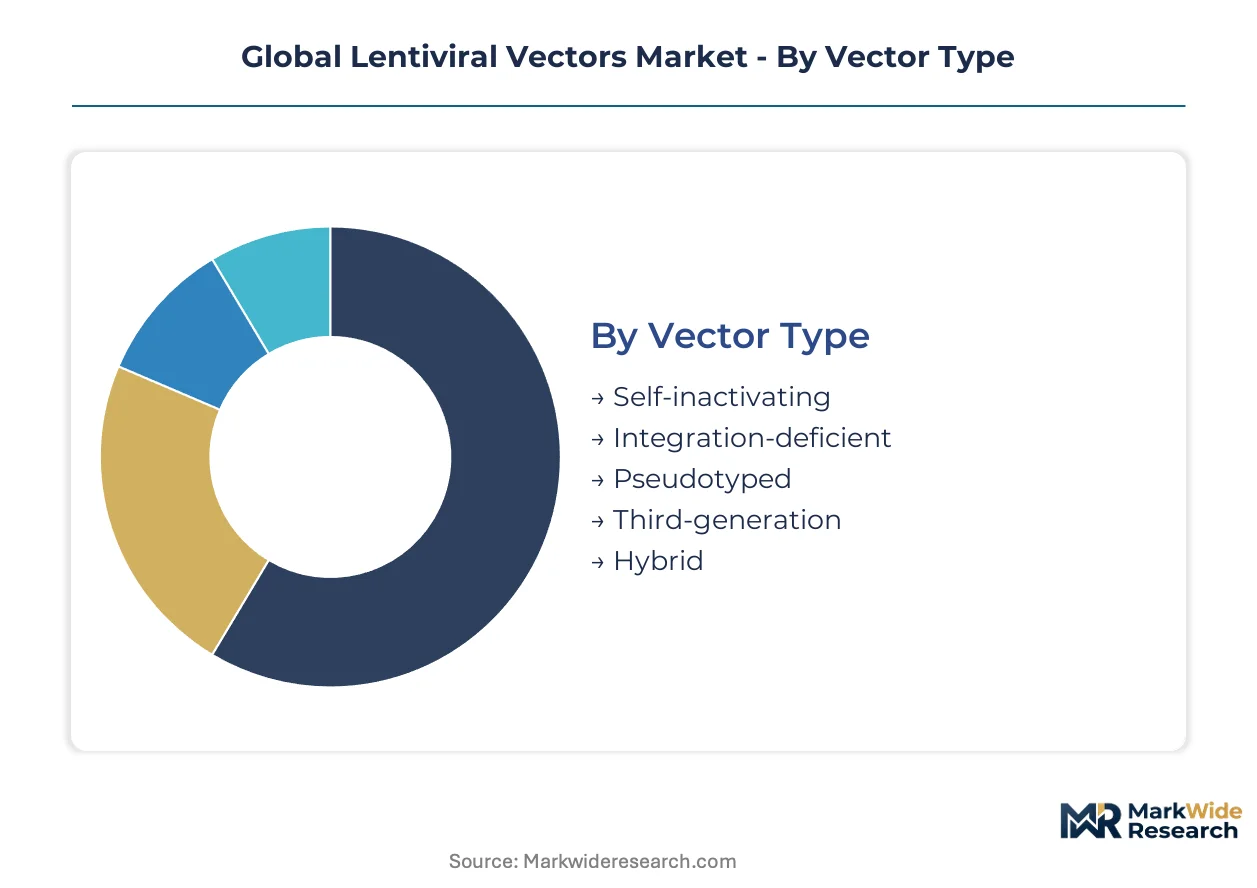
Segmentation in lentiviral vectors reveals how regulatory requirements and manufacturing complexity fragment supply chains. Vector type determines safety profile validation burdens, while production method selection locks in capital intensity for years.
Vector Type:
After-sales service intensity varies sharply by vector type, with self-inactivating variants demanding extensive lot-release documentation support.
- Self-inactivating:Deleted long terminal repeat enhancers eliminate promoter activity to reduce insertional oncogenesis risk. Demand concentrates in FDA-regulated gene therapy pipelines where safety thresholds are non-negotiable; developers absorb premium pricing for regulatory-ready documentation packages.
- Integration-deficient:Episomal persistence mechanisms avoid genomic integration entirely for transient expression applications. Academic medical centers in the United States favor this variant for CRISPR delivery protocols where permanent modification raises ethical review concerns.
- Pseudotyped:VSV-G envelope variants enable broad tropism across mammalian cell types.
- Third-generation:Split-genome designs separate packaging functions across four plasmids.
- Hybrid:Chimeric systems combine lentiviral integration with adenoviral delivery kinetics.
Self-inactivating vectors hold the largest share; momentum sits with integration-deficient alternatives.
Application:
Cost tier stratification separates blockbuster-scale gene therapy from exploratory research applications.
- Gene Therapy:Permanent genetic correction for monogenic diseases drives highest value per dose. Commercial-stage programs at Massachusetts biotech clusters absorb clinical-grade vector volumes for inherited retinal and hematologic indications.
- Cell Engineering:Ex vivo modification of patient-derived cells for autologous therapies. CAR-T manufacturers in Switzerland's Basel region prioritize vector supply security over unit cost given per-patient manufacturing complexity.
- Vaccine Development:Lentiviral delivery of immunogen-encoding sequences for infectious disease prophylaxis.
- Immunotherapy:Tumor-associated antigen presentation enhancement for solid malignancies.
- Functional Genomics:Library-scale screening tools for target identification in pharmaceutical discovery.
Gene therapy commands the deepest value pools; cell engineering applications are expanding most quickly.
End User:
Customer type determines procurement sophistication, with biopharmaceutical firms demanding integrated quality agreements.
- Biopharmaceutical Firms:Integrated gene therapy developers with in-house vector manufacturing capabilities. Large-cap sponsors in the United Kingdom maintain captive production to protect pipeline priority access.
- Research Laboratories:Academic groups requiring research-grade vectors for preclinical proof-of-concept studies.
- Contract Development Organizations:Dedicated CDMOs with platform process expertise serving multiple sponsor pipelines.
- Academic Institutes:University medical centers outsourcing GMP production to specialized manufacturers.
Biopharmaceutical firms dominate procurement volumes; CDMOs are gaining share fastest as externalization accelerates.
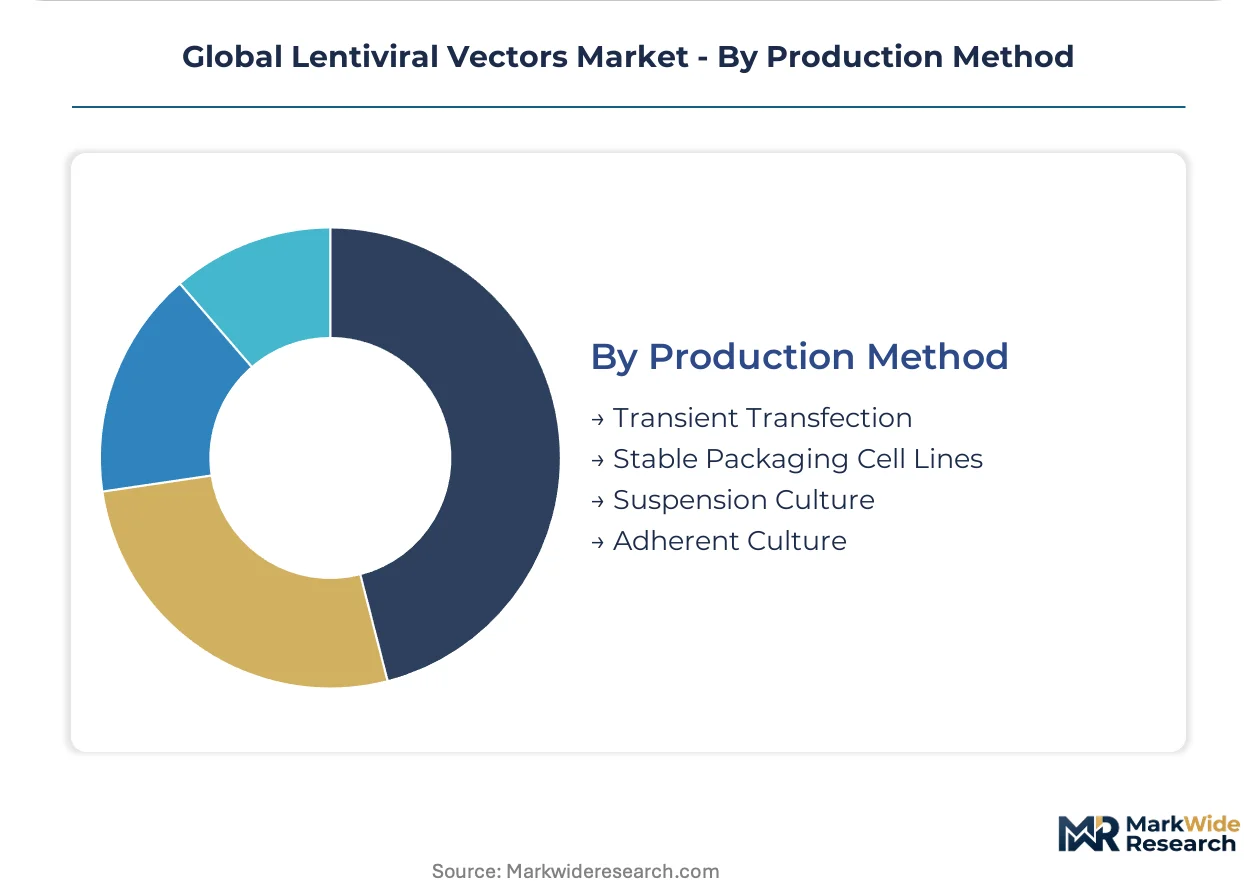
Production Method:
Supply concentration in plasmid DNA inputs shapes method selection for cost-sensitive developers.
- Stable Packaging Cell Lines:Continuous producer clones enabling lot-to-lot consistency for commercial supply. EMA's GMP Annex 2 revisions favor this approach for European market access given reduced operator-dependent variability.
- Transient Transfection:Plasmid co-transfection of HEK293 derivatives for rapid campaign initiation. Early-phase developers in Japan's Kansai biocluster prefer this flexibility for orphan indication programs.
- Suspension Culture:Scalable bioreactor-based production in chemically defined media.
- Adherent Culture:Surface-dependent cell propagation in multi-layer vessel systems.
Stable packaging cell lines anchor commercial supply; transient transfection retains early-phase dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal co-funding mechanisms in the United States are de-risking dedicated CDMO capacity buildouts, while EMA's ATMP classification framework accelerates commercial authorization timelines for European gene therapy developers seeking streamlined market access.
United States
NIH and private foundation consortia absorb rising clinical-grade vector volumes for CAR-T cell therapy programs at academic medical centers. FDA's Chemistry, Manufacturing, and Controls guidance imposes escalating purity and potency validation burdens that filter out undercapitalized developers. Massachusetts' Kendall Square corridor anchors externalized GMP production as institutions consolidate procurement through master service agreements with tier-one CDMOs.
Switzerland
Purpose-built gene therapy manufacturing campuses serve commercial-stage sponsors prioritizing vector supply security over unit cost. Swissmedic maintains alignment with EMA's GMP Annex 2 revisions for biological substances, requiring facility requalification cycles that favor stable packaging cell line adoption. The Basel cluster hosts CDMOs integrating inducible lentiviral packaging systems into GMP-compliant production workflows.
United Kingdom
Proprietary LentiVector platform exclusivity anchors domestic and transatlantic gene therapy pipelines for integrated developers maintaining captive production. The Medicines and Healthcare products Regulatory Agency implements EMA-aligned ATMP frameworks while preserving national flexibility for early-access schemes. Oxfordshire-based manufacturing protects pipeline priority access for large-cap sponsors.
Japan
The PMDA Sakigake pathway attracts vector developers seeking conditional early approval for rare disease indications with unmet need. Early-phase developers in the Kansai biocluster prefer transient transfection flexibility for orphan indication programs. Osaka-based academic medical centers balance in-house research-grade production with selective outsourcing for clinical transition.
Germany
Federal research funding supports stable packaging cell line engineering expertise development amid industry-wide talent scarcity. ECHA's REACH registration requirements for novel viral envelope modifications force extended safety dossier submission for pseudotyping variants beyond VSV-G. Heidelberg and Munich clusters concentrate process analytical technology integration for closed-system automation.
Global Lentiviral Vectors Market Competitive Landscape
On the supply side, the industry is consolidating around platform-process specialists with regulatory-ready documentation capabilities and captive capacity reservation agreements. Tier-one CDMOs with purpose-built gene therapy campuses compete against integrated biopharmaceutical firms maintaining in-house vector manufacturing. Two strategic archetypes dominate: technology licensors leveraging proprietary delivery platforms, and scale operators with integrated media and analytics portfolios. Capacity expansion and strategic partnerships represent the dominant competitive moves, as manufacturers chase lot-to-lot consistency to meet tightening FDA and EMA potency benchmarks.
Among platform-technology specialists, Oxford Biomedica occupies a position exemplifying proprietary LentiVector exclusivity in UK and US pipeline anchoring. Thermo Fisher Scientific and Lonza Group represent the integrated-scale archetype, with the former sustaining global distribution reach through combined media and analytics offerings, and the latter competing via purpose-built manufacturing campuses in Switzerland and the United States. These three entities collectively illustrate the bifurcation between technology-driven and capacity-driven competitive positioning.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Oxford Biomedica |
| Merck KGaA |
| Charles River Laboratories |
| Lonza Group |
| Catalent Biologics |
| WuXi AppTec |
| FinVector |
| Takara Bio |
| Others |
Supply & Pricing Matrix
Trans-Atlantic cold-chain logistics corridors connecting Basel and Boston absorb premium freight costs that cascade through GMP-grade vector pricing, concentrating margin pressure on transient transfection suppliers while amplifying price spreads between research-grade and clinical-grade tiers.
Pricing Analysis
Certification level creates the primary spread between clinical-grade and research-grade vector supply, with FDA master file documentation and EMA ATMP-compliant lot release commanding three-to-five-fold premiums over preclinical material. Three-tier pricing structure across premium, standard, and economy levels stratifies by potency assay rigor and viral titer consistency guarantees. Cost compression in standard-grade supply is intensifying as stable packaging cell line adoption reduces batch failure rates and reprocessing expenses. Academic medical centers exhibit highest price sensitivity, prioritizing per-dose unit economics in competitive grant environments, while integrated biopharmaceutical firms absorb premium pricing to secure supply security for commercial-stage assets.
Supply Chain Analysis
Export-control regimes governing dual-use biological technologies restrict plasmid DNA and packaging cell line flows between designated jurisdictions, fragmenting supplier networks and extending qualification timelines for cross-border manufacturing partnerships. GMP-grade plasmid DNA concentrates in the United States, Germany, and Switzerland, while HEK293-derived producer cell banks draw from proprietary lineages held by a handful of academic licensors. Single-source vulnerability pervades VSV-G pseudotyping reagent supply, with envelope glycoprotein production tethered to captive bioreactor capacity at major CDMO campuses. Distribution runs through temperature-controlled specialist couriers under validated shipper qualification, with batch release documentation trailing physical delivery by seven to fourteen days.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vector manufacturing services attach growing revenue streams as sponsors outsource potency assay development, stability testing, and regulatory documentation packages at margins exceeding upstream production economics.
For Market Incumbents: Entrench platform-process exclusivity through backward integration into plasmid DNA foundry operations, securing raw material sovereignty against transient transfection supply shocks. Expand captive capacity in Switzerland and Massachusetts to preempt competitor entry into CAR-T vector supply. FDA's tightening replication-competent retrovirus detection thresholds favor incumbents with validated assay infrastructure that filters undercapitalized challengers. For New Entrants and Emerging Players: Establish a beachhead in Japan's orphan indication segment, where PMDA Sakigake pathway flexibility rewards agile transient transfection campaigns over capital-intensive stable line investment. Target academic medical centers consolidating procurement through master service agreements, displacing in-house manufacturing at institutions like Stanford Medicine and the University of Pennsylvania. Lead with regulatory documentation bundling rather than unit cost to differentiate from commodity vector suppliers. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates divesting non-core gene therapy manufacturing assets amid pipeline reprioritization toward small-molecule and biologic modalities. Five-to-ten-year viability hinges on stable packaging cell line engineering talent retention and EMA GMP Annex 2 compliance infrastructure. The signal to watch is NIH funding mechanism shifts favoring externalized CDMO production over institutional capital buildouts, which would accelerate channel consolidation and platform-process M&A premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Stable Packaging Cell Line Migration | Lot-to-lot consistency gains satisfy FDA potency benchmarks and reduce batch failure rates at commercial scale. |
| Regulatory Documentation Bundling | Integrated quality agreements with EMA-aligned ATMP frameworks accelerate sponsor market access timelines. |
| Continuous Bioprocessing Adoption | Perfusion culture integration with single-use purification reduces facility footprint and media consumption. |
| Plasmid DNA Foundry Backward Integration | Captive GMP-grade plasmid supply insulates against raw material bottleneck risk in transient production. |
| Inducible Packaging System Licensing | Research-grade toolkit migration into GMP workflows reduces operator-dependent variability at Basel and Kendall Square CDMOs. |
Research Methodology
Cross-validation between primary interviews with vector manufacturing executives, regulatory affairs specialists, and academic principal investigators anchors the qualitative findings against secondary sources including FDA gene therapy guidance documents, EMA ATMP classification frameworks, and ClinicalTrials.gov pipeline tracking. Bottom-up triangulation incorporates CDMO capacity utilization disclosures, NIH funding award databases, and GMP facility inspection records, while top-down calibration draws from pharmaceutical R&D expenditure allocations and gene therapy M&A transaction patterns across the analysis window.
Calibration against historical vector demand curves and CAR-T patient treatment forecasts shapes the analytical framework across vector type, production method, application, and end-user segmentation dimensions. CAGRs derive from regression-adjusted adoption curves incorporating regulatory approval velocity, manufacturing yield improvements, and substitution effects from allogeneic cell therapy platforms. Industry-specific inputs include stable packaging cell line engineering timelines, plasmid DNA lead time volatility, and EMA GMP Annex 2 compliance cost trajectories.
Stress conditions across FDA guidance revision timing, NIH funding continuity, and allogeneic therapy substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory science advancement and manufacturing technology maturation. Material shifts in EMA ATMP commercial authorization pathways or replication-competent retrovirus testing standard harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Europe Cancer Vaccines Market
Cell & Gene Therapy
GMP Cell Banking Services Market
Cell & Gene Therapy
Global Human DNA Vaccines Market
Cell & Gene Therapy
Stem Cell Therapy Market
Cell & Gene Therapy
Oncolytic Virus Therapy Market
Cell & Gene Therapy
Gene Delivery Technologies Market
Cell & Gene Therapy
Asia-Pacific Viral Vector Purification Market
Cell & Gene Therapy
Global Cell Based Immunotherapy Market
Cell & Gene Therapy
Ipilimumab Market
Cell & Gene Therapy
Europe Stem Cell Therapy Market
Cell & Gene Therapy
Middle East and Africa Viral Vector Purification Market
Cell & Gene Therapy
Global Mrna Therapeutics Market
Cell & Gene Therapy
Leukapheresis Products Market
Cell & Gene Therapy
Global Cell and Gene Therapy Manufacturing Services Market
Cell & Gene Therapy
Stem Cell Concentration System Market
Cell & Gene Therapy
Leukemia Therapeutics Treatment Market