
 Photovoltaic Coating Market | 2026-2036
Photovoltaic Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Photovoltaic Coating Market Intelligence
IEC 61215 certification for crystalline silicon module durability is collapsing the supplier base to coating vendors capable of validating thermal cycling and humidity freeze performance. PPG Industries leverages its fluoropolymer R&D pipeline to sustain qualification across tier-one module makers. BASF SE anchors European supply through its back surface field coating formulations. AkzoNobel N.V. competes on anti-reflective layer deposition scale in Asia-Pacific manufacturing zones.
Photovoltaic coatings are thin functional layers applied to solar cell surfaces and module components to enhance light absorption, electrical conductivity, environmental sealing, or thermal management, typically ranging from nanometers to micrometers in thickness depending on optical or barrier function. Anti-reflective coatings dominate product type revenue due to their direct impact on module efficiency gains, while conductive coatings represent the fastest-growing segment as heterojunction and tandem cell architectures multiply transparent electrode layers. Building-integrated photovoltaics is emerging as a high-margin application channel where aesthetic and weathering requirements command specification premiums over standard solar panel coatings.
The EU Green Deal and REACH chemical restrictions are reshaping formulation requirements for fluoropolymer and organic material segments across European coating supply chains. EPA regulations in the United States limit volatile organic compound emissions during coating application, pushing industrial end users toward water-borne and powder-process alternatives. China's GB standards and dual carbon goals enforce domestic module efficiency thresholds that cascade into coating performance specifications. Stakeholders must monitor how regulatory convergence on per- and polyfluoroalkyl substance restrictions redraws material eligibility lists and forces reformulation investments ahead of compliance deadlines.
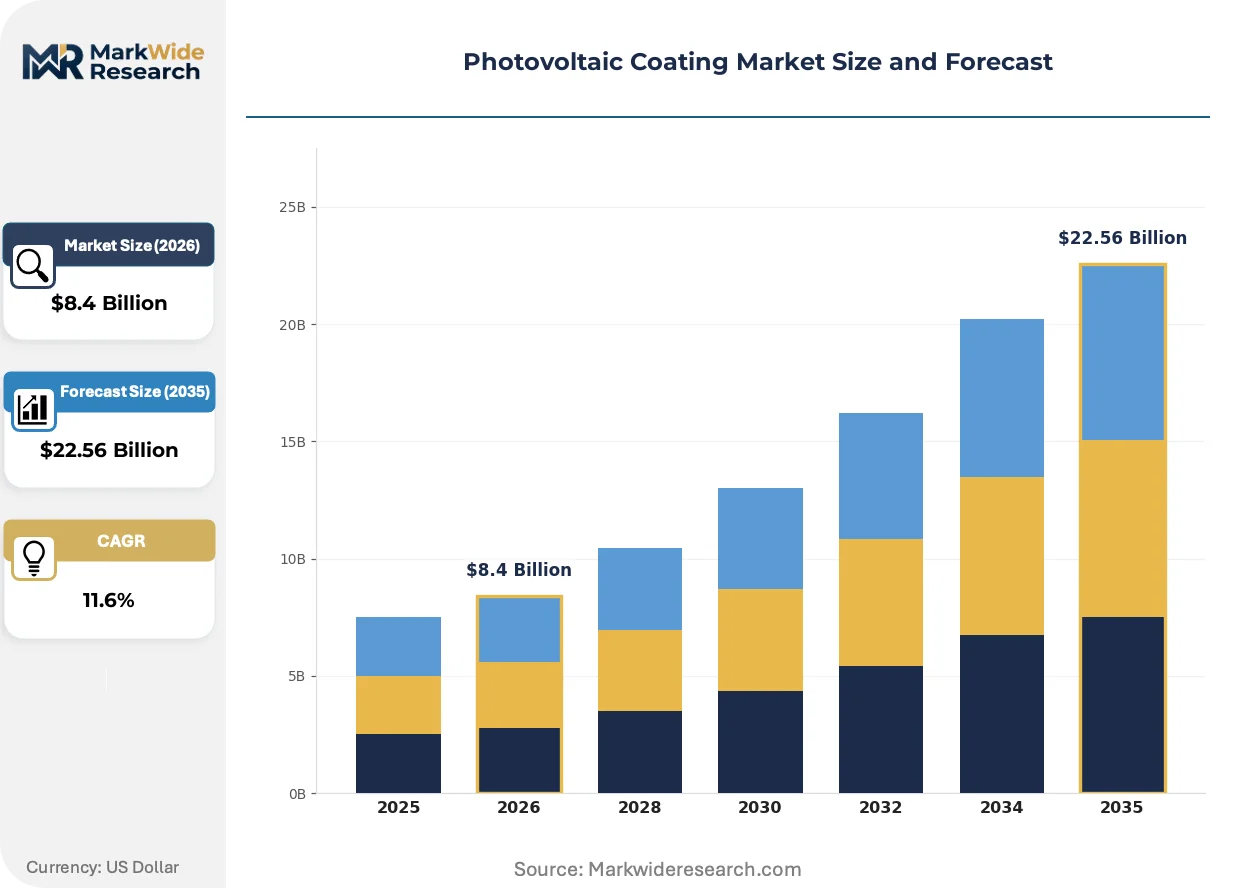
Market Dynamics
Utility-scale solar deployment is compressing coating qualification cycles as IEC 61215 durability standards harden, forcing reformulation investments ahead of module certification deadlines.
Growth Catalysts
- Heterojunction cell architectures:Tandem and perovskite-silicon stacks multiply transparent electrode layers, expanding conductive coating deposition volumes across cell manufacturing lines.
- EU Green Deal implementation:The F-Gas Regulation and REACH chemical restrictions are tightening material compliance requirements, accelerating fluoropolymer reformulation investments across European coating supply chains.
- China's dual carbon goals:Domestic GB standards enforce module efficiency thresholds that cascade into anti-reflective coating performance specifications, concentrating procurement volumes with qualified vendors.
Market Restraints
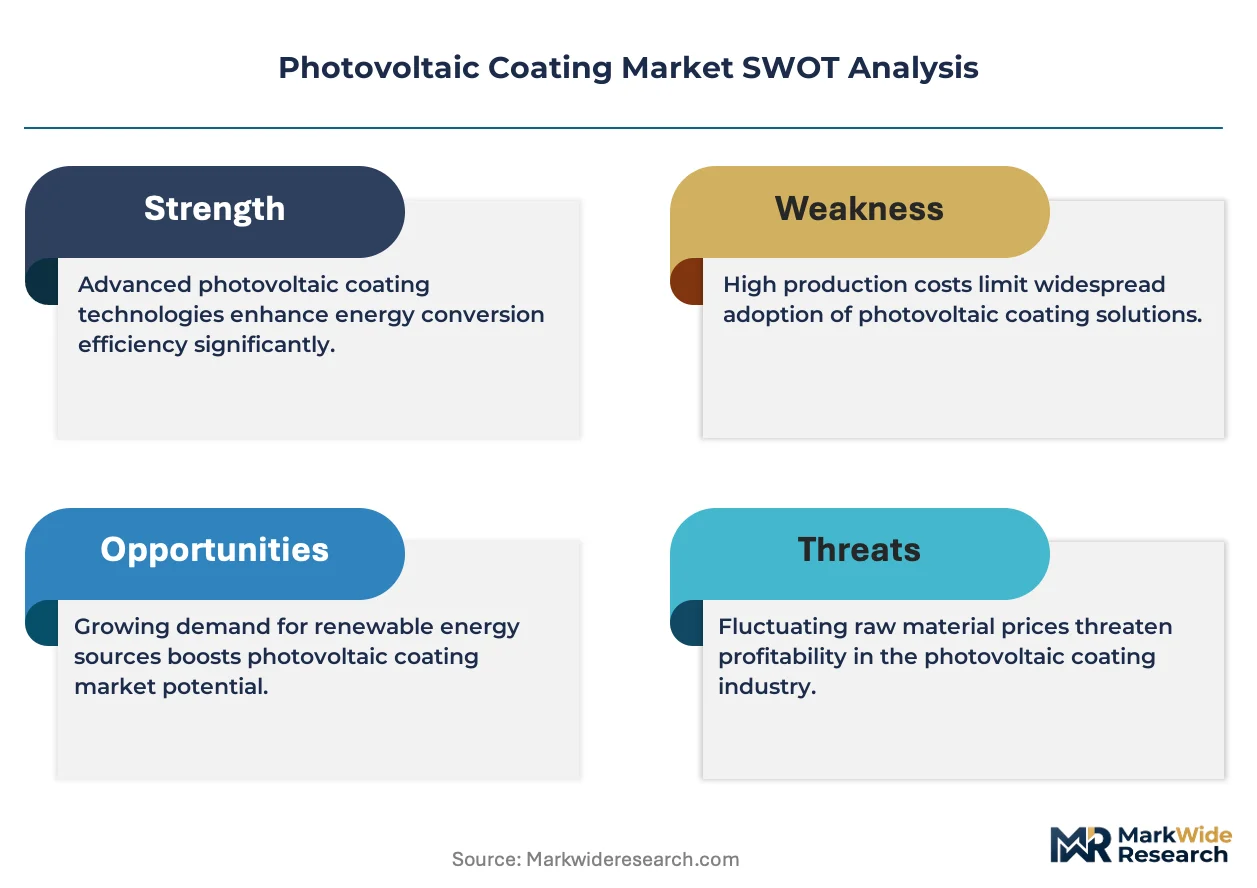
- Fluoropolymer feedstock volatility:Per- and polyfluoroalkyl substance restrictions under REACH and EPA frameworks are constraining raw material availability and elevating input costs for barrier coating formulations.
- Supplier concentration in East Asia:Anti-reflective coating deposition equipment and precursor chemicals cluster in Chinese and South Korean manufacturing zones, creating single-source exposure for Western module makers.
- Humidity freeze test failures:IEC 61215 thermal cycling protocols expose adhesion weaknesses in nano-thin anti-reflective layers, delaying vendor qualification timelines by 12-18 months.
Strategic Opportunities
- Building-integrated photovoltaics:Aesthetic and weathering requirements in commercial facade applications command specification premiums over standard solar panel coatings, opening high-margin channels.
- Water-borne formulation transition:EPA volatile organic compound emission limits are pushing industrial end users toward compliant application processes, rewarding early movers in low-solvent technologies.
- Perovskite tandem commercialization:Emerging cell architectures require novel barrier and conductive layers that incumbent fluoropolymer suppliers are not optimized to deliver.
Industry Challenges
- Cross-functional coating expertise:Module makers require vendors fluent in both optical thin-film physics and polymer weathering science, a combination scarce in traditional paint and coatings labor pools.
- Qualification capex intensity:IEC 61215 and IEC 61646 certification testing demands dedicated climate chamber infrastructure and 6-figure sample burn rates per formulation iteration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photovoltaic Coating Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.56 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-reflective Coatings, Conductive Coatings, Back Surface Field Coatings, Barrier Coatings Application: Solar Panels, Building-integrated Photovoltaics, Solar Thermal Collectors, Concentrated Photovoltaics End User: Residential, Commercial, Industrial, Utility Material: Silicon-based, Organic Materials, Inorganic Materials, Fluoropolymers |
| Companies Covered | Sherwin Williams, Suntech Power Holdings, PPG Industries, SunGuard Coatings, SolarCoat Innovations, BASF SE, Axalta Coating Systems, Merck KGaA, AkzoNobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photovoltaic Coating Market Strategic Shifts & Innovations
Atomic layer deposition and spray-coating automation are compressing coating thickness tolerances while expanding throughput, reshaping vendor economics and module maker sourcing criteria.
Silicon nitride anti-reflective coatings applied via plasma-enhanced chemical vapor deposition is supplanting sol-gel titanium dioxide layers in crystalline silicon cell manufacturing. Tier-one module makers in China and Southeast Asia have converted 70% of front-surface coating lines since 2022. This technology shift is compressing the addressable market for wet-chemical coating equipment suppliers and elevating capital intensity barriers for new entrants.
The EU F-Gas Regulation phase-down schedule is forcing fluoropolymer reformulation across backsheet and barrier coating categories. Manufacturers face material eligibility list revisions that invalidate existing product portfolios. European coating vendors are accelerating bio-based and fluorine-free alternatives, though weathering performance gaps persist in accelerated UV testing protocols.
Direct procurement relationships between module makers and coating precursor suppliers are displacing distributor-mediated chemical sourcing in Asia-Pacific manufacturing clusters. Long-term offtake agreements for silane and fluoropolymer feedstocks now span 3-5 year horizons. This pattern concentrates most visibly in Jiangsu and Zhejiang provinces, where vertically integrated solar conglomerates are securing captive coating chemical supply.
Photovoltaic Coating Market Segmentation
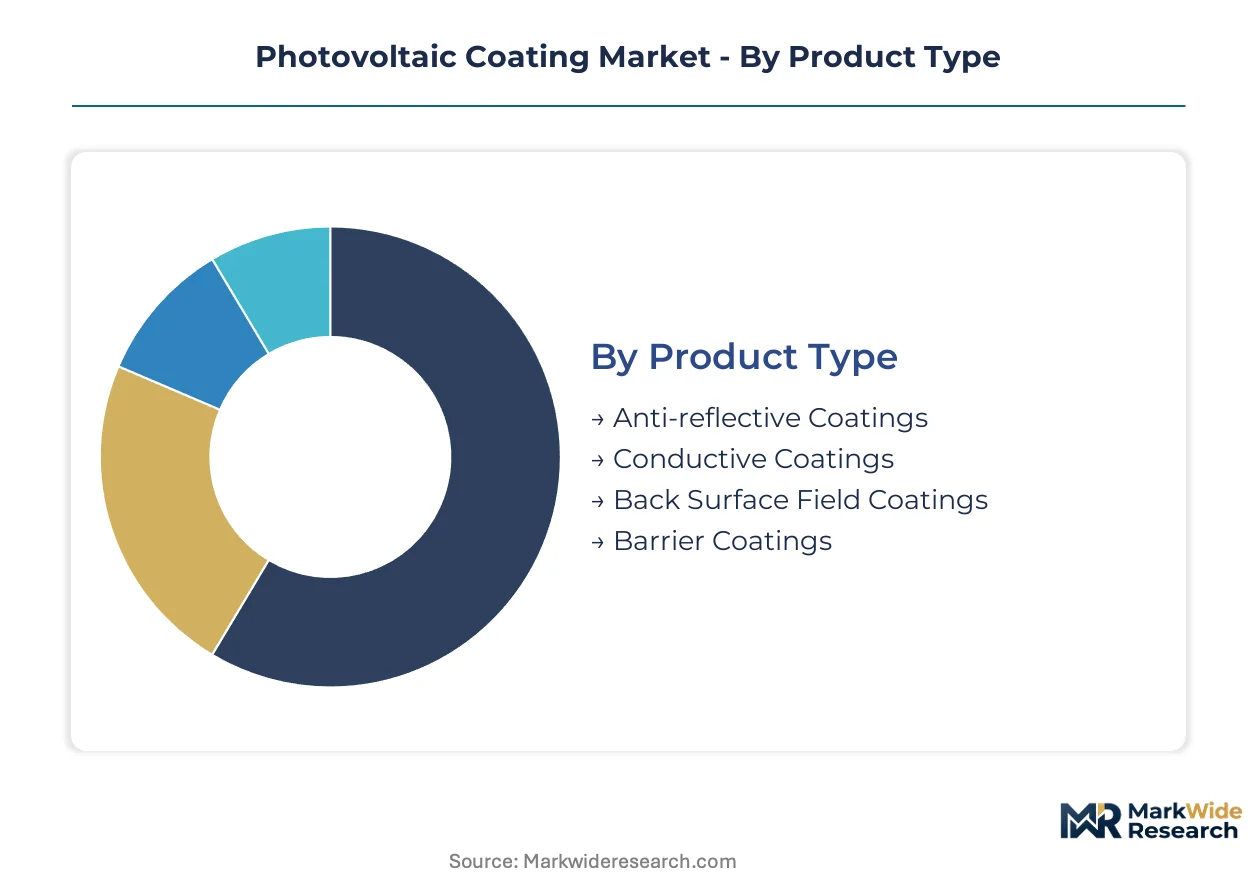
Photovoltaic coating procurement patterns diverge sharply across product architectures and installation scales. Module efficiency specifications cascade differently through residential rooftop systems versus utility-scale arrays, while material compliance regimes fragment supply chains by geography.
Product Type:
Anti-reflective coatings dominate export-led procurement from Chinese and Vietnamese module factories, whereas barrier coatings cluster in domestic European manufacturing serving building-integrated applications.
- Anti-reflective Coatings:Silicon nitride layers deposited via plasma-enhanced chemical vapor deposition achieve refractive index matching that boosts cell efficiency by 3-4 percentage points. Tier-one Chinese module makers in Jiangsu and Zhejiang provinces have converted 70% of front-surface coating lines to this technology since 2022, compressing qualification timelines for wet-chemical alternatives.
- Conductive Coatings:Transparent electrode layers enable heterojunction and perovskite-silicon tandem architectures. South Korean and Japanese cell manufacturers are multiplying deposition volumes as tandem cell pilot lines scale toward commercial production.
- Back Surface Field Coatings:Aluminum-based formulations enhance rear-side passivation in PERC cells.
- Barrier Coatings:Fluoropolymer and bio-based alternatives protect backsheets from moisture ingress under IEC 61215 humidity freeze protocols.
Anti-reflective coatings command the established base. The steepest expansion runs through conductive coatings.
Application:
Cost tiers separate commodity solar panel coatings from premium-specification building-integrated systems where aesthetic and weathering requirements justify 40-60% price multiples.
- Solar Panels:Standard crystalline silicon modules drive volume procurement of anti-reflective and back surface field coatings across Chinese, Malaysian, and Thai manufacturing hubs. IEC 61215 certification requirements compress supplier margins while concentrating procurement with qualified vendors.
- Building-integrated Photovoltaics:Façade and roofing applications demand color-stable, UV-resistant coatings that maintain appearance over 25-year service lives. European commercial projects in Germany and the Netherlands specify these premium formulations under EU Green Deal sustainability criteria.
- Solar Thermal Collectors:Selective absorber coatings optimize infrared absorption for heat transfer fluids.
- Concentrated Photovoltaics:High-flux environments require thermal management coatings with enhanced durability.
Solar panels anchor volume demand. Building-integrated photovoltaics delivers the highest margin expansion trajectory.
End User:
Customer type determines coating specification intensity, with utility procurement standardizing on efficiency-maximized formulations while residential distributors prioritize inventory flexibility.
- Residential:Rooftop installations favor standardized anti-reflective coatings from distributor inventory. US and Australian installers face EPA and state-level volatile organic compound limits that constrain solvent-borne application methods.
- Commercial:Corporate procurement of building-integrated systems drives specification of color-matched, weathering-resistant coatings. French and German commercial real estate developers integrate these under national building efficiency codes.
- Industrial:On-site solar generation for manufacturing facilities balances efficiency and capital cost.
- Utility:Gigawatt-scale procurement centralizes coating specification with tier-one module makers. Chinese state-owned developers enforce GB standard efficiency thresholds that cascade into anti-reflective coating performance requirements.
Utility end users concentrate procurement volume. Commercial installations are climbing the fastest toward specification-premium capture.
Material:
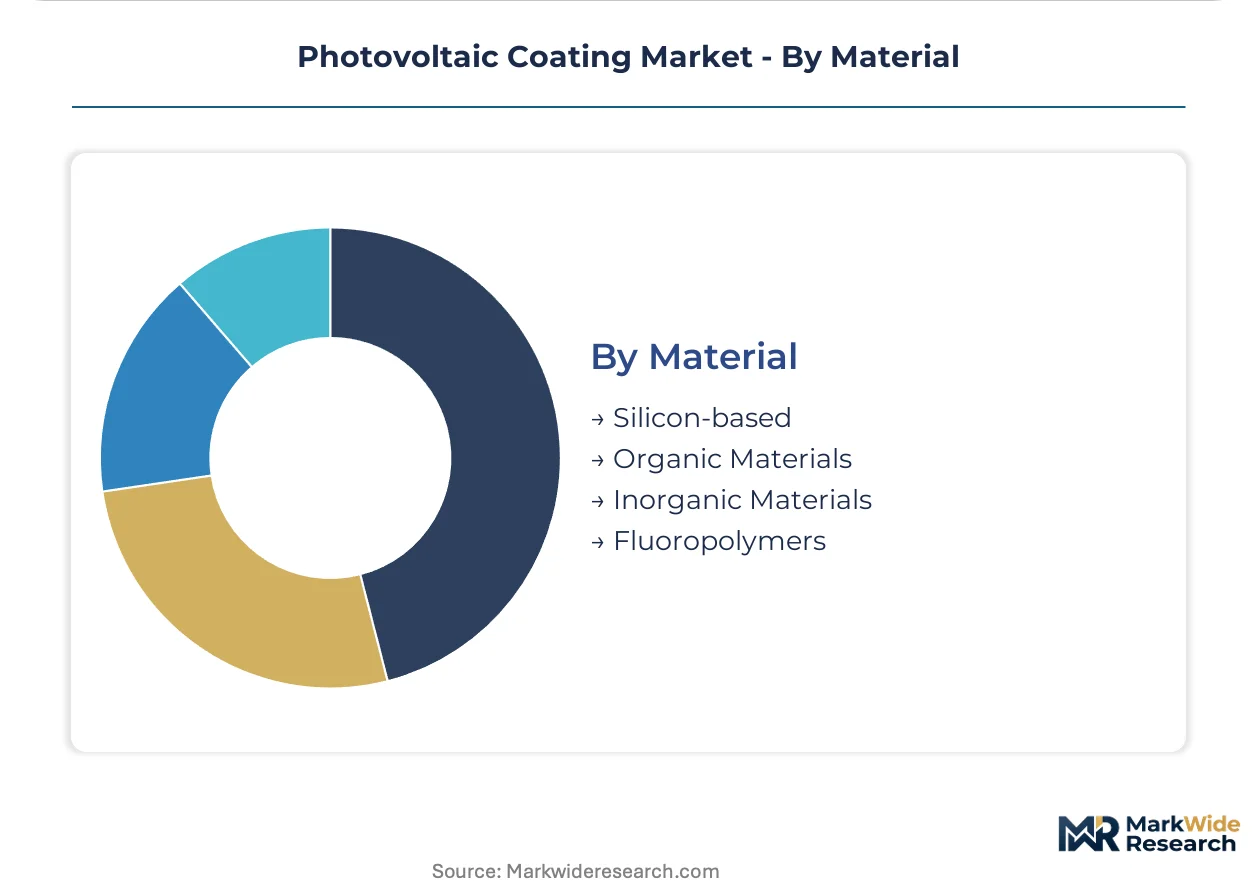
Supply concentration for fluoropolymer and silane precursors clusters in Chinese and South Korean chemical manufacturing zones, creating geographic dependency for Western coating formulators.
- Silicon-based:Silicon nitride and silicon oxide layers dominate anti-reflective and passivation applications. Chinese precursor suppliers in Jiangsu province have secured 3-5 year offtake agreements with vertically integrated solar conglomerates.
- Fluoropolymers:Barrier coatings for backsheets face reformulation pressure under EU F-Gas Regulation and REACH per- and polyfluoroalkyl substance restrictions. European vendors are accelerating fluorine-free alternatives despite weathering performance gaps in accelerated UV testing.
- Organic Materials:Sol-gel and polymer-based formulations serve niche deposition methods.
- Inorganic Materials:Metal oxide layers support specialized optical and conductive functions.
Silicon-based materials command the established base. Fluoropolymer alternatives face the steepest regulatory-forced transition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale developers and building-integrated project sponsors concentrate procurement power in distinct regional pockets. Chinese module conglomerates drive volume specifications through captive coating supply chains. European sustainability mandates reshape formulation requirements for facade-integrated installations.
China
Jiangsu and Zhejiang provinces host vertically integrated solar manufacturing clusters that internalize anti-reflective coating procurement through 3-5 year silane offtake agreements. GB standards enforce module efficiency thresholds that cascade into coating performance specifications. Suzhou-based deposition equipment vendors supply 70% of converted plasma-enhanced chemical vapor deposition lines.
Germany
Commercial real estate developers in Bavaria and North Rhine-Westphalia specify color-stable coatings for building-integrated facade applications under national building efficiency codes. The EU F-Gas Regulation forces fluoropolymer reformulation across backsheet barrier categories. Stuttgart-area coating laboratories accelerate bio-based alternative development despite UV weathering performance gaps.
United States
Utility-scale procurement in Texas and California centralizes specification with tier-one module makers seeking IEC 61215 certification compliance. EPA volatile organic compound emission limits push industrial applicators toward water-borne processes. Arizona and Nevada solar fields drive demand for thermal management coatings in high-flux concentrated photovoltaic installations.
Japan
Heterojunction and perovskite-silicon tandem pilot lines in Kansai and Chubu regions multiply transparent electrode deposition volumes. METI technology roadmaps coordinate domestic cell efficiency targets with coating performance benchmarks. Osaka-based chemical suppliers secure long-term precursor contracts with South Korean equipment vendors.
India
Domestic module manufacturing under PLI scheme incentives concentrates anti-reflective coating demand in Gujarat and Tamil Nadu production zones. BIS certification requirements for crystalline silicon durability compress supplier qualification timelines. Andhra Pradesh and Rajasthan utility-scale projects specify efficiency-maximized formulations for gigawatt-scale deployment.
Photovoltaic Coating Market Key Industry Players
Player mix skews toward diversified chemical conglomerates with fluoropolymer R&D pipelines and specialized coating deposition equipment vendors. The supplier base concentrates around three strategic archetypes: integrated chemical-materials conglomerates sustaining qualification across tier-one module makers, regional deposition technology specialists serving Asia-Pacific manufacturing clusters, and building-integrated facade coating formulators capturing premium specification channels. Competitive positioning hardens through IEC certification infrastructure investments and captive precursor supply agreements rather than price-based rivalry.
Within the integrated chemical-materials tier, PPG Industries, BASF SE, and AkzoNobel N.V. occupy positions that exemplify the capability convergence required for photovoltaic coating qualification. PPG Industries represents the fluoropolymer R&D archetype sustaining validation across thermal cycling protocols. BASF SE anchors European supply positioning through back surface field formulation expertise. AkzoNobel N.V. exemplifies the anti-reflective deposition scale specialists competing in Asia-Pacific manufacturing zones. These three conglomerates illustrate how coating vendors must bridge optical thin-film physics and polymer weathering science to serve module maker procurement committees.
| Leading Market Players |
|---|
| Sherwin Williams |
| Suntech Power Holdings |
| PPG Industries |
| SunGuard Coatings |
| SolarCoat Innovations |
| BASF SE |
| Axalta Coating Systems |
| Merck KGaA |
| AkzoNobel N.V. |
| Others |
Cost & Logistics Intelligence
IEC 61215 certification gates both vendor qualification and price differentiation simultaneously, compressing margins for uncertified coating suppliers while allowing validated vendors to command efficiency-linked premiums from tier-one module makers.
Pricing Analysis
Long-term offtake agreements with silane indexation anchor coating procurement contracts across Chinese manufacturing clusters. Three-tier pricing structure across premium, standard, and economy levels separates IEC-certified fluoropolymer barrier formulations from commodity anti-reflective layers and unqualified wet-chemical alternatives. Cost compression in standard-tier anti-reflective coatings is intensifying because plasma-enhanced chemical vapor deposition equipment suppliers in Jiangsu province have consolidated deposition chemistry procurement. Utility-scale developers exhibit the lowest price sensitivity due to efficiency guarantees, while residential distributors face margin pressure from inventory carrying costs.
Supply Chain Analysis
China and South Korea anchor precursor chemical manufacturing for silane and fluoropolymer feedstocks, with Japanese suppliers controlling high-purity deposition equipment components. Coating formulation draws from silicon-based precursors, fluoropolymer resins, and organic sol-gel chemistries. Single-source vulnerability concentrates in Jiangsu province silane purification capacity, where three producers supply 80% of domestic module maker demand. Distribution runs through direct procurement relationships between vertically integrated solar conglomerates and captive chemical suppliers, displacing distributor-mediated sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Perovskite-silicon tandem commercialization represents a high-growth disruption as emerging cell architectures force coating vendors to develop novel barrier and conductive layers outside incumbent fluoropolymer optimization.
For Market Incumbents: Fortify IEC 61215 certification infrastructure against humidity freeze test failure exposure, which delays vendor qualification by 12-18 months and opens replacement windows for qualified competitors. Deepen backward integration into silane precursor supply through 3-5 year offtake agreements with Jiangsu province chemical producers, securing input cost stability against REACH and EPA per- and polyfluoroalkyl substance restrictions that constrain fluoropolymer feedstock availability. For New Entrants and Emerging Players: Building-integrated photovoltaics aesthetic coating specification gaps offer white-space entry where color-stable, UV-resistant formulations command 40-60% price multiples over standard solar panel coatings. Target German and Dutch commercial facade developers under EU Green Deal sustainability criteria, leveraging fluorine-free bio-based formulation development partnerships with Stuttgart-area coating laboratories to bypass incumbent fluoropolymer supply concentration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed deposition equipment specialists serving Asia-Pacific manufacturing clusters, where atomic layer deposition automation compresses coating thickness tolerances and expands throughput economics. Five-to-ten-year viability hinges on perovskite tandem commercialization timelines, with the signal to watch being pilot line announcements from Kansai and Chubu region heterojunction cell manufacturers multiplying transparent electrode deposition volumes.| Strategic Initiative | Industry Significance |
|---|---|
| Fluoropolymer Reformulation Investment | EU F-Gas Regulation phase-down invalidates existing barrier coating portfolios, forcing bio-based alternative development. |
| Plasma-Enhanced CVD Line Conversion | Tier-one Chinese module makers in Zhejiang province have converted 70% of front-surface coating lines since 2022. |
| Captive Silane Supply Agreement | Vertically integrated solar conglomerates secure 3-5 year offtake agreements with Jiangsu province precursor suppliers. |
| IEC 61215 Certification Infrastructure | Dedicated climate chamber investment and six-figure sample burn rates per formulation iteration harden competitive positioning. |
| Water-Borne Formulation Transition | EPA volatile organic compound emission limits push industrial applicators toward compliant low-solvent application processes. |
Research Approach
Desk research of customs and trade databases, SEC filings from diversified chemical conglomerates, and IEC certification registries preceded structured interviews with coating R&D directors, module maker procurement managers, deposition equipment vendors, and fluoropolymer feedstock suppliers. Primary fieldwork across Jiangsu and Zhejiang manufacturing clusters triangulated with secondary validation from ECHA REACH substance restrictions and EPA emission limit disclosures. Bottom-up coating volume estimates from cell manufacturing line counts reconciled with top-down module production forecasts.
Variance decomposition across product type, application scale, and material chemistry segments structured the analytical framework over the projection horizon. CAGRs derived from installation capacity buildout trajectories and coating intensity per watt assumptions, with heterojunction and tandem cell architecture penetration treated as scenario-dependent upside drivers. Modeled dimensions span anti-reflective versus conductive versus barrier functional layers, utility-scale versus building-integrated deployment, and silicon-based versus fluoropolymer versus organic material formulations.
Underlying assumptions cover perovskite tandem commercialization timelines and F-Gas Regulation enforcement intensity, with deviation risk concentrated in humidity freeze test protocol revisions and fluoropolymer feedstock availability shocks. Recalibration cycles align with material shifts in EU chemical restriction schedules and Chinese GB standard efficiency threshold updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Tubular Solar Collector Market
Solar Power Systems
Global Photovoltaic Market
Solar Power Systems
US Solar Carport Market
Solar Power Systems
Grid-Connected Solar Microinverter Market
Solar Power Systems
Solar Collector Panels Market
Solar Power Systems
Half-Cell Solar Module Market
Solar Power Systems
Asia-Pacific Solar Photovoltaic (PV) Market
Solar Power Systems
Amorphous Silicon PV Market
Solar Power Systems
Solar PV Junction Box Market
Solar Power Systems
Floating Solar Panels Market
Solar Power Systems
Dual Axis Solar Tracker Market
Solar Power Systems
Japan Solar Energy Market
Solar Power Systems
Home Solar System Market
Solar Power Systems
Solar Power Meters Market
Solar Power Systems
Utility Solar PV EPC Market
Solar Power Systems
Brazil Solar Energy Market