
 Fluid Transfer System Market | 2026-2036
Fluid Transfer System Market Size, Share, and Industry Trends Forecast 2026-2036
Fluid Transfer System Market Analysis
Electric vehicle thermal management is expanding its share of fluid transfer specification volumes, displacing traditional internal-combustion fuel and brake line demand. TI Fluid Systems leads in battery cooling circuit development for European and Chinese EV platforms. Cooper Standard anchors its position through polymer formulation R&D for lightweight, chemically resistant hose compounds. Parker Hannifin Corp differentiates via hydraulic system integration across off-highway and industrial end users.
Fluid transfer systems comprise engineered assemblies of pumps, hoses, fittings, and valves designed to convey liquids, gases, or multiphase media under controlled pressure, temperature, and flow parameters, typically manufactured from elastomeric compounds, thermoplastics, or corrosion-resistant metals. Their primary purpose is to ensure leak-free, efficient media movement across industrial process lines, vehicle powertrains, and energy infrastructure. Hoses capture the largest margin pool due to material science intensity and replacement frequency, while electric actuation technology is displacing pneumatic controls in precision applications. Pumps dominate capital expenditure in chemical processing and water treatment installations where duty cycles and reliability requirements are most severe.
EPA fuel-economy and emissions regulations in the US, REACH chemical restrictions in Europe, and China's GB standards for automotive components collectively tighten permissible material compositions and pressure ratings for fluid transfer products. These frameworks force manufacturers to reformulate elastomers and validate new compounds through extended durability testing, raising barriers for suppliers lacking in-house polymer laboratories. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance strategies optimized for one geography may not satisfy emerging requirements in another.
Market Dynamics
Automotive electrification is compressing specification volumes for traditional fuel and brake lines while amplifying demand for lightweight thermal management circuits, forcing incumbent suppliers to retool polymer formulation capabilities toward chemically resistant, high-temperature elastomers.
Growth Catalysts
- EPA Fuel-Efficiency Mandates:US emissions standards are tightening permissible pressure ratings and material compositions for fluid-carrying components, accelerating validation cycles for advanced hose compounds in passenger vehicle platforms.
- Battery Cooling Circuit Demand:Electric vehicle OEMs in Germany's automotive supplier corridor around Stuttgart and Munich are specifying multi-layer thermal management hoses that withstand glycol-based coolants at elevated temperatures.
- REACH Chemical Compliance:European restrictions on phthalates and heavy-metal additives are pushing manufacturers toward bio-based elastomer formulations and fluoropolymer alternatives in industrial process lines.
Market Restraints
- Specialty Polymer Supply Concentration:Fluoroelastomer feedstock production concentrates among Japanese and German chemical suppliers, exposing hose manufacturers to input cost volatility and allocation constraints during demand surges.
- Extended Validation Timelines:OEM thermal cycling and chemical immersion testing protocols now span 18-24 months for new EV cooling circuit designs, compressing supplier development budgets and delaying revenue recognition.
- Pneumatic Actuation Substitution:Electric servo valves are displacing compressed-air controls in precision dispensing and medical fluid handling, eroding demand for traditional pneumatic hose assemblies in high-accuracy segments.
Strategic Opportunities
- India Automotive Component Manufacturing:PLI scheme incentives for advanced automotive technology are attracting fluid transfer system suppliers to establish localized hose extrusion and connector molding capacity for domestic EV platforms.
- Hydrogen Fuel Cell Infrastructure:High-pressure hydrogen dispensing systems require specialized polymer-lined composite hoses with permeation barriers, creating specification white space distinct from legacy fuel handling equipment.
- Data Center Liquid Cooling:Direct-to-chip thermal management systems are adopting quick-connect couplings and chemically inert tubing for dielectric fluid circulation, opening non-automotive demand channels for precision fluid handling components.
Industry Challenges
- Polymer Compounding Expertise Gap:Formulation chemists capable of balancing chemical resistance, permeation performance, and extrusion processability in multi-layer hose structures remain scarce relative to specification demand from electrified powertrain programs.
- Legacy System Integration Complexity:Industrial process operators face friction retrofitting smart sensor-integrated fluid monitoring into existing piping architectures without disrupting continuous production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluid Transfer System Market |
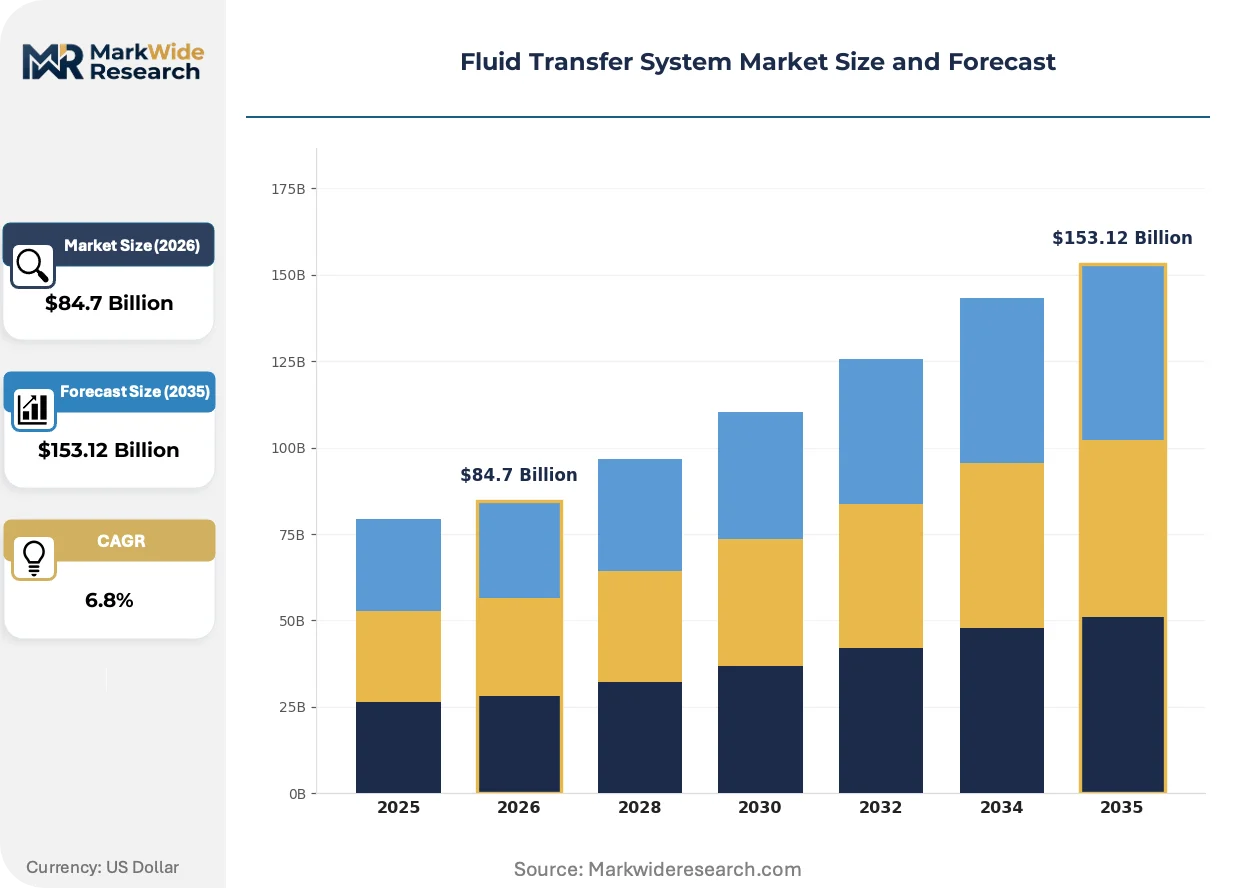
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $153.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pumps, Hoses, Fittings, Valves End User: Manufacturing, Oil & Gas, Automotive, Aerospace Technology: Hydraulic, Pneumatic, Electric, Mechanical Application: Chemical Processing, Water Treatment, Fuel Transfer, Food Processing |
| Companies Covered | Cooper Standard, TI Fluid Systems, Sumitomo Riko Company Limited, Parker Hannifin Corp, Gates Corporation, Akwel, Kongsberg Automotive, Sanoh Industrial Co., Ltd., Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluid Transfer System Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are converging to redefine fluid transfer system specifications across automotive, industrial, and energy infrastructure end uses.
Thermoplastic elastomer blends with dynamic vulcanization are expanding into battery cooling circuits for electric vehicles, offering weight reduction and recycling advantages over conventional rubber hoses. European and Chinese OEMs are adopting these materials at accelerated validation cycles for 2026-2028 platform launches. This expansion is compressing demand for cured-rubber architectures in thermal management applications while elevating specification authority toward polymer laboratories with in-house compounding capabilities.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of fuel hose inner liners and industrial chemical transfer tubes across European manufacturing bases. Compounders must validate alternative barrier polymers through extended permeation and aging protocols, raising technical barriers for suppliers lacking accelerated testing infrastructure. Automotive fuel system and chemical process equipment segments are responding with phased material transitions and dual-source qualification strategies to mitigate supply continuity risk.
Specification consolidation among tier-one automotive thermal management integrators is compressing the supplier base for EV battery cooling circuits. German and Chinese OEMs are reducing qualified hose and connector vendors from six-to-eight per platform to three-to-four preferred partners with full-system design responsibility. This concentration is most visible in Stuttgart and Munich supplier corridors, where proximity-driven technical collaboration now determines specification inclusion more than component pricing alone.
Fluid Transfer System Market Segmentation
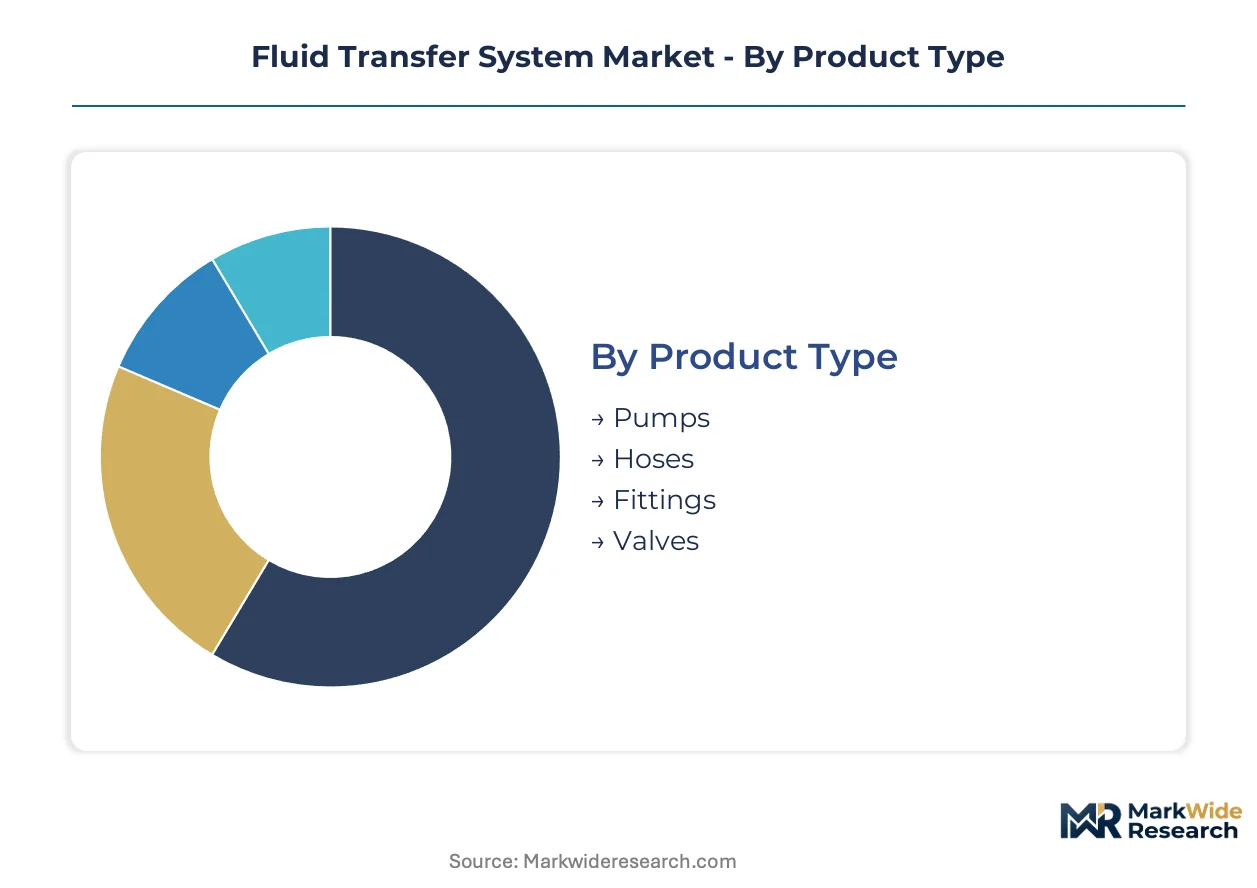
Fluid transfer system specifications diverge sharply based on whether components operate as standalone subsystems or embed within larger thermal management architectures. Segmentation reveals where polymer science intensity concentrates versus where commoditized volume production dominates procurement decisions.
Product Type:
Hoses and pumps anchor fundamentally different value chains—one driven by material formulation cycles, the other by capital equipment procurement patterns—while fittings and valves occupy intermediate positions between these poles.
- Hoses:Multi-layer elastomeric or thermoplastic assemblies conveying pressurized fluids through dynamic routing paths. Demand concentrates in Stuttgart and Munich automotive corridors where OEMs specify glycol-compatible thermal management circuits for battery platforms; EPA fuel-efficiency mandates accelerate validation cycles for lightweight compounds.
- Pumps:Positive displacement or centrifugal mechanisms generating controlled flow rates against system head pressure. Chemical processing installations in Germany and water treatment facilities across US industrial corridors drive capital expenditure; duty cycle reliability requirements dominate specification authority.
- Fittings:Connection hardware sealing hose-to-component interfaces through threaded, quick-connect, or crimped geometries.
- Valves:Flow control devices regulating pressure, direction, or isolation within fluid circuits.
Volume placements concentrate in Hoses; the faster expansion belongs to Pumps.
End User:
Customer procurement patterns split between specification-intensive automotive programs and price-sensitive industrial maintenance cycles, with aerospace representing a certification-isolated tier.
- Automotive:OEM and tier-one supplier procurement of thermal management, fuel, and brake line assemblies. Battery cooling circuit demand from German and Chinese EV platforms is displacing traditional internal-combustion fuel line volumes; REACH chemical compliance tightens permissible elastomer formulations.
- Manufacturing:Industrial process lines requiring chemical transfer, cooling water, and hydraulic power distribution. US EPA emissions standards and OSHA process safety regulations govern material selection for high-pressure chemical handling.
- Oil & Gas:Upstream production and downstream refining infrastructure for hydrocarbon conveyance.
- Aerospace:Aircraft fuel, hydraulic, and environmental control systems subject to FAA certification protocols.
Procurement scale peaks in Manufacturing; specification intensity climbs fastest in Automotive.
Technology:
Actuation mechanisms define competitive boundaries between legacy pneumatic incumbents and electric servo entrants disrupting precision segments.
- Hydraulic:Fluid power systems using incompressible oil media for high-force transmission. Off-highway equipment manufacturers and German industrial automation integrators specify Parker Hannifin-integrated systems; pressure ratings exceed pneumatic alternatives for heavy-duty material handling.
- Electric:Servo motor-driven precision actuation displacing compressed-air controls in medical fluid handling and dispensing accuracy applications. Battery cooling circuit valve actuation in European EV platforms favors electric over pneumatic for thermal cycling durability.
- Pneumatic:Compressed-air power transmission for general automation and legacy industrial processes.
- Mechanical:Direct-coupled or gravity-fed systems without external power actuation.
Installed base dominance rests with Hydraulic; electric actuation is gaining share fastest in precision segments.
Application:
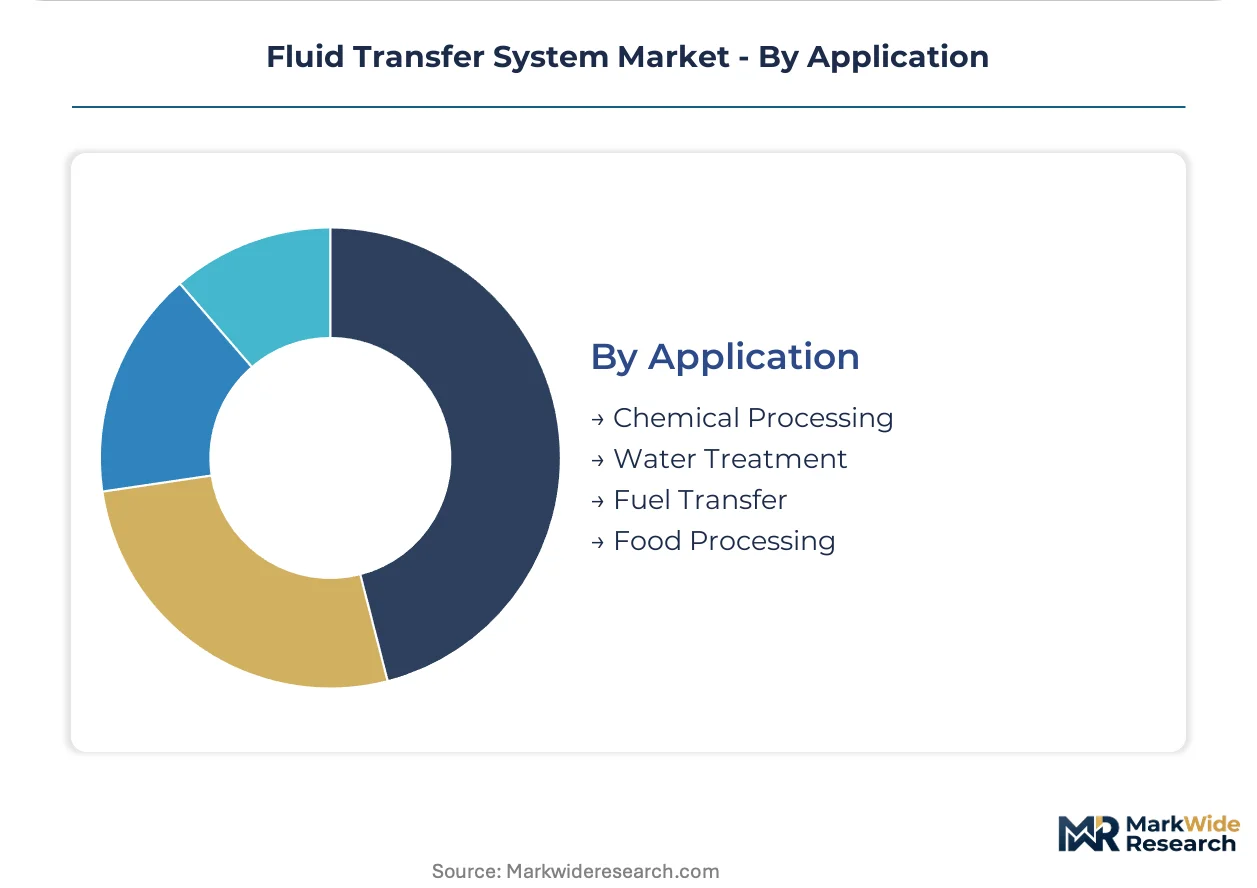
Process severity and media chemistry determine whether specifications prioritize chemical resistance, sanitary design, or high-pressure containment.
- Chemical Processing:Corrosive media handling requiring fluoropolymer-lined hoses and alloy pump housings. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force European compounders toward alternative barrier polymers; extended permeation validation protocols raise technical barriers.
- Fuel Transfer:Hydrocarbon conveyance systems for automotive and aviation platforms. EPA emissions regulations in the US and GB standards in China tighten permeation specifications for fuel hose inner liners; multi-layer thermoplastic structures displace conventional rubber architectures.
- Water Treatment:Municipal and industrial purification, distribution, and wastewater handling infrastructure.
- Food Processing:Sanitary-grade stainless steel and FDA-compliant polymer systems for edible product contact.
Specification complexity peaks in Chemical Processing; standardization pressure is most intense in Water Treatment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production Linked Incentive scheme for advanced automotive technology is drawing fluid transfer system suppliers toward localized hose extrusion and connector molding capacity. Special economic zones in Gujarat and Tamil Nadu offer tax advantages for component manufacturers serving domestic EV platforms.
United States
EPA fuel-efficiency mandates tighten permissible pressure ratings for automotive fluid-carrying components. The agency's emissions standards accelerate validation cycles for advanced hose compounds in passenger vehicle platforms. Detroit's automotive supplier corridor concentrates specification authority for thermal management circuits among tier-one integrators.
Germany
Battery cooling circuit demand from Stuttgart and Munich OEMs specifies multi-layer thermal management hoses for glycol-based coolants. ECHA REACH restrictions on phthalates push manufacturers toward bio-based elastomer formulations. Baden-Württemberg's supplier corridor leverages proximity-driven technical collaboration to determine specification inclusion.
China
GB standards for automotive components tighten material compositions for fluid transfer products alongside MIIT electrification targets. NMPA-aligned durability protocols force reformulation of elastomers through extended testing. Yangtze River Delta EV manufacturers concentrate demand for lightweight thermal management circuits displacing traditional fuel lines.
Japan
METI industrial policy supports hydrogen fuel cell infrastructure deployment requiring specialized polymer-lined composite hoses. JIS standards govern high-pressure containment specifications for alternative fuel systems. Nagoya's automotive supplier base anchors development of permeation barrier technologies for next-generation fluid handling.
Fluid Transfer System Market Vendor Landscape
Top-tier vendors anchor specification authority for EV thermal management circuits, while mid-tier compounders compete on polymer formulation agility. The supplier base compresses as German and Chinese OEMs reduce qualified vendors per platform from six-to-eight to three-to-four preferred partners. Two strategic archetypes dominate: integrated thermal management system designers and specialized elastomer compounders with in-house laboratories. Competitive moves concentrate on backward integration into polymer feedstock and geographic expansion toward India PLI scheme zones.
Within the integrated system designer tier, TI Fluid Systems and Parker Hannifin Corp exemplify contrasting geographic emphases. TI Fluid Systems occupies a position anchored in European and Chinese EV platform development. Parker Hannifin Corp represents the hydraulic power transmission archetype across off-highway and industrial end users. Cooper Standard sits within the polymer formulation specialist category, emphasizing lightweight hose compound development.
| Leading Market Players |
|---|
| Cooper Standard |
| TI Fluid Systems |
| Sumitomo Riko Company Limited |
| Parker Hannifin Corp |
| Gates Corporation |
| Akwel |
| Kongsberg Automotive |
| Sanoh Industrial Co., Ltd. |
| Continental AG |
| Others |
Supply Flow & Price Mechanics
Thermoplastic elastomer adoption in battery cooling circuits simultaneously compresses per-unit material costs and concentrates specification authority among compounders with captive polymer laboratories. This production-method transition rewards German and Chinese OEMs with lighter hose architectures while squeezing margin pools for suppliers lacking in-house formulation capabilities.
Pricing Analysis
Short lead-time premiums distinguish fluid transfer procurement, with EV platform engineers paying 15-25% markups for validated hose compounds against 18-24 month validation timelines versus spot inventory discounts for standard industrial grades. Contract-based long-term offtake dominates automotive thermal management, while commodity spot purchasing persists in manufacturing maintenance cycles. Price differentiation hinges on REACH-compliant certification tiers and volume scale, with tier-one integrators commanding leverage unavailable to aftermarket distributors. Cost compression in standard rubber hose tiers is intensifying because thermoplastic structures displace legacy architectures, eroding margins for non-specialized compounders. Manufacturing procurement teams exhibit highest price sensitivity due to maintenance budget constraints, whereas German OEM platform engineers prioritize technical collaboration over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from Stuttgart and Munich OEMs require qualified hose vendors to maintain parallel compound supply relationships, fragmenting procurement across Japanese and German fluoroelastomer feedstock producers. Geographic supply concentration centers on Germany for automotive specification authority, China for EV platform volume, and Japan for permeation barrier technologies. Raw material dependencies rest on fluoropolymer resins, synthetic rubber feedstocks, and corrosion-resistant metal alloys. Single-source vulnerability concentrates in Japanese fluoroelastomer production, exposing hose manufacturers to allocation constraints during demand surges. Distribution runs through tier-one thermal management integrators who consolidate component sourcing before OEM platform integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as specification authority compresses toward three-to-four preferred partners per platform, forcing weaker compounders without captive laboratories into acquisition or exit.
For Market Incumbents: Extend polymer formulation capabilities through backward integration into specialty resin supply, securing allocation priority during Japanese feedstock constraints. Add capacity in Gujarat and Tamil Nadu PLI zones to capture domestic Indian EV platform demand before qualification windows close. Reinforce specification relationships with Stuttgart corridor OEMs through co-located technical collaboration centers, defending against thermoplastic elastomer substitution threats from emerging compounders. For New Entrants and Emerging Players: Begin with hydrogen fuel cell infrastructure hoses, where permeation barrier specifications remain unsettled and incumbent qualification advantages are weakest. Target data center liquid cooling applications for dielectric fluid handling, a non-automotive channel where precision coupling expertise transfers directly from medical fluid handling experience. Pursue qualification partnerships with Yangtze River Delta EV manufacturers seeking second-source battery cooling circuit suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to tier-one thermal management integrators seeking to fill polymer compounding capability gaps. Five-to-ten year viability favors compounders with REACH-compliant bio-based elastomer pipelines and Indian manufacturing footprints. Acquisition target archetype: mid-cap German or Japanese hose specialists with validated EV platform relationships but constrained capital for geographic expansion. Watch for inflection in ECHA per- and polyfluoroalkyl substance restriction enforcement timelines, which would accelerate alternative barrier polymer qualification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstock | Captive fluoroelastomer supply insulates margin from Japanese allocation constraints during demand surges. |
| Geographic Manufacturing Footprint Expansion | Gujarat and Tamil Nadu capacity captures PLI scheme incentives for domestic Indian EV platform supply. |
| REACH-Compliant Formulation Pipeline | Bio-based elastomer development preempts ECHA Annex XVII restrictions on conventional barrier polymers. |
| Long-term Supply Agreement | Multi-year thermal management contracts with Stuttgart OEMs lock out competitor qualification during platform transitions. |
| Joint Venture with Tier-One Integrator | Co-development partnerships concentrate specification authority for EV battery cooling circuit architectures. |
Methodological Framework
Independent corroboration across tier-one supplier procurement directors, OEM platform engineers, and polymer laboratory technical directors underwrites the qualitative findings in this study. Primary interviews with thermal management system architects, aftermarket distribution channel managers, and regulatory compliance officers combined with secondary validation from SEC 10-K filings, customs and trade databases, and vehicle production registries. Bottom-up segment sizing and top-down market triangulation cross-checked against IHS Markit registration data and ACC industry reports.
Rate-of-change decomposition separates volume growth from value expansion across product type, end user, technology, and application dimensions throughout the forecast period. Segmentation modeling incorporates propulsion architecture shifts, content per vehicle trajectories, and regional production cluster concentration. CAGRs derive from validated platform launch timelines, OEM thermal management specification volumes, and replacement cycle frequencies for hose assemblies in chemical processing installations.
Underlying measurement precision varies by segment; automotive battery cooling circuit specifications carry tighter precision than industrial maintenance hose demand due to visible OEM platform commitments. Forecasts reflect assumptions about REACH enforcement timelines, PLI scheme disbursement continuity, and fluoroelastomer supply allocation patterns. Deviation in ECHA per- and polyfluoroalkyl substance restriction scope or Japanese feedstock production capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
United States Subsea Pumps Market
Pumps and Control Devices
Sanitary Pumps Market
Pumps and Control Devices
Global Mobile Hydraulic Pump Market
Pumps and Control Devices
APAC Positive Displacement Pumps Market
Pumps and Control Devices
Peristaltic Pumps Market
Pumps and Control Devices
Water Intake Screens Market
Pumps and Control Devices
Hydraulic Pumps Market
Pumps and Control Devices
Global Variable Displacement Pumps Market
Pumps and Control Devices
High Power Air Pump Market
Pumps and Control Devices
Marine Pump Market
Pumps and Control Devices
Volute Pump Market
Pumps and Control Devices
Electrohydraulic Pumps Market
Pumps and Control Devices
Intelligent Pump Market
Pumps and Control Devices
Electrostatic Spraying System Market
Pumps and Control Devices
Latin America Centrifugal Pumps Market
Pumps and Control Devices
Hydraulic Dosing Pump Market