
 Asia-Pacific Solar Photovoltaic (PV) Market | 2026-2036
Asia-Pacific Solar Photovoltaic (PV) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Solar Photovoltaic (PV) Market Outlook
Silver paste is repositioning cell metallization economics as copper-interconnect architectures gain traction across Asia-Pacific fabs. LONGi Green Energy Technology Co., Ltd. leverages integrated ingot-to-module capacity to compress production costs. JA Solar Holdings Co anchors its position through PERC-to-TOPCon migration across Chinese manufacturing bases. Adani Green Energy Ltd dominates Indian project development with backward integration into polysilicon and wafering.
Solar photovoltaic systems convert sunlight into direct-current electricity through semiconductor junctions, with monocrystalline silicon cells achieving conversion efficiencies exceeding 22% in mass production. These installations serve grid-connected generation, distributed commercial power, and rural electrification across archipelagic and mainland territories. Bifacial modules capture reflected irradiance from ground surfaces, widening yield premiums in high-albedo desert and snow-prone regions. Rooftop installations face structural constraints in dense Asian megacities, pushing margin pools toward ground-mounted utility arrays with standardized civil engineering. Thin-film cadmium-telluride retains niche relevance where weight restrictions or high-temperature coefficients degrade crystalline performance.
China's MIIT enforces GB standards for module efficiency and fire safety, while India's BIS certification mandates local testing laboratories for imported equipment. Australia's CEC maintains an approved product register that filters market access for inverter and panel suppliers. Japan's METI feed-in tariff transition to auction-based procurement is forcing developers to sharpen capital efficiency assumptions. Stakeholders must track how subsidy phase-outs in South Korea and emerging ASEAN markets reshape project finance structures.
Market Dynamics
Silver paste metallization economics are collapsing as copper-interconnect architectures rewrite cell fabrication cost structures across Asia-Pacific fabs, forcing incumbent suppliers to defend margin pools through rapid process retooling or exit.
Growth Catalysts
- India's PLI scheme:Domestic solar module manufacturing incentives redirect supply chain investments toward captive polysilicon and wafering capacity, reducing import dependency for project developers.
- Utility-scale procurement acceleration:Southeast Asian power utilities are tendering multi-gigawatt ground-mounted arrays with standardized civil engineering specifications, compressing development timelines.
- TOPCon migration:Tunnel oxide passivated contact cell architecture achieves mass-production efficiencies exceeding 24%, displacing legacy PERC lines across Chinese manufacturing bases.
Market Restraints
- Silver price volatility:Precious metal input costs constitute 15-20% of cell metallization expenses, exposing margins to commodity exchange fluctuations.
- Polysilicon supply concentration:Xinjiang-based ingot production dominates upstream feedstock, creating geographic single-point vulnerability for non-Chinese module assemblers.
- BIS certification friction:India's Bureau of Indian Standards mandates local testing laboratory validation for imported equipment, extending equipment qualification timelines.
Strategic Opportunities
- Vietnam utility-scale pipeline:Grid interconnection upgrades and feed-in tariff mechanisms support 10+ GW of project development across central highlands provinces.
- Floating solar deployment:Reservoir-mounted photovoltaic systems exploit water surface cooling effects in Thailand and Indonesia, mitigating land acquisition constraints.
- Copper-interconnect convergence:Electroplated copper busbar technology paired with shingled cell interconnection enables 30-micron finger widths, slashing silver consumption.
Industry Challenges
- Cell metallization skill scarcity:Screen printing and electroplating process engineering talent pools concentrate in legacy semiconductor hubs, constraining fab expansion in emerging manufacturing locations.
- Module recycling infrastructure gaps:End-of-life crystalline silicon recovery capabilities remain underdeveloped across the region, exposing developers to extended producer responsibility liabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Solar Photovoltaic (PV) Market |
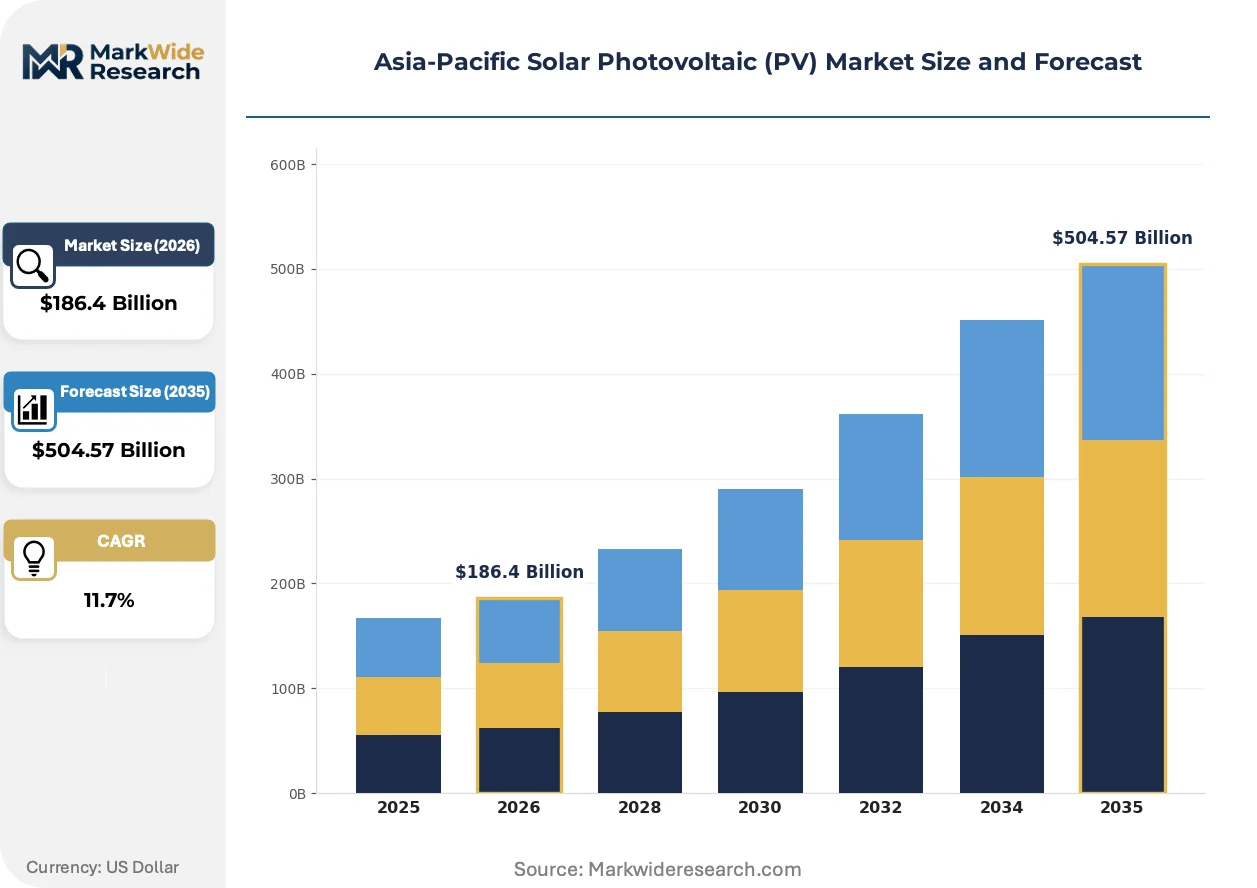
| Market Size in 2026 | $186.4 Billion |
| Market Size in 2035 | $504.57 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Installation Type: Ground-Mounted, Rooftop, Building-Integrated, Off-Grid End User: Residential, Commercial, Industrial, Utility Technology: Standard PV, Concentrated PV, Hybrid Systems, Others |
| Companies Covered | LONGi Green Energy Technology Co., Ltd., Adani Green Energy Ltd, JA Solar Holdings Co, First Solar Inc., Canadian Solar Inc., Trina Solar Ltd, Hanwha Q CELLS Co. Ltd, Astronergy Co., Ltd., JinkoSolar Holdings Co. Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Solar Photovoltaic (PV) Market Strategic Shifts
Bifacial module architecture and heterojunction cell chemistry are converging to reset performance benchmarks, while auction-based procurement mechanisms compress developer return assumptions across Asia-Pacific markets.
Copper-interconnect metallization is rewriting cell fabrication economics. Electroplated copper busbars replace screen-printed silver fingers, cutting precious metal content by 80-90%. Chinese cell manufacturers are retrofitting PERC lines for copper plating at scale. This technology is compressing the cost gap between premium n-type and legacy p-type architectures, accelerating TOPCon adoption timelines.
Japan's METI feed-in tariff transition to auction-based procurement is forcing capital efficiency discipline. Developers must sharpen project finance assumptions as guaranteed price mechanisms phase out. Utility-scale pipeline concentration in Hokkaido and Kyushu regions is accelerating as grid interconnection availability constrains site selection.
Corporate power purchase agreements are displacing traditional utility offtake structures. Data center operators and semiconductor fabs in Singapore and Taiwan are contracting directly with project developers for 15-25 year renewable energy supply. This procurement model shift is visible most acutely in Taiwan's science park clusters, where TSMC and Foxconn affiliates anchor gigawatt-scale demand aggregation.
Asia-Pacific Solar Photovoltaic (PV) Market Segmentation
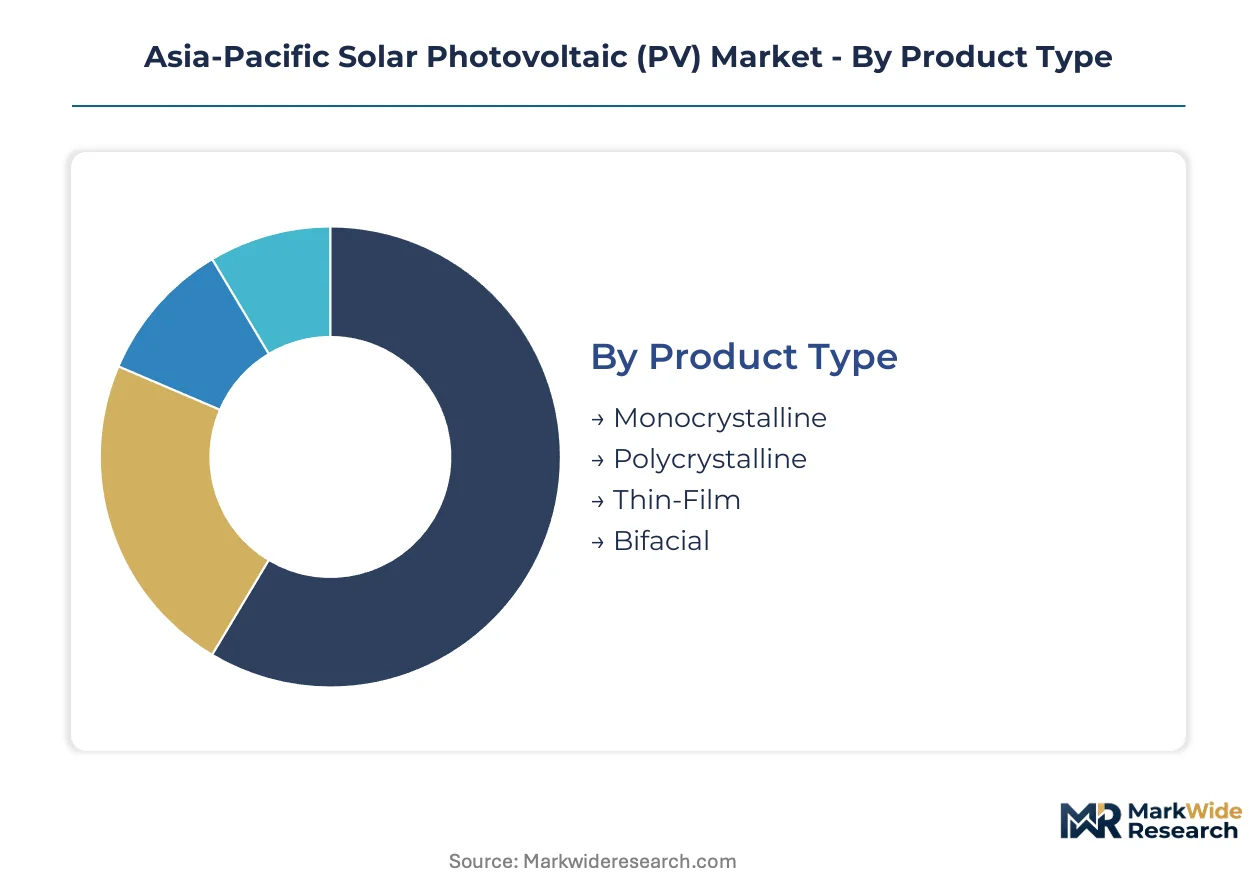
Segmentation in Asia-Pacific solar PV reveals how technology choices and deployment contexts shape procurement economics. Product type and installation configuration determine capital intensity, while end-user category governs financing structures and regulatory exposure.
Product Type:
Integration depth varies sharply: monocrystalline and bifacial modules serve standalone utility arrays, while thin-film retains embedded-system niches where weight or thermal constraints dominate.
- Monocrystalline:Single-crystal silicon ingots yield cell efficiencies exceeding 22% in mass production. Demand concentrates in Chinese manufacturing bases serving Indian and Vietnamese utility-scale procurement, driven by module-level power density requirements in land-constrained sites.
- Bifacial:Dual-sided glass-glass construction captures reflected irradiance from ground surfaces, widening yield premiums in high-albedo desert and snow-prone regions. Deployment accelerates across central highlands provinces in Vietnam and Rajasthan in India where ground conditions maximize rear-side gain.
- Polycrystalline:Multi-crystal silicon cells trade efficiency for lower capital equipment requirements in ingot production.
- Thin-Film:Cadmium-telluride and CIGS chemistries retain relevance in building-integrated applications and high-temperature coefficient environments.
Volume placements concentrate in monocrystalline; the faster expansion belongs to bifacial.
Installation Type:
Cost tier stratification separates standardized civil engineering from customized structural integration.
- Ground-Mounted:Utility-scale arrays with standardized pile driving and tracker systems dominate procurement volumes across Southeast Asian power utility tenders. Deployment timelines compress as Chinese EPC contractors replicate engineering packages across multiple gigawatt-scale sites.
- Rooftop:Distributed commercial and residential systems face structural load constraints in dense Asian megacities. Margin pools shift toward ground-mounted alternatives as grid interconnection availability constrains viable rooftop economics in megacity cores.
- Building-Integrated:Façade and canopy systems substitute conventional construction materials with photovoltaic surfaces.
- Off-Grid:Standalone systems serve archipelagic territories and remote mainland settlements beyond distribution network reach.
Ground-mounted installations absorb the majority of capital deployment; rooftop faces margin compression from interconnection bottlenecks.
End User:
Customer type governs contract duration, creditworthiness, and exposure to subsidy phase-out schedules.
- Utility:State-owned power companies and independent power producers tender multi-gigawatt procurement with 25-year power purchase agreements. India's NTPC and Vietnam's EVN anchor regional demand aggregation through competitive auction mechanisms.
- Industrial:Semiconductor fabs and data center operators in Taiwan and Singapore contract directly for renewable energy supply. Corporate power purchase agreements displace traditional utility offtake with 15-25 year tenors.
- Commercial:Office and retail installations face roof structural limitations in dense urban cores.
- Residential:Distributed generation systems compete with subsidized retail electricity tariffs in markets with incomplete net metering frameworks.
Utility offtake retains volume dominance; industrial direct procurement is climbing the fastest.
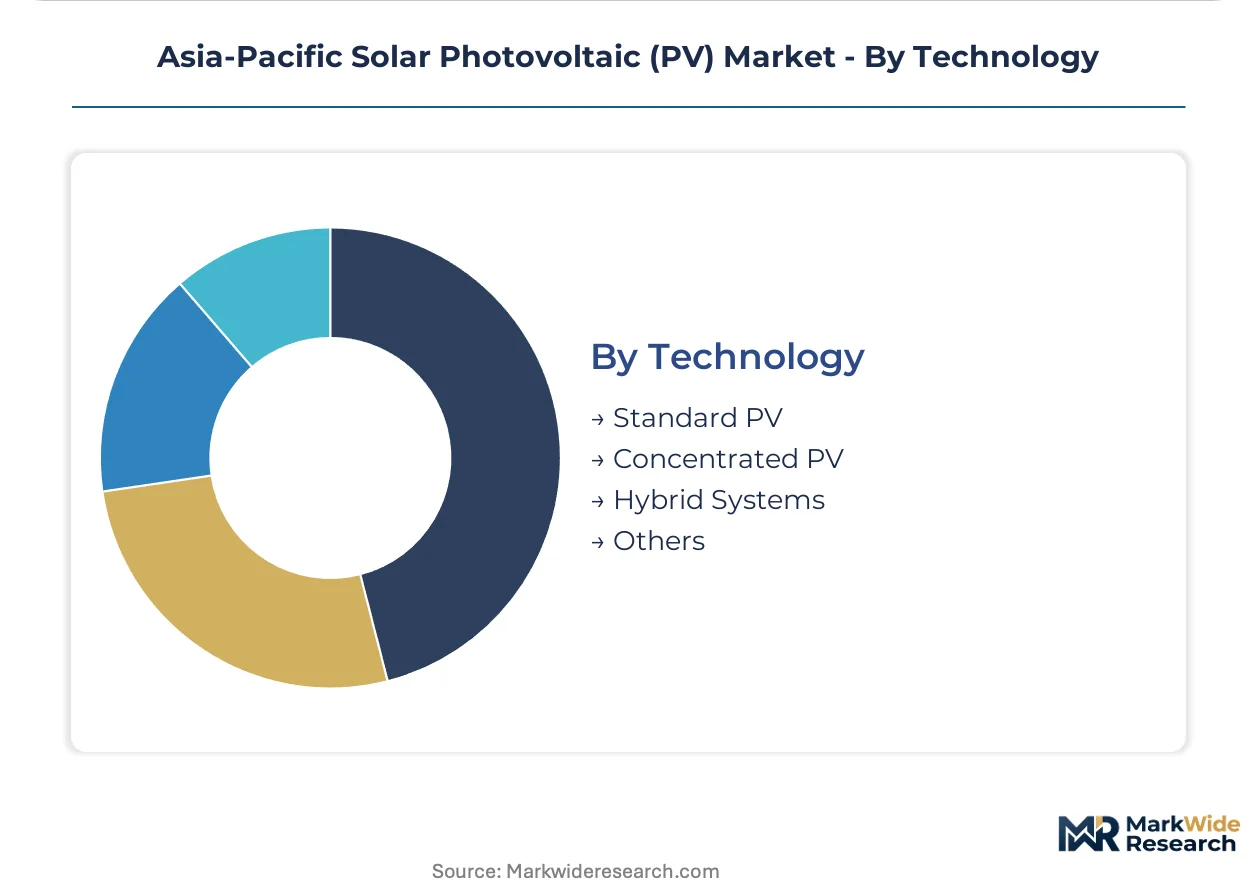
Technology:
Maturity curves separate proven architectures from emerging system configurations.
- Standard PV:Crystalline silicon modules with string or central inverter configurations constitute the installed base. Manufacturing scale in Chinese ingot-to-module facilities compresses unit economics across India and Southeast Asian project pipelines.
- Hybrid Systems:Photovoltaic generation paired with battery storage addresses grid stability constraints in high-renewable penetration markets. Procurement accelerates in South Korea and Japan as feed-in tariff transitions force merchant revenue exposure management.
- Concentrated PV:Lens-based optical concentration on multi-junction cells serves niche high-DNI desert applications.
- Others:Emerging architectures including perovskite tandems and organic photovoltaics remain pre-commercial.
Standard PV captures current deployment volumes; hybrid systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India, China, and Vietnam concentrate Asia-Pacific solar PV procurement volumes, with each market shaped by distinct policy mechanisms and manufacturing capabilities. Utility-scale auctions dominate capital deployment across the region, while distributed generation faces interconnection constraints in dense urban cores.
China
MIIT-enforced GB standards for module efficiency and fire safety compress manufacturing compliance costs for domestic producers. Xinjiang-based polysilicon ingot production dominates upstream feedstock supply, creating geographic concentration for non-Chinese module assemblers. Yangtze River Delta manufacturing clusters anchor integrated ingot-to-module capacity expansion.
India
NTPC and state power utilities tender multi-gigawatt procurement through competitive auction mechanisms with 25-year power purchase agreements. The PLI scheme redirects supply chain investments toward captive polysilicon and wafering capacity, reducing import dependency. Rajasthan's high-albedo desert conditions maximize bifacial module yield premiums in utility-scale arrays.
Vietnam
EVN-anchored feed-in tariff mechanisms support 10+ GW of project development across central highlands provinces with favorable irradiance profiles. Grid interconnection upgrades enable utility-scale pipeline acceleration beyond historical rooftop dominance. Ground-mounted installations with standardized civil engineering specifications compress development timelines.
Japan
METI's feed-in tariff transition to auction-based procurement forces developers to sharpen capital efficiency assumptions as guaranteed price mechanisms phase out. Utility-scale pipeline concentration accelerates in Hokkaido and Kyushu regions where grid interconnection availability constrains site selection. Corporate power purchase agreements displace traditional utility offtake for semiconductor fabs and data center operators.
Australia
The Clean Energy Council maintains an approved product register that filters market access for inverter and panel suppliers through certification requirements. Distributed commercial and residential rooftop installations face structural load constraints in dense metropolitan cores. Merchant revenue exposure management drives hybrid photovoltaic-battery system procurement as grid stability constraints intensify.
Asia-Pacific Solar Photovoltaic (PV) Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated producers commanding premium positioning in utility-scale procurement while pure-play developers compete on project finance execution. The vendor base concentrates around three strategic archetypes: integrated ingot-to-module manufacturers with captive polysilicon supply, pure-play project developers with backward integration into manufacturing, and technology specialists migrating cell architectures from PERC to TOPCon. Dominant competitive moves include capacity expansion in Southeast Asian manufacturing bases and strategic partnerships securing long-term polysilicon offtake.
Within the integrated manufacturing tier, LONGi Green Energy Technology Co., Ltd. and JA Solar Holdings Co exemplify Chinese producers with ingot-to-module capabilities compressing unit economics. Adani Green Energy Ltd anchors Indian project development with upstream manufacturing integration. These three companies represent distinct strategic positioning: Chinese scale-driven manufacturing, Indian domestic supply chain capture, and integrated developer-manufacturer hybrid models competing for utility-scale procurement volumes.
| Leading Market Players |
|---|
| LONGi Green Energy Technology Co., Ltd. |
| Adani Green Energy Ltd |
| JA Solar Holdings Co |
| First Solar Inc. |
| Canadian Solar Inc. |
| Trina Solar Ltd |
| Hanwha Q CELLS Co. Ltd |
| Astronergy Co., Ltd. |
| JinkoSolar Holdings Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
China's dual carbon goals function as the gating mechanism for both qualified supply and premium-tier pricing access, with GB standards enforcement compressing manufacturing compliance costs for domestic producers while elevating entry barriers for non-compliant imports. Module efficiency certifications and fire safety ratings separate premium-tier suppliers from economy alternatives, with BIS certification in India and CEC approval in Australia extending qualification timelines and concentrating margin pools among pre-approved vendors.
Pricing Analysis
The volume-versus-margin split bifurcates sharply between commodity crystalline silicon modules and premium n-type architectures, with project-based long-term offtake contracts dominating utility-scale procurement while spot-market transactions serve distributed commercial segments. Price differentiation rests on cell efficiency tier and certification level, with GB-standard compliance and BIS laboratory validation commanding 15-20% premiums over uncertified alternatives. Cost compression in legacy p-type lines is intensifying because copper-interconnect retooling slashes silver consumption, eroding incumbent metallization margins. Utility buyers exhibit lowest price sensitivity due to 25-year PPA tenors, while residential rooftop installers face acute margin pressure from incomplete net metering frameworks.
Supply Chain Analysis
Direct-to-EPC channels handle hyperscale utility demand across Southeast Asian tenders, with Chinese contractors replicating standardized engineering packages across gigawatt-scale sites. Geographic supply concentrates in China, Vietnam, and India, with Xinjiang-based polysilicon ingot production anchoring upstream feedstock. Raw material dependencies center on metallurgical-grade silicon, silver paste, and copper busbar substrates. Single-source vulnerability in Xinjiang ingot supply creates geographic concentration risk for non-Chinese module assemblers. Distribution runs through integrated ingot-to-module manufacturers with captive polysilicon supply, compressing unit economics for pure-play project developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story, with India's PLI scheme and BIS certification requirements creating a barrier-to-entry moat for domestic manufacturers with captive testing laboratory relationships.
For Market Incumbents: Deepen backward integration into polysilicon and wafering capacity to defend margin pools against copper-interconnect technology disruption from Chinese cell manufacturers. Secure long-term silver and copper offtake agreements to hedge commodity price volatility, while accelerating PERC-to-TOPCon line retrofits to maintain efficiency premiums. Priority capacity addition targets Vietnam and India to capture utility-scale procurement acceleration. For New Entrants and Emerging Players: Floating solar deployment technology offers the most penetrable wedge, with reservoir-mounted systems exploiting water surface cooling effects in Thailand and Indonesia where land acquisition constraints block ground-mounted alternatives. Target Vietnam's central highlands provinces for 10+ GW pipeline access through EVN feed-in tariff mechanisms. Go-to-market angle emphasizes hybrid photovoltaic-battery system integration for grid stability in high-renewable penetration markets. For Investors and Strategic Acquirers: Copper-interconnect metallization adoption at scale is the leading indicator that premium n-type cell economics have compressed sufficiently to displace legacy p-type architectures across the analysis window. Acquisition target archetype: integrated ingot-to-module manufacturers with GB-standard compliance and Southeast Asian manufacturing footprint. Monitor Japan's METI auction-based procurement transition for capital efficiency discipline signals among developers.| Strategic Initiative | Industry Significance |
|---|---|
| Copper-Interconnect Retrofit | Electroplated copper busbars cut silver consumption by 80-90%, rewriting cell fabrication economics. |
| PLI Scheme Capacity Capture | Domestic polysilicon and wafering investment reduces import dependency for Indian project developers. |
| Floating Solar Deployment | Reservoir-mounted systems mitigate land acquisition constraints in Thailand and Indonesia archipelagos. |
| Corporate PPA Aggregation | TSMC and Foxconn affiliates in Taiwan's science parks anchor gigawatt-scale direct procurement demand. |
| Hybrid System Integration | Photovoltaic-battery pairing addresses grid stability constraints in South Korea and Japan tariff transitions. |
Study Parameters
IEA renewable energy databases, EIA international energy statistics, and customs/trade data from India DGFT and China customs authorities formed the secondary backbone, supplemented by SEC filings from listed module manufacturers and project development registries across Southeast Asian power utilities. Primary interviews with utility planning officers at India's NTPC and Vietnam's EVN, EPC contractors in Chinese Yangtze River Delta clusters, and IPP project developers in Rajasthan and Hokkaido validated demand assumptions. Bottom-up capacity installation tracking and top-down policy incentive modeling were triangulated to cross-verify volume estimates.
Historical trendline analysis of module price trajectories and capacity deployment patterns informed the projection framework across the analysis window. Segmentation dimensions modeled include product type (monocrystalline, bifacial, thin-film), installation configuration (ground-mounted, rooftop, floating), end-user category (utility, industrial, commercial), and technology architecture (standard PV, hybrid systems). CAGRs were derived from fitted growth curves incorporating policy phase-out schedules and manufacturing cost reduction trajectories. Industry-specific forecast inputs include silver price volatility assumptions and polysilicon supply concentration metrics.
Several conditions sit outside the modeled scope, including perovskite tandem commercialization timelines and extended producer responsibility enforcement for module recycling. Forecasts reflect documented assumptions regarding subsidy continuity and grid interconnection upgrade schedules. Practitioners should monitor Japan's METI auction clearing prices and India's BIS certification queue lengths for early signals of competitive intensity shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Rooftop Solar Panels Market
Solar Power Systems
Solar Thermal Power Market
Solar Power Systems
Solar Polysilicon Ingot Wafer Cell Module Market
Solar Power Systems
Chile Solar Energy Market
Solar Power Systems
Solar Interconnect Ribbon Market
Solar Power Systems
Australia Solar Power Market
Solar Power Systems
Ecuador Solar Energy Market
Solar Power Systems
Solar Power Bank Market
Solar Power Systems
High Concentration Photovoltaics Market
Solar Power Systems
Bifacial Solar Market
Solar Power Systems
Utility Solar PV EPC Market
Solar Power Systems
Floating Solar System Market
Solar Power Systems
PERC Solar Panels Market
Solar Power Systems
Solar Power Manager Market
Solar Power Systems
France Solar Energy Market
Solar Power Systems
Solar Module Racking Market