
 Grid-Connected Solar Microinverter Market | 2026-2036
Grid-Connected Solar Microinverter Market Size, Share, and Industry Trends Forecast 2026-2036
Grid-Connected Solar Microinverter Market Insights
Software-defined monitoring and energy management subscriptions is rebalancing how microinverter vendors monetize hardware deployments. Enphase Energy leverages its IQ8 platform ecosystem to capture recurring revenue beyond unit sales. SolarEdge Technologies anchors its competitive stance through power optimizer-to-inverter integration that sustains installation efficiency. SMA Solar Technology competes in utility-scale adjacencies while navigating residential microinverter specialization.
A grid-connected solar microinverter converts direct current from individual photovoltaic modules into alternating current synchronized with utility grid frequency, typically operating at 95-97% peak efficiency with maximum power point tracking performed at the module level rather than string level. The device enables granular system monitoring, rapid shutdown compliance, and enhanced energy harvest in partially shaded conditions. Single-phase microinverters dominate residential deployment volumes where rooftop-mounted installation represents the primary delivery mode. Three-phase variants occupy commercial and small industrial segments where higher capacity per unit reduces balance-of-system costs. Hybrid microinverters are gaining structural importance as storage attachment rates climb and installers seek consolidated power electronics.
FERC Order 2222 in the United States enables distributed energy resource aggregation, creating grid services revenue pathways for microinverter-equipped fleets. California's Title 24 building standards and the EU Green Deal's rooftop solar mandates in Germany and the Netherlands shape product certification requirements and interconnection protocols. IEEE 1547 and UL 1741-SA standards dictate grid support functionality including voltage and frequency ride-through capabilities. Stakeholders must evaluate which regulatory jurisdictions will mandate module-level electronics versus string alternatives, as this determination locks in addressable market boundaries for product portfolios.
Market Dynamics
California's NEM 3.0 net metering reforms are forcing residential installers toward storage-coupled microinverter architectures, compressing simple solar-only deployment economics while expanding hybrid system attach rates.
Growth Catalysts
- Module-level rapid shutdown mandates:UL 1741-SA and NEC Article 690.12 requirements in the United States are codifying microinverter adoption for rooftop fire safety compliance.
- Grid services aggregation frameworks:FERC Order 2222 enables distributed energy resource monetization, creating recurring revenue pathways for microinverter fleet operators.
- Shade-tolerant performance architecture:Module-level maximum power point tracking delivers measurable energy harvest gains in partially shaded residential installations.
Market Restraints
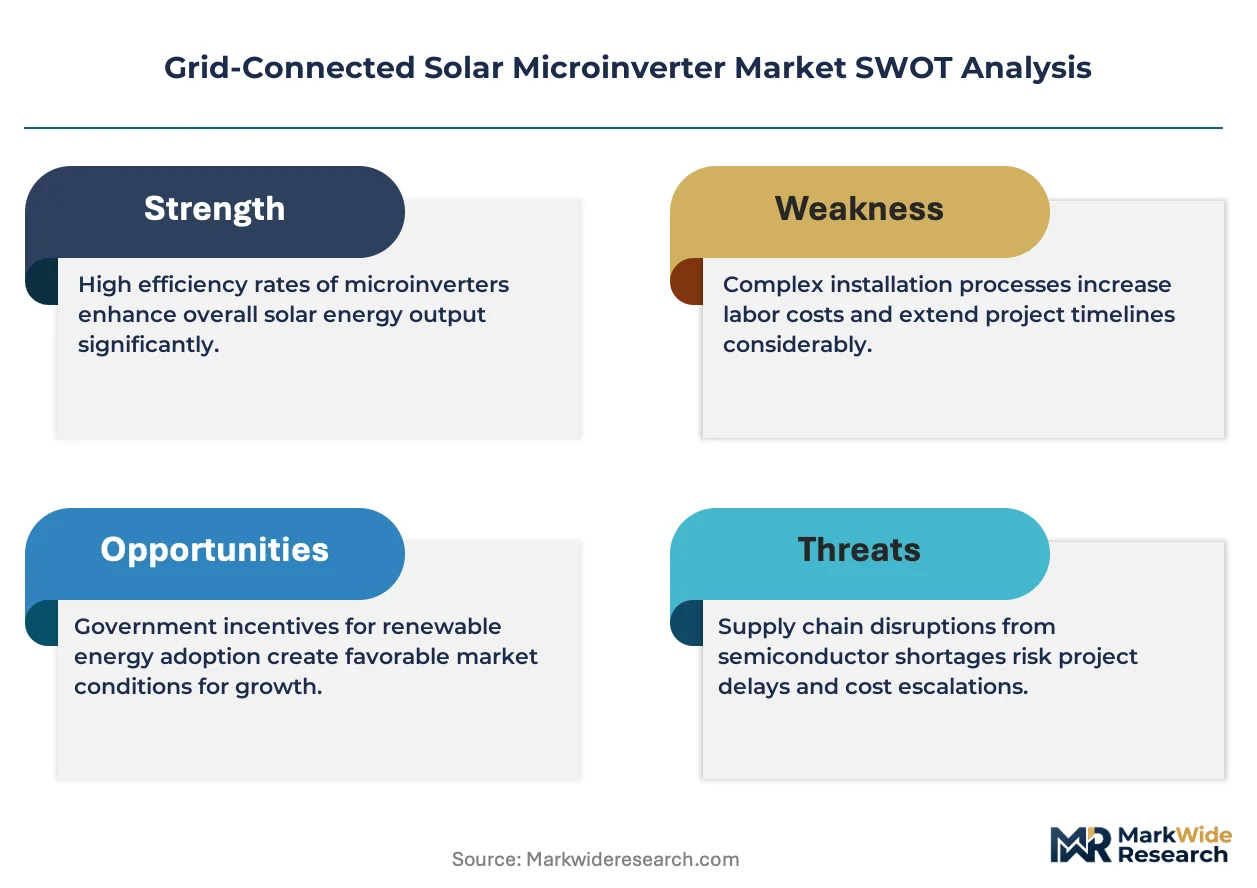
- Power semiconductor supply concentration:Silicon carbide MOSFET and IGBT sourcing depends on concentrated Asian foundry capacity, exposing lead time volatility.
- Balance-of-system cost burden:Per-watt installed cost premiums versus string inverter alternatives persist despite hardware efficiency gains.
- String inverter hybrid substitution:Transformerless string inverters with DC optimizers capture cost-sensitive segments in unshaded commercial rooftops.
Strategic Opportunities
- EU Green Deal rooftop mandates:Germany and Netherlands building codes are accelerating residential solar deployment with module-level electronics requirements.
- Virtual power plant aggregation:Software-defined fleet orchestration creates recurring SaaS revenue beyond hardware unit sales.
- Battery storage convergence:Hybrid microinverters consolidating solar and storage power electronics reduce installation labor and component count.
Industry Challenges
- UL 1741-SA certification timelines:Grid support functionality testing for voltage and frequency ride-through extends product launch cycles.
- Legacy string system retrofit complexity:DC bus voltage mismatches complicate microinverter upgrades on existing solar installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grid-Connected Solar Microinverter Market |
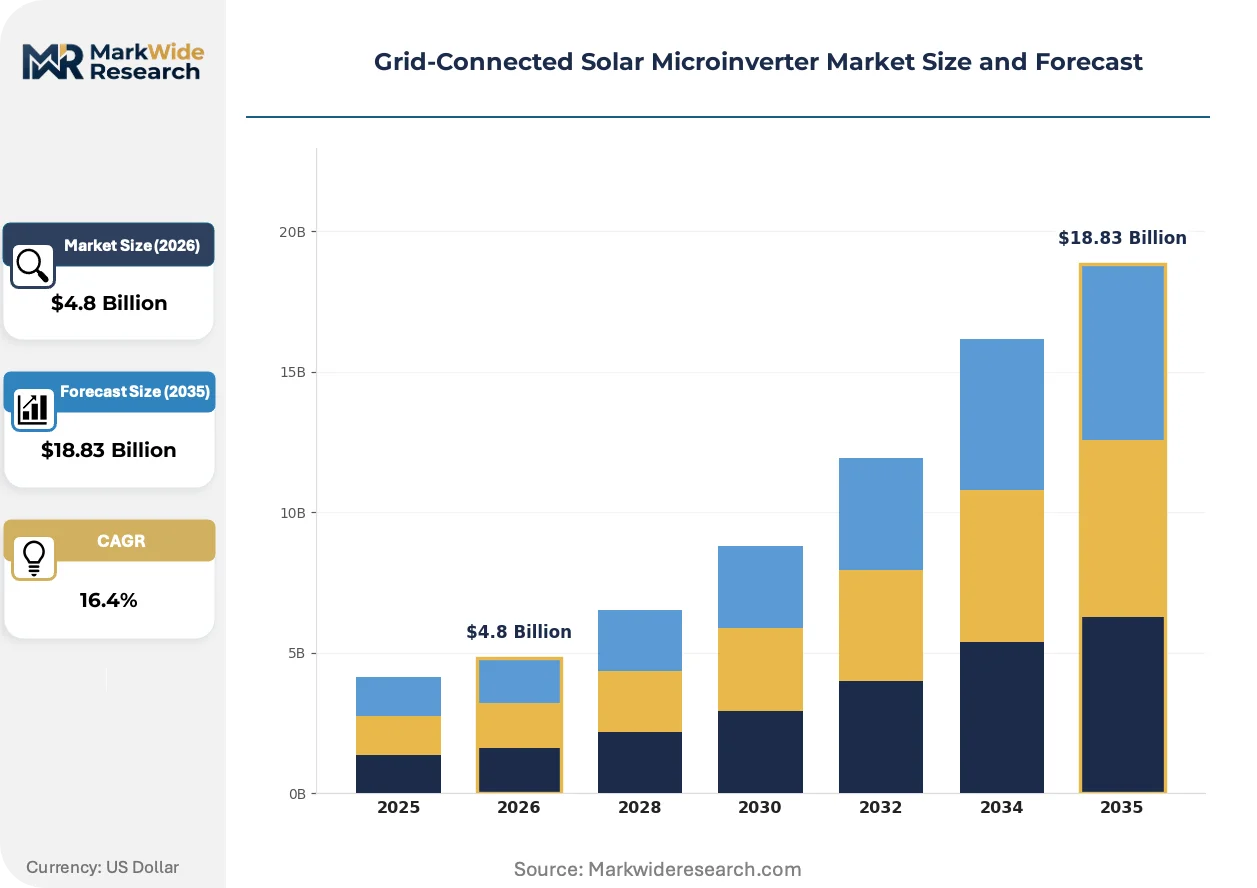
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $18.83 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase Microinverters, Three-Phase Microinverters, Hybrid Microinverters, Smart Microinverters End User: Residential, Commercial, Industrial, Utilities Technology: String Inverters, Central Inverters, Optimized Inverters, Microgrid Solutions Installation: Roof-Mounted, Ground-Mounted, Wall-Mounted, Integrated Systems |
| Companies Covered | Enphase Energy, SolarEdge Technologies, SMA Solar Technology, APsystems, Hoymiles Power Electronics, Sungrow, Altenergy Power System, Chilicon Power, Complete Solaria, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grid-Connected Solar Microinverter Market Trends and Innovations
Software-defined energy management and semiconductor material transitions are compressing hardware differentiation cycles while expanding service revenue capture in residential solar deployments.
Silicon carbide power semiconductors are replacing silicon IGBTs in microinverter DC-AC conversion stages, enabling higher switching frequencies and reduced magnetic component mass. Residential installers in California and Australia are specifying SiC-based units for heat dissipation advantages in attic mounting locations. The technology is integrating thermal management with power density gains that shrink enclosure volumes.
The EU Green Deal's rooftop solar mandates in Germany and the Netherlands are embedding module-level electronics requirements into national building codes. These regulations compress string inverter eligibility in new residential construction. Single-phase microinverter suppliers are prioritizing CE marking and F-Gas Regulation compliance for European market entry.
Homeowners are unbundling monitoring subscriptions from hardware procurement, treating energy visibility as a standalone service purchase. Installer channels are responding with financing structures that separate equipment from software fees. This pattern concentrates in the United States where NEM 3.0 export compensation reductions elevate consumption optimization value.
Grid-Connected Solar Microinverter Market Segmentation
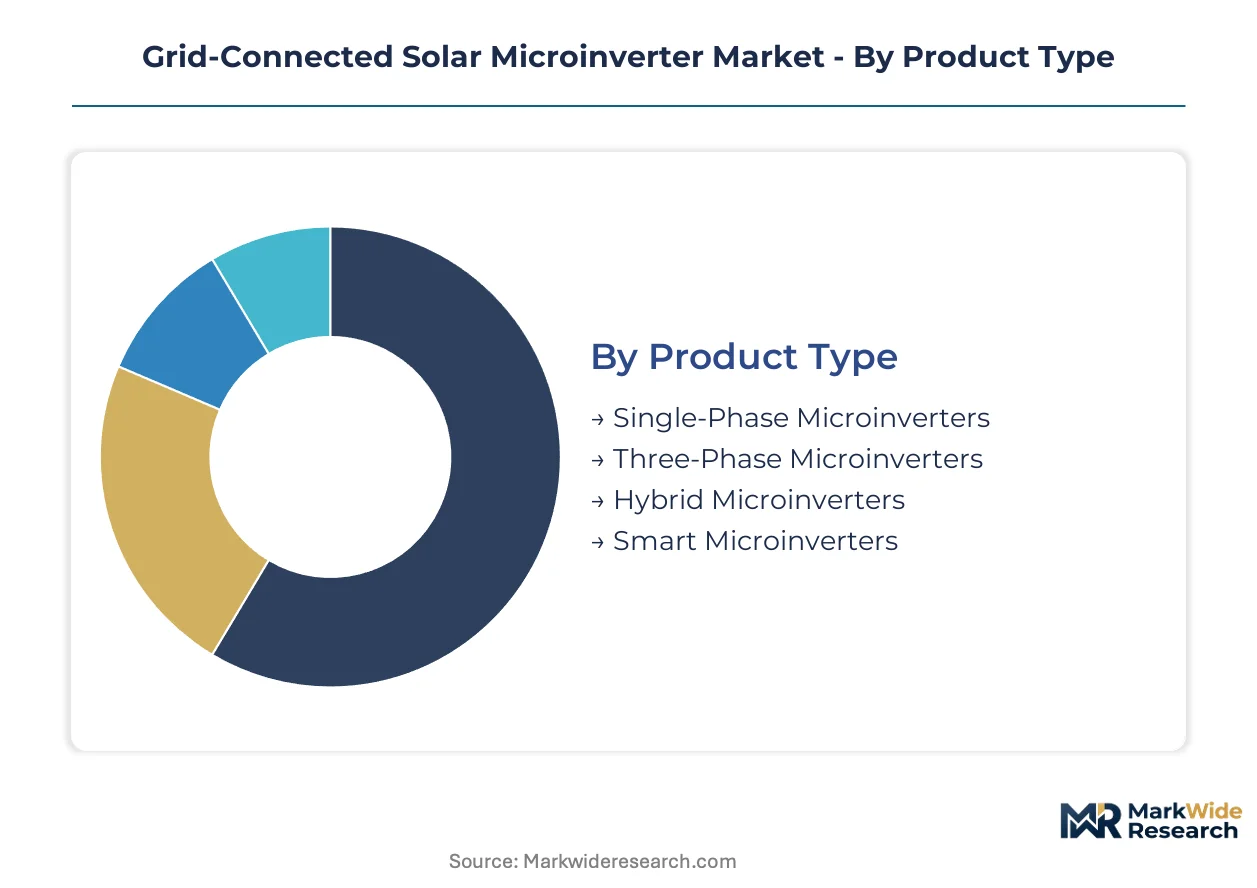
Product architecture choices in grid-connected solar microinverters determine certification pathways, installation labor requirements, and revenue capture models. Segment boundaries align with power capacity thresholds, phase configuration, and storage integration capabilities that reshape stakeholder economics across deployment contexts.
Product Type:
UL 1741-SA grid support certification applies universally across this category, though silicon carbide semiconductor integration and rapid shutdown compliance testing create divergent validation timelines per segment.
- Single-Phase Microinverters:These units handle 240V AC output for residential split-phase distribution systems, typically rated between 250-500 watts per module. California rooftop installers specify single-phase units for NEC Article 690.12 rapid shutdown compliance in attic mounting configurations where thermal management challenges concentrate.
- Three-Phase Microinverters:Designed for 208V or 480V commercial distribution, these higher-capacity units reduce balance-of-system component count through consolidated AC bus architecture. German commercial installers deploy three-phase variants under EU Green Deal rooftop mandates where F-Gas Regulation compliance shapes refrigerant-based cooling exclusions.
- Hybrid Microinverters:Consolidated solar-plus-storage power electronics with DC-coupled battery integration. Demand climbs in Australia where NEM export limitations elevate self-consumption optimization value.
- Smart Microinverters:Software-defined units with embedded grid services functionality for virtual power plant aggregation. IEEE 1547-2018 compliance enables frequency response revenue streams in FERC Order 2222 jurisdictions.
Leading the category by volume: Single-Phase Microinverters. Expanding most quickly: Hybrid Microinverters.
End User:
Customer procurement patterns stratify across financing structures, with power purchase agreements dominating utility-scale procurement and cash or loan products characterizing residential acquisition.
- Residential:Homeowner-driven deployments where module-level monitoring and shade tolerance justify per-watt premiums. California NEM 3.0 export compensation reductions compress simple solar economics while elevating storage-coupled system attach rates.
- Commercial:Small business and multi-tenant facilities with 10-100 kW capacity requirements. Netherlands building codes mandate module-level electronics in new commercial construction under EU Green Deal implementation.
- Industrial:Manufacturing facilities and warehouses with 100-500 kW distributed generation footprints. Three-phase microinverter configurations reduce installation labor through higher capacity per unit.
- Utilities:Distributed solar portfolios aggregated for grid services revenue under FERC Order 2222 frameworks. Virtual power plant software stacks monetize fleet flexibility.
Residential commands absolute deployment volume. Utilities demonstrate the steepest expansion trajectory as aggregation frameworks mature.
Technology:
Technology selection determines maximum power point tracking granularity, fault current contribution, and interoperability with downstream energy management platforms.
- String Inverters:Centralized DC-AC conversion with string-level monitoring. Cost-sensitive commercial segments in unshaded conditions favor this architecture despite reduced granularity.
- Central Inverters:Utility-scale conversion equipment handling 500 kW to multi-megawatt capacity blocks. These units fall outside microinverter taxonomy but compete for utility procurement budgets.
- Optimized Inverters:String inverters paired with DC power optimizers delivering module-level monitoring without full microinverter conversion. SolarEdge Technologies anchors this hybrid architecture in residential and commercial deployment.
- Microgrid Solutions:Island-capable systems with intentional grid-forming functionality for resilience applications. IEEE 1547-2018 grid support requirements govern interconnection standards.
Optimized Inverters hold the largest installed base. Microgrid Solutions gain share fastest as resilience premiums justify hardware cost premiums.
Installation:
Mounting configuration determines thermal management design, wiring complexity, and structural load calculations that cascade into permitting timelines.
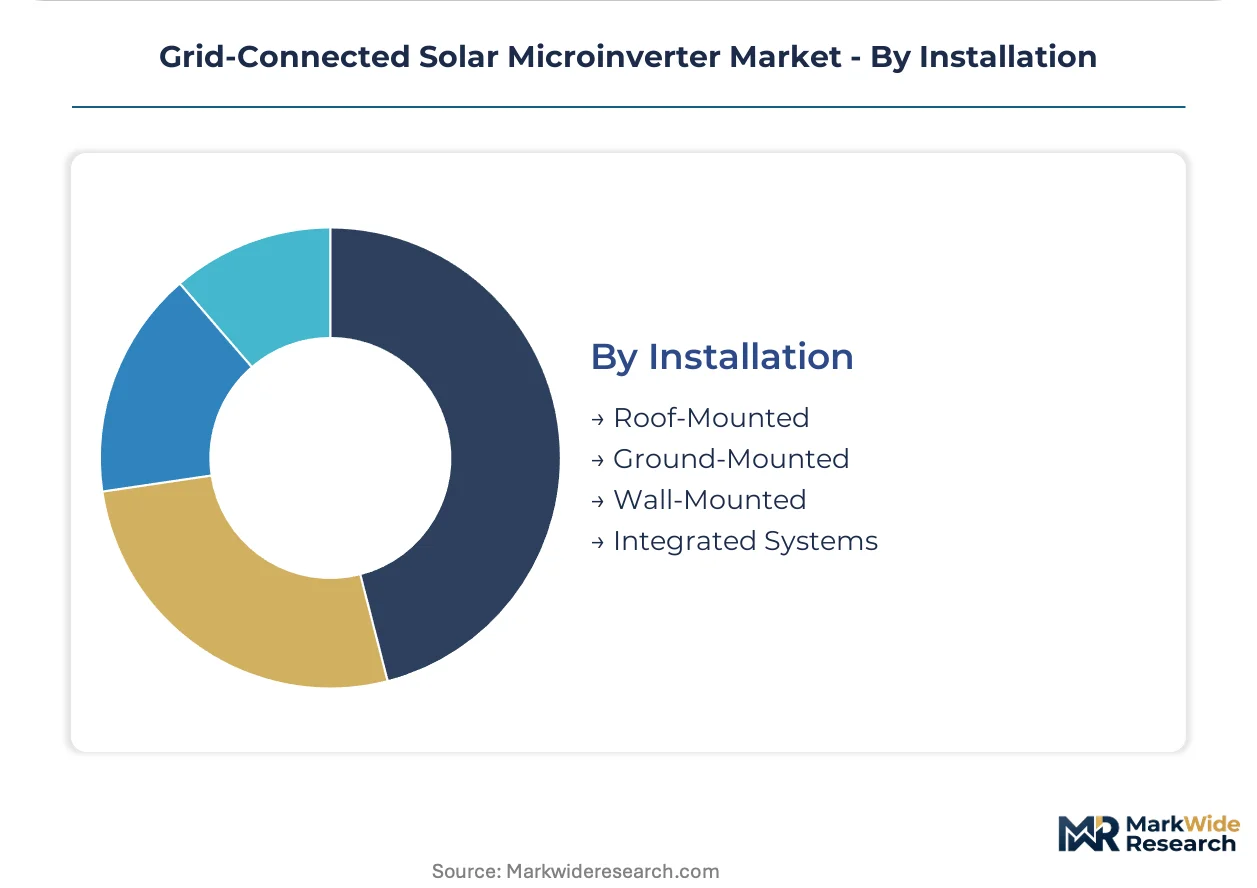
- Roof-Mounted:Behind-module or racking-integrated installation on pitched or flat residential and commercial structures. California Title 24 building standards mandate rapid shutdown capability that microinverters satisfy natively.
- Ground-Mounted:Elevated rack systems for utility-scale and large commercial arrays. Lower ambient temperatures improve conversion efficiency versus rooftop thermal conditions.
- Wall-Mounted:Vertical installation on building facades for aesthetic or structural constraints. German building codes under EU Green Deal implementation increasingly permit facade-integrated photovoltaics.
- Integrated Systems:Factory-assembled solar-plus-storage units with pre-wired microinverters reducing field labor. Australian installers specify integrated systems to accelerate deployment under streamlined permitting pathways.
Roof-Mounted dominates deployment volume. Integrated Systems climb fastest as labor cost inflation elevates prefabrication value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Microinverter production concentrates in Asian manufacturing clusters while consumption tilts toward policy-driven residential markets in North America, Europe, and Australia. This geographic asymmetry shapes trade flows and certification requirements across jurisdictions.
United States
California rooftop installers drive residential deployment volumes under NEM 3.0 export compensation reforms that elevate storage-coupled system economics. FERC Order 2222 enables distributed energy resource aggregation for grid services revenue. The Los Angeles-San Diego corridor anchors installer network density and supply chain distribution.
Germany
EU Green Deal rooftop mandates accelerate new residential construction specifications for module-level electronics. The F-Gas Regulation shapes thermal management design exclusions for refrigerant-based cooling. Bavaria and North Rhine-Westphalia concentrate installer capacity and distribution logistics for Central European markets.
Australia
Network export limitations in Queensland and Victoria elevate self-consumption optimization value for residential battery attachment. The Clean Energy Council accredits products for national deployment eligibility. Sydney and Melbourne metropolitan areas concentrate installer certification and consumer finance channel density.
Netherlands
Building code mandates under EU Green Deal implementation require module-level electronics in new commercial and residential construction. CE marking and interconnection standards harmonize with German certification pathways. The Randstad urban corridor anchors distribution infrastructure for Benelux deployment.
China
Domestic distributed generation policy frameworks support rooftop solar deployment in industrial and commercial segments. GB standards govern grid interconnection and safety certification for local product qualification. The Yangtze River Delta manufacturing cluster supplies power semiconductor components and finished microinverter hardware for export markets.
Grid-Connected Solar Microinverter Market Competitive Landscape
Top-tier vendors anchor the premium residential segment, while mid-tier specialists compete on cost-sensitive commercial deployments. The market structure consolidates around vertically integrated hardware-software platforms and component suppliers with foundry partnerships. Three archetypes dominate: ecosystem orchestrators with recurring revenue capture, power electronics specialists with semiconductor integration, and Asian manufacturers with scale-driven cost positions. Competitive moves concentrate on hybrid storage convergence and virtual power plant software licensing.
Within the ecosystem orchestrator tier, Enphase Energy and SolarEdge Technologies occupy positions defined by software-defined monitoring and energy management integration. SMA Solar Technology represents the European power electronics specialist archetype with utility-scale adjacency exposure. These three companies exemplify divergent strategic postures: one anchored in residential recurring revenue, one in power optimizer-to-inverter integration efficiency, and one in multi-segment portfolio breadth.
| Leading Market Players |
|---|
| Enphase Energy |
| SolarEdge Technologies |
| SMA Solar Technology |
| APsystems |
| Hoymiles Power Electronics |
| Sungrow |
| Altenergy Power System |
| Chilicon Power |
| Complete Solaria |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal rooftop mandates gate qualified supply and premium-tier pricing access by embedding module-level electronics requirements into national building codes across Germany and the Netherlands. UL 1741-SA certification timelines compress supplier eligibility while elevating hardware validation costs that tier pricing by compliance grade.
Pricing Analysis
Margin tightening in economy-tier units reflects silicon carbide MOSFET supply bottlenecks from concentrated Asian foundry capacity. Three-tier pricing structure across premium, standard, and economy levels stratifies by UL 1741-SA grid support certification and semiconductor material grade. Pricing pressure stems from string inverter substitution with DC optimizers in unshaded commercial segments. Residential installers in California demonstrate highest price sensitivity due to NEM 3.0 export compensation compression, while utility-scale aggregators under FERC Order 2222 tolerate premiums for grid services functionality.
Supply Chain Analysis
UL 1741-SA and IEEE 1547-2018 certification requirements gate supplier entry and elongate product launch cycles for new market participants. Silicon carbide wafer production concentrates in China, Japan, and the United States, while power semiconductor packaging and final assembly clusters in Taiwan and South Korea. Raw material dependencies span rare earth magnets for magnetic components, copper busbar for thermal management, and aluminum enclosures for heat dissipation. Single-source vulnerability concentrates in silicon carbide substrate supply from Wolfspeed and Coherent facilities. Distribution runs through installer channel partnerships in California, Bavaria, and New South Wales with direct OEM relationships for utility-scale procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UL 1741-SA certification creates a cost-of-compliance moat that favors incumbent vendors with established testing relationships and elongated product development runway.
For Market Incumbents: Hedge against string inverter hybrid substitution by accelerating silicon carbide integration and backward integration into power semiconductor sourcing. Defensive consolidation should prioritize installer channel control in California and Germany where EU Green Deal mandates compress string eligibility. Capacity addition in Taiwan and South Korea reduces single-source foundry exposure. For New Entrants and Emerging Players: Installer networks in Australia represent the most penetrable channel given NEM export limitations elevating storage-coupled microinverter demand. White-space targets include three-phase commercial variants under Netherlands building code mandates and smart microinverters for FERC Order 2222 aggregation. Go-to-market through virtual power plant software licensing partnerships bypasses hardware margin compression. For Investors and Strategic Acquirers: FERC Order 2222 implementation velocity is the leading indicator that grid services revenue will sustain premium hardware valuations. Long-term viability favors vertically integrated platforms with captive semiconductor supply and recurring SaaS revenue capture. Acquisition target archetype: hybrid microinverter specialists with UL 1741-SA certification and Australian Clean Energy Council accreditation. A model refresh is warranted upon material change in California NEM policy or EU Green Deal enforcement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Integration | Higher switching frequencies reduce magnetic component mass and thermal management costs for attic-mounted residential deployments. |
| Hybrid Storage Convergence | Consolidated solar-plus-storage power electronics reduce installation labor and component count as battery attachment rates climb. |
| Virtual Power Plant Software Licensing | FERC Order 2222 enables recurring SaaS revenue from fleet aggregation beyond transactional hardware unit sales. |
| UL 1741-SA Certification Acceleration | Grid support functionality testing compresses product launch cycles and gates competitor entry in California rooftop markets. |
| Installer Channel Consolidation | Direct relationships with California and German installers secure priority placement under NEM 3.0 and EU Green Deal procurement windows. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this grid-connected solar microinverter analysis. Primary interviews with utility planning officers, EPC contractors, residential installer network heads, and power semiconductor procurement leads at inverter OEMs validated demand assumptions and pricing dynamics. Secondary sources included FERC interconnection filings, EIA distributed generation databases, EU Green Deal implementation documents, and Clean Energy Council product accreditation lists. Bottom-up unit shipment modeling triangulated against top-down addressable market sizing by rooftop installation volume.
Granularity-level modeling disaggregated the analysis window by product type, phase configuration, end-user segment, and regional regulatory framework. Segmentation dimensions captured single-phase versus three-phase deployment, residential versus commercial versus utility procurement, and storage-coupled versus solar-only system architecture. CAGRs derived from regression analysis of historical installation data against policy incentive trajectories and semiconductor cost curves. Industry-specific forecast inputs included NEM 3.0 export compensation schedules and EU Green Deal mandate implementation timelines.
Caveats apply where silicon carbide supply disruptions or California net metering policy reversals could materially shift the outlook. Forecasts reflect assumptions on certification timeline stability and installer channel concentration. A model refresh is warranted upon material change in FERC Order 2222 implementation velocity or EU F-Gas Regulation thermal management exclusions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Asia Pacific Solar Inverter Market
Solar Power Systems
South America Rooftop Solar Market
Solar Power Systems
Solar Mirror Market
Solar Power Systems
Solar PV Module Market
Solar Power Systems
Concentrated Photovoltaic System Market
Solar Power Systems
Solar Panel Lights Market
Solar Power Systems
France Distributed Solar Power Generation Market
Solar Power Systems
Solar Grid-Tied Systems Market
Solar Power Systems
Solar Collector Panels Market
Solar Power Systems
Solar Concentrator Market
Solar Power Systems
Australia Rooftop Solar Market
Solar Power Systems
United States Solar Energy Market
Solar Power Systems
Full-Cell Solar Module Market
Solar Power Systems
US Solar Films Market
Solar Power Systems
Off-Grid Solar Energy Market
Solar Power Systems
Solar Bench Market