
 Brazil Solar Energy Market | 2026-2036
Brazil Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Solar Energy Market Analysis
ABNT NBR IEC 61215 certification is reorganizing the competitive landscape for crystalline silicon module suppliers seeking utility-scale tenders in Brazil. Enel Green Power Brasil leverages its vertically integrated development pipeline to secure grid-connection priority in Northeastern states. Canadian Solar Inc. anchors its position through localized module assembly and aggressive distributed generation channel partnerships.
Brazil solar energy encompasses photovoltaic systems converting sunlight into direct current electricity through semiconductor junctions, typically deployed at 220V alternating current output for grid synchronization. Concentrated solar power remains nascent while photovoltaic technology dominates installed capacity, with bifacial modules capturing margin premiums through elevated energy yield in high-albedo regions like Bahia's arid zones. Utility-scale application leads procurement volumes, though residential rooftop installation is accelerating fastest under ANEEL's simplified net metering thresholds.
ANEEL's distributed generation regulatory framework and ABNT grid-interconnection standards shape equipment qualification timelines and project financing access. Brazil's national development bank BNDES imposes local content requirements that steer module sourcing toward domestic assembly operations. Stakeholders must monitor forthcoming transmission auction schedules and sub-regional irradiance variability to optimize portfolio allocation between Northeastern utility-scale parks and Southeastern distributed assets.
Market Dynamics
Bifacial photovoltaic module technology is compressing developer economics across Brazil's high-albedo regions, forcing recalibration of project IRR models and procurement priorities.
Growth Catalysts
- ANEEL Net Metering Framework:Simplified interconnection thresholds accelerate residential rooftop deployment in Minas Gerais and São Paulo states.
- Agribusiness Cooperatives:Distributed generation uptake among agricultural processors drives module procurement volumes in Southeastern Brazil.
- ABNT NBR IEC 61215 Certification:Standardized crystalline silicon qualification streamlines utility-scale tender participation for domestic assembly operations.
Market Restraints
- Polysilicon Input Volatility:Raw material cost swings compress module margin structures for Brazilian distributors dependent on Asian supply chains.
- Transmission Auction Delays:Grid connection queue uncertainty stalls utility-scale project financial close in Northeastern states.
- Legacy Grid Infrastructure:Distribution network capacity constraints limit distributed generation hosting capacity in rural municipalities.
Strategic Opportunities
- Bahia Arid Zones:Elevated irradiance and land availability position the Northeast for utility-scale bifacial deployment at premium energy yields.
- BNDES Local Content Requirements:Domestic assembly mandates create captive demand for module manufacturing investments in São Paulo industrial corridors.
- Hybrid Solar-Storage Convergence:Co-located battery integration addresses evening peak demand for commercial and industrial off-takers.
Industry Challenges
- Grid-Interconnection Engineering Talent:Scarce specialized labor extends project commissioning timelines for complex bifacial tracking systems.
- ABNT Certification Backlogs:Equipment qualification delays compress developer construction windows ahead of regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Solar Energy Market |
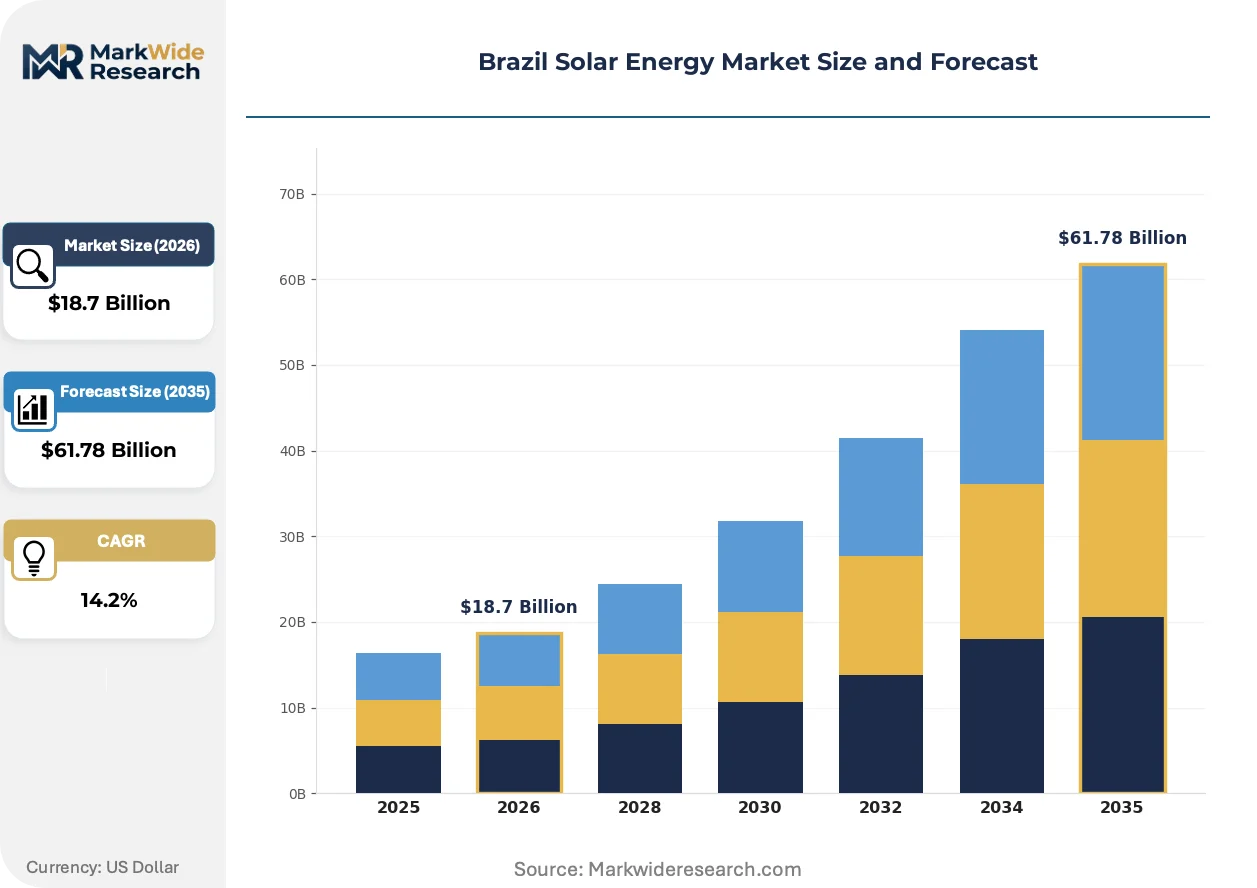
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Photovoltaic, Concentrated Solar Power, Bifacial Modules, Solar Thermal Application: Residential, Commercial, Industrial, Utility-scale End User: Households, Enterprises, Government, Energy Providers Installation Type: On-grid, Off-grid, Rooftop, Ground-mounted |
| Companies Covered | Enel Green Power Brasil, Elera Renováveis, Engie Brasil Energia, EDF Renewables Brasil, JA Solar Holdings Co. Ltd, Canadian Solar Inc., Scatec ASA, Atlas Renewable Energy, JinkoSolar Holding Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Solar Energy Market Emerging Trajectories
Module efficiency gains and regulatory simplification are compressing project development cycles while redrawing competitive boundaries between utility-scale and distributed generation channels.
Passivated emitter and rear contact (PERC) cell architecture is supplanting conventional aluminum back-surface field designs in Brazilian utility tenders. Developers in Ceará and Piauí states prioritize PERC modules for their elevated bifacial compatibility and temperature coefficient advantages. The technology is supplanting older crystalline silicon variants in procurement specifications, compressing margin premiums for legacy suppliers.
ANEEL's distributed generation regulatory framework is restructuring interconnection economics for residential and commercial segments. Simplified net metering thresholds reduce bureaucratic friction for sub-75 kW installations across São Paulo state. The policy shift accelerates channel partnerships between module distributors and electrical contractors in Southeastern metropolitan corridors.
Direct procurement from domestic assembly operations is displacing import-dependent distribution models for large agribusiness cooperatives. Minas Gerais agricultural processors negotiate volume contracts with São Paulo-based module manufacturers to satisfy BNDES local content requirements. This pattern concentrates procurement influence among vertically integrated developers with captive Brazilian production assets.
Brazil Solar Energy Market Segmentation
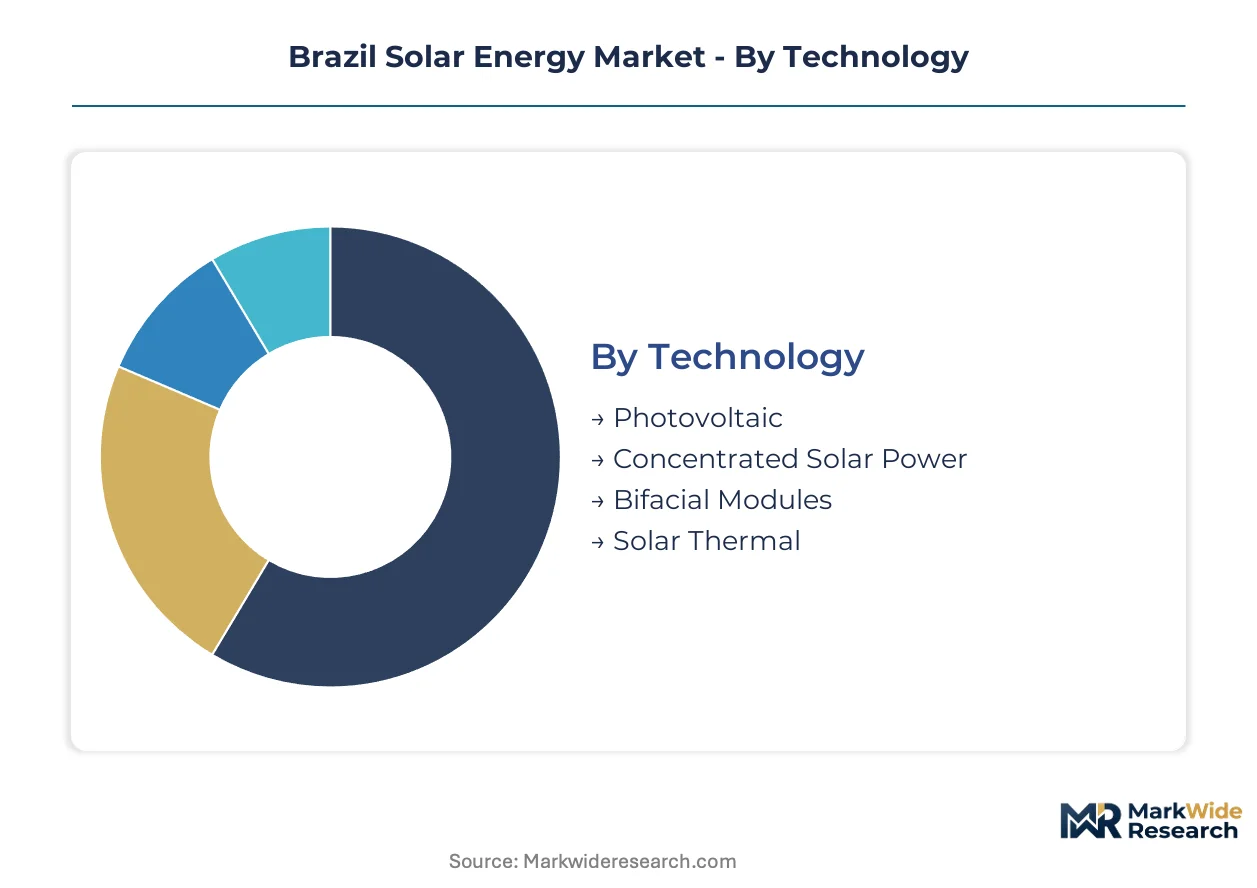
Technology and application boundaries in Brazil's solar market are dissolving as bifacial modules and hybrid storage systems force recalibration of procurement specifications. Segment selection determines access to BNDES financing, ANEEL interconnection priority, and the viability of distributed versus utility-scale development pathways.
Technology:
Photovoltaic variants face substitution pressure from emerging bifacial architectures that capture margin premiums through elevated energy yield in high-albedo regions.
- Photovoltaic:Crystalline silicon junctions converting sunlight to direct current electricity dominate installed capacity through proven reliability and ABNT certification pathways. Utility-scale tenders in Ceará and Piauí specify monocrystalline PERC architectures for temperature coefficient advantages in Northeastern climates.
- Bifacial Modules:Dual-sided cell architecture captures reflected irradiance from ground surfaces, delivering energy yield premiums in Bahia's arid zones. Developers recalculate IRR models around bifacial compatibility as procurement specifications harden in utility-scale auctions.
- Concentrated Solar Power:Thermal collection systems using mirrors to concentrate sunlight remain commercially nascent in Brazil's development pipeline.
- Solar Thermal:Heat absorption systems for water heating and industrial process applications occupy niche deployment segments outside electricity generation.
Photovoltaic technology anchors the volume base while bifacial modules gain share at the steepest rate.
Application:
Cost tier differentiation separates premium utility-scale parks from standardized distributed generation installations competing for interconnection queue priority.
- Utility-scale:Grid-connected solar parks exceeding 5 MW capacity dominate procurement volumes through centralized auction mechanisms and transmission-scale infrastructure. Northeastern states concentrate development gravity around land availability and irradiance profiles.
- Residential:Rooftop systems under 75 kW accelerate fastest under ANEEL's simplified net metering thresholds, with São Paulo metropolitan corridors driving channel volume.
- Commercial:Mid-scale installations serving retail and office facilities navigate more complex interconnection engineering than residential counterparts.
- Industrial:On-site generation for manufacturing and processing facilities competes with grid tariffs through self-consumption economics and demand charge reduction.
Utility-scale application anchors the volume base while residential deployment climbs the fastest.
End User:
Customer type concentration varies sharply across financing access, with BNDES local content requirements steering procurement patterns toward enterprise and energy provider segments.
- Energy Providers:Utility and independent power producer procurement drives module volume through centralized tenders and long-term power purchase agreements. Grid connection priority in ANEEL auctions concentrates influence among established developers.
- Enterprises:Corporate off-takers negotiate direct procurement contracts to satisfy renewable energy targets and hedge electricity price exposure.
- Households:Individual consumers access distributed generation through distributor-financed installation programs and net metering credits.
- Government:Public building and municipal facility procurement operates through distinct tendering frameworks with local content preferences.
Energy providers anchor the volume base while enterprises expand most quickly through corporate renewable procurement.
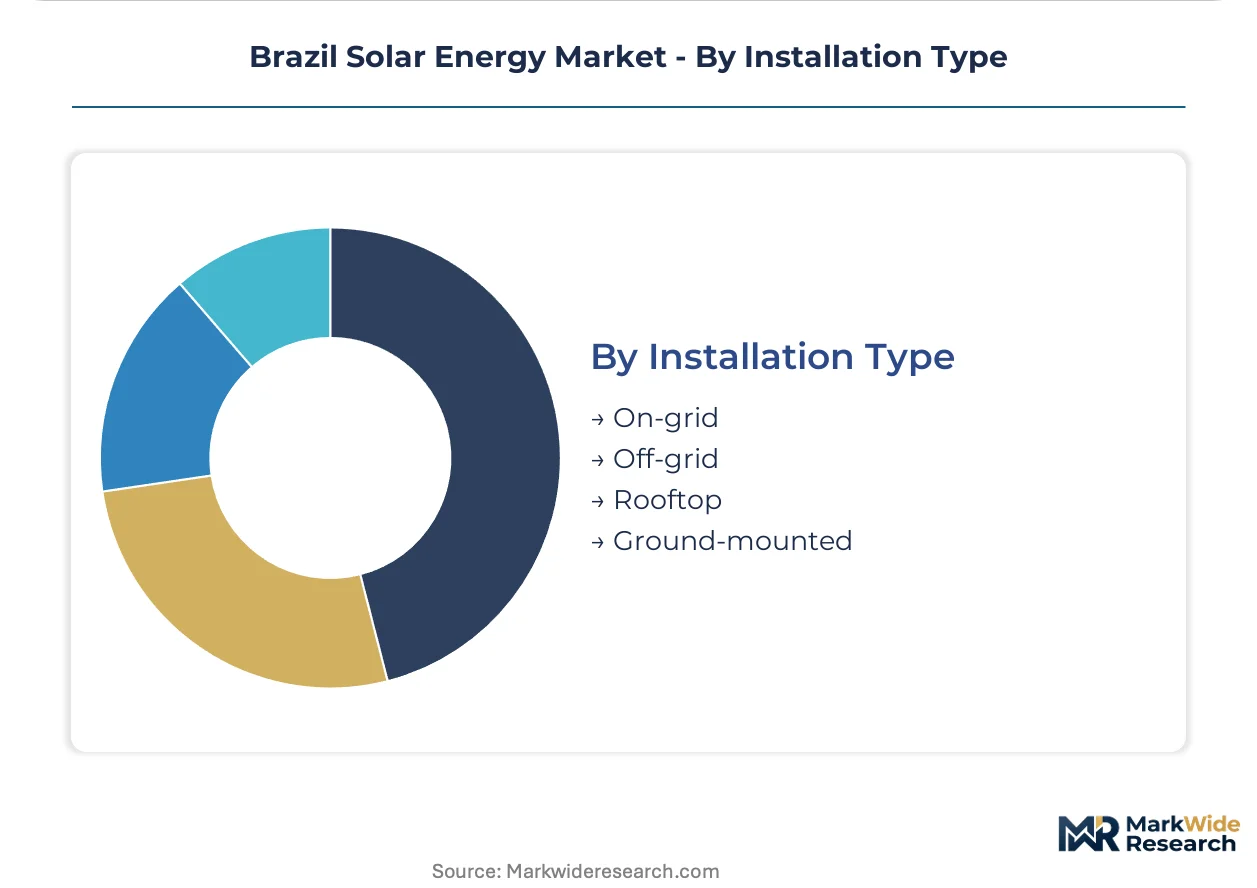
Installation Type:
Geography of deployment constrains technical specification, with grid infrastructure density determining viable installation pathways across Brazil's regional development gradient.
- On-grid:Synchronized systems feeding electricity into distribution networks capture ANEEL net metering benefits and priority dispatch mechanisms. Interconnection queue management in Minas Gerais and São Paulo determines project viability.
- Rooftop:Building-integrated systems minimize land use conflicts and leverage existing electrical infrastructure for distributed generation deployment.
- Ground-mounted:Fixed-tilt and tracking systems on dedicated land parcels dominate utility-scale capacity additions in Northeastern states.
- Off-grid:Standalone systems with battery storage serve remote municipalities beyond distribution network reach.
On-grid installation anchors the volume base while rooftop deployment expands most rapidly through regulatory simplification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Belo Monte-Rio transmission corridor anchors Northeastern Brazil's solar export capacity, while São Paulo's distribution network density enables distributed generation clustering across Southeastern industrial corridors.
Bahia
Arid-zone irradiance premiums attract utility-scale bifacial deployment across the São Francisco River basin. ANEEL's transmission auction schedules determine interconnection queue priority for developers securing land leases near Juazeiro. The Petrolina-Juazeiro twin-city corridor concentrates module logistics and O&M contractor capacity.
Ceará
Coastal wind-solar hybrid potential drives energy provider procurement through combined auction mechanisms. State-level environmental licensing reforms accelerate project permitting timelines for parks near Pecém industrial port. The Pecém Complex anchors manufacturing feedstock supply chains for Northeastern deployment.
Minas Gerais
Agribusiness cooperative demand for distributed generation steers module procurement toward BNDES-compliant domestic assembly. Simplified net metering thresholds under ANEEL's regulatory framework accelerate residential rooftop penetration around Belo Horizonte. The Triângulo Mineiro region concentrates agricultural processing load centers with favorable self-consumption economics.
São Paulo
Metropolitan distribution network density enables rapid interconnection for commercial and industrial rooftop systems. BNDES local content requirements channel module sourcing toward São José dos Campos and Sorocaba industrial corridors. The ABC Paulista manufacturing belt hosts domestic crystalline silicon assembly operations serving Southeastern demand.
Piauí
Land availability and irradiance profiles position the state for next-wave utility-scale auction participation. Transmission infrastructure investments under federal PAC programs reduce grid connection risk for projects near Teresina. The Margem Esquerda do Rio Parnaíba development zone concentrates early-mover developer land banking activity.
Brazil Solar Energy Market Vendor Landscape
Listed leaders compete with private specialists across capital access and development velocity, creating a tiered structure where scale determines auction participation eligibility. The vendor base separates into utility-scale auction specialists, distributed generation channel partners, and integrated manufacturers with captive Brazilian assembly. Three archetypes dominate: vertically integrated energy providers with transmission-scale pipelines, module manufacturers with localized production assets, and pure-play developers monetizing land and permitting expertise. Competitive dynamics center on securing ANEEL interconnection priority and satisfying BNDES local content thresholds.
Among European-headquartered energy providers, Enel Green Power Brasil and Engie Brasil Energia exemplify the integrated developer archetype combining auction participation with grid-connection queue management. Canadian Solar Inc. anchors the manufacturer-developer hybrid model through São Paulo-based module assembly and distributed generation channel partnerships. Elera Renováveis occupies a position among private specialists focused on Northeastern utility-scale origination.
| Leading Market Players |
|---|
| Enel Green Power Brasil |
| Elera Renováveis |
| Engie Brasil Energia |
| EDF Renewables Brasil |
| JA Solar Holdings Co. Ltd |
| Canadian Solar Inc. |
| Scatec ASA |
| Atlas Renewable Energy |
| JinkoSolar Holding Co. Ltd |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Chinese polysilicon refineries shapes module price floors across Brazilian procurement channels, compressing margin structures for distributors while elevating bargaining power for utility-scale developers with volume commitments. This scale dynamic concentrates supply influence among vertically integrated energy providers capable of direct manufacturer negotiations.
Pricing Analysis
Volume-discount tiering structures separate procurement economics across utility-scale auctions, agribusiness cooperative contracts, and residential rooftop installations. Premium pricing attaches to ABNT NBR IEC 61215-certified bifacial modules with elevated temperature coefficients, while standard crystalline silicon variants face cost compression from polysilicon input volatility. Price erosion runs through the residential channel as distributor-financed programs expand, making households the most price-sensitive segment and utility IPPs the least.
Supply Chain Analysis
China and Southeast Asia anchor crystalline silicon wafer and cell production, with Vietnam and Thailand expanding assembly capacity for Brazilian-bound exports. Brazilian distributors draw from these hubs for polysilicon feedstock, silver paste metallization, and aluminum framing components. Single-source vulnerability concentrates in polysilicon refining, where geopolitical trade measures threaten input cost stability. Distribution runs through São Paulo-based logistics corridors serving Southeastern agribusiness demand and Northeastern utility-scale project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's solar market approaches a platform-economics inflection as ANEEL's net metering framework and BNDES local content requirements create interoperability standards that reward ecosystem orchestrators over standalone module vendors.
For Market Incumbents: Fortify grid-connection queue priority through preemptive transmission auction participation in Ceará and Piauí, while deepening backward integration into domestic module assembly to satisfy BNDES thresholds. The threat of PERC technology obsolescence demands R&D allocation toward bifacial compatibility and tracking system integration. For New Entrants and Emerging Players: Lead with distributed generation channel partnerships targeting Minas Gerais agribusiness cooperatives, the most penetrable segment given simplified interconnection thresholds and unmet demand for BNDES-compliant procurement. A contractor-centric go-to-market angle leverages existing electrical installation networks over capital-intensive utility-scale origination. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors developers with captive Brazilian manufacturing assets and ANEEL auction track records. Long-term viability hinges on transmission infrastructure access and regulatory relationship depth. The signal to watch is forthcoming ANEEL distributed generation framework revisions that could restructure net metering economics.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Module Assembly Investment | BNDES local content compliance unlocks preferential financing for São Paulo corridor projects. |
| Transmission Auction Pre-qualification | ANEEL queue priority secures grid connection for Northeastern utility-scale origination. |
| Bifacial Technology Licensing | PERC cell architecture adoption addresses temperature coefficient demands in Ceará and Piauí. |
| Agribusiness Channel Partnership | Minas Gerais cooperative contracts concentrate procurement influence among agricultural processors. |
| Hybrid Solar-Storage Integration | Co-located battery systems capture evening peak demand from commercial and industrial off-takers. |
Methodological Framework
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and grid operators, then refined through secondary validation against EIA data, IEA renewable energy reports, ANEEL regulatory filings, and project development databases. Bottom-up installation capacity estimates were triangulated with top-down market value assessments across the analysis window.
Variance-decomposition framing isolated demand drivers by technology segment, application tier, and regional grid infrastructure maturity. The analytical framework modeled photovoltaic and bifacial module adoption, utility-scale versus distributed generation pathways, and Northeastern versus Southeastern deployment patterns. CAGRs were derived from segmented volume trajectories incorporating ANEEL auction schedules, BNDES financing availability, and irradiance-adjusted capacity factors.
Forecasts assume regulatory continuity in ANEEL net metering and BNDES local content regimes; material policy shifts would require re-modeling. Specific risks include transmission auction delays, polysilicon trade measure volatility, and ABNT certification backlog extensions. Recalibration cycles align with material shifts in ANEEL regulatory frameworks and federal infrastructure investment programs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Panels for Home Market
Solar Power Systems
Solar Metal Roof Market
Solar Power Systems
Saudi Arabia Solar PV Module Market
Solar Power Systems
Alternative Solar Photovoltaic Technologies Market
Solar Power Systems
Solar Photovoltaic Modules Market
Solar Power Systems
Residential Solar Shading System Market
Solar Power Systems
Asia-Pacific Solar Tracker Market
Solar Power Systems
Third Generation Solar Cell Sales Market
Solar Power Systems
Solar Phone Chargers Market
Solar Power Systems
Solar Shingles Market
Solar Power Systems
Czech Republic Solar Energy Market
Solar Power Systems
GCC Solar Water Heater Market
Solar Power Systems
US Solar Market
Solar Power Systems
Solar Concentrator Market
Solar Power Systems
Thin Film Photovoltaic Modules Market
Solar Power Systems
Canada Solar Energy Market