
 High Capacity Power Banks Market | 2026-2036
High Capacity Power Banks Market Size, Share, and Industry Trends Forecast 2026-2036
High Capacity Power Banks Market Foresight
Buyer concentration among remote professionals and outdoor enthusiasts is expanding beyond traditional consumer electronics channels into industrial procurement workflows. Anker Innovations leverages its charging technology heritage to dominate premium retail placement across North American and European electronics chains. Xiaomi sustains aggressive cost positioning through captive component sourcing and direct-to-consumer channel density in Asia. Sony Group Corporation differentiates via battery safety certifications and legacy trust in lithium-ion cell engineering.
High capacity power banks are electrochemical energy storage devices typically rated between 20000mAh and 30000mAh, engineered with lithium-ion or lithium-polymer cells and multiple output ports to sustain laptops, medical equipment, and power tools away from grid access. Fast charging power banks command margin premiums as USB-C Power Delivery and Quick Charge protocols reduce replenishment cycles for time-sensitive users. Multi-port configurations attract industrial and healthcare end users running simultaneous device loads, while solar-integrated variants remain niche due to conversion efficiency constraints and form factor trade-offs.
FCC certification governs electromagnetic emissions for US-bound units, while the EU Battery Regulation and CE marking enforce cell traceability and recyclability thresholds across European markets. China's GB standards and MIIT circulars mandate domestic cell testing protocols that shape export-ready manufacturing lines. Stakeholders must monitor evolving interoperability standards between Quick Charge and USB-C Power Delivery as protocol fragmentation risks inventory obsolescence and warranty exposure.
Market Dynamics
USB-C Power Delivery protocol standardization is compressing replenishment cycles and redrawing competitive boundaries between fast-charge specialists and legacy multi-port manufacturers. Shenzhen's cell packaging cluster now dictates which feature sets reach mass-market price points within eighteen months of specification release.
Growth Catalysts
- EU Battery Regulation traceability mandates:Carbon footprint disclosure requirements are forcing cell provenance upgrades that favor manufacturers with vertically documented supply chains.
- Remote professional equipment loads:Laptop-class power draw requirements above 60W are pushing buyers toward 20000mAh+ capacities previously confined to outdoor recreation segments.
- Lithium-polymer cell chemistry advances:Energy density improvements are enabling slimmer form factors without sacrificing rated capacity, expanding addressable use cases in medical transport and field diagnostics.
Market Restraints
- Lithium carbonate price volatility:Raw material input swings compress margin predictability for mid-tier manufacturers lacking long-term offtake agreements.
- Shenzhen supplier concentration:Overreliance on Pearl River Delta cell packaging and PCB assembly creates geographic risk exposure during regional logistics disruptions.
- Air transport restrictions:IATA lithium-ion watt-hour limits constrain direct-to-consumer shipping economics for capacities above 100Wh.
Strategic Opportunities
- Healthcare field deployment:Portable diagnostic equipment and cold-chain medication transport are creating certified-medical-grade demand segments with price inelasticity.
- India BIS certification pathways:Localized testing infrastructure expansion is reducing time-to-market for manufacturers targeting subcontinent government procurement channels.
- Solar-integrated hybrid architectures:Photovoltaic panel efficiency gains above 22% are narrowing the viability gap for off-grid professional use cases.
Industry Challenges
- FCC Part 15 certification timelines:Electromagnetic compatibility testing backlogs are extending product launch windows by four to six months for US-bound units.
- Quick Charge versus USB-C Power Delivery protocol fragmentation:Inventory configuration complexity is forcing manufacturers to maintain multiple firmware variants and warranty exposure profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Capacity Power Banks Market |
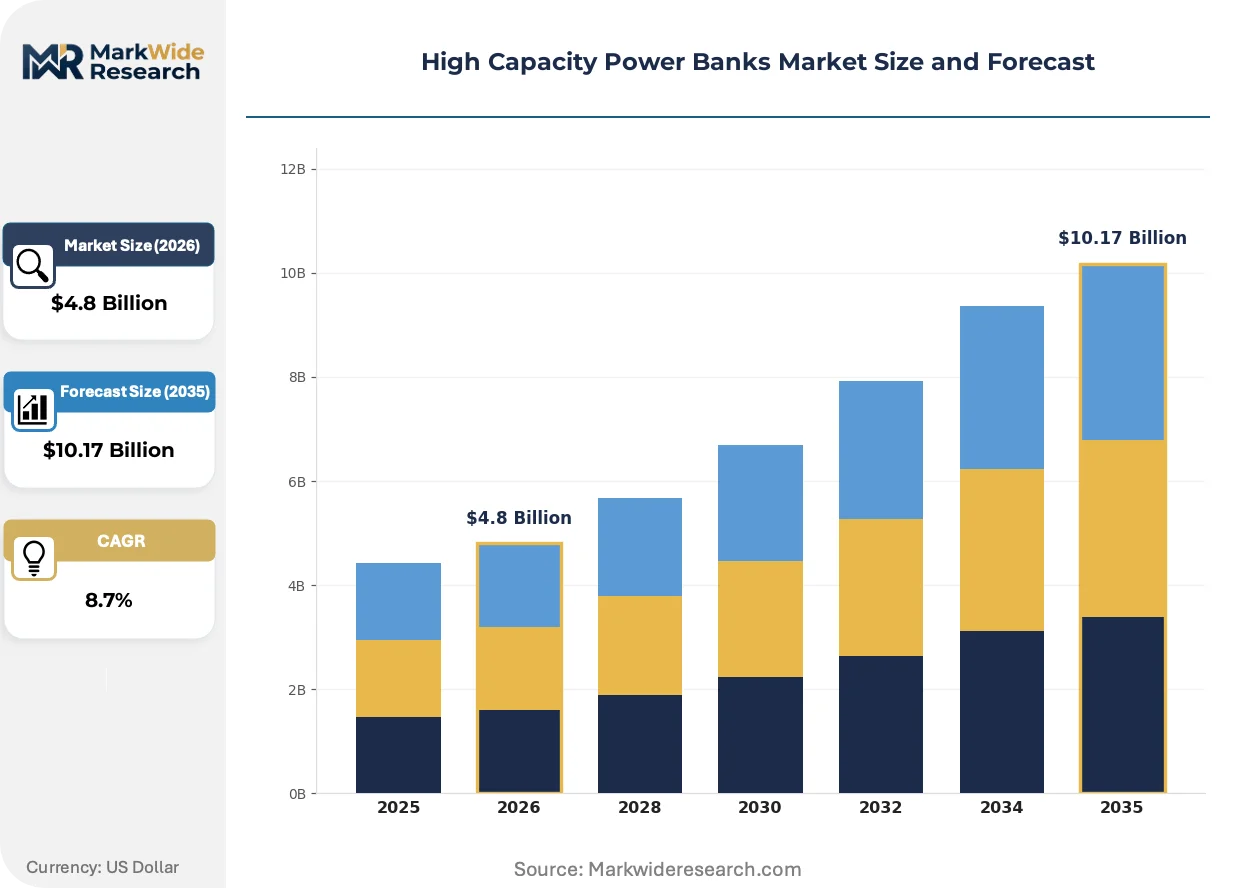
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Power Banks, Solar Power Banks, Fast Charging Power Banks, Multi-Port Power Banks End User: Consumer Electronics, Industrial Equipment, Healthcare Devices, Retail Applications Capacity: 5000mAh, 10000mAh, 20000mAh, 30000mAh Technology: Li-ion, Li-polymer, Quick Charge, USB-C |
| Companies Covered | Anker Innovations, Xiaomi, AUKEY, ADATA Technology, RAVPower, ROMOSS, Sony Group Corporation, Lenovo, Zendure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Capacity Power Banks Market Shifts & Advancements
Gallium nitride transistor adoption is collapsing thermal management footprints while regulatory carbon accounting is rewiring supplier qualification protocols. Buyer behavior is simultaneously fragmenting across direct-to-consumer, industrial procurement, and healthcare channel requirements.
GaN power electronics is converging with traditional silicon-based charging architectures in premium power bank segments. Medical equipment manufacturers and professional video production crews are adopting 65W+ GaN units at triple the pace of general consumer replacement cycles. This convergence is compressing the performance gap between pocket-sized and laptop-dedicated power banks, forcing portfolio rationalization across tier-one manufacturers.
The EU Battery Regulation's digital passport requirements are mandating cell-level traceability from mining through end-of-life recycling. Manufacturers must now integrate blockchain-verified chain-of-custody documentation or forfeit European market access. Medical device and industrial tool OEMs face the steepest compliance cost escalation, with many restructuring supplier qualification around carbon intensity metrics rather than unit cost alone.
Enterprise procurement teams are consolidating portable power purchasing under IT asset management frameworks rather than decentralized departmental buying. Industrial field service divisions and healthcare system logistics departments are displacing consumer retail channels for volumes above fifty units annually. This pattern is most pronounced in Germany and the Netherlands, where ESG procurement mandates intersect with centralized fleet management practices.
High Capacity Power Banks Market Segmentation
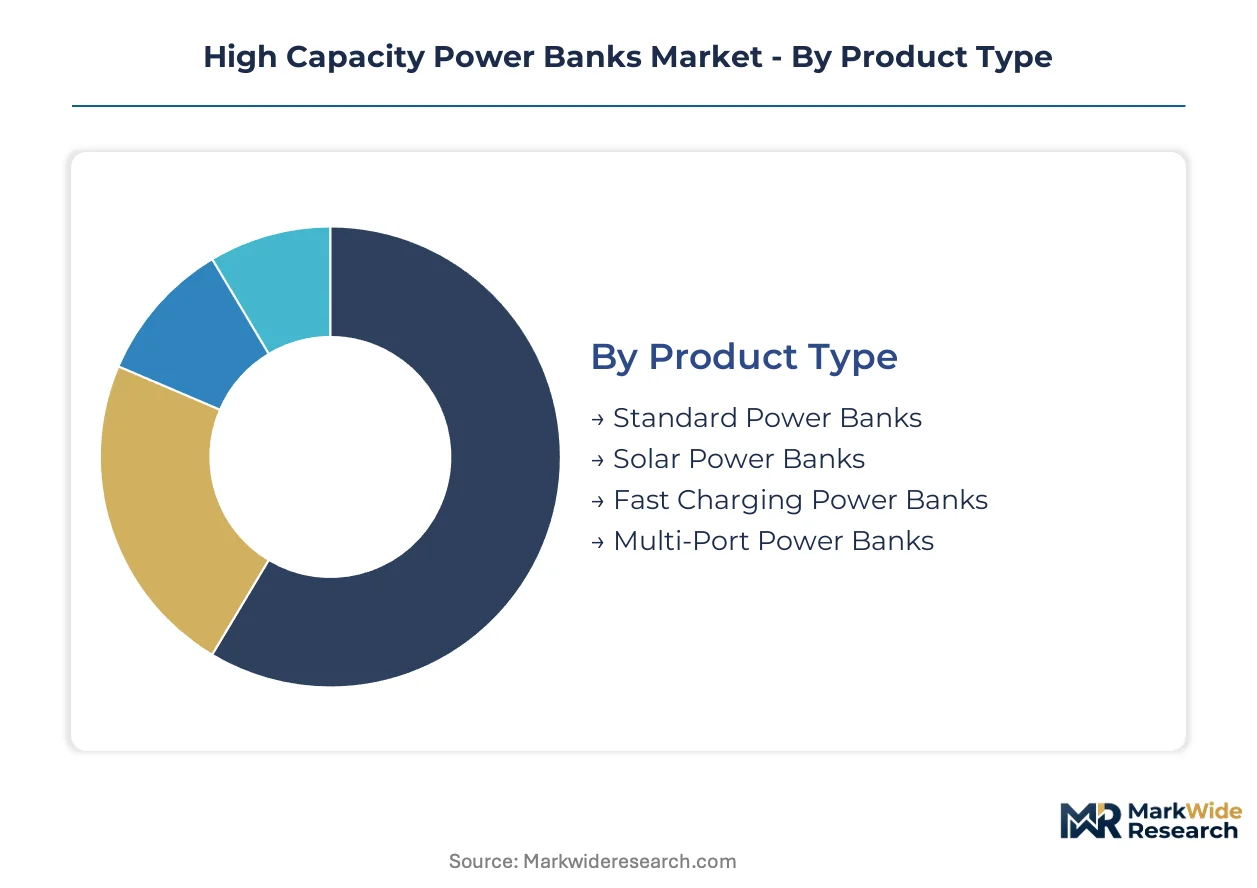
Power bank segmentation reveals divergent engineering priorities across user contexts. Specification thresholds for wattage, capacity, and protocol compatibility determine channel placement and margin capture.
Product Type:
Technology integration intensity separates mass-market units from premium configurations.
- Fast Charging Power Banks:GaN transistor architectures enable 65W+ output in compact form factors. Remote professionals in Germany and the Netherlands drive procurement through IT asset management frameworks seeking USB-C Power Delivery protocol standardization.
- Multi-Port Power Banks:Simultaneous output circuits sustain laptop, medical equipment, and power tool loads. Industrial field service divisions and healthcare system logistics departments in North America favor these for fleet deployment above fifty units annually.
- Standard Power Banks:Silicon-based charging architectures dominate unit economics in Asian retail channels.
- Solar Power Banks:Photovoltaic integration above 22% efficiency narrows viability gaps for off-grid professional use cases.
Multi-port configurations lead on scale; fast charging variants lead on momentum.
End User:
Procurement centralization intensity varies sharply across buyer categories.
- Industrial Equipment:Enterprise procurement teams consolidate portable power purchasing under IT asset management frameworks. FCC Part 15 certification timelines extend product launch windows by four to six months for US-bound field service divisions.
- Healthcare Devices:Certified-medical-grade demand segments exhibit price inelasticity for portable diagnostic equipment and cold-chain medication transport. EU Battery Regulation digital passport requirements mandate blockchain-verified chain-of-custody documentation.
- Consumer Electronics:Direct-to-consumer channel density concentrates in Shenzhen's electronics manufacturing cluster.
- Retail Applications:Electronics chains in North America and Europe anchor premium placement for established charging technology heritage brands.
Healthcare devices command margin premiums; industrial equipment captures volume concentration.
Capacity:
Energy density thresholds dictate transport economics and use case viability.
- 20000mAh:Lithium-polymer cell chemistry advances enable slimmer form factors without sacrificing rated capacity. Medical transport and field diagnostics applications in Europe expand addressable use cases through energy density improvements.
- 30000mAh:Laptop-class power draw requirements above 60W push remote professionals toward capacities previously confined to outdoor recreation segments. IATA lithium-ion watt-hour limits constrain direct-to-consumer shipping economics for capacities above 100Wh.
- 10000mAh:Pocket-sized portability dominates commuter and casual travel replacement cycles.
- 5000mAh:Emergency backup specifications satisfy airline carry-on restrictions with minimal form factor trade-offs.
20000mAh anchors current revenue concentration; 30000mAh exhibits steepest expansion trajectory.
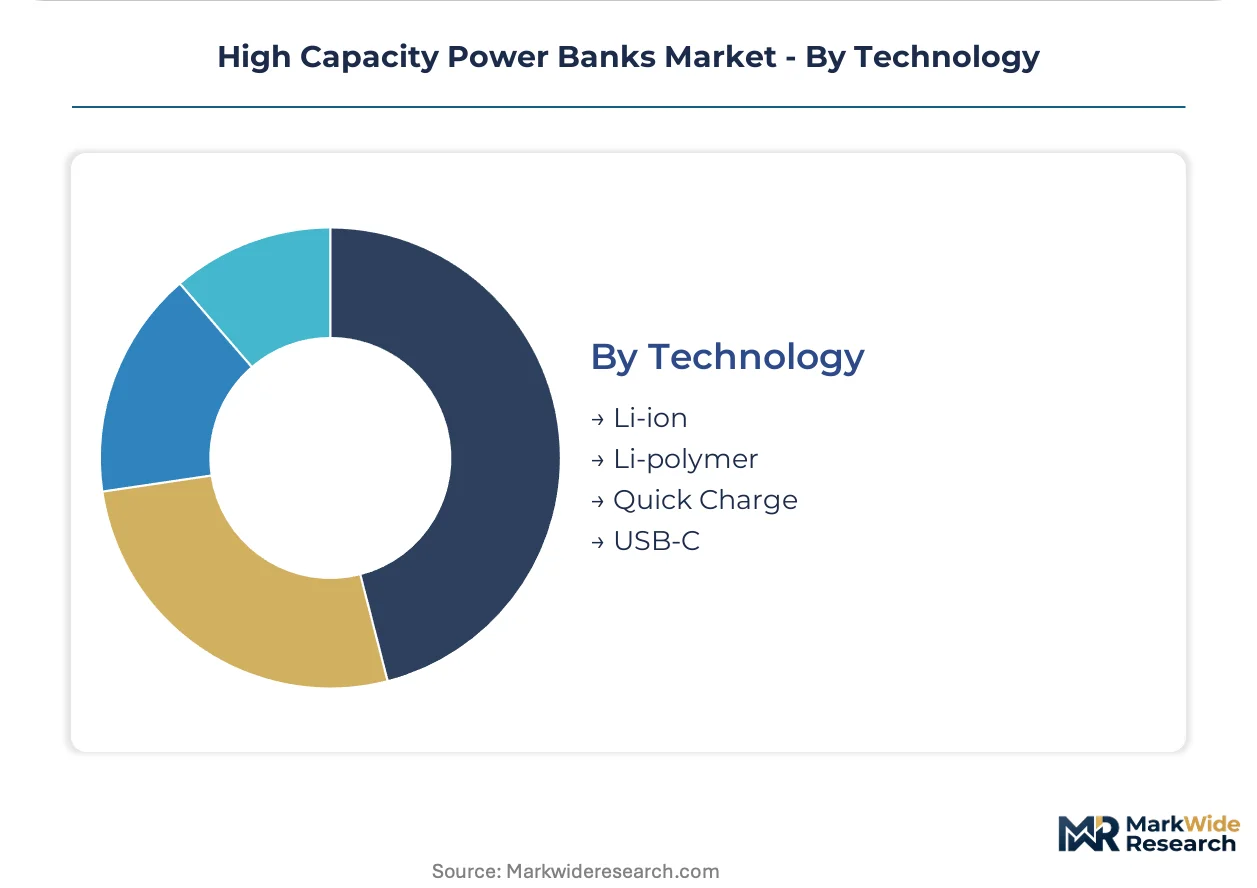
Technology:
Protocol standardization battles reshape inventory configuration complexity.
- USB-C:Power Delivery protocol standardization compresses replenishment cycles and redraws competitive boundaries. Shenzhen's cell packaging cluster dictates which feature sets reach mass-market price points within eighteen months of specification release.
- Li-polymer:Energy density improvements enable medical-grade slim form factors. Carbon footprint disclosure requirements under EU Battery Regulation force cell provenance upgrades favoring vertically documented supply chains.
- Li-ion:Legacy lithium-ion cell engineering sustains cost positioning through captive component sourcing in Asian markets.
- Quick Charge:Protocol fragmentation versus USB-C Power Delivery forces manufacturers to maintain multiple firmware variants and warranty exposure profiles.
USB-C leads on protocol adoption velocity; Li-polymer gains share fastest in premium medical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's electronics manufacturing dominance contrasts sharply with Germany's procurement-centralized demand patterns, while the United States and India represent divergent regulatory compliance pathways for manufacturers seeking market access.
United States
Remote professionals and industrial field service divisions drive procurement above fifty units annually through IT asset management frameworks. FCC Part 15 certification timelines extend product launch windows by four to six months for electromagnetic compatibility compliance. Austin and Seattle tech corridors concentrate demand for laptop-class 65W+ power delivery specifications.
Germany
Enterprise procurement teams consolidate portable power purchasing under centralized fleet management practices with ESG mandates. EU Battery Regulation digital passport requirements enforce blockchain-verified cell traceability from mining through recycling. Bavaria's medical device OEMs command certified-medical-grade segments with price inelasticity for diagnostic equipment power solutions.
China
Shenzhen's Pearl River Delta cell packaging cluster dictates mass-market feature sets reaching price points within eighteen months of specification release. MIIT circulars and GB standards mandate domestic cell testing protocols shaping export-ready manufacturing lines. Xiaomi leverages captive component sourcing and direct-to-consumer channel density across Asia.
India
BIS certification pathway expansion reduces time-to-market for manufacturers targeting government procurement channels and subcontinent industrial deployment. Remote worker adoption and outdoor recreation enthusiasts expand addressable demand beyond traditional consumer electronics. Maharashtra and Karnataka electronics manufacturing zones attract power bank assembly investments.
Japan
METI efficiency standards and legacy trust in lithium-ion cell engineering sustain premium positioning for safety-certified manufacturers. Medical transport and field diagnostics applications demand slimmer lithium-polymer form factors with energy density improvements. Tokyo-Osaka corridor concentrates enterprise procurement for healthcare system logistics departments.
High Capacity Power Banks Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: charging technology heritage brands, cost-positioned direct-to-consumer platforms, and safety-certified industrial suppliers. Consolidation pressures favor manufacturers with vertically documented supply chains capable of EU Battery Regulation compliance. Dominant competitive moves include M&A for cell provenance capabilities and strategic partnerships for healthcare certification pathways.
Within the charging technology heritage tier, Anker Innovations occupies a position exemplifying premium retail placement across North American and European electronics chains. Sony Group Corporation anchors the safety-certified industrial segment, representing legacy trust in lithium-ion cell engineering. Xiaomi sits within the cost-positioned direct-to-consumer archetype, exemplifying aggressive positioning through channel density in Asian markets.
| Leading Market Players |
|---|
| Anker Innovations |
| Xiaomi |
| AUKEY |
| ADATA Technology |
| RAVPower |
| ROMOSS |
| Sony Group Corporation |
| Lenovo |
| Zendure |
| Others |
Supply & Pricing Matrix
Captive lithium-polymer cell production in Shenzhen's Pearl River Delta anchors both supply security and margin control for tier-one manufacturers serving EU and US markets. This backward integration into cell packaging insulates premium brands from lithium carbonate volatility while compressing cost structures for mass-market entrants competing on direct-to-consumer platforms.
Pricing Analysis
Capacity additions in China's Pearl River Delta are reshaping price floors for silicon-based standard power banks while GaN-equipped fast-charging variants sustain margin premiums. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade certified units from consumer retail and white-label economy tiers. Cost compression in mid-market segments intensifies because Xiaomi's captive component sourcing forces competitor margin tightening. Industrial procurement teams exhibit least price sensitivity due to ESG-mandated fleet standardization, while casual commuter buyers drive volume through economy-tier replacement cycles.
Supply Chain Analysis
Air freight cost differentials above 100Wh IATA thresholds constrain direct-to-consumer economics for 30000mAh laptop-class units. Manufacturing concentrates in China, South Korea, and Japan for lithium-ion cell engineering and GaN transistor fabrication. Raw material dependencies rest on lithium carbonate from Australian and Chilean mining operations, copper foil from Japanese rolling mills, and electrolyte solvents from Chinese petrochemical complexes. Single-source vulnerability concentrates in Shenzhen PCB assembly clusters during regional logistics disruptions. Distribution runs through electronics retail chains in Germany and the Netherlands, direct-to-consumer platforms across Asia, and industrial procurement frameworks in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
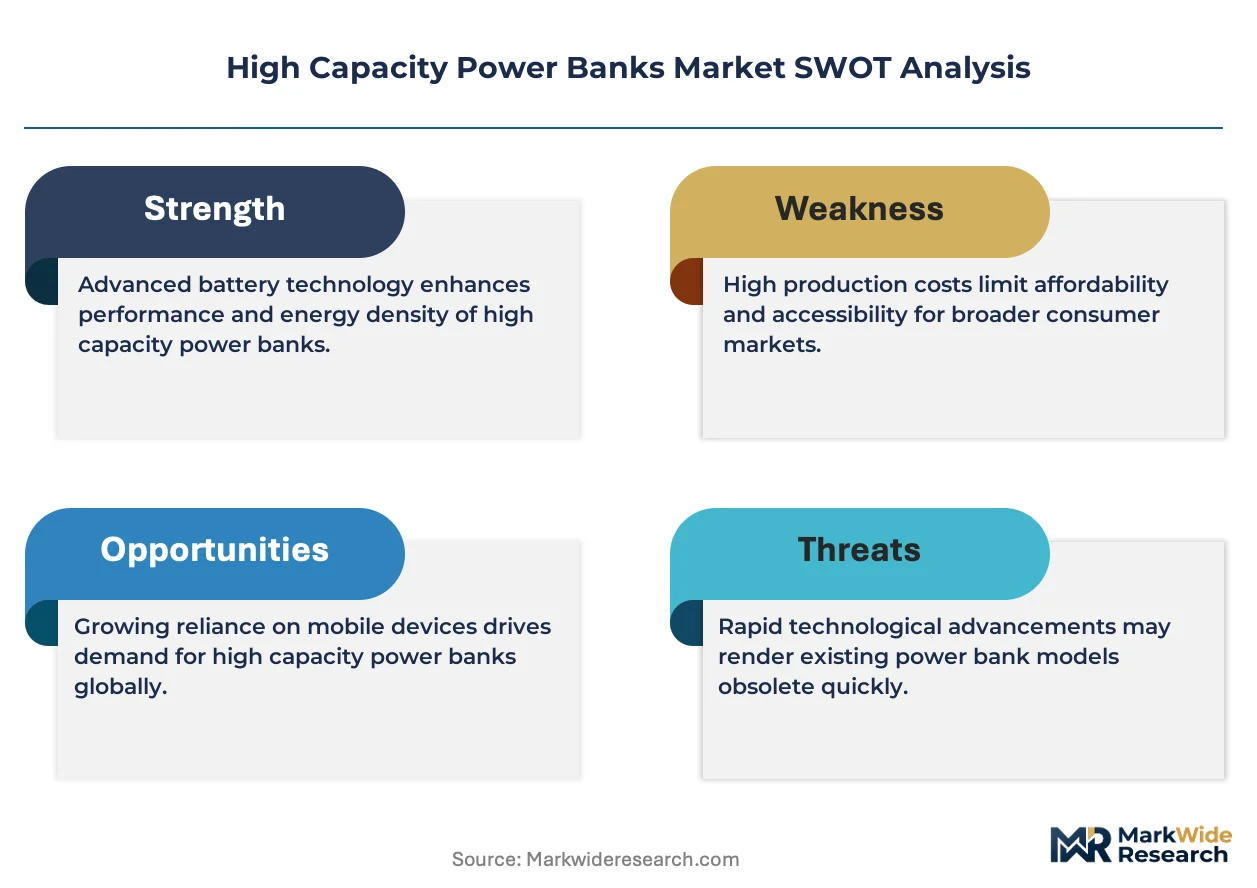
The High Capacity Power Banks Market compounds steadily as remote professional equipment loads institutionalize portable power as IT infrastructure rather than discretionary accessory.
For Market Incumbents: Anchor premium positioning through EU Battery Regulation digital passport compliance and GaN transistor R&D investment. Defend against Xiaomi's cost-positioned channel density by securing healthcare certification pathways for medical-grade segments. Capacity addition in Vietnam or India reduces geographic risk exposure from Pearl River Delta concentration. For New Entrants and Emerging Players: The 65W+ GaN premium tier and economy-tier silicon gap creates entry space for mid-market specialists targeting remote professionals in India and Southeast Asia. Underpenetrated government procurement channels in Maharashtra and Karnataka offer fastest volume accumulation. Direct-to-industrial sales partnerships with field service divisions bypass saturated retail channel slots. For Investors and Strategic Acquirers: Consolidation pressure builds where EU Battery Regulation traceability mandates exceed mid-tier compliance capabilities. Long-term viability favors vertically documented supply chains with blockchain-verified cell provenance. Acquisition targets include medical-grade certification holders and GaN transistor integration specialists. Watch IATA watt-hour threshold revisions as inflection indicator for 30000mAh segment economics.| Strategic Initiative | Industry Significance |
|---|---|
| EU Battery Regulation Compliance Program | Blockchain-verified cell traceability secures European market access for medical-grade manufacturers. |
| GaN Transistor Integration Partnership | 65W+ compact architectures capture remote professional procurement through IT asset management frameworks. |
| India BIS Certification Pathway Investment | Localized testing infrastructure accelerates government procurement channel penetration in Maharashtra. |
| Healthcare OEM Certification Alliance | Portable diagnostic equipment power solutions command price inelasticity in Bavaria's medical device cluster. |
| Alternative Geography Manufacturing Footprint | Vietnam or India assembly reduces Pearl River Delta logistics risk for US-bound FCC-certified units. |
Research Methodology
Bottom-up remote professional and healthcare equipment modeling reconciled against top-down Shenzhen manufacturing output tracking forms the analytical core of this study. Primary interviews with charging technology product managers, industrial procurement officers, healthcare system logistics directors, and FCC certification consultants combined with secondary validation from MIIT circulars, EU Battery Regulation implementation guidance, and IATA lithium-ion shipping guidelines. Trade data from China's General Administration of Customs, electronics retail audit feeds from German and Dutch markets, and hospital procurement database extracts triangulate volume estimates.
Input-output matrices map capacity utilization across lithium-polymer cell packaging lines to end-use demand segments over the projection horizon. Segmentation dimensions modeled include product type, end user category, capacity tier, and protocol technology. CAGRs derive from unit shipment trajectories weighted by average selling price evolution across premium GaN, standard silicon, and economy-tier configurations. Forecast inputs incorporate lithium carbonate price indices, IATA regulatory amendment timelines, and EU carbon accounting implementation schedules.
Caveats apply where lithium carbonate price spikes, IATA watt-hour threshold revisions, or EU Battery Regulation enforcement delays could materially shift the outlook. Forecasts reflect documented assumptions about protocol standardization velocity and healthcare certification pathway expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Battery Storage Boxes Market
Energy Storage
Super Capacitor Energy Storage System Market
Energy Storage
Sodium Sulfur (Nas) Battery for Energy Storage Market
Energy Storage
Global Data Center Energy Storage Market
Energy Storage
ASEAN Energy Storage Market
Energy Storage
Asia-Pacific Energy Storage Systems Market
Energy Storage
Grid Scale Battery Storage Sales Market
Energy Storage
Lead Acid Battery for Energy Storage Market
Energy Storage
Supercapacitor Market
Energy Storage
US Battery Energy Storage System Market
Energy Storage
Hydrogen Liquefaction System Market
Energy Storage
Marine Energy Storage System Market
Energy Storage
Ultracapacitors Market
Energy Storage
Grid-Scale Stationary Battery Storage Market
Energy Storage
Power Bank Market
Energy Storage
Energy Storage Sodium Ion Battery Market