
 Energy and Infrastructure Inertial Systems Market | 2026-2036
Energy and Infrastructure Inertial Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Energy and Infrastructure Inertial Systems Market Insights
Single-source reliance on defense-grade inertial component suppliers is decoupling from commercial energy infrastructure procurement patterns. Bosch Sensortec leverages MEMS fabrication scale to occupy the utility-grade sensor tier. Safran Group anchors European supply through its fiber optic gyro specialization for grid monitoring networks. Analog Devices competes by extending signal processing IP into integrated inertial modules that reduce OEM integration cost.
Energy and infrastructure inertial systems encompass gyroscopic and accelerometric sensors that measure angular rate and linear acceleration with drift specifications often below 0.01 degrees per hour, serving primarily to stabilize platforms, track assets, and enable dead-reckoning navigation where GPS signals degrade. MEMS gyroscopes lead volume shipments for smart grid and industrial automation end users due to their silicon-batch manufacturability and sub-hundred-dollar unit economics at scale. Fiber optic gyros command the premium tier in geophysical surveying applications where bias stability requirements exceed MEMS capability by orders of magnitude.
FAA certification protocols for unmanned aerial systems deployed in utility inspection, EU Green Deal resilience standards, and China's GB national standards for grid-connected equipment collectively shape product roadmaps and market access conditions for inertial system vendors. The EU AI Act's emerging requirements for autonomous decision-making in critical infrastructure will likely extend to sensor fusion systems that embed inertial data with machine learning pipelines. Stakeholders must monitor how dual-use export control expansions affect cross-border transfers of ring laser gyro technology originally developed for defense programs.
Market Dynamics
Defense-grade component suppliers are decoupling from commercial energy infrastructure procurement as utilities prioritize cost-optimized MEMS platforms over military-specification gyros for grid stabilization networks.
Growth Catalysts
- EU Green Deal Resilience Mandates:Infrastructure operators across Germany and France must certify inertial measurement units under new grid-hardening protocols, forcing sensor upgrades at substations and renewable interconnection points.
- Smart Grid Stabilization Platforms:Utilities deploying wide-area monitoring systems require gyroscopic sensors for synchronous phasor measurement, with demand concentrating among transmission operators modernizing legacy infrastructure.
- Renewable Energy Storage Scaling:Battery and pumped-hydro facilities in China and the United States deploy inertial navigation for precise turbine alignment and dam structural monitoring where GPS signals prove unreliable.
Market Restraints
- MEMS Performance Ceiling:Silicon-batch gyroscopes cannot achieve the bias stability required for geophysical surveying applications, forcing dependence on fiber optic alternatives at 10-50x unit cost.
- Dual-Use Export Controls:Ring laser gyro technology originally developed for defense programs faces cross-border transfer restrictions, fragmenting supply chains for high-precision industrial applications.
- Input Cost Volatility:Specialty optical fiber and rare-earth magnet materials concentrate sourcing in limited supplier geographies, exposing fiber optic gyro manufacturers to price instability.
Strategic Opportunities
- EU AI Act Sensor Fusion Requirements:Emerging autonomous decision-making mandates for critical infrastructure will extend certification to machine learning pipelines embedding inertial data, creating first-mover advantages for integrated module vendors.
- Utility-Grade MEMS Volume Tier:Bosch Sensortec's fabrication scale demonstrates pathway to sub-hundred-dollar unit economics at million-unit annual volumes, opening penetration into distribution-level grid monitoring previously served by mechanical alternatives.
- Unmanned Aerial System Inspection:FAA certification protocols for beyond-visual-line-of-sight utility surveys create dedicated demand for compact inertial units with GPS-denied navigation capability.
Industry Challenges
- Fiber Optic Gyro Talent Scarcity:Specialized photonics engineering expertise for coil winding and signal processing concentrates at defense contractors, constraining commercial sector hiring.
- Legacy System Integration Complexity:Substations running 1980s-era SCADA architectures require custom protocol bridges to incorporate modern inertial sensor outputs, extending deployment timelines.
- Multi-Standard Certification Burden:Vendors must simultaneously satisfy FAA airworthiness, EU Green Deal resilience, and China's GB national standards for grid-connected equipment, multiplying testing overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy and Infrastructure Inertial Systems Market |
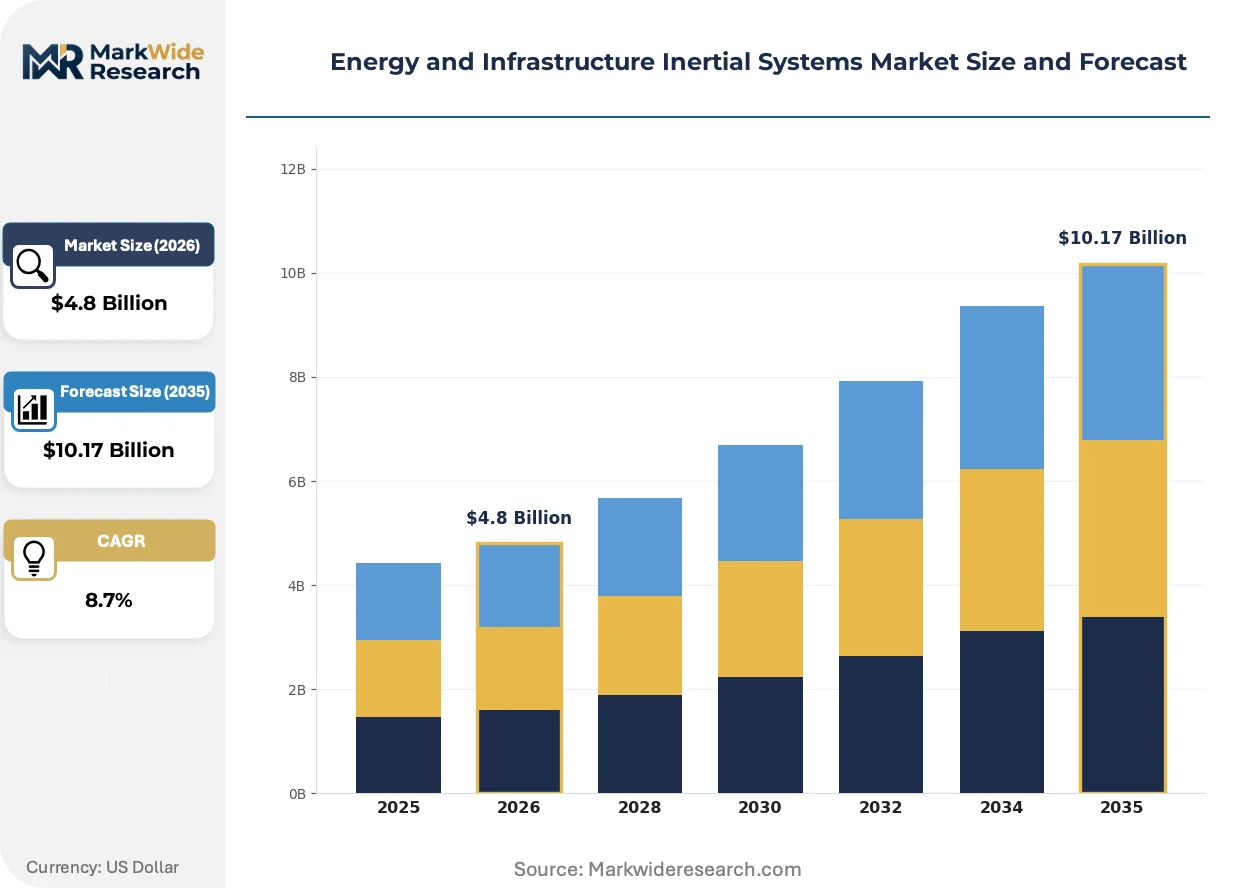
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Gyros, MEMS Gyroscopes, Ring Laser Gyros, Fiber Optic Gyros Technology: Microelectromechanical Systems, Quantum Sensors, Inertial Navigation, Signal Processing End User: Utilities, Oil & Gas, Industrial Automation, Smart Grids Application: Vehicle Navigation, Asset Tracking, Robotics, Geophysical Surveying |
| Companies Covered | Bosch Sensortec, Safran Group, Analog Devices, Thales Group, Northrop Grumman Corporation, Honeywell International, TDK, Silicon Sensing Systems, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy and Infrastructure Inertial Systems Market Trends and Innovations
Silicon-MEMS fabrication advances are compressing the performance gap with fiber optic platforms while machine learning integration is redefining how raw inertial data gets processed at the edge.
MEMS gyroscopes with closed-loop force-feedback architectures are overtaking open-loop designs in utility-grade applications. Transmission operators in Germany and Texas deploy these sensors for platform stabilization at accuracy thresholds previously requiring fiber optic units. The cost compression is enabling dead-reckoning navigation in GPS-challenged environments like urban canyons and underground substations.
The EU AI Act's emerging requirements for autonomous decision-making in critical infrastructure are reshaping product roadmaps for sensor fusion systems. Vendors must now document algorithmic transparency for machine learning pipelines that combine gyroscopic, accelerometric, and visual inputs. Grid monitoring networks across France and the Netherlands face the earliest compliance deadlines, accelerating procurement of certified integrated modules over discrete component assemblies.
Buyer consolidation among national transmission operators is shortening qualification cycles and demanding multi-year performance guarantees. State Grid Corporation of China and TenneT in the Netherlands now specify ten-year drift stability commitments, displacing the traditional transactional component purchasing model. This shift favors vendors with captive MEMS fabrication and in-house calibration capabilities over fabless design houses.
Energy and Infrastructure Inertial Systems Market Segmentation
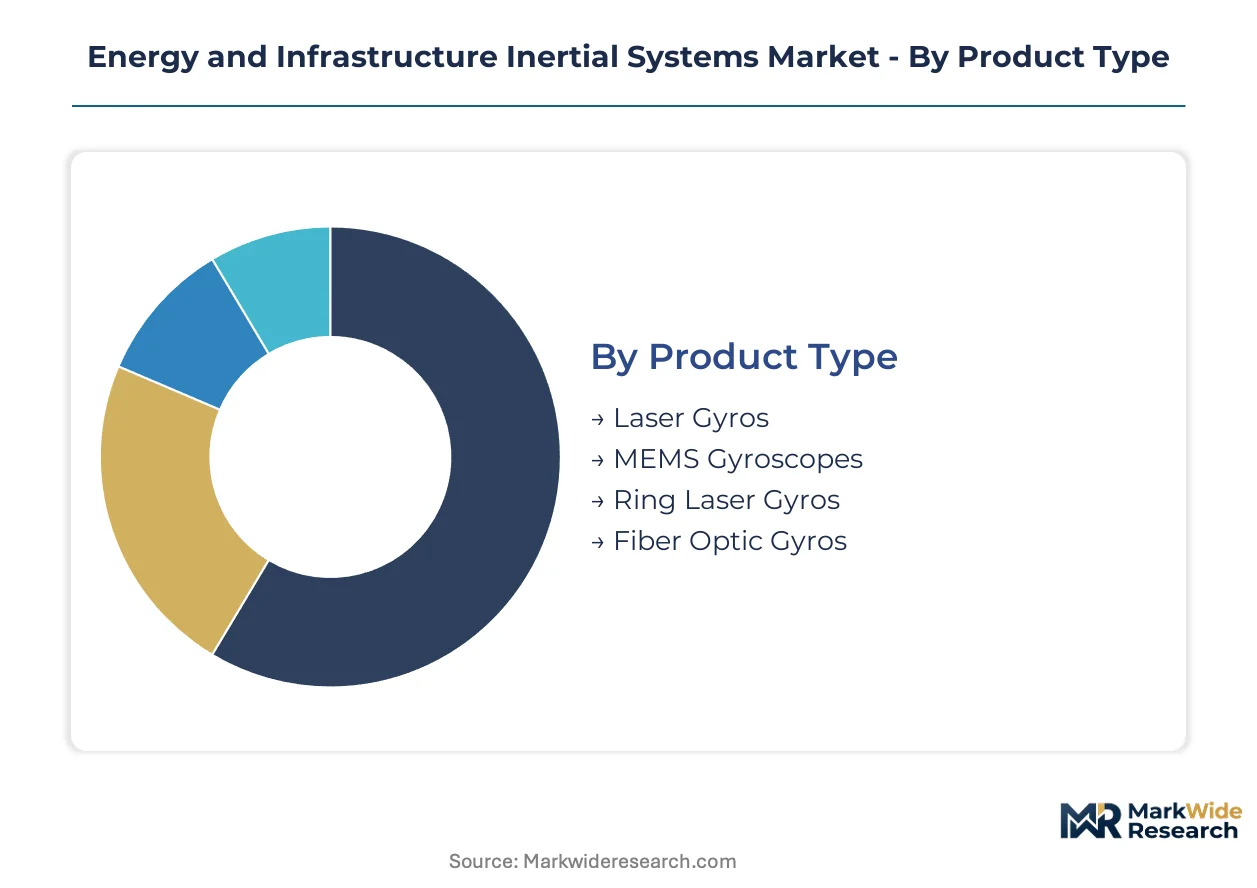
Technology selection in this market hinges on drift tolerance thresholds and total cost of ownership calculations across deployment environments. Procurement patterns diverge sharply between transmission operators demanding ten-year stability guarantees and distribution utilities optimizing for million-unit sensor economics.
Product Type:
Cost-performance positioning separates buyers seeking silicon-batch manufacturability from those requiring defense-grade bias stability.
- MEMS Gyroscopes:Silicon-batch fabrication enables closed-loop force-feedback architectures with sub-hundred-dollar unit economics at utility scale. Demand concentrates among smart grid operators in Germany and Texas deploying platform stabilization networks where GPS signals degrade in urban canyons and underground substations.
- Fiber Optic Gyros:Specialty optical fiber coils with interferometric signal processing achieve bias stability orders of magnitude beyond MEMS capability. Geophysical surveying contractors across the United States and China absorb premium pricing for turbine alignment and dam structural monitoring where GPS denial is absolute.
- Laser Gyros:HeNe gas laser cavities with ring cavity interferometry deliver navigation-grade accuracy for unmanned aerial inspection platforms.
- Ring Laser Gyros:Tri-axial configurations face dual-use export control restrictions that fragment supply chains for cross-border industrial procurement.
Volume sits with MEMS Gyroscopes; growth tilts toward Fiber Optic Gyros.
Technology:
Integration depth distinguishes vendors competing on module completeness versus component specialization.
- Microelectromechanical Systems:Bulk-micromachined silicon structures with capacitive sensing dominate utility-grade shipments through Bosch Sensortec's fabrication scale. Transmission operators in the Netherlands specify these platforms for synchronous phasor measurement systems requiring ten-year drift commitments.
- Signal Processing:Integrated analog front-ends with digital compensation algorithms reduce OEM integration cost and calibration overhead. Analog Devices extends this IP into compact modules capturing procurement from distribution-level grid monitoring previously served by discrete component assemblies.
- Inertial Navigation:Sensor fusion architectures combining gyroscopic, accelerometric, and magnetometric inputs enable dead-reckoning positioning in GPS-challenged environments.
- Quantum Sensors:Cold atom interferometry platforms remain laboratory-scale with limited commercial infrastructure deployment.
Procurement runs deepest through Microelectromechanical Systems; capability gaps favor Signal Processing for AI Act compliance deadlines.
End User:
Regulatory pressure intensity varies across infrastructure sectors facing divergent certification timelines.
- Utilities:Transmission and distribution operators modernizing legacy SCADA architectures drive the steepest expansion trajectory. EU Green Deal resilience mandates force sensor upgrades at German and French substations, while China's State Grid Corporation specifies multi-year performance guarantees displacing transactional purchasing.
- Smart Grids:Wide-area monitoring system deployments concentrate demand for compact inertial units with GPS-denied navigation. FAA certification protocols for beyond-visual-line-of-sight utility surveys create dedicated procurement channels separate from traditional grid hardware.
- Oil & Gas:Pipeline inspection robotics and offshore platform stabilization require marine-hardened enclosures with extended temperature ranges.
- Industrial Automation:Factory robotics and automated guided vehicles absorb volume-tier MEMS platforms for localization and collision avoidance.
Revenue concentrates with Utilities; compliance urgency accelerates Smart Grids procurement most aggressively.
Application:
Environmental constraints determine whether MEMS performance ceilings force fiber optic substitution.
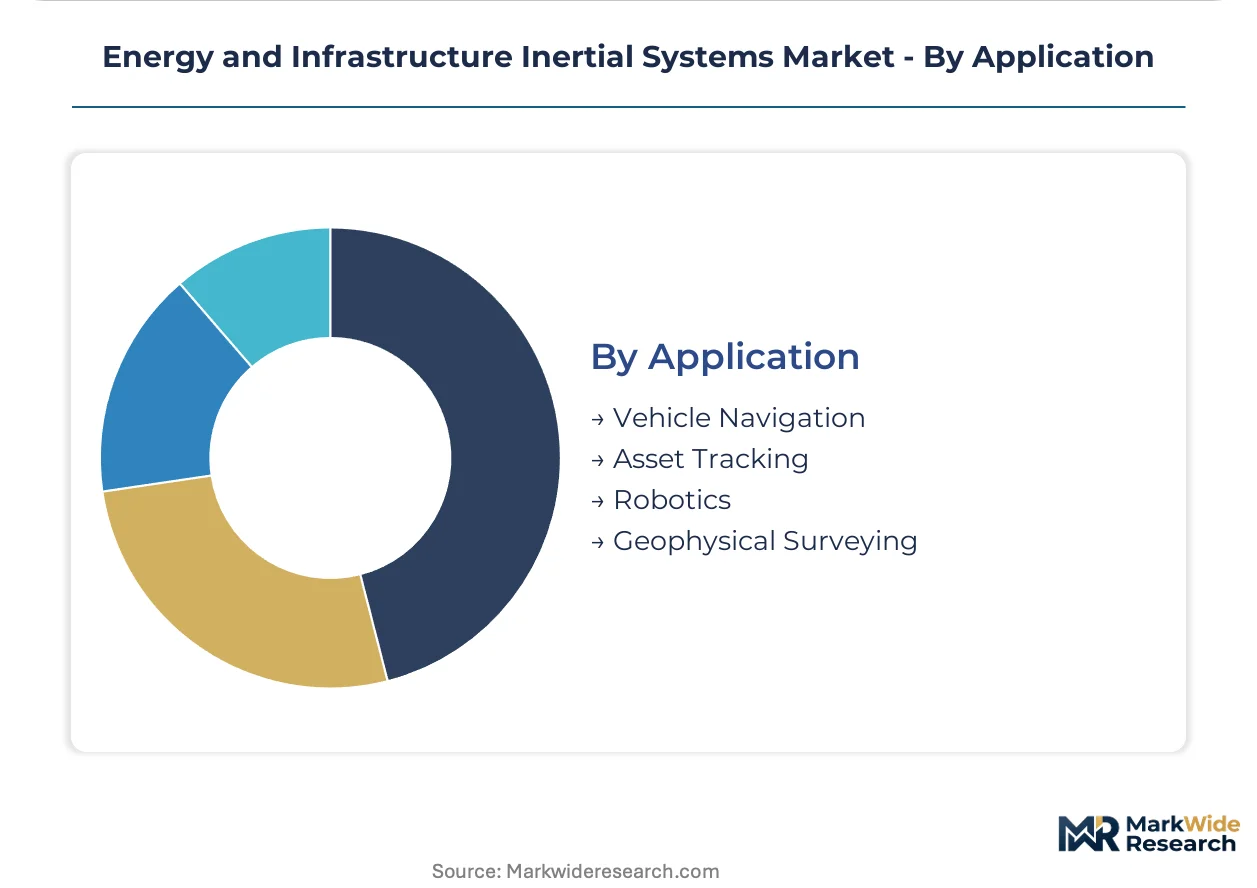
- Geophysical Surveying:Borehole logging and seismic monitoring operations demand bias stability exceeding MEMS capability. Contractors in China and the United States accept 10-50x unit cost premiums for fiber optic platforms ensuring precise turbine alignment in pumped-hydro facilities.
- Asset Tracking:Container and fleet monitoring applications prioritize power efficiency and form factor over absolute accuracy. Silicon-batch economics enable penetration into logistics networks previously unserved by inertial navigation.
- Vehicle Navigation:Autonomous utility vehicles and inspection drones integrate compact units for GPS-denied tunnel and urban canyon operation.
- Robotics:Industrial and field robotics combine inertial data with visual SLAM for localization in unstructured environments.
Technology premiums persist in Geophysical Surveying; unit economics democratize Asset Tracking fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates most visibly across Germany, the United States, and China as each nation scales renewable energy storage and grid modernization investments.
Germany
Transmission operators modernizing legacy SCADA architectures drive sensor procurement at substations and renewable interconnection points. EU Green Deal resilience mandates force certification upgrades for inertial measurement units under new grid-hardening protocols. Industrial clusters in Bavaria and North Rhine-Westphalia host utility-grade MEMS integration facilities serving TenneT and other transmission system operators.
United States
Wide-area monitoring system deployments concentrate demand for synchronous phasor measurement applications across Texas and California grid networks. FAA certification protocols for beyond-visual-line-of-sight utility surveys create dedicated procurement channels for compact inertial units. The Pacific Northwest and Southwest regions host battery and pumped-hydro facilities deploying precise turbine alignment systems where GPS signals prove unreliable.
China
State Grid Corporation specifications for multi-year performance guarantees displace traditional transactional component purchasing across the national transmission network. GB national standards for grid-connected equipment shape product roadmaps and market access conditions for foreign vendors. The Yangtze River Delta and Pearl River Delta clusters concentrate domestic MEMS fabrication and calibration capabilities.
France
Réseau de Transport d'Électricité mandates accelerate sensor fusion procurement for autonomous decision-making in critical infrastructure networks. EU AI Act compliance deadlines for algorithmic transparency reshape machine learning pipeline certification requirements. The Île-de-France region anchors European headquarters for fiber optic gyro specialists serving geophysical surveying contractors.
Netherlands
TenneT specifications for ten-year drift stability commitments favor vendors with captive MEMS fabrication and in-house calibration capabilities. Distribution-level grid monitoring previously served by mechanical alternatives now absorbs silicon-batch sensor economics. The Randstad cluster hosts integrated module vendors capturing procurement from smart grid stabilization platform deployments.
Energy and Infrastructure Inertial Systems Market Competitive Landscape
Capacity expansion dominates the current landscape as vendors scale MEMS fabrication to capture utility-grade volume tiers. The market structures around three player tiers: defense-grade heritage suppliers with fiber optic specialization, silicon-batch scale manufacturers, and integrated module vendors reducing OEM integration cost. Strategic archetypes include captive fabrication specialists, fabless design houses, and signal processing IP extenders. M&A activity and strategic partnerships concentrate among module vendors seeking algorithmic transparency certification for EU AI Act compliance.
Within the defense-to-commercial transition tier, Northrop Grumman Corporation and Honeywell International exemplify heritage suppliers navigating export control restrictions on ring laser gyro technology. Bosch Sensortec occupies the scale-driven position among silicon-batch manufacturers. These three anchors illustrate how procurement patterns decouple from single-source defense-grade reliance as utilities prioritize cost-optimized MEMS platforms.
| Leading Market Players |
|---|
| Bosch Sensortec |
| Safran Group |
| Analog Devices |
| Thales Group |
| Northrop Grumman Corporation |
| Honeywell International |
| TDK |
| Silicon Sensing Systems |
| STMicroelectronics |
| Others |
Pricing and Supply Chain Analysis
Defense-grade fiber optic precision versus utility-grade MEMS scale bifurcates procurement economics and sourcing configurations across the energy and infrastructure inertial systems market. This tier divergence concentrates premium pricing with European and North American specialty fiber coil suppliers while silicon-batch manufacturers in East Asia capture volume economics through captive wafer fabrication.
Pricing Analysis
Volume shipments of MEMS gyroscopes trade at sub-hundred-dollar unit economics against fiber optic platforms commanding 10-50x premiums for geophysical surveying applications. Pricing stratifies across certification intensity, with EU Green Deal resilience mandates and FAA airworthiness protocols creating compliance-cost tiers that OEMs pass through to transmission operators. Cost compression in utility-grade segments is intensifying as Bosch Sensortec scales closed-loop force-feedback architectures, while fiber optic manufacturers face upward pressure from specialty optical fiber and rare-earth magnet input volatility. Distribution utilities optimizing for million-unit sensor economics exhibit highest price sensitivity; geophysical contractors accepting bias stability premiums show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from State Grid Corporation of China and TenneT, while distribution partnerships serve mid-tier industrial automation integrators. Captive MEMS fabrication concentrates in Germany, China, and the Netherlands, with specialty optical fiber coil winding anchored in France and the United States. Raw material dependencies draw from rare-earth magnet suppliers, high-purity silica preform vendors, and precision photonics component specialists. Single-source vulnerability in defense-derived ring laser gyro technology fragments cross-border procurement under dual-use export controls. Distribution runs through authorized component distributors for small-batch industrial orders and direct long-term offtake agreements for utility-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized photonics engineering talent scarcity props pricing power for fiber optic gyro vendors despite MEMS encroachment in adjacent utility segments. Capacity bottlenecks in coil winding expertise and calibration infrastructure constrain supply expansion more than fabrication equipment.
For Market Incumbents: Extend signal processing IP into integrated modules that reduce OEM integration cost and capture EU AI Act compliance procurement from algorithmic transparency requirements. Add captive calibration capacity in the Netherlands or Germany to meet TenneT-style ten-year drift commitments. Defend against MEMS substitution in platform stabilization by emphasizing bias stability specifications that silicon-batch platforms cannot achieve. For New Entrants and Emerging Players: The mid-tier price-point gap between premium fiber optic units and economy MEMS platforms creates white-space opportunity for closed-loop MEMS vendors with enhanced drift specifications. Target distribution-level grid monitoring in the Netherlands and Texas where mechanical alternatives face displacement. Pursue unmanned aerial system inspection certification as the fastest-penetrable segment with dedicated FAA procurement channels separate from saturated utility transmission markets. For Investors and Strategic Acquirers: Re-rating potential sits with integrated module vendors possessing algorithmic transparency certification capabilities given EU AI Act compliance deadlines across French and Dutch grid networks. Long-term viability favors archetypes with captive MEMS fabrication and in-house calibration infrastructure over fabless design houses exposed to foundry allocation risk. Watch State Grid Corporation procurement specification shifts toward multi-year performance guarantees as the inflection signal displacing transactional component purchasing.| Strategic Initiative | Industry Significance |
|---|---|
| Captive MEMS Fabrication Scale-Up | Bosch Sensortec's wafer capacity expansion enables sub-hundred-dollar unit economics at utility-grade volumes. |
| EU AI Act Algorithmic Certification | Sensor fusion vendors documenting machine learning pipeline transparency capture first-mover procurement from RTE mandates. |
| Specialty Optical Fiber Backward Integration | Upstream control over coil winding reduces rare-earth magnet price volatility exposure for geophysical surveying tiers. |
| Multi-Standard Certification Investment | Simultaneous FAA airworthiness, EU Green Deal resilience, and China GB standard compliance opens cross-border procurement access. |
| Calibration Infrastructure Geographic Expansion | In-house drift stability testing facilities in Bavaria or North Rhine-Westphalia satisfy TenneT ten-year commitment requirements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this energy and infrastructure inertial systems analysis. Primary interviews with utility planning officers, transmission system operator procurement leads, MEMS fabrication plant managers, and fiber optic gyro R&D directors combined with secondary validation from FERC interconnection filings, EU Green Deal implementation reports, and China GB standard technical committees. Bottom-up unit shipment modeling triangulated against top-down transmission infrastructure investment forecasts across the analysis window.
Data-stream reconciliation across technology tier shipment volumes, end-user procurement specifications, and regional regulatory compliance timelines informed the analytical framework. Segmentation dimensions modeled include gyroscope technology type, integration depth, utility versus industrial end-use, and application-specific drift tolerance requirements. CAGRs were derived from installed base replacement cycles and renewable energy storage capacity additions. Forecast inputs incorporated smart grid stabilization platform deployment pipelines and unmanned aerial system certification backlogs.
Inputs from transmission operator procurement databases and MEMS foundry capacity disclosures were available through the study window; gaps in defense contractor ring laser gyro production volumes introduce uncertainty bands around high-precision industrial tier estimates. Forecasts reflect assumptions regarding EU AI Act implementation timelines and dual-use export control enforcement intensity. Periodic stress-testing of base assumptions against State Grid Corporation specification updates and FAA rulemaking progress is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Modular Sub-Station Market
Transmission and Distribution
Europe Active Network Management Market
Transmission and Distribution
Global Transmission and Distribution Equipment Market
Transmission and Distribution
Japan High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Water Storage System Market
Transmission and Distribution
Australia High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Ring Main Unit Market
Transmission and Distribution
Power Transmission Cables Market
Transmission and Distribution
South-East Asia DC Distribution Network Market
Transmission and Distribution
Virtual Pipeline Market
Transmission and Distribution
High Voltage Distribution Substation Market
Transmission and Distribution
Pipeline Transportation Market
Transmission and Distribution
High Voltage Direct Current (HVDC) Transmission System Market
Transmission and Distribution
HVDC Transmission Systems Market
Transmission and Distribution
Gas Insulated Transmission Lines Market
Transmission and Distribution
Overhead Line Fault Passage Indicator Market