
 Solar Power Meters Market | 2026-2036
Solar Power Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Power Meters Market Analysis
Multi-source procurement of photovoltaic sensors is recalibrating vendor relationships across the solar metering supply chain. Fluke Corporation leverages its calibration laboratory network to sustain precision instrument credibility in North American utility channels. EKO Instruments anchors Japanese meter exports through JIS-certified pyranometer manufacturing. Apogee Instruments specializes silicon-cell radiometer architectures for distributed generation monitoring.
Solar power meters quantify irradiance, energy yield, and system performance through photodiode, thermopile, or silicon-cell sensors with spectral response ranges from 300 to 2800 nanometers. These instruments enable commissioning verification, performance ratio tracking, and revenue-grade settlement in photovoltaic installations. Smart meters now dominate utility procurement due to remote telemetry and time-of-use billing capabilities, while bi-directional meters capture fastest growth from feed-in tariff regimes. Digital technology segments command premium positioning through ANSI C12.20 accuracy certification, whereas electromechanical units retain residual demand in off-grid rural electrification.
FCC Part 15 governs wireless meter transmissions in the United States, while EU MID Directive 2014/32/EU mandates measurement instrument conformity across member states. India's CEA technical standards for grid connectivity require revenue-grade metering at all solar injection points. Stakeholders must monitor evolving interoperability protocols between meter hardware and distributed energy resource management platforms.
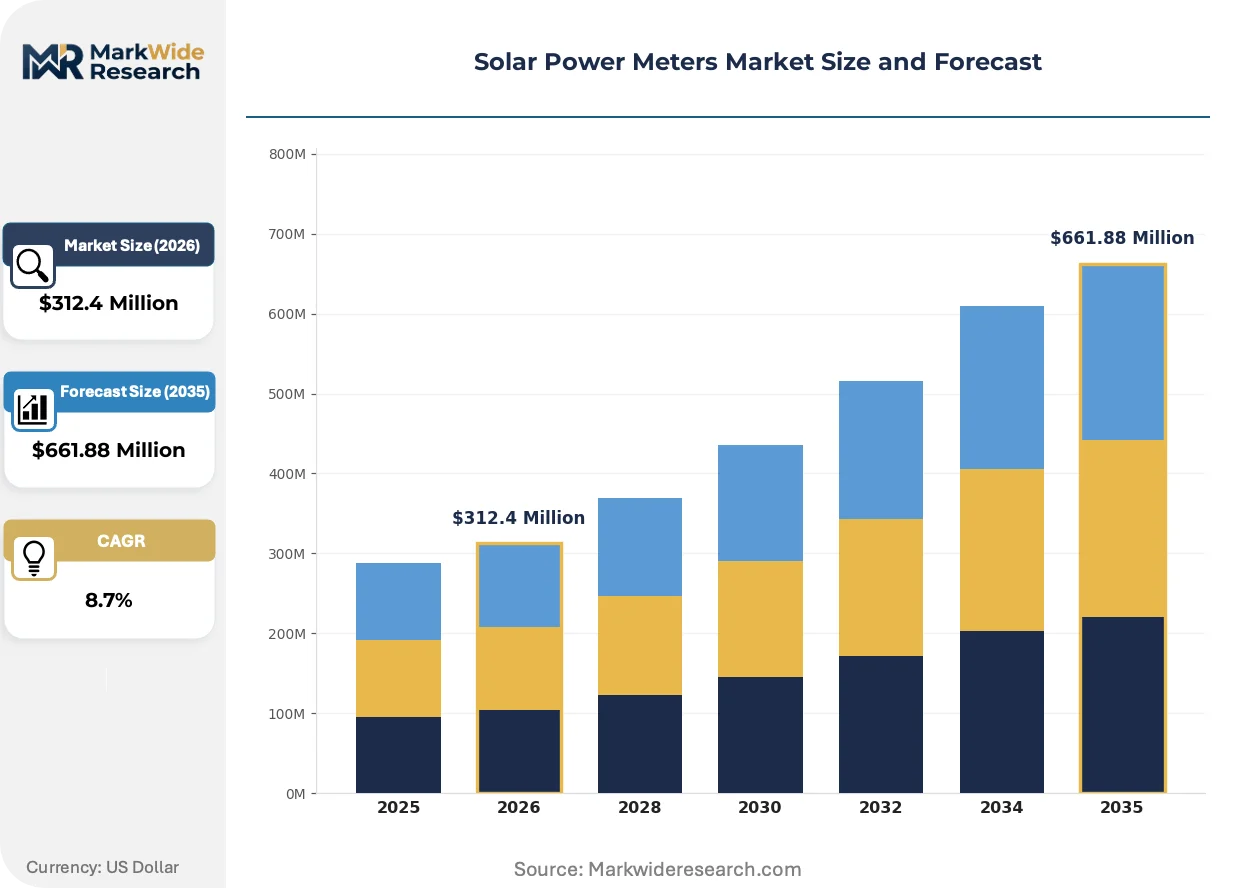
Market Dynamics
Grid interconnection mandates across multiple jurisdictions are forcing synchronous upgrades to revenue-grade metering infrastructure, compressing procurement cycles for utilities and independent power producers alike.
Growth Catalysts
- CEA Technical Standards:India's Central Electricity Authority mandates digital revenue-grade meters at all solar injection points, creating immediate replacement demand across utility-scale installations.
- Silicon-cell radiometry:Distributed generation monitoring applications favor compact photodiode architectures over thermopile sensors for cost-sensitive rooftop deployments.
- EU Green Deal targets:German utilities modernize distribution networks under binding decarbonization timelines, concentrating smart meter procurement in Europe's largest solar market.
Market Restraints
- Precision sensor concentration:High-grade thermopile manufacturing concentrates in Japanese and German facilities, exposing procurement to single-source vulnerabilities.
- Copper and semiconductor volatility:Meter electronics face input cost pressure from fluctuating PCB substrate and analog component markets.
- Spectral range limitations:Silicon-cell sensors truncate measurement accuracy beyond 1100 nanometers, restricting their use in concentrated solar power applications.
Strategic Opportunities
- Bi-directional meter adoption:Feed-in tariff regimes in Spain and Italy accelerate two-way metering deployment for prosumer compensation.
- Remote telemetry convergence:Cellular and mesh network protocols are integrating with distributed energy resource management platforms, opening meter-as-a-service revenue streams.
- ANSI C12.20 certification gap:North American utilities require accuracy-grade meters that few Asian manufacturers currently supply, creating white space for qualified entrants.
Industry Challenges
- Interoperability protocol fragmentation:Meter hardware must interface with multiple DERMS and SCADA standards, extending integration timelines.
- Calibration laboratory scarcity:Revenue-grade certification requires traceable irradiance reference standards that concentrate in national metrology institutes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Power Meters Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Net Meters, Smart Meters, Analog Meters, Bi-Directional Meters End User: Residential, Commercial, Industrial, Government Technology: Electromechanical, Digital, Hybrid, Wireless Installation: Grid-Connected, Off-Grid, Roof-Mounted, Ground-Mounted |
| Companies Covered | EKO Instruments Co., Ltd., Amprobe, Fluke Corporation, FLIR Systems, OTT HydroMet B.V., Campbell Scientific, Inc., Solar Light Company, Inc., General Tools & Instruments, Apogee Instruments, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Power Meters Market Emerging Trajectories
Photovoltaic metering is converging with grid-edge intelligence, transforming standalone instruments into networked data nodes that feed real-time analytics platforms.
LoRaWAN communication modules are integrating into residential and commercial meter enclosures, enabling low-power wide-area telemetry without cellular subscription costs. Australian and Brazilian utilities pilot these architectures for remote monitoring of distributed arrays. The technology is compressing total cost of ownership for rural electrification projects where cellular coverage remains uneven.
FCC Part 15 governs unlicensed wireless transmissions for smart meters in the United States, with recent enforcement actions targeting harmonic interference from dense meter clusters. Utilities in Texas and California are responding with frequency-hopping spread spectrum designs that reduce collision risk in high-deployment zones. This regulatory friction is accelerating hardware redesign cycles for North American suppliers.
Buyer aggregation through energy service companies is displacing direct utility procurement in commercial and industrial segments. These intermediaries bundle metering with performance guarantees, shifting specification authority from plant engineers to financial counterparties. The model concentrates most visibly in Germany and the Netherlands where third-party solar ownership dominates.
Solar Power Meters Market Segmentation
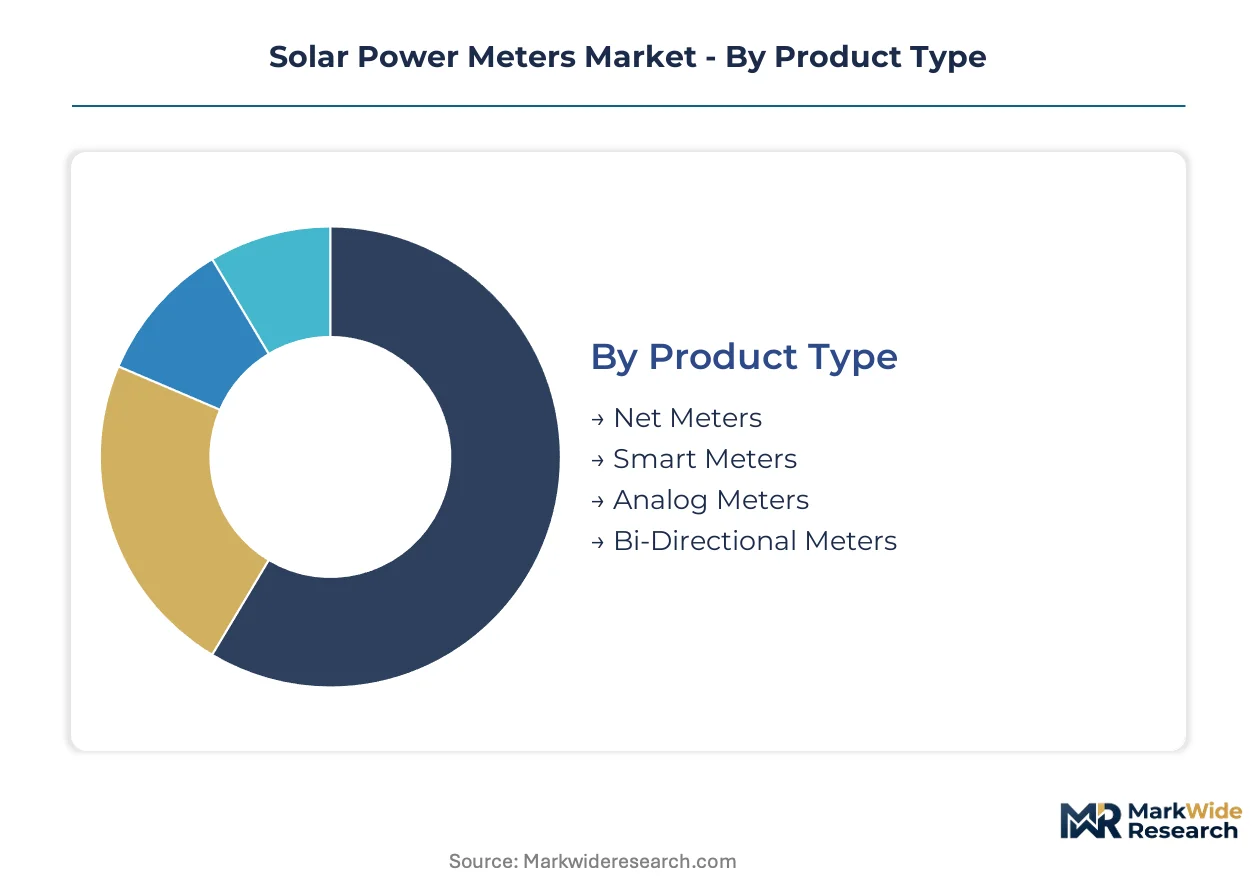
Solar power meter procurement varies sharply across deployment contexts, with accuracy certification and telemetry capabilities driving specification divergence between utility-scale and distributed generation buyers. Understanding these segment boundaries clarifies where vendors must align product architectures with distinct technical and commercial requirements.
Product Type:
Utility procurement teams prioritize telemetry integration and billing-grade precision when selecting meter categories for solar interconnection.
- Smart Meters:These units embed cellular or mesh network modules for remote data transmission alongside time-of-use billing registers. German utilities under EU Green Deal modernization mandates concentrate procurement here, seeking ANSI C12.20 or MID-certified units for distribution network visibility.
- Bi-Directional Meters:Two-way measurement registers track both grid consumption and solar export for net settlement under feed-in tariff regimes. Spanish and Italian prosumer installations drive fastest expansion here as compensation frameworks mature.
- Net Meters:Single-register architectures calculate net energy flow for simple rooftop compensation schemes.
- Analog Meters:Electromechanical dials persist in off-grid rural electrification where digital infrastructure remains uneconomical.
Smart meters lead on scale across utility procurement; bi-directional meters lead on momentum from prosumer segment expansion.
End User:
Customer scale determines specification complexity, with larger installations demanding revenue-grade certification and SCADA integration that residential buyers rarely require.
- Industrial:Manufacturing facilities and data centers mandate high-precision digital meters with power quality monitoring and direct DERMS integration. India's CEA grid-interconnection standards force synchronous upgrades across captive solar installations exceeding 10 MW.
- Commercial:Office buildings and retail chains favor wireless-enabled submetering for tenant billing and sustainability reporting. Energy service companies in Germany and the Netherlands bundle these specifications into third-party ownership structures.
- Residential:Homeowners prioritize cost-compact silicon-cell radiometers for rooftop performance monitoring.
- Government:Public buildings and military installations specify hardened enclosures with encrypted telemetry for critical infrastructure protection.
Industrial deployments dominate absolute unit value; commercial applications are climbing fastest as energy service companies consolidate procurement authority.
Technology:
Sensor architecture and communication protocol choices segment the supply base between precision instrument specialists and volume electronics manufacturers.
- Digital:Solid-state measurement with microprocessor-based error correction achieves ANSI C12.20 accuracy for revenue settlement. North American utilities restrict procurement to this category, creating certification barriers for Asian suppliers lacking traceable calibration laboratory networks.
- Wireless:LoRaWAN and frequency-hopping spread spectrum modules eliminate cellular subscription costs for remote monitoring. Australian and Brazilian utilities pilot these architectures for distributed array telemetry where cellular coverage remains patchy.
- Electromechanical:Rotating disk mechanisms retain residual demand in emerging market rural electrification.
- Hybrid:Combined digital registers with electromechanical displays bridge legacy and modern infrastructure.
Digital technology commands premium positioning through certification requirements; wireless integration shows steepest expansion trajectory as rural electrification scales.
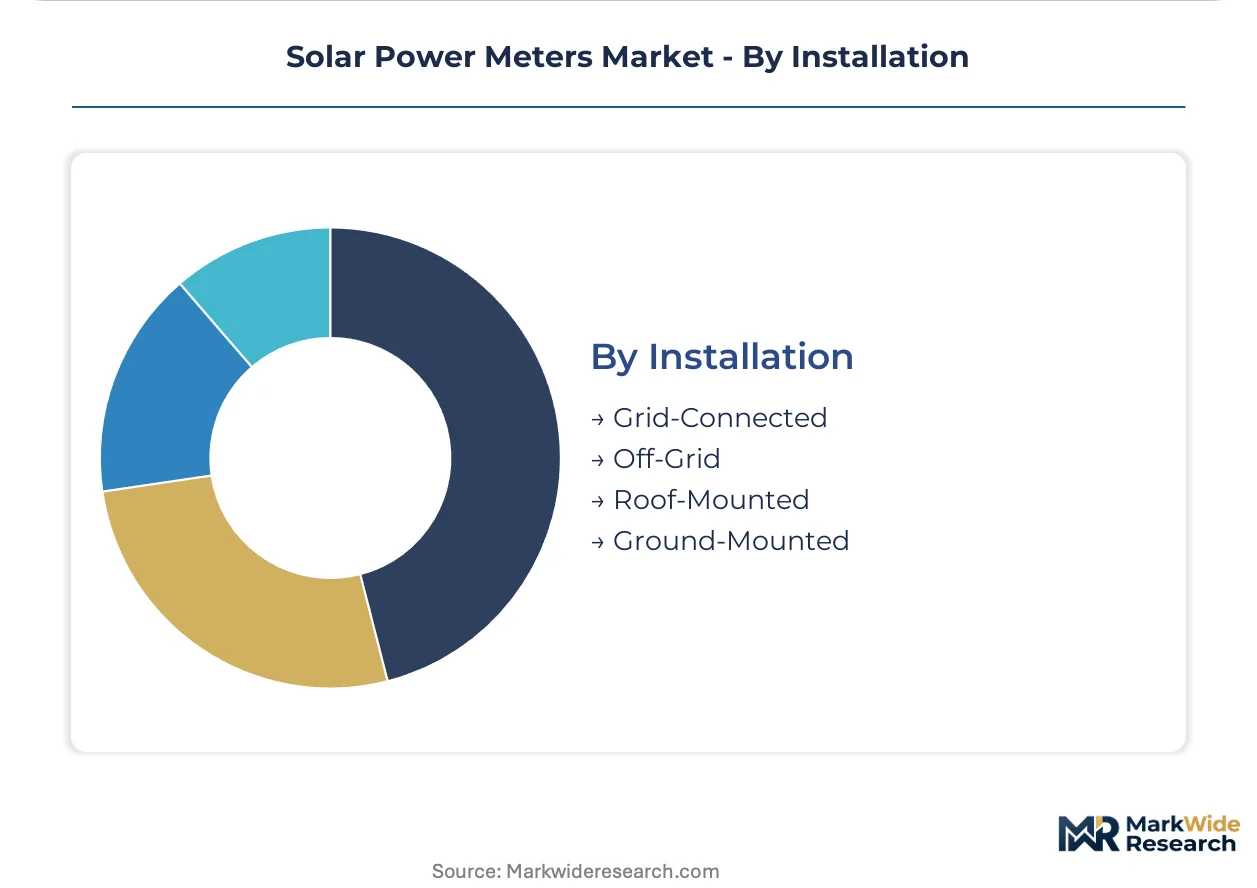
Installation:
Mounting configuration and grid relationship dictate enclosure standards, wiring topology, and environmental hardening requirements.
- Grid-Connected:Revenue-grade meters at utility interconnection points require anti-tamper seals and remote disconnect capability under FCC Part 15 or EU MID compliance frameworks. India's CEA mandates digital units at all solar injection points.
- Roof-Mounted:Compact silicon-cell radiometers with IP65 enclosures monitor distributed generation performance without utility settlement authority. German residential deployments concentrate demand for plug-and-play monitoring accessories.
- Off-Grid:Standalone systems in sub-Saharan Africa and Southeast Asia prioritize battery state-of-charge integration over grid synchronization.
- Ground-Mounted:Utility-scale solar farms specify thermopile pyranometers alongside revenue meters for resource assessment and performance ratio tracking.
Grid-connected installations anchor volume through regulatory mandate; roof-mounted distributed monitoring is expanding most quickly behind prosumer adoption curves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production footprints as manufacturers seek calibration-laboratory proximity and certification cost advantages. JIS-certified facilities in Japan and MID-aligned operations in Germany command premium positioning, while Indian and Chinese producers exploit scale economies for cost-sensitive distributed generation segments.
United States
Utility-scale solar farms in Texas and California drive revenue-grade meter procurement under FERC interconnection standards. FCC Part 15 governs wireless telemetry modules, with frequency-hopping spread spectrum designs reducing interference risks in dense deployment zones. The Southwest solar belt concentrates demand for ANSI C12.20-certified units with remote disconnect capability.
Germany
EU Green Deal decarbonization timelines compress distribution network modernization cycles across Baden-Württemberg and Bavaria. MID Directive 2014/32/EU mandates measurement conformity, while energy service companies in the Netherlands-Germany corridor bundle third-party ownership structures. LoRaWAN pilots in rural Bavaria eliminate cellular subscription costs for distributed array monitoring.
India
CEA technical standards mandate digital revenue-grade meters at all solar injection points above 10 MW capacity. Gujarat and Rajasthan utility-scale installations anchor procurement volume, with Maharashtra captive solar projects forcing synchronous upgrades. BIS certification requirements create entry barriers for uncertified imports.
Japan
JIS-certified pyranometer manufacturing concentrates precision sensor output for export markets. METI renewable energy targets sustain domestic demand, while Kyushu and Hokkaido solar clusters require thermopile architectures for performance ratio tracking. National metrology institutes maintain traceable irradiance reference standards.
Australia
Queensland and New South Wales utilities pilot LoRaWAN-enabled meters for remote distributed generation telemetry where cellular coverage remains patchy. AEMO grid codes mandate revenue-grade settlement accuracy, while rural electrification projects in Western Australia prioritize low-power wide-area protocols. TGA-equivalent electrical safety standards govern enclosure hardening.
Solar Power Meters Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue wireless-telemetry integration and meter-as-a-service revenue models. The supply base stratifies between precision instrument specialists with calibration laboratory networks and volume electronics manufacturers exploiting PCB assembly scale. Three archetypes dominate: JIS-certified Japanese pyranometer specialists, ANSI-aligned North American utility channel incumbents, and cost-optimized Asian silicon-cell radiometer suppliers. Capacity expansion concentrates in calibration-traceable facilities, while strategic partnerships bridge DERMS interoperability gaps.
Among Japanese precision instrument specialists, EKO Instruments Co., Ltd. exemplifies the JIS-certified pyranometer archetype with export-oriented manufacturing positioning. Fluke Corporation anchors North American utility channels through calibration laboratory network density and ANSI C12.20 certification credibility. Apogee Instruments, Inc. occupies the distributed generation monitoring tier, representing silicon-cell radiometer specialization for cost-sensitive rooftop deployments. These three entities illustrate the geographic and technological segmentation governing vendor selection across utility-scale and prosumer market segments.
| Leading Market Players |
|---|
| EKO Instruments Co., Ltd. |
| Amprobe |
| Fluke Corporation |
| FLIR Systems |
| OTT HydroMet B.V. |
| Campbell Scientific, Inc. |
| Solar Light Company, Inc. |
| General Tools & Instruments |
| Apogee Instruments, Inc. |
| Others |
Supply Flow & Price Mechanics
EU Green Deal decarbonization timelines gate qualified supply and premium-tier pricing access for solar power meter vendors, as MID-certified manufacturing capacity concentrates in German and Japanese facilities with traceable calibration laboratory networks. German utilities under binding modernization mandates pay premiums for ANSI C12.20 or MID-certified units, while cost-sensitive distributed generation buyers in emerging markets default to silicon-cell radiometers from Asian suppliers lacking certification infrastructure.
Pricing Analysis
Input-cost pass-through from copper and semiconductor volatility shapes three-tier pricing structure across premium, standard, and economy levels. Premium tiers anchor on ANSI C12.20 accuracy certification and remote telemetry integration for North American and German utilities, while economy tiers serve rooftop monitoring in India and Southeast Asia with silicon-cell architectures. Price differentiation rests on certification grade and after-sales calibration service bundling. Cost compression in standard tiers is intensifying because PCB substrate markets face analog component shortages. Residential prosumer segments exhibit highest price sensitivity; utility-scale IPPs under CEA mandates show lowest.
Supply Chain Analysis
Certification and qualification gating concentrates high-grade thermopile manufacturing in Japan and Germany, with JIS-certified pyranometer output feeding export markets through national metrology institute traceability. Raw material dependencies draw from copper substrate for PCB assemblies, semiconductor analog components for signal processing, and precision optical glass for sensor windows. Single-source vulnerability in irradiance reference standard calibration exposes procurement to national metrology institute queue delays. Distribution runs through direct utility procurement in regulated markets and energy service company aggregation in third-party ownership jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
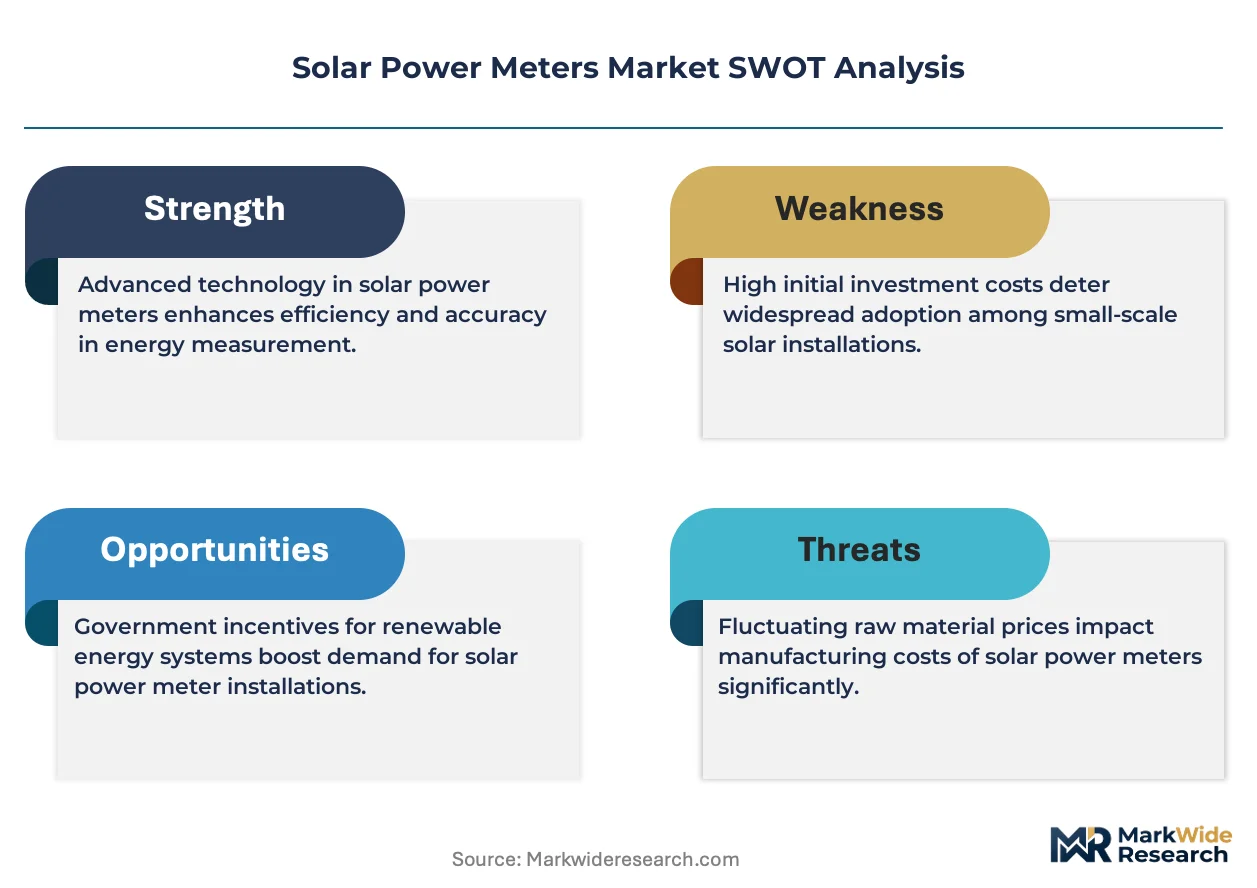
Margin expansion in solar power metering rests on silicon-cell cost-down curves displacing thermopile architectures in distributed generation segments, while premium-tier consolidation around ANSI C12.20 certification creates pricing power for qualified incumbents.
For Market Incumbents: Lock in calibration laboratory network density as a defensive moat against Asian silicon-cell radiometer suppliers seeking ANSI certification entry. Backward integration into precision optical component manufacturing reduces exposure to Japanese and German single-source vulnerabilities. Channel control through utility-direct relationships in Texas and California defends against energy service company procurement aggregation. For New Entrants and Emerging Players: Begin with wireless-telemetry integration for LoRaWAN-enabled rural electrification pilots in Australia and Brazil, where cellular coverage gaps create specification white space uncaptured by incumbent cellular-module architectures. Target commercial submetering bundled with sustainability reporting platforms in the Netherlands-Germany corridor. A meter-as-a-service revenue model with performance guarantees displaces capital-equipment procurement for third-party solar ownership structures. For Investors and Strategic Acquirers: Roll-up economics work for precision instrument specialists with JIS or MID certification credibility because calibration-traceable manufacturing capacity faces capacity constraints under EU Green Deal procurement compression. Long-term viability favors acquisition of mid-tier digital meter manufacturers with latent ANSI C12.20 certification pathways. The signal to watch is CEA mandate expansion below 10 MW thresholds in Indian state markets.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Network Expansion | Traceable irradiance standards under JIS and MID frameworks defend premium-tier positioning against uncertified imports. |
| LoRaWAN Module Integration | Low-power wide-area telemetry eliminates cellular subscription costs for Australian and Brazilian rural electrification pilots. |
| ANSI C12.20 Certification Investment | Accuracy-grade credentialing opens North American utility procurement channels currently closed to Asian suppliers. |
| Energy Service Company Partnership | Third-party ownership bundling in Germany and Netherlands concentrates procurement authority away from direct utility sales. |
| Silicon-cell Radiometer Cost Reduction | Photodiode architecture scaling captures distributed generation volume in cost-sensitive rooftop monitoring applications. |
Methodological Framework
Multiple input streams — structured interviews with utility planning officers and IPP project developers, EPC contractor procurement data, and regulatory filing analysis — were reconciled against secondary validation from FERC interconnection databases, CEA technical standard notifications, and EU MID directive implementation reports. Bottom-up unit economics from project-level meter procurement combined with top-down market sizing from national renewable energy agency capacity forecasts.
Data-stream reconciliation anchored the analytical framework across the projection horizon, modeling segmentation dimensions including product type (smart, bi-directional, net, analog), end-user scale (industrial, commercial, residential, government), technology architecture (digital, wireless, electromechanical, hybrid), and installation context (grid-connected, roof-mounted, off-grid, ground-mounted). CAGRs were derived from installed capacity trajectories and meter replacement cycles under evolving grid-interconnection mandates, with specific weighting for CEA compliance deadlines and EU Green Deal modernization timelines.
Several conditions sit outside the modeled scope, including potential harmonization of interoperability protocols between meter hardware and distributed energy resource management platforms, and abrupt shifts in copper or semiconductor commodity markets. Forecasts reflect documented assumptions about regulatory enforcement consistency and certification body capacity. A model refresh is warranted upon material change in India's CEA technical standard expansion or EU MID directive revision timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
US Solar Tracker Market
Solar Power Systems
Solar-Powered EV Charging Stations Market
Solar Power Systems
Solar PV Inverter Market
Solar Power Systems
Solar Shingles Market
Solar Power Systems
North America Rooftop Solar Market
Solar Power Systems
Europe Solar Photovoltaic (PV) Market
Solar Power Systems
Grid Connected PV Systems Market
Solar Power Systems
Solar Module Racking Market
Solar Power Systems
Optical Solar Reflectors Market
Solar Power Systems
Printable Solar Cells Market
Solar Power Systems
Plastic Solar Cell Market
Solar Power Systems
Solar Power Market
Solar Power Systems
Solar Vacuum Receiver Market
Solar Power Systems
Bangladesh Solar Energy Market
Solar Power Systems
Home Solar System Market
Solar Power Systems
Asia-Pacific Distributed Solar Power Generation Market