
 Solar Photovoltaics Wafer Market | 2026-2036
Solar Photovoltaics Wafer Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Photovoltaics Wafer Market Analysis
Project finance tied to long-term power purchase agreements is fragmenting capital requirements across smaller developers and independent power producers. LONGi Green Energy Technology Co Ltd leverages backward integration into polysilicon and ingot production to control feedstock costs across its wafer operations. JA Solar anchors its competitive stance through high-volume manufacturing of PERC-compatible wafers serving utility-scale developers. JinkoSolar differentiates via n-type wafer development aligned with heterojunction cell roadmaps.
Solar photovoltaics wafers are thin semiconductor discs sliced from monocrystalline or polycrystalline silicon ingots, typically 150-210 mm in diameter and 130-180 micrometers thick, serving as the substrate for photovoltaic cell fabrication where photon absorption generates electron-hole pairs for electricity conversion. Monocrystalline wafers command premium positioning due to higher conversion efficiency and declining cost parity with polycrystalline alternatives. Heterojunction technology applications represent the fastest-growing segment as cell manufacturers pursue efficiency gains above twenty-five percent. Utility-scale solar power plants concentrate the largest volume demand, though rooftop solar applications are expanding in distributed energy markets.
China's MIIT enforces GB standards that mandate minimum efficiency ratings for domestic wafer and cell production, while India's BIS certification requirements create compliance barriers for imported silicon substrates. The EU Green Deal and F-Gas Regulation indirectly shape wafer demand by accelerating solar deployment targets across member states. Stakeholders must monitor polysilicon supply constraints and n-type technology migration timelines when committing to capacity expansion or procurement contracts.
Market Dynamics
Wafer manufacturers face mounting pressure from China's GB standards tightening efficiency thresholds while utility-scale developers accelerate procurement of larger-format substrates. This dual squeeze between regulatory mandates and downstream scale economics is restructuring competitive positioning across the value chain.
Growth Catalysts
- India's PLI scheme:Production-linked incentives are attracting fresh cell and module capacity, concentrating demand for imported silicon substrates in Gujarat and Tamil Nadu manufacturing clusters.
- Heterojunction cell roadmaps:n-type wafer specifications are displacing p-type dominance as cell manufacturers pursue efficiency gains above twenty-five percent in premium utility installations.
- Dual carbon goals:China's national carbon neutrality targets are accelerating domestic polysilicon-to-wafer capacity expansion under MIIT efficiency mandates.
Market Restraints
- Polysilicon supply concentration:Xinjiang-based producers control critical feedstock volumes, creating geographic single-point vulnerability for non-integrated wafer manufacturers.
- Technical limitation in kerf loss:Diamond wire slicing cannot reduce silicon waste below current thresholds without compromising wafer mechanical integrity in high-volume production.
- Regulatory friction from BIS certification:India's Bureau of Indian Standards creates compliance barriers and testing delays for imported silicon substrates entering domestic cell fabrication facilities.
Strategic Opportunities
- Underpenetrated distributed solar:Rooftop installations across Southeast Asian urban centers remain undersupplied with appropriately sized wafers for residential module formats.
- EU Green Deal acceleration:Member state solar deployment targets are generating procurement pull for high-efficiency n-type substrates in German and Spanish utility pipelines.
- Technology convergence:TOPCon cell architectures are driving specification hybridization between traditional PERC-compatible and heterojunction-optimized wafer geometries.
Industry Challenges
- Skill gap in n-type crystal growth:Czochralski pullers with experience in low-oxygen monocrystalline ingot production remain scarce relative to expanding capacity requirements.
- Capex intensity for larger furnaces:210mm-compatible crystal growing equipment demands capital commitments that strain mid-tier manufacturers without captive polysilicon supply.
- Certification timeline compression:Accelerating technology roadmaps are compressing the validation window for new wafer specifications against evolving IEC standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Photovoltaics Wafer Market |
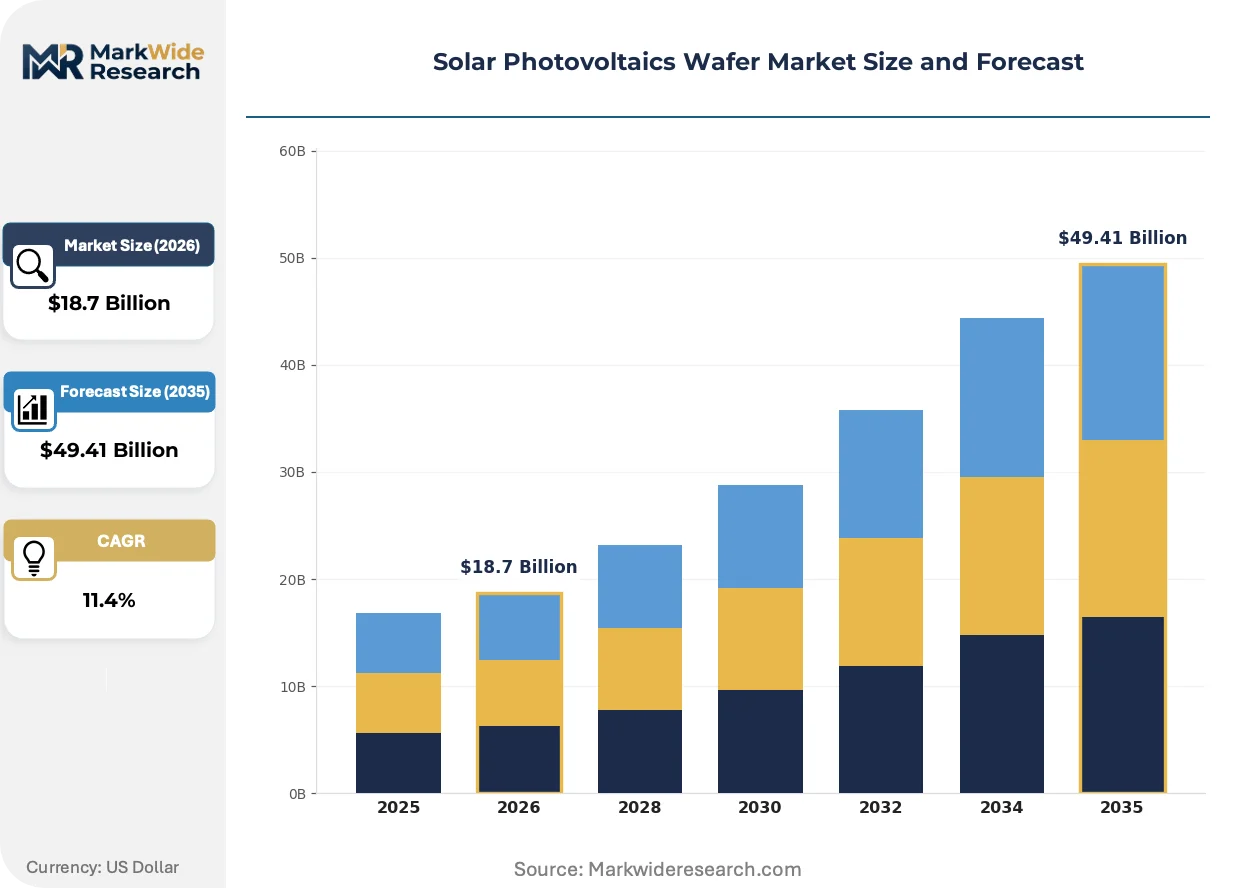
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Bifacial, Thin-Film End User: Residential, Commercial, Industrial, Utility Application: Solar Power Plants, Rooftop Solar, Off-Grid Systems, Building Integrated Technology: Passivated Emitter, Back Surface Field, PERC, Heterojunction |
| Companies Covered | LONGi Green Energy Technology Co Ltd, JA Solar, JinkoSolar, TCL Zhonghuan Renewable Energy Technology Co Ltd, GCL-Poly Energy Holdings Limited, Hanwha Q CELLS, CETC Solar Energy Holdings Co, Sino-American Silicon Products Inc, Canadian Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Photovoltaics Wafer Market Emerging Trajectories
Wafer technology trajectories are converging around efficiency maximization and format standardization, with cell manufacturer roadmaps dictating substrate specifications more aggressively than in prior technology cycles. This inversion of the traditional supply-push dynamic is reshaping R&D priorities across the value chain.
Heterojunction cell architectures are hybridizing wafer requirements by demanding ultra-low oxygen content and specific surface texturing compatibility that sits between traditional PERC and future tandem specifications. Japanese and European cell manufacturers are adopting these substrates fastest, compressing the timeline for p-type capacity obsolescence. The structural consequence is forcing polysilicon purification investments toward semiconductor-grade specifications that were previously reserved for electronic applications.
China's MIIT enforcement of updated GB standards is mandating minimum efficiency ratings for domestic wafer and cell production, eliminating substandard capacity from state-supported supply chains. Industrial consequence includes accelerated consolidation among second-tier manufacturers unable to meet the 23.5% cell efficiency threshold. The most affected segment is polycrystalline wafer production, which is rapidly exiting domestic Chinese supply even as it persists in export-oriented Southeast Asian facilities.
Utility-scale developers are consolidating procurement specifications around 182mm and 210mm formats, fragmenting the addressable market for smaller wafer diameters. Module manufacturers serving distributed solar channels are absorbing legacy 166mm and 158mm supply that utility-scale buyers have abandoned. This bifurcation is most visible in India, where rooftop installers exploit price differentials on depreciating wafer formats while utility projects demand premium large-format substrates.
Solar Photovoltaics Wafer Market Segmentation
Wafer procurement patterns diverge sharply across application contexts, with format specifications and efficiency tiers mapping directly to project finance structures and installation scale. Understanding these segment boundaries clarifies where margin pools concentrate and where technology transitions disrupt incumbent supply relationships.
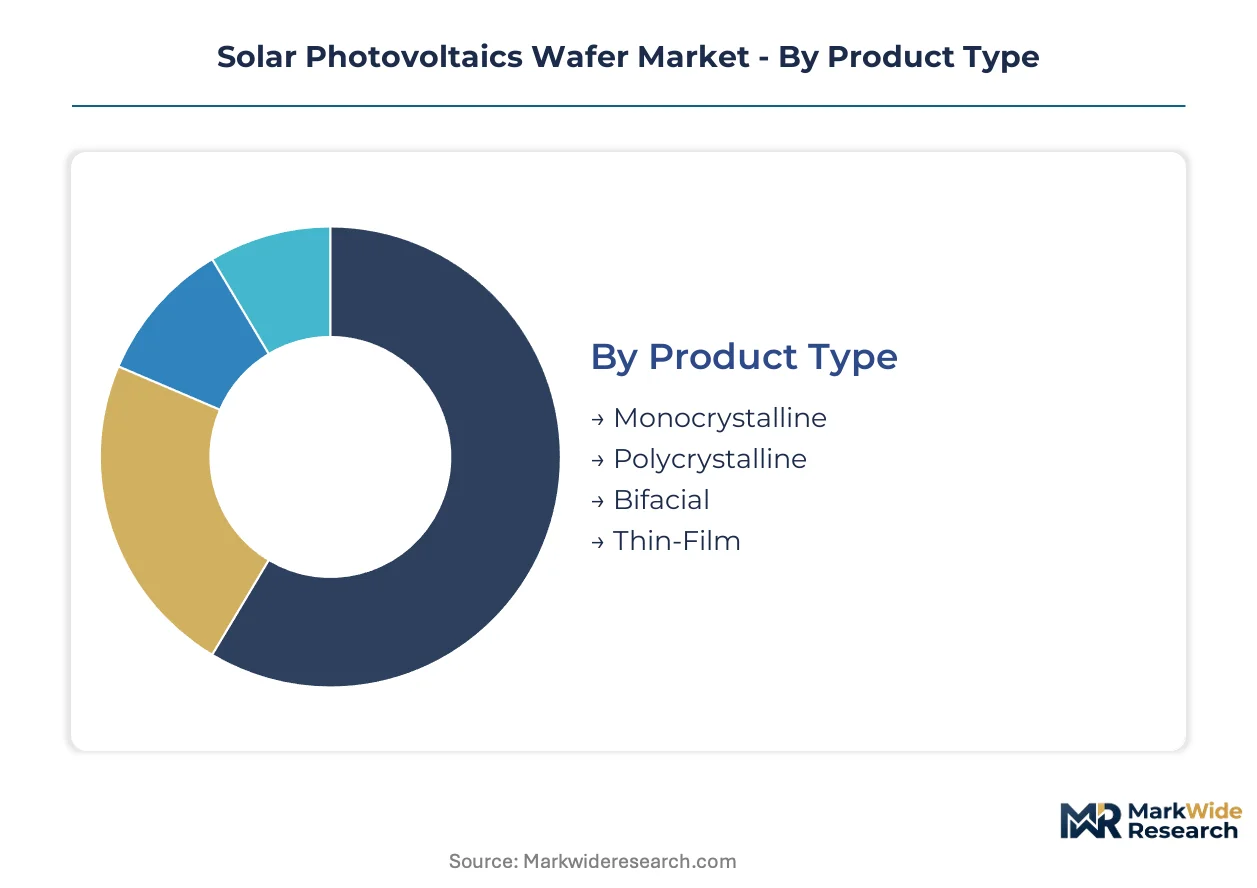
Product Type:
Inventory velocity varies dramatically across crystalline structures, with monocrystalline formats turning fastest as cell manufacturers accelerate n-type migration while polycrystalline stockpiles age in secondary channels.
- Monocrystalline:Single-crystal silicon ingots sliced via Czochralski growth deliver superior electron mobility and conversion efficiency above twenty-two percent. Utility-scale developers in Gujarat and Rajasthan specify these substrates exclusively under India's PLI-linked procurement mandates.
- Polycrystalline:Cast multicrystalline blocks offer lower capital intensity for ingot production but sacrifice efficiency margins. Southeast Asian export-oriented facilities continue absorbing depreciating polycrystalline capacity that China's MIIT efficiency standards have eliminated from domestic supply chains.
- Bifacial:Symmetrically processed wafers enable dual-sided photon capture with rear-side gains of ten to twenty percent. Albedo-dependent projects in Middle Eastern desert installations drive specification pull.
- Thin-Film:Cadmium telluride and copper indium gallium selenide substrates bypass silicon crystallization entirely. Niche applications in building-integrated configurations exploit flexible form factors.
Monocrystalline formats anchor the volume base while heterojunction-optimized n-type variants gain share at the steepest rate.
End User:
Customer scale determines specification tolerance, with residential buyers accepting broader efficiency bands than institutional purchasers whose procurement teams enforce tighter technical compliance.
- Residential:Distributed rooftop installations favor standardized module formats with balance-of-system cost minimization. German and Spanish feed-in tariff structures concentrate demand for premium efficiency wafers in owner-occupied housing segments.
- Commercial:Corporate power purchase agreements drive procurement of higher-wattage modules for rooftop and carport configurations. Tax equity financing structures in the US favor accelerated depreciation on larger-format installations.
- Industrial:Captive consumption models at manufacturing facilities prioritize levelized cost of electricity over upfront capital minimization. Tamil Nadu textile clusters exemplify this segment's procurement concentration.
- Utility:Centralized solar parks above fifty megawatts dominate absolute wafer consumption. China's state-owned power developers enforce 210mm format standardization across their procurement pipelines.
Utility buyers command the procurement volume while commercial distributed segments expand most quickly as corporate renewable targets harden.
Application:
Installation architecture dictates wafer geometry constraints, with ground-mounted configurations tolerating larger formats than weight-restricted rooftop assemblies.
- Solar Power Plants:Utility-scale ground-mounted arrays optimize for levelized cost through high-wattage bifacial modules. Rajasthan's Bhadla solar park exemplifies concentration in this application.
- Rooftop Solar:Distributed installations face structural load limits and shading complexity that favor smaller module formats. Southeast Asian urban centers remain undersupplied with appropriately dimensioned wafers for residential rooftops.
- Off-Grid Systems:Remote electrification projects prioritize reliability and temperature coefficient performance over absolute efficiency. African mini-grid developers source mixed crystalline formats based on local supply availability.
- Building Integrated:Façade and skylight applications demand customized dimensions and aesthetic uniformity. European architects specify these installations under EU Green Deal-linked building renovation mandates.
Solar power plants consume the dominant wafer volumes while building-integrated applications climb the fastest as building codes tighten energy performance standards.
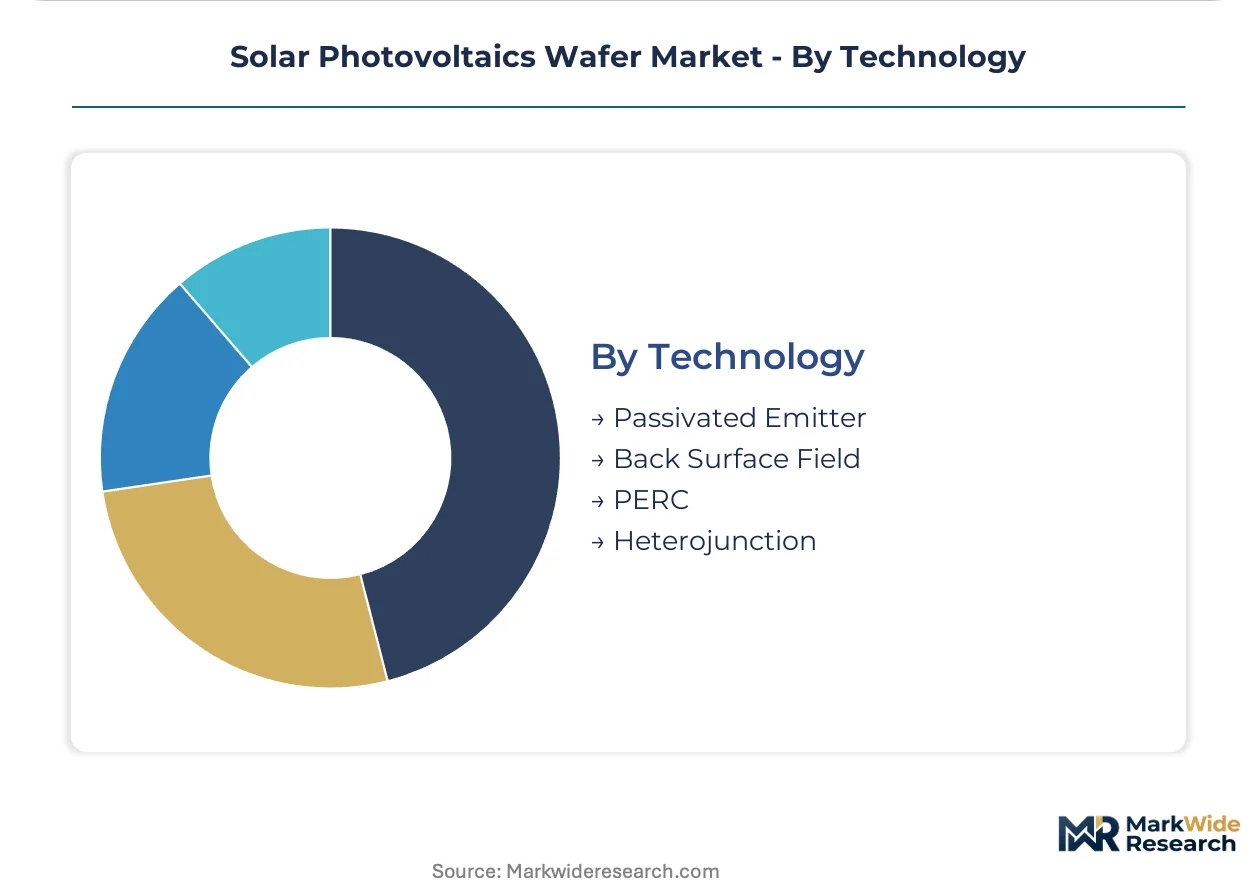
Technology:
Cell architecture roadmaps are fragmenting wafer specification requirements, with heterojunction demands diverging from legacy PERC compatibility in surface preparation and bulk resistivity.
- Passivated Emitter:Early-generation cell designs with limited surface passivation retain niche presence in cost-sensitive markets. Legacy Southeast Asian cell lines continue consuming compatible p-type wafers.
- Back Surface Field:Aluminum-doped rear contacts improve long-wavelength response in conventional cell structures. Declining deployment as PERC and advanced architectures displace this intermediate technology.
- PERC:Passivated emitter and rear contact technology dominates current installed capacity with mature supply chains and established wafer specifications. Chinese cell manufacturers maintain the largest PERC-compatible wafer procurement positions.
- Heterojunction:Amorphous silicon layers on crystalline substrates demand ultra-low oxygen content and specialized surface texturing. Japanese and European cell manufacturers are adopting these substrates fastest, compressing p-type obsolescence timelines.
PERC-compatible specifications retain the installed base while heterojunction requirements expand most steeply as efficiency roadmaps target twenty-five percent conversion thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme subsidies and China's MIIT efficiency mandates are restructuring procurement flows across major manufacturing clusters. Utility-scale developers in Gujarat and Rajasthan specify large-format monocrystalline wafers under production-linked incentive requirements. Germany's EU Green Deal-linked solar deployment targets pull high-efficiency n-type substrates into utility pipelines.
China
Domestic polysilicon-to-wafer capacity expansion accelerates under MIIT enforcement of updated GB standards mandating minimum cell efficiency ratings. The 23.5% threshold eliminates substandard polycrystalline production from state-supported supply chains. Xinjiang-based feedstock producers control critical volumes, creating geographic concentration for non-integrated manufacturers.
India
Gujarat and Tamil Nadu manufacturing clusters concentrate fresh cell and module capacity attracted by PLI scheme subsidies. BIS certification requirements create compliance barriers and testing delays for imported silicon substrates entering domestic fabrication facilities. Rajasthan's Bhadla solar park exemplifies utility-scale procurement standardization around premium large-format substrates.
Germany
EU Green Deal acceleration generates procurement pull for high-efficiency n-type substrates in utility pipelines. Feed-in tariff structures concentrate demand for premium efficiency wafers in owner-occupied residential housing segments. Industrial captive consumption models at manufacturing facilities prioritize levelized cost of electricity over upfront capital minimization.
Japan
Japanese cell manufacturers adopt heterojunction-optimized substrates fastest, compressing timelines for p-type capacity obsolescence. METI technology roadmaps dictate substrate specifications more aggressively than in prior cycles. Domestic polysilicon purification investments shift toward semiconductor-grade specifications previously reserved for electronic applications.
United States
Tax equity financing structures favor accelerated depreciation on larger-format commercial installations. Corporate power purchase agreements drive procurement of higher-wattage modules for rooftop and carport configurations. Distributed energy markets expand as state-level renewable portfolio standards harden corporate procurement mandates.
Solar Photovoltaics Wafer Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The vendor base organizes around three strategic archetypes: polysilicon-integrated wafer manufacturers, pure-play wafer specialists, and cell-integrated backward integrators. Consolidation pressure intensifies as GB standards and format standardization eliminate subscale participants. Dominant competitive moves include captive polysilicon supply commitments and 210mm-compatible furnace capacity expansion.
Among China-based integrated manufacturers, LONGi Green Energy Technology Co Ltd and TCL Zhonghuan Renewable Energy Technology Co Ltd exemplify the polysilicon-integrated archetype controlling feedstock costs across wafer operations. JA Solar occupies a position within the cell-integrated tier, anchoring competitive stance through high-volume manufacturing serving utility-scale developers. These three entities represent distinct strategic postures: backward integration into polysilicon, midstream wafer specialization with scale economics, and downstream cell integration with procurement leverage.
| Leading Market Players |
|---|
| LONGi Green Energy Technology Co Ltd |
| JA Solar |
| JinkoSolar |
| TCL Zhonghuan Renewable Energy Technology Co Ltd |
| GCL-Poly Energy Holdings Limited |
| Hanwha Q CELLS |
| CETC Solar Energy Holdings Co |
| Sino-American Silicon Products Inc |
| Canadian Solar |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Xinjiang polysilicon corridor drives aggressive spot pricing while forcing non-integrated wafer manufacturers into loss-leading contract positions to maintain furnace utilization. MIIT efficiency mandates compound this dynamic by eliminating substandard domestic capacity, concentrating pricing power among polysilicon-integrated incumbents who control both feedstock and wafer output.
Pricing Analysis
Wafer efficiency tier and GB standard compliance level create the primary spread between premium n-type monocrystalline and depreciating p-type polycrystalline formats. Three-tier pricing structure across heterojunction-optimized, PERC-compatible, and legacy polycrystalline levels reflects divergent technology roadmaps. Cost compression in standard-tier wafers intensifies as Chinese state-owned developers consolidate procurement around 210mm formats. Distributed rooftop installers in Southeast Asia exhibit highest price sensitivity, absorbing depreciating 166mm supply abandoned by utility-scale buyers.
Supply Chain Analysis
Export controls on semiconductor-grade polysilicon purification equipment limit technology transfer to emerging wafer manufacturers outside China. Supply concentrates in Xinjiang for polysilicon feedstock, Jiangsu and Zhejiang for crystal growing and slicing, and Malaysia and Vietnam for cell integration serving US tariff-exempt modules. The chain draws from metallurgical-grade silicon, high-purity trichlorosilane, and diamond wire consumables. Single-source vulnerability in Xinjiang-based feedstock creates geographic concentration risk. Distribution runs through long-term offtake contracts to state-owned power developers and module manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technology roadmap fragmentation across heterojunction, TOPCon, and perovskite-tandem architectures creates specialist niche opportunities for wafer manufacturers with precise specification capabilities. Corporate renewable procurement mandates and distributed solar acceleration generate demand heterogeneity that rewards agile substrate suppliers.
For Market Incumbents: Harden feedstock security through backward integration into polysilicon or captive supply agreements with Xinjiang-based producers. Accelerate 210mm-compatible furnace deployment ahead of format standardization lock-in by China's state-owned developers. MIIT efficiency threshold escalation threatens subscale PERC-compatible capacity, making n-type crystal growth expertise the critical defensive lever.
For New Entrants and Emerging Players: Southeast Asian distributed solar markets remain underpenetrated with appropriately dimensioned wafers for residential rooftop constraints. Target building-integrated photovoltaic applications in EU Green Deal-linked renovation pipelines where customized dimensions and aesthetic uniformity command specification premiums. Pursue technology licensing partnerships with Japanese heterojunction cell manufacturers seeking non-Chinese substrate supply.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because GB standard enforcement and format standardization eliminate subscale participants without captive polysilicon or n-type expertise. Acquisition targets should display semiconductor-grade purification capabilities and low-oxygen Czochralski operational experience. Monitor polysilicon spot price volatility as the inflection signal for margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Xinjiang feedstock concentration forces captive supply commitments to secure wafer margin stability. |
| 210mm Furnace Capacity Expansion | China's state-owned developers enforce format standardization that eliminates smaller diameter addressable markets. |
| Heterojunction-Optimized Wafer Development | Japanese and European cell manufacturers adopt ultra-low oxygen substrates fastest, compressing p-type obsolescence timelines. |
| Long-Term Offtake Agreements with IPPs | Project finance structures fragment procurement across smaller developers seeking supply certainty. |
| Technology Licensing for n-Type Crystal Growth | Skill scarcity in low-oxygen monocrystalline ingot production creates partnership leverage for experienced puller operators. |
Methodological Framework
A standing panel of wafer manufacturing executives, cell procurement managers at tier-one module suppliers, EPC contractors in Gujarat and Rajasthan, and polysilicon trading specialists provided ongoing calibration against market developments. Primary interviews with these stakeholders combined with secondary validation from MIIT GB standard filings, India BIS certification records, EU Green Deal implementation documents, and customs trade data. Bottom-up capacity utilization tracking and top-down demand projection from utility pipeline databases enabled triangulation.
Scenario bracketing around polysilicon supply disruption, n-type migration velocity, and tariff regime changes anchored the analytical framework across the projection horizon. Segmentation modeling incorporated crystalline structure, end-use scale, application architecture, and cell technology compatibility dimensions. CAGRs derived from installed capacity buildout trajectories and module efficiency roadmaps. Forecast inputs included furnace utilization rates, diamond wire slicing yield improvements, and albedo-dependent bifacial gain assumptions.
Practitioners should monitor MIIT efficiency threshold revisions, India PLI scheme allocation outcomes, and Xinjiang labor practice trade actions for early signals requiring forecast reassessment. Material shifts in heterojunction cell commercialization timelines or perovskite-tandem technology viability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar PV Module Market
Solar Power Systems
South America Solar Tracker Market
Solar Power Systems
AR Photovoltaic Glass Market
Solar Power Systems
Solar Microinverter and Power Optimizer Market
Solar Power Systems
Amorphous Silicon PV Market
Solar Power Systems
Solar System in Kuwait Market
Solar Power Systems
GCC Solar Water Heater Market
Solar Power Systems
Europe Solar Backsheet Market
Solar Power Systems
Polycrystalline Solar Panel Market
Solar Power Systems
Off-Grid Solar Lighting Market
Solar Power Systems
Asia-Pacific Distributed Solar Power Generation Market
Solar Power Systems
Hybrid Solar Panel Market
Solar Power Systems
APAC Solar Micro Inverters Market
Solar Power Systems
Bacteria Powered Solar Cell Market
Solar Power Systems
Denmark Solar Energy Market
Solar Power Systems
Solar Panels Frame Market