
 Beam Combining Optics Market | 2026-2036
Beam Combining Optics Market Size, Share, and Industry Trends Forecast 2026-2036
Beam Combining Optics Market Insights
Defense prime contractors is collapsing as the dominant buyer archetype for high-power beam combining systems, while semiconductor lithography toolmakers gain procurement share. Edmund Optics leverages its catalog distribution model to serve research institutions with standardized fiber couplers and beam splitters. CASIX Inc. anchors Chinese supply chains for nonlinear optical crystals used in frequency conversion stages. Cailabs specializes in waveguide-based spatial multiplexers that address telecommunications infrastructure buildouts.
Beam combining optics encompass precision elements that merge multiple laser beams into a single output with controlled phase, polarization, and intensity profiles, typically manufactured from fused silica, BK7 glass, or nonlinear crystals with lambda-tenth surface flatness specifications. These components enable power scaling beyond single-emitter limits for materials processing, directed energy, and optical communications systems. Optical assemblies command premium positioning due to their integration complexity and alignment sensitivity, while waveguide technology segments show accelerated development activity as planar lightwave circuits mature for datacenter interconnects. Free-space optics retains dominance in military and industrial applications where power handling and thermal resilience outweigh packaging density requirements.
ITAR regulations in the United States restrict beam combining hardware exports for power levels exceeding specified thresholds, compelling non-U.S. buyers to develop indigenous sourcing or seek ITAR-free alternatives. The EU AI Act and emerging dual-use export controls under the EU Green Deal framework increasingly classify high-power laser systems as strategic technologies subject to licensing review. ISO 10110 optical drawing standards and MIL-PRF-13830B surface quality specifications govern acceptance criteria across defense and medical device supply chains. Stakeholders must monitor regulatory fragmentation between U.S., European, and Asian export control regimes when configuring multi-source manufacturing strategies.
Market Dynamics
Coherent beam combining architectures are displacing incoherent power scaling methods in directed-energy systems, forcing suppliers to requalify for phase-locked array contracts while legacy single-beam optics face procurement compression.
Growth Catalysts
- Semiconductor lithography tool refresh cycles:EUV power scaling requirements at 600W and beyond are mandating multi-beam architectures for wafer throughput, pulling precision combiner demand from ASML's supply base in Germany and the Netherlands.
- ITAR threshold escalation:The U.S. State Department's revised Category XV controls are accelerating indigenous development programs in France, Israel, and South Korea for ITAR-free coherent combining hardware.
- Fused silica thermal resilience advances:Improved zero-thermal-expansion substrates from Heraeus and Corning are enabling 100kW-class continuous-wave operation in materials processing systems.
Market Restraints
- Nonlinear crystal supply concentration:BBO and LBO crystal growth capacity concentrates in Fujian province, creating single-source vulnerability for frequency conversion stages in ultraviolet beam combining chains.
- Lambda-tenth surface metrology capex:Sub-nanometer interferometry equipment for flatness verification requires capital outlays exceeding standard optical shop floor economics, excluding mid-tier fabricators from defense qualification.
- REACH substance restrictions:ECHA candidate list additions for lead-containing optical glasses are forcing reformulation of traditional crown-flint achromats used in visible combining architectures.
Strategic Opportunities
- Datacenter interconnect buildouts:Spatial multiplexers for CPO (co-packaged optics) architectures represent unaddressed volume demand as hyperscalers deploy 51.2T switch generations requiring multi-fiber beam combination.
- India PLI scheme for photonics:The Ministry of Electronics and Information Technology's production-linked incentive for optical components is attracting module assembly investment that could extend to combiner sourcing localization.
- Free-space-to-waveguide hybrid integration:Convergence of bulk optic power handling with PLC packaging density opens packaging architectures for industrial fiber laser systems previously locked into pure free-space designs.
Industry Challenges
- Active phase control firmware integration:Combining system vendors must embed real-time piston correction algorithms, requiring software competencies foreign to traditional passive optics manufacturers.
- MIL-PRF-13830B inspection bottleneck:Scratch-dig qualification to 40-20 or 20-10 specifications creates throughput constraints at defense-tier coating houses, extending lead times for qualified combiner deliveries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beam Combining Optics Market |
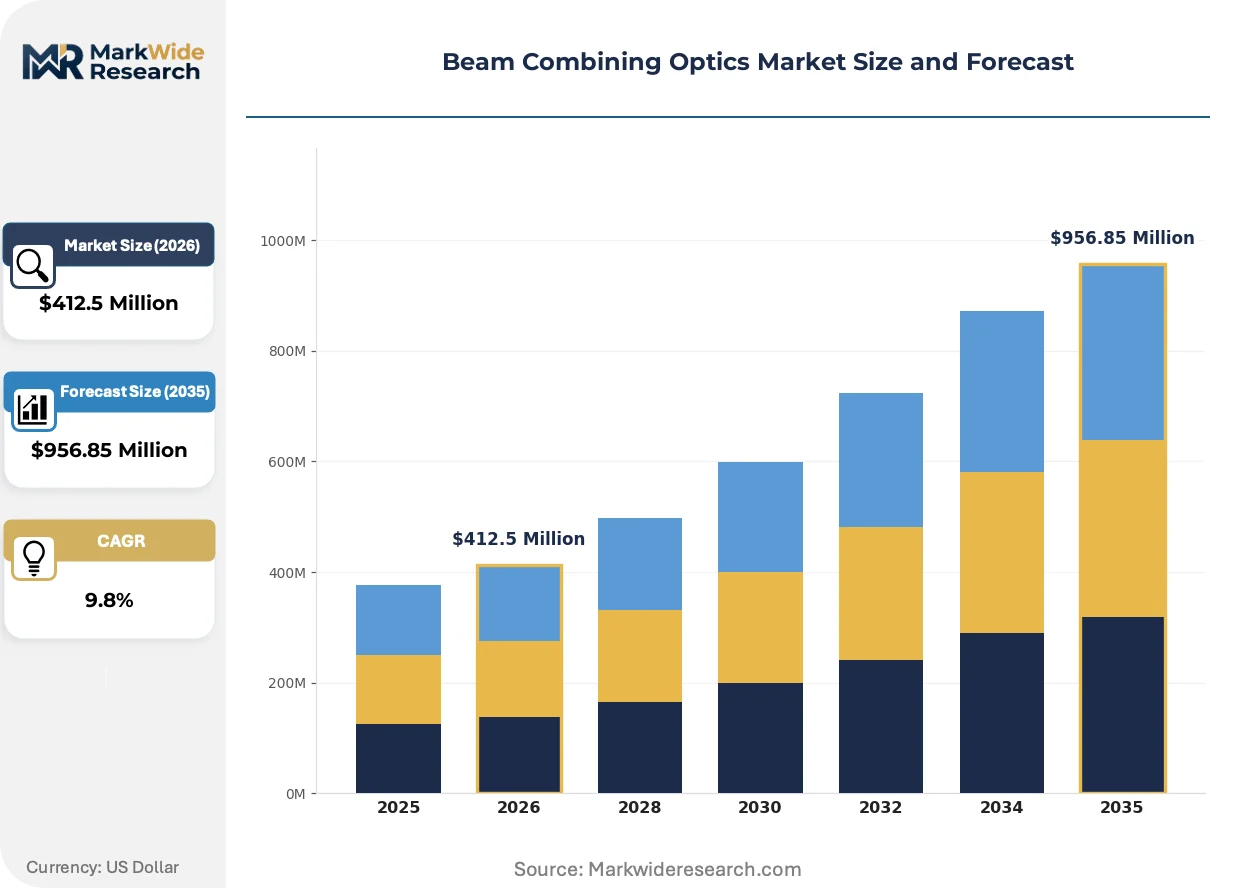
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $956.85 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Couplers, Beam Splitters, Optical Assemblies, Laser Combiners Technology: Free-Space Optics, Waveguide Technology, Spatial Filtering, Nonlinear Optics Application: Telecommunications, Medical Devices, Industrial Equipment, Military Systems End User: Aerospace, Healthcare, Electronics, Research Institutions |
| Companies Covered | OPTOMAN, Edmund Optics, EKSMA Optics, Cailabs, PowerPhotonic Ltd., CASIX Inc., Civan Lasers, Hind High Vacuum Company Pvt Ltd., LightComm Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beam Combining Optics Market Trends and Innovations
Photonic integration roadmaps are compressing the boundary between free-space and waveguide combining architectures, forcing suppliers to place parallel bets on bulk optic refinement and planar lightwave circuit scaling.
Waveguide-based spatial multiplexers are bifurcating the telecommunications infrastructure segment from military and industrial applications. Cailabs and similar specialists are shipping multi-plane light conversion modules to datacenter interconnect programs in France and Japan. The technology is bifurcating procurement specifications, with telecom buyers prioritizing insertion loss and channel count while defense programs emphasize power handling and radiation hardness.
The EU AI Act's classification of high-power laser systems as dual-use technologies subject to export licensing review is tightening supplier qualification documentation. German optics houses in Jena and Oberkochen are restructuring customer-facing technical data packages to satisfy emerging EU Green Deal framework disclosure requirements. Semiconductor lithography toolmakers with EUV programs are most affected, as beam combining subsystems now trigger strategic technology review thresholds previously reserved for complete laser sources.
Defense prime contractors are consolidating vendor panels for coherent combining arrays, compressing qualification cycles from multi-year development agreements to 18-month performance-gate contracts. The U.S. Army's Rapid Capabilities and Critical Technologies Office and similar procurement units in the UK and Australia are driving this compression. Materials processing OEMs in Germany and Japan retain longer development timelines, creating a two-speed supplier engagement model that strains engineering resource allocation.
Beam Combining Optics Market Segmentation
Beam combining optics procurement channels diverge sharply by performance tier and regulatory sensitivity. Defense integrators source through qualified vendor panels with ITAR compliance, while semiconductor toolmakers and datacenter operators leverage catalog distributors for standardized components.
Product Type:
Catalog distributors like Edmund Optics move high-volume fiber couplers and beam splitters to research institutions and industrial OEMs, while optical assemblies and laser combiners flow through direct sales channels to defense primes and lithography toolmakers.
- Optical Assemblies:Integrated multi-element systems requiring active alignment and hermetic sealing for phase-locked array applications. Defense primes in the United States and Germany concentrate procurement here, constrained by MIL-PRF-13830B surface quality bottlenecks at qualified coating houses.
- Fiber Couplers:Precision fused components merging multiple fiber inputs with controlled mode-field overlap. Semiconductor lithography supply chains in Germany's Jena cluster and the Netherlands pull volume for EUV power scaling architectures.
- Beam Splitters:Dielectric-coated substrates dividing optical power with polarization or wavelength selectivity.
- Laser Combiners:Multi-beam integration modules for power scaling beyond single-emitter limits.
By volume, fiber couplers lead. By growth pace, optical assemblies are climbing the fastest.
Technology:
Cost tiers separate mature free-space architectures from emerging waveguide platforms, with spatial filtering and nonlinear optics occupying intermediate price-performance positions.
- Free-Space Optics:Bulk crystal and glass elements handling kilowatt-class continuous-wave loads with lambda-tenth surface specifications. Military directed-energy programs in the United States, United Kingdom, and Australia anchor demand, though REACH substance restrictions on lead-containing glasses force crown-flint achromat reformulation.
- Waveguide Technology:Planar lightwave circuits and multi-plane light conversion modules enabling datacenter interconnect density. Cailabs in France and Japanese specialists ship spatial multiplexers to telecommunications infrastructure buildouts, with insertion loss and channel count driving procurement specifications distinct from defense requirements.
- Spatial Filtering:Aperture and mode-matching techniques for beam quality control in precision applications.
- Nonlinear Optics:Frequency conversion crystals for ultraviolet and visible beam combining chains.
Free-space optics retains revenue dominance. Waveguide technology shows steepest expansion trajectory.
Application:
Customer type determines margin structure, with military systems commanding premium pricing for ITAR-compliant hardware and medical devices requiring ISO 13485 traceability.
- Military Systems:Coherent beam combining arrays for directed-energy weapons and counter-UAS applications. The U.S. Army's Rapid Capabilities and Critical Technologies Office compresses vendor qualification cycles to 18-month performance-gate contracts, while France, Israel, and South Korea accelerate indigenous ITAR-free development.
- Telecommunications:Spatial multiplexers for CPO architectures and 51.2T switch generation deployment. Hyperscalers in Japan and France drive unaddressed volume demand as planar lightwave circuits mature for multi-fiber beam combination.
- Industrial Equipment:Materials processing systems requiring 100kW-class continuous-wave operation.
- Medical Devices:Precision combiners for surgical and diagnostic laser systems with stringent biocompatibility requirements.
Military systems generate highest average selling prices. Telecommunications infrastructure is expanding most quickly.
End User:
Supply concentration varies by end-user sophistication, with aerospace and electronics demanding captive supply relationships while research institutions accept catalog distribution.
- Electronics:Semiconductor lithography toolmakers and photonics module assemblers requiring sub-nanometer interferometry verification. ASML's supply base in Germany and the Netherlands pulls precision combiner demand, with EU AI Act dual-use classifications triggering strategic technology review for beam combining subsystems.
- Aerospace:Satellite and directed-energy platforms requiring radiation-hardened and thermally resilient optics. India's PLI scheme for photonics is attracting module assembly investment that could extend to localized combiner sourcing.
- Healthcare:Hospital systems and device manufacturers with ISO 10110 optical drawing compliance requirements.
- Research Institutions:Universities and national laboratories sourcing standardized components through catalog channels.
Electronics commands procurement volume. Aerospace shows fastest share gain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision optics clusters export beam combining hardware to semiconductor lithography toolmakers in the Netherlands and defense integrators across NATO member states, establishing the dominant trade-flow corridor in this technology segment.
United States
Directed-energy weapons programs and counter-UAS applications pull coherent beam combining arrays from qualified vendor panels. ITAR Category XV controls administered by the State Department restrict exports above specified power thresholds, compelling domestic sourcing for military systems. The Rapid Capabilities and Critical Technologies Office compresses vendor qualification cycles to 18-month performance-gate contracts, concentrating procurement around established defense optics suppliers in Arizona and Florida.
Germany
EUV lithography power scaling at 600W-plus mandates multi-beam architectures from ASML's supply base. ECHA REACH restrictions on lead-containing optical glasses force reformulation of traditional crown-flint achromats. The precision optics cluster around Jena and Oberkochen anchors specialized supply chains where Zeiss and Schott coordinate substrate and coating capabilities for defense and semiconductor customers.
China
Indigenous development programs accelerate for ITAR-free coherent combining hardware as export controls tighten elsewhere. MIIT production standards govern optical component qualification for domestic military and telecommunications applications. Fujian province concentrates BBO and LBO crystal growth capacity, creating single-source vulnerability for frequency conversion stages that module assemblers in Shenzhen and Shanghai must navigate.
France
Telecommunications infrastructure buildouts drive spatial multiplexer procurement for CPO architectures and 51.2T switch deployments. The EU AI Act classification of high-power laser systems as dual-use technologies triggers strategic technology review thresholds for beam combining subsystems. Cailabs in Paris ships multi-plane light conversion modules to datacenter interconnect programs, anchoring waveguide-based spatial multiplexing capabilities.
India
The Ministry of Electronics and Information Technology's production-linked incentive scheme for photonics attracts module assembly investment that could extend to localized combiner sourcing. BIS standards compliance requirements shape qualification protocols for defense and telecommunications procurement. Bangalore and Hyderabad clusters host emerging photonics assembly operations serving domestic aerospace programs and export markets in Southeast Asia.
Beam Combining Optics Market Competitive Landscape
Player mix skews toward defense-qualified precision optics houses and catalog distributors serving research institutions, with emerging waveguide specialists capturing telecommunications infrastructure contracts. Consolidation pressure concentrates around coherent beam combining arrays where qualification timelines and ITAR compliance create defensive moats. Three archetypes dominate: vertically integrated substrate-to-coating operations, catalog distributors with standardized component libraries, and waveguide technology specialists. Competitive moves center on strategic partnerships for phase-locked array development and capacity expansion in zero-thermal-expansion fused silica substrates.
Among catalog distributors, Edmund Optics occupies a position exemplifying high-volume standardized component supply to research institutions and industrial OEMs. Cailabs represents the waveguide specialist archetype, anchoring spatial multiplexer capabilities for telecommunications applications. CASIX Inc. sits within the nonlinear crystal supplier tier, occupying a position tied to frequency conversion stage supply chains. These three named entities illustrate the segmentation between distribution-led, waveguide-technology, and materials-specialist competitive vectors without exhausting the vendor landscape.
| Leading Market Players |
|---|
| OPTOMAN |
| Edmund Optics |
| EKSMA Optics |
| Cailabs |
| PowerPhotonic Ltd. |
| CASIX Inc. |
| Civan Lasers |
| Hind High Vacuum Company Pvt Ltd. |
| LightComm Technology |
| Others |
Pricing and Supply Chain Analysis
Zero-thermal-expansion fused silica substitution for conventional BK7 substrates simultaneously shifts procurement gravity toward Heraeus and Corning supply chains while compressing margin structures for mid-tier fabricators unable to absorb lambda-tenth metrology capex. This materials transition concentrates pricing power with substrate specialists capable of 100kW-class thermal resilience certification.
Pricing Analysis
Free-space-to-waveguide technology-generation pricing gaps separate legacy bulk-optic architectures from emerging planar lightwave circuit platforms, with hybrid integration commanding intermediate premiums. Three-tier pricing structure across ITAR-compliant defense-grade, ISO-certified industrial-grade, and catalog-standard research-grade levels stratifies procurement channels. Cost compression in visible achromat segments intensifies because ECHA REACH restrictions on lead-containing glasses force crown-flint reformulation R&D absorption. Semiconductor lithography toolmakers exhibit lowest price sensitivity due to EUV power scaling mandates, while research institutions sourcing through Edmund Optics catalog channels face highest budget constraints.
Supply Chain Analysis
Germany and China anchor beam combining optics manufacturing, with Jena-Oberkochen clusters supplying defense-qualified assemblies and Fujian province concentrating BBO and LBO crystal growth for frequency conversion stages. Raw material dependencies rest on Heraeus fused silica ingots, Schott optical glass formulations, and Fujian nonlinear crystal substrates. Single-source vulnerability in Fujian crystal capacity creates supply chain risk for ultraviolet beam combining chains. Distribution runs through qualified vendor panels for defense primes, direct sales for lithography toolmakers, and catalog channels for research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photonic integration roadmaps are triggering platform-economics inflection as waveguide-based spatial multiplexers interoperate with co-packaged optics ecosystems, collapsing traditional boundaries between bulk-optic and planar lightwave circuit procurement specifications.
For Market Incumbents: Shield MIL-PRF-13830B-qualified coating capacity through captive investment or exclusive offtake agreements with Arizona and Florida defense-tier houses, as 18-month vendor qualification compression by the U.S. Army's Rapid Capabilities and Critical Technologies Office erodes multi-year contract moats. Deepen backward integration into zero-thermal-expansion fused silica substrate production to secure thermal resilience certification for 100kW-class directed-energy programs.
For New Entrants and Emerging Players: BIS fast-track certification for India's PLI scheme photonics module assemblers offers lowest barrier to defense and telecommunications procurement qualification. Target datacenter interconnect spatial multiplexer demand from hyperscaler CPO deployments as the most penetrable segment, leveraging insertion loss specifications distinct from defense power-handling requirements. Pursue joint development agreements with Cailabs-class waveguide specialists for technology transfer into industrial fiber laser hybrid architectures.
For Investors and Strategic Acquirers: The market sits at a qualification-timeline compression phase that favors vertically integrated substrate-to-coating operations with existing ITAR infrastructure. Long-term viability over the next decade hinges on regulatory compliance scalability across fragmented U.S., EU, and Asian export control regimes. Acquisition focus should center on German precision optics houses in Jena and Oberkochen with ASML supply base relationships. Watch for EU AI Act dual-use classification enforcement against semiconductor lithography beam combining subsystems as inflection indicator for strategic technology review expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| ITAR-Free Hardware Development | France, Israel, and South Korea indigenous programs reduce U.S. export control dependency for coherent combining arrays. |
| Waveguide Technology Acquisition | Cailabs-class spatial multiplexer capabilities capture hyperscaler datacenter interconnect procurement. |
| Zero-Thermal-Expansion Substrate Capacity Expansion | Heraeus and Corning supply relationships secure 100kW-class materials processing system qualification. |
| REACH-Compliant Glass Reformulation | ECHA substance restriction compliance preserves visible achromat market access for crown-flint architectures. |
| PLI Scheme Module Assembly Investment | India Ministry of Electronics and Information Technology incentives localize combiner sourcing for Southeast Asia export markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs records, and industry technical standards, with inputs drawn from defense systems integrators, semiconductor lithography procurement leads, precision optics coating house operations managers, and telecommunications infrastructure engineers. Secondary validation sources include ITAR Category XV control amendments, ECHA REACH candidate list updates, EU AI Act dual-use classifications, ISO 10110 optical drawing standards, and MIL-PRF-13830B surface quality specifications. Bottom-up demand modeling from end-use application segments triangulates against top-down supply capacity assessments across German, U.S., and Chinese manufacturing clusters.
Segmentation dimensions modeled span product type, technology platform, application vertical, and end-user sophistication tier, with additional granularity on regulatory compliance intensity across defense, semiconductor, and telecommunications procurement channels. Value projections across the analysis window derive from volume forecasts multiplied by segment-specific average selling prices, with CAGR trajectories anchored in EUV power scaling roadmaps, directed-energy weapons program funding disclosures, and hyperscaler co-packaged optics deployment timelines. Industry-specific forecast inputs include ASML lithography tool refresh cycles and U.S. Army Rapid Capabilities and Critical Technologies Office vendor panel consolidation patterns.
Underlying assumptions cover sustained ITAR threshold escalation, EU dual-use export control harmonization, and fused silica thermal resilience advancement, with deviation risk concentrated in nonlinear crystal supply disruption from Fujian province concentration and REACH substance restriction timeline acceleration. Recalibration cycles align with material shifts in export control regime enforcement, semiconductor lithography power scaling milestones, and datacenter interconnect generation transitions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Fiber Optics Market
Optics
Photonics Market
Optics
Camera Module Lens Market
Optics
MEMS Mirrors Market
Optics
Photonics Sensor Market
Optics
Middle East and Africa Optical Imaging Market
Optics
Europe Laser Interferometer Market
Optics
Optical Fiber Raw Material Market
Optics
Global Nanophotonics Market
Optics
Interchangeable Lens Market
Optics
Optical Sensing Market
Optics
Anomaloscope Market
Optics
Excimer Laser Market
Optics
Optical Fiber Market
Optics
Optical Wavelength Service Market
Optics
Polymeric Optical Fiber Market