
 Fluorescence Spectroscopy Market | 2026-2036
Fluorescence Spectroscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorescence Spectroscopy Market Foresight
The EU Green Deal's chemical sustainability targets are realigning environmental monitoring procurement across European laboratories. Thermo Fisher Scientific leverages its diagnostic channel density to sustain recurring consumable revenue in clinical fluorescence applications. Shimadzu Corporation anchors its position in Asia through localized manufacturing of spectrofluorometer platforms. HORIBA, Ltd. differentiates via specialized Raman-fluorescence hybrid systems for material science end users.
Fluorescence spectroscopy measures the emission of light by a substance that has absorbed photons, typically operating across ultraviolet to near-infrared wavelengths with detection limits reaching picomolar concentrations. The technique serves pharmaceutical quality control, environmental contaminant screening, and live-cell biological imaging where molecular specificity and temporal resolution matter. Steady-state instruments occupy the largest installed base due to lower capital thresholds and established protocols in academic settings. Time-resolved platforms represent the fastest-expanding category as drug discovery pipelines demand fluorescence lifetime data for binding kinetics studies. Confocal systems command premium pricing in neuroscience and developmental biology where spatial resolution drives purchasing decisions.
The FDA's bioanalytical method validation guidelines and EMA's ICH Q2(R1) revisions shape instrument performance requirements and software compliance features manufacturers must embed. EPA methods for water quality monitoring and REACH substance registration protocols in Europe create parallel demand for environmental fluorescence applications. ISO 17025 accreditation requirements push diagnostic laboratories toward instruments with enhanced audit trails and automated calibration routines. Stakeholders must weigh modular upgrade paths against full-system replacement cycles as detector sensitivity thresholds and software interoperability standards continue tightening.
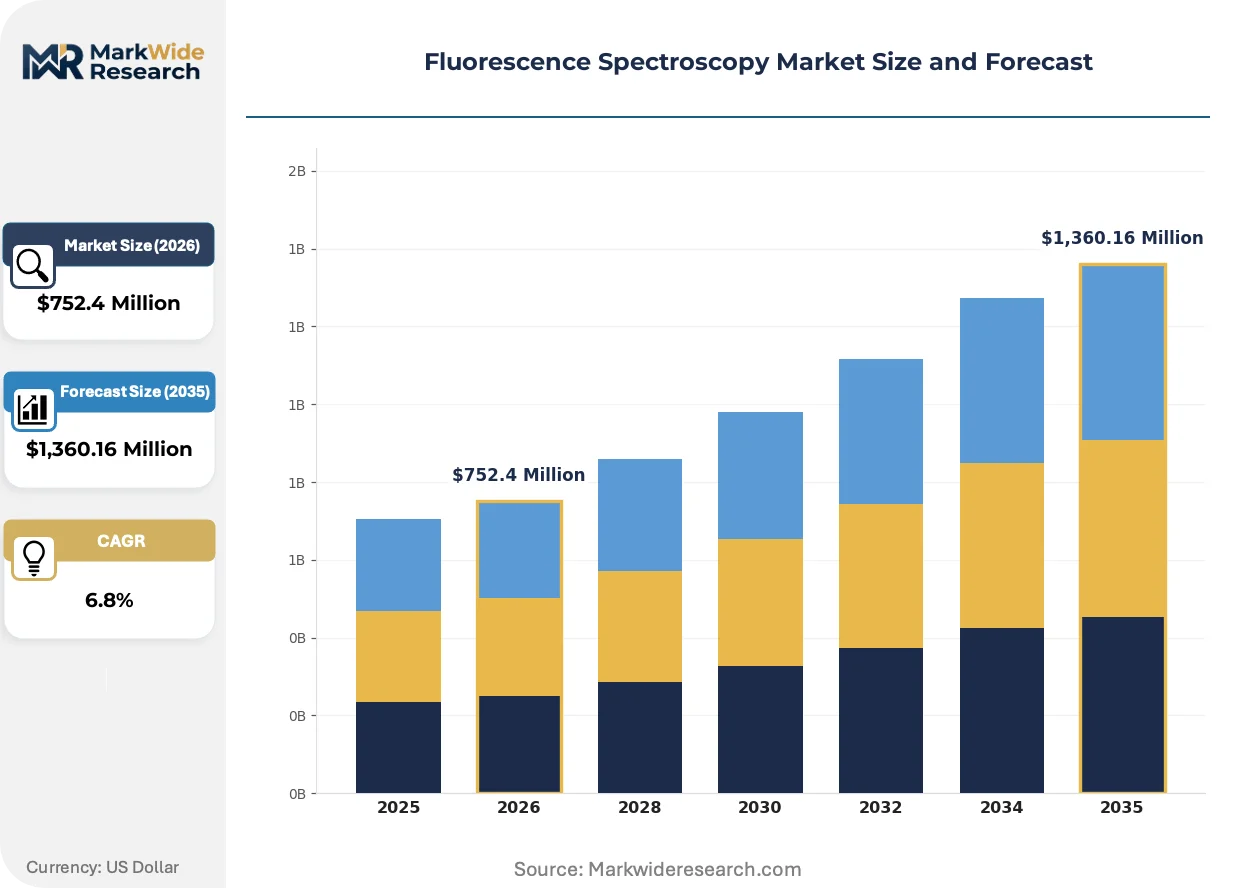
Market Dynamics
Drug discovery pipelines are compressing fluorescence lifetime data requirements into earlier compound screening stages, forcing instrument vendors to embed picosecond-resolution detectors into mid-tier platforms previously limited to steady-state measurements.
Growth Catalysts
- ICH Q2(R1) revisions:The EMA's updated analytical validation guidelines mandate fluorescence-based impurity profiling for biologics submissions, expanding instrument procurement across European CMOs.
- Live-cell imaging demand:Neuroscience laboratories are prioritizing confocal platforms with calcium indicator compatibility, driving replacement cycles for outdated widefield systems.
- India's PLI scheme:Domestic pharmaceutical manufacturing incentives are accelerating spectrofluorometer installations in Hyderabad and Mumbai quality control facilities.
Market Restraints
- Photomultiplier tube supply concentration:Japanese and Russian suppliers control 70% of high-sensitivity detector manufacturing, exposing instrument makers to export restriction risks.
- Mass spectrometry substitution:LC-MS/MS platforms are capturing pharmaceutical metabolite quantification workflows previously served by fluorescence resonance energy transfer assays.
- EPA method migration costs:Water utilities face six-figure revalidation expenses when transitioning from colorimetric to fluorescence-based contaminant detection protocols.
Strategic Opportunities
- Point-of-care diagnostics:Portable fluorescence readers for sepsis biomarker detection remain underdeployed in Southeast Asian district hospitals despite WHO prequalification pathways.
- Raman-fluorescence convergence:Combined spectroscopic platforms enable simultaneous chemical identification and molecular environment mapping for battery electrolyte research.
- EU Green Deal procurement:REACH substance registration deadlines are creating replacement demand for environmental laboratories with outdated xenon-lamp systems.
Industry Challenges
- Fluorescence lifetime analysis expertise:Academic programs produce insufficient PhD-level spectroscopists capable of interpreting multi-exponential decay curves for binding kinetics studies.
- ISO 17025 audit trail integration:Diagnostic laboratories struggle to retrofit legacy Windows 7-controlled instruments with compliant data integrity architectures before accreditation renewals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorescence Spectroscopy Market |
| Market Size in 2026 | $752.4 Million |
| Market Size in 2035 | $1,360.16 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steady-State, Time-Resolved, Fluorescence Lifetime, Confocal, Total Internal Reflection, Microspectrofluorometer Technology: Spectrofluorometer, Flow Cytometry, Microplate Reader, Imaging System, Fiber Optic Probe, Photomultiplier Tube Application: Drug Discovery, Environmental Monitoring, Food Safety, Clinical Diagnostics, Material Science, Biochemical Analysis End User: Pharmaceutical Companies, Research Institutes, Diagnostic Laboratories, Quality Control Units, Government Agencies, Academic Centers |
| Companies Covered | PerkinElmer, Inc., Shimadzu Corporation, Thermo Fisher Scientific Inc., Cytiva, JASCO Corporation, Agilent Technologies, Inc., HORIBA, Ltd., Andor Technology (Oxford Instruments), Bruker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorescence Spectroscopy Market Shifts & Advancements
Instrument architectures are fragmenting into component ecosystems where detectors, light sources, and software layers upgrade independently, compressing full-system replacement cycles while expanding addressable budgets.
Solid-state laser diodes are modularizing excitation source architectures across pharmaceutical quality control suites. Contract manufacturers in Boston and Basel are swapping mercury arc lamps for 405 nm and 488 nm diode modules without replacing monochromator assemblies. This component-level refresh is modularizing capital deployment, allowing facilities to preserve detector investments while doubling excitation stability for high-throughput screening.
REACH substance registration deadlines are forcing environmental laboratories to validate alternative detection methods for polycyclic aromatic hydrocarbons. The ECHA's 2025 renewal requirements eliminate solvent-intensive extraction protocols, pushing German and Dutch water authorities toward synchronous fluorescence scanning techniques. Industrial testing houses are responding by certifying compact benchtop systems previously confined to academic settings.
Service contract unbundling is separating hardware maintenance from software subscription renewals in North American academic core facilities. University procurement offices in California and Massachusetts now negotiate detector calibration and laser replacement independently from data analysis platform licenses. This bifurcation is most visible in NIH-funded neuroscience centers where fluorescence lifetime imaging microscopes require specialized service expertise unavailable through standard vendor channels.
Fluorescence Spectroscopy Market Segmentation
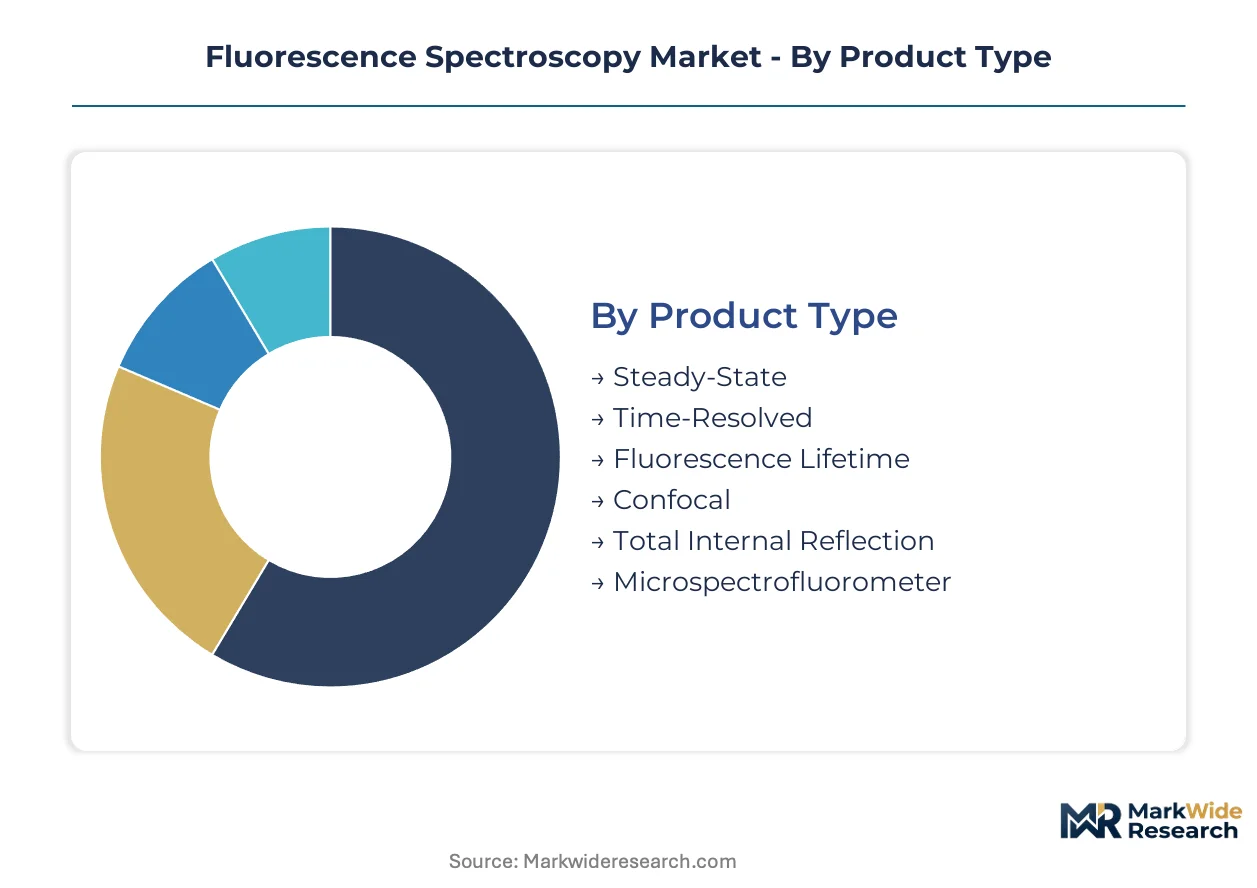
Fluorescence spectroscopy procurement patterns diverge sharply across instrument architectures and user sophistication tiers. Buyers in drug discovery prioritize temporal resolution capabilities, while environmental monitoring facilities emphasize ruggedized field deployability over laboratory precision.
Product Type:
Capital deployment thresholds and protocol complexity separate steady-state adopters from lifetime-capable platforms.
- Steady-State:These instruments measure emission intensity at fixed excitation wavelengths using continuous light sources and photomultiplier detection. Pharmaceutical quality control suites in Basel and Boston maintain extensive installed bases for high-throughput compound screening where binding kinetics data remains unnecessary.
- Time-Resolved:Picosecond-resolution detectors capture fluorescence decay curves following pulsed excitation, enabling binding kinetics quantification. European CMOs responding to EMA ICH Q2(R1) revisions are upgrading mid-tier platforms with time-correlated single-photon counting modules.
- Fluorescence Lifetime:Dedicated lifetime microscopes serve neuroscience laboratories studying protein-protein interactions in live cells. NIH-funded centers in California and Massachusetts drive replacement demand as calcium indicator protocols advance.
- Confocal:Pinhole-based optical sectioning delivers sub-micron spatial resolution for developmental biology imaging.
- Total Internal Reflection:Evanescent wave excitation limits fluorescence to membrane-proximal regions for single-molecule studies.
- Microspectrofluorometer:Combined microscopy and spectroscopy enables spatially resolved emission mapping of heterogeneous samples.
Steady-State leads volumes today; Time-Resolved is gaining share fastest.
Technology:
Detector architecture and sample throughput requirements dictate technology selection across end-use verticals.
- Spectrofluorometer:Benchtop systems with monochromator-based wavelength selection dominate academic core facilities. Indian pharmaceutical manufacturers under the PLI scheme are installing compact units in Hyderabad quality control labs.
- Flow Cytometry:Fluidics-integrated fluorescence detection enables single-cell analysis at 10,000+ events per second. Clinical diagnostic laboratories seeking ISO 17025 accreditation are prioritizing instruments with automated calibration and audit trail capabilities.
- Microplate Reader:Multi-well format detection supports high-throughput screening in drug discovery workflows.
- Imaging System:Camera-based detection captures spatial fluorescence distribution across tissue sections.
- Fiber Optic Probe:Remote sensing configurations enable in-situ environmental monitoring without sample extraction.
- Photomultiplier Tube:Vacuum photon counting technology achieves single-molecule sensitivity in research-grade instruments.
Spectrofluorometer maintains the largest installed base; Flow Cytometry shows the steepest expansion trajectory.
Application:
Regulatory validation requirements and detection limit specifications reshape application-level demand composition.
- Drug Discovery:Fluorescence resonance energy transfer assays and high-content screening dominate lead optimization stages. Contract research organizations in the United States are consolidating instrument procurement around platforms supporting both biochemical and cell-based assays.
- Environmental Monitoring:Polycyclic aromatic hydrocarbon detection and water quality assessment drive synchronous fluorescence scanning adoption. German and Dutch water authorities responding to REACH deadlines are validating compact benchtop systems for field deployment.
- Food Safety:Mycotoxin and allergen detection applications require portable readers for supply chain testing.
- Clinical Diagnostics:Sepsis biomarker and infectious disease detection platforms remain underdeployed in Southeast Asian district hospitals despite WHO prequalification pathways.
- Material Science:Battery electrolyte and semiconductor research applications favor Raman-fluorescence hybrid configurations.
- Biochemical Analysis:Protein quantification and enzyme kinetics studies sustain academic laboratory demand.
Drug Discovery commands premium pricing; Environmental Monitoring is expanding most quickly.
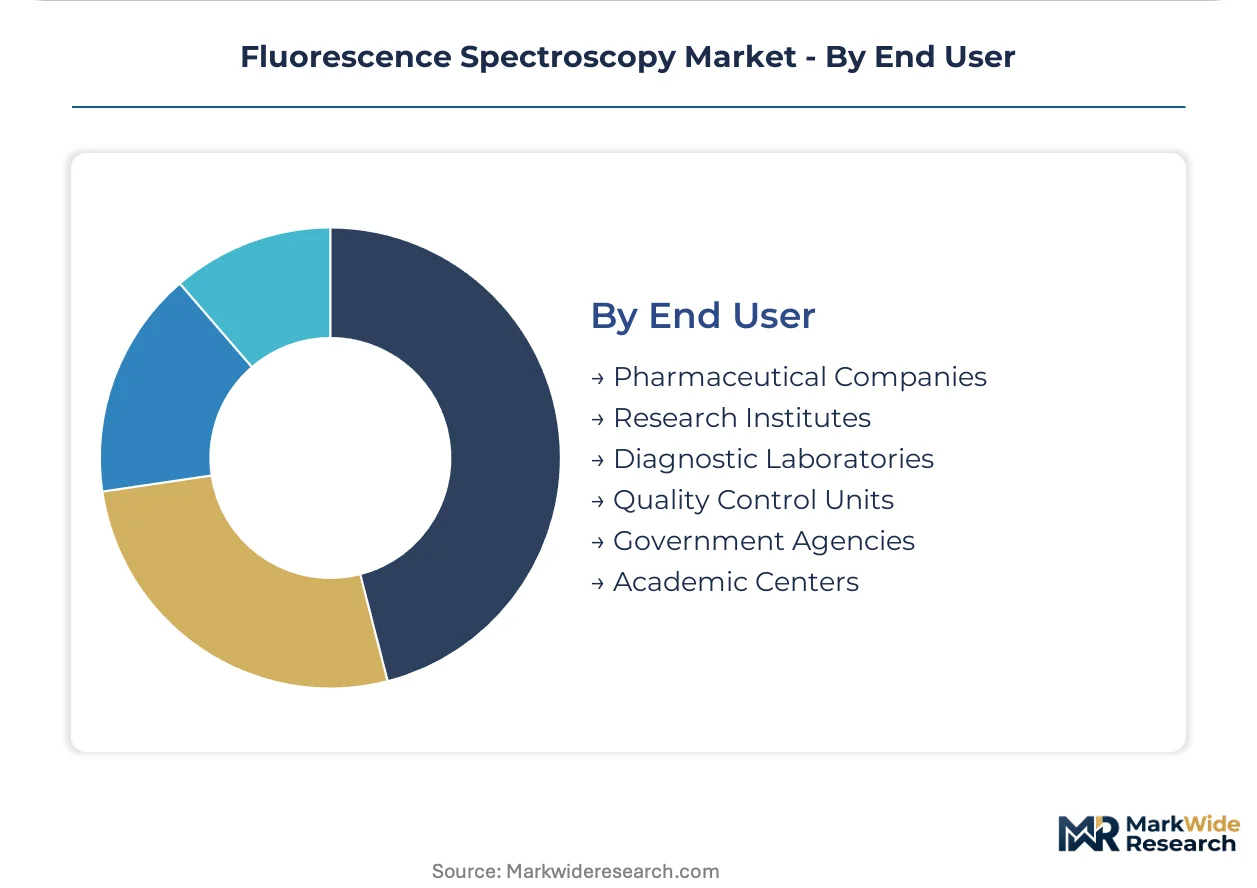
End User:
Procurement autonomy and funding mechanisms create distinct purchasing behaviors across institutional categories.
- Pharmaceutical Companies:Integrated drug discovery and quality control functions drive consolidated vendor relationships. FDA bioanalytical method validation requirements are forcing software compliance upgrades across GMP facilities.
- Research Institutes:Principal investigator autonomy produces fragmented instrument procurement with emphasis on modular upgrade paths. Service contract unbundling is separating hardware maintenance from software subscriptions in NIH-funded neuroscience centers.
- Diagnostic Laboratories:Accreditation-driven standardization favors instruments with embedded audit trails and automated calibration.
- Quality Control Units:Manufacturing-integrated testing demands high uptime guarantees and rapid service response.
- Government Agencies:Environmental monitoring and food safety mandates sustain multi-year procurement cycles.
- Academic Centers:Core facility models concentrate sophisticated instrumentation while individual labs retain basic fluorescence capabilities.
Pharmaceutical Companies dominate capital expenditure; Diagnostic Laboratories are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fluorescence spectroscopy instrumentation originated in post-war German optics laboratories and Massachusetts academic centers, establishing supply chains that persist across the United States, Germany, Japan, China, and India today.
United States
NIH-funded neuroscience centers in California and Massachusetts drive confocal platform replacement cycles for calcium indicator protocols. FDA bioanalytical method validation guidelines force GMP facilities toward software compliance upgrades. Greater Boston contract research organizations consolidate procurement around dual biochemical and cell-based assay platforms.
Germany
ECHA REACH substance registration deadlines eliminate solvent-intensive extraction protocols for polycyclic aromatic hydrocarbon detection. German water authorities validate synchronous fluorescence scanning techniques for field deployment. Industrial testing houses in the Rhine-Ruhr region certify compact benchtop systems previously confined to academic settings.
Japan
Photomultiplier tube manufacturing concentration exposes instrument supply chains to export restriction vulnerabilities. METI funding priorities support domestic spectrofluorometer platform development. Tokyo and Osaka pharmaceutical quality control suites maintain extensive steady-state instrument installed bases for high-throughput screening.
China
Domestic pharmaceutical manufacturing expansion accelerates quality control instrument procurement in Shanghai and Suzhou industrial parks. NMPA bioanalytical validation standards tighten software compliance requirements for imported platforms. Yangtze River Delta battery electrolyte research favors Raman-fluorescence hybrid configurations for material science applications.
India
PLI scheme incentives accelerate spectrofluorometer installations in Hyderabad and Mumbai pharmaceutical quality control facilities. CDSCO analytical validation guidelines reshape instrument performance requirements for domestic manufacturers. Karnataka and Maharashtra academic core facilities prioritize modular upgrade paths over full-system replacement cycles.
Fluorescence Spectroscopy Market Competitive Landscape
Premium-margin players sit above commodity-margin players across detector sensitivity tiers and software compliance depth. The vendor base stratifies into three tiers: integrated life science conglomerates with diagnostic channel density, specialized optics houses with Raman-fluorescence hybrid capabilities, and regional fabricators serving price-sensitive academic markets. Strategic moves concentrate on service contract unbundling and solid-state laser diode modularization.
Within the integrated conglomerate tier, Thermo Fisher Scientific Inc. and PerkinElmer, Inc. exemplify diagnostic channel leverage for recurring consumable revenue. Shimadzu Corporation anchors Asia-Pacific positioning through localized manufacturing presence. Specialized optics representation includes HORIBA, Ltd., which occupies a position in material science hybrid system segments.
| Leading Market Players |
|---|
| PerkinElmer, Inc. |
| Shimadzu Corporation |
| Thermo Fisher Scientific Inc. |
| Cytiva |
| JASCO Corporation |
| Agilent Technologies, Inc. |
| HORIBA, Ltd. |
| Andor Technology (Oxford Instruments) |
| Bruker Corporation |
| Others |
Supply & Pricing Matrix
Captive photomultiplier tube manufacturing in Japan and Russia anchors both supply security and pricing power for high-sensitivity fluorescence systems, creating tiered market access where detector origin determines instrument certification tier and service bundling depth.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates time-resolved platforms with picosecond detectors from steady-state academic units and refurbished legacy systems. Price differentiation hinges on FDA 21 CFR Part 11 software compliance tier and photomultiplier sensitivity grade. Cost compression in mid-tier steady-state instruments is intensifying because solid-state laser diodes displace mercury arc lamps without full-system replacement. Academic core facilities exhibit highest price sensitivity; GMP pharmaceutical suites show lowest.
Supply Chain Analysis
Refurbishment flows for xenon-lamp steady-state systems extend asset life in Indian and Chinese academic markets, creating secondary supply channels that compete with new instrument sales. Manufacturing concentrates in Japan, Germany, and the United States, with photomultiplier tubes, diffraction gratings, and solid-state laser diodes as critical inputs. Single-source vulnerability in vacuum photon counting technology exposes instrument makers to export restriction risks. Distribution runs through direct field service organizations for pharmaceutical accounts and academic core facility distributors for research institutes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluorescence spectroscopy functions as a stable compounder where regulatory validation requirements for bioanalytical methods perpetuate replacement cycles regardless of macroeconomic conditions.
For Market Incumbents: Anchor service contract unbundling to capture NIH-funded neuroscience centers requiring specialized fluorescence lifetime expertise unavailable through standard channels. Deepen backward integration into solid-state laser diode modules to offset photomultiplier supply concentration. Defend against LC-MS/MS substitution in metabolite quantification by embedding binding kinetics capabilities into mid-tier platforms. For New Entrants and Emerging Players: The gap between premium confocal systems and economy steady-state units creates entry space for compact time-resolved platforms targeting European CMOs responding to EMA ICH Q2(R1) revisions. Southeast Asian district hospitals represent the most penetrable geography for portable sepsis biomarker readers despite WHO prequalification pathways. Pursue regulatory sandbox partnerships with Indian CDSCO to accelerate PLI scheme qualification. For Investors and Strategic Acquirers: Roll-up economics work for specialized optics houses with Raman-fluorescence hybrid capabilities because material science battery electrolyte research demands simultaneous chemical identification and molecular environment mapping unavailable from pure-play vendors. Target mid-cap instrument fabricators with ISO 17025-compliant software architectures and established academic channel relationships. Watch for ECHA REACH deadline acceleration as inflection signal for environmental laboratory replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Detector Modularization Program | Picosecond-resolution TCSPC modules upgrade mid-tier platforms without full-system replacement. |
| Regulatory Compliance Certification | FDA 21 CFR Part 11 and EMA ICH Q2(R1) software validation opens GMP facility procurement. |
| Service Contract Unbundling | Hardware maintenance separation from software subscriptions captures NIH-funded neuroscience centers. |
| Localized Manufacturing Expansion | Domestic assembly in Hyderabad and Mumbai accelerates PLI scheme qualification for Indian pharmaceutical quality control. |
| Raman-Fluorescence Hybrid Development | Combined platforms serve Yangtze River Delta battery electrolyte research with simultaneous chemical identification. |
Research Methodology
Bottom-up pharmaceutical and environmental laboratory modeling reconciled against top-down spectrofluorometer production tracking forms the analytical core. Primary interviews with instrument vendor product managers, academic core facility directors, CMO quality control leads, and diagnostic laboratory accreditation officers combined with secondary validation from FDA bioanalytical method validation guidelines, EMA ICH Q2(R1) revision documents, EPA water quality monitoring protocols, and NIH funding allocation databases. Triangulation across bottom-up installation data and top-down manufacturer shipment records ensures cross-verification.
Historical trendline analysis of steady-state to time-resolved platform mix shifts informed projection modeling across the analysis window. Segmentation dimensions include instrument architecture, detector technology, application vertical, and end-user procurement autonomy. CAGRs derive from regression analysis of replacement cycle compression and regulatory-driven upgrade mandates. Forecast inputs incorporate photomultiplier tube supply constraints and solid-state laser diode adoption curves.
Caveats apply where photomultiplier export restrictions, mass spectrometry substitution acceleration, or EPA method migration cost thresholds could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Boron Analyzer Market
Analytical Instruments
Spectrophotometers Market
Analytical Instruments
Near-Infrared Spectroscopy Market
Analytical Instruments
Global Particle Size Analyzer Market
Analytical Instruments
Global Infrared Thermography Market
Analytical Instruments
Automatic Polarimeter Market
Analytical Instruments
Global IR Spectroscopy Market
Analytical Instruments
Global Electron Microscopy and Sample Preparation Market
Analytical Instruments
Flame Spectrometers Market
Analytical Instruments
Melt Flow Meter Market
Analytical Instruments
Potentiometric Titrators Market
Analytical Instruments
Tunable Diode Laser Analyzer Market
Analytical Instruments
Flame Ionization Detectors Market
Analytical Instruments
Global Spectroscopy Market
Analytical Instruments
Laser-Induced Breakdown Spectroscopy Market
Analytical Instruments
Elemental Analyzer Market