
 Optical Measuring Systems Market | 2026-2036
Optical Measuring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Measuring Systems Market Outlook
Sub-micron precision tiers is unwinding legacy mid-range equipment positions as aerospace and semiconductor buyers reject older platforms. Hexagon Manufacturing Intelligence leverages its CMM software ecosystem to anchor European automotive accounts. Mitutoyo Corporation sustains dominance in Asian electronics supply chains through dense service center networks. Carl Zeiss AG specializes in ultra-high-resolution optics that command premium positioning in medical device metrology.
Optical measuring systems deploy structured light, laser triangulation, or interferometric principles to capture dimensional data with resolutions reaching nanometer scales, serving quality assurance and reverse-engineering workflows across discrete manufacturing. Coordinate measuring machines retain the largest installed base among product types, though 3D scanners capture the fastest expansion as portable units displace fixed-gauge stations on factory floors. Machine vision technology leads margin pools through software-recurring revenue models, while laser triangulation competes on throughput in high-volume electronics assembly.
FDA quality system regulations mandate traceable calibration intervals for production optical equipment, forcing capital refresh cycles among medical device manufacturers. The EU Machinery Directive and CE marking requirements shape product design standards for systems deployed in European automated lines. ISO 10360 geometric accuracy standards govern competitive benchmarking and procurement specifications worldwide. Stakeholders must weigh interoperability investments against proprietary platform lock-in as shop-floor digitalization accelerates.
Market Dynamics
The shift toward sub-micron precision tiers is compressing legacy mid-range equipment positions across aerospace and semiconductor manufacturing, forcing incumbents to reconfigure product portfolios or cede share to specialized ultra-high-resolution platforms.
Growth Catalysts
- EU Machinery Directive:CE marking requirements for automated production lines are elevating calibration standards and accelerating capital refresh cycles among European manufacturers.
- Electric powertrain tolerances:Automotive OEMs are expanding metrology budgets to accommodate tighter dimensional specifications for battery housings and motor assemblies.
- Stuttgart-Munich corridor:Germany's precision engineering cluster concentrates demand for coordinate measuring machines serving medical device and automotive Tier-1 suppliers.
Market Restraints
- Optics supply concentration:German and Japanese specialty glass manufacturers control critical lens substrates, exposing buyers to allocation risk during demand surges.
- Interferometer complexity:Vibration isolation requirements and thermal stability constraints limit deployment on standard factory floors without environmental enclosures.
- ISO 10360 compliance costs:Third-party geometric accuracy certification adds 12-18% to total cost of ownership for mid-range system buyers.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor packaging and mobile assembly are creating first-time demand for portable 3D scanning systems.
- Laser-structured light convergence:Hybrid sensors combining triangulation speed with interferometric precision are opening medical implant inspection applications.
- Service unbundling:Software-recurring revenue models for machine vision analytics are displacing traditional hardware-plus-maintenance contracts in high-volume electronics.
Industry Challenges
- Metrology software integration:Shop-floor digitalization requires optical systems to feed data directly into MES and QMS platforms, straining legacy architectures.
- Calibration technician scarcity:NIST-traceable certification programs produce fewer qualified specialists than replacement demand across aerospace and medical device sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Measuring Systems Market |
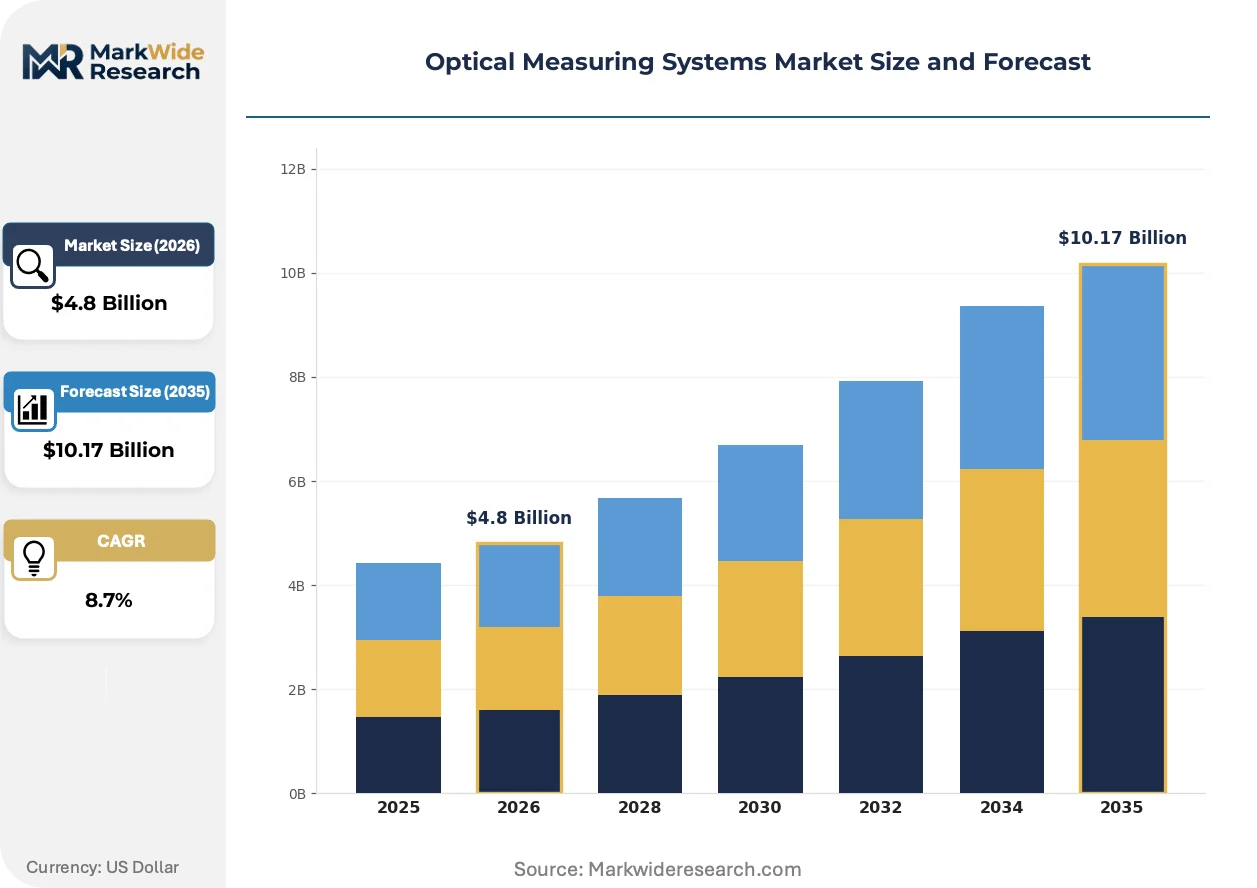
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Scanners, Coordinate Measuring Machines, Laser Scanners, Optical Comparators Technology: Interferometry, Geometric Measurement, Machine Vision, Laser Triangulation End User: Aerospace, Automotive, Electronics, Manufacturing Application: Quality Control, Research & Development, Process Control, Calibration |
| Companies Covered | Hexagon Manufacturing Intelligence, Mitutoyo Corporation, Carl Zeiss AG, FARO Technologies, Nikon Instruments, Jenoptik AG, Keyence Corporation, Zygo Corporation, GOM GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Measuring Systems Market Strategic Shifts
Portable 3D scanning systems are displacing fixed-gauge stations on factory floors, while software-defined measurement workflows are unbundling hardware from analytics revenue. These shifts are compressing traditional product lifecycle assumptions and opening new competitive terrain.
Structured light projection technology is fragmenting the portable measurement segment as semiconductor and consumer electronics manufacturers adopt handheld units for in-line dimensional verification. Asian contract manufacturers are deploying these systems at workstation scale rather than centralized metrology labs. The technology is fragmenting established CMM replacement cycles and enabling distributed quality control architectures.
REACH substance restrictions and RoHS amendments are forcing optical component suppliers to reformulate coatings and housing materials for European market access. Medical device manufacturers face additional scrutiny under MDR traceability requirements for production-line equipment. German and Swiss precision optics firms are accelerating material qualification programs to maintain CE marking eligibility.
Buyer consolidation among automotive Tier-1 suppliers is concentrating procurement leverage and compressing vendor qualification timelines. Reverse auction platforms for capital equipment are displacing traditional sales relationships in high-volume electronics assembly. This pattern is most visible in South Korea and Taiwan, where semiconductor packaging houses are standardizing on multi-site framework agreements.
Optical Measuring Systems Market Segmentation
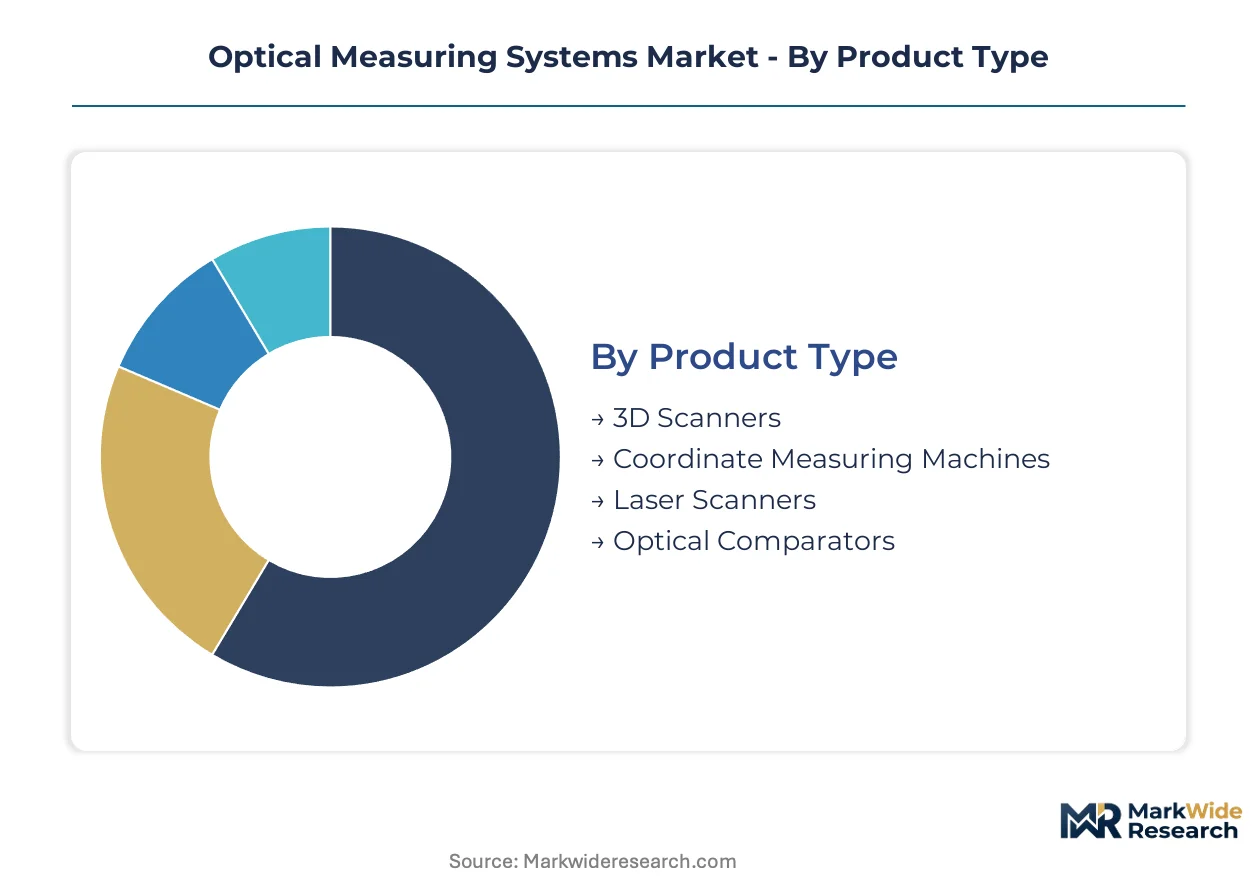
Segmentation in optical measuring systems tracks how precision requirements fragment across measurement modalities and deployment contexts. Portfolio configuration decisions hinge on whether buyers prioritize absolute accuracy, throughput speed, or shop-floor portability.
Product Type:
Margin pools concentrate in systems that combine hardware durability with software-recurring revenue streams, particularly where calibration services extend customer lifetime value.
- Coordinate Measuring Machines:Bridge and gantry architectures deliver sub-micron accuracy through tactile and optical probing combinations. German automotive Tier-1 suppliers around Stuttgart anchor replacement demand as legacy CMMs age out of ISO 10360 compliance windows.
- 3D Scanners:Handheld and arm-mounted units capture complex geometries without fixture requirements, serving aerospace MRO and heritage part replication. Portable units are displacing fixed-gauge stations fastest where production lines reconfigure frequently.
- Laser Scanners:Long-range terrestrial and short-range metrology variants serve civil engineering and industrial inspection respectively.
- Optical Comparators:Shadowgraph and video-based systems persist in high-volume electronics for rapid pass-fail screening.
The dominant share belongs to Coordinate Measuring Machines, while 3D Scanners are gaining share fastest through distributed quality control adoption.
Technology:
Cost tier stratification separates capital-intensive interferometric platforms from volume-deployable triangulation systems.
- Machine Vision:Camera-array systems with embedded analytics enable 100% in-line inspection at electronics assembly speeds. South Korean semiconductor packaging houses deploy these at workstation scale rather than centralized labs, compressing feedback loops.
- Laser Triangulation:Single-point and line-projection sensors balance resolution against acquisition speed for battery housing and motor assembly verification. Automotive OEMs expanding electric powertrain metrology budgets drive capacity additions here.
- Interferometry:White-light and laser interferometers achieve nanometer-scale resolution for wafer-flatness and optical component qualification.
- Geometric Measurement:Photogrammetry and structured-light systems serve large-volume metrology where CMM reach is impractical.
Machine Vision commands the largest installed base through software attach rates, though Laser Triangulation is expanding most quickly via automotive electrification programs.
End User:
Application maturity varies sharply by sector certification requirements and tolerance specifications.
- Automotive:Powertrain electrification is tightening dimensional specifications for battery enclosures and e-motor housings, expanding metrology capital budgets among German and Japanese OEMs.
- Aerospace:FAA airworthiness directives and EASA certification protocols mandate traceable measurement chains for flight-critical components, sustaining premium platform demand.
- Electronics:Miniaturization trends in semiconductor packaging and mobile device assembly drive throughput-focused inspection economics.
- Manufacturing:General industrial applications span tool verification, reverse engineering, and supplier quality assurance.
Automotive retains the deepest penetration, while Electronics is climbing fastest on contract manufacturer capacity expansion.
Application:
Customer type differentiation separates capital-equipment buyers from consumables-oriented service purchasers.
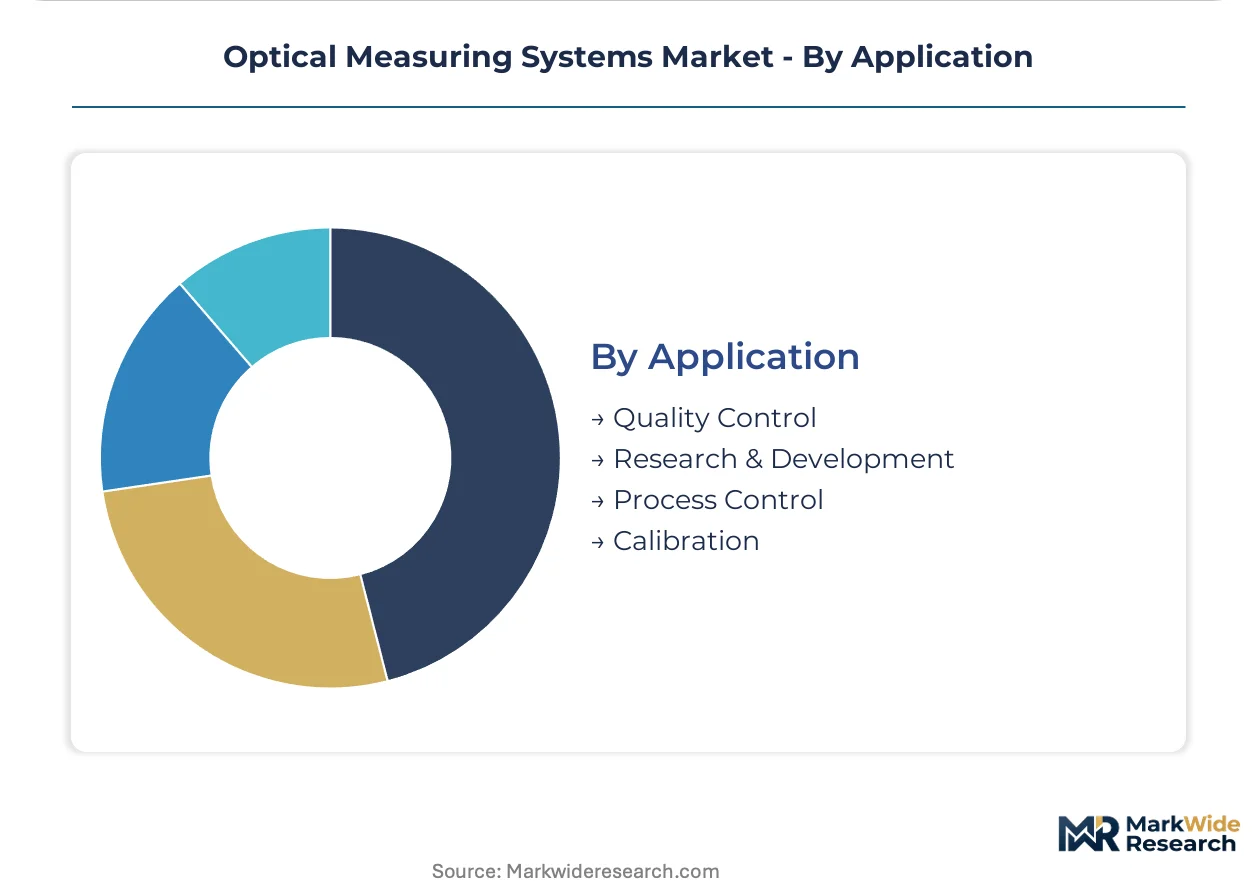
- Quality Control:In-line and at-line inspection workflows dominate volume deployment, particularly where FDA quality system regulations mandate traceable calibration intervals for medical device production.
- Process Control:Real-time dimensional feedback loops enable closed-loop machining adjustments, concentrated in precision engineering clusters.
- Research & Development:Metrology R&D applications span material characterization and prototype validation with lower volume but higher specification flexibility.
- Calibration:NIST-traceable and DAkkS-accredited service demand is outstripping certified technician supply across aerospace and medical device sectors.
Quality Control holds the dominant position, while Process Control is advancing fastest through MES integration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate the lowest price elasticity, absorbing premium positioning for sub-micron systems, while contract manufacturers in Vietnam and India prioritize throughput economics over absolute accuracy. This divergence shapes vendor portfolio strategies across geographies.
Germany
Automotive electrification and medical device precision requirements sustain premium equipment demand. The EU Machinery Directive and CE marking requirements enforce calibration standards that accelerate capital refresh cycles. Stuttgart and Munich anchor the precision engineering corridor where Tier-1 suppliers concentrate CMM replacement orders.
United States
Aerospace MRO and semiconductor packaging drive demand for portable 3D scanning and interferometric platforms. FDA quality system regulations mandate traceable calibration intervals for medical device production equipment. The Pacific Northwest and Greater Boston clusters concentrate metrology R&D procurement for next-generation battery and photonics applications.
China
Domestic EV battery manufacturing and semiconductor packaging expansion create volume demand for laser triangulation systems. MIIT industrial upgrading guidelines and GB standards for measurement equipment shape procurement specifications. The Yangtze River Delta and Pearl River Delta manufacturing belts concentrate contract manufacturer adoption of handheld structured-light scanners.
Japan
Electronics miniaturization and automotive sensor production sustain demand for machine vision and high-speed inspection systems. METI technology roadmaps for manufacturing competitiveness influence R&D subsidy allocation. The Chubu region around Nagoya anchors precision optics supply chains serving semiconductor equipment OEMs.
India
PLI scheme incentives for semiconductor packaging and mobile assembly are creating first-time demand for portable metrology systems. BIS certification requirements for imported measurement equipment shape vendor qualification timelines. Karnataka and Tamil Nadu electronics manufacturing clusters concentrate initial deployments of distributed quality control architectures.
Optical Measuring Systems Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with precision optics specialists commanding premium positioning while volume electronics suppliers compete on sensor throughput and service density. The market structure tilts toward consolidated positions in ultra-high-resolution tiers and fragmented competition in portable scanning segments. Three archetypes dominate: German-Japanese precision optics houses, Asian electronics-focused platform vendors, and North American portable metrology specialists. Competitive moves concentrate on software ecosystem lock-in through calibration service bundling and geographic expansion via regional certification partnerships.
Among German precision engineering houses, Carl Zeiss AG and Jenoptik AG exemplify the optics-centric archetype leveraging heritage lens manufacturing capabilities. Hexagon Manufacturing Intelligence and FARO Technologies occupy positions bridging hardware platforms with software-recurring revenue models. Mitutoyo Corporation represents the Asian service-density archetype, anchoring market presence through dense technical support networks rather than technology differentiation alone.
| Leading Market Players |
|---|
| Hexagon Manufacturing Intelligence |
| Mitutoyo Corporation |
| Carl Zeiss AG |
| FARO Technologies |
| Nikon Instruments |
| Jenoptik AG |
| Keyence Corporation |
| Zygo Corporation |
| GOM GmbH |
| Others |
Value Chain & Pricing Dynamics
Structured light sensors replacing laser triangulation in handheld 3D scanning are simultaneously shifting component sourcing toward Asian optical foundries and compressing hardware margins through commoditized CMOS arrays.
Pricing Analysis
Calibration service contracts and software analytics subscriptions drive lifetime value beyond initial hardware transactions. Three-tier pricing structure across premium interferometric, standard CMM, and economy portable scanner levels separates absolute accuracy buyers from throughput-focused manufacturers. Price differentiation hinges on ISO 10360 certification grade and bundled environmental enclosure specifications. Cost compression in mid-range CMM tiers is intensifying because reverse auction platforms concentrate procurement leverage among automotive Tier-1 suppliers. Electronics contract manufacturers in Vietnam and India exhibit highest price sensitivity, while German precision engineering clusters absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Strategic stockpiling of specialty glass substrates prevails over just-in-time preferences given allocation risk during semiconductor equipment demand surges. German and Japanese precision optics houses anchor critical lens substrate supply, with South Korean and Taiwanese foundries expanding CMOS sensor fabrication. Raw material dependencies include fused silica blanks, aspheric molding compounds, and vibration-dampening granite bases. Single-source vulnerability concentrates in German specialty glass manufacturers controlling high-NA objective production. Distribution runs through authorized technical service centers rather than direct OEM relationships, with calibration certification bundling extending customer lock-in.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric powertrain tolerance tightening represents a structural inflection accelerating capital refresh cycles and expanding addressable spend among automotive metrology buyers.
For Market Incumbents: Shield installed base positions by deepening backward integration into proprietary calibration artifact manufacturing and securing DAkkS accreditation exclusivity in Stuttgart-Munich corridor service centers. Counter portable scanner commoditization through software ecosystem lock-in that feeds measurement data directly into Siemens and SAP MES platforms. Vertical integration into NIST-traceable certification programs addresses technician scarcity threatening service revenue streams. For New Entrants and Emerging Players: Lead with India PLI scheme beneficiary segments where first-time portable metrology demand outpaces established service infrastructure. Target Karnataka and Tamil Nadu electronics manufacturing clusters with handheld structured-light units priced below Mitutoyo service density economics. Pursue calibration technician training partnerships with regional technical institutes as differentiated channel strategy. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision optics specialists with captive lens substrate supply over hardware-assemblers dependent on merchant components. Five-to-ten year viability favors acquisition targets combining interferometric IP with recurring software revenue attach rates. Watch FDA quality system regulation enforcement intensity as inflection indicator for medical device production equipment refresh velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Unbundling | Software-recurring models displace hardware-plus-maintenance contracts in South Korean semiconductor packaging. |
| Hybrid Sensor Development | Laser-structured light convergence opens medical implant inspection applications requiring sub-micron throughput. |
| Regional Certification Partnerships | BIS accreditation investments accelerate vendor qualification timelines in India electronics manufacturing clusters. |
| Backward Integration into Optics | In-house objective manufacturing insulates against German specialty glass allocation risk during demand surges. |
| MES Platform Integration | Direct data pipelines into Siemens and SAP systems entrench incumbent positions against portable scanner entrants. |
Study Parameters
The analysis maps coordinate measuring machines, 3D scanners, laser triangulation systems, and interferometric platforms, each validated through metrology lab directors, automotive Tier-1 quality engineers, medical device regulatory affairs leads, and semiconductor packaging procurement managers. Primary fieldwork combined with secondary validation against FDA quality system guidance documents, EU Machinery Directive technical annexes, ISO 10360 calibration records, and SEC filings from listed precision equipment manufacturers. Bottom-up segment sizing triangulated against top-down industry spend estimates from automotive and electronics trade associations.
Consistency checks validated volume and value outputs against external benchmarks including customs data for optical instrument trade flows and capital expenditure disclosures from major automotive OEMs. Segmentation dimensions modeled include product architecture, measurement principle technology, end-use industry certification requirements, application workflow type, and regional regulatory cluster across the projection horizon. CAGRs derived from fitted growth curves applied to disclosed replacement cycle frequencies and electrification program timelines. Industry-specific inputs encompassed EU Machinery Directive implementation schedules and FDA inspection observation trends.
The analysis sits within stated boundaries; outcomes outside sustained electric vehicle production scaling or stable German-Japanese optics supply would require recalibration. Forecasts reflect documented assumptions regarding calibration technician training pipeline throughput and REACH substance restriction amendment timelines. Revision becomes warranted when semiconductor capital equipment demand volatility crosses thresholds disrupting specialty glass substrate allocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Optical Profilometer Market
Optics
Stroboscope Market
Optics
Global Enhanced Vision System Market
Optics
Tunable Laser Market
Optics
Optical Gratings Market
Optics
Asia-Pacific Anti-Blue Ray Myopia Lenses Market
Optics
Excimer Lasers for DUV Lithography Market
Optics
Fixed Focal Length Lenses Market
Optics
North America Optical Imaging Market
Optics
Optical Sensing Market
Optics
Fiber Optics Market
Optics
Advanced Optics Market
Optics
Global High Purity Quartz Glass Market
Optics
Asia-Pacific Optical Imaging Market
Optics
Optical Telephoto Lens Market
Optics
India Laser Market