
 Phenolic Resin Market | 2026-2036
Phenolic Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Phenolic Resin Market Intelligence
Specialty chemical distribution is fragmenting as regional distributors lose ground to direct procurement arrangements between resin producers and tier-one compounders. Sumitomo Bakelite Co. Ltd leverages its integrated phenol-to-resin manufacturing footprint across Japanese and Chinese plants to secure feedstock cost advantages. SI Group anchors its position through specialized novolac formulations serving North American friction and abrasives customers. Hexion Inc. competes by controlling a broad resol and novolac portfolio that spans construction adhesives, foundry binders, and composite matrices.
Phenolic resin denotes a thermosetting synthetic polymer produced by condensing phenol with formaldehyde under acidic or alkaline catalysis, yielding cross-linked networks with exceptional thermal stability above 300°C, inherent flame resistance, and strong adhesion to substrates. Novolac grades, requiring hexamethylenetetramine cross-linkers for full cure, dominate high-temperature electrical laminates and powder molding compounds where precise flow control matters. Resol resins, self-curing under heat through residual methylol functionality, lead adhesive and insulation foam applications where single-component processing streamlines manufacturing. Moulding compounds represent the fastest-growing product category as electric vehicle battery housings and power module enclosures drive demand for thermally conductive, fire-resistant polymer matrices.
EPA formaldehyde emission standards for composite wood products and REACH restrictions on hazardous substance classifications shape formulation choices and market access conditions for phenolic resin suppliers operating in North America and Europe. China's GB standards for indoor air quality and building material fire safety, enforced by SAMR and MEE, create parallel compliance obligations for producers serving domestic construction and electrical markets. Stakeholders must monitor evolving fire safety codes in transportation and energy infrastructure, as regulatory tightening in multiple jurisdictions simultaneously elevates performance requirements and restricts conventional chemistries.
Market Dynamics
Automotive electrification and fire-safety code tightening across transportation and energy infrastructure are compressing formulation cycles and forcing resin producers to certify thermally conductive grades faster than traditional development timelines permit.
Growth Catalysts
- REACH low-emission mandates:European ECHA restrictions on formaldehyde classifications are redirecting compounder procurement toward certified low-VOC resol grades, opening premium pricing tiers for compliant suppliers.
- Electric vehicle thermal management:Battery module housings and power electronics enclosures require flame-resistant polymer matrices with thermal conductivity above 1.5 W/m·K, pulling novolac-based moulding compounds into automotive tier-one supply chains.
- Jiangsu-Shandong production clustering:China's concentrated phenol-to-resin manufacturing corridors enable just-in-time feedstock access and compressed logistics costs for East Asian friction material producers.
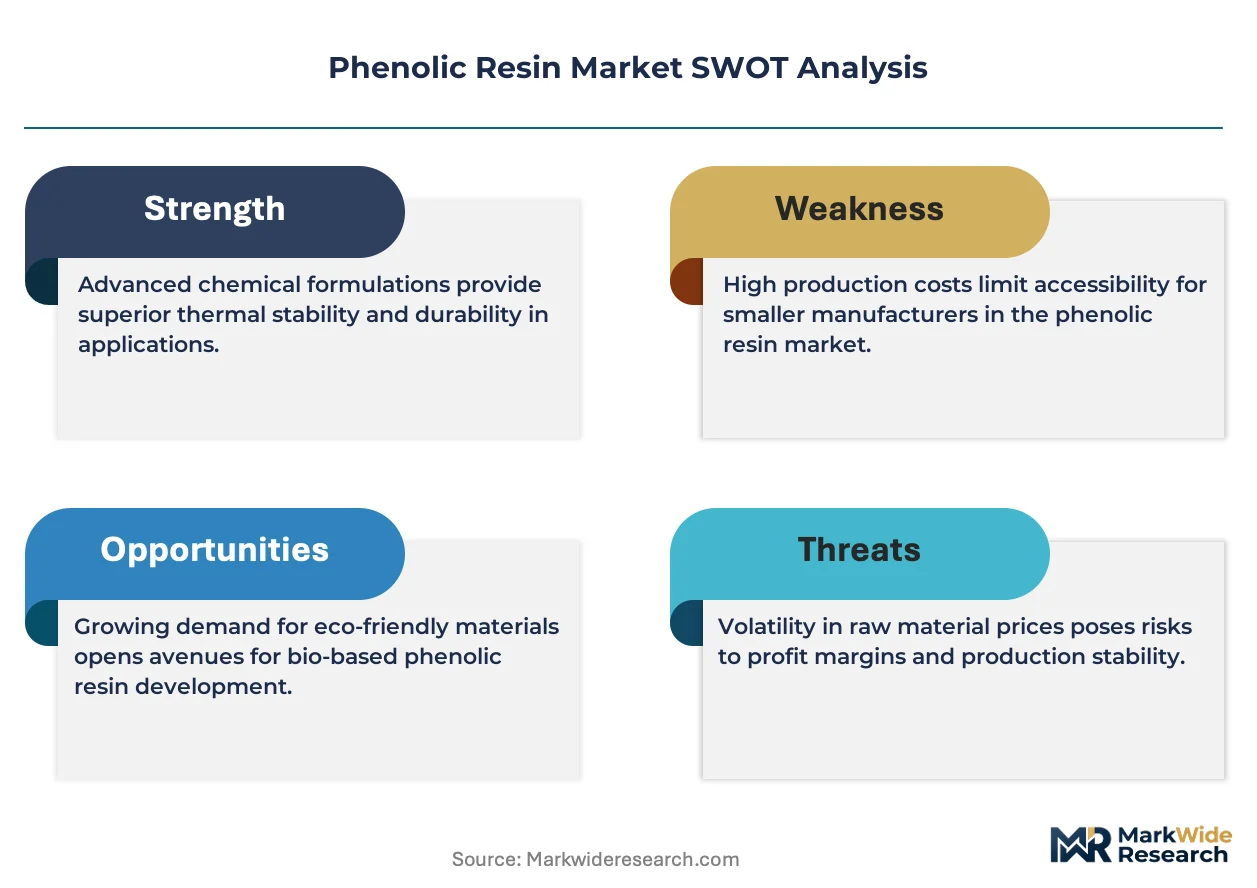
Market Restraints
- Formaldehyde price volatility:Methanol-to-formaldehyde production costs fluctuate with natural gas benchmarks, squeezing margin stability for resol manufacturers dependent on spot feedstock purchasing.
- Single-region supply concentration:Overreliance on Chinese phenol derivatives creates exposure to SAMR environmental enforcement actions and port logistics disruptions affecting global resin availability.
- Epoxy substitution in laminates:High-performance epoxy systems with comparable Tg and lower processing viscosity are capturing share in electrical laminate applications where flow control requirements have relaxed.
Strategic Opportunities
- India construction chemicals penetration:BIS fire-safety certifications for high-rise building materials remain underdeveloped, creating first-mover advantage for phenolic foam insulation suppliers establishing local compounding partnerships.
- US Inflation Reduction Act domestic content:IRA clean energy manufacturing credits incentivize North American production of battery housing materials, rewarding localized phenolic resin supply for EV supply chains.
- Bio-based phenol feedstock integration:Lignin-derived phenol substitutes are achieving technical parity in novolac formulations, enabling carbon intensity reductions that align with EU Green Deal procurement preferences.
Industry Challenges
- Cross-regional certification parallelism:Separate EPA formaldehyde emission protocols, REACH substance registrations, and China GB standards force redundant testing expenditures for multi-jurisdictional suppliers.
- Specialized resin synthesis expertise scarcity:Formulation chemists capable of tuning molecular weight distributions for high-temperature friction applications command premium compensation and limited talent pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phenolic Resin Market |
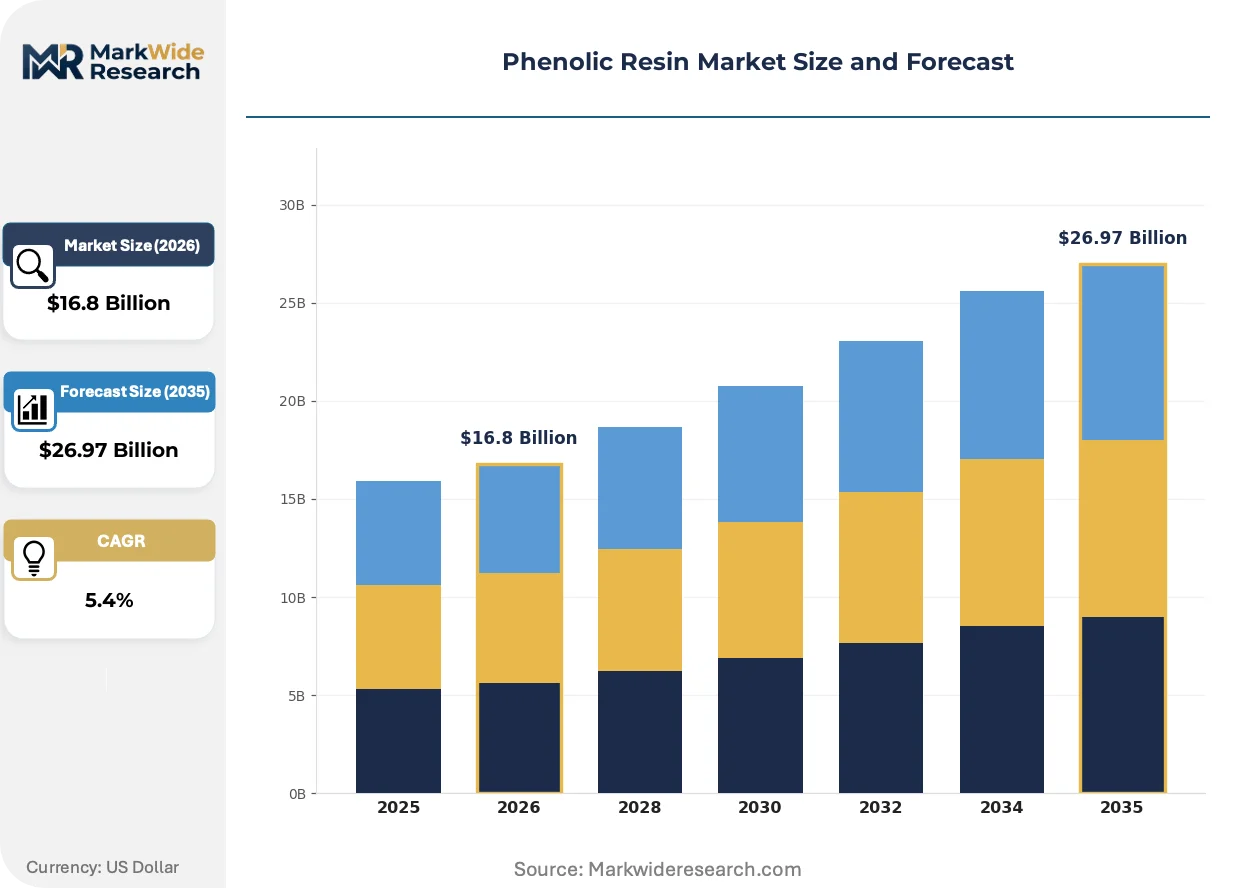
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $26.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Novolac, Resol, Latex, Moulding Compounds End User: Aerospace, Automotive, Electrical, Construction Application: Adhesives, Coatings, Composites, Laminates Form: Solid, Liquid, Powder, Gel |
| Companies Covered | Sumitomo Bakelite Co. Ltd, SI Group, Hexion Inc., BASF SE, DIC Corporation, Kolon Industries Inc., Georgia-Pacific Chemicals, Hexcel Corporation, Prefere Resins Holding GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phenolic Resin Market Strategic Shifts & Innovations
Formulation science is pivoting toward bio-attributed feedstocks and closed-loop manufacturing while digital process control enables batch-to-batch consistency previously unattainable in thermoset production.
Waterborne phenolic dispersions are migrating from laboratory-scale trials to commercial friction material manufacturing. Brake pad compounders in Germany and Japan are qualifying these systems to eliminate solvent handling infrastructure. The technology is migrating from niche aerospace applications toward high-volume automotive production, compressing capital requirements for new entrant compounders.
EPA formaldehyde emission standards for composite wood products are tightening testing protocols and lowering permissible emission thresholds. Panel manufacturers serving US residential construction are reformulating adhesives toward resol systems with enhanced methylol condensation control. The regulation is forcing adhesive suppliers to document supply chain traceability for urea-formaldehyde alternatives.
Direct procurement arrangements between resin producers and tier-one compounders are displacing traditional distributor networks. Friction material manufacturers in China's automotive corridor now negotiate annual volume contracts with Sumitomo Bakelite and Hexion representatives rather than regional chemical distributors. This channel compression is most visible in Jiangsu province, where compounders report 12-15% feedstock cost reductions from eliminated margin stacking.
Phenolic Resin Market Segmentation
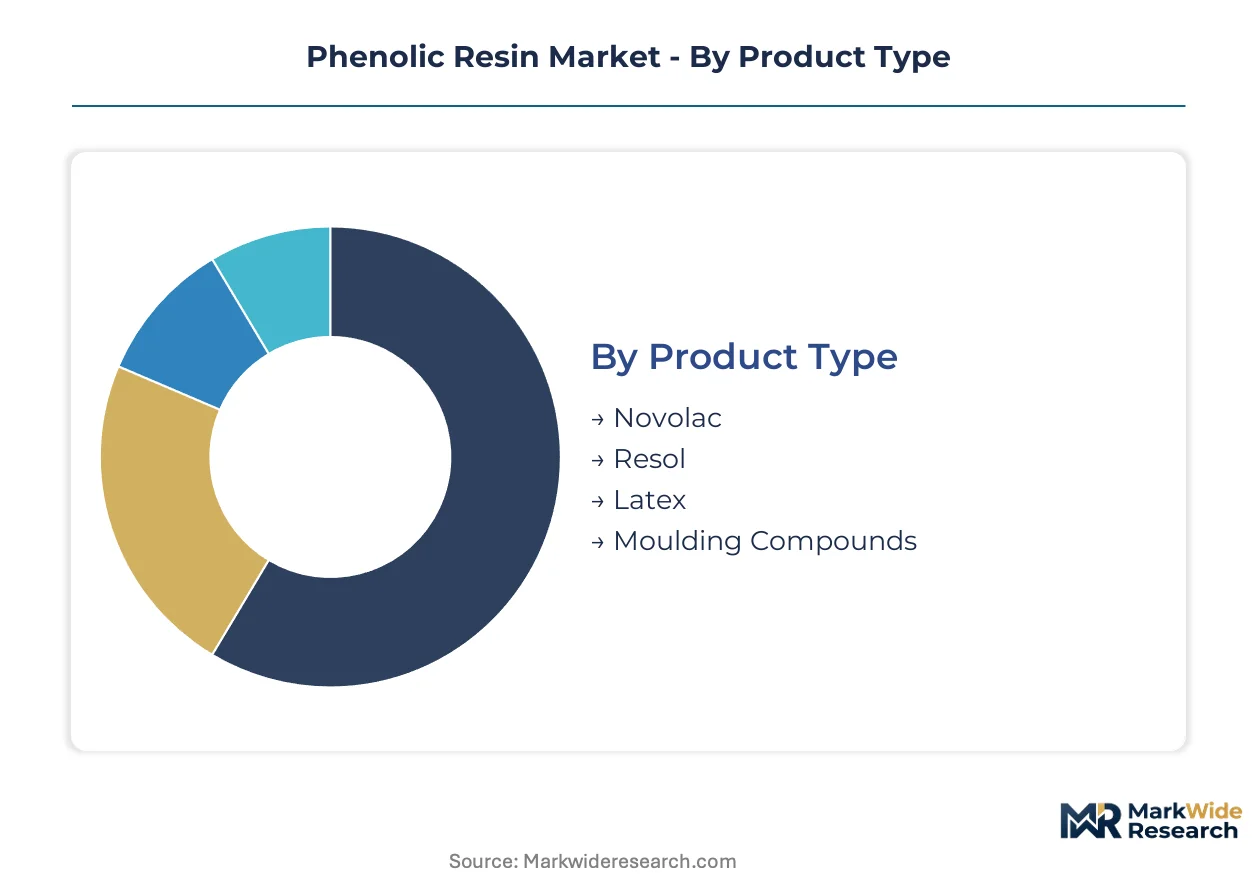
Phenolic resin segmentation reveals how molecular architecture and physical form dictate addressable markets. Distinctions between novolac and resol chemistries, combined with end-use fire-safety requirements, determine supplier R&D allocation and regional manufacturing investments.
Product Type:
Use-case spectra span single-component processing convenience to precise flow control in high-temperature molding.
- Novolac:Acid-catalyzed phenol-formaldehyde condensates requiring hexamethylenetetramine cross-linkers for full cure. Novolac grades dominate high-temperature electrical laminates and powder molding compounds where precise flow control matters. Demand concentrates in Japanese and German electrical laminate manufacturers serving EV power module substrates.
- Resol:Alkaline-catalyzed systems with residual methylol functionality enabling self-curing under heat. Resol resins lead adhesive and insulation foam applications where single-component processing streamlines manufacturing. EPA formaldehyde emission standards are redirecting US construction adhesive procurement toward low-emission resol grades.
- Latex:Aqueous phenolic dispersions for coating and impregnation applications requiring film-forming flexibility.
- Moulding Compounds:Pre-formulated novolac or resol-based composites with fillers and reinforcements for compression or injection molding.
The dominant share belongs to resol, while moulding compounds are closing the gap fastest.
End User:
Cost tiers separate commodity construction applications from certified aerospace and automotive specifications.
- Automotive:Brake friction materials, under-the-hood components, and battery housings requiring thermal stability above 300°C. China's Jiangsu province hosts the densest clustering of automotive phenolic resin consumption.
- Electrical:Laminate substrates, insulation systems, and power electronics enclosures. REACH compliance is redirecting European electrical laminate procurement toward certified low-VOC grades.
- Construction:Adhesives for composite wood panels, insulation foams, and fire-resistant coatings. EPA formaldehyde emission standards are tightening testing protocols for US residential construction applications.
- Aerospace:High-performance composites and ablative materials requiring batch-to-batch consistency and full supply chain traceability.
Automotive commands the largest volume position, though electrical is expanding most quickly on EV thermal management demand.
Application:
Application maturity correlates with regulatory certification depth and customer concentration.
- Adhesives:Wood panel bonding, friction material attachment, and structural assembly. Panel manufacturers serving US residential construction are reformulating toward resol systems with enhanced methylol condensation control.
- Laminates:Electrical grade and decorative paper-based substrates. High-performance epoxy systems are capturing share in electrical laminate applications where flow control requirements have relaxed.
- Composites:Fiber-reinforced matrices for transportation and industrial equipment. Battery module housings and power electronics enclosures pull novolac-based moulding compounds into automotive tier-one supply chains.
- Coatings:Protective and functional surface treatments requiring corrosion resistance and thermal barrier properties.
Adhesives retain the volume lead, while composites show the steepest expansion trajectory on electrification demand.
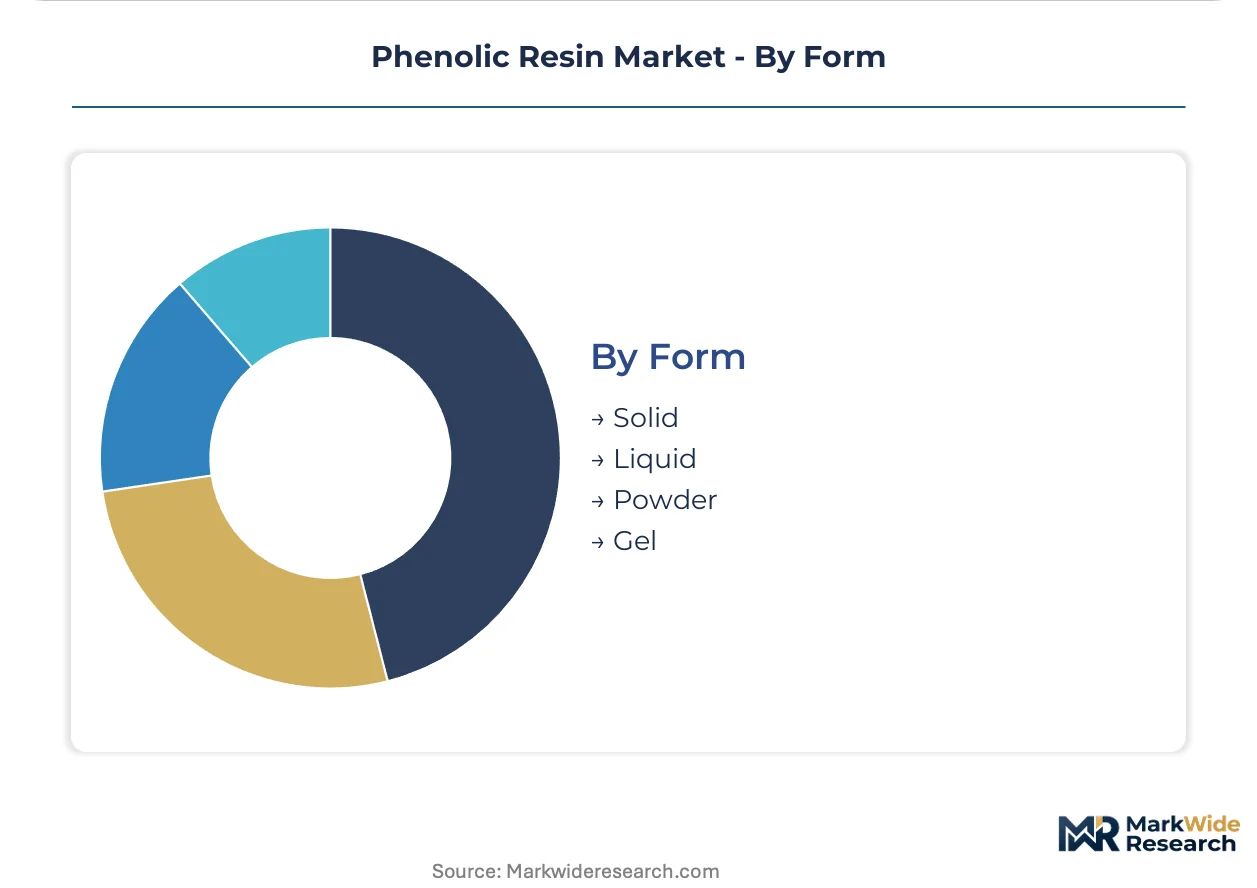
Form:
Supply concentration in East Asian manufacturing corridors favors liquid and solid forms for just-in-time feedstock access.
- Liquid:Pumpable resols for adhesive blending and coating operations. China's Shandong province production clusters enable compressed logistics costs for liquid resin distribution.
- Solid:Flaked or pelletized novolacs for powder compounding and controlled dissolution. Solid forms dominate Japanese electrical laminate manufacturing for precise batch weighing.
- Powder:Pre-ground moulding compounds ready for direct compression or transfer molding.
- Gel:Thixotropic systems for vertical surface coating and gap-filling applications.
Liquid holds the dominant share, with solid form gaining ground on powder molding compound growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US Inflation Reduction Act manufacturing credits and China's dual carbon goals are redirecting phenolic resin capacity investments toward battery supply chains and low-emission production corridors.
China
Automotive electrification and fire-safety mandates for high-rise construction are pulling resol and novolac grades into Jiangsu and Shandong province manufacturing clusters. SAMR and MEE enforcement of GB standards for indoor air quality and building material fire safety creates parallel compliance obligations for domestic producers. The Yangtze River Delta corridor hosts the densest concentration of phenol-to-resin integrated facilities serving friction material and electrical laminate compounders.
United States
IRA clean energy manufacturing credits incentivize domestic production of battery housing materials for EV supply chains. EPA formaldehyde emission standards for composite wood products tighten testing protocols and redirect adhesive procurement toward certified low-VOC resol systems. The Southeast automotive corridor spanning Tennessee and South Carolina is attracting phenolic moulding compound capacity for power module enclosures.
Germany
Brake friction material manufacturers are qualifying waterborne phenolic dispersions to eliminate solvent handling infrastructure under ECHA REACH restrictions. The KBA enforces stringent fire-safety codes for automotive under-the-hood components that favor novolac-based thermally conductive grades. The Ruhr industrial region maintains specialized compounding expertise for high-temperature electrical laminates serving EV power electronics.
Japan
METI industrial policy supports lignin-derived phenol substitutes achieving technical parity in novolac formulations for carbon intensity reduction. JIS standards for electrical insulation materials maintain rigorous batch-to-batch consistency requirements that favor established resin synthesis expertise. The Kansai region around Osaka anchors powder molding compound production for automotive and aerospace thermal management applications.
India
BIS fire-safety certifications for high-rise building materials remain underdeveloped, creating first-mover positioning for phenolic foam insulation suppliers establishing local compounding partnerships. The PLI scheme for advanced chemistry cell manufacturing indirectly supports demand for thermally conductive polymer matrices in battery assembly. Maharashtra and Gujarat industrial corridors are emerging as procurement destinations for construction adhesive and electrical laminate resin grades.
Phenolic Resin Market Key Industry Players
On the supply side, the industry is consolidating around integrated phenol-to-resin manufacturers and specialized formulation specialists serving certified applications. Tier-one automotive and electrical compounders increasingly negotiate direct procurement arrangements, compressing traditional distributor margins. Two strategic archetypes dominate: integrated chemical conglomerates controlling upstream phenol feedstock, and technology-focused specialists commanding premium positioning in high-temperature friction and aerospace specifications. Competitive moves center on backward integration into phenol production and geographic co-location with East Asian automotive manufacturing corridors.
Among integrated chemical conglomerates, Sumitomo Bakelite Co. Ltd exemplifies the archetype of phenol-to-resin manufacturing control across Japanese and Chinese production assets. BASF SE and DIC Corporation occupy positions within the diversified multinational tier, leveraging broad specialty chemical portfolios to serve multiple end-use segments. Within the specialist tier, SI Group and Hexion Inc. represent formulation-focused competitors anchoring positions in North American friction materials and construction adhesives respectively. Prefere Resins Holding GmbH sits within the European specialist segment, while Kolon Industries Inc. and Georgia-Pacific Chemicals exemplify regional scale players with captive feedstock access in South Korea and North American forest products integration.
| Leading Market Players |
|---|
| Sumitomo Bakelite Co. Ltd |
| SI Group |
| Hexion Inc. |
| BASF SE |
| DIC Corporation |
| Kolon Industries Inc. |
| Georgia-Pacific Chemicals |
| Hexcel Corporation |
| Prefere Resins Holding GmbH |
| Others |
Cost & Logistics Intelligence
Chinese phenol-to-resin manufacturing corridors in Jiangsu and Shandong provinces concentrate upstream feedstock control, compressing margin pools toward downstream compounders with direct procurement leverage and tier-one automotive certification.
Pricing Analysis
Volume-discount tiering structures separate annual contract holders from spot purchasers, with pricing stratifying across REACH-certified premium grades, standard industrial resols, and economy construction adhesives. Price differentiation hinges on formaldehyde emission certification tiers and geographic proximity to Shandong production clusters. Cost compression in standard-grade resols is intensifying because methanol-to-formaldehyde feedstock volatility squeezes non-integrated manufacturers. Construction adhesive compounders exhibit highest price sensitivity, while aerospace laminates tolerate premiums for batch-to-batch consistency guarantees.
Supply Chain Analysis
Export-control regimes on phenol derivatives and formaldehyde process technology limit technology transfer to emerging production regions, reinforcing East Asian supply dominance. Manufacturing gravity centers on China, Japan, and South Korea, with feedstock supply drawing from methanol steam-reforming and phenol cumene-oxidation streams. Single-region concentration creates vulnerability to SAMR environmental enforcement actions and Yangtze River Delta port logistics disruptions. Distribution runs through direct procurement arrangements between resin producers and tier-one automotive compounders, displacing traditional regional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification fragments demand across thermally conductive battery housings, fire-resistant friction materials, and power electronics substrates, creating specialized formulation niches that resist commoditization.
For Market Incumbents: Insulate margin positions by deepening captive phenol production in Jiangsu corridor facilities and accelerating REACH-compliant low-VOC resol certification for European electrical laminate supply chains. Secure exclusive supply arrangements with tier-one EV battery housing compounders before epoxy substitution threats intensify in laminate applications.
For New Entrants and Emerging Players: Build out local compounding partnerships in Maharashtra and Gujarat industrial corridors to capture first-mover positioning in India's underdeveloped BIS fire-safety certification landscape for high-rise phenolic foam insulation. Target waterborne phenolic dispersion qualification programs with German brake friction manufacturers eliminating solvent handling infrastructure.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed North American construction adhesive specialists lacking integrated phenol feedstock control. Five-to-ten year viability favors specialists with automotive thermal management certification and lignin-derived phenol substitute R&D pipelines. Monitor EPA formaldehyde emission threshold tightening as inflection signal for resol grade demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenol Production | Captive cumene-oxidation capacity in Jiangsu locks in feedstock cost advantages against methanol volatility. |
| Low-VOC Resol Certification Investment | REACH-compliant grades command premium positioning in European electrical laminate procurement. |
| Waterborne Dispersion Scale-Up | Eliminates solvent handling capital for German brake friction compounders under ECHA restrictions. |
| Local Compounding Partnership in India | First-mover BIS certification for high-rise phenolic foam insulation in Maharashtra corridor. |
| Lignin-Derived Phenol R&D Pipeline | EU Green Deal procurement preferences reward carbon intensity reductions in novolac formulations. |
Research Approach
Cross-validation between primary interviews with resin plant managers, procurement leads at tier-one automotive compounders, and distribution channel partners anchors the qualitative findings against secondary validation from customs trade data, ACC and Cefic industry reports, and SEC 10-K filings. Bottom-up demand modeling triangulates with top-down phenol consumption estimates across the analysis window.
Calibration against historical capacity utilization rates and feedstock cost trajectories shapes the analytical framework across product type, end-use industry, and regional production hub segmentation. CAGRs derive from modeled volume-demand elasticity and price-cost margin compression dynamics, incorporating EV battery housing content-per-vehicle assumptions and construction adhesive regulatory substitution curves.
Practitioners should monitor EPA formaldehyde emission standard revisions, SAMR environmental enforcement intensity, and epoxy substitution rates in electrical laminates for early signals requiring forecast reassessment. Material shifts in REACH substance classification protocols or Yangtze River Delta logistics disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polyol Market
Polymers & Resins
Polyethylene Terephthalate (PET) Foam Market
Polymers & Resins
Europe Medical Polyethylene Market
Polymers & Resins
Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market
Polymers & Resins
Plastic Calendering Resins Market
Polymers & Resins
Global Polymer Chameleons Market
Polymers & Resins
Glycolide Polymers Market
Polymers & Resins
France Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Global Amino Resin Market
Polymers & Resins
United States Geopolymer Market
Polymers & Resins
Thermoplastic Polyurethane (TPU) Market
Polymers & Resins
Biobased Thermosetting Polymers Market
Polymers & Resins
Polyaryletherketone (PAEK) Market
Polymers & Resins
Dispersant Polymer Market
Polymers & Resins
Global Cyanate Ester Resins Market