
 Global Amino Resin Market | 2026-2036
Global Amino Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Amino Resin Market Foresight
The gap between low-emission premium grades and standard commodity amino resins is expanding as environmental certification requirements harden across end-use sectors. BASF SE leverages its integrated methanol-to-derivatives chain to sustain cost leadership in melamine formaldehyde production. Hexion anchors North American supply through controlled distribution into wood laminate processors. Georgia-Pacific Chemicals differentiates via specialized resin systems for moisture-resistant construction panels.
Amino resins are thermosetting polymers synthesized through condensation reactions of formaldehyde with melamine, urea, or phenol, cured via acid catalysis to form cross-linked networks with hardness ratings exceeding 2H pencil scale. These resins function primarily as adhesives, surface coatings, and molding compounds where thermal stability and moisture resistance prove critical. Urea formaldehyde dominates volume flows in furniture manufacturing due to mature cost structures, while melamine formaldehyde captures expanding margin pools in electrical appliances requiring higher heat tolerance. Powder form resins lead packaging solutions applications where precise metering and extended shelf stability reduce waste.
EPA formaldehyde emission standards under TSCA Title VI and REACH restrictions on free formaldehyde content reshape product formulations and testing protocols for market access. China's GB standards and the EU Green Deal chemical sustainability criteria further compress allowable emission thresholds, forcing reformulation investments. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned certification spending.
Market Dynamics
Formaldehyde emission caps under EPA TSCA Title VI and REACH are fragmenting the supplier base into certified premium-grade specialists versus commodity producers, forcing capital reallocation toward low-emission synthesis and third-party testing infrastructure.
Growth Catalysts
- Wood laminate demand surge:Furniture manufacturers in China and Germany are expanding panel board capacity to serve residential construction, pulling amino resin volumes through certified supply chains.
- REACH Annex XVII restrictions:The EU's tightening free formaldehyde limits are accelerating reformulation toward melamine-urea co-condensates with superior hydrolytic stability.
- Electrical appliance heat tolerance requirements:Manufacturers of circuit breakers and switch housings specify melamine formaldehyde for thermal endurance above 150°C, creating specification pull distinct from commodity adhesives.
Market Restraints
- Methanol price volatility:Natural gas fluctuations and Chinese coal-to-methanol policy shifts transmit directly to formaldehyde feedstock costs, compressing resin margins without pass-through mechanisms.
- Supply concentration in Shandong and Louisiana:Over half of global melamine capacity clusters in these two chemical corridors, exposing buyers to weather-related shutdowns and logistics bottlenecks.
- Substitution by polyurethanes in flexible laminates:Reactive hot-melt PUR systems are capturing edge-banding and membrane press applications where formaldehyde-free certification commands price premiums.
Strategic Opportunities
- India's furniture manufacturing expansion:The PLI scheme for wood-based panels and BIS certification mandates for emission standards are opening import substitution opportunities for low-emitting resin systems.
- Construction panel moisture resistance tier:Exterior-grade MUF resins for OSB and plywood in hurricane-prone US Gulf Coast states represent an underserved specification segment.
- Digital formulation platforms:AI-driven catalyst optimization and cure-kinetics modeling are reducing lab-to-production cycles from months to weeks, compressing R&D costs for specialty grades.
Industry Challenges
- Cross-jurisdiction certification complexity:Maintaining parallel EPA CARB Phase 2, REACH, and China GB 18580 test protocols strains quality assurance teams and extends product launch timelines.
- Legacy reactor retrofit requirements:Continuous condensation process upgrades for reduced free formaldehyde demand eight-figure capital commitments with five-year payback horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Amino Resin Market |
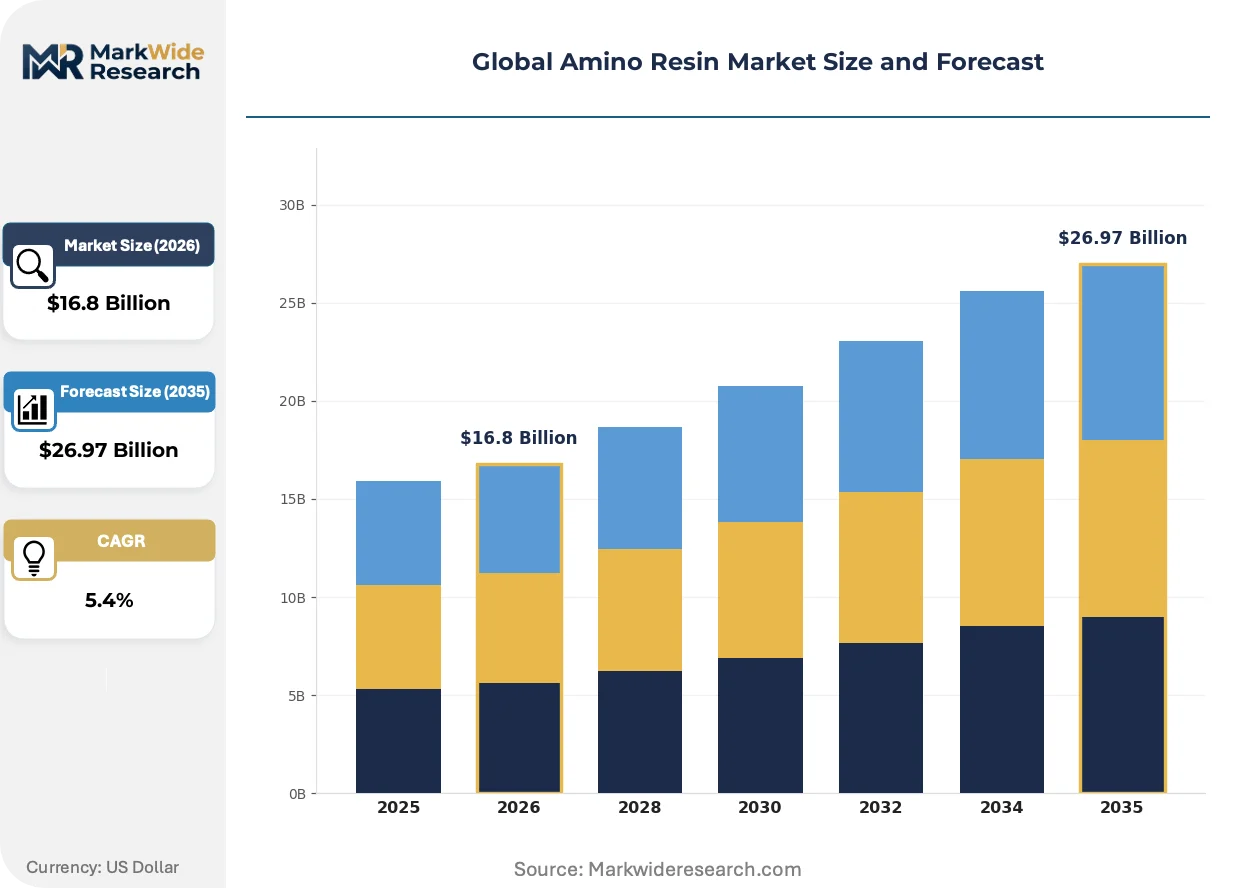
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $26.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Melamine Formaldehyde, Urea Formaldehyde, Phenol Formaldehyde, Benzoguanamine Resin Application: Wood Laminates, Textile Finishing, Paper Coatings, Automotive Parts, Electrical Appliances End User Industry: Furniture Manufacturing, Construction Materials, Consumer Electronics, Packaging Solutions Form: Powder, Liquid, Granular, Flake |
| Companies Covered | BASF SE, Hexion, Georgia-Pacific Chemicals, DIC Corporation, Dynea AS, Arclin Inc., Ercros SA, Chemique Adhesives & Sealants Ltd, Acron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Amino Resin Market Shifts & Advancements
Low-emission synthesis routes and digital quality assurance systems are converging to redefine competitive advantage, separating specification-grade suppliers from volume commodity players through verifiable performance data rather than nominal certifications.
Bio-based formaldehyde scavenger technology is unifying emission control with process efficiency. Chitosan and tannin-derived additives now scavenge residual formaldehyde during cure without extending press cycles. European OSB manufacturers in Austria and Finland are adopting these systems to meet EU Green Deal criteria. This unifying capability is compressing the price gap between premium low-emission grades and reformulated standard resins.
REACH authorization procedures for formaldehyde under SVHC candidate listing are tightening documentary requirements across the value chain. Importers must now demonstrate supply chain due diligence through SCIP database entries. German laminate flooring producers are responding by requiring full substance disclosure from resin suppliers back to methanol source. The construction panel segment faces the steepest compliance cost escalation.
Specification buying through certified supplier lists is displacing spot-market purchasing in North American furniture manufacturing. Large millwork operations in North Carolina and Michigan now mandate third-party emission testing with lot-specific certificates. Distributor relationships are thinning as direct contracts with resin formulators offer traceability guarantees. This concentration is most visible in kitchen cabinet and ready-to-assemble furniture supply chains.
Global Amino Resin Market Segmentation
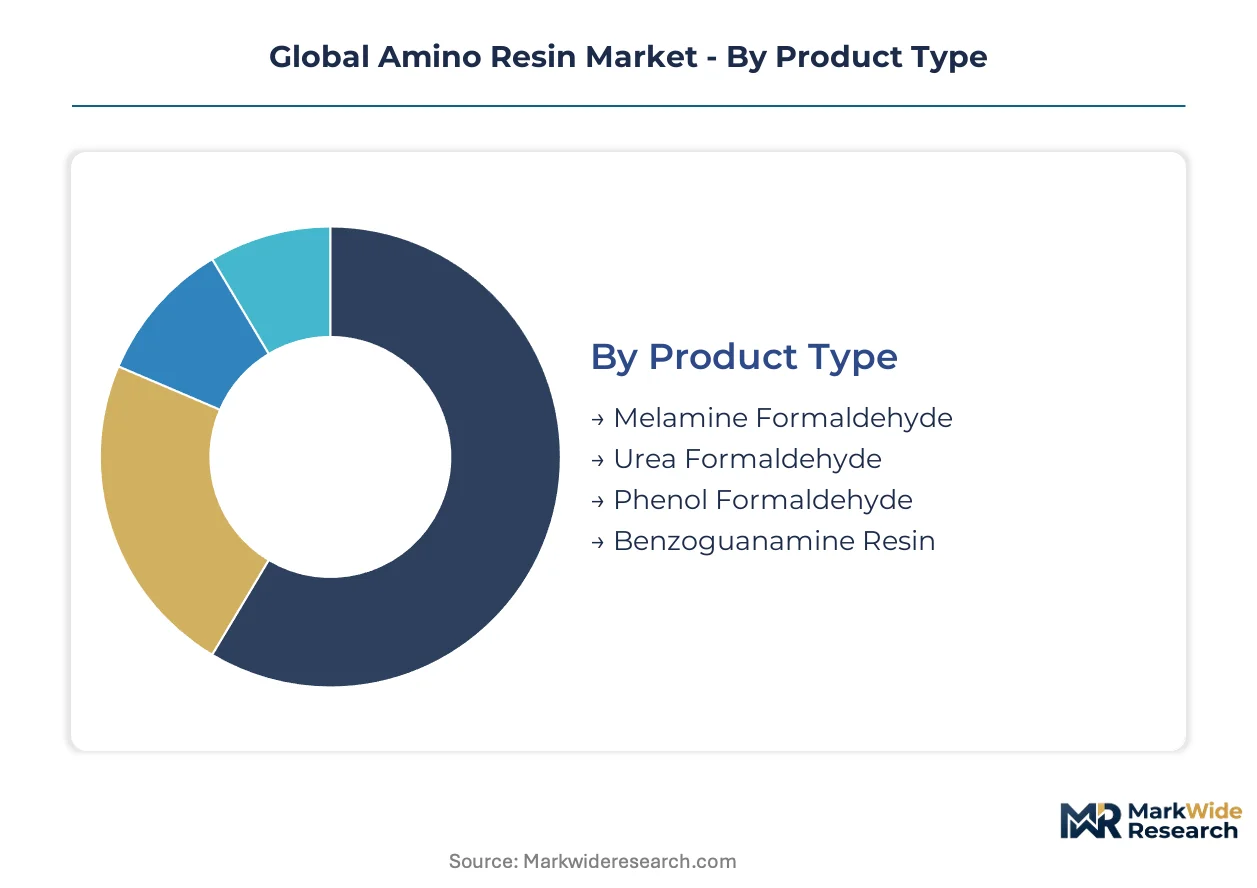
Amino resin segmentation reflects divergent certification burdens across product grades. EPA TSCA Title VI and REACH Annex XVII compliance costs concentrate in furniture-facing segments, while electrical and automotive applications prioritize thermal performance over emission protocols.
Product Type:
Certification-burden intensity varies sharply: melamine formaldehyde faces REACH SVHC scrutiny for residual monomer content, while urea formaldehyde carries the heaviest EPA formaldehyde emission testing protocols for wood adhesive applications.
- Melamine Formaldehyde:Thermosetting polymer formed from melamine and formaldehyde condensation, delivering thermal stability above 150°C and surface hardness exceeding 2H pencil rating. Electrical appliance manufacturers in Germany and China specify this grade for circuit breaker housings and switch components, driven by IEC 60695 glow-wire ignition requirements that commodity resins cannot satisfy.
- Urea Formaldehyde:Cost-optimized condensation product of urea and formaldehyde dominating furniture adhesive volumes. Panel board producers in North Carolina and Michigan pull this grade through certified supply chains, constrained by CARB Phase 2 and EPA TSCA Title VI third-party testing mandates that add 8-12% to delivered costs.
- Phenol Formaldehyde:High-moisture-resistance thermoset for exterior construction panels and marine plywood applications.
- Benzoguanamine Resin:Specialty grade delivering superior alkali resistance and electrical insulation for coil coatings and industrial finishes.
Leading the category by volume: Urea Formaldehyde. Growing fastest: Melamine Formaldehyde.
Application:
Cost tier stratification separates commodity adhesive applications from specification-driven coating and molding segments, with testing protocol costs determining margin capture.
- Wood Laminates:Primary consumption channel for amino resins in particleboard, MDF, and plywood bonding. Kitchen cabinet manufacturers in the US Southeast and Germany's North Rhine-Westphalia cluster demand lot-specific emission certificates, compressing spot-market suppliers.
- Electrical Appliances:Melamine formaldehyde molding compounds for switches, connectors, and housings requiring UL 94 V-0 flammability ratings. Appliance assemblers in China and Mexico specify this segment for thermal endurance above 150°C.
- Textile Finishing:Crease-resistant fabric treatments using dimethylol urea derivatives, facing substitution pressure from DMEU-free alternatives.
- Paper Coatings:Wet-strength additives for packaging and decorative papers, concentrated in Finnish and Austrian pulp mills.
- Automotive Parts:Underhood components and interior trim requiring heat and solvent resistance, supplied through IATF 16949 certified channels.
Dominating by revenue: Wood Laminates. Expanding most quickly: Electrical Appliances.
End User Industry:
Customer type fragmentation splits the market between specification buyers with certified supplier lists and price-sensitive volume purchasers.
- Furniture Manufacturing:Largest demand sink for urea formaldehyde adhesives in panel board lamination. Ready-to-assemble furniture producers in China and Poland drive volume, constrained by BIFMA e3 and LEED v4.1 emission credit requirements.
- Construction Materials:OSB, plywood, and engineered lumber for residential and commercial building. Gulf Coast states in the US specify exterior-grade MUF resins for hurricane-resistant sheathing.
- Consumer Electronics:Circuit boards, connectors, and housings requiring halogen-free flame retardancy. South Korean and Taiwanese electronics assemblers specify melamine formaldehyde for reflow soldering compatibility.
- Packaging Solutions:Moisture-resistant corrugated and folding carton adhesives, with powder form resins preferred for extended shelf stability.
Leading by volume: Furniture Manufacturing. Gaining share fastest: Consumer Electronics.
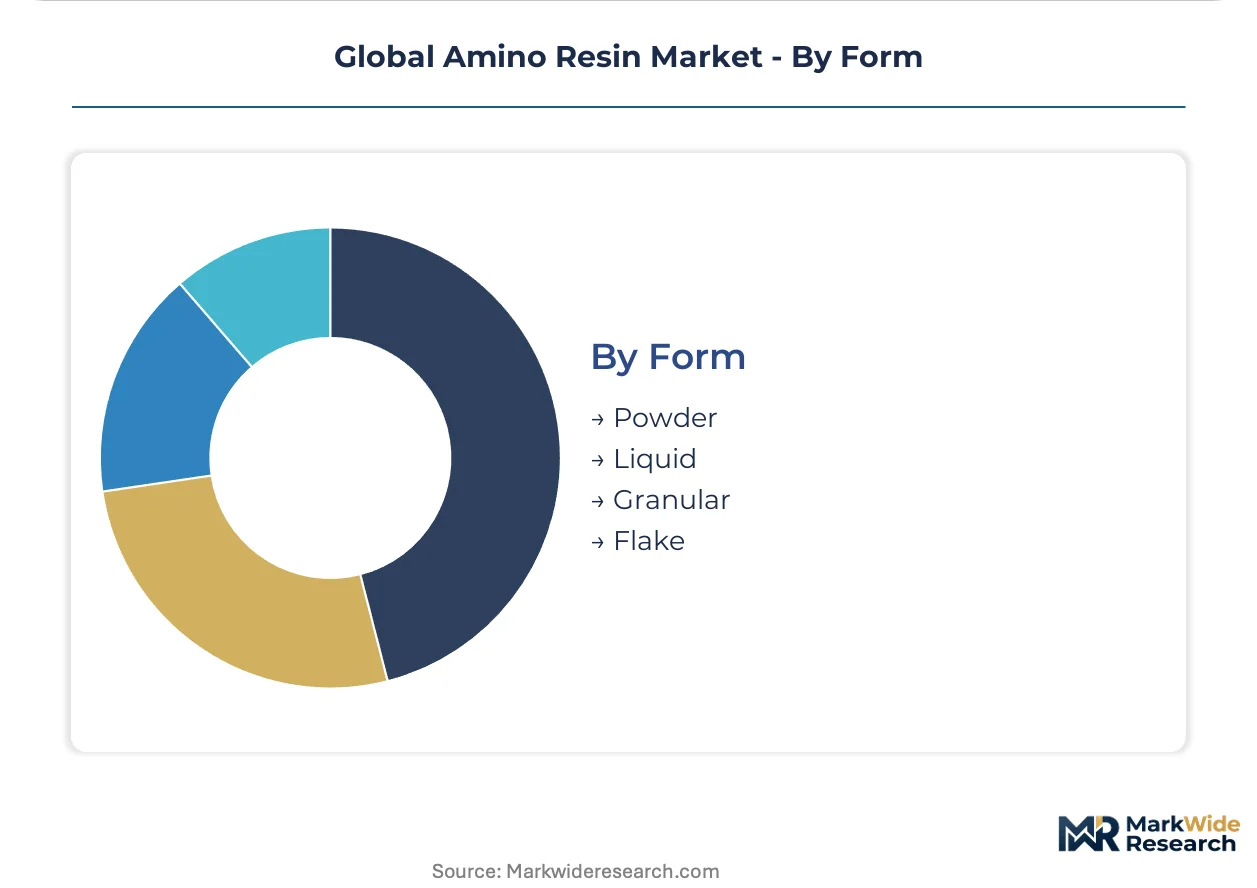
Form:
Supply concentration in powder production centers on Shandong and Louisiana chemical corridors, with liquid form distribution constrained by tanker fleet availability.
- Powder:Free-flowing spray-dried resin with precise metering characteristics and 18-month shelf stability. Wood laminate processors in Germany and the US favor this form for automated blending systems.
- Liquid:Aqueous solution resins for direct spray application in textile and paper finishing. Finnish paper mills and Chinese textile processors consume this grade in bulk tanker deliveries.
- Granular:Intermediate moisture content for specialty molding compound preparation.
- Flake:Low-dust handling form for manual batching in smaller furniture operations.
Dominating by volume: Powder. Climbing the fastest: Liquid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province's chemical corridor hosts over half of global melamine capacity, drawing feedstock from regional coal-to-methanol complexes while serving panel board manufacturers across East Asia. This concentration pattern repeats in Louisiana's Gulf Coast petrochemical belt, where hurricane exposure and logistics constraints shape procurement strategies for North American buyers.
China
Furniture exporters in Zhejiang and Jiangsu provinces drive urea formaldehyde consumption for ready-to-assemble products bound for European and North American retailers. GB 18580 emission standards from the Ministry of Ecology and Environment force continuous reformulation investments. The Yangtze River Delta cluster around Shanghai integrates resin production with particleboard manufacturing, reducing inland logistics costs for moisture-resistant grades.
Germany
Kitchen cabinet manufacturers in North Rhine-Westphalia specify melamine formaldehyde for thermal endurance in electrical housings and switch components. REACH Annex XVII restrictions on free formaldehyde accelerate adoption of melamine-urea co-condensates with superior hydrolytic stability. The Cologne-Düsseldorf industrial corridor concentrates testing laboratories and certification bodies serving EU-wide supply chains.
United States
EPA TSCA Title VI compliance costs concentrate in Southeast panel board operations supplying residential construction. North Carolina and Michigan millwork facilities now mandate lot-specific third-party emission certificates, displacing spot-market suppliers. The Gulf Coast states specify exterior-grade MUF resins for hurricane-resistant OSB sheathing, creating specification pull distinct from interior furniture grades.
India
The PLI scheme for wood-based panels and BIS certification mandates for emission standards open import substitution opportunities for low-emitting resin systems. Maharashtra and Gujarat furniture clusters expand capacity to serve domestic middle-class housing demand. Mumbai-Pune chemical manufacturers invest in formaldehyde scavenger technology to meet EU-equivalent standards for export-oriented panel producers.
Japan
Electronics assemblers in the Kanto region specify melamine formaldehyde for reflow soldering compatibility in circuit breaker housings and connector systems. METI efficiency regulations drive adoption of powder form resins with precise metering characteristics for automated blending. The Nagoya industrial corridor supplies thermal-resistant grades to appliance manufacturers serving Southeast Asian export markets.
Global Amino Resin Market Competitive Landscape
Capital-heavy producers compete with asset-light formulators across a market structure that fragments between integrated petrochemical giants and specialized resin compounders. BASF SE and Hexion anchor the integrated tier with captive methanol-to-formaldehyde supply chains, while regional blenders serve spot-market furniture manufacturers without certification infrastructure. Three archetypes dominate: integrated chemical majors with backward feedstock control, regional formulators with testing laboratory partnerships, and specialty compounders focused on electrical-grade melamine systems. Competitive moves concentrate on reactor retrofit investments for low-emission synthesis and direct contracting relationships that bypass distributor networks.
Among European-integrated chemical majors, BASF SE exemplifies the methanol-derivatives chain archetype with cost leadership in melamine formaldehyde production. Hexion occupies a position within North American supply consolidation, anchoring controlled distribution into wood laminate processors. Georgia-Pacific Chemicals represents the specialty-grade vector, differentiating through resin systems for moisture-resistant construction panels. These three anchors illustrate how certification burdens and feedstock integration separate sustainable margin capture from commodity volume competition.
| Leading Market Players |
|---|
| BASF SE |
| Hexion |
| Georgia-Pacific Chemicals |
| DIC Corporation |
| Dynea AS |
| Arclin Inc. |
| Ercros SA |
| Chemique Adhesives & Sealants Ltd |
| Acron |
| Others |
Supply & Pricing Matrix
Lot-specific emission certification mandates from North Carolina and Michigan millwork facilities are compressing spot-market supplier participation and forcing capital deployment toward third-party testing infrastructure. This specification-driven procurement shift concentrates pricing power with integrated producers possessing captive laboratory networks while fragmenting volume-tier pricing.
Pricing Analysis
Yield-guaranteed throughput contracts dominate premium-grade melamine formaldehyde supply to electrical appliance manufacturers, with pricing stratifying across EPA-certified, REACH-compliant, and standard commodity tiers. Price differentiation rests on certification burden intensity and captive methanol integration, with BASF and Hexion commanding 15-20 point spreads over regional blenders. Cost compression in standard urea formaldehyde intensifies as Chinese coal-to-methanol policy shifts transmit directly to feedstock costs. Furniture manufacturers exhibit highest price sensitivity, while electrical-grade buyers prioritize thermal performance guarantees over unit economics.
Supply Chain Analysis
Direct-to-mill contracts with lot-traceability documentation now handle specification-grade demand from kitchen cabinet and ready-to-assemble furniture producers, displacing distributor intermediaries. Production gravity centers on Shandong Province and Louisiana's Gulf Coast corridor, drawing methanol feedstock from regional coal-to-chemical and natural gas steam-cracker complexes. Raw material dependencies on formaldehyde, melamine crystals, and urea prills expose formulations to energy price volatility and weather-related logistics interruptions. Single-source vulnerability from hurricane exposure in Louisiana creates procurement contingency planning requirements for North American buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formaldehyde emission standard divergence across EPA, REACH, and China GB frameworks is consolidating the supplier base, forcing sub-scale regional blenders toward specialty niches or exit.
For Market Incumbents: To counter polyurethane substitution in flexible laminates, BASF and Hexion should deepen backward integration into methanol-derivatives chains while deploying AI-driven catalyst optimization to compress R&D cycles for low-emission grades. Certification infrastructure investments in third-party testing partnerships defend specification-grade positioning against commodity erosion. For New Entrants and Emerging Players: Digital formulation platforms offering cure-kinetics modeling as-a-service present the lowest barrier entry path, enabling asset-light participation in specialty melamine-urea co-condensates. India's PLI scheme for wood-based panels offers the most penetrable geography, with BIS certification mandates creating import substitution demand for EU-equivalent emission systems. Target direct contracting with Maharashtra and Gujarat furniture clusters bypassing established distributor networks. For Investors and Strategic Acquirers: The window for entry favors regional formulators with testing laboratory partnerships and established EPA CARB Phase 2 certification infrastructure. Long-term viability hinges on reactor retrofit completion for reduced free formaldehyde synthesis, with five-year payback horizons separating sustainable margin capture from stranded asset risk. Monitor REACH SVHC candidate listing progression for formaldehyde authorization procedures as inflection indicator for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Reactor Retrofit for Low-Emission Synthesis | EPA TSCA Title VI compliance separates certified suppliers from commodity volume players. |
| Backward Integration into Methanol Feedstock | Captive formaldehyde production insulates margin structures from natural gas volatility. |
| AI-Driven Catalyst Optimization Platforms | Digital formulation tools compress lab-to-production cycles from months to weeks. |
| Direct Mill Contracting with Lot Traceability | Specification buying in North Carolina and Michigan displaces distributor relationships. |
| Joint Venture in India PLI Scheme Zones | Maharashtra and Gujarat clusters offer import substitution for EU-equivalent emission standards. |
Research Methodology
Trade databases, chemical industry association reports, and SEC filings from integrated petrochemical majors formed the secondary backbone, cross-referenced with primary interviews involving resin plant managers, procurement leads at panel board manufacturers, distribution channel partners, and technical R&D directors. Bottom-up volume modeling across grade tiers, end-use industries, and regional production hubs combined with top-down macroeconomic validation to establish market sizing boundaries.
Historical trendline analysis of methanol-to-formaldehyde cost pass-through patterns and certification-driven price spreads informed the projection framework. Segmentation dimensions modeled include product type, application, end-user industry, and form factor across the analysis window. CAGRs derived from elasticity-adjusted demand curves incorporating electrical appliance heat tolerance specifications and furniture manufacturing emission compliance intensity.
The model holds under stable regulatory enforcement trajectories; deviation in REACH authorization timing or EPA testing protocol amendments would shift volume and value outputs. Periodic stress-testing of base assumptions against methanol price volatility and hurricane-related supply disruptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Green Polyols Market
Polymers & Resins
Beverage Processing Polymers Market
Polymers & Resins
Ethylene Vinyl Acetate (EVA) Market
Polymers & Resins
Polypropylene Filler Sheet Market
Polymers & Resins
Global High Temperature Resin Market
Polymers & Resins
Bisphenol a Market
Polymers & Resins
Styrenic Block Copolymer (SBC) Market
Polymers & Resins
Global Polymer Market
Polymers & Resins
Isosorbide-Based Engineering Polymer Monomers Market
Polymers & Resins
PCR Polyolefins Market
Polymers & Resins
GCC Vinyl Flooring Market
Polymers & Resins
Polyethylene Furanoate Market
Polymers & Resins
Asia-Pacific Super Absorbent Polymers (SAP) Market
Polymers & Resins
Liquid Saturated Polyester Resin Market
Polymers & Resins
Asia-Pacific Opaque Polymers Market
Polymers & Resins
Global Graft Polyols Market