
 Sheet Moulding Compound (SMC) Market | 2026-2036
Sheet Moulding Compound (SMC) Market Size, Share, and Industry Trends Forecast 2026-2036
Sheet Moulding Compound (SMC) Market Insights
Automotive-grade SMC formulations is rotating toward higher fiber-loading and Class-A surface specifications as OEMs substitute metal closures. Continental Structural Plastics leverages its vertical integration across compounding and compression molding to secure multi-year vehicle platform contracts. Toray Group anchors global supply of carbon-fiber-reinforced SMC variants through its Japanese and US production bases. IDI Composites International specializes in custom-engineered formulations for electrical and corrosion-resistant applications, occupying a defensible niche above commodity general-purpose grades.
Sheet Moulding Compound consists of unsaturated polyester or vinyl ester resin premixed with chopped glass fibers, fillers, and thickeners, supplied as a ready-to-mold dough that cures under heat and pressure to produce high-strength, dimensionally stable parts. The material serves primarily as a metal-replacement solution where corrosion resistance, electromagnetic transparency, or complex geometric integration reduces assembly cost. Fire Retardant SMC commands premium positioning in electrical infrastructure and mass-transit interior applications where UL 94 V-0 equivalence is mandatory. High-Temperature SMC grows fastest among product tiers as under-hood automotive applications and industrial equipment housings push continuous-use temperature requirements above 200°C. Body Panels represents the most mature application segment, though Electrical Components offers wider margin pools due to shorter qualification cycles and lower tooling capital intensity.
The EPA governs volatile organic compound emissions from SMC manufacturing facilities under Clean Air Act Title V permitting, while OSHA mandates styrene exposure limits that shape plant ventilation investments and resin formulation choices. REACH registration requirements in Europe restrict certain phthalate-based thickeners, compelling compounders to validate alternative chemistries through ECHA substance evaluation protocols. Stakeholders must monitor evolving crashworthiness certification protocols from NHTSA and Euro NCAP, as these determine whether SMC structural components qualify for primary load-bearing roles beyond current non-structural and semi-structural applications.
Market Dynamics
Automotive OEMs are substituting SMC for steel closures at an accelerating pace, driven by EU fleet CO₂ mandates and US CAFE standards that penalize curb weight. This substitution pressure is restructuring compounding capacity location decisions and resin formulation R&D priorities across supplier networks.
Growth Catalysts
- F-Gas Regulation:Europe's phasedown of hydrofluorocarbon blowing agents is forcing reformulation investments that favor low-density SMC grades with superior thermal insulation properties.
- Electrical infrastructure:Grid hardening investments and EV charging station rollouts are consuming fire-retardant SMC for enclosures and busbar supports requiring UL 94 V-0 certification.
- Carbon fiber loading:Hybrid glass-carbon SMC variants are penetrating motorsport and premium EV architectures where specific stiffness requirements exceed conventional glass-reinforced capabilities.
Market Restraints
- Styrene price volatility:Unsaturated polyester resin feedstock costs fluctuate with benzene and ethylene spot markets, compressing compounder margins during upstream petrochemical cycles.
- Tooling capital intensity:Compression molds for Class-A body panels require hardened steel cavities with vacuum venting systems that cost multiples of injection molding equivalents.
- Thermoplastic substitution:Long-fiber-reinforced polypropylene from Celanese and SABIC competes for semi-structural applications with faster cycle times and end-of-life recyclability.
Strategic Opportunities
- India automotive:Maruti Suzuki and Tata Motors supplier parks present greenfield SMC specification opportunities as domestic OEMs lightweight entry-level platforms.
- Hydrogen storage:Type IV pressure vessel liners and boss components represent emerging demand for filament-wound SMC overwraps in heavy-duty transport applications.
- CSRD alignment:EU corporate sustainability reporting mandates are creating first-mover advantage for compounders with verified recycled content and bio-based resin pathways.
Industry Challenges
- Surface quality certification:Achieving OEM paint-line compatibility requires 18-24 month qualification cycles with extensive weathering and distortion testing protocols.
- Press operator scarcity:Compression molding expertise has atrophied in North American manufacturing regions as metal stamping dominated automotive supplier employment.
- Resin thickener migration:REACH restrictions on magnesium oxide thickeners are forcing validation of alternative chemistries with uncertain viscosity stability windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sheet Moulding Compound (SMC) Market |
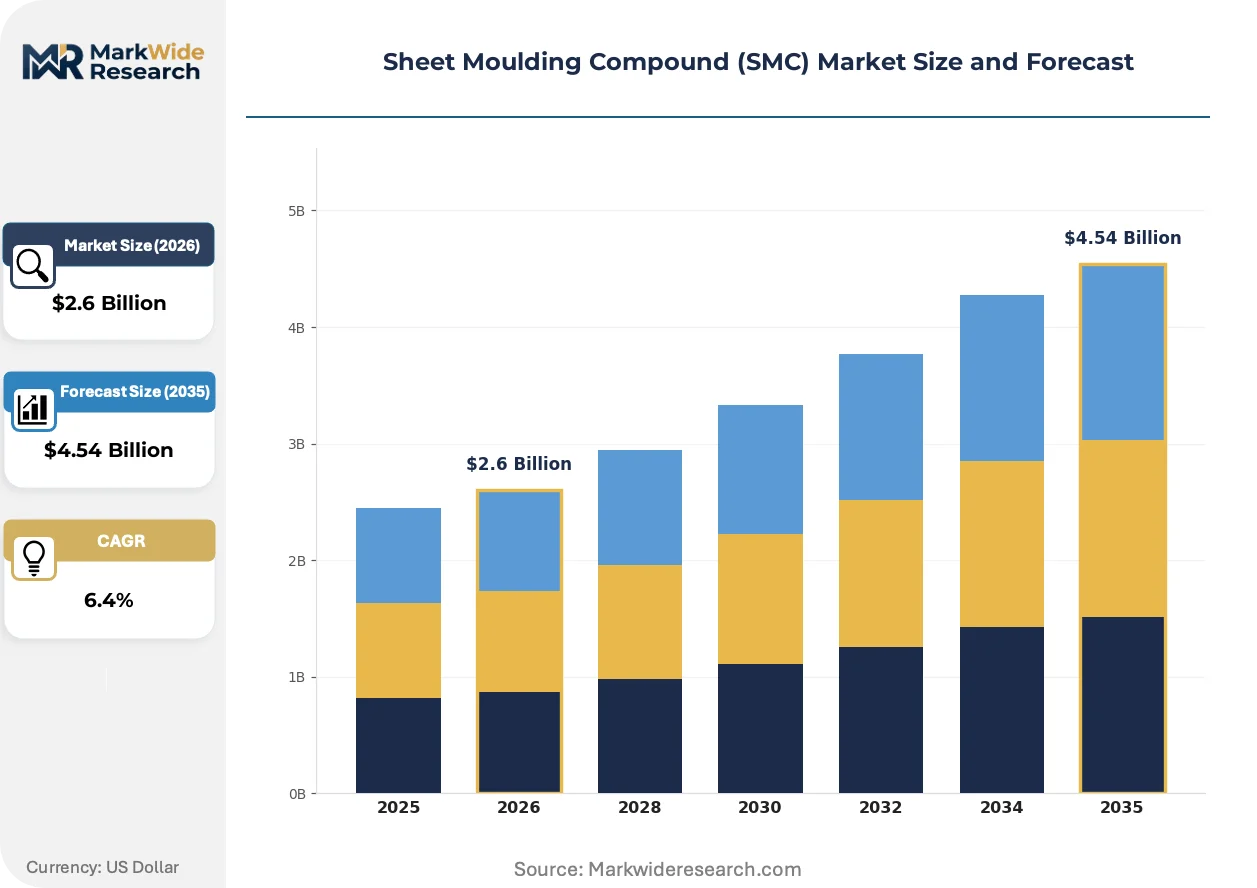
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $4.54 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Purpose SMC, Fire Retardant SMC, High-Temperature SMC, Electrical Insulating SMC End User: Automotive OEMs, Building & Construction, Electrical & Electronics, Aerospace Application: Body Panels, Electrical Components, Interior Parts, Industrial Equipment Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Continental Structural Plastics Inc., Toray Group, IDI Composites International, Changzhou RealLand Composite Material Technology, Mitsui Chemicals, Menzolit, Core Molding Technologies, BMC Materials, Polynt Composites, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sheet Moulding Compound (SMC) Market Trends and Innovations
Formulation chemistry and fiber architecture are evolving in parallel, with bio-based resins and recycled carbon fiber feedstocks entering qualification pipelines. These material shifts are reshaping supplier qualification criteria and end-of-life value recovery assumptions.
Recycled carbon fiber SMC is supplanting virgin glass-reinforced grades in non-appearance structural brackets. BMW and Jaguar Land Rover procurement teams have adopted volume targets for recycled fiber content in under-hood applications. This specification shift is compressing the addressable market for conventional chopped-strand products while rewarding compounders with secure recycled fiber supply agreements.
REACH substance evaluation protocols are accelerating phase-out of cobalt-based promoters and phthalate thickeners across European compounding operations. ECHA's 2024-2025 rolling action plan targets specific unsaturated polyester catalyst packages, forcing reformulation validation cycles. German and French automotive suppliers are responding by dual-sourcing from compounders with alternative cure chemistry portfolios.
Direct long-fiber thermoplastic (DLFT) hybrid processes are capturing semi-structural applications previously served by compression-molded SMC. Tier-1 suppliers in Michigan and Ontario are installing combined SMC/DLFT press lines to offer OEMs material flexibility within single tooling investments. This equipment convergence is most visible in North American pickup truck bed and tailgate programs where weight targets fluctuate across model years.
Sheet Moulding Compound (SMC) Market Segmentation
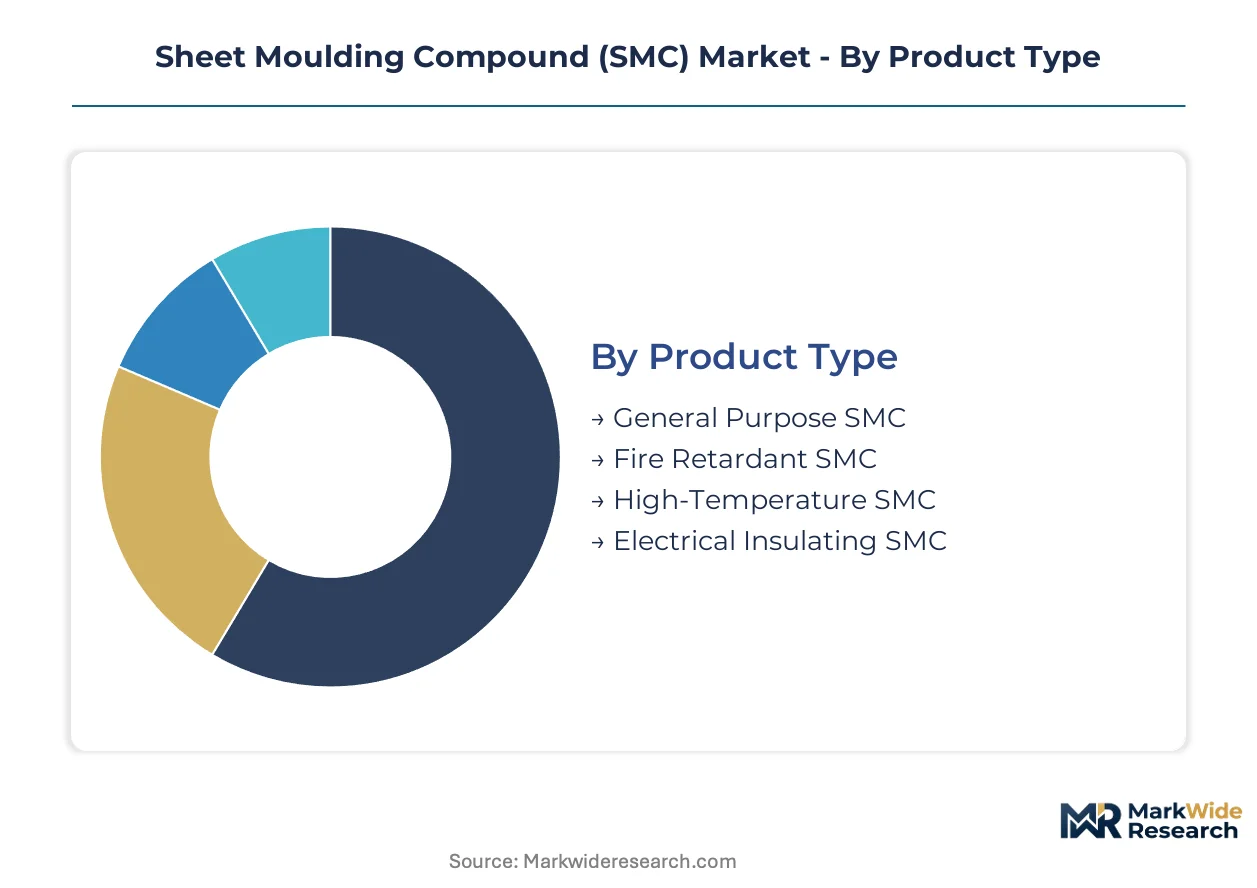
Segmentation in SMC markets reflects divergent certification burdens and tooling economics. Product-grade specifications determine regulatory compliance pathways, while end-use concentration shapes regional compounding investments and margin structures.
Product Type:
REACH substance restrictions and UL certification tiers fragment formulation strategies across European and North American supply bases.
- General Purpose SMC:Standard unsaturated polyester formulations with chopped glass reinforcement serve non-critical structural brackets and industrial housings. Demand concentrates in German automotive supplier networks where BMW and Volkswagen platforms specify cost-optimized closure components.
- Fire Retardant SMC:Halogen-free formulations achieve UL 94 V-0 ratings through aluminum trihydrate or phosphorus-based additives. US electrical infrastructure rollouts and mass-transit interior mandates in California and New York consume volume as grid hardening investments accelerate.
- High-Temperature SMC:Vinyl ester and specialized epoxy matrices withstand continuous service above 200°C for under-hood applications.
- Electrical Insulating SMC:Low-loss formulations with controlled dielectric properties serve transformer housings and EV power electronics enclosures.
Established volume favors General Purpose SMC; emerging adoption favors Fire Retardant SMC.
End User:
Customer procurement scale determines qualification cycle length and captive compounding arrangements.
- Automotive OEMs:Platform-level contracts spanning 5-7 model years anchor global SMC consumption. EU fleet CO₂ mandates and US CAFE standards penalizing curb weight drive substitution of steel closures across BMW, Volkswagen, and Detroit Three supplier networks.
- Building & Construction:Infrastructure corrosion resistance and electromagnetic transparency specifications displace metal in utility housings and architectural cladding. German and French public procurement rules increasingly reference EPD certification for embodied carbon.
- Electrical & Electronics:Shorter qualification cycles and lower tooling capital intensity yield wider margin pools than automotive programs.
- Aerospace:Secondary structural brackets and interior panels specify carbon-fiber-reinforced variants with stringent flame-smoke-toxicity certification.
Procurement concentration tilts toward Automotive OEMs; margin expansion favors Electrical & Electronics.
Application:
Surface quality requirements and load-bearing specifications create distinct tooling investment profiles across use cases.
- Body Panels:Class-A surface specifications demand hardened steel molds with vacuum venting systems and 18-24 month OEM qualification cycles. German and US automotive platforms represent the most mature demand segment with established paint-line compatibility protocols.
- Electrical Components:Enclosures, busbar supports, and insulator housings prioritize dielectric performance over cosmetic finish. EV charging infrastructure deployment across California, Texas, and Germany consumes fire-retardant grades with faster design-to-production timelines.
- Interior Parts:Mass-transit seating shells and HVAC housings specify low-emission formulations meeting German BIFMA or French NF standards.
- Industrial Equipment:Chemical-resistant housings and pump components serve corrosion-critical process industries.
Tooling intensity distinguishes Body Panels; speed-to-market advantages cluster in Electrical Components.
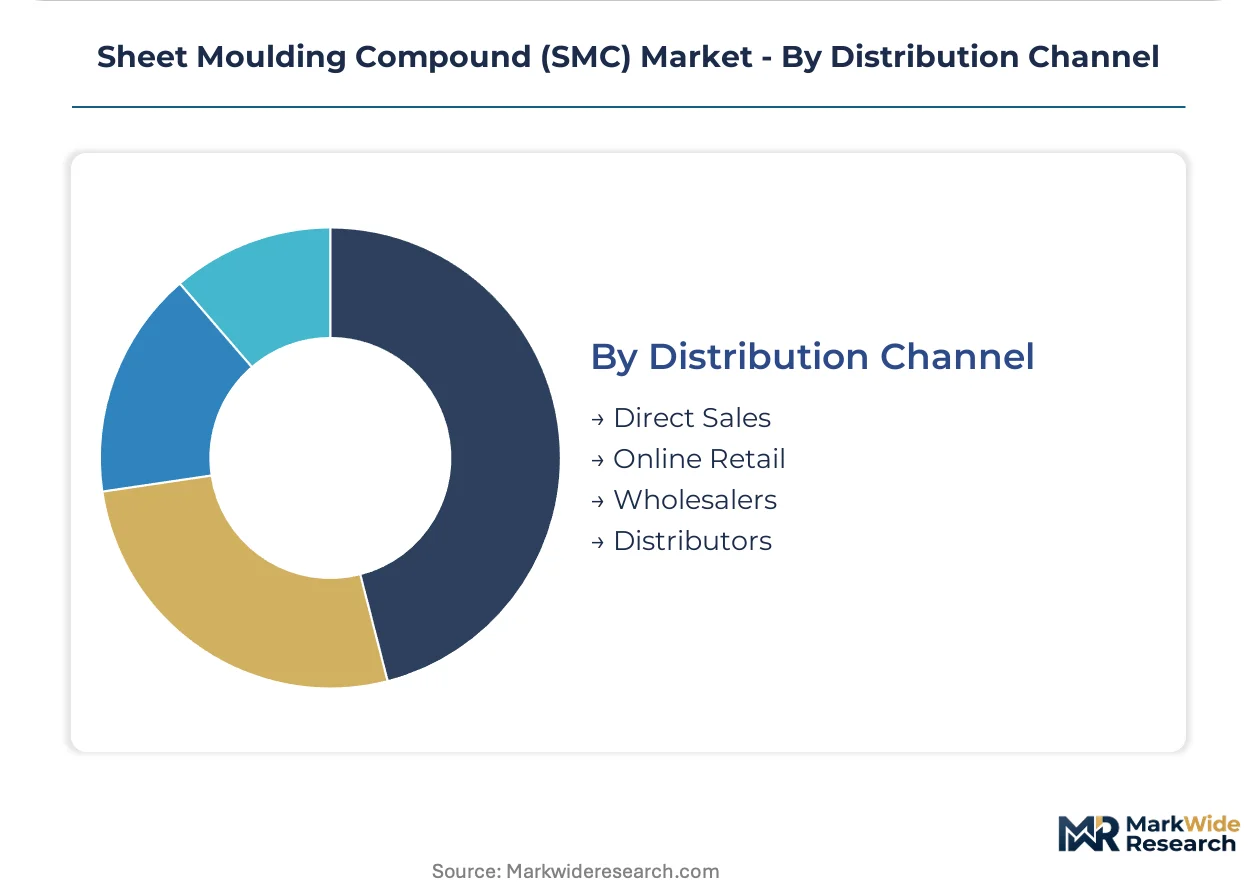
Distribution Channel:
Volume scale and technical service requirements determine channel selection across customer tiers.
- Direct Sales:Automotive OEMs and Tier-1 suppliers negotiate multi-year platform contracts with embedded formulation development and just-in-time delivery guarantees. German and Japanese OEM procurement teams favor direct relationships with compounders possessing in-house compression molding capability.
- Distributors:Regional stocking locations serve mid-volume electrical and industrial accounts requiring technical specification support and smaller lot sizes.
- Wholesalers:General-purpose grades for construction and repair applications move through building material supply chains.
- Online Retail:Sample quantities and standardized grades for prototyping and maintenance operations.
Platform-scale contracts concentrate through Direct Sales; fragmented demand routes through Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compounders cluster capacity near automotive assembly corridors and electrical manufacturing hubs. Germany, the United States, China, Japan, and India concentrate the bulk of formulation facilities and compression molding infrastructure.
Germany
BMW and Volkswagen supplier networks anchor composite-intensive vehicle platforms across Bavaria and Lower Saxony. REACH substance evaluation protocols from ECHA are accelerating phase-out of cobalt-based promoters and phthalate thickeners. The Stuttgart-Munich corridor hosts captive compounding operations serving premium EV architectures with carbon-fiber-reinforced variants.
United States
Detroit Three supplier networks and electrical infrastructure rollouts consume fire-retardant grades for EV charging enclosures and mass-transit interiors. EPA Clean Air Act Title V permitting governs styrene emissions from compounding facilities in Michigan and Ohio. The Great Lakes manufacturing belt retains compression molding expertise for Class-A body panel programs.
China
Domestic OEM lightweighting mandates and grid hardening investments are expanding SMC specification for closure panels and transformer housings. MIIT industrial standards and GB certification protocols shape resin formulation choices for electrical applications. The Yangtze River Delta concentrates compounding capacity serving automotive Tier-1 suppliers in Shanghai and Jiangsu.
Japan
Toray Group's domestic production bases supply carbon-fiber-reinforced variants for motorsport and aerospace secondary structures. METI carbon neutrality roadmaps are pressuring compounders to validate bio-based resin pathways and recycled fiber content. The Nagoya-Tokyo corridor integrates SMC with hybrid thermoplastic processes for industrial equipment housings.
India
Maruti Suzuki and Tata Motors supplier parks present greenfield specification opportunities as domestic OEMs lightweight entry-level platforms. BIS standards and PLI scheme incentives are attracting compounding investments near automotive clusters in Maharashtra and Gujarat. The Pune-Chennai corridor is emerging as a regional hub for electrical-grade formulations serving transformer and switchgear manufacturers.
Sheet Moulding Compound (SMC) Market Competitive Landscape
Concentration sits with vertically integrated compounders possessing in-house compression molding capability and multi-year platform contracts. The vendor base spans three tiers: global resin producers with captive SMC lines, independent compounders serving niche certification requirements, and regional fabricators competing on logistics proximity. Strategic moves center on backward integration into resin production and geographic expansion through joint ventures near emerging automotive clusters.
Among North American-based suppliers, Continental Structural Plastics Inc. and Core Molding Technologies exemplify the integrated compounder-molder archetype with captive supply chain control. Toray Group anchors the premium carbon-fiber-reinforced tier through Japanese and US production bases. IDI Composites International occupies a defensible position in custom-engineered formulations for electrical and corrosion-resistant applications above commodity grades.
| Leading Market Players |
|---|
| Continental Structural Plastics Inc. |
| Toray Group |
| IDI Composites International |
| Changzhou RealLand Composite Material Technology |
| Mitsui Chemicals |
| Menzolit |
| Core Molding Technologies |
| BMC Materials |
| Polynt Composites |
| Others |
Pricing and Supply Chain Analysis
Recycled carbon fiber substitution for virgin glass-reinforced grades is simultaneously redrawing compounding capacity maps across Germany, Japan, and the United States while compressing margin structures for conventional chopped-strand producers lacking secure fiber supply agreements.
Pricing Analysis
REACH substance evaluation protocols dictate the pricing tier structure across European supply bases, separating cobalt-free formulations from legacy grades facing ECHA-mandated phase-outs. Three-tier pricing structure across premium high-temperature vinyl ester, standard unsaturated polyester, and economy general-purpose grades reflects certification burden and fiber loading density. Cost compression in commodity general-purpose tiers is intensifying because benzene and ethylene feedstock volatility transmits directly to unsaturated polyester resin costs. Automotive OEM procurement teams exhibit lowest price sensitivity due to captive platform contracts, while mid-volume electrical distributors face acute margin pressure from spot resin markets.
Supply Chain Analysis
Inventory cycles for magnesium oxide thickeners have lengthened to 8-12 weeks as REACH restrictions force dual-sourcing validation across German and French compounders. Raw material supply concentrates in Germany, the United States, and Japan, with carbon fiber feedstock drawing from Toray Group's domestic and North Carolina production bases. Styrene monomer and chopped glass fiber dependencies create exposure to single-source petrochemical corridors through the US Gulf Coast and Rotterdam-Antwerp refining hubs. Logistics chokepoints at Bremerhaven and Long Beach container terminals compound lead-time uncertainty for Asian-sourced specialty additives. Distribution runs through direct platform contracts for automotive Tier 1 suppliers, with regional distributors serving fragmented electrical and industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation is accelerating as OEM qualification protocols splinter across fire-retardant UL tiers, high-temperature under-hood specifications, and recycled-content mandates, creating defendable niches for formulation specialists above commodity general-purpose grades.
For Market Incumbents: Shield multi-year platform contracts by accelerating backward integration into bio-based resin pathways ahead of EU CSRD alignment deadlines. Secure captive recycled carbon fiber supply agreements before BMW and Jaguar Land Rover volume targets harden into binding procurement clauses. Expand compression molding capacity in the Pune-Chennai corridor to capture Tata Motors and Maruti Suzuki lightweighting programs before greenfield compounders establish local qualification relationships. For New Entrants and Emerging Players: UL 94 V-0 fast-track certification for halogen-free electrical grades offers the most penetrable entry point, as EV charging infrastructure rollouts in California, Texas, and Germany compress design-to-production timelines versus 18-24 month automotive body panel qualifications. Target transformer housing and busbar support applications where dielectric performance requirements exceed cosmetic finish standards. Pursue joint venture structures with established regional distributors to bypass direct OEM procurement barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed compounders possessing captive compression molding infrastructure but lacking carbon fiber formulation portfolios or Asian geographic exposure. Five-to-ten year viability hinges on successful navigation of REACH thickener restrictions and thermoplastic substitution pressure from long-fiber-reinforced polypropylene. Monitor German automotive supplier dual-sourcing announcements as the inflection indicator for alternative cure chemistry validation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Resins | CSRD alignment creates first-mover advantage for compounders with verified renewable content pathways. |
| Carbon Fiber SMC Capacity Expansion | Toray Group's supply constraints open windows for entrants with secure recycled fiber agreements. |
| Joint Venture in Maharashtra-Gujarat Corridor | PLI scheme incentives and BIS standard convergence attract compounding investments near Tata Motors clusters. |
| Alternative Cure Chemistry Validation | ECHA's rolling action plan on cobalt promoters forces reformulation R&D across European supply bases. |
| Combined SMC/DLFT Press Line Installation | Equipment convergence in Michigan and Ontario offers OEMs material flexibility within single tooling investments. |
Research Methodology
Initial hypotheses were tested against primary input from SMC plant managers, automotive Tier 1 procurement leads, electrical infrastructure procurement officers, and resin R&D directors, then refined against customs trade data, ACC and Cefic industry reports, SEC 10-K filings from listed compounders, and vehicle production databases. Bottom-up volume estimates from country-level compounding capacity were triangulated with top-down demand projections derived from OEM lightweighting target disclosures and grid hardening investment announcements.
Variance decomposition across product type, end-use industry, regional production hub, and certification tier shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by value-per-ton differentials across general-purpose, fire-retardant, and high-temperature grades. Industry-specific forecast inputs included EU fleet CO₂ mandate compliance curves and EV charging station deployment schedules across California, Texas, and Germany.
Decision-makers should treat outputs as directional under assumptions of sustained automotive lightweighting mandates and stable REACH enforcement timelines; material deviation in petrochemical feedstock costs or thickener regulatory scope would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Opacifiers Market
Specialty Compounds
Collagen Hydrolysates Market
Specialty Compounds
Argan Oil Market
Specialty Compounds
Latin America Hydroxypropyl Methylcellulose Market
Specialty Compounds
Lauramidopropyl Betaine Market
Specialty Compounds
Global Acetyls Market
Specialty Compounds
Neohespiridine Market
Specialty Compounds
Potassium Monopersulfate (KMPS) Market
Specialty Compounds
Lithopone Market
Specialty Compounds
North America Polyphenylene Sulfide Compounds Market
Specialty Compounds
Filler Masterbatch Market
Specialty Compounds
Toner Resins Market
Specialty Compounds
Global Specialty Amines Market
Specialty Compounds
Middle East and Africa Polypropylene Compounds Market
Specialty Compounds
Silicone Masterbatches Market
Specialty Compounds
GCC Specialty Chemicals Market