
 Global Cyanate Ester Resins Market | 2026-2036
Global Cyanate Ester Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cyanate Ester Resins Market Foresight
China is reconfiguring regional supply dynamics through expanded domestic prepreg and resin synthesis capacity. Huntsman International LLC leverages its integrated Bisphenol E and M backbone chemistry to sustain North American aerospace qualification pipelines. Hexcel Corporation anchors downstream demand through captive prepreg operations serving Tier 1 airframers. Solvay competes in European high-temperature laminates by controlling proprietary toughening additive technology.
Cyanate ester resins are thermosetting polymers formed by cyanate functional group trimerization into triazine networks, delivering glass transition temperatures exceeding 250°C and dielectric constants below 3.0 for extreme thermal and electrical environments. These properties position them as matrix materials in structural composites and interlayer dielectrics where epoxy systems fail. Thermosetting resins occupy the largest volume share due to established qualification in military airframes and satellite bus structures. Prepregs represent the fastest-expanding format as automated fiber placement adoption rises in commercial aerospace. Electronic packaging applications concentrate margin pools where low-loss dielectric performance commands specification premiums in 5G base station substrates and advanced semiconductor substrates.
FDA oversight of medical device composites, EPA emissions controls on solvent-based processing, and REACH substance restrictions on residual cyanate monomers collectively elevate formulation and handling compliance costs. ECHA hazard classification updates for unreacted cyanate groups are forcing reformulation investments across European resin producers. Manufacturers must monitor regulatory divergence between EPA risk evaluations and REACH authorization timelines while positioning low-monomer product lines for dual-jurisdiction qualification.
Market Dynamics
Automated fiber placement technology is compressing qualification timelines for cyanate ester prepregs, forcing resin producers to synchronize formulation stability with real-time manufacturing data feeds from Tier 1 airframer production lines.
Growth Catalysts
- EU Green Deal carbon-neutrality mandates:European aerospace OEMs are rewriting material specifications to favor low-cure-energy thermosets, pulling cyanate esters into wingbox and empennage structures previously reserved for epoxies.
- China's domestic satellite constellation deployment:State-funded programs are absorbing high-purity resin volumes for bus structures and antenna substrates, creating dedicated supply corridors bypassing traditional export channels.
- 5G base station substrate demand:Low-loss dielectric requirements in millimeter-wave infrastructure are displacing PTFE laminates with cyanate ester-based alternatives in Huawei and Ericsson qualification pipelines.
Market Restraints
- Bisphenol E feedstock concentration:North American synthesis capacity for the backbone monomer remains captive to two integrated chemical complexes, exposing formulators to single-source disruption risk.
- Residual cyanate monomer toxicity:ECHA hazard classification updates for unreacted functional groups are forcing reformulation investments that extend European product requalification cycles by 18-24 months.
- Polyimide substitution in extreme thermal zones:Engine nacelle applications above 300°C service temperature are migrating toward thermoplastic polyimide matrices despite higher processing costs.
Strategic Opportunities
- India's PLI scheme for defense aerospace:Domestic composite airframe programs are creating first-mover advantages for resin suppliers establishing local blending and qualification facilities.
- Semiconductor advanced packaging convergence:Hybrid bonding and chiplet architectures are merging thermal management with dielectric performance requirements that cyanate ester laminates uniquely satisfy.
- Japan's METI carbon fiber recycling mandates:Thermoset matrix technologies compatible with solvolysis recovery processes are gaining preferential specification in closed-loop manufacturing contracts.
Industry Challenges
- Cure kinetics modeling expertise scarcity:Formulators lack sufficient simulation talent to predict triazine network formation across variable humidity and pressure conditions in out-of-autoclave processing.
- Multi-jurisdiction certification parallelism:Simultaneous FAA, EASA, and CAAC qualification for a single prepreg grade requires duplicative testing protocols that strain R&D bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cyanate Ester Resins Market |
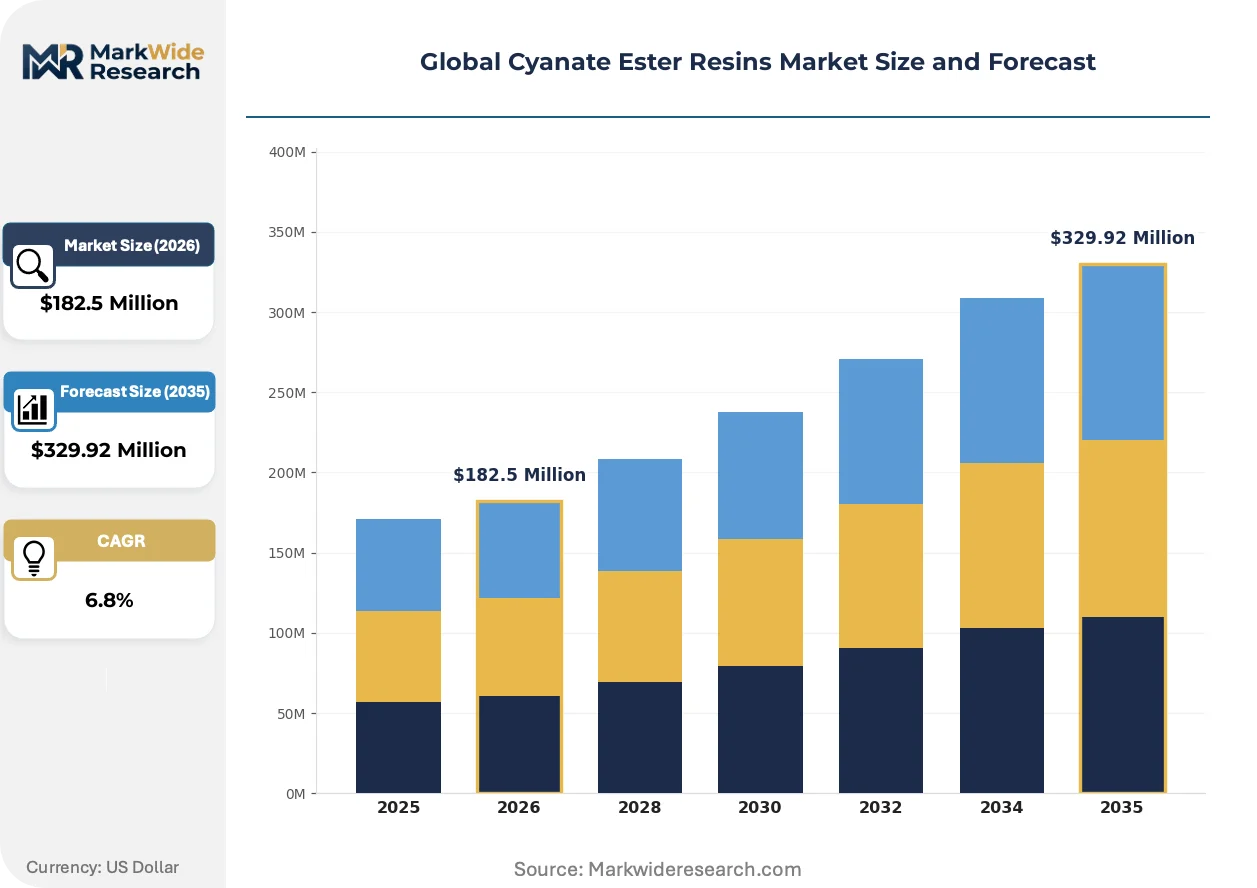
| Market Size in 2026 | $182.5 Million |
| Market Size in 2035 | $329.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermosetting Resins, Prepregs, Adhesives, Composite Materials Technology: Electrochemical, Thermal Curing, UV Curing, Radiation Curing Application: Aerospace Components, Electronic Packaging, Automotive Parts, High-Performance Coatings End User Industry: Semiconductor Manufacturing, Defense Equipment, Marine Engineering, Telecommunications |
| Companies Covered | Huntsman International LLC, Hexcel Corporation, Toray Advanced Composites, MITSUBISHI GAS CHEMICAL COMPANY, INC, Solvay, Henkel AG & Company, Lonza, Gurit, TenCate Advanced Composites, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cyanate Ester Resins Market Shifts & Advancements
Real-time rheology monitoring and predictive cure modeling are collapsing development cycles for high-temperature thermosets, compressing the traditional 5-7 year airframe qualification pathway into 3-4 year windows.
Digital twin process simulation is digitizing how resin formulators validate cure cycle robustness. Tier 1 suppliers are embedding sensor-fed models into production environments to anticipate exotherm peaks and residual stress formation. The technology is digitizing quality assurance protocols that previously required destructive testing of full-scale articles.
REACH authorization timelines for residual cyanate monomers are forcing European producers toward closed-loop synthesis designs. ECHA's evolving hazard classifications are triggering capital allocation toward low-monomer product lines that preempt regulatory friction. Aerospace laminates bearing the CE marking are migrating fastest toward these reformulated grades to maintain EU market access.
Consolidated procurement by Chinese state-owned satellite manufacturers is displacing fragmented distributor networks with direct long-term supply agreements. Domestic resin blenders are capturing volume through captive relationships with CAST and CASC subsidiaries. This concentration is most visible in Shanghai and Xi'an manufacturing clusters where prepreg qualification runs directly feed constellation production schedules.
Global Cyanate Ester Resins Market Segmentation
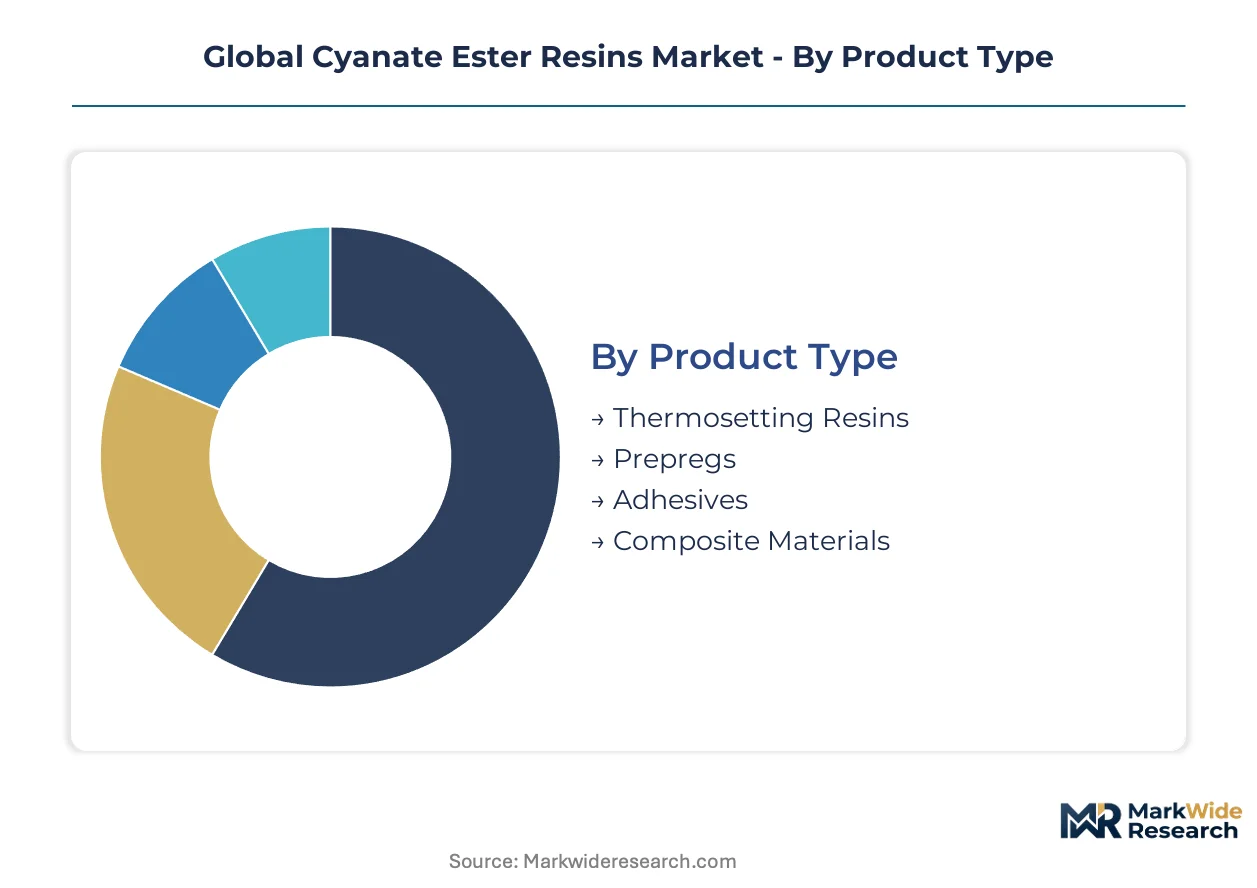
Cyanate ester resin specifications diverge sharply across curing platforms and end-use thermal requirements. Segmentation reveals how aerospace qualification pipelines, semiconductor packaging tolerances, and defense procurement cycles each dictate distinct formulation priorities and margin structures.
Product Type:
Volume concentration tracks directly against qualification maturity and downstream integration depth.
- Thermosetting Resins:These base polymers form triazine networks through cyanate trimerization, delivering glass transition temperatures above 250°C. Military airframe programs and satellite bus structures in the United States and China absorb the bulk of qualified volumes, with procurement tied to FAA and CAAC certification timelines.
- Prepregs:Resin-impregnated fiber sheets enable automated fiber placement in commercial aerospace manufacturing. Tier 1 airframers in Germany and Japan are compressing qualification windows from five years to three through real-time rheology monitoring, pulling prepregs into wingbox applications previously reserved for epoxies.
- Adhesives:Structural bonding formulations serve repair and assembly operations in marine engineering and defense equipment.
- Composite Materials:Finished laminates integrate cyanate ester matrices with carbon fiber reinforcements for radomes and antenna substrates.
Thermosetting resins hold installed capacity. Prepregs are rotating up the share rankings.
Technology:
Platform selection hinges on cure cycle energy requirements and out-of-autoclave processing feasibility.
- Thermal Curing:Conventional heat-activated triazine formation dominates aerospace qualification databases. European OEMs under EU Green Deal mandates are favoring lower-cure-energy variants to reduce autoclave energy intensity in wingbox production.
- UV Curing:Photoinitiated polymerization enables rapid processing for electronic packaging laminates. Semiconductor substrate manufacturers in South Korea and Taiwan are adopting UV platforms for 5G base station dielectrics where throughput trumps thermal performance.
- Electrochemical:Niche deposition methods serve specialized coating applications with precise thickness control.
- Radiation Curing:Electron beam processing accommodates temperature-sensitive substrates in advanced packaging.
Thermal curing anchors current aerospace specifications. UV curing is climbing the fastest as millimeter-wave infrastructure deployment accelerates.
Application:
End-use thermal and dielectric specifications partition the market into distinct margin tiers.
- Aerospace Components:Structural composites for empennage, wingbox, and satellite bus structures demand the highest purity grades. China's domestic constellation programs are absorbing dedicated supply corridors through CAST and CASC procurement channels, bypassing traditional export distributors.
- Electronic Packaging:Low-loss dielectric substrates for 5G infrastructure and advanced semiconductor packages command specification premiums. Huawei and Ericsson qualification pipelines are displacing PTFE laminates with cyanate ester alternatives in millimeter-wave base stations.
- Automotive Parts:Underhood thermal management applications remain limited by cost-positioning against polyimides.
- High-Performance Coatings:Protective formulations serve industrial equipment requiring chemical resistance and thermal stability.
Aerospace components retain qualification depth. Electronic packaging is gaining share fastest on semiconductor convergence trends.
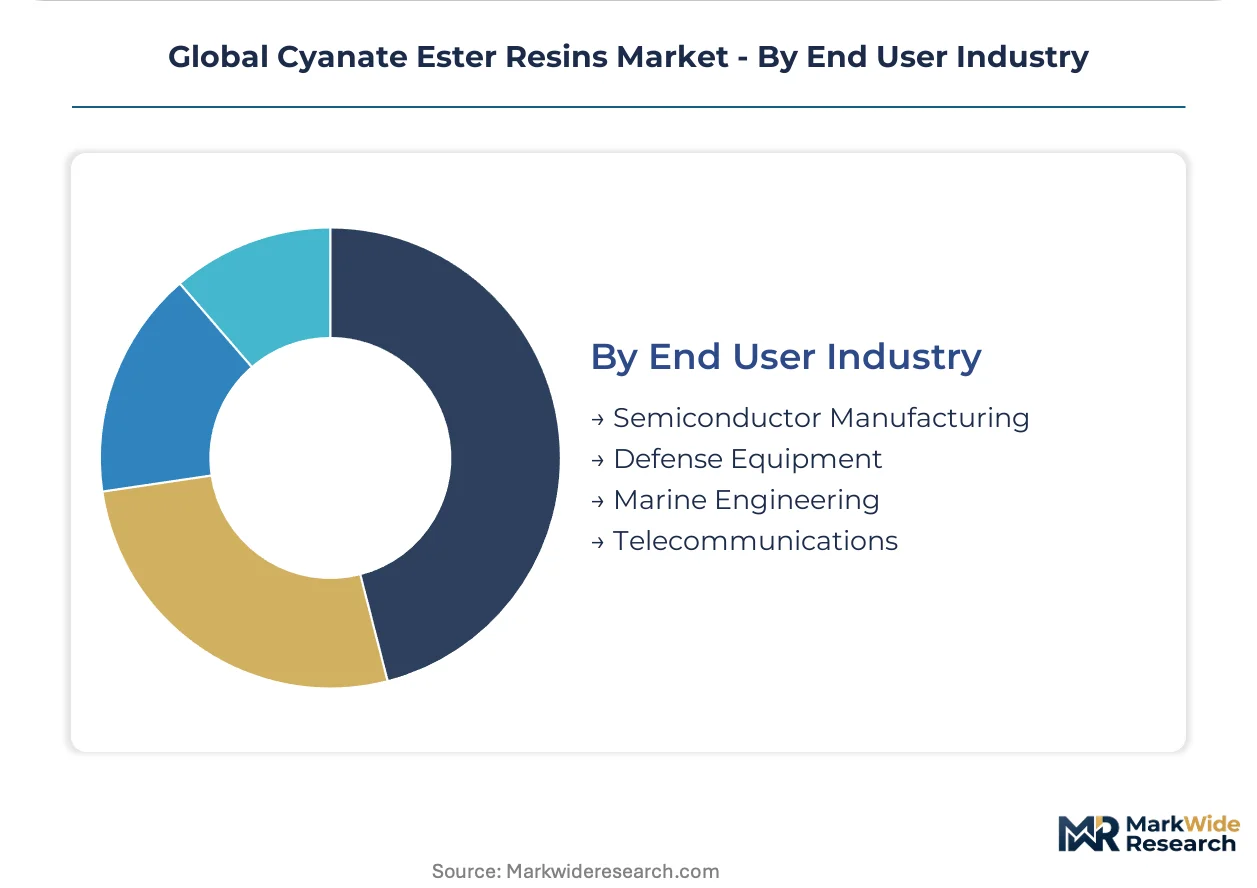
End User Industry:
Procurement concentration varies sharply between state-funded programs and commercial volume markets.
- Semiconductor Manufacturing:Advanced packaging and substrate applications merge thermal management with dielectric performance requirements. Hybrid bonding and chiplet architectures in Japan and the United States are creating specification pull for cyanate ester laminates that satisfy both functions.
- Defense Equipment:Military airframe and radar dome programs sustain qualified resin volumes through multi-year procurement cycles. India's PLI scheme for defense aerospace is creating first-mover opportunities for suppliers establishing local blending facilities.
- Telecommunications:5G infrastructure deployment drives dielectric substrate demand across base station supply chains.
- Marine Engineering:Structural composites for naval vessels and offshore platforms require moisture-resistant matrix systems.
Defense equipment holds program longevity. Semiconductor manufacturing is rotating up the share rankings on packaging technology convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated chemical complexes in the United States and Germany control backbone monomer synthesis for cyanate ester formulations. China and Japan are expanding captive prepreg capacity to serve satellite constellation and semiconductor packaging demand. India's defense procurement programs are attracting first-mover resin suppliers establishing local blending facilities.
United States
FAA qualification timelines for commercial airframe prepregs sustain demand for high-purity thermosetting resins. EPA emissions controls on solvent-based processing elevate compliance costs for formulators serving military aerospace programs. Huntsman International LLC anchors North American supply through integrated Bisphenol E and M backbone chemistry in Texas and Louisiana manufacturing corridors.
Germany
Tier 1 airframers in Hamburg and Munich are compressing qualification windows through automated fiber placement adoption. EU Green Deal carbon-neutrality mandates favor lower-cure-energy thermosets for wingbox and empennage structures. The Stuttgart industrial cluster hosts formulation facilities supplying prepreg operations across European aerospace supply chains.
China
State-funded satellite constellation programs through CAST and CASC subsidiaries absorb dedicated high-purity resin volumes for bus structures and antenna substrates. MIIT domestic carbon fiber mandates accelerate captive prepreg capacity expansion in Shanghai and Xi'an manufacturing clusters. Domestic resin blenders are displacing traditional export channels through direct long-term supply agreements.
Japan
METI carbon fiber recycling mandates favor thermoset matrix technologies compatible with solvolysis recovery processes. Semiconductor substrate manufacturers in Osaka and Nagoya are adopting UV curing platforms for 5G base station dielectrics. Toray Advanced Composites anchors downstream integration through captive prepreg operations serving regional aerospace qualification pipelines.
India
PLI scheme incentives for defense aerospace are creating procurement pull for structural composite airframe programs. BIS material specifications for military applications require localized qualification testing that extends product approval cycles. Karnataka and Maharashtra industrial corridors are attracting resin suppliers establishing blending and qualification facilities to capture first-mover advantages.
Global Cyanate Ester Resins Market Competitive Landscape
Integrated chemical conglomerates and specialized composite material suppliers split the market through differentiated control of backbone synthesis versus downstream prepreg integration. Three strategic archetypes dominate competitive positioning: integrated monomer-to-prepreg operators, captive aerospace qualification specialists, and regional formulation blenders serving state-funded programs. Capacity expansion and strategic technology licensing represent the dominant competitive moves as players synchronize formulation stability with automated manufacturing data feeds.
Within the integrated chemical tier, Huntsman International LLC and Solvay exemplify archetypes combining backbone monomer synthesis with aerospace qualification depth. Hexcel Corporation occupies a position as a captive prepreg specialist leveraging downstream integration to anchor Tier 1 airframer relationships. Among Asia-Pacific-based operators, MITSUBISHI GAS CHEMICAL COMPANY, INC represents the regional formulation archetype serving semiconductor packaging convergence trends.
| Leading Market Players |
|---|
| Huntsman International LLC |
| Hexcel Corporation |
| Toray Advanced Composites |
| MITSUBISHI GAS CHEMICAL COMPANY, INC |
| Solvay |
| Henkel AG & Company |
| Lonza |
| Gurit |
| TenCate Advanced Composites |
| Others |
Supply & Pricing Matrix
Shanghai-Xi'an rail freight corridors carry Bisphenol E feedstock from coastal synthesis hubs to inland prepreg facilities, with transport cost volatility amplifying price spreads between aerospace-qualified grades and standard industrial formulations. This logistics architecture concentrates margin capture among integrated operators while forcing independent blenders to absorb tariff exposure on imported backbone monomers.
Pricing Analysis
REACH authorization timelines dictate the pricing tier structure across European supply chains, separating low-monomer reformulated grades from legacy formulations facing regulatory sunset. Pricing stratifies across aerospace-qualified, industrial-standard, and economy blending tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in industrial-tier resins is intensifying because Chinese domestic producers are flooding satellite program procurement channels. Defense aerospace buyers exhibit lowest price sensitivity, while electronics packaging converters face acute margin pressure from PTFE laminate competition.
Supply Chain Analysis
Toray Advanced Composites and Hexcel Corporation hold captive prepreg capacity serving Tier 1 airframer qualification pipelines. Geographic concentration centers on the United States, China, and Germany, with backbone monomer synthesis anchored in Texas and Louisiana chemical corridors. Raw material dependencies rest on Bisphenol E and M feedstocks, cyanuric chloride activators, and high-purity solvents. Single-source vulnerability pervades North American Bisphenol E supply, where two integrated complexes control domestic availability. Distribution runs through direct long-term agreements with state-funded satellite manufacturers and aerospace OEM qualification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities are expanding as semiconductor packaging convergence splits demand between thermal-management-focused and dielectric-performance-focused formulation niches. This demand-side divergence creates specialized supply corridors that favor focused players over generalist resin suppliers.
For Market Incumbents: Entrench aerospace qualification depth through accelerated FAA-EASA-CAAC parallel certification investments, defending against polyimide substitution in engine nacelle applications above 300°C. Pursue backward integration into Bisphenol E synthesis capacity to neutralize single-source feedstock risk. Channel control through embedded technical service teams at Tier 1 airframer production lines sustains formulation stability requirements for automated fiber placement adoption. For New Entrants and Emerging Players: Pursue India's defense aerospace PLI scheme corridors, where localized BIS qualification testing creates 18-24 month first-mover windows before incumbent replication. The semiconductor advanced packaging segment in Japan and South Korea offers penetrable white space, with hybrid bonding architectures merging thermal and dielectric requirements that cyanate ester laminates uniquely satisfy. A go-to-market angle targeting UV curing platform adoption for 5G base station substrates bypasses entrenched thermal curing qualification barriers. For Investors and Strategic Acquirers: Regional formulation blenders with captive state-funded relationships in China represent the priority acquisition archetype, given CAST and CASC procurement consolidation displacing traditional distributor networks. Long-term viability across the analysis window hinges on solvolysis-compatible matrix technologies gaining preferential specification under Japan's METI carbon fiber recycling mandates. Monitor ECHA hazard classification updates for unreacted cyanate monomers as the inflection signal forcing accelerated reformulation capital deployment across European supply chains. Quarterly review of CAAC qualification pipeline progress and MIIT domestic carbon fiber mandate implementation is advised to detect inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bisphenol E Synthesis | Huntsman International LLC's integrated Texas-Louisiana corridors neutralize single-source disruption risk for North American formulators. |
| Low-Monomer Product Line Expansion | REACH authorization timelines force European producers toward reformulated grades maintaining EU market access for aerospace laminates. |
| Local Blending Facility Establishment | India's Karnataka and Maharashtra industrial corridors attract resin suppliers capturing PLI scheme procurement pull for defense airframe programs. |
| UV Curing Platform Qualification | South Korean and Taiwanese semiconductor substrate manufacturers adopt photoinitiated polymerization for 5G base station dielectric throughput. |
| Closed-Loop Synthesis Design Investment | ECHA hazard classification updates trigger capital allocation toward preemptive regulatory compliance in European resin production. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings from integrated chemical conglomerates. Primary interviews engaged plant managers at backbone monomer synthesis facilities, procurement leads at Tier 1 aerospace OEMs, technical R&D directors at prepreg operations, and distribution channel partners serving satellite program supply chains. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators to validate volume and value estimates.
Forecast inputs include aerospace qualification pipeline timelines, semiconductor packaging technology roadmaps, and regulatory authorization schedules across FAA, EASA, and CAAC jurisdictions. Segmentation dimensions span curing platform, application thermal requirements, end-use industry procurement concentration, and regional production hub configuration. CAGRs derive from fitted growth curves calibrated to historical qualification cycle compression and automated manufacturing adoption rates. Industry-specific inputs incorporate carbon fiber recycling mandate implementation trajectories and 5G infrastructure deployment schedules.
Sensitivities concentrate around ECHA regulatory timeline acceleration, Chinese state-funded program budget reallocations, and polyimide technology cost reduction curves. Forecasts reflect documented assumptions on cure kinetics modeling expertise availability and multi-jurisdiction certification parallelism strain. Quarterly review of prepreg qualification pipeline throughput, satellite constellation launch schedules, and REACH authorization progression is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
BPA-Free Epoxy Resins Market
Polymers & Resins
Vinyl Acetate Ethylene Copolymer Powder Market
Polymers & Resins
Emulsion PVC Market
Polymers & Resins
High-Purity Epoxy Resin Market
Polymers & Resins
Macroporous Strong Acid Cation Exchange Resin Market
Polymers & Resins
Polyvinyl Butyral (PVB) Resins Market
Polymers & Resins
Polyvinyl Butyral (PVB) Market
Polymers & Resins
Nylon Resins Market
Polymers & Resins
APAC Polyethylene Terephthalate Market
Polymers & Resins
BMI Resins Market
Polymers & Resins
Polyvinyl Chloride Resins Market
Polymers & Resins
Modified Alkyd Resin Market
Polymers & Resins
Hybrid Polymer Market
Polymers & Resins
North America Super Absorbent Polymers (SAP) Market
Polymers & Resins
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market
Polymers & Resins
Bio-Based and Synthetic Polyamide Market