
 United States Geopolymer Market | 2026-2036
United States Geopolymer Market Size, Share, and Industry Trends Forecast 2026-2036
United States Geopolymer Market Intelligence
Performance-based specification consulting is expanding how geopolymer suppliers monetize expertise beyond bulk material sales. Geopolymer Solutions LLC leverages its Gulf Coast project portfolio to anchor regional specification authority. BASF SE sustains R&D intensity across alkali-activated binder chemistries for precast applications. Wagners Holding Company dominates transportation infrastructure contracts through its integrated testing and certification services.
Geopolymers are inorganic aluminosilicate binders formed by alkali activation of metakaolin, fly ash, or slag at ambient to moderate temperatures, yielding ceramic-like matrices with compressive strengths exceeding 50 MPa and fire resistance above 1000°C. Their primary purpose is to replace Portland cement in structural concrete, thermal insulation, and hazardous waste encapsulation where chemical stability and reduced embodied carbon are specified. Concrete products command the largest share of current shipments, while coatings for steel fireproofing represent the fastest-expanding margin pool due to stringent ASTM E119 testing requirements. Building materials applications lead volume, though waste management segments for nuclear and heavy-metal stabilization are deepening specification stickiness through EPA Treatment Standards for Hazardous Waste.
EPA enforcement of Resource Conservation and Recovery Act standards directly shapes geopolymer demand for hazardous waste solidification, while ASTM International and ACI Committee 239 govern material qualification for structural acceptance. State departments of transportation in California, Texas, and New York now embed lifecycle carbon thresholds into pavement and bridge procurement, effectively mandating alternative binder verification. Stakeholders must monitor whether federal Buy America provisions expand to cover alkali activator chemicals and whether emerging state low-carbon concrete codes trigger specification fragmentation across jurisdictions.
Market Dynamics
State-level low-carbon procurement mandates are compressing specification timelines for federal and municipal infrastructure contracts, forcing rapid validation of alkali-activated binder performance against legacy Portland cement baselines.
Growth Catalysts
- EPA Treatment Standards for Hazardous Waste:Enforcement of Resource Conservation and Recovery Act provisions is mandating geopolymer solidification for heavy-metal and nuclear waste streams, locking in multi-year offtake agreements.
- Texas coastal resilience standards:Thermal barrier and chloride resistance specifications for Gulf Coast infrastructure are accelerating material substitution in bridge decks and marine piles.
- Fly ash beneficiation:Advanced classification and carbon-removal technologies are stabilizing aluminosilicate precursor quality, reducing batch-to-batch binder variability.
Market Restraints
- Sodium silicate supply concentration:Domestic alkali activator production clusters in the Gulf Coast chemical corridor, exposing buyers to hurricane-related supply interruptions.
- ASTM E119 certification timeline:Fireproofing coating qualification requires 12-18 month testing cycles, delaying revenue recognition for new formulations.
- Precast concrete substitution:Ultra-high-performance concrete with reduced clinker content competes for structural rehabilitation budgets in Midwest transportation departments.
Strategic Opportunities
- California Department of Transportation lifecycle carbon thresholds:Embedded carbon mandates in pavement procurement are creating first-mover advantage for verified low-carbon binder suppliers.
- Steel fireproofing coatings:ASTM E119 compliance for commercial high-rise construction represents underpenetrated specification territory outside traditional concrete applications.
- Digital twin integration:Coupling geopolymer mix design with predictive curing analytics is enabling performance-guaranteed contracting models for federal highway rehabilitation.
Industry Challenges
- ACI Committee 239 certification backlog:Structural engineer licensure for alkali-activated materials lags specification demand, constraining project execution capacity.
- Precursor logistics reconfiguration:Fly ash and slag sourcing from retired coal plants requires new rail and barge networks, complicating just-in-time delivery for megaprojects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Geopolymer Market |
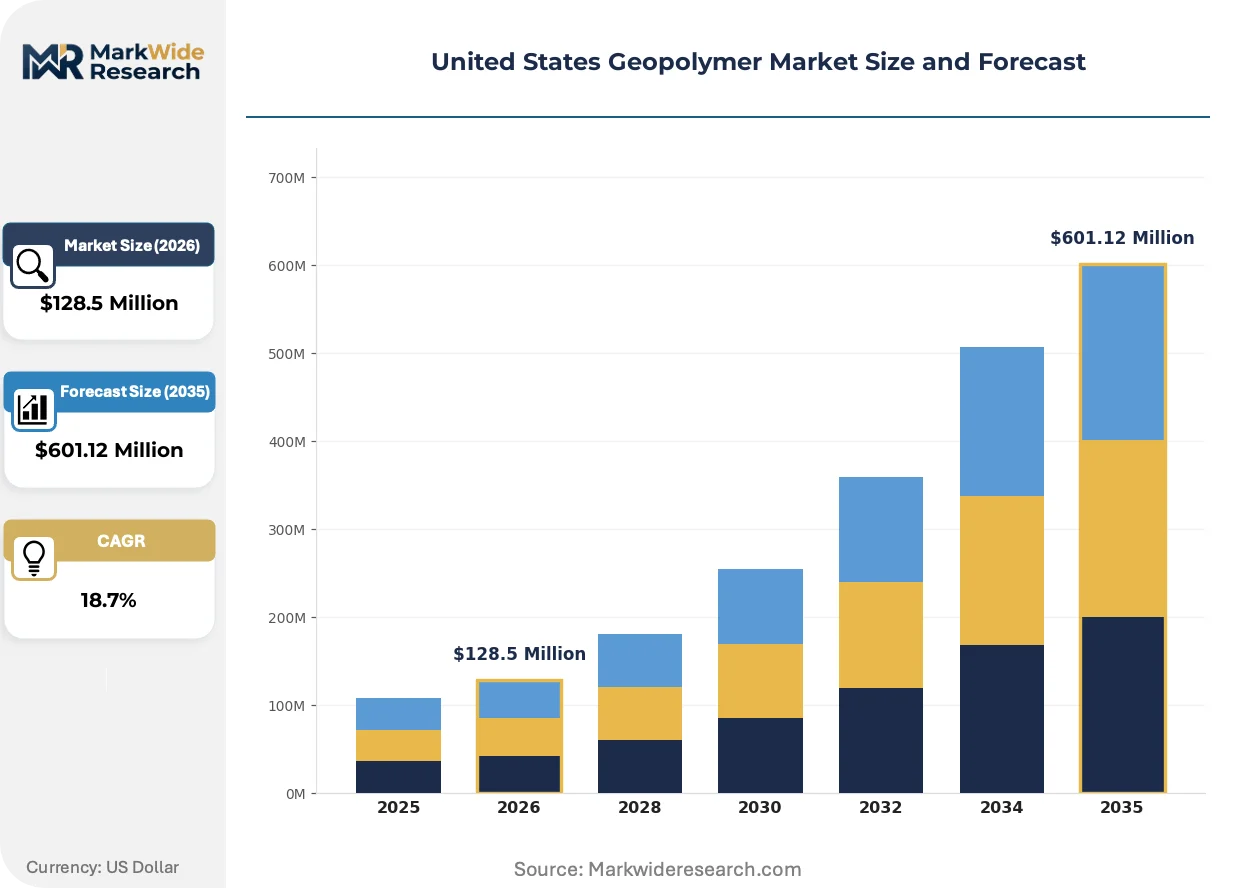
| Market Size in 2026 | $128.5 Million |
| Market Size in 2035 | $601.12 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concrete, Adhesives, Coatings, Mortars End Use Industry: Construction, Automotive, Aerospace, Electrical Form: Powder, Liquid, Granule, Pellet Application: Building Materials, Insulation, Waste Management, Fireproofing |
| Companies Covered | BASF SE, PCI Augsburg GmbH, Geopolymer Solutions LLC, Imerys S.A., Zeobond Pty Ltd., Schlumberger Limited, Wagners Holding Company, Milliken & Company Inc., CEMEX S.A.B. de C.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Geopolymer Market Strategic Shifts & Innovations
Alkali-activated binder chemistry is converging with digital manufacturing controls, compressing the gap between laboratory formulation and field-scale reliability. Three developments are restructuring competitive advantage.
Self-consolidating geopolymer mixes with rheology-modifying admixtures are automating placement in complex formwork geometries. Transportation infrastructure contractors in Florida and Texas are specifying these formulations for segmental bridge construction. The technology is automating quality assurance workflows, reducing on-site testing labor by embedding sensors directly into precast elements.
The EPA's enforcement posture under the Resource Conservation and Recovery Act is tightening hazardous waste solidification requirements. Industrial waste generators in Ohio and Pennsylvania must now document long-term leach resistance beyond legacy cement-based treatments. Nuclear decommissioning projects at Department of Energy sites are driving specification for chemically optimized metakaolin blends with 90-day strength verification protocols.
Performance-based contracting is displacing conventional material procurement in federal highway rehabilitation. State departments of transportation in California, New York, and Texas now tie contractor payment to 20-year durability metrics rather than per-ton material delivery. This model concentrates risk with suppliers capable of integrated testing and certification services, favoring vertically integrated regional players over commodity distributors.
United States Geopolymer Market Segmentation
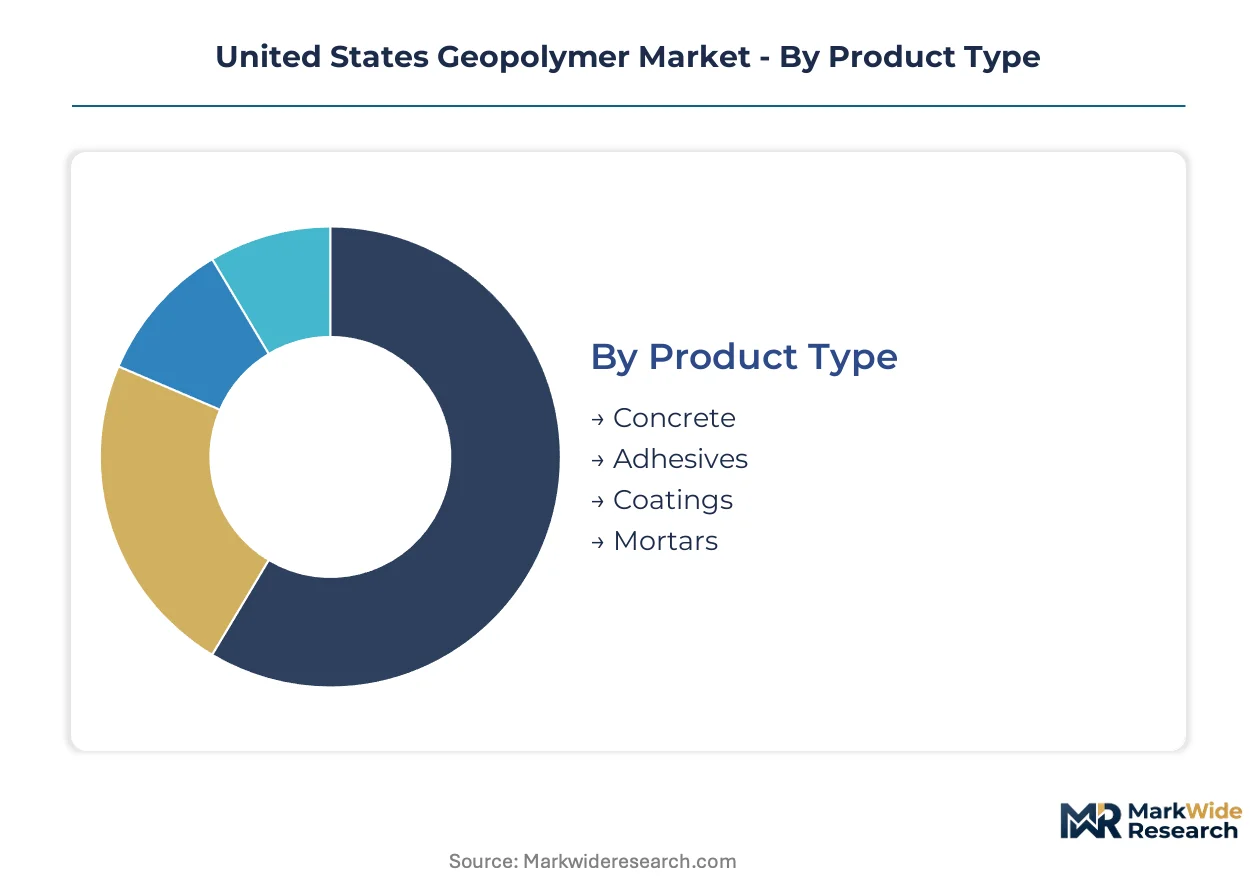
Geopolymer procurement decisions hinge on specification-grade performance validation rather than commodity pricing, forcing suppliers to align product architectures with distinct end-use certification pathways. Segmentation reveals how alkali-activated binders fragment across construction methodologies, industrial safety mandates, and precursor delivery formats.
Product Type:
Specification complexity and installation labor intensity drive buyer selection between bulk structural applications and precision-applied systems.
- Concrete:Bulk structural mixes incorporating fly ash or slag precursors deliver compressive strengths exceeding 50 MPa for bridge decks and marine piles. Texas and Florida departments of transportation specify these formulations for coastal infrastructure where chloride resistance thresholds exceed Portland cement capabilities.
- Coatings:Thin-film fireproofing systems for commercial steel structures require 12-18 month ASTM E119 certification cycles but command premium margins in high-rise construction. Demand concentrates in California and New York where building codes mandate enhanced thermal barrier performance.
- Adhesives:Bonding agents for precast segmental construction enable rapid assembly of transportation infrastructure components.
- Mortars:Repair-grade formulations target spall remediation in federal highway rehabilitation contracts across the Midwest.
Volume sits with Concrete; growth tilts toward Coatings.
End Use Industry:
Regulatory enforcement intensity and project scale separate high-volume infrastructure buyers from specialized industrial adopters.
- Construction:Public works agencies in California, Texas, and Florida embed lifecycle carbon thresholds into pavement and bridge procurement, mandating alternative binder verification. Federal highway rehabilitation contracts now tie payment to 20-year durability metrics rather than per-ton delivery.
- Waste Management:EPA Treatment Standards for Hazardous Waste under RCRA provisions mandate geopolymer solidification for heavy-metal and nuclear streams. Ohio and Pennsylvania industrial generators must document long-term leach resistance beyond legacy cement treatments.
- Automotive:Lightweight panel applications for electric vehicle thermal management remain pre-commercial.
- Aerospace:Fire-resistant interior components face qualification barriers from FAA certification timelines.
- Electrical:Encapsulation formulations for high-voltage infrastructure gain specification in utility transmission projects.
Construction commands current volume; Waste Management expands most quickly on regulatory lock-in.
Form:
Logistics economics and batch-to-batch consistency requirements determine whether buyers accept field-mixing complexity or pay premiums for pre-processed delivery.
- Powder:Dry aluminosilicate precursors blended with alkali activators at point-of-use dominate precast concrete operations. Fly ash beneficiation technologies are stabilizing precursor quality, reducing variability in Texas and Florida transportation contracts.
- Liquid:Pre-activated sodium silicate solutions enable rapid deployment in hazardous waste solidification where EPA documentation requirements demand predictable setting behavior.
- Granule:Intermediate processing formats suit remote construction sites lacking batching infrastructure.
- Pellet:Densified forms reduce shipping costs for nuclear decommissioning projects at Department of Energy sites requiring 90-day strength verification protocols.
Powder retains volume leadership; Liquid gains share fastest where field quality assurance is constrained.
Application:
Performance guarantee structures and specification stickiness separate recurring maintenance budgets from one-time capital deployments.
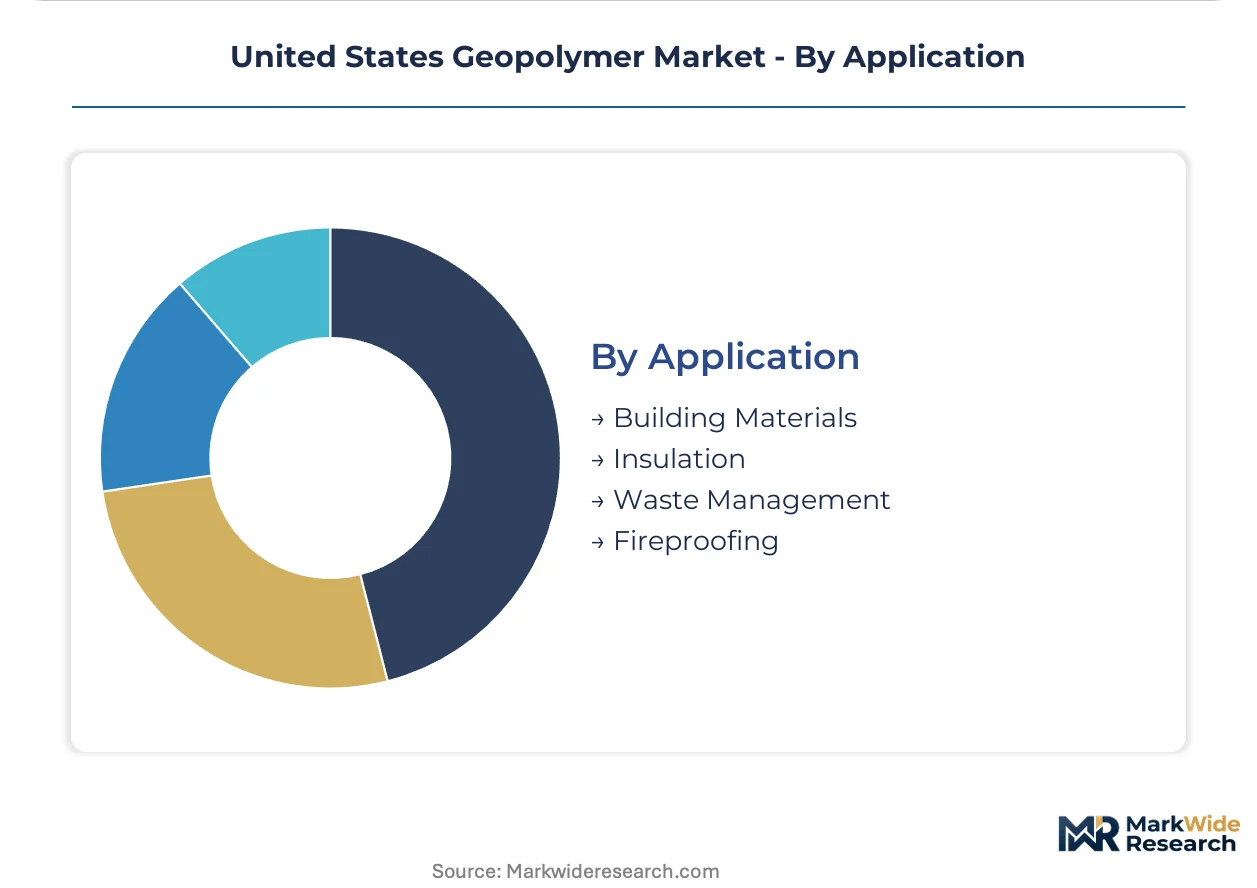
- Building Materials:Structural concrete and masonry units for commercial and residential construction represent the largest current shipment category. State low-carbon procurement mandates in California and New York are accelerating material substitution in public building projects.
- Fireproofing:Steel coating applications for commercial high-rise construction represent underpenetrated specification territory with steep margin profiles. ASTM E119 compliance requirements create defensive moats for qualified suppliers.
- Insulation:Thermal barrier boards for industrial process equipment face competition from mineral wool in cost-sensitive retrofit markets.
- Waste Management:Nuclear and heavy-metal stabilization applications deepen specification stickiness through EPA Treatment Standards, locking in multi-year offtake agreements with limited supplier mobility.
Building Materials anchor current volume; Fireproofing climbs the fastest on code-driven specification expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston-Galveston chemical corridor anchors domestic geopolymer production through concentrated sodium silicate manufacturing and Gulf Coast precursor processing infrastructure.
Texas
Coastal resilience standards for bridge decks and marine piles drive specification intensity along the Gulf Coast. Texas Department of Transportation mandates chloride resistance thresholds that exceed Portland cement capabilities in Corpus Christi and Houston port districts. Fly ash beneficiation facilities in the East Texas rail corridor stabilize aluminosilicate quality for transportation contracts.
California
Lifecycle carbon thresholds embedded in Caltrans pavement procurement accelerate alternative binder verification. EPA Region 9 enforcement of hazardous waste solidification requirements locks in geopolymer demand from industrial generators in the Central Valley. Los Angeles and San Francisco high-rise construction codes mandate ASTM E119 thermal barrier performance for steel fireproofing coatings.
Florida
Segmental bridge construction specifications in Miami-Dade and Tampa Bay metro areas automate placement through self-consolidating mix designs. Florida Department of Transportation thermal barrier requirements for coastal infrastructure intersect with hurricane resilience funding. Precast concrete operations in the Jacksonville port district embed sensors for automated quality assurance workflows.
Ohio
Industrial waste generators in the Ohio River Valley must document long-term leach resistance under tightened RCRA enforcement postures. Federal highway rehabilitation contracts across the Midwest specify repair-grade mortars for spall remediation. Cleveland and Cincinnati metropolitan planning organizations tie contractor payment to 20-year durability metrics rather than per-ton delivery.
New York
Building codes in New York City mandate enhanced thermal barrier performance for commercial steel structures. State procurement guidelines embed low-carbon concrete verification requirements into public works budgets. Buffalo and Rochester infrastructure agencies specify alkali-activated binders for freeze-thaw resistance in bridge deck rehabilitation.
United States Geopolymer Market Key Industry Players
Capital-heavy producers compete with asset-light specification consultants for margin capture across the value chain. The vendor base concentrates around integrated testing and certification services that reduce project execution risk for transportation agencies. Three strategic archetypes dominate: vertically integrated regional contractors with captive precursor supply, multinational chemical conglomerates with alkali activator production, and specialized solidification service providers for hazardous waste streams. Capacity expansion and performance-guaranteed contracting models represent the dominant competitive moves.
Within the integrated regional tier, Wagners Holding Company and Geopolymer Solutions LLC exemplify contractors bundling material supply with certification services. BASF SE occupies a position among multinational chemical suppliers with captive alkali activator production. These three anchors illustrate how specification authority and precursor control determine competitive positioning in procurement environments that prioritize verified durability metrics over commodity pricing.
| Leading Market Players |
|---|
| BASF SE |
| PCI Augsburg GmbH |
| Geopolymer Solutions LLC |
| Imerys S.A. |
| Zeobond Pty Ltd. |
| Schlumberger Limited |
| Wagners Holding Company |
| Milliken & Company Inc. |
| CEMEX S.A.B. de C.V. |
| Others |
Cost & Logistics Intelligence
Certified geopolymer formulator concentration along the Houston-Galveston chemical corridor compresses labor-cost differentials between premium ASTM E119-qualified coating suppliers and economy-grade bulk concrete providers. Gulf Coast alkali activator production clusters anchor pricing-tier spreads to regional wage arbitrage in precursor handling and quality assurance labor.
Pricing Analysis
Performance-guaranteed contracting anchors value-based pricing for federal highway rehabilitation, tying contractor payment to verified 20-year durability metrics rather than per-ton material delivery. Three-tier pricing structure across premium, standard, and economy levels separates ASTM E119-certified fireproofing coatings from Caltrans-verified low-carbon binders and unverified bulk concrete alternatives. Cost compression in economy-grade formulations intensifies because fly ash beneficiation investments spread fixed costs across larger volumes. Municipal transportation agencies exhibit highest price sensitivity due to constrained public works budgets, while nuclear decommissioning contractors at Department of Energy sites demonstrate lowest sensitivity given EPA-mandated documentation requirements.
Supply Chain Analysis
Rail and barge freight economics from retired coal plants in the Ohio River Valley and East Texas dominate landed cost calculations for aluminosilicate precursors. Domestic supply concentrates in the Gulf Coast chemical corridor for sodium silicate alkali activators, the Appalachian rail network for fly ash, and the Great Lakes region for slag processing. Raw material dependencies rest on metakaolin from Georgia kaolin deposits, beneficiated fly ash from Midwest utilities, and imported bauxite residues for high-performance blends. Hurricane exposure along the Texas-Louisiana chemical corridor presents single-source vulnerability for alkali activator supply. Distribution runs through vertically integrated regional contractors bundling material supply with certification services, bypassing commodity distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where precursor control and captive testing services determine margin capture. Players are pursuing backward integration into fly ash beneficiation and alkali activator production to secure supply continuity and specification authority.
For Market Incumbents: Deepen captive precursor supply through rail-linked fly ash beneficiation facilities in the East Texas corridor, insulating against hurricane-related alkali activator interruptions. Expand ACI Committee 239 certification capacity to relieve structural engineer licensure bottlenecks constraining project execution. Defend against ultra-high-performance concrete substitution in Midwest transportation departments by embedding 20-year durability guarantees into performance-based contracts. For New Entrants and Emerging Players: Enter via steel fireproofing coatings for commercial high-rise construction in California and New York, where ASTM E119 compliance requirements create defensive moats for first-qualified suppliers. Target nuclear decommissioning waste solidification at Department of Energy sites, where 90-day strength verification protocols lock in multi-year offtake agreements with limited supplier mobility. Pursue digital twin integration partnerships with state departments of transportation to enable predictive curing analytics and performance-guaranteed contracting. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated regional specialists given embedded lifecycle carbon mandates in California, Texas, and New York procurement guidelines. Long-term viability hinges on specification authority consolidation as performance-based contracting displaces commodity procurement across federal highway rehabilitation. Acquisition targets should combine alkali activator production with ACI 239 certification services. The signal to watch is expansion of federal Buy America provisions to cover alkali activator chemicals, which would revalue domestic production assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive fly ash beneficiation reduces batch-to-batch variability for Texas and Florida transportation contracts. |
| ACI Committee 239 Certification Capacity Expansion | Structural engineer licensure for alkali-activated materials relieves project execution bottlenecks. |
| Performance-Guaranteed Contracting Models | Payment tied to 20-year durability metrics concentrates risk with integrated testing and certification providers. |
| Digital Twin Integration for Predictive Curing | Sensor-embedded precast elements automate quality assurance workflows for segmental bridge construction. |
| ASTM E119 Fireproofing Coating Qualification | Twelve-to-eighteen month certification cycles create defensive moats in California and New York high-rise markets. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with plant managers at alkali activator production facilities, procurement leads at state departments of transportation, technical R&D directors at precast concrete operations, and EPA compliance officers at industrial waste generators validated demand assumptions. Secondary sources included EPA RCRA enforcement databases, ACI Committee 239 technical reports, Caltrans and TxDOT procurement guidelines, and SEC 10-K disclosures from multinational chemical suppliers. Bottom-up volume estimates from precursor consumption patterns reconciled with top-down infrastructure spending allocations across the analysis window.
Data-stream reconciliation across shipment volumes, project awards, and specification adoption curves informed the analytical framework. Segmentation dimensions modeled encompassed product type, end-use industry, precursor form, and application, cross-referenced with regional regulatory intensity and procurement mandate adoption. CAGRs derived from infrastructure spending trajectories, EPA enforcement postures, and state-level low-carbon concrete code expansion. Industry-specific forecast inputs included fly ash supply forecasts from coal plant retirement schedules and ASTM E119 certification pipeline visibility.
Revisions become necessary when EPA enforcement postures shift, state low-carbon procurement mandates accelerate or fragment across jurisdictions, or hurricane disruptions alter Gulf Coast alkali activator supply economics. Forecasts reflect assumptions regarding specification timeline compression and performance-based contracting adoption. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Phenolic Resin Market
Polymers & Resins
Saudi Arabia Engineering Plastics Market
Polymers & Resins
Global Impregnating Resins Market
Polymers & Resins
Fire Resins Market
Polymers & Resins
Bio-Based Thermoplastic Elastomer Market
Polymers & Resins
Conductive Polymers Market
Polymers & Resins
Sustainable Polymers Market
Polymers & Resins
Bio-Based Polyvinyl Chloride Market
Polymers & Resins
India Polymer Emulsion Market
Polymers & Resins
Polypropylene Powder Market
Polymers & Resins
Asia-Pacific Opaque Polymers Market
Polymers & Resins
Polyurethane (PU) Microspheres Market
Polymers & Resins
Indonesia Polypropylene Market
Polymers & Resins
Paper Processing Resins Market
Polymers & Resins
North America Thermoplastics Market
Polymers & Resins
Granular Polytetrafluoroethylene (PTFE) Market