
 Polyaryletherketone (PAEK) Market | 2026-2036
Polyaryletherketone (PAEK) Market Size, Share, and Industry Trends Forecast 2026-2036
Polyaryletherketone (PAEK) Market Analysis
Modular compound formulations is pivoting buyer choice away from standardized grades toward application-specific PAEK blends. Victrex plc dominates high-performance aerospace grades through backward integration into polymerization assets. Evonik Industries AG differentiates via medical-grade purity protocols that sustain premium positioning in implantable device supply chains. Solvay S.A. competes across European automotive thermal management segments with reinforced PAEK compounds.
Polyaryletherketone denotes a family of semi-crystalline thermoplastics containing alternating aryl, ether, and ketone linkages, with glass transition temperatures exceeding 143°C and continuous service temperatures above 250°C. These properties enable metal replacement in load-bearing components exposed to aggressive chemicals and mechanical stress. PAEK 1000 and PAEK 2000 grades anchor current revenue pools due to established qualification pathways in aerospace and oil-gas equipment. The 3D printing application segment represents the fastest-expanding demand channel as filament producers qualify laser-sintering parameters for patient-specific medical implants and complex ducting geometries.
FDA 21 CFR biocompatibility requirements and EMA MDR substance regulations shape medical-grade PAEK approval timelines and testing burdens. REACH restrictions on perfluorinated additives and EU F-Gas Regulation phase-downs indirectly steer compounders toward halogen-free processing aids and lower-emission production routes. Stakeholders must monitor evolving aerospace OEM qualification protocols and polymer recycling mandates to anticipate grade obsolescence risks and circular-economy compliance obligations.
Market Dynamics
PAEK compounders face mounting pressure from aerospace OEM qualification protocols that demand full lot traceability and thermal history documentation, compressing supplier margins while locking out non-integrated competitors.
Growth Catalysts
- FDA 21 CFR biocompatibility pathways:Medical device manufacturers accelerate metal-to-polymer substitution in spinal implants and trauma fixation, expanding addressable surgical volumes.
- Laser-sintering parameter qualification:Additive manufacturing service bureaus validate PAEK filaments for patient-specific cranial plates and complex ducting, opening geometries impossible with machining.
- Germany's industrial clusters:Automotive thermal management and chemical processing equipment demand anchor specialized reinforced grades, sustaining premium compound consumption.
Market Restraints
- Fluoropolymer feedstock volatility:Perfluorinated additive costs swing with fluorspar concentrate availability, squeezing compounder margins on medical-grade batches.
- Polymerization asset concentration:High-performance PAEK resin supply concentrates among three integrated producers, creating qualification bottlenecks for second-source seekers.
- PEEK-to-PAEK thermal gap:Lower-cost polyetheretherketone satisfies sub-250°C applications, capping volume expansion in price-sensitive industrial segments.
Strategic Opportunities
- EMA MDR substance regulations:Stricter implantable device material disclosure mandates favor PAEK suppliers with established biocompatibility dossiers over metal incumbents.
- Hydrogen economy infrastructure:Compression seals and valve components in electrolyzer stacks represent unserved demand for chemically resistant thermoplastics.
- Recycling mandate alignment:EU circular-economy compliance obligations drive interest in regrind-qualified aerospace grades, rewarding early mechanical recycling investments.
Industry Challenges
- Aerospace OEM qualification timelines:Multi-year material approval cycles lock working capital in development batches before revenue recognition.
- Polymerization technician scarcity:Specialized high-temperature reactor operation expertise concentrates among retiring cohorts, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyaryletherketone (PAEK) Market |
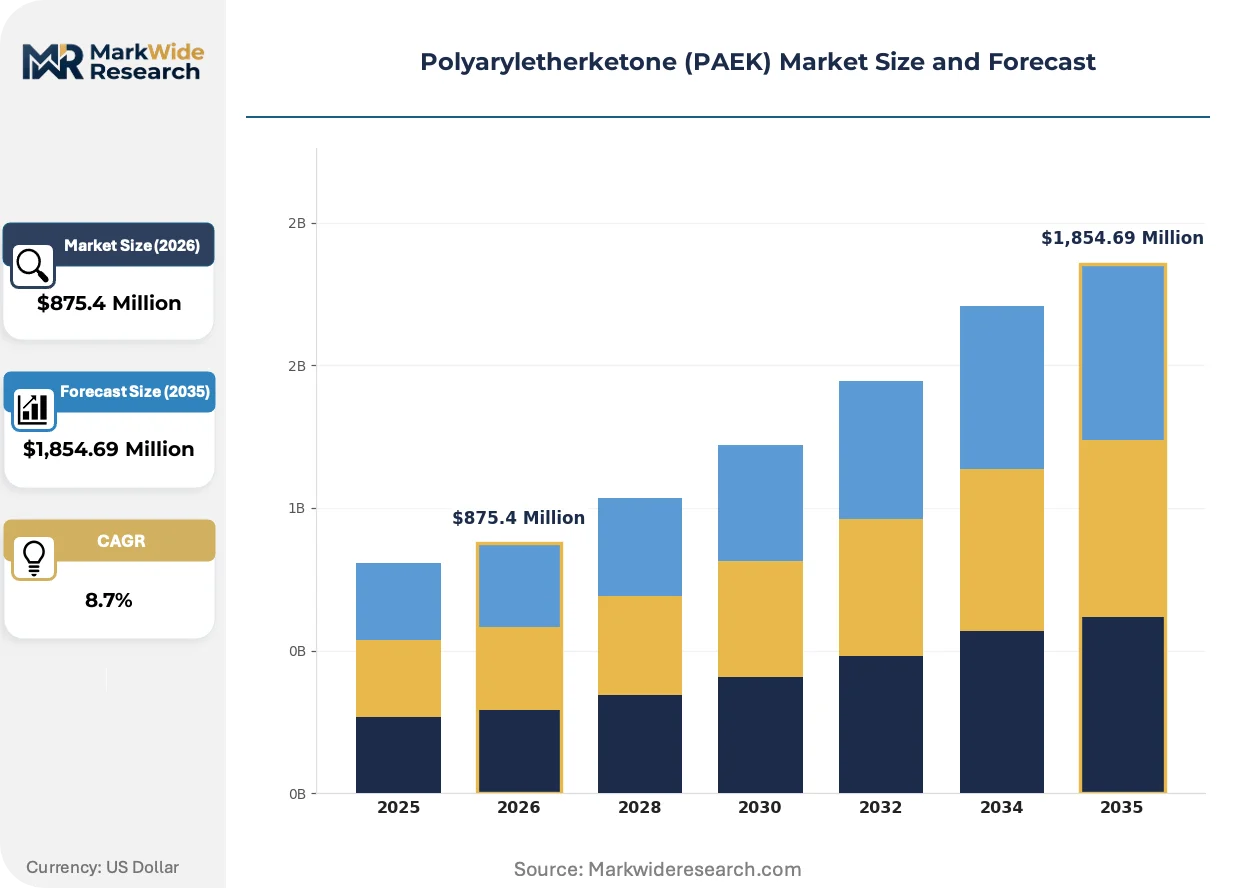
| Market Size in 2026 | $875.4 Million |
| Market Size in 2035 | $1,854.69 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PAEK 1000, PAEK 2000, PAEK 3000, PAEK 4000 End Use Industry: Aerospace, Automotive, Electronics, Medical Form: Powder, Granules, Rods, Sheets Application: 3D Printing, Mold Making, Bearings, Sealings |
| Companies Covered | Victrex plc, Evonik Industries AG, Solvay S.A., Arkema SA, Celanese Corporation, Mitsubishi Chemical Corporation, SABIC, Ensinger, Toray Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyaryletherketone (PAEK) Market Emerging Trajectories
Process intensification and regulatory disclosure requirements are compressing development cycles while fragmenting buyer specifications across end-use verticals.
Continuous fiber-reinforced PAEK tapes are unifying thermoplastic composite manufacturing with aerospace structural bonding workflows. Tier-1 aerostructures suppliers adopt automated fiber placement at production rates exceeding thermoset equivalents. This unifying capability collapses the traditional machining-to-assembly sequence, eliminating fastener count and touch labor from wingbox fabrication.
EU F-Gas Regulation phase-downs are redirecting compounders toward halogen-free processing aids and lower-emission extrusion routes. Manufacturers reformulate lubricant packages to maintain melt flow indices without perfluorinated additives. Medical-grade producers face the steepest reformulation burden, as implantable device purity protocols conflict with conventional additive chemistries.
Specification-driven procurement now dominates aerospace and medical device supply chains, displacing commodity-grade spot purchasing. Buyers consolidate vendor panels to single-source qualified grades, extracting volume commitments in exchange for design-lock status. Germany and Switzerland exhibit the most pronounced consolidation, where automotive and surgical instrument OEMs enforce dual-source bans on critical structural polymers.
Polyaryletherketone (PAEK) Market Segmentation
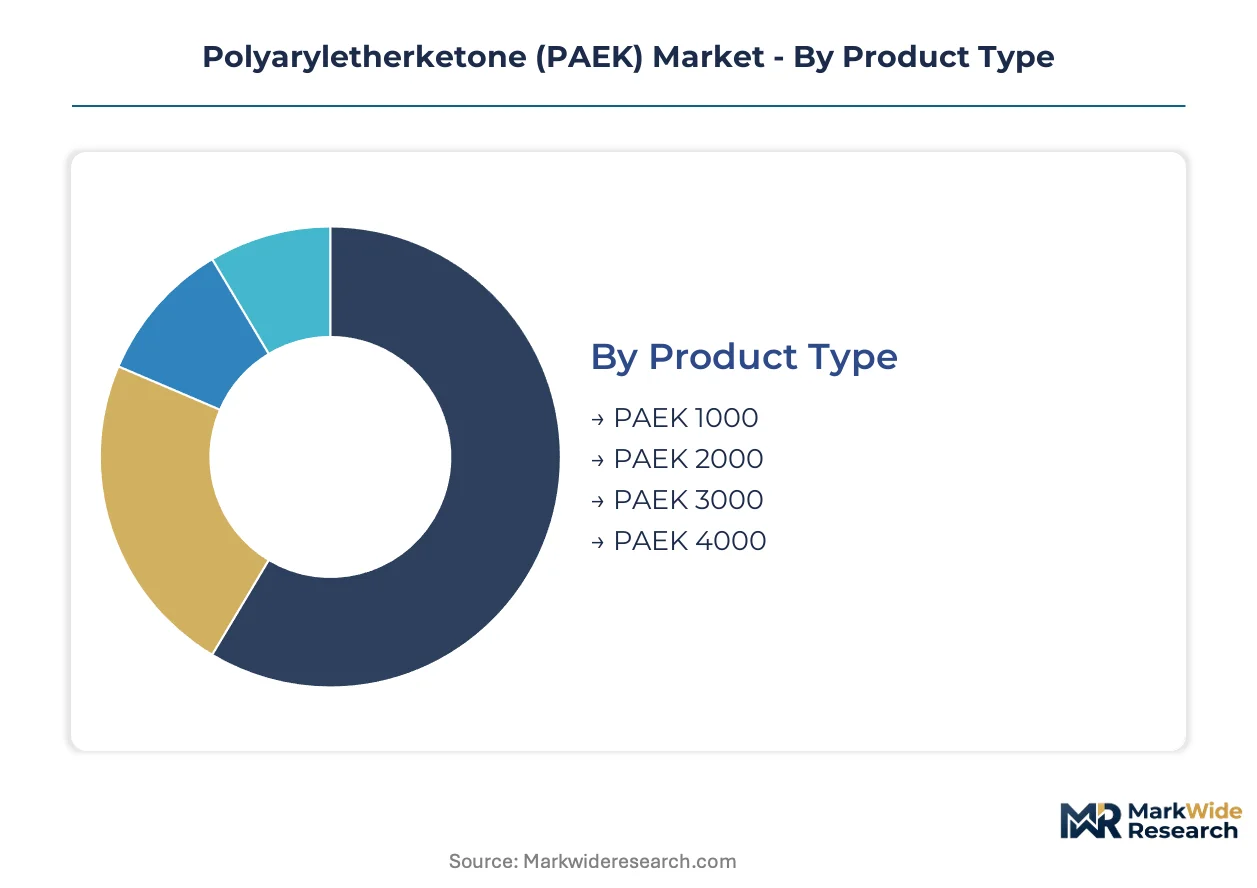
PAEK buyers navigate divergent certification burdens across segments, with aerospace and medical grades demanding multi-year qualification protocols while industrial applications permit faster substitution cycles. Segmentation discipline separates margin-accretive specialty grades from volume-driven commodity positions.
Product Type:
FDA 21 CFR biocompatibility pathways and aerospace OEM qualification protocols concentrate heaviest on intermediate molecular weight grades, while lower-tier industrial specifications tolerate broader batch variability.
- PAEK 1000:Lowest molecular weight grade with melt viscosity optimized for injection molding of thin-walled electrical connectors and semiconductor wafer carriers. Demand concentrates in Japan's electronics fabrication clusters where METI-guided supply chain localization drives substitution of imported fluoropolymers.
- PAEK 2000:Mid-range viscosity grade balancing flow characteristics with mechanical strength for load-bearing aerospace brackets and spinal implant cages. German automotive thermal management suppliers specify this grade for charge air cooler end caps exposed to glycol-based coolants.
- PAEK 3000:Higher molecular weight variant targeting compression-molded bearings and thrust washers in chemical processing equipment. European REACH compliance documentation requirements extend approval timelines for compounders serving oil-gas valve manufacturers.
- PAEK 4000:Highest viscosity grade reserved for extruded stock shapes and filament feedstocks where melt strength dominates processing economics. Additive manufacturing service bureaus in Switzerland qualify this grade for laser-sintering of patient-specific cranial reconstruction plates.
PAEK 2000 sits at the top of the volume ranking, with PAEK 4000 climbing the fastest.
End Use Industry:
Margin structures diverge sharply across end-use verticals, with implantable device supply chains sustaining 40-60% price premiums over industrial bearing applications.
- Aerospace:Primary structural brackets, ducting clips, and firewall seals where FAA flame-smoke-toxicity certification governs material selection. Tier-1 aerostructures suppliers in France and Germany enforce dual-source bans on flight-critical polymer grades.
- Automotive:Thermal management components including water pump housings, thermostat bodies, and electric motor slot liners. KBA type-approval requirements for underhood materials constrain formulation flexibility for compounders serving German OEMs.
- Electronics:Wafer handling fixtures, connector bodies, and semiconductor test sockets where electrostatic discharge control meets dimensional stability requirements. Taiwan's semiconductor packaging houses drive specification tightening for high-temperature reflow compatibility.
- Medical:Spinal fusion cages, trauma fixation plates, and dental healing abutments where EMA MDR substance disclosure mandates favor suppliers with pre-assembled biocompatibility dossiers. Swissmedic and TGA mutual recognition agreements accelerate multi-jurisdiction approvals for qualified grades.
Aerospace commands the highest average selling prices, with Medical expanding most quickly.
Form:
Processing method selection dictates form factor demand, with powder formats capturing additive manufacturing growth while extruded shapes serve legacy machining workflows.
- Powder:Laser-sintering feedstock with controlled particle size distributions for layer-wise fusion in patient-specific implant production. EMA MDR batch traceability requirements extend from resin synthesis through final sterilization.
- Granules:Injection molding and extrusion compounds where melt homogeneity determines mechanical property consistency. Automotive suppliers in Germany specify granule lots with full thermal history documentation for warranty traceability.
- Rods:Machining stock for prototype development and low-volume bearing production where near-net-shape economics fail. Swiss surgical instrument manufacturers machine rod stock into custom retractor handles and drill guides.
- Sheets:Thermoforming blanks for aircraft interior panels and chemical equipment linings requiring planar stock with controlled crystallinity. FAA cabin material fire-testing protocols add 18-24 months to sheet grade qualification cycles.
Granules dominate current shipment volumes, with Powder gaining share fastest.
Application:
Application-specific performance thresholds separate qualified grades from commodity substitutes, with bearing and sealing applications tolerating broader property bands than implantable or flight-critical uses.
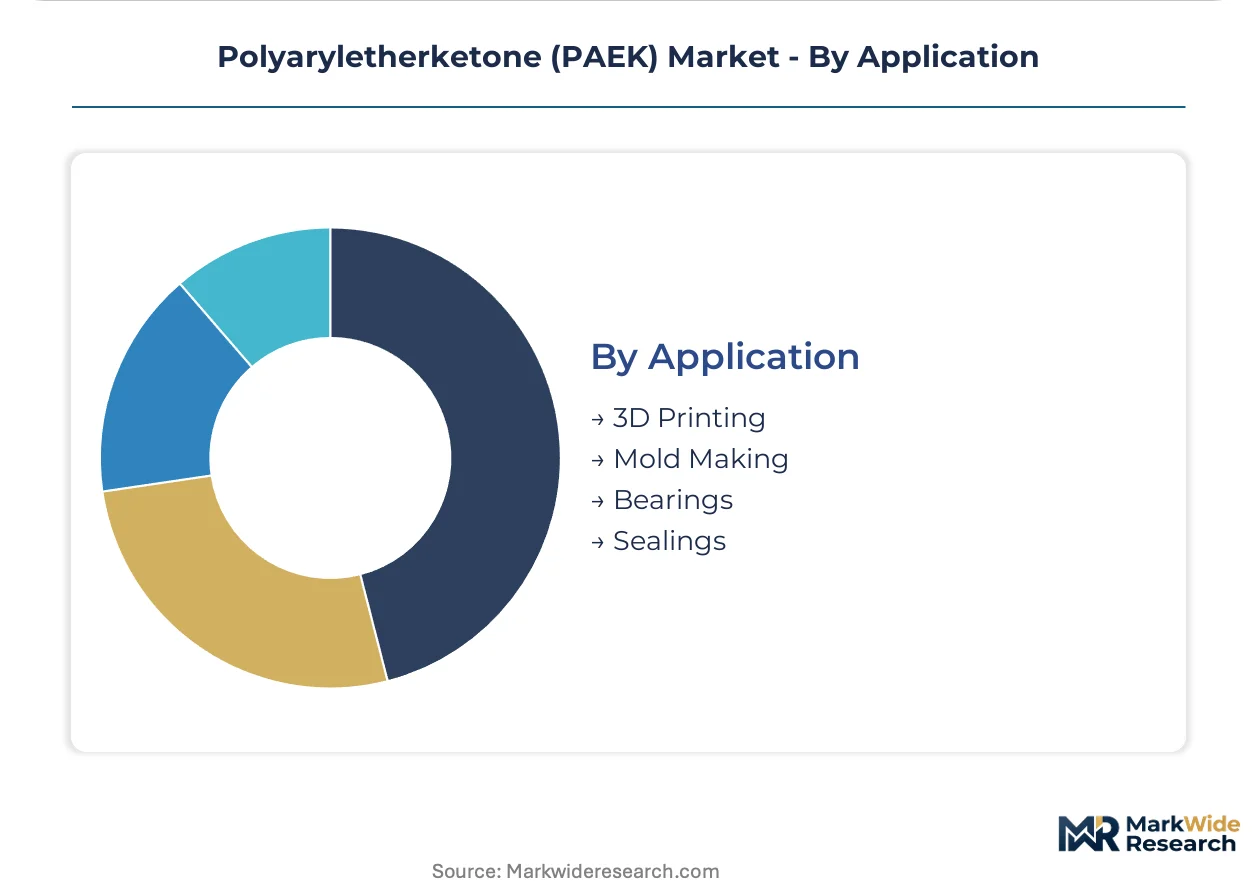
- 3D Printing:Additive manufacturing of complex geometries including conformal cooling channels and topology-optimized brackets impossible with subtractive methods. Laser-sintering parameter qualification at service bureaus in Germany and Switzerland locks filament suppliers into multi-year validation partnerships.
- Mold Making:Tooling inserts and prototype molds where PAEK's thermal stability permits direct injection of high-temperature engineering polymers without cooling cycle penalties. Automotive styling studios in Italy specify mold-grade blocks for rapid iteration of concept interior panels.
- Bearings:Self-lubricating bushings and thrust washers replacing bronze and PTFE composites in chemical pumps and food processing equipment. FDA food-contact compliance for bearing grades requires migration testing protocols less stringent than implantable device standards.
- Sealings:Compression packings, valve seats, and flange gaskets exposed to aggressive media across temperature cycling. EU F-Gas Regulation phase-downs redirect seal compounders toward halogen-free processing aids without perfluorinated lubricants.
Bearings anchor current volume leadership, with 3D Printing showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PAEK commercialization traces to 1978 UK polymerization breakthroughs at Imperial Chemical Industries, establishing the thermoplastic's industrial lineage before aerospace and medical applications drove geographic expansion across specialized manufacturing clusters.
United States
FAA flame-smoke-toxicity certification requirements anchor aerospace demand for PAEK structural brackets and firewall seals. Boeing and Lockheed Martin qualification protocols enforce full lot traceability, compressing supplier margins while locking in qualified grades. Wichita, Kansas aerostructures manufacturers source certified compounds for wingbox fabrication.
Germany
KBA type-approval mandates for underhood thermal management components sustain automotive consumption of reinforced PAEK grades. REACH documentation burdens extend compounder approval timelines for oil-gas valve manufacturers. Baden-Württemberg automotive clusters specify PAEK 2000 for charge air cooler end caps exposed to glycol-based coolants.
Switzerland
Swissmedic implantable device regulations favor suppliers with pre-assembled biocompatibility dossiers over metal incumbents in spinal fusion applications. TGA mutual recognition agreements accelerate multi-jurisdiction approvals for qualified medical grades. Basel-area surgical instrument manufacturers machine PAEK rod stock into custom retractor handles and drill guides.
Japan
METI-guided supply chain localization drives substitution of imported fluoropolymers with PAEK 1000 in semiconductor wafer handling fixtures. JIS standards for high-temperature reflow compatibility tighten specification requirements for electronics packaging houses. Kyushu electronics fabrication clusters consume injection-molded grades for thin-walled connector applications.
United Kingdom
EMA MDR substance disclosure mandates accelerate metal-to-polymer substitution in trauma fixation devices. MHRA post-Brexit regulatory divergence creates parallel approval pathways for medical-grade compounders. Lancashire aerospace tier-1 suppliers enforce dual-source bans on flight-critical polymer grades for structural bonding workflows.
Polyaryletherketone (PAEK) Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade stratification, with aerospace and medical qualification status separating pricing tiers. Three integrated resin producers concentrate high-performance polymerization capacity, while compounders and fabricators occupy downstream fragmentation. Backward integration into polymerization assets defines the dominant archetype, followed by medical-grade purity specialists and reinforced compound formulators. Capacity expansion and strategic partnerships constitute the primary competitive moves, with qualification-driven design-lock agreements locking out second-source seekers.
Within the integrated producer tier, Victrex plc and Evonik Industries AG exemplify divergent strategic positioning. Victrex anchors the aerospace-grade segment through captive polymerization control, while Evonik occupies the medical-grade purity vector with established implantable device supply chain presence. Solvay S.A. represents the reinforced compound formulator archetype, competing across European automotive thermal management segments. These three companies collectively demonstrate how qualification status and backward integration determine margin capture in PAEK markets.
| Leading Market Players |
|---|
| Victrex plc |
| Evonik Industries AG |
| Solvay S.A. |
| Arkema SA |
| Celanese Corporation |
| Mitsubishi Chemical Corporation |
| SABIC |
| Ensinger |
| Toray Industries, Inc. |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation phase-downs gate qualified supply and premium-tier pricing access, as compounders lacking halogen-free processing aid formulations face exclusion from medical-grade and aerospace procurement panels. Buyers with EMA MDR-compliant biocompatibility dossiers command price premiums while non-qualified suppliers absorb reformulation costs or exit high-margin segments entirely.
Pricing Analysis
Three-tier pricing structure across aerospace-qualified, medical-grade, and industrial-standard levels concentrates margin capture among backward-integrated resin producers. Price differentiation hinges on FDA 21 CFR certification status and full lot traceability documentation, with aerospace OEMs paying substantial premiums for thermal history-verified grades. Cost compression in industrial-standard tiers intensifies because PEEK substitution caps volume expansion in sub-250°C applications. Electronics fabrication buyers in Japan exhibit highest price sensitivity, while Swiss spinal implant manufacturers accept least price elasticity for qualified medical grades.
Supply Chain Analysis
Dual-sourcing requirements at Boeing, Lockheed Martin, and German Tier-1 aerostructures suppliers mandate multi-supplier qualification, yet polymerization asset concentration among three integrated producers creates persistent bottlenecks. Geographic supply concentrates in the United Kingdom, Germany, and the United States, where captive polymerization capacity anchors qualified resin output. Raw material dependencies encompass fluorspar concentrates for perfluorinated additives, high-purity diphenyl ether feedstocks, and specialized high-temperature reactor components. Single-source vulnerability concentrates in polymerization technician expertise, where retiring cohorts constrain capacity expansion. Distribution runs through qualified compounder networks with direct OEM supply agreements for certified grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PAEK markets represent a late-cycle quality story as aerospace and medical device buyers consolidate procurement around specification-qualified grades, displacing commodity-grade spot purchasing with design-lock agreements that reward certification investment over volume scale.
For Market Incumbents: Deploy captive polymerization capacity expansion to defend against second-source seekers attempting qualification pathway shortcuts. Aerospace OEM dual-source bans and EMA MDR substance disclosure mandates create defensive moats for suppliers with established biocompatibility dossiers. Capacity addition in Germany's Baden-Württemberg cluster reinforces proximity to automotive thermal management demand while locking out regional compounders lacking backward integration. For New Entrants and Emerging Players: Hydrogen economy infrastructure buyers represent an underserved archetype with unserved demand for electrolyzer compression seals and valve components. White-space targets include laser-sintering filament supply to Swiss additive manufacturing service bureaus and regrind-qualified aerospace grades for EU circular-economy compliance. Go-to-market positioning should emphasize mechanical recycling partnerships with tier-1 aerostructures suppliers seeking sustainability credentials. For Investors and Strategic Acquirers: Roll-up economics work for medical-grade compounders with pre-assembled FDA 21 CFR dossiers because EMA MDR approval timelines create acquisition premiums over de novo qualification investments. Long-term viability favors targets with established implantable device supply chain presence and halogen-free processing aid formulations aligned with EU F-Gas phase-downs. Watch hydrogen economy infrastructure procurement announcements as inflection indicator for chemically resistant thermoplastic demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymerization Assets | Victrex plc's captive resin production locks in aerospace-grade margin capture against non-integrated compounders. |
| Medical-Grade Purity Protocol Investment | Evonik Industries AG's implantable device dossiers sustain premium positioning through EMA MDR compliance. |
| Halogen-Free Processing Aid Reformulation | EU F-Gas Regulation alignment separates qualified suppliers from additive chemistry-dependent competitors. |
| Laser-Sintering Parameter Qualification Partnership | Swiss service bureau validation agreements lock filament suppliers into multi-year design-lock arrangements. |
| Mechanical Recycling Infrastructure Buildout | Regrind-qualified aerospace grades reward early EU circular-economy compliance investments. |
Methodological Framework
Multiple input streams — primary interviews with polymerization plant managers, aerospace procurement leads, and medical device regulatory affairs directors; secondary validation against SEC 10-K filings, EMA submission databases, and Cefic chemical industry reports; customs and trade flow data — were reconciled through bottom-up and top-down triangulation. Stakeholder engagement encompassed technical R&D directors at integrated resin producers, distribution channel partners serving German automotive clusters, and biomedical engineers at Swiss spinal implant manufacturers.
Data-stream reconciliation across product type, end-use industry, form factor, and application dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from segment-level volume and value trajectories modeled against qualification timeline assumptions and substitution elasticity parameters. Industry-specific forecast inputs incorporated aerospace OEM design-lock agreement tenors and EMA MDR batch traceability documentation burdens.
Underlying measurement precision varies by segment; aerospace and medical-grade volumes carry tighter precision than industrial bearing applications given consolidated procurement data availability. Forecasts reflect assumptions regarding polymerization capacity expansion timelines, regulatory approval pathway durations, and hydrogen economy infrastructure deployment rates. Deviation in EU circular-economy mandate enforcement intensity or aerospace OEM qualification protocol stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Europe Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Global Low Density Polyethylene (LDPE) Foams Market
Polymers & Resins
Global Amorphous Polyalphaolefin (APAO) for Hot Melt Market
Polymers & Resins
Global High Performance Polyethylene Market
Polymers & Resins
Polybutene-1 Market
Polymers & Resins
Polyurethane (PU) Microspheres Market
Polymers & Resins
Polyisobutylene (PIB) Market
Polymers & Resins
Europe Polyamide Market
Polymers & Resins
Phenoxy Resins Market
Polymers & Resins
GCC Polyethylene Terephthalate (PET) Market
Polymers & Resins
Soy Polysaccharides Market
Polymers & Resins
Polar Polymers Market
Polymers & Resins
PVDF Resin Market
Polymers & Resins
Conditioning Polymers Market
Polymers & Resins
Polyethylene Wax Market
Polymers & Resins
Fluorinated Ethylene Propylene (FEP) Market