
 Glycolide Polymers Market | 2026-2036
Glycolide Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Glycolide Polymers Market Analytics
Specialized polymer chemist availability is unwinding as academic programs in materials science pivot toward battery and semiconductor substrates, tightening the talent pipeline for glycolide synthesis expertise. Evonik Industries leverages its backward integration into lactide and glycolide monomers to control feedstock quality for medical-grade PLGA. Corbion NV anchors European supply through its Netherlands-based fermentation and purification infrastructure. Mitsui Chemicals competes on Asian pharmaceutical channel access, sustaining long-term offtake agreements with Japanese suture manufacturers.
Glycolide polymers comprise aliphatic polyesters synthesized through ring-opening polymerization of glycolide monomer, typically copolymerized with lactide or caprolactone to tune degradation rates from weeks to months for controlled drug release or tissue scaffolding. PLGA copolymers dominate formulation supply due to their tunable hydrolytic degradation and established toxicology profiles, while PGA homopolymer retains niche surgical suture applications where rapid absorption is clinically indicated. Drug delivery systems represent the fastest-expanding application segment as pharmaceutical developers adopt polymeric microspheres for long-acting injectable formulations. Granule and pellet formulations command premium positioning over powders where batch-to-batch molecular weight consistency determines regulatory submission outcomes.
FDA enforces biocompatibility and degradation-byproduct toxicity standards under ISO 10993 guidelines that govern glycolide polymer implant eligibility, while EMA's Medical Device Regulation requires enhanced clinical evidence for absorbable polymer Class III devices. REACH compliance in Europe constrains residual monomer thresholds, adding purification cost burdens that favor scaled manufacturers over emerging entrants. Stakeholders must monitor evolving pharmacopeial monograph revisions for polyglycolide and polylactide materials, as compendial standard shifts can invalidate existing drug master files and trigger reformulation cycles.
Market Dynamics
FDA and EMA biocompatibility frameworks are tightening purity benchmarks for implant-grade glycolide copolymers, forcing manufacturers to reconfigure purification trains and validate new analytical methods. This regulatory compression is reshaping competitive positioning by favoring scaled producers with captive monomer supply and dedicated quality infrastructure.
Growth Catalysts
- Long-acting injectable formulations:Pharmaceutical developers are adopting polymeric microspheres for extended-release therapeutics, creating sustained offtake for PLGA copolymers with tunable degradation profiles.
- ISO 10993 biocompatibility harmonization:Converging FDA and EMA toxicology standards are streamlining dual-market submissions for absorbable polymer devices, reducing regulatory duplication costs.
- Heidelberg-Aachen polymer clusters:Concentrated surgical instrument OEMs and specialized research infrastructure in Germany are generating localized demand for high-purity glycolide feedstocks.
Market Restraints
- Lactide-glycolide monomer volatility:Fermentation-derived lactic acid feedstocks face agricultural input price swings that transmit directly to copolymer production economics.
- Netherlands-based fermentation concentration:European glycolide supply anchors through Corbion's single-site infrastructure, creating geographic vulnerability to regional energy or logistics disruptions.
- REACH residual monomer thresholds:ECHA-mandated purity ceilings add purification cost burdens that disadvantage emerging entrants without scaled distillation capacity.
Strategic Opportunities
- Japanese pharmaceutical channel access:Mitsui Chemicals' long-term offtake agreements with domestic suture manufacturers demonstrate viable entry pathways for Asian market penetration.
- Battery and semiconductor substrate pivot:Materials science academic programs are diverting talent from polymer synthesis, creating acquisition opportunities for glycolide expertise at distressed valuations.
- Granule and pellet premium positioning:Batch-to-batch molecular weight consistency requirements for regulatory submissions favor formulated products over commodity powders.
Industry Challenges
- Specialized polymer chemist scarcity:Academic program pivots toward energy storage materials are constraining the talent pipeline for ring-opening polymerization expertise.
- Pharmacopeial monograph revision risk:Compendial standard shifts for polyglycolide and polylactide materials can invalidate existing drug master files and trigger costly reformulation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glycolide Polymers Market |
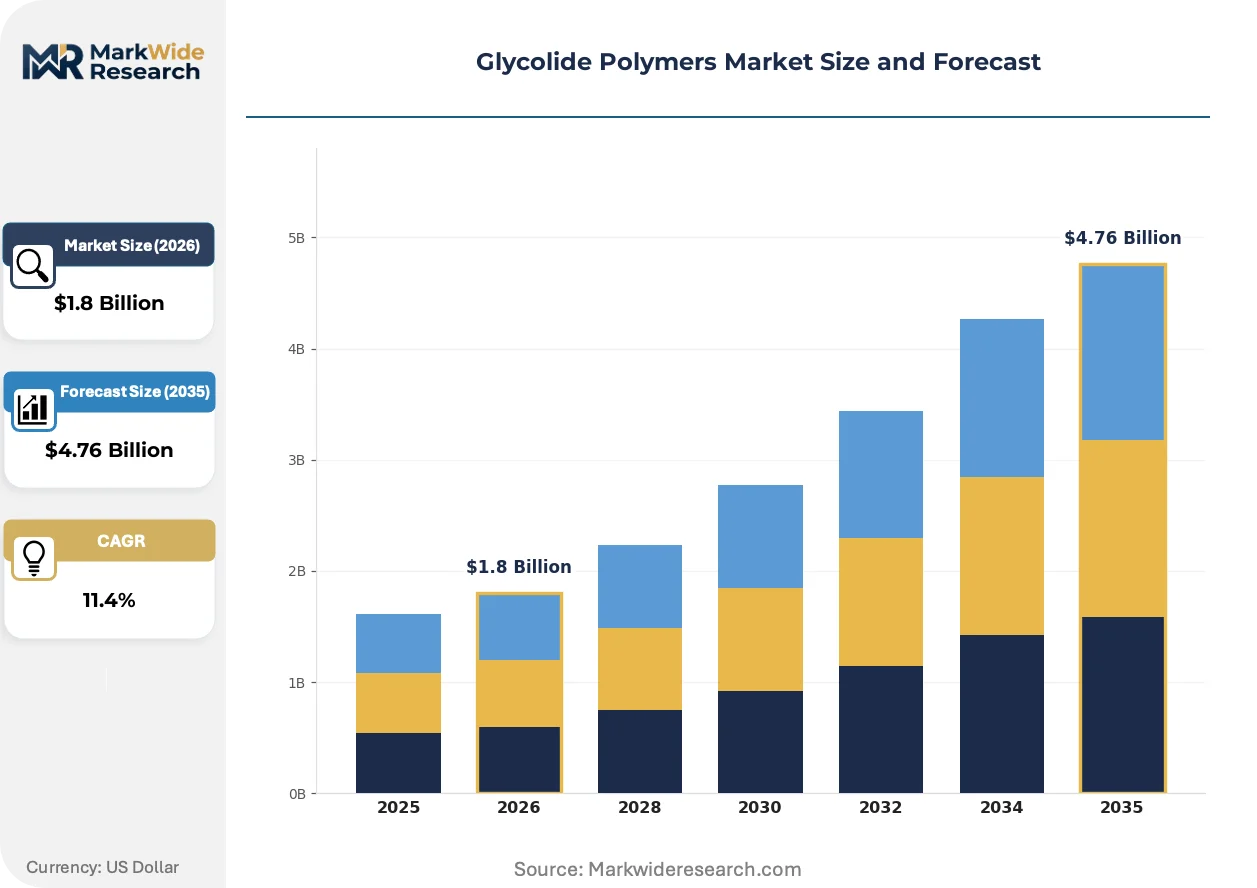
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA, PCL, PGA, PLGA Application: Biomedical Devices, Drug Delivery Systems, Tissue Engineering, Surgical Sutures Formulation Type: Granules, Pellets, Powders, Films End User: Pharmaceuticals, Biotech Companies, Research Institutions, Medical Device Manufacturers |
| Companies Covered | Evonik Industries, Corbion NV, Ashland, Mitsui Chemicals, Jinan Digang Bioengineering Co., Ltd., Poly-Med Incorporated, Bezwada Biomedical, Akina, Inc., Merck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glycolide Polymers Market Evolving Landscape
Ring-opening polymerization control technologies are fragmenting established process hierarchies, enabling new entrants to achieve molecular weight precision previously guarded by incumbent expertise. This technical democratization is compressing the traditional capability moat around medical-grade glycolide production.
Continuous flow reactor designs for glycolide polymerization are fragmenting batch-process dominance in medical-grade production. Korean and Chinese equipment suppliers are delivering skid-mounted systems at capital costs 40% below traditional stirred-tank installations. This hardware accessibility is compressing the minimum efficient scale for implant-grade polymer manufacturing, enabling mid-sized pharmaceutical developers to bring synthesis in-house.
EMA's Medical Device Regulation enhanced clinical evidence requirements for absorbable polymer Class III devices are fragmenting submission strategies across European notified bodies. Manufacturers must now generate extended degradation kinetic data and histopathological response studies that exceed prior MDD thresholds. German and Swiss device developers are responding by pre-submission engagement with BfArM and Swissmedic to align study protocols before pivotal trials commence.
Specification-grade procurement is displacing commodity purchasing in North American hospital supply chains. Integrated delivery networks now require lot-level molecular weight certificates and residual monomer COAs for suture and mesh procurement. This documentation burden is most visible in California and Massachusetts health systems, where centralized pharmacy committees have standardized absorbable polymer qualification protocols across member facilities.
Glycolide Polymers Market Segmentation
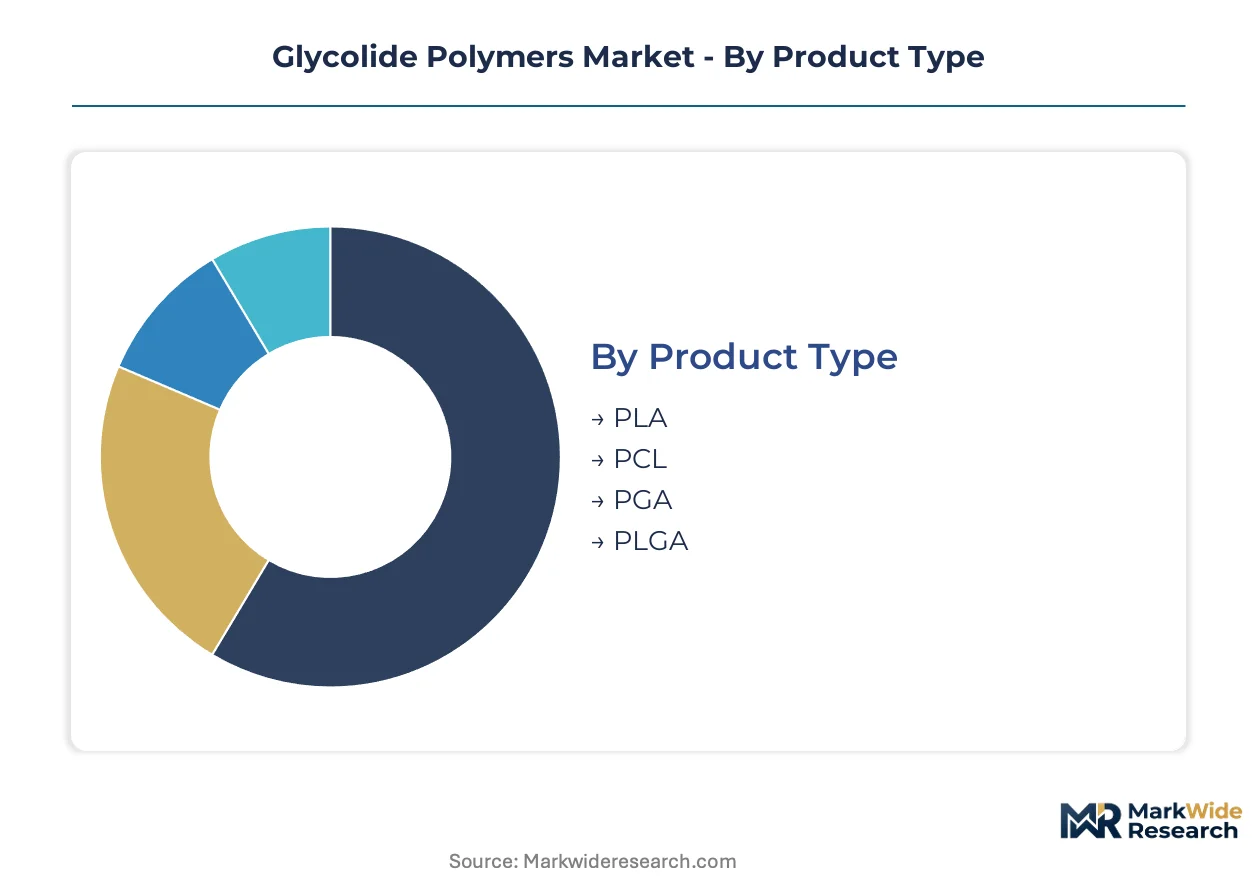
Glycolide polymer procurement patterns diverge sharply across product grades and end-use specifications. Medical device qualification protocols and pharmaceutical formulation requirements create distinct demand clusters that resist standardization.
Product Type:
Domestic production capacity concentrates PLGA and PGA supply in Germany, Japan, and the United States, while PLA and PCL grades flow through broader international trade channels.
- PLGA:Lactide-glycolide copolymers dominate controlled-release formulations through tunable degradation kinetics spanning weeks to months. Pharmaceutical developers in Massachusetts and Basel specify PLGA for long-acting injectable microspheres where batch molecular weight consistency determines regulatory submission success.
- PGA:Polyglycolic acid homopolymer retains surgical suture applications demanding rapid hydrolytic absorption with minimal tissue reaction. Japanese suture manufacturers anchor PGA offtake through dedicated supply agreements with domestic polymer producers.
- PLA:Polylactide serves orthopedic fixation devices and soft tissue anchors where slower degradation matches bone remodeling timelines.
- PCL:Polycaprolactone extends degradation windows beyond one year for contraceptive implants and tendon augmentation scaffolds.
PLGA commands the established base. The steepest expansion runs through PGA as rapid-absorption suture demand intensifies in ambulatory surgical centers.
Application:
Cost tiers separate commodity surgical supply procurement from premium pharmaceutical formulation contracts with dedicated quality infrastructure requirements.
- Drug Delivery Systems:Polymeric microspheres enable extended-release therapeutics for schizophrenia, diabetes, and oncology indications. FDA drug master file submissions for PLGA-based depot formulations require exhaustive degradation kinetic documentation that filters out non-specialized suppliers.
- Surgical Sutures:Absorbable monofilament and braided constructs demand rapid tensile strength loss profiles calibrated to tissue healing rates. German surgical instrument OEMs around Heidelberg specify suture-grade PGA with residual monomer thresholds below REACH-mandated ceilings.
- Biomedical Devices:Hernia mesh, dural substitutes, and cardiovascular patches utilize glycolide copolymers for temporary mechanical support during tissue integration.
- Tissue Engineering:Three-dimensional scaffolds for cartilage and bone regeneration exploit polyester biodegradability to match neo-tissue formation rates.
Surgical Sutures anchor volume throughput. Drug Delivery Systems generate the fastest margin expansion as pharmaceutical pricing power exceeds commodity medical supply contracting.
Formulation Type:
Customer type stratification separates pharmaceutical compounders seeking certified granule supply from research laboratories tolerating variable powder specifications.
- Granules:Uniform particle size distributions and validated melt flow indices support hot-melt extrusion and injection molding of implantable devices. Swiss device developers specify granule formulations with lot-level molecular weight certificates for Class III submission packages.
- Pellets:Cylindrical extrudates optimize feeding consistency in twin-screw compounding operations for drug-polymer matrix preparation.
- Powders:Spray-dried or precipitated powders serve solvent-based coating applications and laboratory-scale formulation development with lower documentation burdens.
- Films:Cast or extruded sheets provide barrier membranes for guided tissue regeneration and controlled-release laminate structures.
Granules concentrate premium positioning. Powders expand most quickly in academic and emerging market segments where cost sensitivity outweighs qualification overhead.
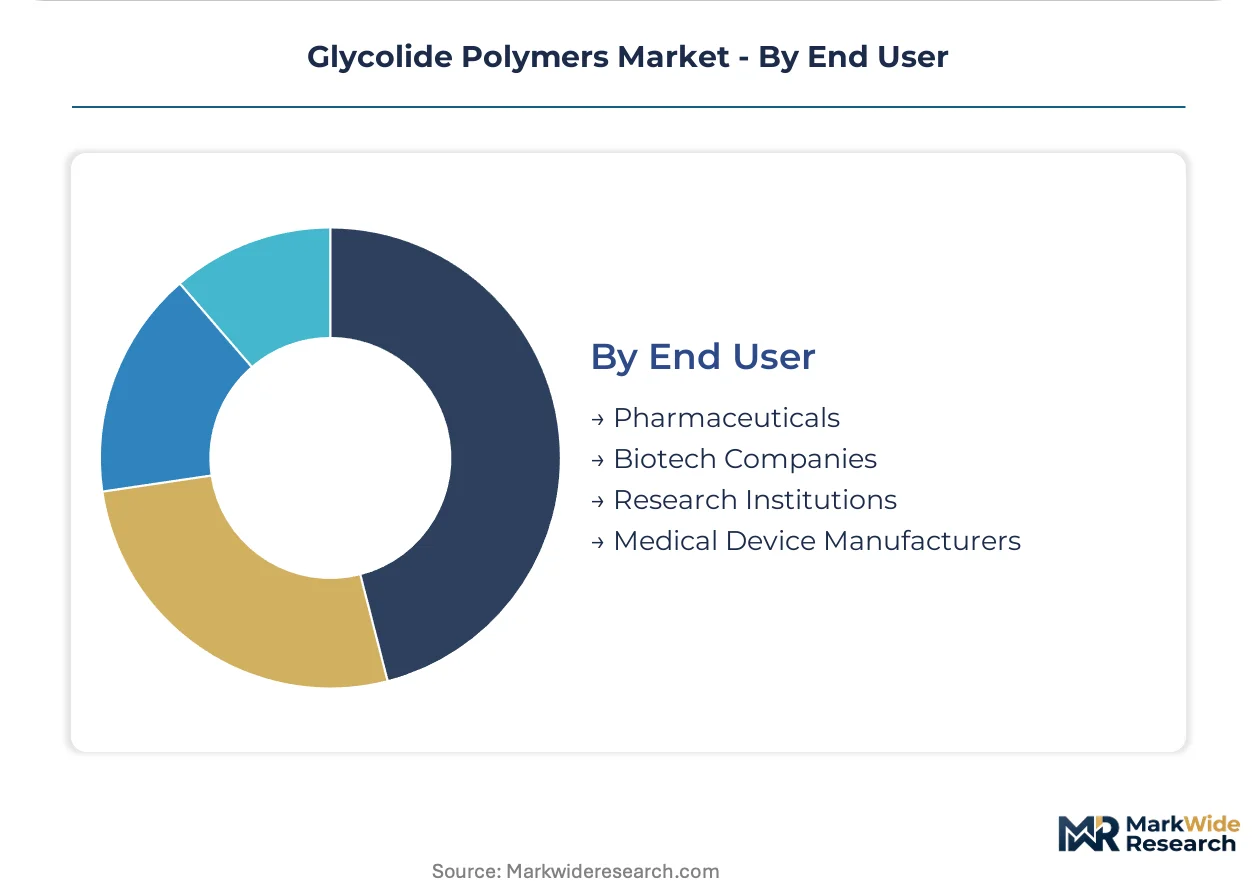
End User:
Supply concentration favors scaled manufacturers with dedicated medical-grade polymer infrastructure over generalist chemical producers.
- Pharmaceuticals:Big pharma and specialty pharmaceutical developers specify glycolide polymers for commercialized long-acting injectables with billion-dollar revenue thresholds. EMA MDR compliance costs and FDA Type II drug master file maintenance requirements create vendor stickiness once qualification is achieved.
- Medical Device Manufacturers:Surgical suture, mesh, and fixation device producers demand ISO 13485-certified polymer supply with validated sterilization compatibility. Integrated delivery networks in California now require residual monomer certificates for absorbable implant procurement.
- Biotech Companies:Clinical-stage developers purchase smaller polymer lots for formulation feasibility and toxicology studies prior to commercial scale-up.
- Research Institutions:Academic laboratories drive early-stage scaffold and delivery system innovation with lower volume, higher specification variety requirements.
Medical Device Manufacturers anchor procurement volume. Pharmaceuticals generate the steepest value expansion as drug-polymer conjugate pipelines mature toward commercialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany absorbs glycolide polymers primarily for precision surgical instruments, while the United States channels supply into long-acting pharmaceutical injectables, and Japan anchors PGA demand through dedicated suture manufacturing agreements. This consumption-mix differential shapes procurement specifications and regulatory engagement strategies across major demand centers.
United States
Massachusetts and California health systems drive specification-grade procurement for drug delivery matrices and absorbable implants. FDA enforces ISO 10993 biocompatibility standards with tightening purity benchmarks for implant-grade copolymers. Greater Boston pharmaceutical developers specify PLGA microspheres for commercialized long-acting injectables with exhaustive degradation kinetic documentation.
Germany
Heidelberg-Aachen polymer clusters concentrate surgical instrument OEMs demanding REACH-compliant residual monomer thresholds below ECHA-mandated ceilings. EMA's Medical Device Regulation requires enhanced clinical evidence for Class III absorbable devices. Specialized research infrastructure around Aachen generates localized demand for high-purity glycolide feedstocks with validated sterilization compatibility.
Japan
Domestic suture manufacturers anchor PGA offtake through long-term supply agreements with integrated chemical producers. PMDA aligns with converging FDA-EMA toxicology standards for streamlined dual-market submissions. Osaka-based surgical supply producers specify rapid-absorption PGA homopolymer for ambulatory surgical center applications.
China
Jinan and Zhengzhou biengineering specialists expand fermentation-derived lactic acid capacity for lactide-glycolide copolymer production. NMPA strengthens biocompatibility frameworks for absorbable polymer implants under harmonized GB standards. Shandong Peninsula research clusters develop ring-opening polymerization expertise for medical-grade polyester synthesis.
Switzerland
Swissmedic pre-submission engagement protocols attract German and domestic device developers seeking alignment on extended degradation studies. Basel pharmaceutical compounders specify granule formulations with lot-level molecular weight certificates for Class III submission packages. Zurich-anchored medical technology firms drive premium procurement for validated melt flow index consistency.
Glycolide Polymers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into monomer supply distinguishing scaled producers from formulation-dependent competitors. The market structure concentrates procurement leverage among three to four manufacturers with captive fermentation and purification infrastructure. Two strategic archetypes dominate: integrated chemical conglomerates controlling feedstock quality through in-house lactide-glycolide production, and specialized biomedical polymer houses focusing on regulatory submission support and customized molecular weight specifications. Competitive moves center on capacity expansion in medical-grade fermentation trains and technology licensing partnerships for continuous flow reactor designs.
Among European integrated producers, Evonik Industries and Corbion NV exemplify the upstream-controlled archetype, with Netherlands-based fermentation infrastructure anchoring regional supply security. Mitsui Chemicals occupies a position representing Asian pharmaceutical channel access through long-term offtake structures with domestic suture manufacturers. These three entities illustrate how geographic feedstock concentration and regulatory compliance capabilities determine vendor stickiness in pharmaceutical and medical device procurement.
| Leading Market Players |
|---|
| Evonik Industries |
| Corbion NV |
| Ashland |
| Mitsui Chemicals |
| Jinan Digang Bioengineering Co., Ltd. |
| Poly-Med Incorporated |
| Bezwada Biomedical |
| Akina, Inc. |
| Merck |
| Others |
Value Network & Pricing Analysis
Medical-grade fermentation capacity utilization above 85 percent at Netherlands-based facilities compresses marginal cost curves for implant-grade glycolide copolymers, concentrating pricing power among producers with captive lactide-glycolide monomer supply and forcing smaller compounders toward toll manufacturing arrangements or exit.
Pricing Analysis
Long-term offtake agreements spanning 3-5 years dominate pharmaceutical procurement, locking in molecular weight specifications and residual monomer thresholds that filter out non-specialized suppliers, while spot purchasing persists for research-grade powders where documentation burdens remain minimal. Price differentiation hinges on ISO 13485 certification tier and batch-level analytical certificates, with REACH-compliant granules commanding substantial premiums over standard-grade pellets. Cost compression in commodity PGA suture feedstocks is intensifying because Chinese fermentation capacity expansions are transmitting agricultural input price volatility directly to copolymer production economics. Academic research institutions exhibit highest price sensitivity, tolerating broader molecular weight distributions, whereas Swiss device developers demonstrate lowest sensitivity due to Class III submission package requirements.
Supply Chain Analysis
Port congestion at Rotterdam and Antwerp elevates inbound logistics costs for fermentation-derived lactic acid feedstocks, compressing margins for European compounders dependent on Asian agricultural inputs. Supply concentrates in the Netherlands, Germany, and Japan, with Corbion's single-site infrastructure creating geographic vulnerability to regional energy disruptions. Raw material dependencies rest on corn-derived dextrose for fermentation, specialized catalysts for ring-opening polymerization, and validated packaging for moisture-sensitive granules. Single-source vulnerability permeates medical-grade monomer supply where backward integration barriers exceed capital thresholds for emerging entrants. Distribution runs through ISO-certified polymer distributors serving pharmaceutical compounders and direct mill relationships with surgical suture OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PLGA microsphere platform economics are reaching an inflection as pharmaceutical developers consolidate vendor lists around suppliers offering integrated regulatory submission support, with interoperability between drug master file maintenance and continuous manufacturing validation emerging as the decisive ecosystem moat.
For Market Incumbents: Shield formulation expertise by acquiring distressed ring-opening polymerization talent from academic programs pivoting toward battery substrates, and deepen captive lactide-glycolide production in Germany to preempt REACH-mandated purity ceiling compliance costs that disadvantage non-integrated competitors. For New Entrants and Emerging Players: Anchor in Chinese pharmaceutical channel access by licensing continuous flow reactor designs from Korean equipment suppliers at capital costs below traditional stirred-tank installations, targeting domestic long-acting injectable developers seeking to reduce import dependency for PLGA microspheres. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among medical-grade polymer houses with validated drug master file portfolios and dedicated quality infrastructure, positioning them as prime acquisition targets over commodity fermentation operators; monitor EMA Medical Device Regulation harmonization progress as the inflection signal for European vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Evonik Industries' captive lactide-glycolide production controls feedstock quality for medical-grade PLGA formulations. |
| Continuous Flow Reactor Deployment | Korean equipment suppliers enable mid-sized pharmaceutical developers to bring glycolide polymer synthesis in-house. |
| Long-term Supply Agreement | Mitsui Chemicals' offtake structures with Japanese suture manufacturers demonstrate viable Asian market entry pathways. |
| Regulatory Submission Support Investment | Swiss device developers pre-engage Swissmedic to align extended degradation study protocols before pivotal trials commence. |
| Specialized Talent Acquisition | Materials science academic pivots toward energy storage create distressed valuations for glycolide synthesis expertise. |
Research Methodology
The analysis maps PLGA copolymer, PGA homopolymer, PLA, and PCL product grades, each validated through polymer chemists at medical device OEMs, pharmaceutical formulation scientists, regulatory affairs specialists, and procurement managers at integrated delivery networks, combining primary interviews with secondary validation against FDA drug master file submissions, EMA Medical Device Regulation guidance documents, REACH compliance databases, and pharmacopeial monograph revisions, with bottom-up and top-down triangulation across fermentation capacity disclosures and surgical suture import records.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling across copolymer ratio specifications, application categories spanning drug delivery systems through tissue engineering, formulation types from granules through films, and end-user archetypes distinguishing big pharma from research institutions, deriving CAGRs from degradation kinetic documentation requirements and regulatory submission pipeline analysis without year-specific assumptions.
Material uncertainties — pharmacopeial monograph revisions, EMA MDR implementation delays, fermentation feedstock price volatility — sit outside the modeled envelope; forecasts reflect assumptions about regulatory harmonization progress and polymer chemist pipeline recovery that could shift competitive positioning substantially. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Paper Processing Resins Market
Polymers & Resins
Polyurethane (PU) Microspheres Market
Polymers & Resins
Thermosetting Plastics Market
Polymers & Resins
Vinyl Acetate Monomer (VAM) Market
Polymers & Resins
Neoprene Market
Polymers & Resins
Plastisols Market
Polymers & Resins
Global Cyanate Ester Resins Market
Polymers & Resins
Polyolefin Wax Market
Polymers & Resins
Thermoplastic Polyurethane (TPU) Market
Polymers & Resins
Polyol Esters Market
Polymers & Resins
Resin Dispersion Market
Polymers & Resins
Europe Polyolefin Market
Polymers & Resins
Ethylene Copolymer Market
Polymers & Resins
MDI, TDI, and Polyurethane Market
Polymers & Resins
Styrenics Market
Polymers & Resins
Global Styrene Acrylic Emulsion Polymer Market