
 Solid-Grade Thermoplastic Acrylic (Beads) Resin Market | 2026-2036
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market Analytics
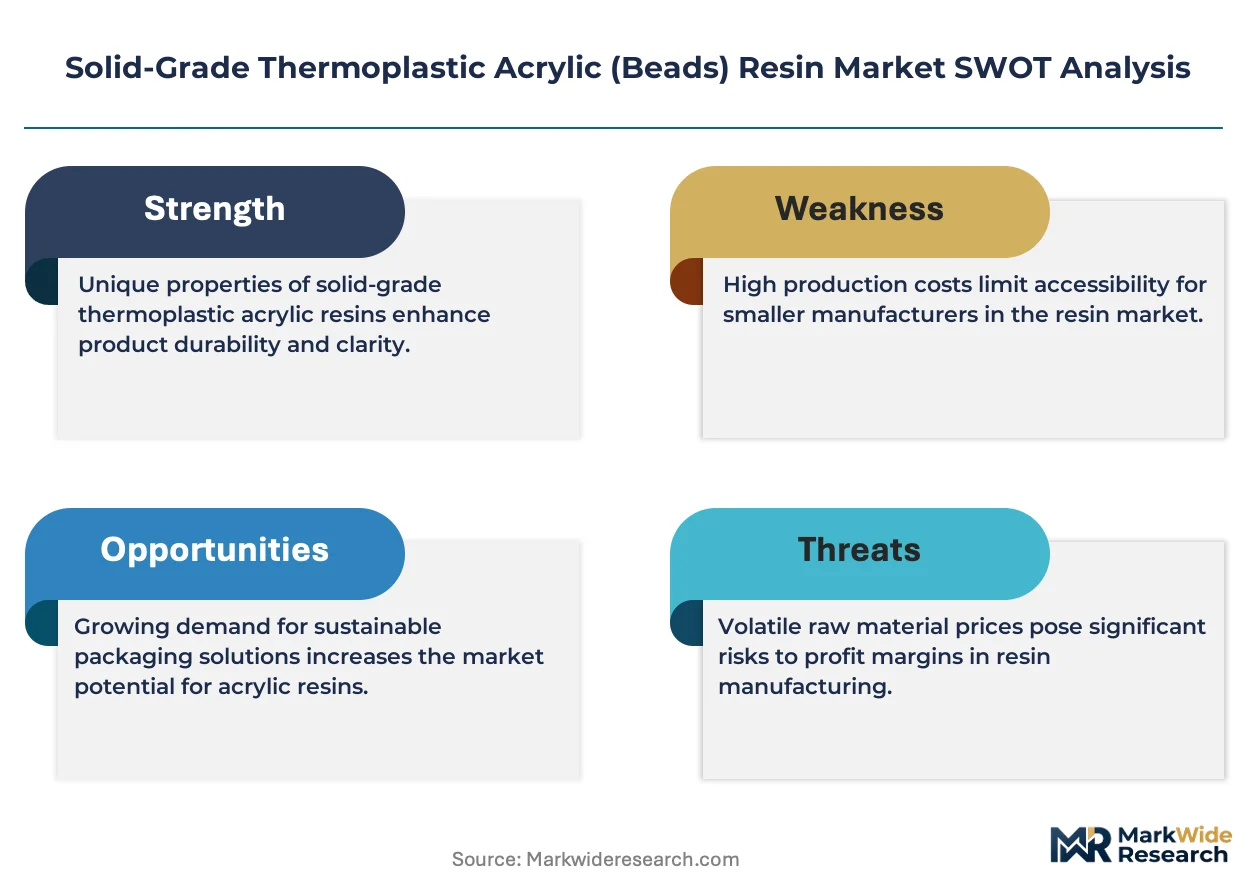
EU REACH restrictions on volatile organic compound emissions is shifting procurement priorities across European coatings formulators toward low-solvent solid-grade systems. Covestro AG leverages its backward integration into methacrylate monomers to sustain cost-competitive bead production at scale. Röhm GmbH anchors its position through specialized PMMA bead grades optimized for automotive clearcoat applications. Mitsubishi Chemical Corporation differentiates via proprietary suspension polymerization technology that yields narrow particle-size distribution.
Solid-grade thermoplastic acrylic beads are spherical polymer particles synthesized through suspension or emulsion polymerization of methyl methacrylate and comonomers, typically ranging from 10 to 200 microns in diameter, engineered for dispersion in solvent-borne or water-based coating matrices to impart hardness, gloss retention, and weatherability. The beads product type dominates volume consumption in automotive refinish and OEM coating segments where controlled particle morphology determines optical performance and scratch resistance. Films and sheets applications represent the fastest-expanding structural category, driven by electronics display laminates and architectural glazing interlayers where thermoplastic processability replaces thermoset alternatives. Coatings applications retain the deepest margin pools due to formulation complexity and technical service requirements that lock in supplier relationships.
EPA National Emission Standards for Hazardous Air Pollutants in the United States and China's GB standards on industrial volatile organic compound limits are tightening permissible solvent content in coating formulations, directly expanding addressable demand for solid-grade bead systems that reduce liquid carrier requirements. ECHA REACH authorization processes for methacrylate monomer precursors are reshaping raw material access conditions for European producers, favoring integrated manufacturers with captive monomer supply. Stakeholders must monitor evolving substance restriction timelines and calibrate capital allocation between bead capacity expansion and alternative resin platform development.
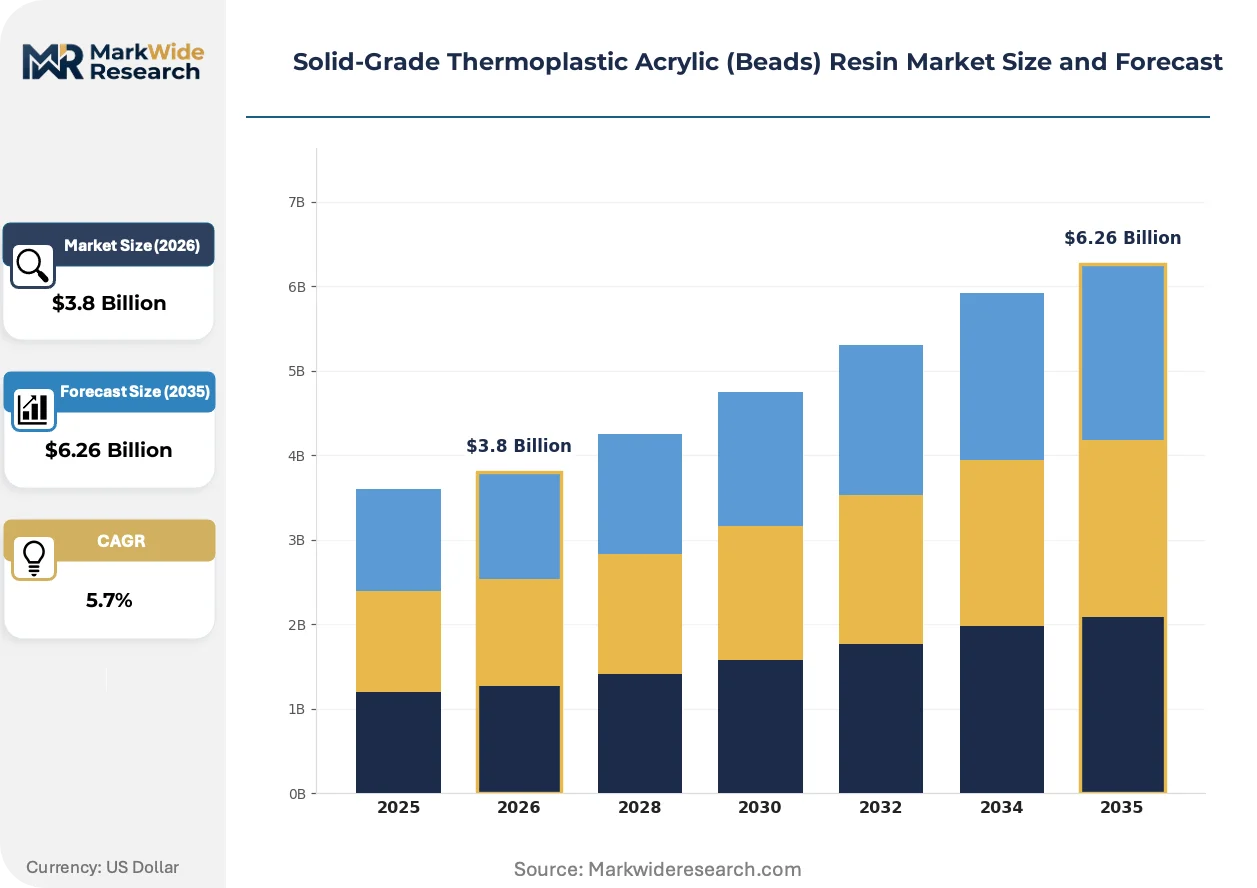
Market Dynamics
REACH restrictions on volatile organic compound emissions are redirecting European coatings formulators toward solid-grade bead systems that minimize solvent carriers, while automotive OEMs in Germany and Japan expand specification of thermoplastic acrylic beads for exterior clearcoats.
Growth Catalysts
- Automotive OEM Specification:German and Japanese vehicle manufacturers are expanding thermoplastic acrylic bead adoption in exterior coating systems to meet durability and gloss retention requirements.
- ECHA REACH Compliance:Restrictions on solvent-borne alternatives across European coatings applications are redirecting formulation demand toward solid-grade bead systems with reduced volatile organic compound content.
- Yangtze River Delta Concentration:China's chemical manufacturing corridor is consolidating bead production capacity to serve regional coatings and electronics laminates demand.
Market Restraints
- Methacrylate Monomer Volatility:Fluctuating methyl methacrylate feedstock costs compress margin stability for non-integrated bead producers lacking captive monomer supply.
- European Supply Concentration:ECHA REACH authorization processes for methacrylate precursors favor integrated manufacturers with backward integration, constraining raw material access for independent formulators.
- Water-Borne Formulation Limits:Technical constraints on bead dispersion stability in high-water-content matrices restrict substitution rates in certain industrial coating segments.
Strategic Opportunities
- Electronics Display Laminates:Films and sheets applications for architectural glazing and display interlayers represent underpenetrated demand expansion beyond traditional coatings.
- EPA NESHAP Alignment:United States National Emission Standards for Hazardous Air Pollutants are tightening solvent content limits, expanding addressable demand for solid-grade systems in North American industrial coatings.
- Suspension Polymerization Advancement:Narrow particle-size distribution technologies are enabling premium automotive clearcoat applications with enhanced optical performance specifications.
Industry Challenges
- Formulation Technical Service Capacity:Coatings applications require deep technical support relationships that strain specialist producer resources against integrated chemical majors.
- Dual Carbon Transition Complexity:China's GB standards on industrial volatile organic compound limits and dual carbon goals are forcing simultaneous reconfiguration of production processes and supply chain logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid-Grade Thermoplastic Acrylic (Beads) Resin Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beads, Films, Sheets, Coatings Application: Automotive, Construction, Electronics, Consumer Goods End User: Manufacturers, Retailers, Distributors, OEMs Distribution Channel: Online, Direct Sales, Wholesale, Retail |
| Companies Covered | Covestro AG, LG Chem Ltd., Röhm GmbH, Sumitomo Chemical Co. Ltd., Arkema S.A., Mitsubishi Chemical Corporation, Dow Inc., Wanhua Chemical Group Co. Ltd., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market Evolving Landscape
Polymerization technology advancement and regulatory emission limits are converging to reshape product specifications and procurement criteria across coatings and structural applications.
Advanced suspension polymerization systems with narrow particle-size distribution control are absorbing specification share in premium automotive clearcoat segments. Tier-1 automotive suppliers and refinish formulators are adopting these grades at accelerated rates to meet OEM gloss retention and scratch resistance benchmarks. The technology is absorbing margin pools previously captured by conventional bead grades with broader distribution profiles.
ECHA REACH authorization timelines for methacrylate monomer precursors are compressing raw material access windows for European non-integrated producers. Integrated manufacturers with captive monomer supply are securing preferential positioning in authorization queues. Coatings formulators dependent on external bead supply are diversifying supplier relationships to mitigate concentration risk.
Specification-driven procurement is consolidating around technical service capabilities rather than commodity pricing alone. Large automotive OEMs and industrial coatings buyers are unbundling after-sales support from product supply, creating preference premiums for producers with embedded formulation expertise. This pattern is most pronounced in German automotive supply chains and Japanese industrial coatings distribution networks.
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market Segmentation
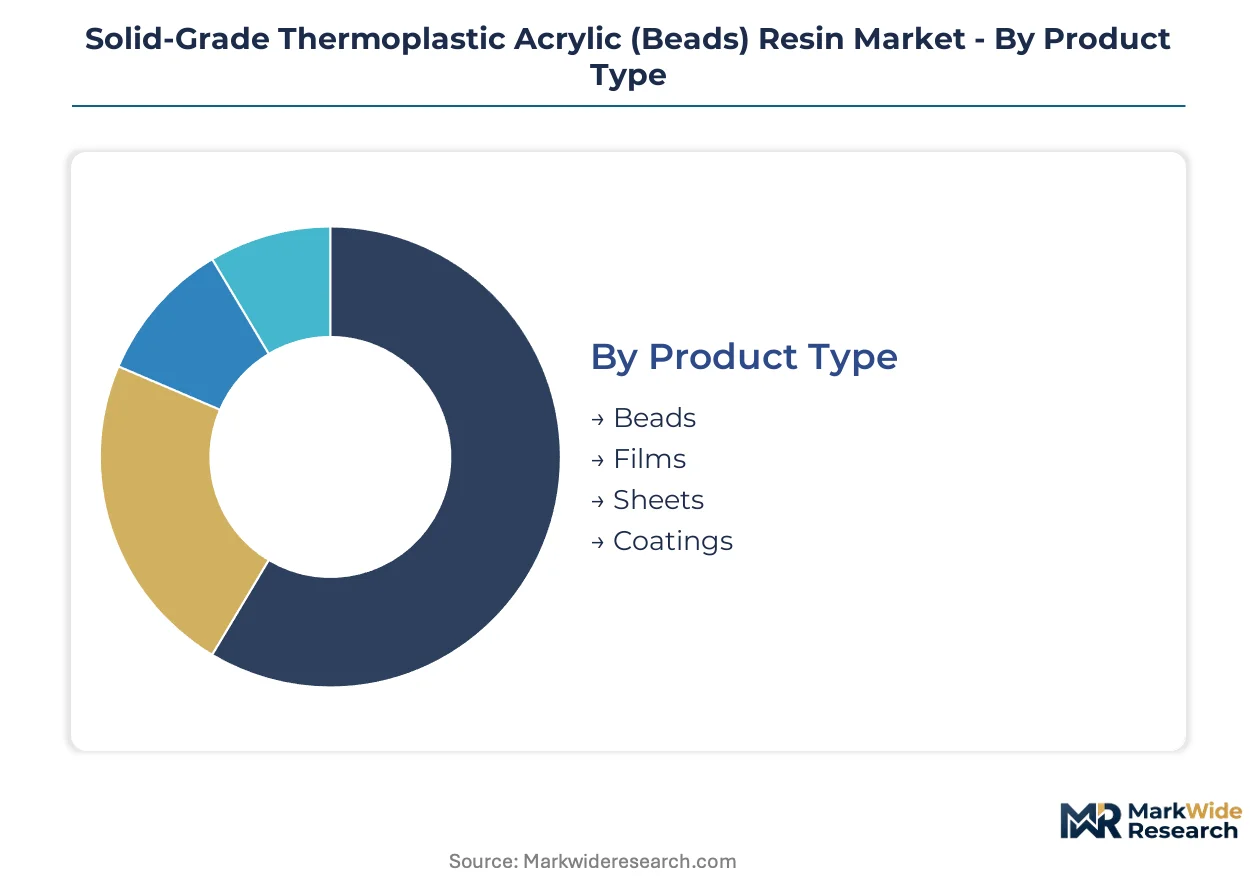
Segmentation in solid-grade thermoplastic acrylic beads reveals distinct procurement patterns across formulation complexity tiers. Buyers prioritize particle morphology control in automotive coatings while electronics laminates drive specification divergence in structural forms.
Product Type:
Formulation viscosity requirements and thermal processing windows determine buyer selection across product categories.
- Beads:Spherical polymer particles ranging 10 to 200 microns synthesized through suspension polymerization of methyl methacrylate comonomers. Demand concentrates in German and Japanese automotive OEM clearcoat specifications where controlled particle morphology governs optical performance and scratch resistance benchmarks.
- Films:Extruded thermoplastic layers engineered for display laminates and glazing interlayers. Electronics manufacturers in China's Yangtze River Delta are expanding procurement of these grades to replace thermoset alternatives in architectural and consumer electronics applications.
- Sheets:Cast or extruded PMMA panels for structural glazing and signage substrates. Construction specifiers favor these for weatherability and thermoformability in facade applications.
- Coatings:Pre-dispersed resin systems for solvent-borne and water-based matrices. Formulators value these for reduced volatile organic compound content under tightening EPA NESHAP and ECHA REACH emission limits.
Beads lead on scale; films lead on momentum.
Application:
End-use performance thresholds and regulatory exposure shape segment prioritization for suppliers.
- Automotive:Exterior clearcoats and refinish systems demanding gloss retention and mar resistance. German OEMs specify narrow particle-size distribution grades at expanding rates for durability benchmarking.
- Construction:Architectural glazing, facade cladding, and protective coatings. Specifiers prioritize weatherability certification and regional building code compliance.
- Electronics:Display laminates, optical films, and device housings. This segment climbs the fastest as display manufacturers replace glass with PMMA interlayers for weight reduction.
- Consumer Goods:Cosmetic packaging, lighting fixtures, and decorative surfaces. Brand owners source these for aesthetic clarity and recyclability positioning.
Automotive leads on scale; electronics leads on momentum.
End User:
Technical service intensity and volume scale differentiate procurement relationships across buyer types.
- Manufacturers:Integrated coatings and plastics producers with captive formulation capabilities. These buyers source raw beads for in-house dispersion and compounding operations.
- Retailers:Specialty chemical distributors serving small-batch industrial accounts. Inventory breadth and just-in-time availability determine supplier selection.
- Distributors:Regional logistics intermediaries consolidating shipments for fragmented downstream demand. Margin compression from bulk purchasing power shapes their sourcing strategy.
- OEMs:Tier-1 automotive suppliers and electronics assemblers with direct material specification authority. These buyers unbundle technical support from product supply, creating preference premiums for embedded formulation expertise.
Manufacturers lead on scale; OEMs lead on momentum.
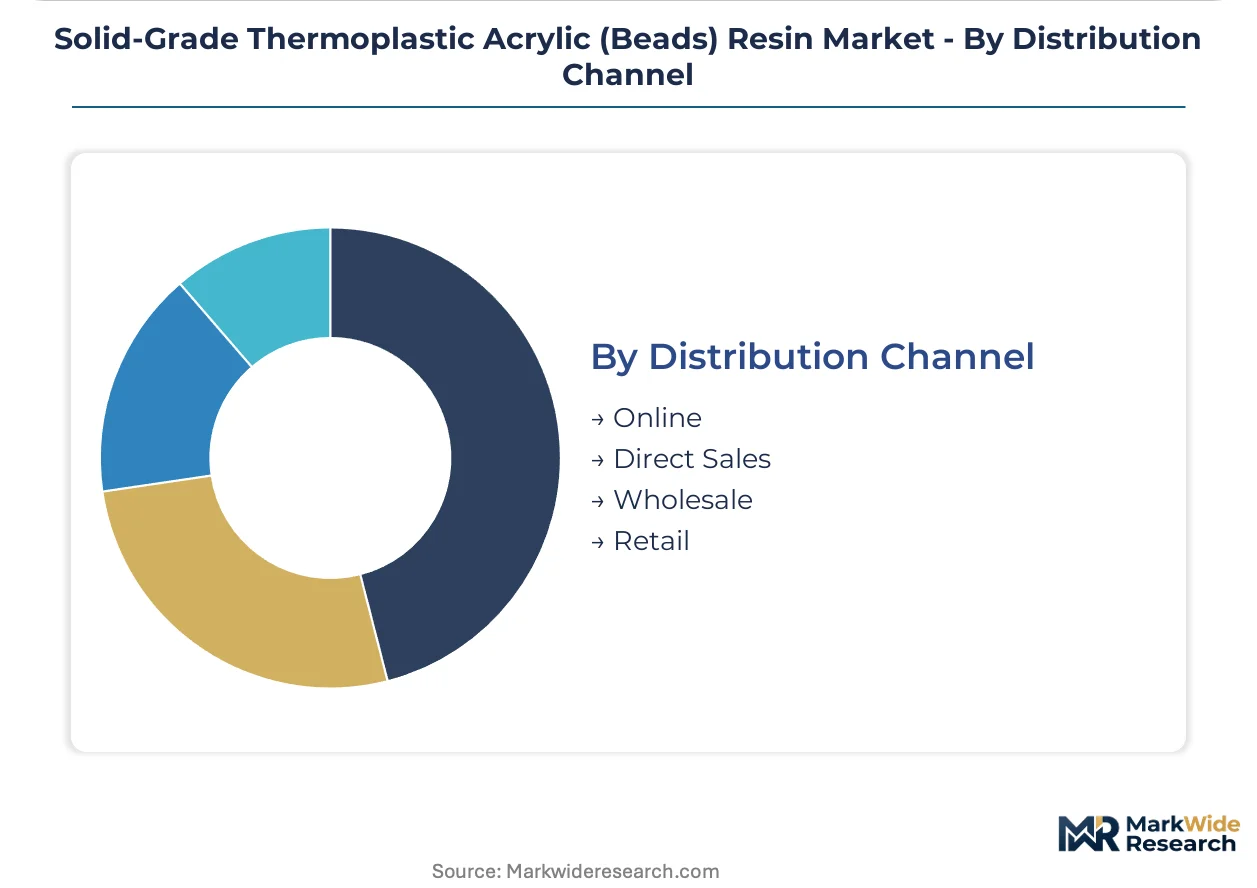
Distribution Channel:
Order size, technical support requirements, and geographic coverage determine channel selection patterns.
- Online:Digital procurement platforms for standardized grades and small volumes. Buyers value specification transparency and rapid price discovery for non-critical applications.
- Direct Sales:Manufacturer-to-buyer relationships for high-volume automotive and electronics accounts. These channels absorb the deepest margin pools due to formulation co-development requirements.
- Wholesale:Bulk intermediaries aggregating demand across multiple industrial sectors. Regional concentration in China's Yangtze River Delta chemical corridor supports efficient inventory positioning.
- Retail:Counter sales and local stockists for maintenance, repair, and small-project demand. Geographic proximity outweighs price sensitivity for urgent procurement needs.
Direct sales lead on scale; online leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial-scale production of solid-grade thermoplastic acrylic beads originated in post-war Germany and Japan, where specialized polymerization techniques developed for optical applications. These foundational manufacturing clusters established technical standards that persist in today's premium automotive and electronics specifications.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria specify narrow particle-size distribution grades for exterior clearcoat durability benchmarking. ECHA REACH authorization processes for methacrylate precursors favor producers with captive monomer supply chains. The Rhine-Ruhr chemical corridor concentrates backward-integrated bead manufacturing to serve Tier-1 supplier networks.
China
Electronics laminates manufacturers in the Yangtze River Delta drive specification divergence toward films and sheets applications. GB standards on industrial volatile organic compound limits force simultaneous reconfiguration of production processes and supply chain logistics. Shanghai and surrounding Jiangsu province cities consolidate bead production capacity for regional coatings demand.
Japan
Display manufacturers replace glass with PMMA interlayers for weight reduction in consumer electronics. METI industrial standards shape procurement criteria for optical-grade bead specifications. The Kansai region around Osaka anchors suspension polymerization expertise for premium automotive clearcoat applications.
United States
Industrial coatings formulators respond to EPA National Emission Standards for Hazardous Air Pollutants by expanding solid-grade system adoption. The Gulf Coast petrochemical corridor supports methacrylate monomer production for bead manufacturing feedstock. Texas and Louisiana facilities serve automotive refinish markets across North America.
South Korea
Electronics assemblers in the Seoul Capital Area source specialized bead grades for display laminate interlayers. Domestic chemical producers leverage proximity to Samsung and LG display manufacturing clusters. Busan-Ulsan industrial complexes support both monomer production and downstream bead compounding operations.
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation technical service capabilities and captive monomer supply integration. The vendor base organizes into three tiers: integrated chemical majors with backward integration into methacrylate monomers, specialist bead producers with proprietary suspension polymerization technology, and regional compounders serving fragmented industrial demand. Consolidation pressures concentrate among mid-scale European producers facing ECHA REACH authorization bottlenecks. Dominant competitive moves include capacity expansion in China's Yangtze River Delta and strategic partnerships locking in automotive OEM specification relationships.
Among integrated chemical majors, Covestro AG and Mitsubishi Chemical Corporation exemplify archetypes of backward-integrated producers controlling methacrylate monomer supply chains. Röhm GmbH occupies a specialist position within the premium-tier segment, representing manufacturers with proprietary polymerization technologies optimized for narrow particle-size distribution requirements. These three anchors demonstrate how geographic origin and corporate structure correlate with strategic positioning: German GmbH and AG entities alongside Japanese kabushiki gaisha structures dominate high-margin specification-driven procurement channels.
| Leading Market Players |
|---|
| Covestro AG |
| LG Chem Ltd. |
| Röhm GmbH |
| Sumitomo Chemical Co. Ltd. |
| Arkema S.A. |
| Mitsubishi Chemical Corporation |
| Dow Inc. |
| Wanhua Chemical Group Co. Ltd. |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap German specialists anchor premium pricing discipline through embedded technical service relationships with Baden-Württemberg automotive OEMs, while their limited captive monomer access forces reliance on spot methyl methacrylate markets that transmit feedstock volatility directly into margin compression.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates narrow particle-size distribution grades for automotive clearcoats from commodity beads serving industrial maintenance coatings. Price differentiation stems from certification tier and after-sales bundling intensity. Cost compression in standard grades is intensifying because Yangtze River Delta producers are expanding bead capacity without matching technical service infrastructure. Small-batch refinish formulators exhibit highest price sensitivity; Tier-1 automotive suppliers with unbundled procurement show lowest.
Supply Chain Analysis
Methyl methacrylate feedstock supply rests on integrated producers in Germany, Japan, and the United States Gulf Coast, with merchant monomer markets drawing from spot-traded volumes in South Korea and China. Key inputs include methacrylate monomers, suspension polymerization initiators, and specialized bead classification equipment. Single-source vulnerability concentrates in European REACH authorization queues for monomer precursors. Distribution runs through direct sales channels for automotive OEM accounts and wholesale intermediaries for fragmented industrial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Solid-Grade Thermoplastic Acrylic (Beads) Resin Market functions as a stable compounder, with regulatory emission limits across multiple geographies ensuring steady substitution demand for low-solvent solid-grade systems.
For Market Incumbents: Deploy backward integration into methacrylate monomers to defend margin stability against feedstock volatility threatening non-integrated European producers. Expand suspension polymerization capacity in China's Yangtze River Delta to capture electronics laminates growth while ECHA REACH authorization bottlenecks constrain regional competitor supply. For New Entrants and Emerging Players: Begin with display laminate interlayers for consumer electronics manufacturers in South Korea's Seoul Capital Area, where optical-grade bead specifications remain underpenetrated by established coatings-focused incumbents. Pursue technical partnership routes with Samsung and LG supply chain engineering teams rather than direct OEM qualification. For Investors and Strategic Acquirers: Integrated chemical majors with captive monomer supply are the most active acquirer in this space, targeting mid-scale European specialists facing ECHA authorization constraints. Long-term viability hinges on automotive OEM specification lock-in durability. Watch for EPA NESHAP enforcement acceleration as inflection signal for North American demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomers | Covestro AG and Mitsubishi Chemical Corporation secure feedstock cost stability against merchant MMA volatility. |
| Suspension Polymerization Scale-Up | Narrow particle-size distribution capacity expansion captures premium automotive clearcoat specification share. |
| Long-term Supply Agreement | Direct sales relationships with German Tier-1 suppliers lock in multi-year technical service contracts. |
| Joint Venture | Yangtze River Delta partnerships with Wanhua Chemical Group Co. Ltd. access regional electronics laminates demand. |
| Green Manufacturing Transition | Water-borne bead dispersion R&D aligns with EPA NESHAP and ECHA REACH emission limit trajectories. |
Research Methodology
Direct dialogue with coatings formulators, automotive OEM procurement directors, suspension polymerization plant managers, and electronics display laminate engineers grounded this analysis, cross-referenced against customs trade data, ACC and Cefic chemical industry reports, SEC 10-K filings, and ECHA substance authorization databases. Bottom-up bead volume estimates triangulated with top-down coatings market sizing across the analysis window.
Segment-level projections incorporated grade tier, end-use industry, and regional production hub dimensions throughout the forecast period. CAGRs derived from regression analysis of historical methyl methacrylate consumption patterns, automotive OEM specification adoption curves, and regulatory emission limit implementation schedules. Model inputs included REACH authorization timeline probabilities and GB standards enforcement intensity assumptions.
Several conditions sit outside the modeled scope, including unannounced methacrylate monomer plant closures, automotive platform engineering changes affecting clearcoat specifications, and suspension polymerization technology breakthroughs. Forecasts reflect documented assumptions about regulatory enforcement continuity and feedstock supply elasticity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Poly (1-Decene) Market
Polymers & Resins
Global Polyphthalamide Market
Polymers & Resins
Metallocene Polyolefin Market
Polymers & Resins
Polyimide Resin Market
Polymers & Resins
Asia-Pacific Polyamide Market
Polymers & Resins
Europe Polyolefin Foam Market
Polymers & Resins
Vinyl Acetate Emulsion Polymers Market
Polymers & Resins
Seed Polymers Market
Polymers & Resins
Biopolymer Tubes Market
Polymers & Resins
Global Opaque Polymers Market
Polymers & Resins
Amorphous Polyolefin Market
Polymers & Resins
Middle East Engineering Plastics Market
Polymers & Resins
Polyalkylene Glycols (Pags) Market
Polymers & Resins
Global Ultra-High Molecular Weight Polyethylene Market
Polymers & Resins
Vinyl Acetate Ethylene (VAE) Market
Polymers & Resins
Europe Polyurethane Market