
 Japan Methanol Market | 2026-2036
Japan Methanol Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Methanol Market Insights
Natural gas is shifting away from naphtha as the dominant feedstock for Japanese methanol production, altering unit economics across the Kanto and Kansai industrial belts. Mitsubishi Gas Chemical Company leverages its integrated syngas-to-derivatives platform to sustain cost advantages in formaldehyde and methyl tert-butyl ether chains. JX Nippon Oil & Energy Corporation anchors supply reliability through its coastal refining and import terminal network. Mitsui & Co. competes by controlling seaborne methanol trade flows into Yokkaichi and Kashima.
Methanol is a light, volatile alcohol with the chemical formula CH3OH, produced industrially via steam reforming of natural gas or coal gasification followed by catalytic synthesis; its purity grades range from fuel-grade at 99.85% to chemical-grade at 99.95% for specialty applications. The substance functions primarily as a chemical building block for formaldehyde, acetic acid, and methyl methacrylate, while emerging energy applications exploit its hydrogen carrier properties and direct combustion characteristics. Chemical Grade methanol dominates margin pools due to stringent purity requirements in pharmaceutical and electronics solvents, whereas Fuel Grade volumes are accelerating fastest as METI-backed pilot projects test methanol bunkering at Yokohama and Nagoya ports. Feedstock segmentation remains mature, with industrial buyers in plastics and construction channeling procurement through long-term offtake contracts rather than spot markets.
METI enforces fuel quality standards under the Act on the Quality Control of Gasoline and Other Fuels, while JIS K 1501 governs methanol purity for chemical applications and the Industrial Safety and Health Act mandates workplace exposure limits through the Japan Industrial Standards Committee. These frameworks elevate compliance costs for importers but simultaneously protect domestic producers from lower-grade foreign supply. Stakeholders must monitor METI's evolving hydrogen strategy and port infrastructure investments to determine whether methanol retains its position as a transitional fuel or becomes stranded by direct ammonia or hydrogen adoption.
Market Dynamics
METI's carbon neutrality roadmap is compressing feedstock specifications across Japan's methanol value chain, forcing producers to abandon naphtha cracking in favor of natural gas reforming and imported low-carbon methanol. This regulatory pressure is redrawing competitive boundaries between coastal importers and domestic syngas operators.
Growth Catalysts
- Automotive fuel diversification:Japanese OEMs are testing methanol direct injection and methanol-hydrogen co-firing in next-generation powertrains, creating pull-through demand from Toyota and Honda R&D programs.
- METI port infrastructure mandates:Government-backed bunkering pilots at Yokohama and Nagoya are establishing methanol as a compliant marine fuel under the International Maritime Organization's 2025 carbon intensity regulations.
- Osaka-Kobe petrochemical clustering:Dense buyer concentration around the Keihin industrial zone enables pipeline-connected distribution and reduces logistics friction for formaldehyde and acetic acid producers.
Market Restraints
- Natural gas import dependency:Japan lacks indigenous methane reserves, exposing steam reforming economics to LNG price volatility and yen-dollar exchange rate swings.
- Chinese supply concentration:Over 60% of seaborne methanol arriving at Yokkaichi and Kashima originates from coal-gasification plants in Shaanxi and Inner Mongolia, creating single-source vulnerability.
- Ammonia substitution threat:METI's parallel hydrogen carrier investments favor ammonia for power generation co-firing, potentially leapfrogging methanol in the national decarbonization hierarchy.
Strategic Opportunities
- Carbon capture integration:Blue methanol production using captured CO2 from steel and cement facilities offers compliance arbitrage against JIS K 1501 purity standards.
- Chiba refining complex repurposing:Decommissioned fluid catalytic cracking units can retrofit to methanol-to-olefins service, extending asset life for JX Nippon Oil & Energy Corporation.
- Electronics-grade solvent demand:Semiconductor fabs in Kumamoto and Hiroshima require 99.95% chemical-grade methanol for photoresist stripping, commanding margin premiums over fuel-grade volumes.
Industry Challenges
- Catalyst supply bottleneck:Domestic syngas producers depend on imported copper-zinc-alumina catalysts from German and Chinese suppliers, with 18-month order backlogs disrupting turnaround schedules.
- Workforce transition friction:Naphtha-cracking veterans lack training in natural gas reforming and carbon capture operations, slowing plant conversions in the Kansai belt.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Methanol Market |
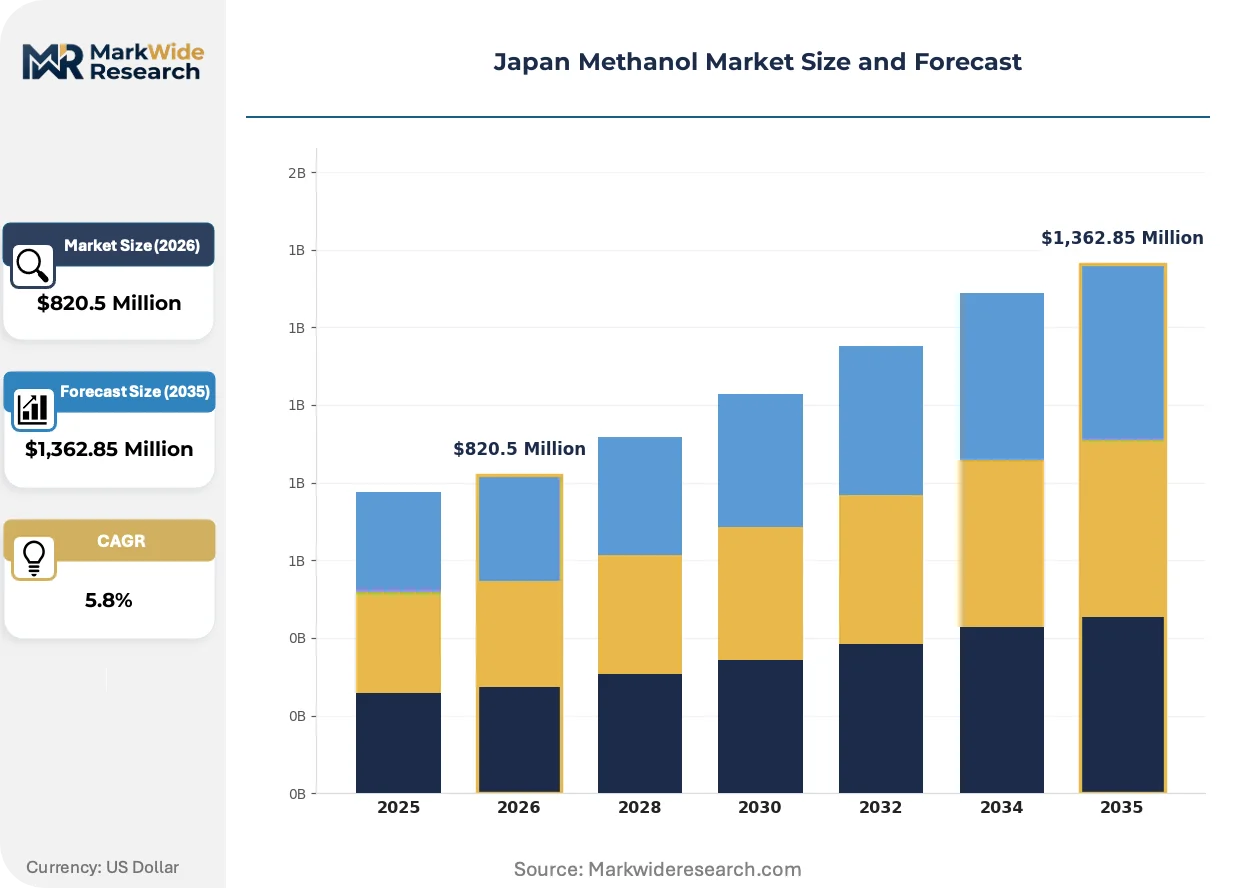
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,362.85 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Grade, Chemical Grade, Industrial Grade, Feedstock Application: Fuel, Solvent, Chemical Synthesis, Adhesives End User: Automotive, Construction, Healthcare, Plastics Distribution Channel: Direct Sales, Wholesale, Retail, Online |
| Companies Covered | Methanex Corporation, JX Nippon Oil & Energy Corporation, Mitsubishi Gas Chemical Company, Sumitomo Corporation, Japan Energy Corporation, Mitsui & Co., Toyo Soda Manufacturing, Idemitsu Kosan Co., Ltd., Showa Denko K.K., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Methanol Market Trends and Innovations
Japan's methanol sector is converging on dual-use infrastructure that serves both chemical feedstock and energy carrier applications. This functional overlap is compressing traditional segment boundaries and forcing asset reinvestment decisions.
Biomethanol production via gasification of construction wood waste is unifying circular economy mandates with industrial chemical supply. Forestry cooperatives in Hokkaido and Kyushu are aggregating feedstock for 50,000-tonne-per-year demonstration plants. This distributed production model is undermining the historical dominance of mega-scale coastal import terminals.
METI's 2023 Hydrogen Strategy revision tightened specifications for methanol-derived hydrogen used in fuel cell vehicles, requiring sulfur content below 0.1 ppm. Refiners in Chiba and Yokkaichi are installing additional hydrotreating capacity to meet this standard. The pharmaceutical and electronics solvent segments absorb these compliance costs most readily due to existing purity protocols.
Long-term offtake contracting is displacing spot market participation among construction and plastics manufacturers. Buyers in the Osaka-Kobe corridor now favor 36-month fixed-price agreements with volume flexibility clauses rather than quarterly tenders. This shift is most pronounced in formaldehyde derivatives used for engineered wood panels, where resin producers seek feedstock cost predictability.
Japan Methanol Market Segmentation
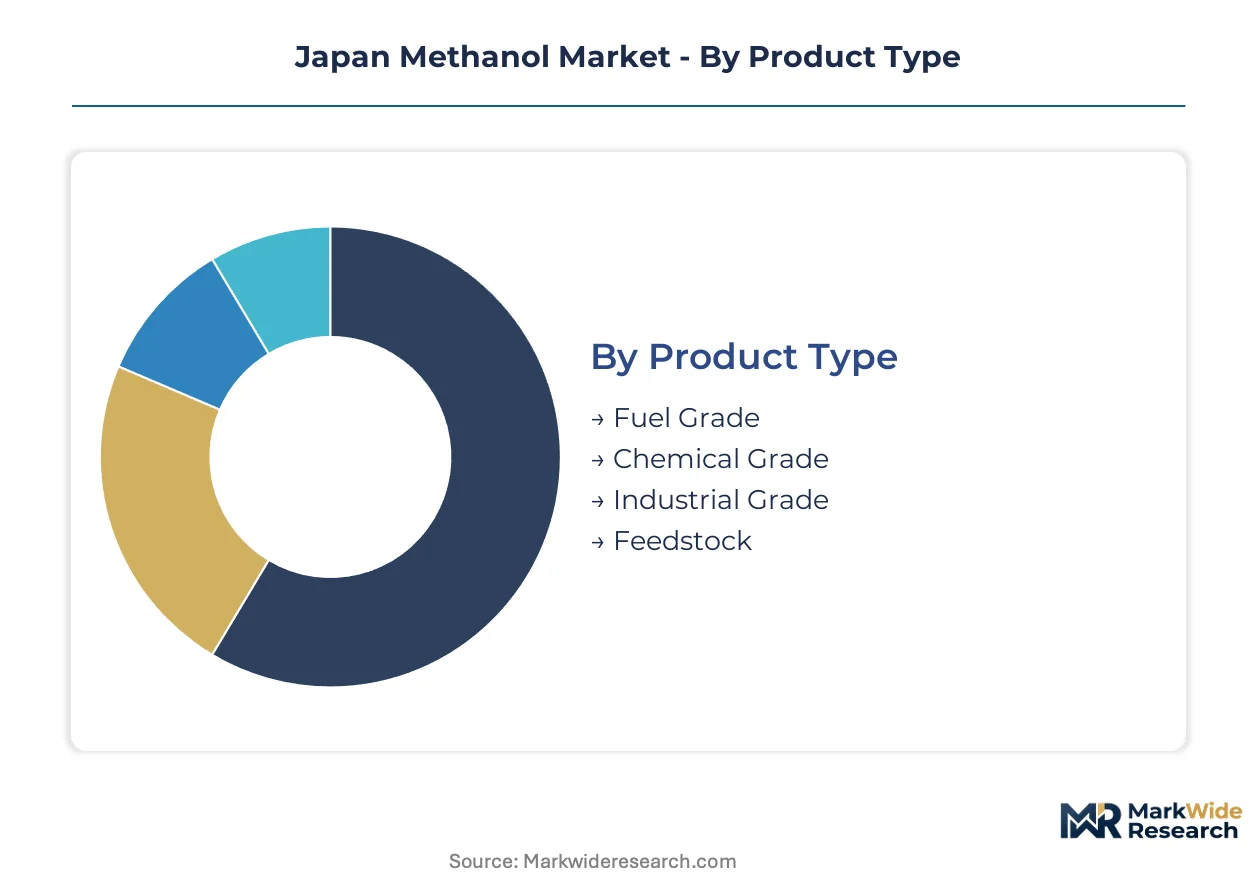
Segmentation in Japan's methanol market reflects divergent compliance burdens across METI fuel standards, JIS K 1501 chemical specifications, and sector-specific purity thresholds. Understanding these divides clarifies procurement patterns among Osaka-Kobe formaldehyde producers and Chiba fuel-blending operators.
Product Type:
METI's fuel quality enforcement under the Act on the Quality Control of Gasoline and Other Fuels imposes tiered certification burdens, with chemical-grade methanol requiring JIS K 1501 validation and fuel-grade volumes facing bunkering-specific sulfur limits.
- Chemical Grade:Purity specifications of 99.95% minimum govern pharmaceutical and electronics solvent applications. Semiconductor fabs in Kumamoto and Hiroshima absorb premium pricing for photoresist stripping compliance under JIS K 1501 protocols.
- Fuel Grade:99.85% purity suffices for marine bunkering and automotive blending trials. Yokohama and Nagoya port infrastructure investments by METI are accelerating uptake among coastal shipping operators facing IMO carbon intensity regulations.
- Industrial Grade:Intermediate purity bands serve construction adhesive and general solvent markets with reduced testing overhead.
- Feedstock:Unrefined methanol streams enter syngas-to-derivatives chains at Mitsubishi Gas Chemical and JX Nippon Oil facilities without terminal distribution.
Chemical Grade sits at the top of the volume ranking, with Fuel Grade climbing the fastest.
Application:
Application segmentation tracks margin dispersion across energy-transition pilots versus mature chemical conversion economics, with fuel applications capturing policy premiums and solvent volumes defending established margin pools.
- Chemical Synthesis:Formaldehyde, acetic acid, and methyl methacrylate production consumes the majority of Japanese methanol throughput. Osaka-Kobe petrochemical corridors concentrate demand through pipeline-connected formaldehyde plants serving engineered wood panel manufacturers.
- Fuel:Direct methanol injection and hydrogen carrier trials by Toyota and Honda R&D programs are pulling volumes away from traditional chemical channels. METI-backed bunkering infrastructure at Yokohama and Nagoya is establishing marine fuel offtake.
- Solvent:Electronics-grade stripping and pharmaceutical extraction maintain steady demand under existing JIS purity protocols.
- Adhesives:Construction sector consumption flows through long-term offtake contracts rather than spot procurement.
Chemical Synthesis commands the largest revenue share, while Fuel applications are expanding most quickly.
End User:
End user segmentation reveals divergent procurement sophistication, with automotive and plastics buyers negotiating multi-year contracts while construction and healthcare sectors prioritize supply security over price optimization.
- Plastics:Methyl methacrylate and formaldehyde resin producers in the Keihin industrial zone anchor methanol demand through 36-month fixed-price agreements with volume flexibility clauses.
- Automotive:OEM testing programs for methanol-hydrogen co-firing are creating pilot-scale demand distinct from mass-market fuel economics.
- Construction:Engineered wood panel manufacturers channel procurement through formaldehyde derivative suppliers rather than direct methanol sourcing.
- Healthcare:Pharmaceutical solvent requirements under JIS K 1501 impose batch-level traceability that elevates supplier qualification costs.
Plastics sits at the top of the volume ranking, with Automotive gaining share fastest.
Distribution Channel:
Channel segmentation reflects supply chain concentration around coastal import terminals versus distributed demand clusters, with direct sales capturing volume premiums and wholesale channels serving fragmented inland buyers.
- Direct Sales:Pipeline-connected formaldehyde and acetic acid producers in Chiba and Osaka-Kobe purchase directly from Mitsubishi Gas Chemical and JX Nippon Oil syngas facilities, bypassing terminal markups.
- Wholesale:Regional distributors aggregate volumes for construction adhesive and general solvent buyers across Kyushu and Hokkaido, absorbing inventory risk against spot price volatility.
- Retail:Small-volume pharmaceutical and laboratory solvent buyers access chemical-grade methanol through specialized chemical distributors with JIS certification documentation.
- Online:Digital procurement platforms are emerging for standard-grade solvent volumes, though purity documentation requirements limit adoption in regulated applications.
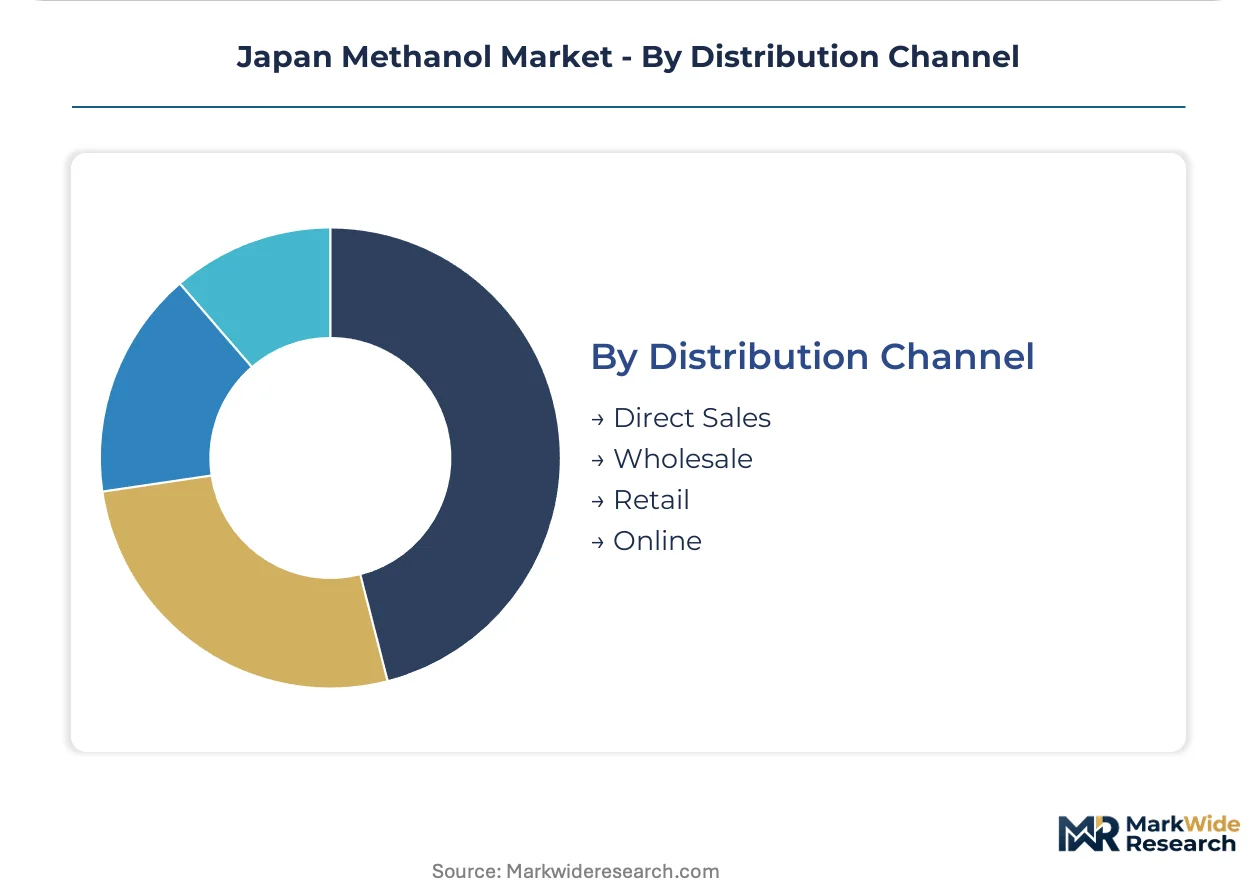
Direct Sales sits at the top of the volume ranking, with Wholesale maintaining stable share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Osaka-Kobe petrochemical corridor anchors Japanese methanol consumption through pipeline-connected formaldehyde plants and acetic acid facilities. METI's carbon neutrality mandates are redrawing feedstock flows across industrial belts, compressing naphtha cracking in favor of natural gas reforming. Demand clusters concentrate around three distinct geographies with divergent compliance burdens.
Kanto/Tokyo
Semiconductor fabs in Kumamoto and photoresist stripping operations pull chemical-grade methanol volumes through the Keihin industrial zone. METI enforces JIS K 1501 purity standards that elevate supplier qualification costs for pharmaceutical solvent buyers. Chiba's integrated refining complex processes imported seaborne methanol for syngas-to-derivatives chains serving construction adhesive manufacturers.
Kansai/Osaka
Engineered wood panel producers channel procurement through formaldehyde derivative suppliers rather than direct methanol sourcing. The Act on the Quality Control of Gasoline and Other Fuels imposes tiered certification burdens on fuel-grade volumes entering marine bunkering trials. Osaka-Kobe's dense buyer concentration enables pipeline-connected distribution that reduces logistics friction for methyl methacrylate production.
Chubu/Nagoya
Toyota and Honda R&D programs are testing methanol-hydrogen co-firing in next-generation powertrains, creating pilot-scale demand distinct from mass-market fuel economics. METI-backed port infrastructure investments at Nagoya are establishing methanol as a compliant marine fuel under IMO carbon intensity regulations. Yokkaichi import terminals anchor supply reliability for regional plastics manufacturers.
Kyushu
Forestry cooperatives are aggregating construction wood waste feedstock for biomethanol demonstration plants unifying circular economy mandates with chemical supply. The Industrial Safety and Health Act mandates workplace exposure limits through the Japan Industrial Standards Committee, elevating compliance costs for distributed production models. Pharmaceutical solvent requirements in Fukuoka impose batch-level traceability that favors established distributors.
Hokkaido
Biomethanol production via gasification of forestry residues is undermining historical dominance of mega-scale coastal import terminals. METI's 2023 Hydrogen Strategy revision tightened specifications for methanol-derived hydrogen used in fuel cell vehicles, requiring additional hydrotreating capacity investments. Sapporo-based wholesale distributors aggregate volumes for general solvent buyers across northern construction markets.
Japan Methanol Market Competitive Landscape
Global majors compete with regional champions across feedstock access and coastal terminal control. The vendor base stratifies between integrated syngas operators, seaborne importers, and trading houses managing trade flows. Three archetypes dominate: natural gas reformers with captive derivatives capacity, import terminal operators securing supply reliability, and diversified traders arbitraging geographic price differentials. Capacity expansion and backward integration into syngas production represent the dominant competitive moves.
Within the integrated operator tier, Mitsubishi Gas Chemical Company and JX Nippon Oil & Energy Corporation exemplify domestic champions leveraging coastal refining assets and pipeline-connected distribution. Mitsui & Co. occupies a position among trading houses controlling seaborne methanol flows into Yokkaichi and Kashima terminals. These three entities represent distinct strategic postures: captive syngas-to-derivatives chains, import-terminal supply security, and trade-flow arbitrage respectively.
| Leading Market Players |
|---|
| Methanex Corporation |
| JX Nippon Oil & Energy Corporation |
| Mitsubishi Gas Chemical Company |
| Sumitomo Corporation |
| Japan Energy Corporation |
| Mitsui & Co. |
| Toyo Soda Manufacturing |
| Idemitsu Kosan Co., Ltd. |
| Showa Denko K.K. |
| Others |
Pricing and Supply Chain Analysis
Captive syngas-to-derivatives integration at Mitsubishi Gas Chemical and JX Nippon Oil anchors pricing power along Japan's industrial coasts, insulating domestic producers from spot volatility while exposing importers to yen-dollar swings and LNG tariff fluctuations.
Pricing Analysis
LNG-linked feedstock costs pass through to methanol contract structures with a 3-6 month lag, compressing margins when currency depreciation outpaces fuel oil index movements. Three-tier pricing structure across chemical-grade, fuel-grade, and industrial-grade levels separates semiconductor solvent buyers paying JIS K 1501 premiums from marine bunkering volumes facing IMO sulfur caps. Pricing pressure stems from Chinese coal-gasification supply flooding Yokkaichi and Kashima terminals. Plastics manufacturers in the Keihin zone show lowest price sensitivity due to 36-month fixed-price offtake agreements, while construction adhesive buyers absorb spot market exposure.
Supply Chain Analysis
METI's evolving carbon neutrality roadmap functions as a de facto local-content rule, pressuring refiners to source blue methanol with documented CO2 capture credentials rather than unverified seaborne cargoes. Supply concentrates in China, Malaysia, and Trinidad and Tobago, with Shaanxi coal-gasification plants feeding over half of Japanese import volumes. Copper-zinc-alumina catalysts from German and Chinese suppliers, LNG feedstock, and specialized tanker fleets constitute critical input dependencies. Single-source vulnerability to Chinese supply concentration creates structural risk for Chiba and Osaka-Kobe consumers. Distribution runs through coastal import terminals at Yokkaichi and Kashima, with pipeline connections serving formaldehyde and acetic acid producers directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's methanol market functions as a regulatory compounder where METI's hydrogen-methanol co-firing mandates and IMO bunkering compliance deadlines are accelerating demand formation faster than supply-side adaptation.
For Market Incumbents: Hedge against ammonia substitution by securing carbon capture integration at Chiba and Yokkaichi facilities, converting steel and cement sector CO2 streams into blue methanol certification arbitrage. Defend syngas-to-derivatives margins through backward integration into forestry waste gasification partnerships in Hokkaido and Kyushu, preempting distributed biomethanol challengers. For New Entrants and Emerging Players: Enter via electronics-grade solvent distribution gaps in Kumamoto and Hiroshima semiconductor corridors, where JIS K 1501 batch-traceability requirements have elevated supplier qualification costs beyond incumbent tolerance. Target pharmaceutical extraction volumes in Fukuoka through specialized chemical distributors with existing certification documentation, bypassing direct terminal competition. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale coastal terminal operators because METI port infrastructure mandates are consolidating bunkering service requirements around Nagoya and Yokohama, creating captive offtake visibility. Five-to-ten year viability hinges on methanol retaining transitional fuel status against direct hydrogen adoption. Watch METI's parallel ammonia power-generation investments as the critical signal for methanol's position in the national decarbonization hierarchy.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | Blue methanol certification arbitrages against JIS K 1501 purity standards at Chiba facilities. |
| Biomethanol Capacity Buildout | Forestry waste gasification in Hokkaido unifies circular economy mandates with chemical supply security. |
| Electronics-Grade Hydrotreating Investment | Additional sulfur removal capacity meets METI's 0.1 ppm specification for fuel cell vehicle hydrogen. |
| Long-Term Marine Bunkering Agreement | IMO carbon intensity compliance locks coastal shipping operators into methanol offtake at Nagoya. |
| Catalyst Supply Partnership | Domestic copper-zinc-alumina sourcing agreements reduce 18-month order backlogs disrupting turnarounds. |
Research Methodology
Multiple input streams — plant manager interviews at Kanto and Kansai syngas facilities, procurement lead discussions at downstream formaldehyde and acetic acid producers, distribution channel partner assessments, and technical R&D director consultations — were reconciled against customs and trade data, METI energy statistics, JIS standard documentation, and SEC filings from listed chemical companies. Bottom-up capacity and throughput estimates were triangulated against top-down consumption models derived from end-use industry production indices.
Historical methanol price series and import volume patterns were cross-referenced against panel input from industry stakeholders to establish baseline trajectory assumptions across the analysis window. Segmentation dimensions modeled include purity grade tier, end-use application, and regional production hub clustering. CAGRs were derived from slope fitting across reconciled demand projections and supply-side capacity announcements. Industry-specific forecast inputs incorporated METI hydrogen strategy revision timelines and IMO marine fuel regulation implementation schedules.
Inputs from METI statistical releases, JIS committee documentation, and customs trade records were available through the study window; gaps in real-time catalyst inventory data and confidential offtake contract terms introduce uncertainty bands around near-term price elasticity estimates. Forecasts reflect assumptions regarding currency stability and Chinese supply continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
RO Membrane Chemicals Market
Chemicals
Airbag Propellant Chemicals Market
Chemicals
Mercuric Chloride Market
Chemicals
Integrated Chemistry Systems Market
Chemicals
Potassium Iodide Market
Chemicals
Fatty Alcohol Market
Chemicals
Aluminum Ammonium Sulfate Market
Chemicals
6 Hexanediol Market
Chemicals
Potassium Hydrogen Fluoride Market
Chemicals
Scouring Agents Market
Chemicals
Natural Fatty Alcohols Market
Chemicals
Global Commodity Chemicals Market
Chemicals
Methoprene Market
Chemicals
Non PVC Plasticizers Market
Chemicals
Dimethyldichlorosilane Market
Chemicals
Iso Nonanol Market