
 Polyvinylpyrrolidone (PVP) Market | 2026-2036
Polyvinylpyrrolidone (PVP) Market Size, Share, and Industry Trends Forecast 2026-2036
Polyvinylpyrrolidone (PVP) Market Outlook
Pharmaceutical formulation demand is shifting toward advanced solubilization and controlled-release applications, pulling higher-grade PVP volumes. BASF SE leverages its Ludwigshafen manufacturing complex to sustain pharmaceutical-grade supply chains across Europe. Ashland Global Holdings Inc anchors North American demand through specialized film-forming polymer portfolios. Evonik Industries differentiates via R&D intensity in copovidone and custom molecular weight variants for oral dosage forms.
Polyvinylpyrrolidone is a synthetic water-soluble polymer formed by N-vinylpyrrolidone monomer polymerization, with molecular weights ranging from K15 to K90 grades denoting viscosity profiles in aqueous solution. It functions primarily as a binder, film former, solubilizer, and stabilizer across pharmaceutical tablets, topical formulations, and industrial adhesives. PVP K90 leads pharmaceutical-grade revenue pools due to its superior binding capacity in high-dose tablet matrices. Cosmetic-grade demand grows fastest among grade categories, driven by hair fixative and skincare film-former applications in premium personal care formulations. Food-grade PVP occupies a mature niche, concentrated in beverage clarification and packaging adhesives with stable but limited expansion.
EMA guidelines on excipient quality and USP-NF monograph compliance shape pharmaceutical-grade PVP market access and testing protocols. China's NMPA implements GB standards for food-contact polymers, while REACH registration requirements in Europe govern industrial-grade import volumes. FDA oversight of binder specifications in ANDA filings further constrains supplier qualification timelines. Stakeholders must monitor regulatory divergence between pharmacopeial standards as regional purity thresholds tighten and excipient master file documentation becomes a competitive gate.
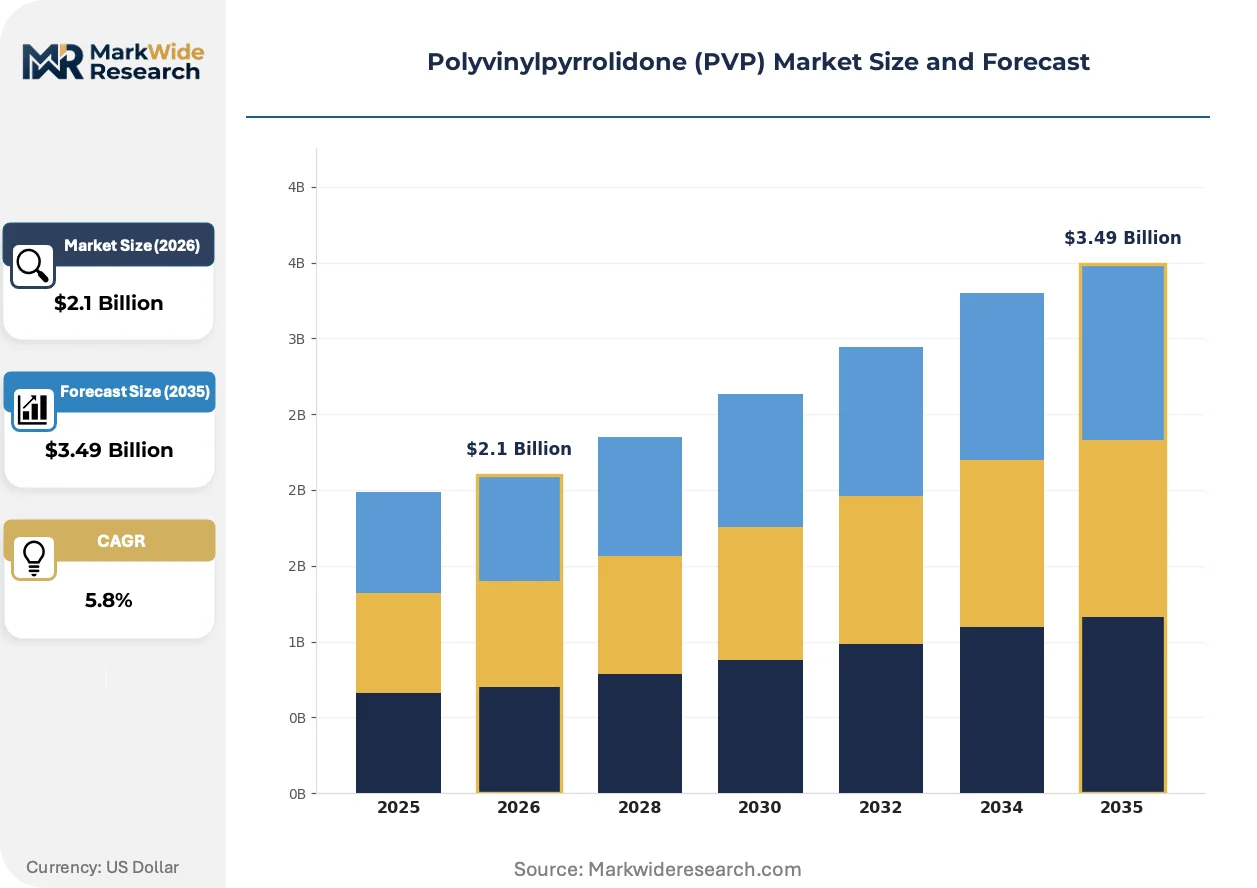
Market Dynamics
Pharmaceutical-grade PVP demand is concentrating around high-viscosity K90 variants as tablet formulations push toward higher active pharmaceutical ingredient loads per unit dose. This viscosity-grade compression is forcing capacity reallocation across polymerization trains and tightening qualification timelines for excipient suppliers.
Growth Catalysts
- Controlled-release matrix expansion:Oral solid dosage form manufacturers in Germany are scaling copovidone adoption for extended-release coatings, pulling specialized PVP grades into chronic therapeutic categories.
- REACH excipient purity mandates:ECHA registration requirements for polymer impurities are disqualifying lower-grade suppliers and consolidating pharmaceutical channel access for certified producers.
- Jiangsu chemical cluster scale:China's specialized polymer production corridors in Jiangsu province are achieving pharmaceutical-grade export volumes that reshape Asia-Pacific supply availability.
Market Restraints
- N-vinylpyrrolidone feedstock volatility:Acetylene-based monomer production faces energy cost pressure from natural gas pricing swings, compressing margin stability for non-integrated polymerizers.
- Ludwigshafen supply concentration:European pharmaceutical-grade volumes depend heavily on a single integrated chemical complex, creating geographic vulnerability to site-specific disruption.
- Carbomer substitution in topical gels:Carbopol polymers are displacing PVP in certain dermatological formulations where viscosity control and bioadhesion requirements overlap.
Strategic Opportunities
- Cosmetic film-former premiumization:Hair fixative and skincare brands in South Korea are specifying ultra-low residual monomer PVP grades, opening price-tier expansion above pharmaceutical standards.
- Biodegradable PVP analog R&D:Polymer chemistry convergence with enzymatic degradation pathways is enabling next-generation excipient positioning for sustainability-conscious formulators.
- Direct-to-formulator digital channels:Specialty chemical distributors are building e-procurement platforms that bypass traditional multilevel distribution for mid-volume pharmaceutical customers.
Industry Challenges
- Excipient master file documentation:FDA Type II DMF preparation requires 18-24 month timelines and specialized regulatory affairs capacity that smaller polymer producers struggle to staff.
- Polymerization train flexibility:Switching between K15 and K90 molecular weight grades demands reactor cleaning protocols that extend changeover downtime and compress asset utilization.
- Analytical method harmonization:Divergent USP-NF and Ph.Eur. monograph testing protocols force dual qualification investments for suppliers serving transatlantic pharmaceutical markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyvinylpyrrolidone (PVP) Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVP K30, PVP K60, PVP K90, PVP Iodine Grade: Pharmaceutical Grade, Cosmetic Grade, Food Grade, Industrial Grade Application: Pharmaceuticals, Cosmetics, Food and Beverages, Adhesives End User: Pharmaceutical Manufacturers, Cosmetic Companies, Food Processors, Chemical Firms |
| Companies Covered | Boai NKY Pharmaceuticals Ltd., Shanghai Yuking Water Soluble Material Tech Co., Ltd., BASF SE, JH Nanhang Life Sciences Co., Ltd., Hangzhou Motto Science & Technology Co., Ltd., Ashland Global Holdings Inc, Evonik Industries, Zhangzhou HuaFu Chemical Co. Ltd., NIPPON SHOKUBAI CO., LTD., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyvinylpyrrolidone (PVP) Market Strategic Shifts
Polyvinylpyrrolidone manufacturing is pivoting toward molecular weight precision and impurity control as pharmaceutical customers tighten specification windows. These technical advances are redrawing competitive boundaries between commodity polymerizers and specialized excipient houses.
Continuous polymerization reactor technology is rewriting process economics for pharmaceutical-grade PVP production. BASF SE and specialized European producers are retrofitting batch trains with continuous flow systems that tighten molecular weight distribution curves. This precision is compressing batch-to-batch variability penalties and enabling just-in-time excipient supply contracts with generic drug manufacturers.
EMA's updated excipient quality risk management guidelines are forcing polymer suppliers to expand impurity profiling beyond residual monomer to include peroxide and aldehyde specifications. The industrial consequence is capital deployment into advanced analytical infrastructure and quality control headcount. Oral dosage form producers in Italy and Spain are responding by consolidating supplier lists to those with documented EMA inspection histories.
Formulation scientists at generic pharmaceutical houses are shortening binder qualification cycles from 12 months to 90-day rapid-switch programs. This compression is displacing traditional excipient specification processes and rewarding PVP suppliers with pre-validated grade portfolios. The pattern is most visible in India's ANDA-focused contract development organizations, where speed-to-filing determines commercial success.
Polyvinylpyrrolidone (PVP) Market Segmentation
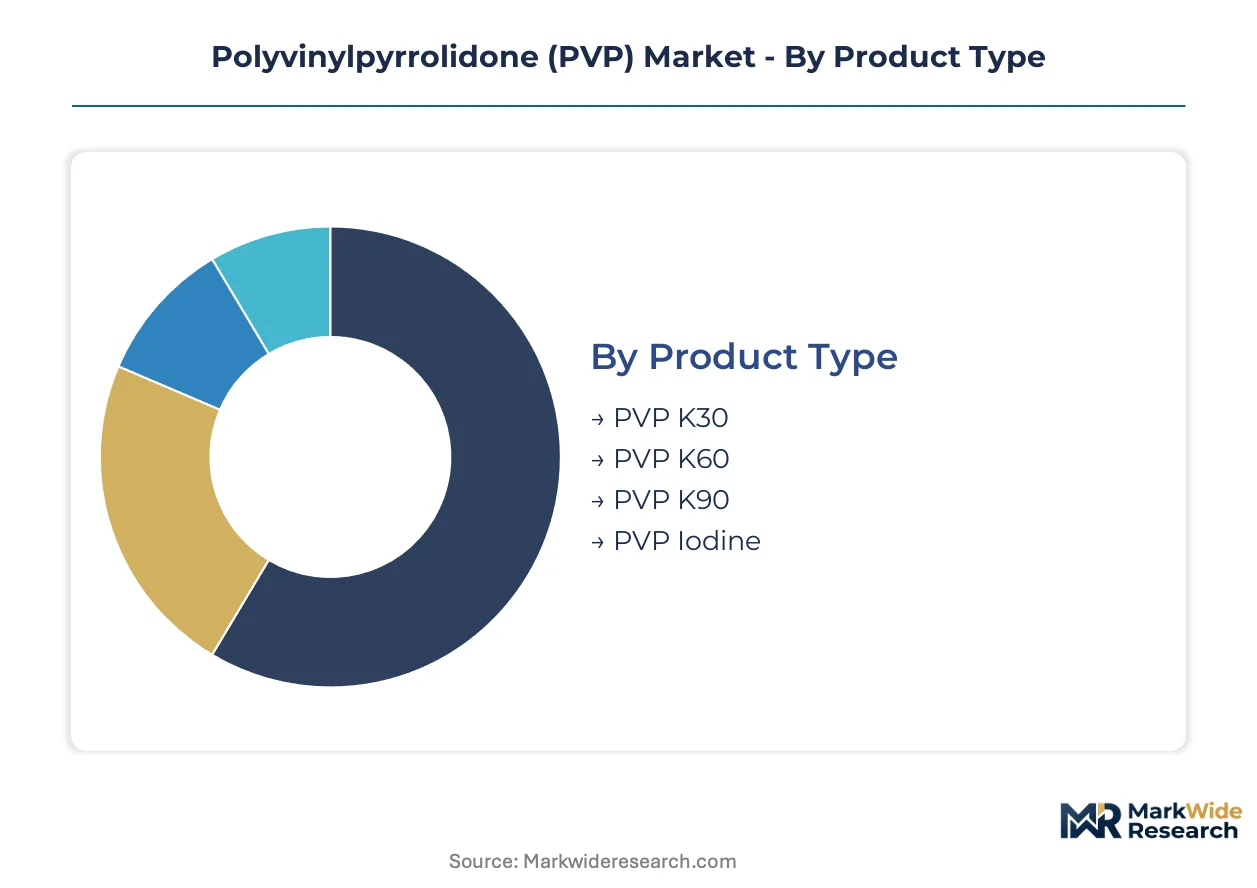
PVP segmentation reflects divergent purity standards and qualification barriers across end-use verticals. Pharmaceutical-grade specifications command premium positioning through FDA Type II DMF documentation and EMA inspection histories. Grade differentiation determines accessible customer pools and pricing power more than molecular weight alone.
Product Type:
Capital intensity escalates with molecular weight due to extended polymerization cycles and tighter process control requirements.
- PVP K30:Low-viscosity polymer (approximate molecular weight 40,000) serves as a solubilizer in parenteral solutions and topical sprays. Demand concentrates in India's ANDA-focused contract development organizations where rapid excipient qualification cycles favor established low-viscosity grades.
- PVP K90:High-viscosity grade (approximate molecular weight 1,000,000+) functions as the primary binder in high-dose tablet matrices. German pharmaceutical manufacturers in Ludwigshafen and Leverkusen are scaling K90 volumes for extended-release oral solid dosage forms requiring superior binding capacity.
- PVP K60:Mid-range viscosity polymer bridges solubilization and binding applications with moderate capital requirements.
- PVP Iodine:Antiseptic complex finds concentrated demand in surgical scrubs and wound care formulations with stable but mature expansion profiles.
PVP K90 absorbs the bulk of installed capacity; PVP Iodine is expanding most quickly in hospital antiseptic protocols.
Grade:
Margin structures stratify sharply across certification tiers, with pharmaceutical and cosmetic grades capturing value through impurity control investments.
- Pharmaceutical Grade:Residual monomer specifications below 10 ppm and peroxide/aldehyde profiling under EMA quality risk management guidelines. Jiangsu province chemical clusters are achieving export volumes that reshape Asia-Pacific supply availability for certified producers.
- Cosmetic Grade:Ultra-low residual monomer specifications are opening price-tier expansion above pharmaceutical standards in South Korean hair fixative and skincare film-former applications. Premium personal care brands are specifying grades with enhanced sensory profiles.
- Food Grade:GB standards compliance for food-contact polymers in China and FDA food additive regulations govern beverage clarification and packaging adhesive applications with stable but limited expansion trajectories.
- Industrial Grade:REACH registration requirements in Europe govern import volumes for adhesive and coating applications with lower purity thresholds and compressed margins.
Pharmaceutical Grade commands the dominant share of qualification-intensive capacity; Cosmetic Grade is climbing the fastest on premium personal care specification trends.
Application:
Customer concentration patterns determine contract structure, with pharmaceutical and adhesive applications favoring long-term supply agreements over spot procurement.
- Pharmaceuticals:Binder, film former, and solubilizer functions in tablets, capsules, and parenteral formulations. Controlled-release matrix expansion in Germany is pulling specialized copovidone and high-viscosity PVP grades into chronic therapeutic categories.
- Cosmetics:Hair fixative and skincare film-former applications in premium personal care formulations. South Korean beauty brands are driving fastest segment expansion through ultra-low residual monomer specifications.
- Food and Beverages:Beverage clarification and packaging adhesives with mature demand concentrated in China's domestic market and export processing zones.
- Adhesives:Industrial binding applications facing substitution pressure from alternative polymers in certain viscosity-control segments.
Pharmaceuticals lock in the majority of long-term supply contracts; Cosmetics is gaining share fastest on premiumization trends.
End User:
Procurement sophistication varies dramatically, with pharmaceutical manufacturers demanding full excipient master file documentation while chemical firms prioritize volume pricing.
- Pharmaceutical Manufacturers:Oral solid dosage form producers in Italy and Spain are consolidating supplier lists to those with documented EMA inspection histories. FDA ANDA filing requirements constrain supplier qualification timelines to 18-24 months for Type II DMF preparation.
- Cosmetic Companies:Premium hair fixative and skincare brands in South Korea are specifying grades above pharmaceutical purity standards, opening price-tier expansion opportunities.
- Food Processors:Beverage clarification and packaging adhesive users with stable demand patterns and lower documentation burdens.
- Chemical Firms:Industrial adhesive and coating formulators facing REACH registration compliance costs and feedstock volatility pressure.
Pharmaceutical Manufacturers anchor the highest-visibility supply relationships; Cosmetic Companies are expanding procurement most aggressively on premium grade specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu province's specialized chemical clusters function as a tax-incentive zone attracting pharmaceutical-grade polymer investment. China's coastal manufacturing corridors concentrate PVP capacity for export-oriented drug excipient supply chains.
China
Domestic pharmaceutical manufacturers in Jiangsu and Shandong provinces are scaling copovidone adoption for extended-release formulations. NMPA implements GB standards for food-contact polymers while tightening excipient quality documentation. The Yangtze River Delta chemical corridor achieves pharmaceutical-grade export volumes that reshape Asia-Pacific supply availability.
Germany
Oral solid dosage form producers in Ludwigshafen and Leverkusen are consolidating supplier lists to certified producers with EMA inspection histories. REACH registration requirements for polymer impurities are disqualifying lower-grade suppliers. The Ludwigshafen integrated chemical complex sustains pharmaceutical-grade supply chains across Europe despite geographic concentration risk.
United States
FDA Type II DMF preparation timelines constrain supplier qualification to 18-24 months for generic drug manufacturers. ANDA-focused contract development organizations in New Jersey and Massachusetts are shortening binder qualification cycles to 90-day rapid-switch programs. Ashland Global Holdings anchors North American demand through specialized film-forming polymer portfolios.
India
ANDA-focused contract development organizations in Hyderabad and Ahmedabad favor established low-viscosity PVP K30 grades for rapid excipient qualification. CDSCO alignment with USP-NF monograph compliance shapes market access protocols. Domestic pharmaceutical formulation demand pulls higher-grade PVP volumes into solubilization and controlled-release applications.
South Korea
Premium hair fixative and skincare brands in Seoul are specifying ultra-low residual monomer PVP grades above pharmaceutical purity standards. MFDS cosmetic safety regulations drive documentation requirements for film-former applications. The Seoul Capital Area concentration of beauty manufacturers opens price-tier expansion for certified excipient suppliers.
Polyvinylpyrrolidone (PVP) Market Competitive Environment
Top-tier vendors anchor pharmaceutical-grade supply chains, while mid-scale polymerizers compete on cosmetic and industrial grade flexibility. The vendor base stratifies between integrated chemical conglomerates with captive monomer supply and specialized excipient houses focused on DMF documentation. Two strategic archetypes dominate: backward-integrated producers controlling N-vinylpyrrolidone feedstock, and regulatory-specialist firms with pre-validated grade portfolios. Capacity expansion and portfolio diversification toward biodegradable analogs represent the dominant competitive moves.
Among German-based chemical conglomerates, BASF SE and Evonik Industries exemplify the integrated archetype with Ludwigshafen manufacturing infrastructure. Shanghai Yuking Water Soluble Material Tech Co., Ltd. represents the Chinese specialist tier achieving pharmaceutical-grade export certification. Boai NKY Pharmaceuticals Ltd. occupies a position bridging domestic supply and international qualification standards.
| Leading Market Players |
|---|
| Boai NKY Pharmaceuticals Ltd. |
| Shanghai Yuking Water Soluble Material Tech Co., Ltd. |
| BASF SE |
| JH Nanhang Life Sciences Co., Ltd. |
| Hangzhou Motto Science & Technology Co., Ltd. |
| Ashland Global Holdings Inc |
| Evonik Industries |
| Zhangzhou HuaFu Chemical Co. Ltd. |
| NIPPON SHOKUBAI CO., LTD. |
| Others |
Value Chain & Pricing Dynamics
N-vinylpyrrolidone monomer costs cascade through pharmaceutical-grade PVP tiers, with acetylene-based feedstock volatility compressing margins for non-integrated polymerizers while backward-integrated producers at Ludwigshafen and Jiangsu maintain pricing power through captive supply.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to excipient orders requiring sub-30-day fulfillment, while spot inventory of industrial-grade material trades at discounts to contract benchmarks. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial certification levels separates DMF-documented grades from cosmetic ultra-low monomer variants and REACH-registered industrial volumes. Cost compression in industrial-grade segments is intensifying because carbomer substitution in topical gels erodes volume commitments. Generic drug manufacturers in India exhibit highest price sensitivity due to ANDA filing cost pressures, while South Korean cosmetic houses show lowest sensitivity for sensory-optimized film-former grades.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Shanghai, and Mumbai orchestrate hub-and-spoke patterns for pharmaceutical-grade material, with secondary nodes in São Paulo and Singapore serving Latin American and Southeast Asian formulation houses. Manufacturing concentrates in Germany, China, and the United States, with Jiangsu province chemical clusters achieving export certification volumes that reshape Asia-Pacific availability. Feedstock draws from acetylene producers in Sichuan and natural gas crackers in the North Sea, with peroxide initiators sourced from Belgian and Japanese specialty chemical houses. Single-source vulnerability concentrates at the Ludwigshafen integrated complex, where site-specific disruption would cascade through European pharmaceutical supply chains. Distribution runs through excipient master file holders with pre-validated grade portfolios, bypassing traditional multilevel channels for mid-volume pharmaceutical customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyvinylpyrrolidone supply chains are consolidating around REACH-registered producers with EMA inspection histories, as regulatory compliance timelines disqualify smaller polymerizers lacking dedicated regulatory affairs capacity.
For Market Incumbents: Acquire continuous polymerization reactor assets to tighten molecular weight distribution curves and compress batch-to-batch variability penalties. BASF SE and Evonik Industries should expand copovidone capacity in Ludwigshafen to capture controlled-release matrix demand from German oral solid dosage form producers. Defensive positioning requires locking 36-month supply agreements with ANDA-focused contract development organizations before rapid-switch qualification programs displace traditional specification processes. For New Entrants and Emerging Players: Begin with cosmetic-grade film-former supply to South Korean beauty manufacturers, where ultra-low residual monomer specifications command price tiers above pharmaceutical standards. White-space exists in biodegradable PVP analog R&D for sustainability-conscious formulators in Western Europe. Direct-to-formulator digital procurement platforms offer a channel bypass opportunity for mid-volume pharmaceutical customers currently served through multilevel distribution. For Investors and Strategic Acquirers: FDA Type II DMF approval for a new Jiangsu province producer is the leading indicator that Asia-Pacific supply availability is structurally expanding beyond incumbent control. Long-term viability favors vertically integrated producers with captive N-vinylpyrrolidone supply and documented EMA inspection histories. Acquisition targets should display pre-validated grade portfolios enabling 90-day rapid-switch qualification cycles. Monitor CDSCO alignment with USP-NF monograph compliance as the signal for Indian market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Polymerization Retrofit | BASF SE tightens molecular weight precision to enable just-in-time excipient contracts with generic manufacturers. |
| Copovidone Capacity Expansion | German producers capture extended-release coating demand from chronic therapeutic oral solid dosage form manufacturers. |
| Biodegradable PVP Analog R&D | Polymer chemistry convergence with enzymatic degradation pathways opens sustainability positioning for European formulators. |
| Direct-to-Formulator Digital Channel | Specialty chemical distributors bypass multilevel distribution for mid-volume pharmaceutical customers in India and the United States. |
| Excipient Master File Documentation Investment | Producers with FDA Type II DMF and EMA inspection histories consolidate supplier lists from Italian and Spanish pharmaceutical manufacturers. |
Study Parameters
Multi-period observation of N-vinylpyrrolidone feedstock pricing, polymerization train utilization rates, and excipient master file submission timelines anchored the trend analysis, supplemented by interviews with plant managers at integrated chemical complexes, procurement leads at generic drug manufacturers, regulatory affairs directors at excipient houses, and distribution channel partners in Rotterdam and Shanghai. Secondary validation drew from ECHA REACH registration databases, USP-NF monograph revision notices, FDA Type II DMF submission logs, and customs trade data for pharmaceutical-grade polymer imports. Bottom-up volume estimates from individual polymerization facilities triangulated against top-down demand projections from oral solid dosage form production statistics.
Input-output matrices modeled capacity-expansion decisions against qualification timeline constraints across the projection horizon. Segmentation dimensions included molecular weight grade tier, end-use industry vertical, certification level, and regional production hub cluster. CAGRs derived from slope analysis of historical volume trajectories adjusted for polymerization train commissioning schedules and regulatory approval pathway delays. Forecast inputs incorporated acetylene feedstock cost curves and EMA excipient quality risk management guideline revision schedules.
Underlying measurement precision varies by segment; pharmaceutical-grade volumes with DMF documentation carry tighter precision than industrial-grade spot market estimates. Forecasts reflect documented assumptions regarding polymerization yield rates and qualification timeline compression. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
EVA Copolymer Market
Polymers & Resins
Polyisobutene Market
Polymers & Resins
Global Hydroxypropyl Cellulose Market
Polymers & Resins
Global Polyethylene Market
Polymers & Resins
Polyimide Resin Market
Polymers & Resins
Polymeric Sand Market
Polymers & Resins
Global Polyalkylene Glycol (PAG) and Esters Market
Polymers & Resins
Ionomer Resins Market
Polymers & Resins
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market
Polymers & Resins
Optically Clear Resin Market
Polymers & Resins
Epoxy Resin Market
Polymers & Resins
Polyalkylene Glycols (Pags) Market
Polymers & Resins
Solid State Resins Market
Polymers & Resins
North America Engineering Plastics Market
Polymers & Resins
HDPE Large Blow Molded Products Market
Polymers & Resins
Global Emulsion Polymer Market