
 Biobased Thermosetting Polymers Market | 2026-2036
Biobased Thermosetting Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Biobased Thermosetting Polymers Market Outlook
Petrochemical feedstock dependency is narrowing as epoxidized vegetable oil platforms achieve parity on cure kinetics and glass transition temperature. BASF leverages its Ludwigshafen integrated site to secure lysine-derived diamine precursors for bio-epoxy hardeners. Corbion anchors global supply of biobased building blocks through its Thailand fermentation complex. Evonik competes on specialty amine curing agents that tolerate higher bio-content ratios without sacrificing pot life.
Biobased thermosetting polymers are crosslinked macromolecular networks synthesized from renewable monomers such as epoxidized linseed oil, succinic acid derivatives, or lignin-replacement phenolics, cured via thermal or catalytic mechanisms to yield irreversible three-dimensional structures with defined Tg and modulus values. Epoxy resins lead product type volume due to established aerospace and wind blade qualification protocols, while polyurethane captures the fastest application growth in automotive seating foam where OEMs mandate recycled and renewable content thresholds. High performance grade formulations command concentrated margin pools because electronics and medical device manufacturers require sub-50 ppm ionic purity and halogen-free flame retardancy.
The EU Green Deal and REACH authorization lists restrict bisphenol-A and isocyanate monomer usage, redirecting formulation R&D toward bio-epoxy and non-isocyanate polyurethane platforms. FDA food-contact notification requirements and EPA TSCA Section 5 premanufacture reviews govern US market entry for novel biobased crosslinkers, creating compliance bottlenecks that favor incumbents with established regulatory dossiers. Stakeholders must monitor feedstock competition from renewable diesel and SAF offtake agreements that could tighten epoxidized oil availability before biorefinery capacity scales.
Market Dynamics
REACH authorization timelines and EU Green Deal carbon-border adjustments are compressing formulation windows for petrochemical thermosets, forcing compounders to validate bio-epoxy drop-in replacements before 2030 compliance deadlines lock in.
Growth Catalysts
- EU Green Deal carbon pricing:Industrial emitters face escalating costs for fossil-derived feedstocks, redirecting capital toward epoxidized vegetable oil platforms with verified lifecycle carbon reductions.
- Wind blade manufacturers:OEM qualification protocols for bio-epoxy composites in 80-meter-plus rotor blades are accelerating, with laminate testing data now accepted by major certification bodies.
- Thailand fermentation clusters:Dedicated biorefinery capacity for succinic acid and C5/C6 sugar streams is securing feedstock supply for diamine and anhydride hardener production at scale.
Market Restraints
- Epoxidized oil input volatility:Competing offtake from renewable diesel and sustainable aviation fuel producers is tightening vegetable oil availability before dedicated biopolymer feedstock plantations mature.
- Glass transition temperature gaps:Bio-based epoxy formulations still trail petrochemical benchmarks by 15-20°C in high-Tg applications, limiting adoption in under-the-hood automotive and electronics molding.
- FDA food-contact notification timelines:Novel biobased crosslinkers face 18-24 month premarket review cycles that favor incumbents with established regulatory dossiers and delay challenger market entry.
Strategic Opportunities
- Non-isocyanate polyurethane platforms:Cyclic carbonate-amine chemistry eliminates isocyanate handling hazards while meeting automotive seating foam mandates for renewable content thresholds.
- India PLI scheme for advanced materials:Domestic production-linked incentives are attracting fermentation-derived building block investments to serve Asian coating and adhesive formulators.
- Digital twin formulation:Computational curing kinetics modeling is compressing R&D cycles for custom bio-thermoset blends, enabling rapid customer-specific qualification.
Industry Challenges
- Specialized polymer chemist scarcity:Formulation expertise spanning both renewable feedstock characterization and thermoset network design concentrates at a handful of academic-industry partnership programs.
- Multi-standard certification stacking:Simultaneous aerospace NADCAP, automotive IATF, and electronics IPC qualification requirements demand redundant testing budgets that strain mid-scale compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biobased Thermosetting Polymers Market |
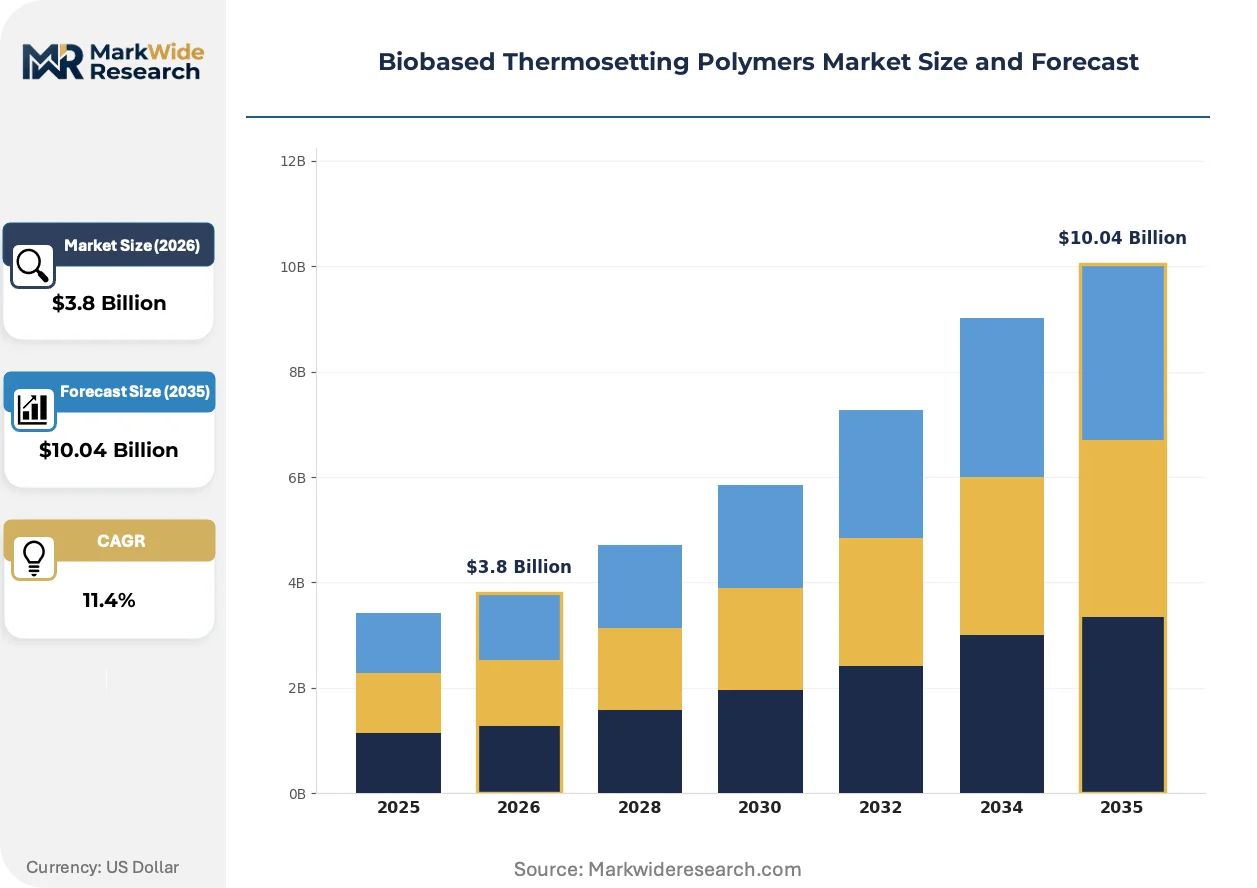
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy Resins, Polyurethane, Melamine, Urea Formaldehyde Application: Construction, Automotive, Electronics, Coatings End User: Manufacturers, OEMs, Contractors, CPG Companies Grade: Standard Grade, High Performance, Specialty Grade, Industrial Grade |
| Companies Covered | BASF, Corbion, NatureWorks, Mitsubishi Chemical Corporation, Evonik Industries, DuPont, Novamont, Braskem, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biobased Thermosetting Polymers Market Strategic Shifts
Computational materials science and automated high-throughput screening are collapsing the traditional empirical development cycle for bio-thermoset formulations, compressing time-to-qualification from years to months.
Machine learning-guided molecular design is digitizing the prediction of cure kinetics and mechanical property outcomes for novel epoxidized oil structures. Formulators at specialty chemical houses now screen thousands of virtual monomer combinations before bench synthesis. This capability is compressing the competitive moat of incumbents with decades of empirical databases.
REACH authorization list expansions for bisphenol-A and aromatic amine hardeners are mandating systematic substitution programs across European coating and composite manufacturers. Downstream formulators face reformulation deadlines that invalidate existing product certifications. Electronics and medical device segments are responding fastest, where halogen-free and sub-50 ppm ionic purity specifications already favor bio-derived alternatives.
Automotive OEMs now mandate recycled and renewable content thresholds in supplier contracts rather than requesting voluntary sustainability disclosures. Tier-1 seating and interior component manufacturers must document mass-balance certificates through blockchain-tracked supply chains. Germany and France lead enforcement, with compliance data submitted directly to ECHA SCIP database requirements.
Biobased Thermosetting Polymers Market Segmentation
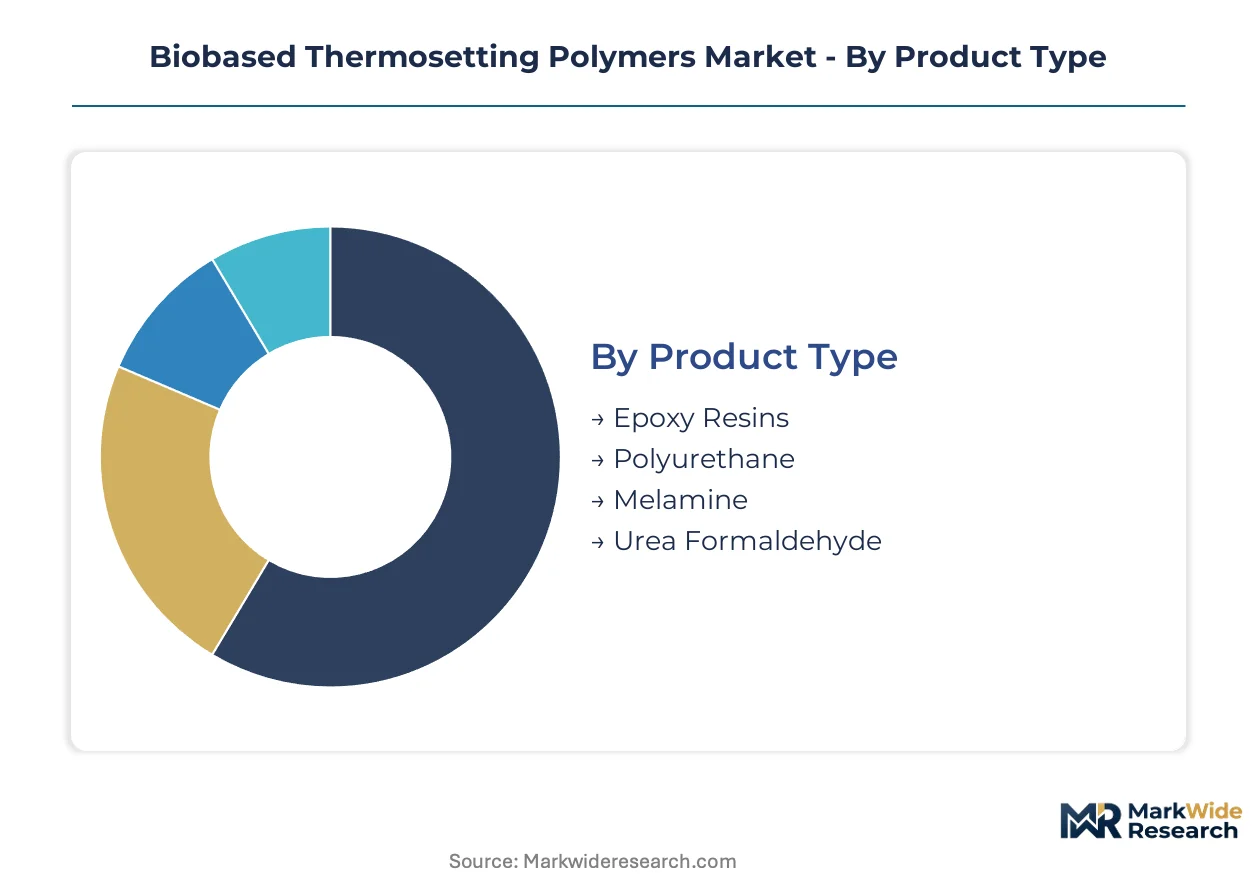
Segmentation reveals how biobased thermosetting polymers serve divergent technical and commercial requirements across epoxy platforms, polyurethane foams, and formaldehyde-based systems. Each product type demands distinct formulation expertise, curing infrastructure, and regulatory dossiers that reshape competitive positioning.
Product Type:
After-sales technical service intensity varies sharply across these chemistries, with epoxy and polyurethane requiring dedicated field support for cure validation while melamine and urea formaldehyde run on specification-driven procurement.
- Epoxy Resins:Crosslinked networks from epoxidized vegetable oils and bio-derived diamine hardeners deliver glass transition temperatures approaching petrochemical benchmarks. Demand concentrates in Germany and the Netherlands where wind blade manufacturers qualify 80-meter-plus rotor laminates under DNV certification protocols. REACH authorization deadlines for bisphenol-A accelerate substitution timelines.
- Polyurethane:Non-isocyanate platforms using cyclic carbonate-amine chemistry eliminate hazardous handling while meeting automotive seating foam mandates for renewable content. BMW and Mercedes-Benz procurement contracts now require mass-balance documentation through blockchain-tracked supply chains. Thailand fermentation clusters secure succinic acid feedstock for scaled production.
- Melamine:Bio-derivatized triazine platforms serve decorative laminates and flame-retardant applications with lower formulation service overhead.
- Urea Formaldehyde:Lignin-replacement phenolic variants address particleboard and plywood adhesives with cost-sensitive specification selling.
Epoxy resins hold the largest share; momentum sits with polyurethane as automotive OEMs harden renewable content mandates.
Application:
Application segmentation tracks how regulatory pressure and performance thresholds redistribute volume across construction, mobility, electronics, and protective coatings.
- Construction:Structural adhesives and composite reinforcements for mass timber and prefabricated modules require EPD-verified carbon reductions. German and Austrian building codes now specify biobased content thresholds for public procurement.
- Automotive:Lightweighting programs deploy bio-epoxy composites for body-in-white panels and interior structural components. EU Green Deal carbon-border adjustments tighten cost competitiveness against petrochemical baselines.
- Electronics:High-purity grades with sub-50 ppm ionic contamination serve semiconductor encapsulation and printed circuit board laminates.
- Coatings:Protective and decorative formulations face REACH authorization restrictions on aromatic amine hardeners.
Construction absorbs the greatest volume; automotive applications are climbing the fastest as OEM qualification protocols mature.
End User:
End user categories reflect divergent procurement sophistication, from specification-driven manufacturers to compliance-heavy CPG brands.
- Manufacturers:Tier-1 and Tier-2 component producers integrate bio-thermosets into existing cure ovens and compression molding lines.
- OEMs:Volkswagen, Stellantis, and Siemens direct supplier qualification programs mandate third-party sustainability certification.
- Contractors:Construction applicators require field-level technical support for ambient-cure bio-epoxy flooring and adhesive systems.
- CPG Companies:Nestlé and Unilever packaging divisions specify food-contact-compliant biobased coatings for metal can linings.
Manufacturers dominate current offtake; CPG companies are gaining share fastest as food-contact notification pathways clear.
Grade:
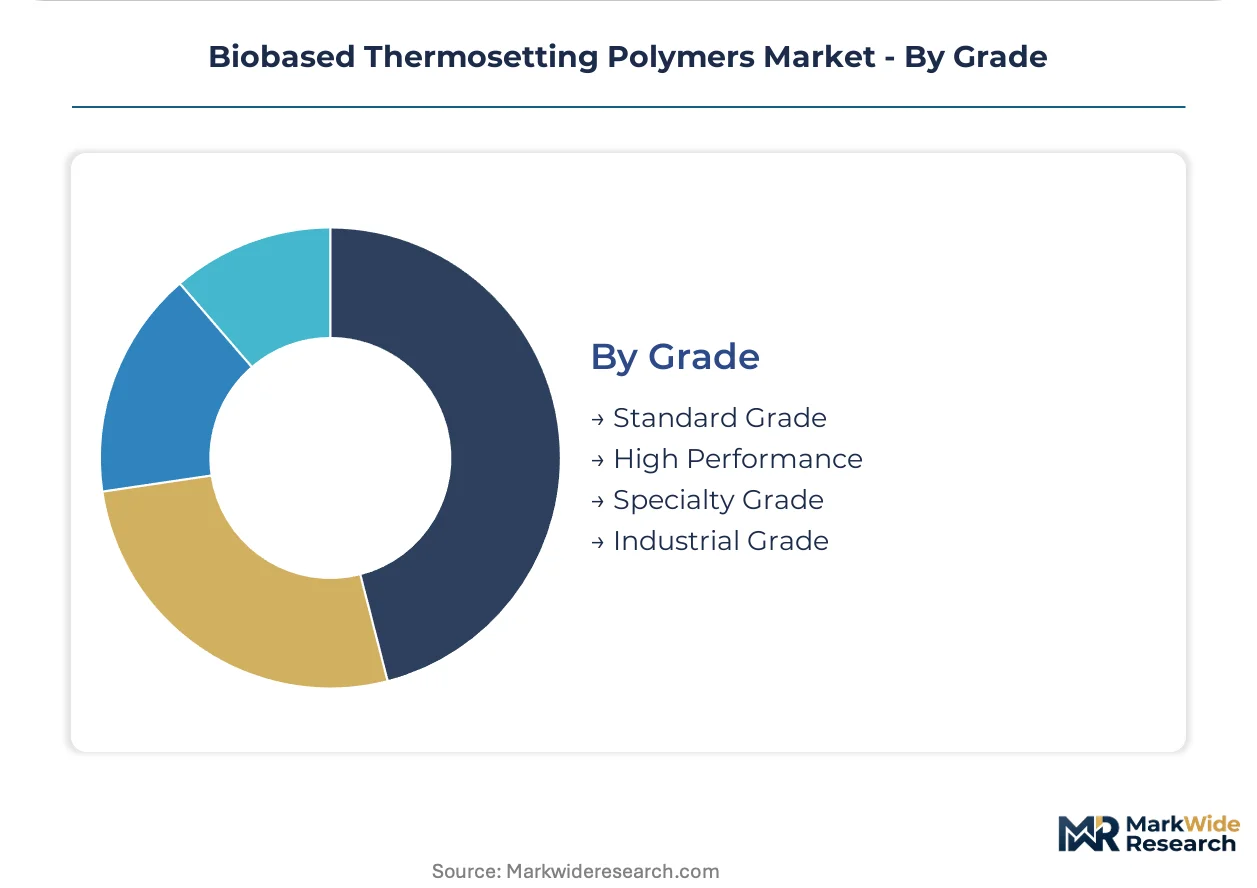
Grade stratification mirrors margin architecture, with high-performance and specialty grades commanding qualification-intensive selling while standard and industrial grades compete on feedstock cost.
- Standard Grade:General-purpose formulations for construction adhesives and non-structural composites with established supply chains.
- High Performance:Electronics and medical device segments require halogen-free flame retardancy and ionic purity below 50 ppm.
- Specialty Grade:Custom cure kinetics for aerospace NADCAP and automotive IATF qualification programs.
- Industrial Grade:Volume applications in particleboard resins and foundry binders with minimal technical service overhead.
Standard grade leads by volume; specialty grade shows the steepest expansion trajectory as multi-standard certification requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports bio-epoxy formulations to French and Dutch wind blade manufacturers while Thailand ships fermentation-derived succinic acid to hardener producers across Asia-Pacific. This trade-flow pattern concentrates supply-side investment in Ludwigshafen and Bangkok while demand clusters around Rotterdam and Shanghai.
Germany
Automotive OEMs in Stuttgart and Munich mandate bio-epoxy composites for lightweighting programs in body-in-white panels. REACH authorization deadlines for bisphenol-A accelerate substitution timelines across coating formulators. BASF anchors pilot production at its Ludwigshafen integrated site, securing lysine-derived diamine precursors for regional hardener supply.
United States
Electronics manufacturers in Silicon Valley and Research Triangle Park demand sub-50 ppm ionic purity grades for semiconductor encapsulation. EPA TSCA Section 5 premanufacture reviews create compliance bottlenecks that favor incumbents with established regulatory dossiers. Texas Gulf Coast petrochemical corridors are retrofitting fermentation capacity to serve biobased anhydride production.
Thailand
Automotive seating foam producers for Japanese transplant OEMs require mass-balance certificates through blockchain-tracked supply chains. The country's Board of Investment incentives attract fermentation-derived building block investments. Corbion anchors global supply of biobased building blocks through its Rayong fermentation complex, serving diamine and anhydride hardener production.
China
Wind turbine OEMs in Jiangsu and Guangdong provinces qualify 80-meter-plus rotor laminates under domestic certification protocols. MIIT dual carbon goals redirect state-owned chemical conglomerates toward epoxidized vegetable oil platforms. Yangtze River Delta chemical parks are expanding dedicated biorefinery capacity for C5/C6 sugar stream processing.
Netherlands
Coating formulators in Rotterdam and Eindhoven face EU Green Deal carbon-border adjustments on fossil-derived feedstock imports. ECHA SCIP database requirements enforce mass-balance documentation across supplier tiers. DSM-Firmenich's Geleen operations exemplify specialty amine curing agent production that tolerates higher bio-content ratios.
Biobased Thermosetting Polymers Market Competitive Environment
Channel-controlling players compete with product-specialist players for formulation partnerships with tier-1 automotive and electronics manufacturers. The vendor base concentrates around integrated chemical conglomerates with captive fermentation capacity and specialty houses with regulatory dossier depth. Three archetypes dominate: feedstock-integrated multinationals, specialty amine hardener specialists, and regional fermentation-based compounders. M&A activity targets fermentation asset acquisition, while strategic partnerships secure offtake agreements for epoxidized oil supply.
Among feedstock-integrated multinationals, BASF and Evonik Industries occupy positions that exemplify divergent strategic approaches to bio-epoxy hardener supply. BASF represents the vertically integrated archetype through its Ludwigshafen site control over lysine-derived diamine precursors. Evonik sits within the specialty chemicals tier, anchoring competitive positioning on curing agent formulations that maintain pot life at elevated bio-content ratios. Corbion, as a Thailand-based fermentation pure-play, exemplifies the regional supply security model that global formulators increasingly depend upon for succinic acid and C5/C6 sugar stream access.
| Leading Market Players |
|---|
| BASF |
| Corbion |
| NatureWorks |
| Mitsubishi Chemical Corporation |
| Evonik Industries |
| DuPont |
| Novamont |
| Braskem |
| Arkema |
| Others |
Value Chain & Pricing Dynamics
Thailand's fermentation cluster concentration for succinic acid and C5/C6 sugar streams concentrates upstream margin capture with Corbion's Rayong complex, while downstream formulation value pools fragment across German hardener specialists and Chinese wind blade compounders competing on mass-balance certification premiums.
Pricing Analysis
First-generation bio-epoxy formulations trade at 15-25% premiums to petrochemical baselines, while next-generation non-isocyanate polyurethane platforms command wider spreads reflecting elimination of isocyanate handling infrastructure. Pricing stratifies across specialty, high-performance, and industrial tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in standard-grade construction adhesives is intensifying as Chinese epoxidized vegetable oil capacity scales. Tier-1 automotive seating foam manufacturers exhibit lowest price sensitivity due to renewable content mandate compliance requirements.
Supply Chain Analysis
Extended payment terms from German automotive OEMs now stretch to 90-120 days, forcing hardener producers to utilize supply-chain finance facilities anchored in Rotterdam commodity trading houses. Feedstock supply concentrates in Thailand, Germany, and China, with epoxidized linseed oil, lysine-derived diamines, and fermentation-derived succinic acid as critical inputs. Single-source vulnerability around vegetable oil offtake competition from renewable diesel producers poses structural risk. Distribution runs through regional compounding hubs that blend base resins with customer-specific cure packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise spanning renewable feedstock characterization and thermoset network design concentrates at fewer than twelve academic-industry partnership programs globally, creating persistent capability scarcity that reshapes competitive entry economics.
For Market Incumbents: Pre-empt substitution threats from non-isocyanate polyurethane platforms by accelerating cyclic carbonate-amine chemistry R&D partnerships with Thai fermentation houses. Defend margin position through backward integration into epoxidized vegetable oil supply via long-term offtake agreements with dedicated biopolymer feedstock plantations before renewable diesel competition tightens availability. For New Entrants and Emerging Players: India's underpenetrated coating and adhesive formulator base offers white-space expansion under PLI scheme incentives for fermentation-derived building block production. Target construction adhesive specifications in German and Austrian public procurement where biobased content thresholds now mandate compliance. Pursue digital twin formulation partnerships to compress customer-specific qualification cycles without legacy empirical database dependencies. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty amine hardener producers holding established REACH regulatory dossiers. Five-to-ten year viability hinges on feedstock supply security rather than formulation differentiation alone. Monitor ECHA SCIP database submission volumes as inflection indicator for mass-balance certification adoption velocity across European supplier tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Secures epoxidized vegetable oil availability before renewable diesel competition tightens input markets. |
| Non-Isocyanate Polyurethane Platform Development | Eliminates isocyanate handling hazards while meeting BMW and Mercedes-Benz renewable content mandates. |
| Digital Twin Formulation Capability | Compresses R&D cycles for custom bio-thermoset blends through computational curing kinetics modeling. |
| REACH Regulatory Dossier Investment | Creates compliance moats against challenger entry given 18-24 month FDA food-contact notification timelines. |
| Blockchain-Tracked Mass-Balance Certification | Enables Tier-1 supplier qualification under automotive OEM procurement contract requirements. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with plant managers at German and Thai fermentation facilities, technical R&D directors at specialty chemical houses, procurement leads at automotive Tier-1 seating suppliers, and wind blade laminate qualification engineers; and secondary validation through customs and trade flow data, ECHA SCIP database filings, SEC 10-K chemical segment disclosures, and ACC/Cefic bioplastics production statistics. Bottom-up capacity and offtake estimates triangulated against top-down market sizing from feedstock availability models.
Forecast inputs considered grade tier stratification across standard, high-performance, specialty, and industrial classifications; end-use industry segmentation spanning construction, automotive, electronics, and coatings; and regional production hub clustering around Ludwigshafen, Rayong, and Yangtze River Delta chemical parks. CAGRs derived from elasticity-adjusted adoption curves reflecting REACH authorization deadline impacts and automotive OEM mandate enforcement trajectories. Feedstock competition from renewable diesel and sustainable aviation fuel offtake agreements served as key demand-side constraint variables.
Practitioners should monitor ECHA authorization list expansions, EU carbon-border adjustment implementation pace, and biorefinery capacity commissioning schedules for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Amorphous Polyolefin Market
Polymers & Resins
Aromatic Ketone Polymer Market
Polymers & Resins
Global Polyphthalamide Market
Polymers & Resins
India Epoxy Resins Market
Polymers & Resins
Polyimide Resin Market
Polymers & Resins
Polymer Foam Market
Polymers & Resins
Polyglycerol Polyricinoleate Market
Polymers & Resins
Scleroglucan Market
Polymers & Resins
Poly(P-Phenylene Ether) (PPE) Market
Polymers & Resins
Resorcinol Formaldehyde Resin Market
Polymers & Resins
Thermoplastic Polyamide Elastomer (TPE) Market
Polymers & Resins
Plastic Compounding Market
Polymers & Resins
Chelating Resins Market
Polymers & Resins
Global Solid Masterbatches Market
Polymers & Resins
UV Stabilized Thermoplastic Elastomer for Automotive Market
Polymers & Resins
Middle-East and Africa Epoxy Resins Market