
 Weighing Agents Market | 2026-2036
Weighing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Weighing Agents Market Analytics
Maintenance contracts and fluid-recycling services are repositioning how weighing agents generate recurring revenue for suppliers. Schlumberger leverages its integrated drilling-services platform to bundle chemical supply with real-time density management. Elkem ASA anchors its position through specialized micronization capabilities that meet API barite specifications. Newpark Resources competes by controlling regional blending facilities near active shale basins.
Weighing agents are high-density mineral additives formulated to precise specific-gravity targets, typically between 4.1 and 4.3 for barite grades, that control hydrostatic pressure in drilling fluids and modify density in coatings and polymer compounds. Baryte dominates drilling fluid applications due to its cost-performance ratio at extreme downhole pressures, while calcium carbonate serves lower-density well-completion tasks where acid solubility matters. Powder-form weighing agents command the largest volume share across oilfield and industrial applications, though liquid suspensions are gaining share in automated mud-mixing systems.
API specification standards, EPA discharge regulations for offshore drilling fluids, and REACH registration requirements for mineral imports collectively constrain product formulations and supplier qualification timelines. The EPA's effluent limitations for synthetic-based drilling muds directly influence barite purity thresholds and treatment additive selection. Stakeholders must monitor evolving critical-mineral designations and regional sourcing mandates that could redirect supply chain priorities without warning.
Market Dynamics
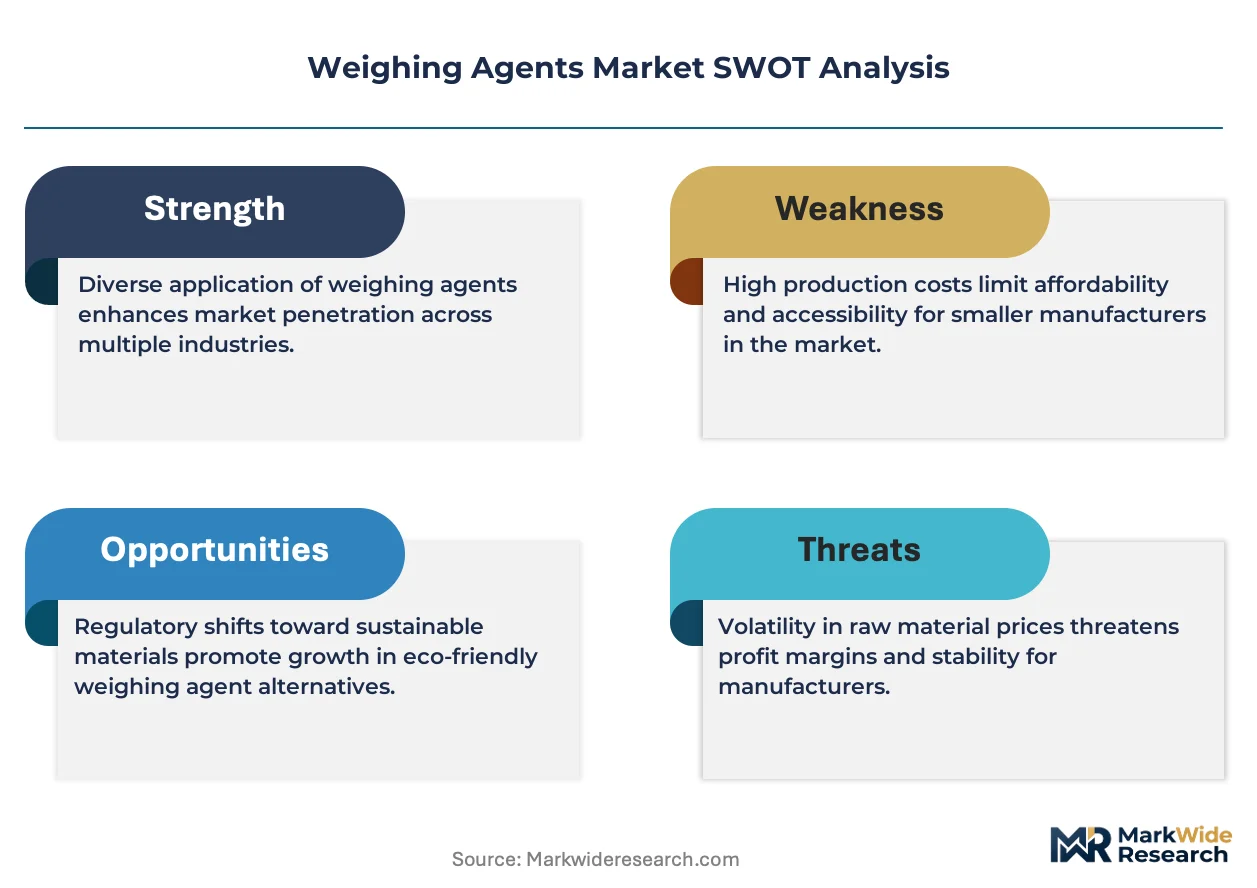
REACH compliance deadlines and API specification tightening are compressing supplier qualification timelines while simultaneously concentrating procurement among micronization-capable processors. This regulatory squeeze favors integrated service providers over commodity traders.
Growth Catalysts
- Permian Basin drilling intensity:Texas operators are expanding lateral lengths beyond 15,000 feet, requiring higher barite loading per wellbore and sustaining density-management service contracts.
- EPA effluent limitation guidelines:Offshore discharge rules for synthetic-based muds are mandating cleaner barite grades, creating specification premiums for low-mercury, low-cadmium ore sources.
- Micronization automation:Precision grinding technology is enabling API-grade particle-size distribution at throughput rates that manual classification cannot match.
Market Restraints
- Chinese barite export licensing:Concentration of 4.2+ specific-gravity ore in Guizhou and Hunan provinces creates supply vulnerability when export quotas tighten without warning.
- Calcium carbonate substitution:Acid-soluble weighting agents are displacing barite in well-completion fluids where formation damage tolerance outweighs density requirements.
- REACH registration costs:ECHA substance dossier preparation for mineral imports exceeds EUR 100,000 per variant, excluding smaller traders from European supply chains.
Strategic Opportunities
- Argentina Vaca Muerta development:Neuquén Basin operators are importing U.S. blending expertise, creating first-mover advantage for suppliers establishing regional micronization capacity.
- Coatings density modification:Automotive underbody sealant formulations are adopting high-loading mineral dispersions to replace metal flake, opening industrial volume outside oilfield cyclicality.
- EU Critical Raw Materials Act:Barite's designation under the CRM list is accelerating strategic stockpiling mandates and domestic processing incentives across member states.
Industry Challenges
- API RP 13K certification backlog:Third-party testing laboratory capacity constraints are extending qualification timelines for new ore sources beyond operator drilling schedules.
- Fluid-recycling integration:Closed-loop mud systems require weighing agent recovery and reprocessing infrastructure that most regional blenders lack, forcing capital deployment or partnership dependency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weighing Agents Market |
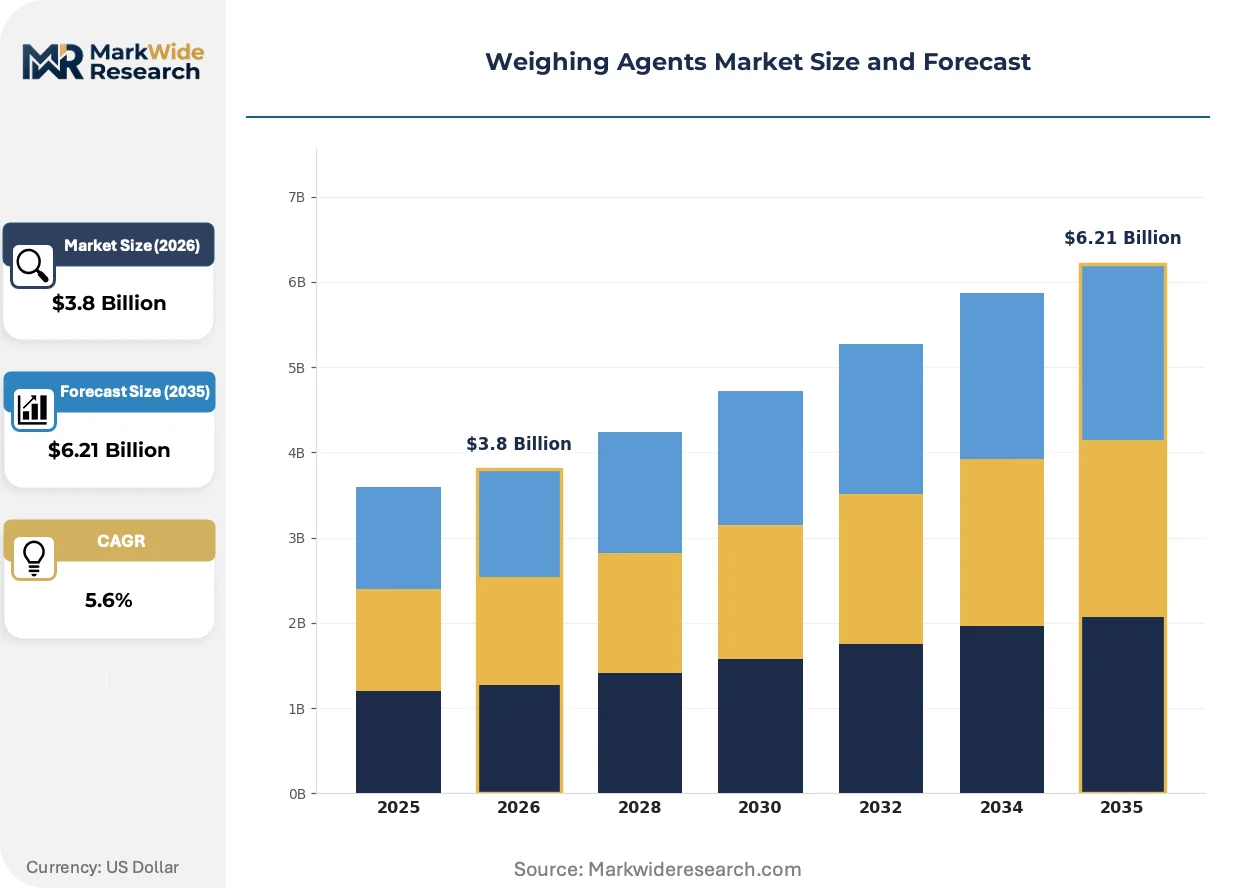
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Carbonate, Baryte, Talc, Clay Application: Drilling Fluids, Paints, Plastics, Ceramics End User: Oil & Gas, Construction, Pharmaceutical, Food Processing Form: Granular, Powder, Liquid, Paste |
| Companies Covered | Schlumberger, Baroid Industrial Drilling Products, Elkem ASA, Global Drilling Fluids and Chemicals, BHGE, Carmeuse, Imdex, Newpark Resources, United Mud-Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weighing Agents Market Evolving Landscape
Automation in mud-mixing systems is compressing the viable particle-size distribution for weighing agents while simultaneously elevating liquid suspension formats over traditional powder handling.
Automated density control systems are expanding into offshore drilling platforms where real-time hydrostatic pressure management reduces non-productive time. Gulf of Mexico operators are retrofitting legacy rigs with continuous-mix skids that demand pre-dispersed barite slurries rather than bulk powder. This format shift is expanding into land-based operations as Permian contractors replicate offshore efficiency standards.
REACH authorization requirements for heavy mineral imports are tightening purity documentation across European supply chains. ECHA's expanded substance evaluation program is forcing importers to establish certified chain-of-custody from mine to blender. Nordic offshore drillers are responding by consolidating procurement through Rotterdam-based processors with in-house analytical laboratories.
Integrated service contracts are displacing spot chemical purchases among supermajor operators. Density management is bundling with directional drilling and logging services, compressing standalone weighing agent margins while extending contract duration. This restructuring is most visible in U.S. unconventional plays where operators prioritize single-vendor accountability over component cost optimization.
Weighing Agents Market Segmentation
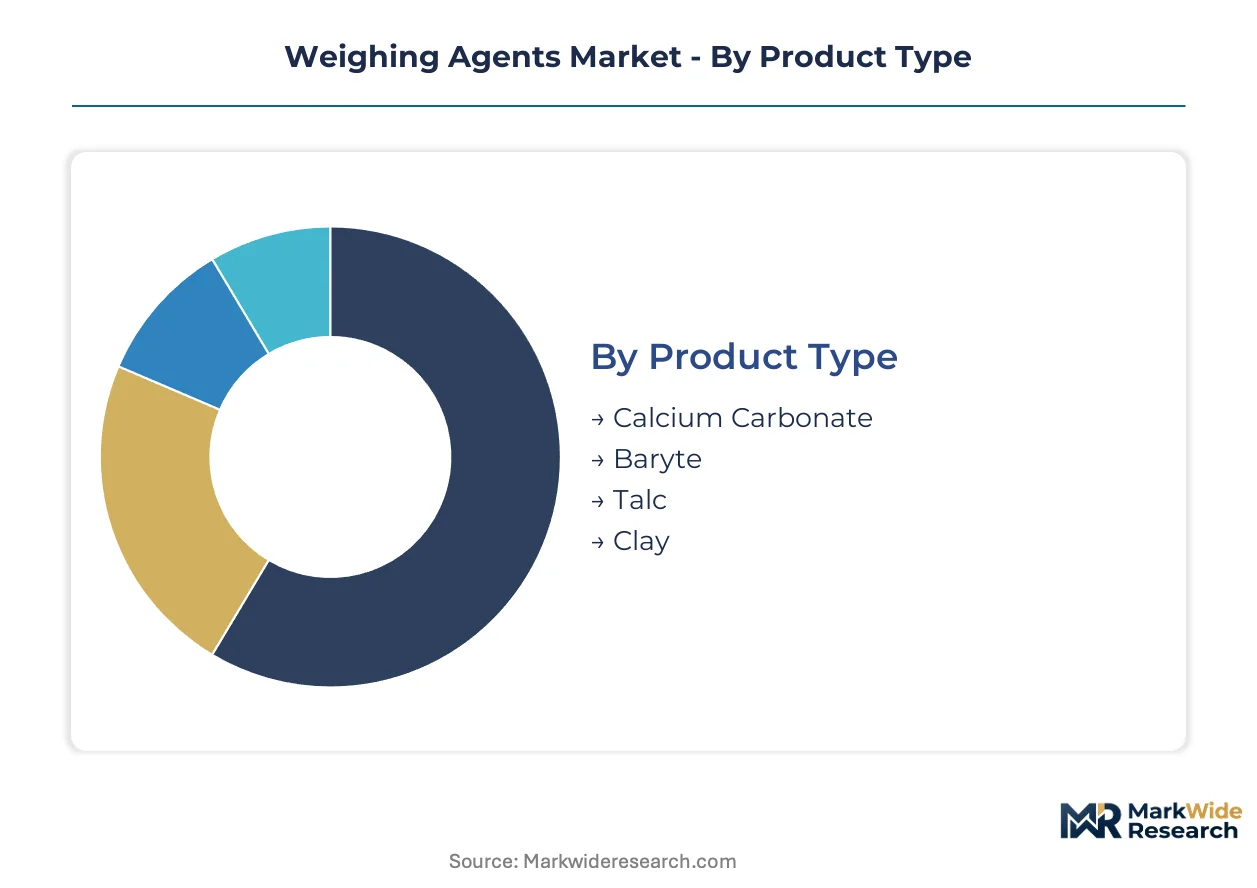
Weighing agent selection hinges on density specifications and end-use tolerances that vary sharply across oilfield, industrial, and consumer applications. Segmentation reveals where micronization capabilities command premium pricing versus where commodity grades suffice.
Product Type:
Volume concentrates in barite for drilling density, while premium margins accrue to specialized grades with tight particle-size distribution.
- Baryte:High-specific-gravity mineral (4.1–4.3 SG) dominates drilling fluid density management. Permian Basin operators load 800–1,200 pounds per lateral foot, sustaining demand for API-grade micronized ore despite Chinese export licensing volatility.
- Calcium Carbonate:Acid-soluble weighing agent serves well-completion fluids where formation damage tolerance outweighs maximum density requirements. Gulf of Mexico drillers specify this grade for reservoir sections where post-drilling acid cleanup is planned.
- Talc:Soft, lamellar structure suits plastics compounding and automotive underbody coatings requiring low abrasion during processing.
- Clay:Bentonite and attapulgite grades provide thixotropic weighting in specialty drilling muds where viscosity control accompanies density modification.
Today's leader: Baryte. Tomorrow's challenger: Calcium Carbonate.
Application:
Application mix tracks oilfield cycle intensity, with industrial coatings offering counter-cyclical volume during drilling downturns.
- Drilling Fluids:Oil and gas operations consume the largest tonnage, with synthetic-based mud formulations driving specification premiums for low-mercury, low-cadmium barite under EPA effluent guidelines.
- Paints:Automotive underbody sealants and marine coatings adopt high-loading mineral dispersions to replace metal flake, opening volume outside hydrocarbon extraction cyclicality.
- Plastics:Polymer compounding for automotive and construction products uses talc and calcium carbonate to adjust specific gravity without sacrificing melt flow properties.
- Ceramics:Whiteware and sanitaryware manufacturing employs barite and clay for density control during firing, with quality grades commanding sourcing premiums.
Drilling Fluids anchors current revenue; Paints exhibits the steepest expansion trajectory as automotive lightweighting drives mineral substitution for metal.
End User:
Customer concentration varies from consolidated supermajors with integrated service contracts to fragmented construction material suppliers.
- Oil & Gas:Supermajor operators bundle density management with directional drilling services, compressing standalone chemical margins while extending contract duration through single-vendor accountability.
- Construction:Cement and concrete admixture producers consume calcium carbonate grades where density modification affects pumpability and placement characteristics.
- Pharmaceutical:Tablet formulation and excipient applications demand food-grade or USP-certified mineral purity with documented chain-of-custody.
- Food Processing:Limited specialty use in sugar refining and beverage clarification where GRAS-status minerals meet FDA purity thresholds.
Oil & Gas retains procurement scale; Construction offers margin stability through non-cyclical infrastructure spending.
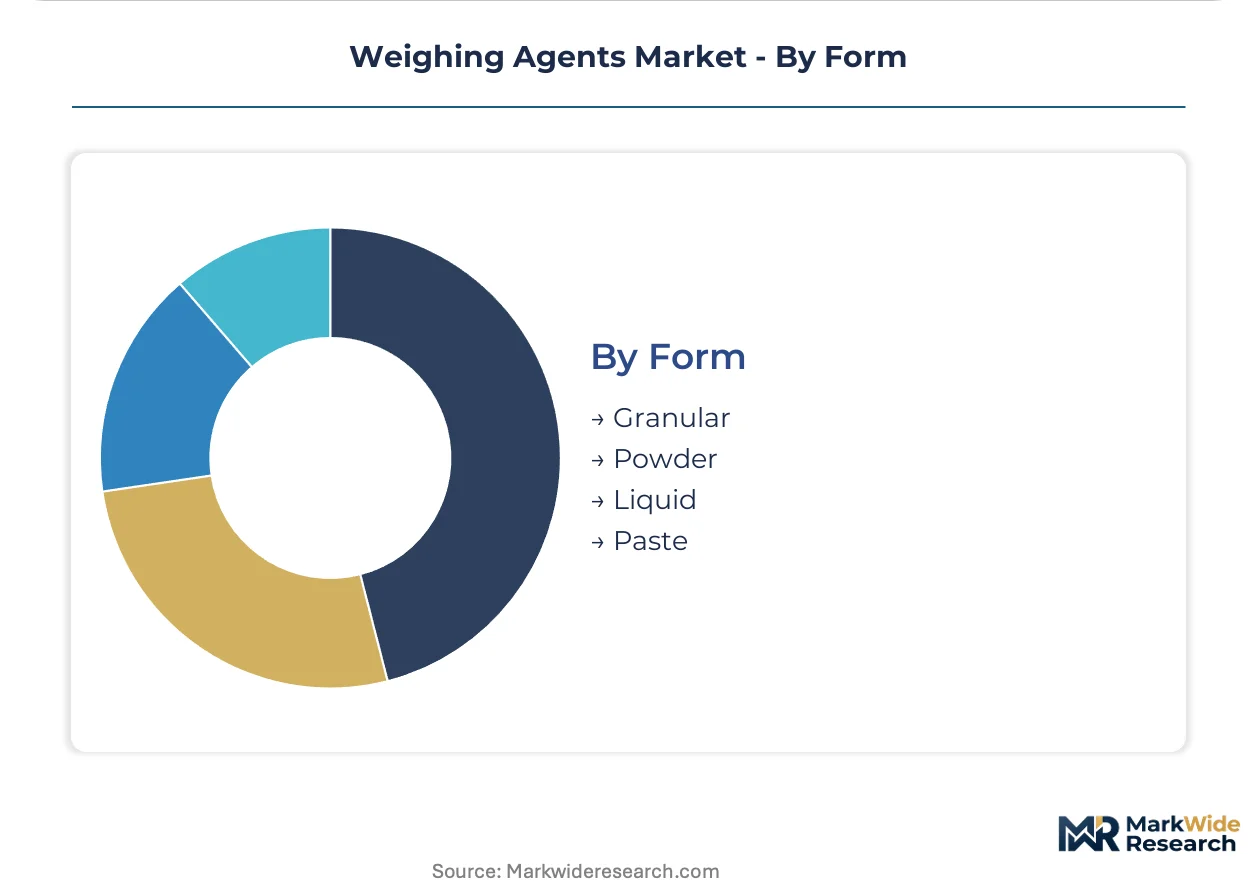
Form:
Physical format selection reflects handling automation levels and mixing system compatibility across land and offshore operations.
- Powder:Traditional bulk format commands largest volume share across oilfield and industrial applications, though dust control and pneumatic handling costs erode economics at smaller scale.
- Liquid:Pre-dispersed slurries gain share in automated mud-mixing systems, with Gulf of Mexico operators retrofitting continuous-mix skids that demand this format for real-time density control.
- Granular:Coarse grades suit construction admixtures and ceramics where dissolution rate or firing behavior matters more than rapid dispersion.
- Paste:High-solids formulations serve niche coatings and sealant applications where viscosity stability during storage reduces downstream processing steps.
Powder dominates tonnage; Liquid suspensions are climbing the fastest as automation penetrates land-based drilling operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates barite ore exports while the United States consumes the largest processed volumes, creating a trans-Pacific supply dynamic that shapes regional investment priorities.
United States
Permian Basin operators in Texas and New Mexico drive demand through extended lateral drilling programs exceeding 15,000 feet. EPA effluent limitation guidelines for synthetic-based muds mandate low-mercury barite grades that command sourcing premiums. Houston hosts the densest concentration of blending facilities serving Gulf of Mexico offshore contracts.
China
Guizhou and Hunan provinces concentrate 4.2+ specific-gravity ore reserves that supply global drilling fluid manufacturers. Export licensing volatility from the country's trade administration creates periodic supply squeezes for international processors. Qingdao port infrastructure handles the majority of seaborne barite shipments to Asia-Pacific refiners.
Norway
North Sea drilling contractors source API-grade micronized barite for subsea completions under stringent North Sea discharge regulations. The country's petroleum safety authority enforces trace-metal documentation that exceeds baseline EU requirements. Stavanger anchors regional procurement through integrated service company headquarters.
Saudi Arabia
Aramco's unconventional gas development in the Jafurah Basin is expanding horizontal drilling intensity that requires density-management chemicals. The national oil company mandates local content requirements that favor domestic blending investments over direct imports. Dhahran industrial clusters host emerging micronization capacity to serve regional operators.
Brazil
Pre-salt carbonate reservoirs in the Santos Basin demand acid-soluble calcium carbonate weighing agents for reservoir protection. ANP regulatory frameworks for offshore chemical discharge influence formulation selection among international service providers. Macaé serves as the primary logistics hub for Campos and Santos basin supply operations.
Weighing Agents Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated oilfield service providers commanding drilling fluid contracts while independent mineral processors supply industrial coatings and construction applications. The market structure concentrates around three tiers: multinational energy service companies with captive chemical divisions, specialized micronization houses with API certification, and regional blenders competing on logistics proximity. Two dominant competitive moves define current positioning: backward integration into ore sourcing to secure 4.2+ SG material, and partnership arrangements with automated mud-mixing system vendors to lock in liquid suspension format demand.
Among integrated service providers, Schlumberger exemplifies the bundled chemical-and-services archetype through its drilling fluids platform. Elkem ASA represents specialized micronization capability with European regulatory compliance infrastructure. Newpark Resources anchors the regional blender tier through basin-proximate facility networks in active shale plays.
| Leading Market Players |
|---|
| Schlumberger |
| Baroid Industrial Drilling Products |
| Elkem ASA |
| Global Drilling Fluids and Chemicals |
| BHGE |
| Carmeuse |
| Imdex |
| Newpark Resources |
| United Mud-Chem |
| Others |
Value Network & Pricing Analysis
API-grade micronization capability against commodity ore sorting creates a sharp bifurcation that manifests in both pricing power and supply chain configuration. Premium processors command sourcing premiums through certified low-mercury, low-cadmium ore streams while regional blenders compete on logistics proximity alone.
Pricing Analysis
Capacity additions in Saudi Arabia and Argentina are reshaping price floors for regional barite processing. Three-tier pricing structure across API-certified, industrial-grade, and unprocessed ore levels dominates the market. Price differentiation rests on mercury content thresholds and REACH documentation depth. Cost compression in the commodity tier is intensifying because Chinese export licensing volatility forces spot-market purchasing. Supermajor operators show least price sensitivity through bundled service contracts; construction admixture buyers exhibit highest sensitivity.
Supply Chain Analysis
Fluid-recycling recovery flows are creating reverse-logistics infrastructure that most regional blenders lack, forcing capital deployment or partnership dependency. Ore supply concentrates in China, India, and Morocco. Processing draws from Guizhou 4.2+ SG reserves, API-certified micronization capacity, and automated grinding equipment. Single-source vulnerability runs through Chinese export quota administration. Distribution runs through Rotterdam for European REACH compliance and Houston for Gulf of Mexico offshore contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. EPA effluent limitation guidelines and REACH authorization requirements are redirecting procurement toward documented low-trace-metal specifications that only certified processors can guarantee.
For Market Incumbents: Cement API RP 13K certification pipelines through third-party laboratory partnerships to compress qualification timelines. Deepen backward integration into Guizhou and Hunan ore offtake agreements before Chinese export licensing tightens again. Calcium carbonate substitution in well-completion fluids represents the most pressing substitute threat; counter through micronization automation investments that acid-soluble grades cannot match. For New Entrants and Emerging Players: Enter via Argentina's Vaca Muerta development where Neuquén Basin operators are importing U.S. blending expertise and domestic micronization capacity remains scarce. Target coatings density modification for automotive underbody sealants as the most penetrable industrial segment outside oilfield cyclicality. Pursue joint-venture structures with established ore processors rather than greenfield mining investments. For Investors and Strategic Acquirers: Consolidation pressure builds where fluid-recycling integration demands capital scales that regional blenders cannot self-finance. The 5-10 year viability window favors processors with captive API-grade micronization and in-house analytical laboratories. Acquisition target archetype: Rotterdam-based or Houston-based regional blenders with basin-proximate logistics but lacking backward ore integration. Monitor ECHA substance evaluation program expansion and EU Critical Raw Materials Act stockpiling mandates as inflection indicators for European supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ore Sourcing | Captive supply of 4.2+ SG Guizhou reserves insulates against Chinese export quota volatility. |
| Micronization Automation Deployment | API-grade particle-size distribution at throughput rates manual classification cannot match. |
| Liquid Suspension Format Expansion | Pre-dispersed slurries align with Gulf of Mexico continuous-mix skid retrofits and land-based replication. |
| REACH Compliance Infrastructure Investment | In-house analytical laboratories in Rotterdam consolidate Nordic offshore driller procurement. |
| Fluid-Recycling Recovery Systems | Closed-loop mud reprocessing capability locks in supermajor integrated service contracts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions included drilling fluids engineers at supermajor operators, procurement leads at regional oilfield service companies, micronization plant managers, and ECHA regulatory affairs specialists. Secondary validation drew from API specification documentation, EPA effluent limitation guideline filings, REACH registration dossiers, and customs trade data for barite ore shipments. Bottom-up volume modeling and top-down market sizing triangulated segment outputs.
Comparable-period anchoring linked projection assumptions to historical drilling intensity patterns across the Permian Basin, Gulf of Mexico, and North Sea. Segmentation dimensions spanned product grade tier, application end-use, physical format, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating lateral length extension trends and synthetic-based mud formulation shifts. Forecast inputs included automated mud-mixing system penetration rates and EU Critical Raw Materials Act implementation timelines.
Inputs from API laboratory certification queues and ECHA substance evaluation schedules were available through the study window; gaps in real-time Chinese export licensing administration introduce uncertainty bands around ore price assumptions. Forecasts reflect documented assumptions about regulatory enforcement intensity and drilling contractor automation adoption. Practitioners should monitor EPA effluent guideline revision cycles and Aramco Jafurah Basin development pace for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Europe Fuel Additives Market
Additives
Global Packaging Additives Market
Additives
Friction Modifier Additives Market
Additives
Citric Acid Anhydrous Market
Additives
Citric Acid Market
Additives
Magnesium Stearate Market
Additives
Global Silica-Based Matting Agents Market
Additives
Global Flame Retardant Masterbatches Market
Additives
Fluoropolymer Additives Market
Additives
Liquid Thickeners Market
Additives
Chemical Silage Additives Market
Additives
Ammonium Phosphatide Market
Additives
Printing Ink Additives Market
Additives
Ammonium Acetate Market
Additives
South Africa Acidulants Market
Additives
Sorbitan Laurate Market