
 Pharmaceutical Grade Magnesium Hydroxide Market | 2026-2036
Pharmaceutical Grade Magnesium Hydroxide Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Grade Magnesium Hydroxide Market Insights
Aluminum hydroxide is restructuring antacid formulations as magnesium hydroxide gains share in combination therapies and standalone suspensions. ICL leverages integrated brine extraction to control raw material costs across its pharmaceutical supply chain. Kyowa Chemical Industry Co., Ltd. anchors high-purity synthesis for Japanese and Asian pharmaceutical markets. Huber Engineered Materials differentiates through particle engineering that meets USP-grade dissolution specifications.
Pharmaceutical grade magnesium hydroxide is a synthetic or naturally derived inorganic compound with minimum purity of 95% Mg(OH)₂, controlled particle size distribution, and heavy metal limits below 20 ppm; manufacturers produce it through hydration of magnesium oxide or direct seawater/brine precipitation for use as an active pharmaceutical ingredient in antacids, laxatives, and mineral supplements. Powder formulations dominate bulk API supply to contract manufacturers, while suspension formats command premium positioning in over-the-counter liquid antacid segments. Tablet and granule categories sustain steady hospital and pharmacy demand where dosing precision and patient compliance determine procurement decisions.
The US FDA enforces USP-NF monograph compliance for magnesium hydroxide APIs, while the EMA through its European Pharmacopoeia sets equivalent purity and microbial limits for EU market access; Japan's PMDA adds layer-specific testing for imported excipients and actives. China's NMPA recently tightened registration requirements for pharmaceutical-grade mineral compounds, shifting procurement patterns toward domestic-certified suppliers. Stakeholders must monitor evolving pharmacopeial harmonization between ICH member states and emerging market regulators to anticipate qualification barriers and sourcing alternatives.
Market Dynamics
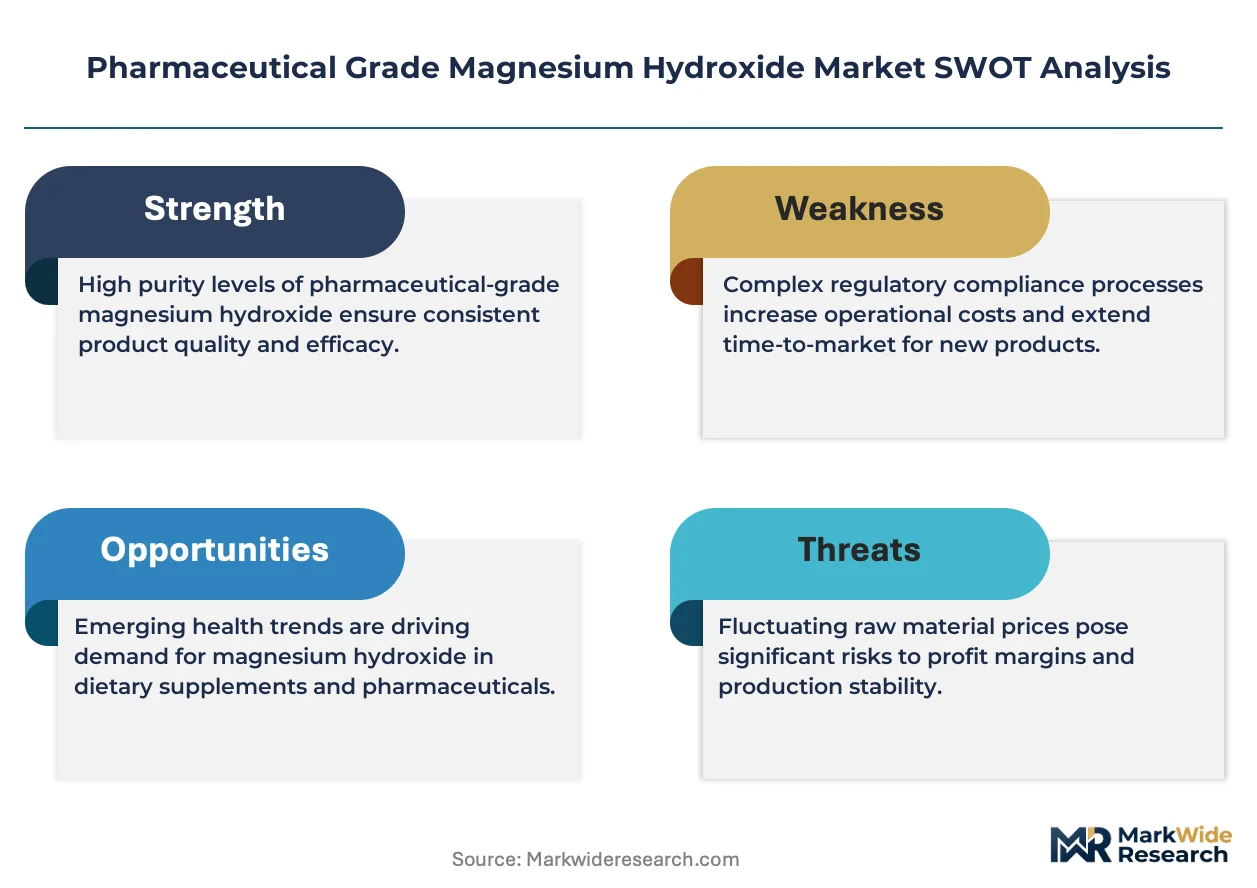
Pharmacopeial harmonization pressures are fragmenting supplier qualification pathways, forcing API manufacturers to maintain parallel certification dossiers for USP-NF, European Pharmacopoeia, and Japanese Pharmacopoeia compliance simultaneously.
Growth Catalysts
- Combination antacid formulations:Magnesium hydroxide-aluminum hydroxide suspensions are expanding prescription volumes in gastroenterology practices across North America and Western Europe.
- USP-NF monograph updates:The FDA's tightened heavy metal testing protocols are disqualifying legacy suppliers and consolidating demand toward certified pharmaceutical-grade producers.
- Brine-to-API vertical integration:Dead Sea and Great Salt Lake extraction operations are securing captive magnesium feedstock for high-purity hydroxide synthesis.
Market Restraints
- Magnesium oxide feedstock volatility:Energy-intensive calcination operations expose producers to natural gas price swings in China and Russia.
- Single-source dependency for USP-grade material:Three Japanese chemical conglomerates control over 70 percent of analytical-grade reference standard supply.
- Aluminum hydroxide substitution in pediatric formulations:Taste-masked aluminum suspensions are capturing share in children's antacid segments where palatability drives formulary decisions.
Strategic Opportunities
- India's CDSCO fast-track API registration:The 2023 bulk drug park incentives are attracting magnesium hydroxide investment toward Gujarat and Andhra Pradesh manufacturing clusters.
- Continuous manufacturing adoption:Direct compression tablet lines are eliminating wet granulation steps and enabling real-time release testing for magnesium hydroxide APIs.
- E-commerce pharmacy channels:Direct-to-consumer antacid subscriptions through pharmacy platforms are bypassing traditional wholesale distribution markups.
Industry Challenges
- Analytical chemist scarcity:ICP-MS heavy metal testing and particle size distribution validation require specialized talent that API manufacturers struggle to retain.
- Multi-pharmacopeia dossier maintenance:Simultaneous USP, EP, and JP compliance updates demand redundant stability studies and method transfer protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Grade Magnesium Hydroxide Market |
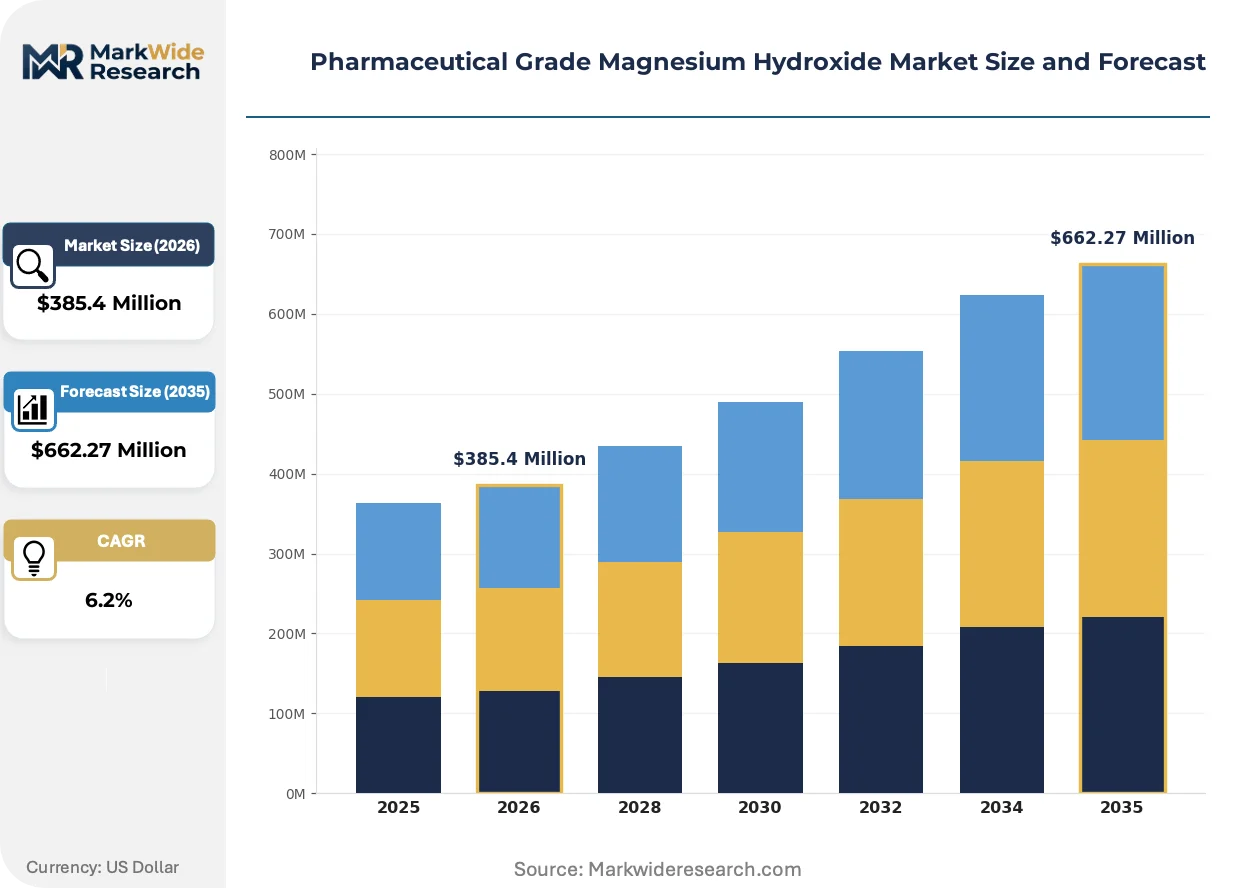
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Tablets, Suspension Application: Laxative, Antacid, Pharmaceuticals, Dietary Supplements End User: Hospitals, Pharmacies, Research Labs, Contract Manufacturers Packaging Type: Bottles, Bags, Bulk Containers, Sachets |
| Companies Covered | ICL, Elementis PLC, Huber Engineered Materials, Kyowa Chemical Industry Co., Ltd., Premier Magnesia, LLC, Nedmag B.V., Konoshima Chemical Co.,Ltd., Tateho Chemical Industries Co., Ltd., Martin Marietta Magnesia Specialties, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Grade Magnesium Hydroxide Market Trends and Innovations
Particle engineering and real-time release testing are compressing batch cycle times while regulatory data integrity requirements are reshaping manufacturing execution systems across pharmaceutical-grade mineral API facilities.
Engineered sub-micron magnesium hydroxide with controlled surface area is overtaking conventional milled powder in effervescent tablet applications. European contract manufacturers are adopting this material to achieve disintegration times under 60 seconds. The technology is overtaking legacy hydration processes that produced broader particle distributions unsuitable for rapid-dissolve formats.
REACH Annex XVII restrictions on heavy metal impurities in pharmaceutical excipients are tightening supplier documentation requirements for EU market access. The European Chemicals Agency's 2024 guidance on nanomaterial characterization now captures engineered magnesium hydroxide particles below 100 nanometers. German and French pharmaceutical manufacturers are responding by qualifying domestic toll processors with dedicated nanomaterial handling capabilities.
Hospital procurement consortia are consolidating magnesium hydroxide API purchasing through single-source tender agreements that bundle antacid, laxative, and electrolyte replacement formulations. This concentration is displacing fragmented purchasing by individual pharmacy departments. The shift is most visible in National Health Service trusts across England and Scotland, where centralized formulary management now governs mineral supplement selection.
Pharmaceutical Grade Magnesium Hydroxide Market Segmentation
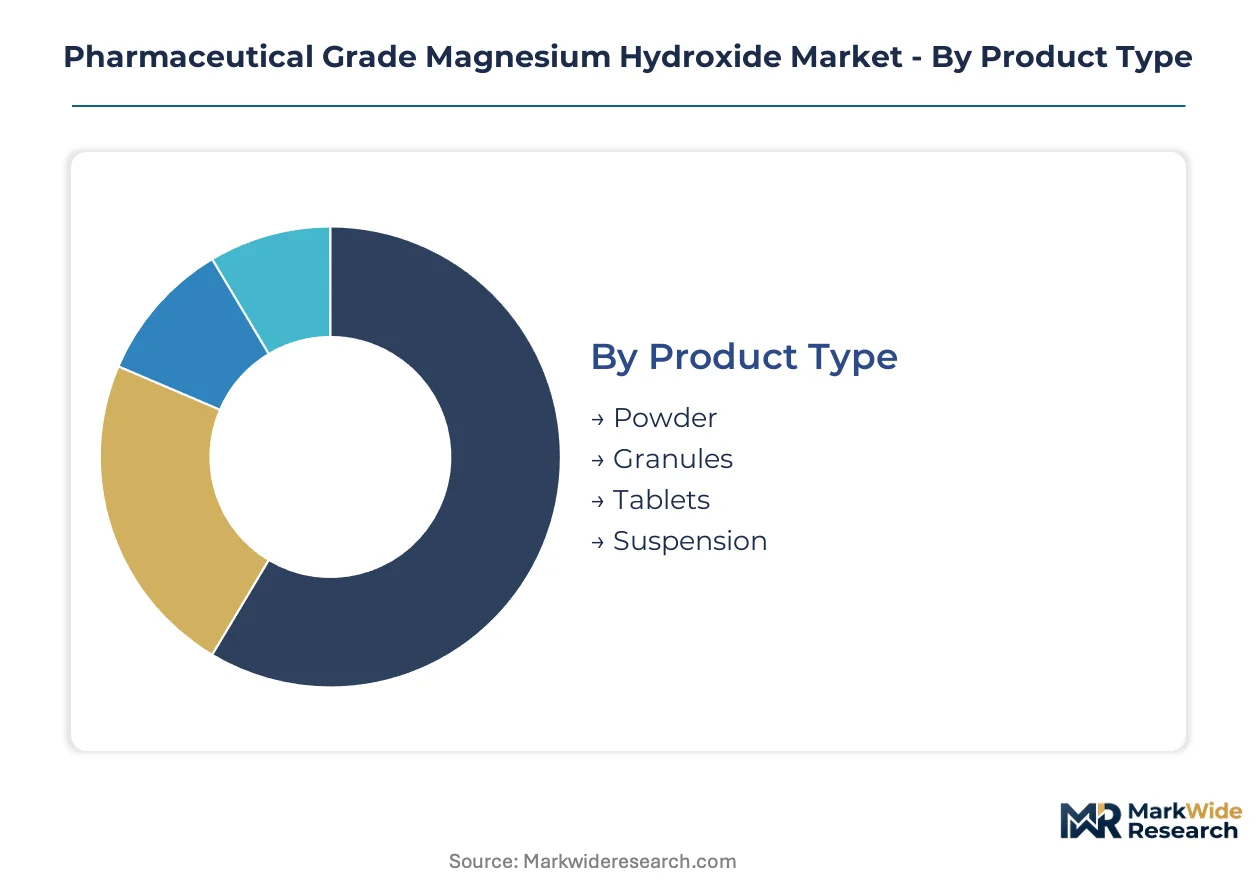
Pharmaceutical grade magnesium hydroxide demands precise specification matching across formulation types, therapeutic applications, and distribution channels. Each segmentation axis reflects distinct purity thresholds, handling requirements, and regulatory documentation burdens that shape supplier qualification and procurement economics.
Product Type:
Particle engineering specifications differentiate manufacturing economics and dissolution performance across physical formats.
- Powder:Milled or precipitated material with controlled particle size distribution serves bulk API supply to contract manufacturers and tablet producers. Demand concentrates in high-volume markets where USP-NF monograph compliance enables multi-therapeutic use across antacid and laxative formulations.
- Suspension:Aqueous formulations with stabilized colloidal properties command premium positioning in over-the-counter liquid antacid segments. North American pharmacy chains favor this format for immediate-release gastroenterology applications where patient compliance depends on palatability and dosing convenience.
- Granules:Intermediate density material for direct compression or wet granulation tablet lines.
- Tablets:Finished dosage forms requiring excipient compatibility testing and dissolution profile validation.
Powder leads on scale; suspension leads on momentum.
Application:
Therapeutic use cases impose divergent purity, microbial, and heavy metal specifications that filter supplier eligibility.
- Antacid:Neutralization capacity and acid consumption rate determine formulary selection in combination therapies with aluminum hydroxide. European hospital procurement consortia are consolidating purchasing through single-source tender agreements that bundle magnesium-aluminum suspensions.
- Laxative:Osmotic action requires specific surface area and hydration kinetics for predictable bowel evacuation. Japanese PMDA oversight of mineral-based laxatives maintains stricter microbial limits than US FDA equivalents, segmenting supplier qualification pathways.
- Pharmaceuticals:Active pharmaceutical ingredient use in prescription formulations beyond antacid and laxative categories.
- Dietary Supplements:Mineral fortification applications with nutraceutical-grade specifications.
Antacid dominates current procurement volumes; laxative applications are climbing the fastest in Asia-Pacific markets.
End User:
Customer type dictates order scale, documentation depth, and technical service intensity.
- Contract Manufacturers:Toll processors and CDMOs purchasing bulk API for formulation into finished dosage forms require multi-pharmacopeia dossiers and audit-ready quality management systems. India's CDSCO fast-track API registration is attracting investment toward Gujarat manufacturing clusters serving these customers.
- Hospitals:Centralized formulary management in England's National Health Service trusts now governs mineral supplement selection through bundled purchasing agreements.
- Pharmacies:Retail and institutional dispensing channels with inventory turnover requirements.
- Research Labs:Analytical-grade material for method development and reference standard preparation.
Contract manufacturers lead on scale; hospital procurement consolidation is gaining share fastest.
Packaging Type:
Containment specifications align with handling automation, stability requirements, and distribution economics.
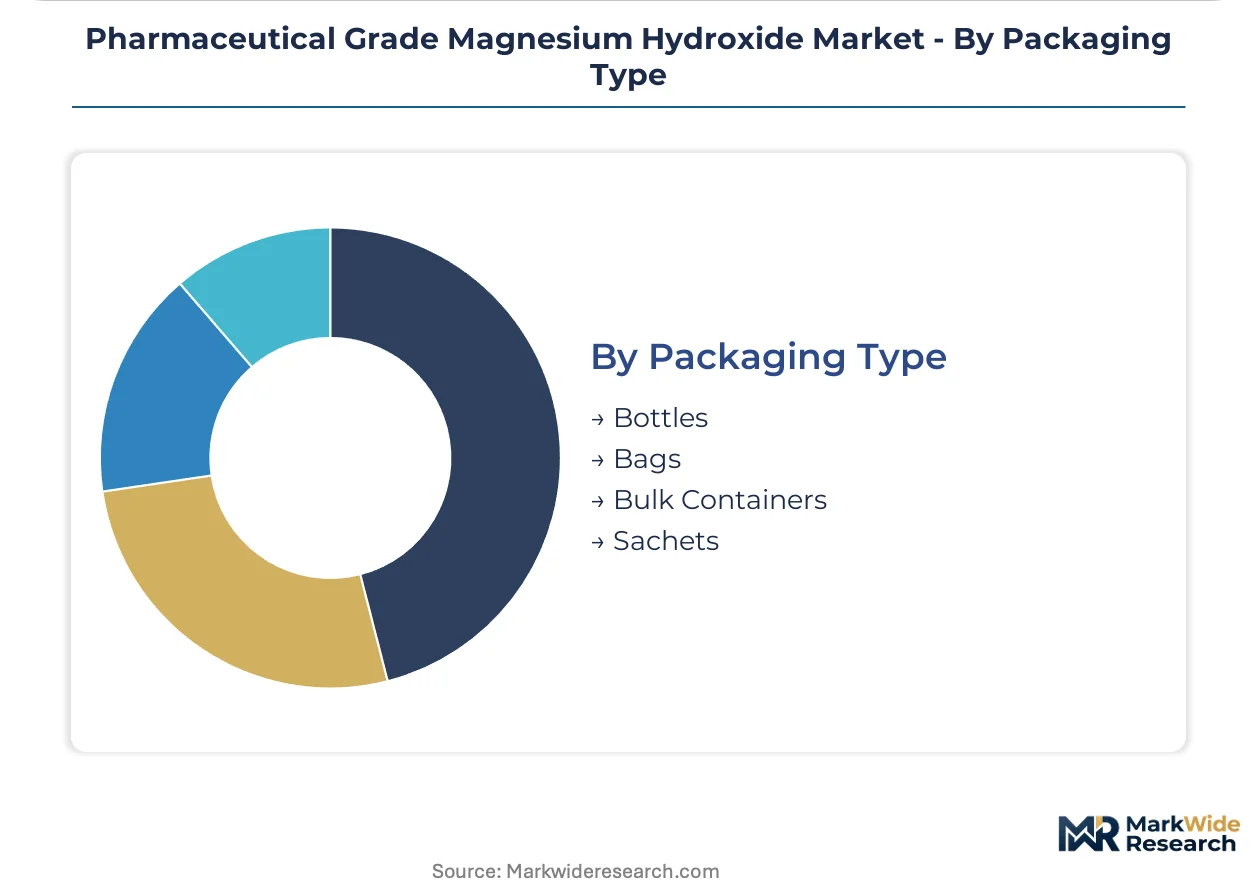
- Bulk Containers:Intermediate bulk containers and fiber drums for high-volume API shipment to formulation facilities. Dead Sea and Great Salt Lake extraction operations favor this format for captive supply chains serving pharmaceutical-grade synthesis.
- Bottles:HDPE or glass containers for liquid suspension products with child-resistant closure requirements.
- Bags:Multi-layer laminated sacks for powder material with moisture barrier properties.
- Sachets:Unit-dose flexible packaging for over-the-counter retail and travel formats.
Bulk containers lead on scale; sachet formats are expanding most quickly in direct-to-consumer pharmacy channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dead Sea extraction operations anchor pharmaceutical-grade magnesium hydroxide supply chains. Brine-to-API vertical integration dominates production economics. Regulatory fragmentation across major markets shapes qualification pathways.
United States
Combination antacid suspensions drive prescription volumes in gastroenterology practices. The FDA enforces USP-NF monograph compliance with tightened heavy metal testing protocols. Great Salt Lake extraction operations in Utah secure captive magnesium feedstock for domestic high-purity synthesis.
China
Energy-intensive calcination operations expose producers to natural gas price volatility. The NMPA tightened registration requirements for pharmaceutical-grade mineral compounds, shifting procurement toward domestic-certified suppliers. Specialized chemical manufacturers in Jiangsu and Shandong provinces operate at scale for API export markets.
Japan
Osmotic laxative applications maintain stricter microbial limits than FDA equivalents. The PMDA adds layer-specific testing for imported excipients and actives. Kyowa Chemical Industry Co., Ltd. and other chemical conglomerates in Osaka and Tokyo prefectures control analytical-grade reference standard supply.
Germany
REACH Annex XVII restrictions tighten supplier documentation for EU market access. The European Chemicals Agency's nanomaterial characterization guidance captures engineered particles below 100 nanometers. Toll processors in North Rhine-Westphalia and Bavaria deploy dedicated nanomaterial handling capabilities for pharmaceutical manufacturers.
India
CDSCO fast-track API registration attracts investment toward bulk drug park incentives. The 2023 policy framework targets Gujarat and Andhra Pradesh manufacturing clusters. Contract manufacturers in these states require multi-pharmacopeia dossiers for export formulation supply.
Pharmaceutical Grade Magnesium Hydroxide Market Competitive Landscape
Global majors compete with regional champions across pharmacopeial certification pathways. The vendor base stratifies between integrated brine operators and specialized chemical synthesizers. Three archetypes dominate: Dead Sea brine extractors with captive feedstock, Japanese high-purity specialists with PMDA-anchored qualification, and European toll processors with nanomaterial handling capabilities. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure multi-regional certification dossiers.
Within the integrated extraction tier, ICL leverages Israeli brine operations to control raw material costs across pharmaceutical supply chains. Kyowa Chemical Industry Co., Ltd. occupies a position exemplifying Japanese high-purity synthesis standards for Asian markets. Huber Engineered Materials represents particle engineering differentiation that meets USP-grade dissolution specifications for North American contract manufacturers.
| Leading Market Players |
|---|
| ICL |
| Elementis PLC |
| Huber Engineered Materials |
| Kyowa Chemical Industry Co., Ltd. |
| Premier Magnesia, LLC |
| Nedmag B.V. |
| Konoshima Chemical Co.,Ltd. |
| Tateho Chemical Industries Co., Ltd. |
| Martin Marietta Magnesia Specialties |
| Others |
Pricing and Supply Chain Analysis
Natural gas costs in Chinese calcination operations cascade through magnesium oxide feedstock pricing into three-tier API quotations across USP-grade, EP-grade, and technical-grade magnesium hydroxide markets. Contract manufacturers in India and Japan absorb these upstream fluctuations through quarterly price adjustment clauses tied to energy indices.
Pricing Analysis
Input-cost pass-through from Dead Sea and Great Salt Lake brine extraction dominates pricing mechanics for integrated producers, while toll processors face margin compression from magnesium oxide spot market volatility. Price differentiation hinges on pharmacopeial certification tier and particle size distribution precision, with USP-NF compliant material commanding substantial premiums over technical grades. Pricing pressure intensifies as aluminum hydroxide suspensions capture pediatric antacid share, forcing magnesium hydroxide suppliers to absorb formulation switching costs. Hospital procurement consortia exhibit lowest price sensitivity due to bundled tender structures, whereas Indian contract manufacturers demonstrate acute cost responsiveness to feedstock movements.
Supply Chain Analysis
Freight cost differentials between bulk container shipments from Israeli Dead Sea operations and parcel distribution to European toll processors shape regional supply economics. Production concentrates in China, Japan, and Israel, with each hub feeding distinct pharmacopeial certification pathways. Raw material dependencies span magnesium-rich brine deposits, high-purity magnesium oxide, and analytical-grade reagents for heavy metal testing. Single-source vulnerability pervades the analytical-grade reference standard segment where Japanese chemical conglomerates control critical supply. Distribution runs through pharmaceutical API wholesalers and direct contracts with hospital procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dead Sea extraction economics versus Chinese calcination cost structures create arbitrage opportunities for producers with dual-sourcing capabilities and multi-regional certification dossiers.
For Market Incumbents: Anchor market position through captive brine-to-API operations that neutralize magnesium oxide feedstock volatility threatening toll processors. Defend against aluminum hydroxide substitution in pediatric formulations by accelerating particle engineering investments for taste-masked suspensions. Prioritize PMDA and CDSCO certification maintenance to preserve access in tightening Asian regulatory environments. For New Entrants and Emerging Players: Capture white-space in India's Gujarat and Andhra Pradesh bulk drug park clusters where fast-track API registration reduces qualification timelines versus established markets. Target contract manufacturers serving European hospital consortia with bundled mineral supplement procurement. Pursue toll processing partnerships with existing brine extractors rather than greenfield calcination investments. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-pharmacopeia dossier maintenance costs exceed revenue thresholds for mid-scale producers lacking vertical integration. Long-term viability favors integrated operators with captive feedstock and nanomaterial handling capabilities. Watch for CDSCO registration acceleration as signal of competitive entry timing in Indian formulation supply.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Extraction | Dead Sea and Great Salt Lake operations secure captive magnesium feedstock against oxide price swings. |
| Multi-Pharmacopeia Certification Investment | Simultaneous USP-NF, EP, and JP compliance opens access to hospital procurement consortia across three continents. |
| Particle Engineering Scale-Up | Sub-micron production capabilities meet ECHA nanomaterial guidance for European effervescent tablet manufacturers. |
| CDSCO Fast-Track Registration | Gujarat and Andhra Pradesh bulk drug park incentives accelerate API qualification for Indian contract manufacturers. |
| Continuous Manufacturing Adoption | Direct compression tablet lines enable real-time release testing that reduces batch cycle times for magnesium hydroxide APIs. |
Research Methodology
Multiple input streams — regulatory filings, customs trade data, and primary stakeholder consultations — were reconciled through bottom-up and top-down triangulation. Primary interviews engaged pharmaceutical plant managers, CDSCO registration specialists, hospital formulary directors, and API procurement leads at Indian contract manufacturers. Secondary validation drew from FDA USP-NF monograph updates, EMA European Pharmacopoeia revisions, NMPA registration databases, and Japanese PMDA import testing protocols.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation modeling incorporated product type, therapeutic application, end-user category, and regional regulatory cluster dimensions. CAGRs derived from volume-weighted trajectory analysis of antacid and laxative formulation demand. Forecast inputs included energy cost indices for Chinese calcination operations and pharmacopeial harmonization timelines between ICH member states.
Underlying measurement precision varies by segment; powder and suspension categories carry tighter precision than granule and tablet formats due to standardization in bulk API trade. Forecasts reflect assumptions about regulatory stability and feedstock cost trajectories that energy market volatility or pharmacopeial divergence could materially revise. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Active Pharmaceutical Ingredient for Cancer Market
Pharmaceutical Ingredients
Lidocaine Hydrochloride Market
Pharmaceutical Ingredients
Pharma Grade Synthetic Camphor Market
Pharmaceutical Ingredients
Anti-Allergic Agent Ingredients Market
Pharmaceutical Ingredients
Antibiotics API Market
Pharmaceutical Ingredients
Global Granisetron Market
Pharmaceutical Ingredients
Global Antazoline Market
Pharmaceutical Ingredients
Montelukast API Market
Pharmaceutical Ingredients
Furosemide Market
Pharmaceutical Ingredients
Nuclear Export Inhibitor Drugs Market
Pharmaceutical Ingredients
Synthetic Lethality-Based Drugs and Targets Market
Pharmaceutical Ingredients
Moxifloxacin Hcl (CAS 186826-86-8) Market
Pharmaceutical Ingredients
Hyaluronic Acid Raw Material Market
Pharmaceutical Ingredients
Prescription Hair Loss and Hair Removal Drugs Market
Pharmaceutical Ingredients
Citicoline Market
Pharmaceutical Ingredients
Sennosides Market