
 Antibiotics API Market | 2026-2036
Antibiotics API Market Size, Share, and Industry Trends Forecast 2026-2036
Antibiotics API Market Insights
Market Context with Strategic Players
India's antibiotics API production corridor is narrowing the cost gap with Chinese suppliers while scaling fermentation capacity for penicillin and cephalosporin intermediates. Sandoz Group leverages backward integration into sterile API manufacturing to secure supply for its generic injectables portfolio across European hospitals. Centrient Pharmaceuticals anchors its position through enzymatic biocatalysis technology that cuts solvent waste in cephalosporin synthesis. Aurobindo Pharma competes on volume scale, operating multi-ton fermentation facilities that feed oral solid dosage markets in North America and Africa.
Technical Definition and Structural Segments
Antibiotics API comprises the biologically active molecular entities—typically produced via fermentation, semi-synthetic modification, or total chemical synthesis—that confer antibacterial activity in finished dosage forms, with purity specifications often exceeding 99.0% and impurity profiles governed by ICH Q3A/Q3B guidelines. These APIs serve as the foundational inputs for formulations targeting bacterial infections in human and veterinary medicine. Penicillins and cephalosporins together occupy the mature volume core of the market, where margin pools have compressed due to commoditization and procurement consolidation by generic drug manufacturers. Macrolides represent a faster-growing structural pocket, driven by rising respiratory infection burdens and hospital formulary preferences for azithromycin alternatives. The end-user dimension tilts toward contract manufacturing organizations, which now control a disproportionate share of capacity planning for biopharmaceutical companies seeking to outsource fermentation-based production.
Regulatory Framework and Forward Outlook
The FDA, EMA, and India's CDSCO collectively shape market access through divergent inspection protocols, with the FDA's data integrity emphasis and EMA's REACH-aligned environmental discharge rules raising site qualification costs for fermentation plants. China's NMPA has tightened import registration requirements for antibiotics API, forcing foreign suppliers to establish local analytical testing partnerships or joint-venture filing agents. Stakeholders must monitor how antimicrobial resistance policy at WHO and national levels reshapes reimbursement for legacy antibiotic classes, as this will determine which API chemistries retain commercial viability against novel therapeutic alternatives.
Market Dynamics
Antimicrobial stewardship programs in tertiary care hospitals are tightening procurement specifications for intravenous antibiotic formulations, forcing API suppliers to validate sterility assurance levels and impurity profiles that exceed baseline pharmacopeial standards.
Growth Catalysts
- CDSCO's Active Pharmaceutical Ingredient Inspection Scheme:India's tightened facility audits are accelerating quality upgrades among Hyderabad and Ahmedabad manufacturers, expanding their eligibility for US and EU supply contracts.
- Enzymatic biocatalysis:Fermentation-based producers deploying engineered hydrolases for cephalosporin intermediate synthesis are cutting solvent consumption by half, lowering environmental compliance costs and cycle times.
- Hospital formulary consolidation:European procurement alliances are standardizing on azithromycin alternatives for respiratory protocols, pulling macrolide API volumes upward.
Market Restraints
- Fermentation input volatility:Corn steep liquor and soybean meal prices swing with agricultural commodity cycles, compressing margin predictability for penicillin and cephalosporin bulk producers.
- Single-source concentration:China controls over 80 percent of key penicillin G potassium salt capacity, exposing downstream formulators to geopolitical supply disruption.
- ICH Q3D elemental impurity limits:The guideline's tightened thresholds for catalyst residues in metal-mediated synthetic steps are forcing expensive process revalidation across semi-synthetic cephalosporin lines.
Strategic Opportunities
- Veterinary feed additive channels:Sub-therapeutic antibiotic restrictions in the EU are creating demand for precision-dosed veterinary APIs in Brazil and Southeast Asian poultry markets.
- Continuous flow chemistry:Conventional batch fermentation for macrolide intermediates is giving way to plug-flow reactor systems that halve facility footprints and enable distributed manufacturing.
- India's PLI scheme for bulk drugs:The production-linked incentive program is subsidizing greenfield fermentation capacity for critical starting materials, attracting contract manufacturing commitments from European generics firms.
Industry Challenges
- Stability testing bottlenecks:FDA's data integrity emphasis on forced degradation studies is extending ANDA submission timelines for API suppliers lacking in-house analytical method development teams.
- Legacy equipment retrofit costs:Stainless steel fermentation trains built for 99.0 percent purity targets require seven-figure capital injections to meet current 99.5 percent specifications and real-time release testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibiotics API Market |
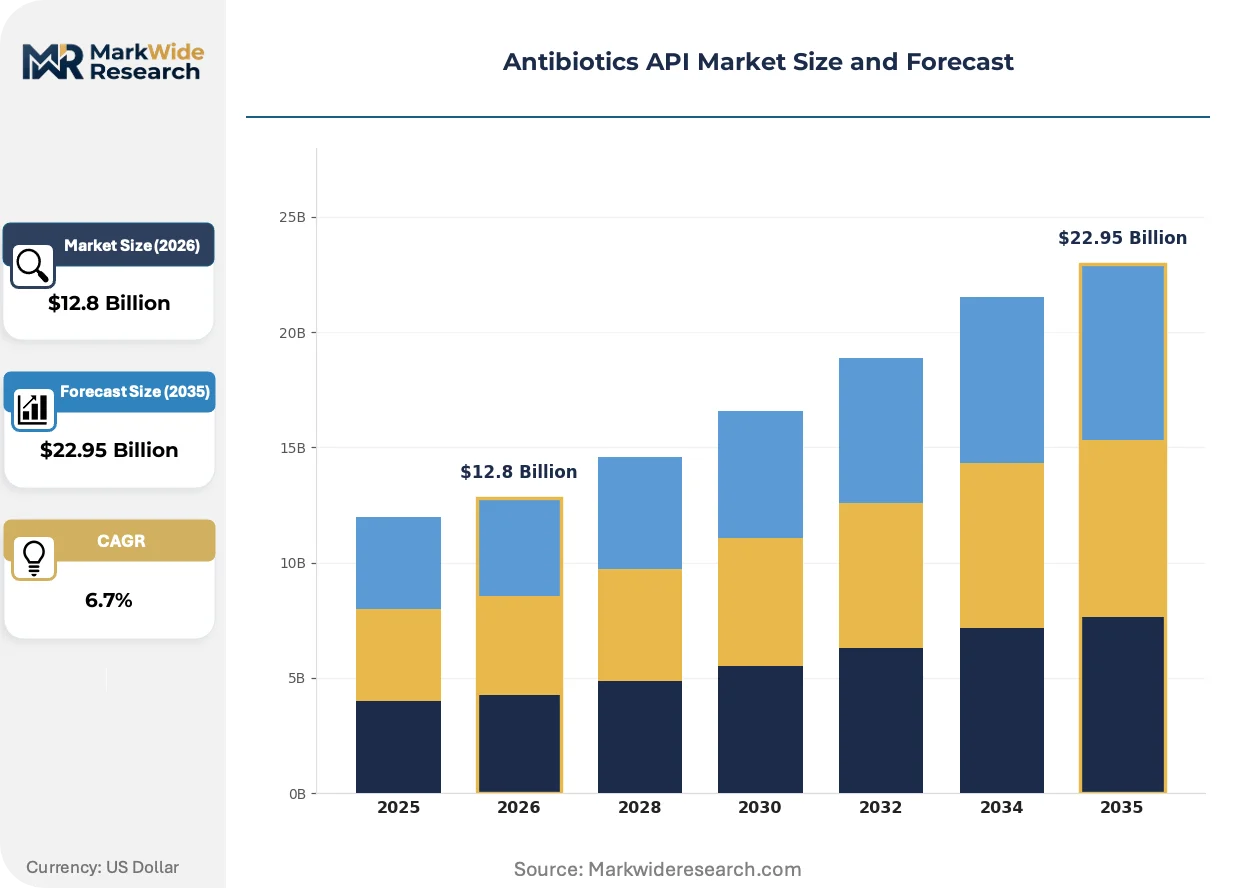
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Penicillins, Cephalosporins, Macrolides, Tetracyclines, Aminoglycosides Application: Human Therapeutics, Veterinary Medicine, Agricultural Use, Research & Development, Pharmaceutical Manufacturing Form: Powder, Crystalline, Liquid, Granules, Suspension End User: Generic Drug Manufacturers, Contract Manufacturing Organizations, Biopharmaceutical Companies, Research Institutions |
| Companies Covered | Sandoz Group, Centrient Pharmaceuticals, Aurobindo Pharma, Fresenius Kabi, CordenPharma, ACS DOBFAR, DAEWOONG PHARMACEUTICAL, Parabolic Drugs, Penam Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibiotics API Market Trends and Innovations
Biocatalytic process intensification and real-time analytical technologies are compressing development cycles for complex antibiotic intermediates while regulatory data integrity mandates reshape facility investment priorities.
Enzymatic transamination for side-chain attachment in semi-synthetic penicillins is collapsing the traditional chemical step count from twelve to four, reducing organic solvent volumes by 60 percent. Contract manufacturing organizations serving North American generic injectables markets are adopting these routes fastest, with three facilities completing tech transfers in the past eighteen months. The structural consequence is collapsing capital barriers for mid-scale entrants who previously required multi-hundred-million-dollar chemical synthesis infrastructure.
REACH-aligned environmental discharge rules for fermentation effluents are tightening volatile organic compound and total nitrogen limits at EU manufacturing sites, forcing producers to install membrane bioreactor and advanced oxidation process systems. The industrial consequence is a 15-25 percent uplift in site qualification costs that disadvantages smaller fermentation operators. Cephalosporin API suppliers targeting European hospital procurement alliances are responding by consolidating production at coastal facilities with existing wastewater treatment infrastructure.
Hospital purchasing cooperatives are unbundling API sourcing from finished dosage form contracts, creating direct procurement relationships with fermentation specialists that bypass traditional pharmaceutical distribution intermediaries. This disintermediation is most visible in German and French hospital networks, where formulary managers now negotiate API supply agreements separate from compounding pharmacy services. The shift is compressing price discovery cycles and exposing API suppliers to direct volume commitment penalties previously borne by finished dose manufacturers.
Antibiotics API Market Segmentation
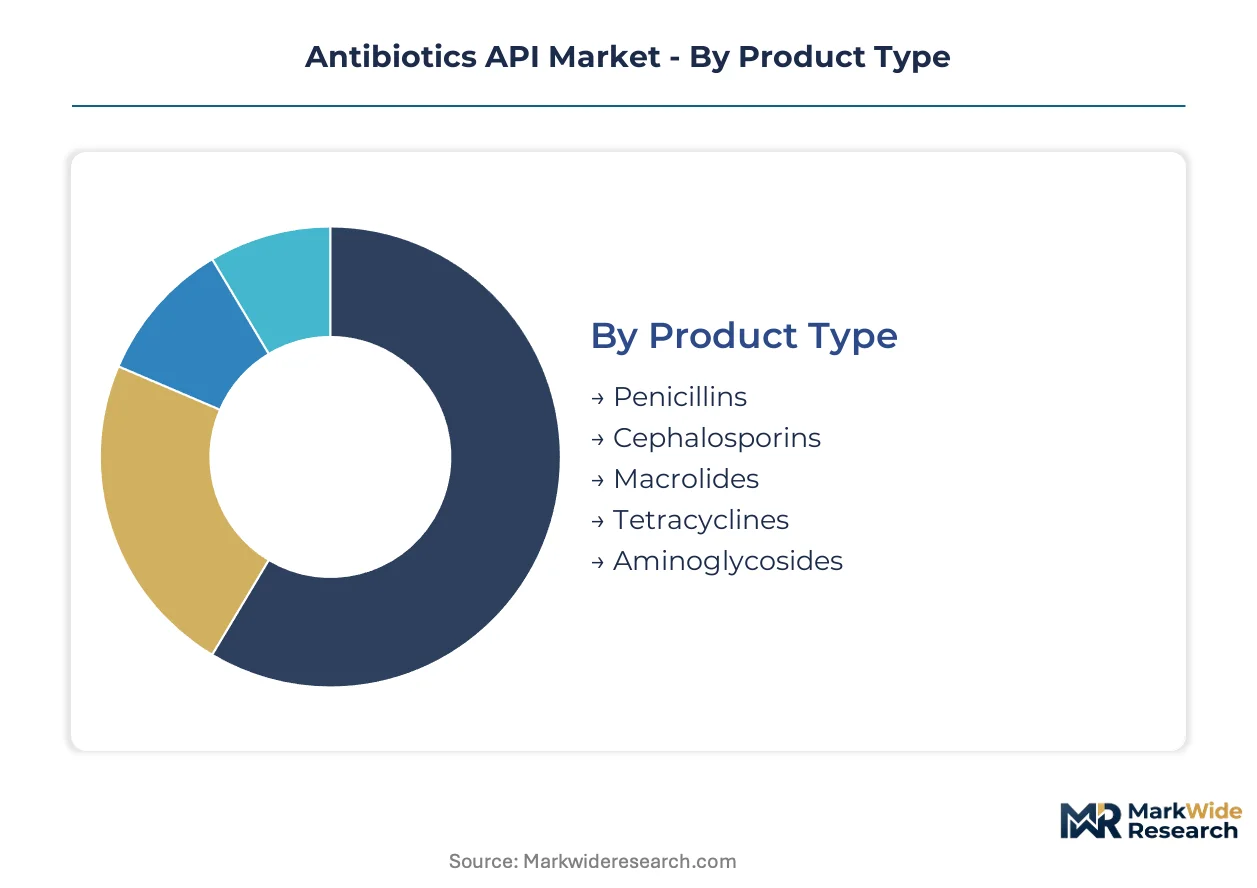
Antibiotics API procurement patterns diverge sharply across molecular classes and end-use channels, with fermentation scale and sterility assurance requirements determining supplier qualification barriers. Contract manufacturers and generic formulators impose distinct technical specifications that reshape capacity allocation across India's manufacturing clusters.
Product Type:
After-sales technical service intensity varies dramatically across antibiotic classes, with cephalosporin and macrolide APIs requiring ongoing process optimization support that penicillin suppliers rarely provide.
- Penicillins:Fermentation-derived beta-lactam cores with established 6-APA intermediate supply chains dominate volume procurement. Generic injectable manufacturers in North America source heavily from Hyderabad fermentation clusters where CDSCO-inspected facilities have secured US supply contracts.
- Cephalosporins:Semi-synthetic modifications demand enzymatic biocatalysis expertise and solvent recovery systems that raise facility capital requirements. European hospital procurement alliances are consolidating purchases around suppliers with REACH-compliant effluent treatment, compressing the qualified vendor pool.
- Macrolides:Azithromycin alternatives for respiratory protocols are climbing fastest among hospital formularies.
- Tetracyclines:Veterinary feed channels in Brazil and Southeast Asia sustain demand despite EU sub-therapeutic restrictions.
- Aminoglycosides:Narrow therapeutic indices limit production to specialized fermentation operators with validated impurity profiling.
Penicillins hold the largest share; momentum sits with macrolides.
Application:
Cost tier differentiation separates commodity human therapeutics from precision-dosed veterinary channels where formulation complexity commands premium pricing.
- Human Therapeutics:Intravenous antibiotic formulations for hospital stewardship programs require sterility assurance levels exceeding 99.5 percent purity and real-time release testing protocols that disqualify legacy fermentation equipment.
- Veterinary Medicine:Poultry and livestock applications in emerging markets are absorbing API volumes displaced from EU feed additive restrictions, with Brazilian regulators tightening residue monitoring that favors certified suppliers.
- Agricultural Use:Soil amendment and crop protection applications face mounting environmental scrutiny from EPA and ECHA discharge rules.
- Research & Development:Antimicrobial resistance studies at academic institutions demand gram-scale lots with documented impurity spectra.
- Pharmaceutical Manufacturing:Finished dose producers in Ahmedabad and Vadodara clusters source fermentation intermediates for oral solid dosage export markets.
Human therapeutics commands the revenue concentration; veterinary medicine offers the steepest expansion trajectory.
Form:
Volume economics favor powder and crystalline formats that minimize cold chain burden across tropical distribution corridors.
- Powder:Bulk fermentation output for oral solid dosage manufacturing requires moisture-controlled packaging and validated stability testing that extends ANDA submission timelines for suppliers lacking in-house analytical teams.
- Crystalline:Purified salt forms for injectable formulations demand particle size distribution control that determines dissolution rates in compounding pharmacy reconstitution.
- Liquid:Aqueous suspensions for pediatric formulations require preservative validation against USP antimicrobial effectiveness testing.
- Granules:Intermediate processing for sustained-release tablet coatings.
- Suspension:Ready-to-use formulations for veterinary drench applications in Australian and New Zealand livestock markets.
Powder dominates procurement tonnage; crystalline formats gain share in hospital injectable channels.
End User:
Customer type determines contract structure, with contract manufacturing organizations demanding volume commitments that generic manufacturers avoid.
- Generic Drug Manufacturers:Sandoz Group and Aurobindo Pharma operate backward integration into sterile API production to secure supply for European hospital tenders, validating impurity profiles that exceed baseline pharmacopeial standards.
- Contract Manufacturing Organizations:Fermentation specialists in Hyderabad supply North American generic injectables markets through direct procurement relationships that bypass traditional pharmaceutical distribution intermediaries.
- Biopharmaceutical Companies:Novel antibiotic developers source specialized intermediates for combination therapy candidates targeting resistant pathogens.
- Research Institutions:University laboratories and government research centers purchase reference standards and analytical samples.
Generic drug manufacturers represent the largest demand pool; contract manufacturing organizations are expanding capacity planning control fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China controls over 80 percent of key penicillin G potassium salt capacity, concentrating supply risk for downstream formulators worldwide. India has narrowed the cost gap with Chinese suppliers while scaling fermentation clusters in Hyderabad and Ahmedabad. European hospital procurement alliances are tightening environmental and sterility specifications, reshaping qualified supplier pools.
China
Domestic fermentation capacity for beta-lactam intermediates supplies generic drug makers across emerging markets. The NMPA has tightened import registration requirements, forcing foreign API suppliers to establish local analytical testing partnerships or joint-venture filing agents. Zhejiang and Shandong provinces host concentrated penicillin bulk production corridors.
India
Hyderabad and Ahmedabad manufacturing clusters supply generic injectable markets in North America and Africa through CDSCO-inspected facilities. The PLI scheme for bulk drugs subsidizes greenfield fermentation capacity for critical starting materials, attracting contract manufacturing commitments from European generics firms. CDSCO's tightened facility audits are accelerating quality upgrades for US and EU supply eligibility.
United States
Hospital procurement of intravenous antibiotic formulations is expanding as antimicrobial stewardship programs tighten sterility assurance specifications. The FDA's quality-by-design mandates for active pharmaceutical ingredients raise compliance barriers for new API entrants. Generic injectable manufacturers source heavily from Indian fermentation clusters with validated impurity profiles.
Germany
Hospital purchasing cooperatives in German and French networks are unbundling API sourcing from finished dosage form contracts, creating direct procurement relationships with fermentation specialists. The EMA's REACH-aligned environmental discharge rules for fermentation effluents tighten volatile organic compound limits at manufacturing sites. Coastal facilities with existing wastewater treatment infrastructure are consolidating cephalosporin API production.
Brazil
Veterinary feed additive channels are absorbing API volumes displaced from EU sub-therapeutic restrictions, with Brazilian regulators tightening residue monitoring that favors certified suppliers. Poultry and livestock applications in emerging markets sustain demand for precision-dosed veterinary APIs. ANVISA oversight shapes import qualification for fermentation-derived intermediates.
Antibiotics API Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fermentation and biocatalysis niches. The market structures around three tiers: multinational generics houses with backward integration into sterile API production, mid-scale fermentation specialists serving contract manufacturing channels, and regional bulk suppliers competing on volume scale. Strategic moves center on enzymatic process licensing and coastal facility consolidation for REACH-compliant effluent treatment.
Within the integrated generics tier, Sandoz Group exemplifies backward integration into sterile API manufacturing to secure hospital supply contracts. Centrient Pharmaceuticals anchors the biocatalysis specialist position through enzymatic technology for cephalosporin synthesis. Aurobindo Pharma occupies the scale-driven archetype, operating multi-ton fermentation facilities that feed oral solid dosage export markets.
| Leading Market Players |
|---|
| Sandoz Group |
| Centrient Pharmaceuticals |
| Aurobindo Pharma |
| Fresenius Kabi |
| CordenPharma |
| ACS DOBFAR |
| DAEWOONG PHARMACEUTICAL |
| Parabolic Drugs |
| Penam Laboratories |
| Others |
Pricing and Supply Chain Analysis
Hyderabad's fermentation corridor concentrates penicillin and cephalosporin intermediate capacity, translating upstream scale into pricing leverage over North American generic injectable manufacturers who lack alternative qualified suppliers. CDSCO-inspected facilities in this cluster command premium contract terms from European hospital procurement alliances seeking REACH-compliant effluent treatment, while smaller Ahmedabad operators absorb margin compression from legacy equipment retrofit costs.
Pricing Analysis
ICH Q3D elemental impurity limits dictate the pricing tier structure across semi-synthetic cephalosporin lines, separating facilities with validated metal-mediated synthetic steps from those facing expensive process revalidation. Three-tier pricing structure across premium, standard, and economy levels reflects sterility assurance certification, with hospital formulary consolidation intensifying cost compression in the standard tier. Generic drug manufacturers exhibit highest price sensitivity due to procurement consolidation, while biopharmaceutical companies developing novel antibiotics show lowest sensitivity for specialized intermediates.
Supply Chain Analysis
Contract manufacturing organizations in Hyderabad and Ahmedabad control disproportionate shares of fermentation-based capacity planning for North American generic injectables markets. Raw material dependencies center on corn steep liquor and soybean meal for fermentation media, plus specialized enzyme catalysts for biocatalytic process steps. Single-source concentration in Chinese penicillin G potassium salt capacity exposes downstream formulators to geopolitical disruption risk. Distribution runs through direct procurement relationships that bypass traditional pharmaceutical distribution intermediaries, particularly visible in German and French hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Process optimization services and analytical method development support represent the fastest-expanding recurring-revenue layer, outpacing commodity fermentation output as FDA data integrity mandates extend ANDA submission timelines for API suppliers lacking in-house capabilities.
For Market Incumbents: Harden sterility assurance validation and real-time release testing protocols to defend against emerging enzymatic biocatalysis specialists capturing European hospital procurement share. Prioritize backward integration into critical starting materials through India's PLI-subsidized greenfield capacity, insulating margin pools from agricultural commodity input volatility. For New Entrants and Emerging Players: Mid-scale fermentation facilities with REACH-aligned environmental discharge capabilities in coastal Indian states represent the most penetrable entry point for European generics firms seeking qualified cephalosporin suppliers. Veterinary feed additive channels in Brazil and Southeast Asian poultry markets offer secondary white-space expansion as EU sub-therapeutic restrictions displace volumes. Lead with enzymatic biocatalysis technology licensing to collapse capital barriers against legacy chemical synthesis infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because hospital purchasing cooperative disintermediation concentrates volume commitment risk with fewer qualified fermentation operators. Target acquisition archetypes combine coastal wastewater treatment infrastructure with CDSCO-inspected quality systems. Monitor antimicrobial resistance policy shifts at WHO and national reimbursement levels as the signal for which API chemistries retain commercial viability against novel therapeutic alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Biocatalysis Licensing | Engineered hydrolases cut solvent consumption by half, lowering EMA-aligned environmental compliance costs for cephalosporin synthesis. |
| Coastal Facility Consolidation | REACH-compliant effluent treatment infrastructure at existing coastal sites absorbs 15-25 percent qualification cost uplift disadvantageing smaller operators. |
| PLI-Subsidized Capacity Expansion | India's production-linked incentive program attracts European generics contract manufacturing commitments for critical starting materials. |
| Direct Hospital Procurement Relationships | Bypassing traditional pharmaceutical distribution intermediaries compresses price discovery cycles and exposes API suppliers to volume commitment penalties. |
| Real-Time Analytical Technology Adoption | Process analytical technology investments satisfy FDA data integrity emphasis on forced degradation studies and accelerate ANDA submissions. |
Research Methodology
The analysis maps penicillin, cephalosporin, macrolide, tetracycline, and aminoglycoside API sub-sectors, each validated through fermentation plant managers, regulatory affairs leads at CDSCO-inspected facilities, hospital formulary directors, and generic drug procurement executives. Primary interview intelligence triangulates against FDA filings, EMA submissions, CDSCO inspection reports, and customs trade data for fermentation equipment and beta-lactam intermediate flows. Bottom-up capacity modeling and top-down demand estimation from hospital procurement databases converge across the analysis window.
Assumptions hold fixed the current regulatory inspection protocol divergence between FDA, EMA, and CDSCO, while varying antimicrobial resistance policy stringency and agricultural commodity input price trajectories. Segmentation dimensions span molecular class, sterility assurance tier, administration route, and regional regulatory cluster. CAGRs derive from facility capacity utilization rates and hospital formulary adoption curves for azithromycin alternatives. Forecast inputs incorporate enzymatic biocatalysis technology transfer velocity and REACH-aligned effluent treatment capital deployment timing.
Practitioners should monitor CDSCO audit frequency escalation, NMPA import registration requirement tightening, and WHO antimicrobial resistance guideline revisions for early signals of supply eligibility disruption or reimbursement compression. Quarterly review of corn steep liquor price indices, European hospital procurement alliance tender volumes, and FDA warning letter issuance patterns for data integrity violations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Vitamins and Derivatives Market
Pharmaceutical Ingredients
Calcium Gluconate Market
Pharmaceutical Ingredients
Scopolamine Market
Pharmaceutical Ingredients
Synthetic Lethality-Based Drugs and Targets Market
Pharmaceutical Ingredients
Pharmaceutical Hot Melt Extrusion Market
Pharmaceutical Ingredients
India Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Pharmaceutical Grade Magnesium Hydroxide Market
Pharmaceutical Ingredients
Cetrorelix Acetate API Market
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
Small Molecule Drug Discovery Market
Pharmaceutical Ingredients
Originator Small Molecule Drug Market
Pharmaceutical Ingredients
Global Pharmaceutical Grade Silica Gel Market
Pharmaceutical Ingredients
Oridonin Market
Pharmaceutical Ingredients
Lipids Active Pharmaceutical Ingredient Market
Pharmaceutical Ingredients
Pharmaceutical Desiccants Market
Pharmaceutical Ingredients
Oral Doxycycline Hyclate Market