
 Sennosides Market | 2026-2036
Sennosides Market Size, Share, and Industry Trends Forecast 2026-2036
Sennosides Market Analytics
A capital-intensity divergence between integrated botanical extractors and contract manufacturers is bifurcating competitive dynamics in sennosides. Himalaya Drug Company leverages captive cultivation of Cassia angustifolia across Indian agro-climatic zones to secure raw material sovereignty. Alchem International anchors its position through dedicated extraction infrastructure serving European pharmacopeial markets. Boehringer Ingelheim Pharmaceuticals competes via GMP-certified synthetic sennoside capacity aligned with prescription laxative channels.
Sennosides comprise hydroxyanthracene glycosides extracted primarily from Cassia angustifolia and Cassia acutifolia senna leaves, functioning as stimulant laxatives through colonic motility activation via prostaglandin-mediated water and electrolyte secretion. Natural sennosides dominate volume throughput due to entrenched consumer preference for botanical-origin digestive aids across Asian and European markets. Synthetic sennosides capture premium pricing in pharmaceutical-grade tablet formulations where batch-to-batch consistency exceeds pharmacopeial thresholds. The dietary supplement application segment sustains above-average growth as direct-to-consumer powder and capsule formats expand through online retail channels.
USP monograph specifications and European Pharmacopoeia (EP) identity assays govern sennoside content verification for pharmaceutical-grade products, while FDA dietary supplement cGMP rules enforce manufacturing controls across U.S.-distributed botanical laxatives. India's CDSCO and AYUSH ministry jointly regulate sennoside-containing formulations under dual-track pharmaceutical and traditional medicine frameworks. Stakeholders must monitor evolving pharmacopeial limits on anthraquinone impurities and adapt sourcing strategies as climate variability threatens Indian senna leaf yields.
Market Dynamics
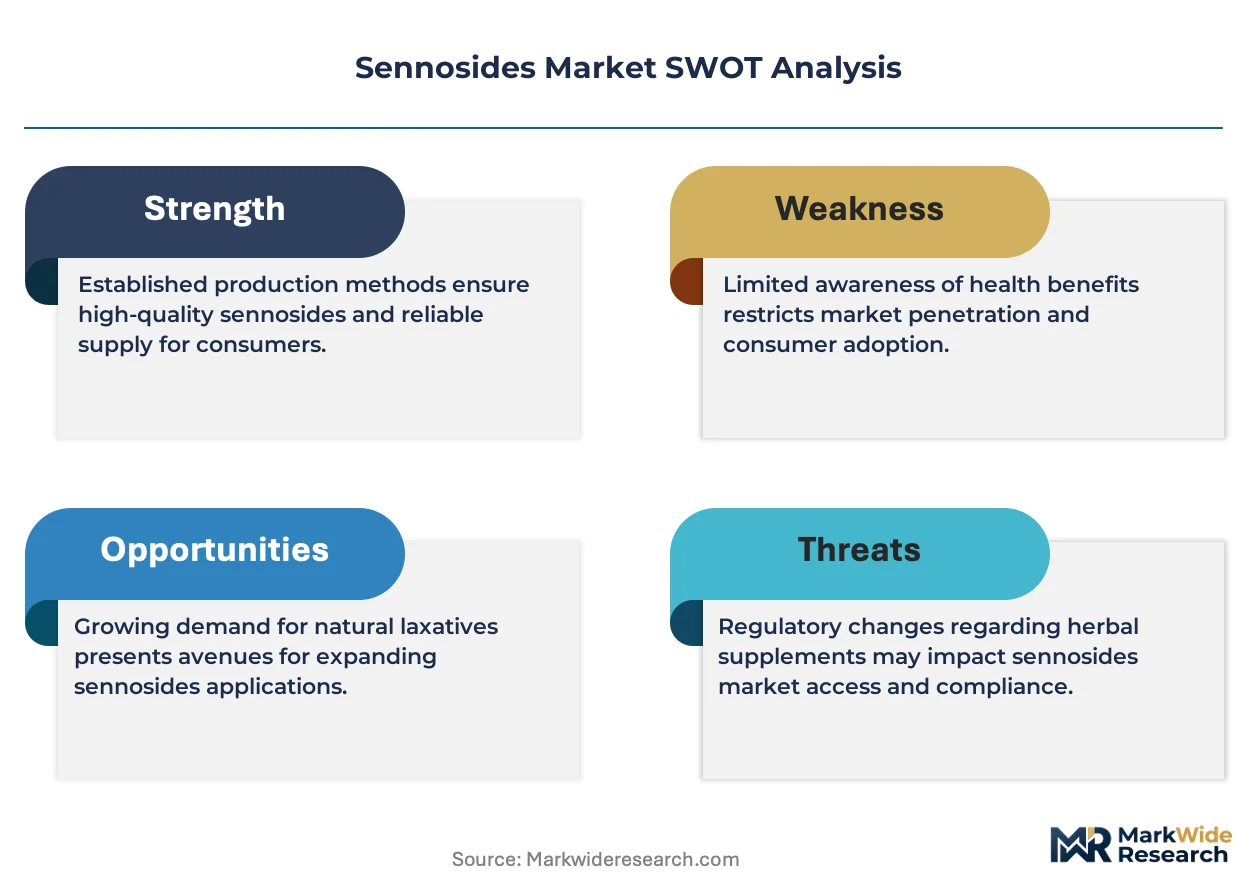
Pharmacopeial tightening on anthraquinone impurity limits is compressing supplier margins while rewarding batch-certified producers, creating a bifurcation between commodity-grade botanical extractors and pharmaceutical-grade compounders.
Growth Catalysts
- Dietary supplement channel expansion:Direct-to-consumer capsule and powder formats through e-commerce platforms are pulling volume from traditional pharmacy retail, with India's AYUSH ministry streamlining botanical laxative registration pathways.
- USP monograph alignment:Pharmaceutical compounders upgrading to United States Pharmacopeia sennoside A+B assay specifications are securing preferred supplier status with hospital procurement networks.
- Captive cultivation scaling:Integrated producers controlling Cassia angustifolia farming across Rajasthan and Gujarat agro-zones are insulating raw material costs from monsoon yield volatility.
Market Restraints
- Indian monsoon dependency:Rainfall variability across Thar Desert cultivation belts threatens leaf harvest volumes and sennoside concentration consistency.
- European Pharmacopoeia identity testing:EP sennoside reference standard compliance adds 12-18 month certification timelines for new market entrants.
- Polyethylene glycol substitution:Osmotic laxatives are capturing prescription channel volume where clinicians prioritize predictable onset timing over botanical origin.
Strategic Opportunities
- German pharmacy channel:Underpenetrated positioning in Apotheken-verteilt botanical digestive aids offers premium pricing capture versus supermarket supplement aisles.
- Sustained-release formulation technology:Converging hydroxypropyl methylcellulose matrix systems with sennoside glycosides enables overnight-action positioning against immediate-release competitors.
- Japan PMDA botanical drug pathway:The Ministry of Health, Labour and Welfare's simplified Kampo-derived laxative approval framework rewards standardized extract documentation.
Industry Challenges
- Analytical chemist scarcity:Qualified personnel capable of high-performance liquid chromatography sennoside quantification against pharmacopeial reference standards command premium compensation in Ahmedabad and Hyderabad extraction clusters.
- Dual-track compliance complexity:India's CDSCO pharmaceutical licensing and AYUSH traditional medicine registration require parallel documentation systems for identical active ingredients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sennosides Market |
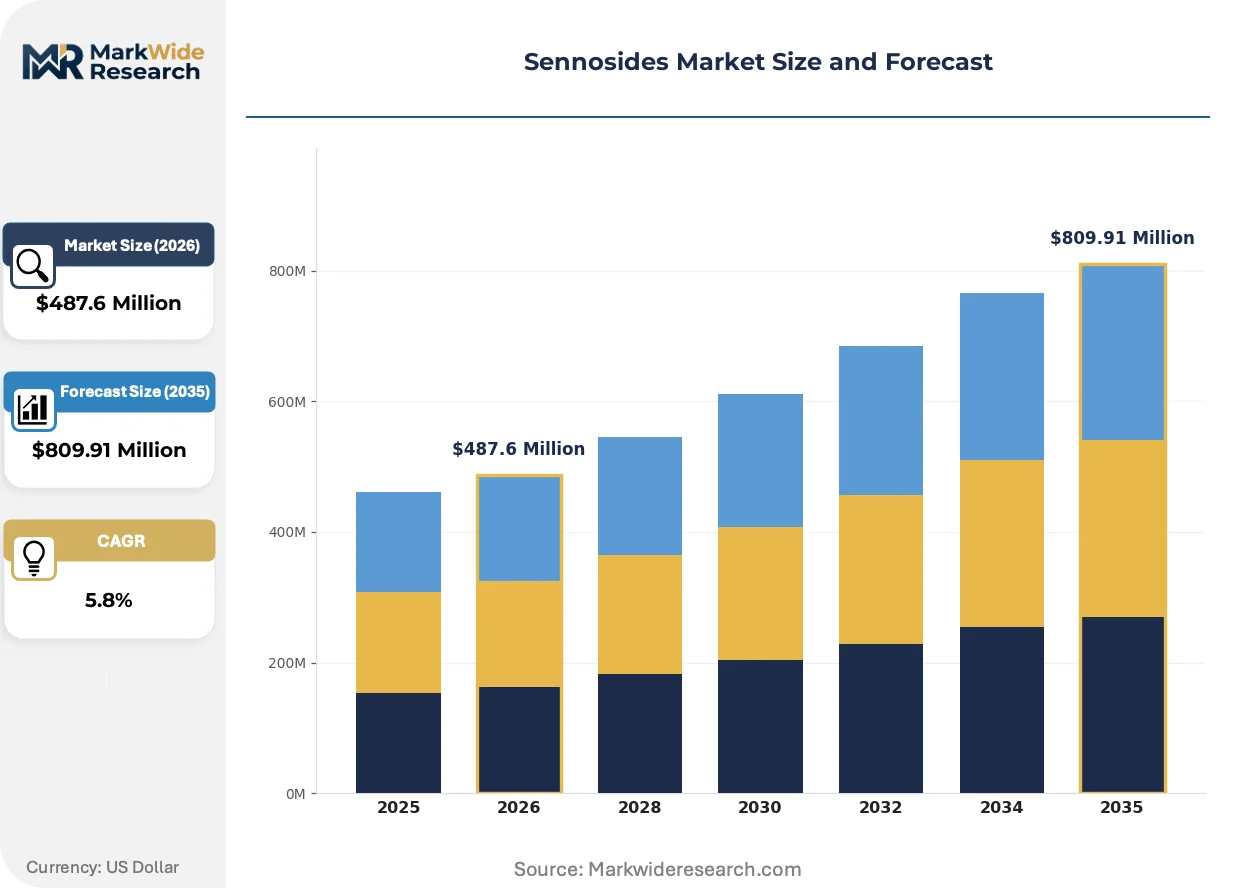
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Sennosides, Synthetic Sennosides, Herbal Extracts, Pharmaceutical Grade Application: Laxative, Digestive Aid, Weight Management, Dietary Supplement End User: Pharmacies, Hospitals, Health Stores, Online Retailers Form: Tablets, Capsules, Liquid, Powder |
| Companies Covered | Herbalife Nutrition, NOW Foods, Nature's Way, Swanson Health Products, Solgar, Himalaya Drug Company, Boehringer Ingelheim Pharmaceuticals, Alchem International, Phytex Australia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sennosides Market Evolving Landscape
Continuous processing technology and spectroscopic real-time release testing are compressing batch cycle times while pharmacopeial digitization and direct-to-consumer channel expansion are rewriting competitive positioning rules.
Supercritical carbon dioxide extraction is displacing traditional ethanol maceration methods in pharmaceutical-grade sennoside production. European contract manufacturers serving EMA-regulated markets are adopting these systems to achieve sub-50 ppm residual solvent specifications. This displacement is compressing capacity utilization at solvent-based extraction facilities unable to fund equipment upgrades.
REACH registration requirements for anthraquinone derivatives are tightening substance volume tracking across European supply chains. ECHA's updated classification guidance now triggers downstream user notification obligations for sennoside concentrations above specified thresholds. German and French formulators are responding by segregating pharmaceutical and cosmetic-grade production lines to prevent cross-contamination liability.
Subscription-based replenishment models are capturing recurring revenue from chronic constipation management consumers. Direct-to-consumer brands bypassing pharmacy intermediaries now account for expanding volume share in North American and Western European markets. California and London metropolitan areas exhibit highest adoption of automated monthly delivery for standardized sennoside doses.
Sennosides Market Segmentation
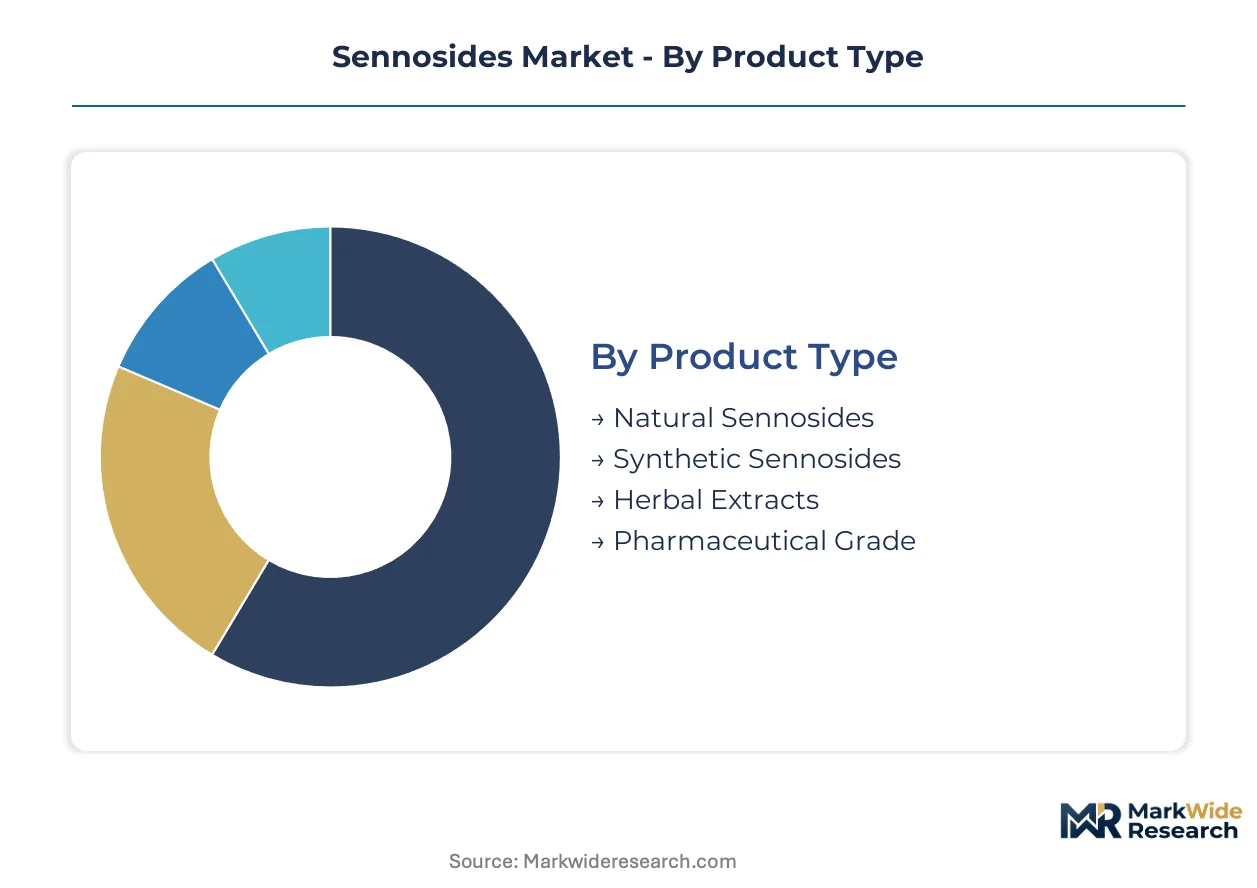
Sennoside product differentiation tracks pharmacopeial certification tiers rather than functional performance, with margin pools concentrating in pharmaceutical-grade and sustained-release formats. Segmentation strategy must account for dual regulatory pathways in India and divergent purity standards between USP-aligned and AYUSH-registered channels.
Product Type:
Margin pools concentrate in synthetic and pharmaceutical-grade segments where batch certification commands premium pricing over commodity botanical extracts.
- Natural Sennosides:Hydroxyanthracene glycosides extracted from Cassia angustifolia and Cassia acutifolia senna leaves through ethanol maceration or supercritical CO2 methods. Demand concentrates in India's AYUSH-registered formulations and European botanical supplement channels where consumer preference for plant-origin digestive aids persists despite variable sennoside A+B ratios.
- Synthetic Sennosides:Chemically synthesized hydroxyanthracene derivatives with precise stereochemical control over sennoside A and B epimers. Hospital procurement networks in Germany and Japan prioritize this segment for prescription laxative formulations where pharmacopeial assay consistency exceeds 98%.
- Herbal Extracts:Standardized senna leaf preparations with specified total hydroxyanthracene glycoside content but variable individual sennoside ratios.
- Pharmaceutical Grade:USP monograph-compliant material with documented impurity profiles for anthraquinone derivatives and residual solvents.
Natural sennosides hold installed capacity across Rajasthan and Gujarat cultivation belts. Synthetic sennosides are rotating up the share rankings as European EMA-regulated formulators prioritize batch consistency.
Application:
Volume throughput clusters in laxative formulations while dietary supplement applications are gaining share fastest through direct-to-consumer channel expansion.
- Laxative:Stimulant cathartic action through colonic prostaglandin-mediated water and electrolyte secretion, with onset typically 6-12 hours post-ingestion. Hospital formularies in Mumbai and Delhi maintain procurement contracts for standardized sennoside tablets, though polyethylene glycol osmotic alternatives are capturing prescription volume where clinicians prioritize predictable timing.
- Digestive Aid:Functional positioning for occasional constipation relief in non-pathological populations, often combined with fiber or probiotic co-formulations.
- Weight Management:Adjunct use for temporary water weight reduction through purgative action, subject to regulatory scrutiny from FDA and EFSA for unsubstantiated metabolic claims.
- Dietary Supplement:Direct-to-consumer capsule and powder formats bypassing pharmacy intermediaries, with California and London metropolitan areas exhibiting highest automated replenishment adoption for standardized daily doses.
Laxative applications hold installed capacity in institutional procurement networks. Dietary supplements are climbing the fastest as e-commerce subscription models capture recurring revenue from chronic constipation management consumers.
End User:
Channel margins compress from hospital procurement downward through health stores to online retailers, with pricing power inversely correlated with buyer concentration.
- Pharmacies:German Apotheken and Indian retail pharmacy chains dispense prescription and over-the-counter sennoside tablets under pharmacist supervision, with USP-certified products commanding shelf placement premiums.
- Hospitals:Centralized purchasing departments in tertiary care facilities negotiate multi-year supply agreements for pharmaceutical-grade sennoside formulations, prioritizing batch documentation and pharmacopeial compliance over unit cost.
- Health Stores:Specialized retailers in Western European markets curate botanical digestive aid assortments, with Swiss and Austrian outlets showing particular preference for organic-certified senna leaf provenance.
- Online Retailers:Direct-to-consumer platforms aggregate fragmented demand for capsule and powder formats, with fulfillment infrastructure in Ahmedabad and Hyderabad serving domestic and export markets.
Hospital procurement holds installed capacity in pharmaceutical-grade throughput. Online retailers are expanding most quickly as subscription-based replenishment models bypass traditional pharmacy intermediaries.
Form:
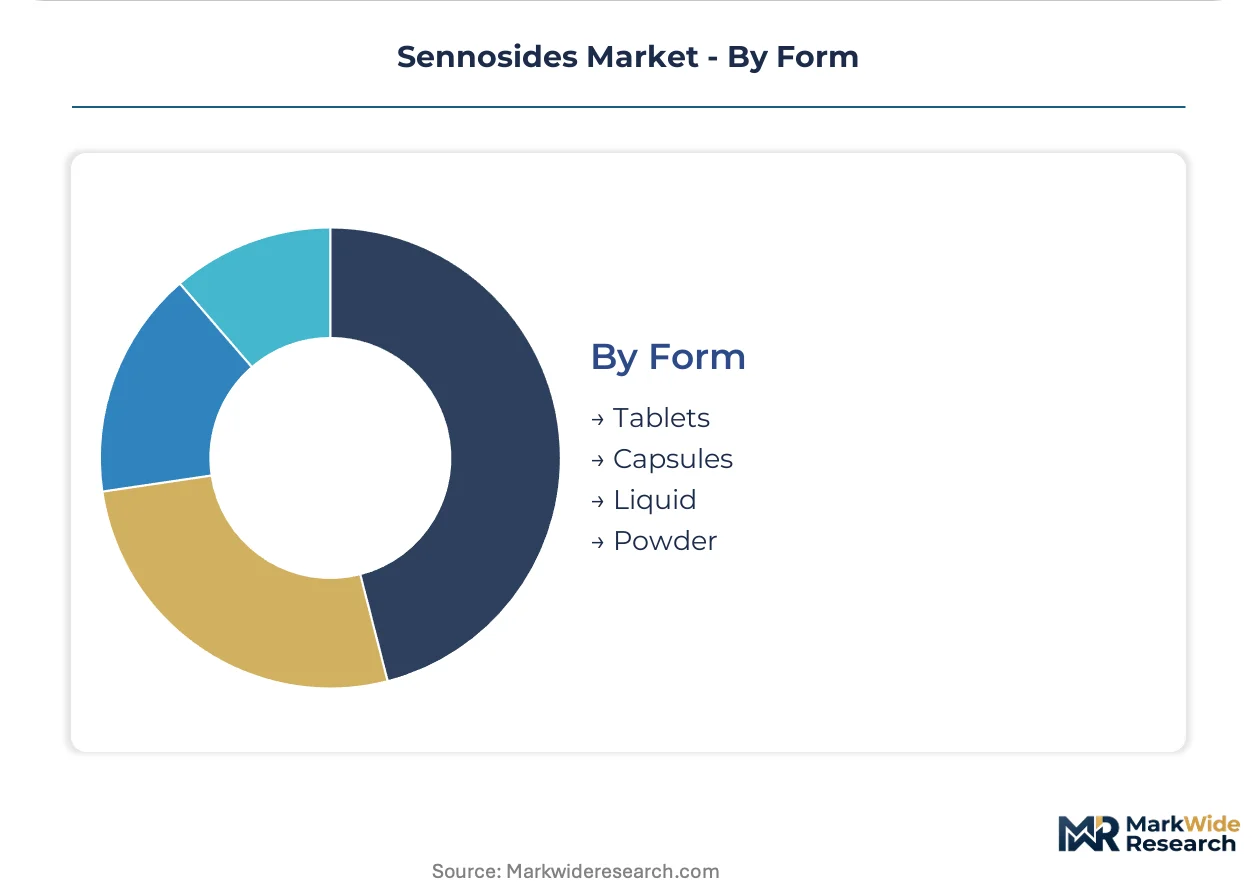
Manufacturing complexity and finished goods margins escalate from powder through liquid to capsule and tablet formats, with excipient selection driving differentiation in sustained-release positioning.
- Tablets:Compressed dosage forms with hydroxypropyl methylcellulose matrix systems enabling overnight-action positioning against immediate-release competitors, predominant in German and Japanese prescription channels.
- Capsules:Gelatin or vegetable-derived shells containing sennoside powder or granules, preferred in North American dietary supplement markets for swallowability and dose flexibility.
- Liquid:Aqueous or hydroalcoholic extracts with standardized glycoside concentration, common in pediatric and geriatric populations where solid dosage form administration presents challenges.
- Powder:Bulk botanical material or standardized extract for compounding pharmacies and consumer-measured dosing, with lowest per-unit margins but highest volume throughput in Indian traditional medicine channels.
Tablet formulations hold installed capacity in pharmaceutical-grade production infrastructure. Capsules are rotating up the share rankings as direct-to-consumer brands prioritize convenience and dose standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Indian buyers prioritize cost-effective AYUSH-registered formulations, while German hospital procurement networks absorb premium pricing for pharmacopeial-certified material.
United States
Direct-to-consumer subscription models capture recurring revenue from chronic constipation management consumers in California and metropolitan New York. FDA dietary supplement cGMP rules enforce manufacturing controls across botanical laxative distribution channels. Extraction infrastructure in the Northeast serves domestic formulation demand while importing standardized sennoside APIs from Indian suppliers.
Germany
Apotheken-dispensed botanical digestive aids command shelf placement premiums over supermarket supplement aisles. EMA pharmacopeial standards and REACH registration requirements for anthraquinone derivatives tighten substance volume tracking across supply chains. Contract manufacturers in Bavaria adopt supercritical carbon dioxide extraction systems to achieve sub-50 ppm residual solvent specifications for EMA-regulated markets.
India
AYUSH ministry streamlining of botanical laxative registration pathways accelerates domestic formulation approvals. CDSCO pharmaceutical licensing and AYUSH traditional medicine registration operate dual-track compliance frameworks for identical active ingredients. Captive Cassia angustifolia cultivation across Rajasthan and Gujarat agro-zones insulates raw material costs from monsoon yield volatility.
Japan
Hospital procurement networks prioritize synthetic sennoside formulations where pharmacopeial assay consistency exceeds 98%. PMDA's simplified Kampo-derived laxative approval framework rewards standardized extract documentation for traditional medicine positioning. Pharmaceutical compounders in the Kanto region align production with prescription channel demand for predictable onset timing.
United Kingdom
Health stores in London and the Southeast curate botanical digestive aid assortments with preference for organic-certified senna leaf provenance. MHRA enforcement of EU-retained pharmacopeial standards governs sennoside content verification for pharmaceutical-grade products. Online retail fulfillment infrastructure aggregates fragmented demand for capsule and powder formats bypassing traditional pharmacy intermediaries.
Sennosides Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the sennosides market. Integrated botanical extractors with captive cultivation assets compete against contract manufacturers serving pharmacopeial markets and synthetic producers aligned with prescription channels. Three archetypes dominate: backward-integrated Indian cultivator-extractors, European GMP-certified compounders, and pharmaceutical-grade synthetic specialists. Capacity expansion in supercritical extraction infrastructure and geographic licensing partnerships represent the primary competitive moves reshaping positioning.
Among India-based integrated producers, Himalaya Drug Company exemplifies the cultivator-extractor archetype through captive farming operations. Alchem International occupies a position within the European contract manufacturing tier serving pharmacopeial markets. Boehringer Ingelheim Pharmaceuticals anchors the synthetic specialization segment aligned with hospital procurement networks.
| Leading Market Players |
|---|
| Herbalife Nutrition |
| NOW Foods |
| Nature's Way |
| Swanson Health Products |
| Solgar |
| Himalaya Drug Company |
| Boehringer Ingelheim Pharmaceuticals |
| Alchem International |
| Phytex Australia |
| Others |
Value Network & Pricing Analysis
Capacity utilization at supercritical CO2 extraction facilities in Bavaria and Gujarat creates scale economies that compress unit costs for pharmaceutical-grade sennoside batches while elevating price floors for ethanol-based competitors unable to fund equipment upgrades. This scale bifurcation concentrates margin pools among integrated producers with captive cultivation assets, forcing commodity-grade botanical extractors toward cost-plus contracting or exit.
Pricing Analysis
Subscription-based replenishment models for direct-to-consumer sennoside capsules generate lifetime value exceeding transactional pharmacy purchases through automated monthly delivery retention. Three-tier pricing structure across pharmaceutical-grade, AYUSH-registered, and commodity botanical tiers reflects USP certification premiums and batch documentation depth. Cost compression in commodity extracts is intensifying because Indian monsoon variability forces spot-market leaf sourcing. Hospital procurement networks in Germany and Japan absorb the highest premiums, while Indian traditional medicine channels exhibit extreme price sensitivity.
Supply Chain Analysis
Container availability constraints on India-Europe trade lanes elevate inbound logistics costs for standardized sennoside APIs destined for EMA-regulated formulators. Supply concentrates in India, Germany, and Japan, with Rajasthan and Gujarat cultivation belts feeding extraction clusters in Ahmedabad and Hyderabad. Raw material dependencies center on Cassia angustifolia leaf harvests, supercritical CO2 equipment, and USP reference standards. Single-source vulnerability from Indian monsoon dependency threatens annual volume planning. Distribution runs through hospital procurement networks, Apotheken dispensaries, and direct-to-consumer fulfillment platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sennosides market is recovering from cyclical pressure as pharmacopeial tightening and climate volatility force supplier consolidation. Indian monsoon variability and USP certification upgrades represent the cyclical drivers compressing marginal capacity.
For Market Incumbents: Secure backward integration into captive Cassia angustifolia cultivation across Rajasthan and Gujarat to insulate raw material costs from monsoon yield volatility. Invest in supercritical CO2 extraction capacity to meet EMA sub-50 ppm residual solvent specifications and defend against polyethylene glycol substitution in prescription channels. For New Entrants and Emerging Players: Lead with sustained-release tablet formulations targeting German Apotheken channels where underpenetrated positioning offers premium pricing capture versus supermarket supplement aisles. Prioritize USP monograph alignment and pharmacopeial reference standard certification to secure hospital procurement network access. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription brands with automated replenishment infrastructure in California and London metropolitan areas. Long-term viability over the next decade favors acquisition targets with dual-track CDSCO-AYUSH compliance capabilities and supercritical extraction assets. The signal to watch is EP certification timeline compression for new market entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Cultivation Scaling | Backward integration into Rajasthan and Gujarat agro-zones insulates raw material costs from monsoon volatility. |
| Supercritical CO2 Extraction Adoption | Equipment upgrades enable sub-50 ppm residual solvent compliance for EMA-regulated European markets. |
| USP Monograph Alignment | Batch certification secures preferred supplier status with hospital procurement networks in Germany and Japan. |
| Sustained-Release Formulation Development | Hydroxypropyl methylcellulose matrix systems enable overnight-action positioning against immediate-release competitors. |
| Direct-to-Consumer Channel Expansion | Subscription-based replenishment models capture recurring revenue from chronic constipation management consumers. |
Research Methodology
A spread of perspectives from extraction facility managers, CDSCO regulatory affairs officers, hospital procurement directors, and AYUSH formulation specialists converged on the working assumptions. Primary interviews combined with secondary validation against USP monograph databases, EP reference standard specifications, FDA dietary supplement cGMP guidance, and Indian customs trade data. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Segmentation dimensions modeled include product type tier, application channel, pharmacopeial certification grade, and regional regulatory cluster across the projection horizon. CAGRs derived from slope analysis of historical price-volume relationships and forward capacity expansion announcements. Forecast inputs incorporated monsoon yield variability scenarios and EP certification timeline distributions.
The analysis sits within stated boundaries; outcomes outside sustained pharmacopeial tightening or abrupt climate regime shifts would require recalibration. Forecasts reflect documented assumptions on substitution elasticity and channel migration rates. Recalibration cycles align with material shifts in USP monograph revisions and Indian AYUSH ministry registration pathway changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Pharmaceutical Propellants Market
Pharmaceutical Ingredients
Cyprosin Market
Pharmaceutical Ingredients
Small-Molecule Injectable Market
Pharmaceutical Ingredients
Pharmaceutical Grade Amino Acid Market
Pharmaceutical Ingredients
Synthetic Lethality-Based Drugs and Targets Market
Pharmaceutical Ingredients
Biologic Excipients Market
Pharmaceutical Ingredients
Anti-Allergic Agent Ingredients Market
Pharmaceutical Ingredients
Oral Doxycycline Hyclate Market
Pharmaceutical Ingredients
Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market
Pharmaceutical Ingredients
Pharmaceutical Grade Hyaluronic Acid Market
Pharmaceutical Ingredients
Oxycodone Drugs Market
Pharmaceutical Ingredients
Alpha Lipoic Acid API Market
Pharmaceutical Ingredients
Nuclear Export Inhibitor Drugs Market
Pharmaceutical Ingredients
Pharmaceutical Desiccants Market
Pharmaceutical Ingredients
Sulphonamides Market