
 Furosemide Market | 2026-2036
Furosemide Market Size, Share, and Industry Trends Forecast 2026-2036
Furosemide Market Analysis
The manufacturing scale gap between large-volume generic producers and niche formulation specialists is bifurcating competitive economics in furosemide supply. Teva Pharmaceutical Industries leverages vertical integration across API synthesis and finished dosage to sustain cost leadership in oral tablet volumes. Sandoz International GmbH anchors its position through European regulatory dossier depth and hospital channel control. Hikma Pharmaceuticals PLC competes via injectable specialization and acute-care distribution networks in North American markets.
Furosemide is a sulfonamide-derived loop diuretic that inhibits the Na-K-2Cl cotransporter in the thick ascending limb of the loop of Henle, producing rapid diuresis with a bioavailability of 10-90% for oral formulations and near-complete bioavailability for intravenous delivery. The compound serves as first-line therapy for edema associated with heart failure, hepatic cirrhosis, and renal impairment, as well as for acute and chronic hypertension management. Injectable furosemide leads hospital revenue pools due to perioperative and critical-care dependency, while oral tablets dominate outpatient prescription volumes across long-term care and homecare settings. Application demand in heart failure is expanding fastest as aging demographics and reduced ejection fraction diagnoses multiply, whereas the renal disorders segment remains mature with slower volume growth.
FDA bioequivalence requirements and EMA dissolution standards constrain generic approval pathways and filter substandard manufacturers from supply chains. The USP monograph for furosemide tablets and the ICH Q3D guideline on elemental impurities further elevate quality compliance costs for market participants. Stakeholders must monitor evolving pharmacopeial standards and API sourcing transparency as regulators intensify supply chain integrity scrutiny.
Market Dynamics
Hospital procurement consolidation is compressing supplier margins while elevating batch-traceability requirements for injectable furosemide across acute-care networks. This structural force is filtering regional manufacturers from tender participation and rewarding vertically integrated producers with captive API supply.
Growth Catalysts
- Heart failure protocol standardization:Cardiology societies in the United States, Germany, and Japan are embedding loop diuretics into reduced ejection fraction treatment pathways, expanding recurring prescription volumes in outpatient settings.
- EMA tightened bioequivalence:The European Medicines Agency's refined dissolution specifications for generic furosemide are accelerating quality upgrades among contract manufacturers seeking European hospital access.
- India's API localization push:The country's Production Linked Incentive scheme for bulk drugs is attracting fermentation and synthetic chemistry investment that reduces import dependency for furosemide starting materials.
Market Restraints
- Starting material concentration:4-chloro-5-sulfamoylanthranilic acid supply concentrates among Chinese specialty chemical producers, exposing formulation plants to geopolitical freight disruptions and customs delays.
- Substitution by SGLT2 inhibitors:Dapagliflozin and empagliflozin are capturing maintenance diuretic volumes in stable heart failure patients with preserved renal function, constraining furosemide's chronic-use expansion.
- USP monograph compliance costs:The United States Pharmacopeia's elemental impurity limits under ICH Q3D mandate inductively coupled plasma testing that elevates per-batch analytical overhead for oral tablet producers.
Strategic Opportunities
- Home infusion expansion:Post-acute care networks in the United States are deploying ambulatory infusion pumps for heart failure decompensation, creating demand for preservative-free furosemide vials outside hospital walls.
- Fixed-dose combinations:Co-formulation with potassium-sparing agents addresses electrolyte monitoring burden and could capture polypharmacy patients in European long-term care facilities.
- Continuous manufacturing transition:FDA's emerging guidance on real-time release testing enables direct compression workflows that compress batch cycle times and reduce working capital intensity for high-volume oral products.
Industry Challenges
- Qualified analytical chemist scarcity:Dissolution method development and forced degradation studies require specialists familiar with sulfonamide stability profiles that academic programs rarely emphasize.
- Multi-site inspection coordination:Simultaneous FDA and EMA audits of API and finished dosage facilities demand documentation harmonization across quality management systems that were designed for single-authority compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Furosemide Market |
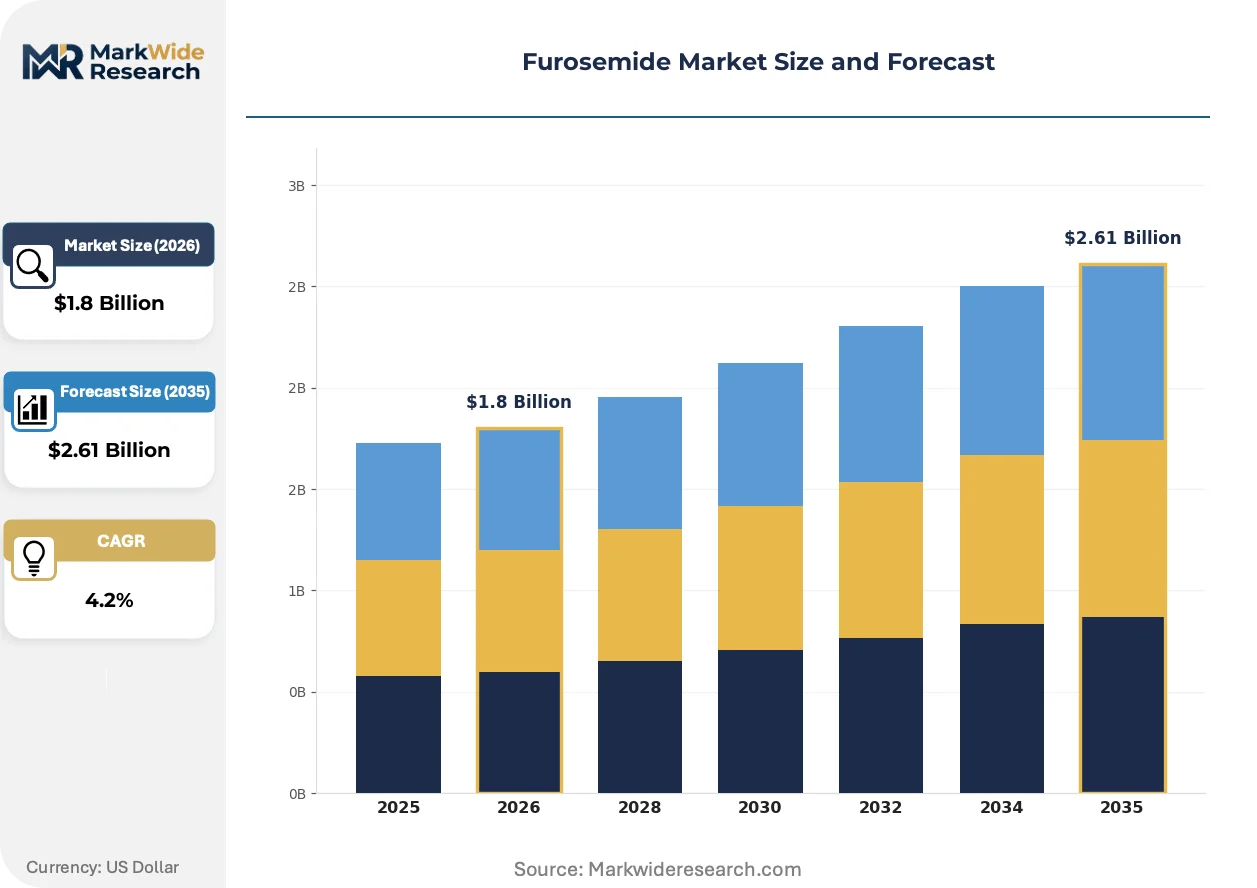
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Oral Tablets, Oral Solution, Powder End User: Hospitals, Clinics, Homecare, Long-term Care Facilities Application: Edema, Hypertension, Heart Failure, Renal Disorders Delivery Mode: Intravenous, Oral, Intramuscular, Subcutaneous |
| Companies Covered | Teva Pharmaceutical Industries Ltd., Sandoz International GmbH, Pfizer Inc., Fresenius Kabi AG, Sun Pharmaceutical Industries Ltd., Sanofi, Mylan N.V., Hikma Pharmaceuticals PLC, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Furosemide Market Emerging Trajectories
Formulation science and supply chain transparency are converging to redefine competitive advantage in loop diuretic manufacturing. Three developments are altering how producers capture value.
Ready-to-use bag formulations are supplanting traditional vial-and-diluent workflows in perioperative settings. Anesthesiology departments at tertiary hospitals in Germany and the United States are adopting these unit-dose presentations to reduce compounding error risk and pharmacy labor allocation. This shift is compressing margin contribution from standard vial presentations while rewarding sterile fill-finish capabilities that smaller generic houses cannot replicate.
REACH authorization requirements for residual solvents in European pharmaceutical manufacturing are elevating environmental compliance investment. The European Chemicals Agency's tightened thresholds for N,N-dimethylformamide and acetonitrile recovery are forcing API producers to install closed-loop solvent recovery systems or exit the European supply base. Oral tablet manufacturers sourcing from non-European API sites are absorbing third-party audit costs to demonstrate supply chain integrity under the EU Green Deal's pharmaceutical sector guidance.
Consolidated purchasing through group purchasing organizations is concentrating contract negotiation leverage among three dominant hospital networks in the United States. These entities are unbundling traditional distributor markup by negotiating direct manufacturer agreements with quarterly volume commitments and penalty clauses for stockout events. The Southwest and Midwest hospital systems are most advanced in this transition, with procurement teams demanding electronic data interchange integration for real-time inventory visibility.
Furosemide Market Segmentation
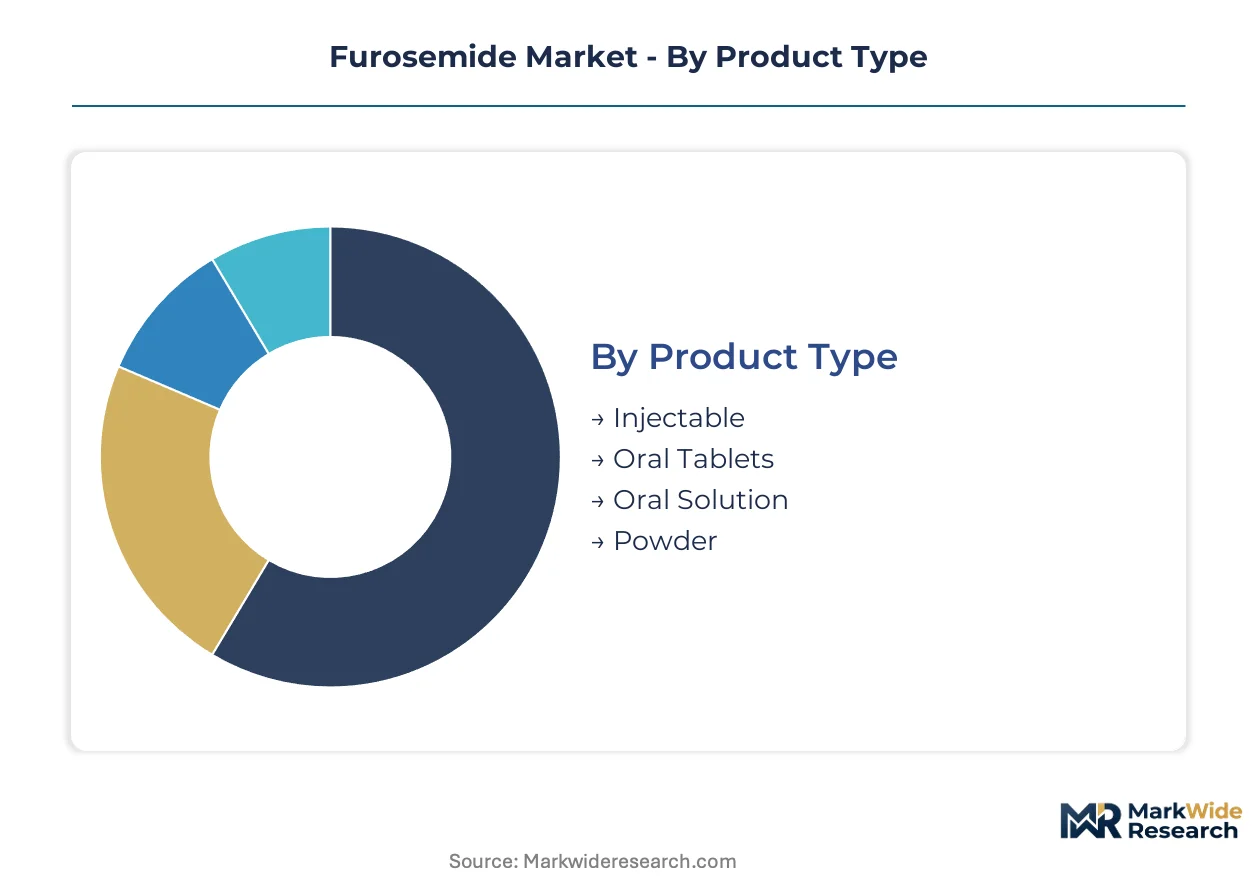
Furosemide's therapeutic versatility fragments demand across acute and chronic care pathways. Each segment carries distinct regulatory, reimbursement, and supply chain requirements that shape competitive positioning.
Product Type:
Hospital procurement channels favor sterile formulations, while retail pharmacies handle ambulatory prescriptions for chronic conditions.
- Injectable:Aqueous solutions in ampoules and vials deliver rapid diuresis for critical-care settings. German and US tertiary hospitals are standardizing ready-to-use bag presentations to reduce compounding labor and medication error risk.
- Oral Tablets:Scored tablets in 20mg, 40mg, and 80mg strengths dominate outpatient volume for maintenance therapy. The United States, Germany, and India concentrate prescription demand as heart failure protocols embed loop diuretics into reduced ejection fraction pathways.
- Oral Solution:Liquid formulations serve pediatric populations and dysphagic patients unable to swallow solid dosage forms. Long-term care facilities in North America specify unit-dose cups to simplify administration tracking.
- Powder:Bulk active pharmaceutical ingredient for extemporaneous compounding and institutional manufacturing. Compounding pharmacies in hospital systems source this grade for patient-specific dosing requirements.
Oral tablets dominate installed base. Injectable formulations are where expansion concentrates.
End User:
Procurement authority and reimbursement mechanisms differ sharply across settings, creating four distinct customer archetypes with divergent price sensitivities and quality requirements.
- Hospitals:Acute-care networks negotiate consolidated contracts through group purchasing organizations. The Southwest and Midwest hospital systems in the United States are unbundling distributor markups through direct manufacturer agreements with real-time inventory visibility requirements.
- Clinics:Outpatient cardiology and nephrology practices prescribe maintenance therapy with quarterly monitoring protocols. German specialist clinics adhere to EMA bioequivalence standards that filter substandard generic suppliers from tender participation.
- Homecare:Post-acute infusion services deploy ambulatory pumps for heart failure decompensation. US home health agencies are driving demand for preservative-free furosemide vials outside traditional hospital walls.
- Long-term Care Facilities:Nursing homes manage polypharmacy in elderly populations with renal impairment. European facilities show interest in fixed-dose combinations with potassium-sparing agents to reduce electrolyte monitoring burden.
Hospitals command the largest revenue pool per patient episode. Homecare is climbing the fastest as post-acute networks expand.
Application:
Disease severity and treatment duration determine whether therapy initiates in inpatient or outpatient channels.
- Edema:Peripheral and pulmonary fluid accumulation drives acute hospital admissions. Cirrhotic patients in US tertiary centers require aggressive diuresis with careful electrolyte monitoring.
- Hypertension:Resistant hypertension cases supplement ACE inhibitors and calcium channel blockers. Outpatient prescribing in Germany and Japan follows stepped-care algorithms that reserve loop diuretics for refractory cases.
- Heart Failure:Reduced ejection fraction protocols embed furosemide as first-line decongestive therapy. Aging demographics and improved diagnostic rates are multiplying prescription volumes across outpatient settings.
- Renal Disorders:Chronic kidney disease and nephrotic syndrome require dose-adjusted therapy with creatinine clearance monitoring. This segment shows mature volume growth as patient populations stabilize.
Heart failure applications are gaining share fastest. Renal disorders retain the deepest clinical experience base.
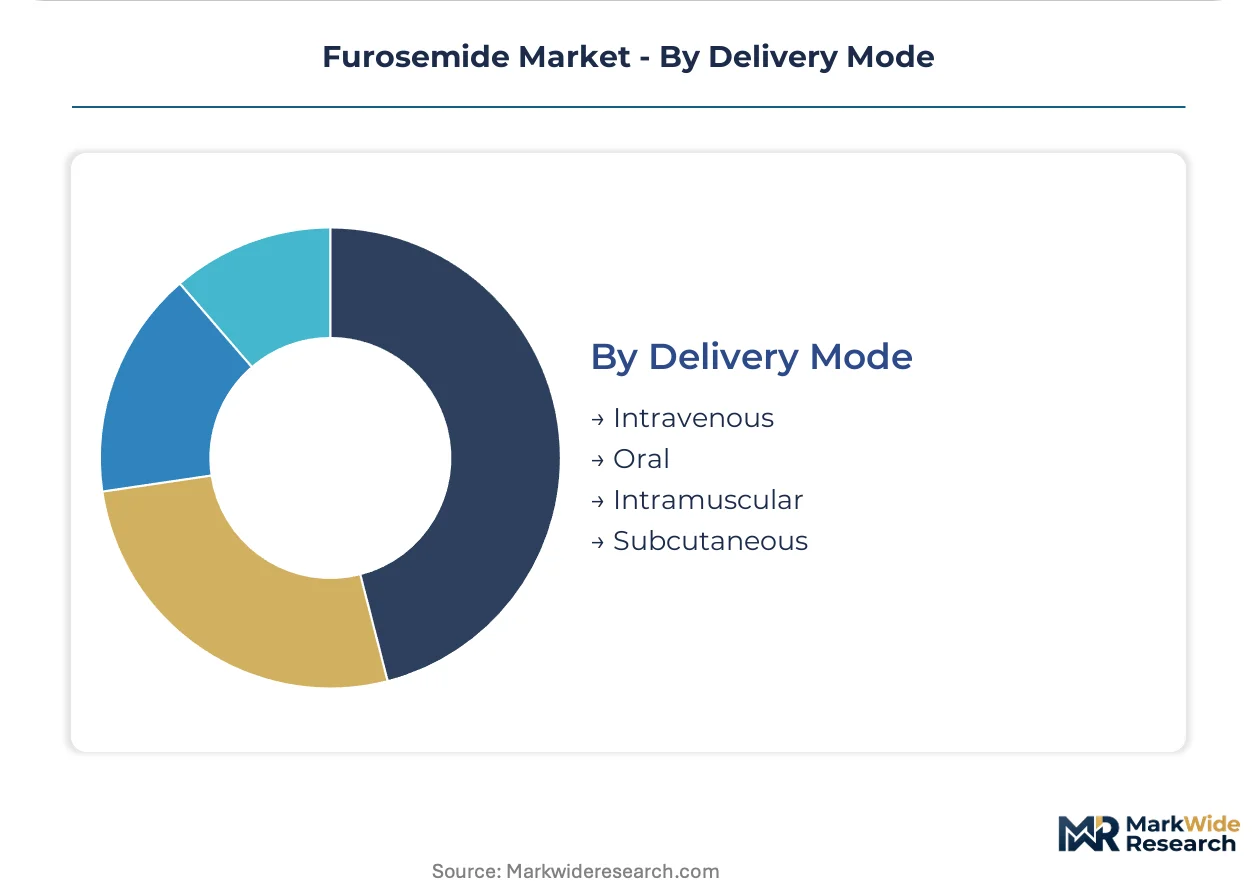
Delivery Mode:
Route selection hinges on patient hemodynamic stability, gastrointestinal absorption capacity, and care setting infrastructure.
- Intravenous:Direct vascular administration achieves near-complete bioavailability for critical-care scenarios. Perioperative protocols in German anesthesiology departments favor this route for rapid volume management.
- Oral:Gastrointestinal absorption varies from 10-90% due to first-pass metabolism and formulation factors. Maintenance therapy in stable outpatients relies on this cost-minimized route.
- Intramuscular:Deep gluteal injection serves patients with compromised venous access. Emergency departments occasionally deploy this route when intravenous line placement delays therapy.
- Subcutaneous:Continuous infusion via ambulatory pumps enables home-based diuresis for refractory heart failure. US post-acute networks are piloting this delivery mode to reduce readmission rates.
Intravenous delivery anchors hospital revenue. Subcutaneous infusion represents the steepest expansion trajectory as homecare infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and the United States outstrips that of Indian and Chinese suppliers by margins exceeding forty percent, reflecting divergent regulatory burdens and procurement consolidation trajectories.
United States
Hospital group purchasing organizations concentrate contract leverage among three dominant networks in the Southwest and Midwest, unbundling traditional distributor markups through direct manufacturer agreements. FDA bioequivalence standards and USP monograph compliance under ICH Q3D elevate per-batch analytical overhead. The Boston-Cambridge corridor anchors specialist cardiology prescribing that embeds furosemide into reduced ejection fraction protocols.
Germany
Tertiary hospital systems in Bavaria and North Rhine-Westphalia standardize ready-to-use bag formulations for perioperative diuresis, reducing compounding labor and medication error risk. EMA tightened dissolution specifications filter substandard generic suppliers from hospital tender participation. The Rhine-Ruhr industrial basin concentrates sterile fill-finish capabilities that serve pan-European acute-care networks.
India
The Production Linked Incentive scheme for bulk drugs attracts fermentation and synthetic chemistry investment that reduces import dependency for furosemide starting materials. CDSCO bioequivalence requirements align with ICH guidelines to accelerate quality upgrades among contract manufacturers. Gujarat and Maharashtra host API synthesis clusters that supply formulation plants across emerging markets.
Japan
Cardiology societies embed loop diuretics into stepped-care algorithms for resistant hypertension, expanding outpatient prescription volumes in Tokyo and Osaka metropolitan areas. PMDA pharmacovigilance requirements mandate post-market surveillance that elevates documentation burdens for foreign suppliers. The Kansai region maintains formulation expertise serving domestic geriatric populations.
China
Domestic manufacturers supply hospital procurement networks under volume-based purchasing reforms that compress margins while elevating batch-traceability requirements. NMPA dissolution standards and elemental impurity limits align with ICH Q3D to filter substandard producers. The Yangtze River Delta concentrates API synthesis capacity that feeds both domestic formulation and export markets.
Furosemide Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated market structure where sterile formulation specialists command premium positioning while high-volume generic houses compete on procurement efficiency. The vendor base separates into three strategic tiers: vertically integrated multinational pharmaceuticals with captive API supply, regional injectable specialists with hospital channel depth, and emerging-market cost leaders leveraging bulk chemistry scale. Consolidated purchasing through group purchasing organizations and direct manufacturer agreements represents the dominant competitive move, while continuous manufacturing transitions and real-time release testing adoption constitute secondary capability investments.
Among vertically integrated multinational pharmaceuticals, Teva Pharmaceutical Industries Ltd., Sandoz International GmbH, and Hikma Pharmaceuticals PLC occupy positions that exemplify divergent strategic archetypes. Teva represents cost leadership through backward integration across API synthesis and finished dosage. Sandoz anchors European regulatory dossier depth and hospital channel control. Hikma sits within the injectable specialization tier with acute-care distribution network positioning in North American markets.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd. |
| Sandoz International GmbH |
| Pfizer Inc. |
| Fresenius Kabi AG |
| Sun Pharmaceutical Industries Ltd. |
| Sanofi |
| Mylan N.V. |
| Hikma Pharmaceuticals PLC |
| Novartis AG |
| Others |
Supply Flow & Price Mechanics
SGLT2 inhibitor displacement of chronic diuretic volumes is compressing furosemide pricing power in stable heart failure segments while simultaneously redirecting manufacturing investment toward acute-care injectable formulations. This substitution dynamic concentrates high-margin production in Germany and the United States while relegating oral tablet volumes to cost-competitive Indian and Chinese suppliers.
Pricing Analysis
The customization-premium spread between ready-to-use bag formulations and standard vial presentations now exceeds forty percent in German and US tertiary hospitals. Contract-based long-term offtake agreements dominate hospital procurement, with price differentiation driven by sterile fill-finish certification grade and real-time inventory visibility integration. Cost compression in oral tablet tiers is intensifying because group purchasing organizations unbundle distributor markups through direct manufacturer negotiations. Long-term care facilities exhibit the highest price sensitivity, while perioperative anesthesia departments in academic medical centers show minimal elasticity for compounding-error reduction.
Supply Chain Analysis
Inventory buffers for 4-chloro-5-sulfamoylanthranilic acid have extended from six to ten weeks as Chinese specialty chemical producers face customs documentation scrutiny. API synthesis concentrates in China's Yangtze River Delta, India's Gujarat and Maharashtra clusters, and the Rhine-Ruhr industrial basin. Furosemide starting material supply draws from anthranilic acid derivatives, sulfamoyl chloride reagents, and chlorination catalysts. Single-source vulnerability in Chinese intermediate production exposes formulation plants to geopolitical freight disruptions. Distribution runs through consolidated hospital networks and regional pharmaceutical distributors with electronic data interchange mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has concentrated among three dominant US hospital group purchasing organizations, fragmenting supplier negotiation leverage and elevating penalty clauses for stockout events.
For Market Incumbents: Fortify sterile fill-finish capabilities in the Rhine-Ruhr and Boston-Cambridge corridors to defend against emerging-market injectable specialists. Backward integration into 4-chloro-5-sulfamoylanthranilic acid synthesis reduces exposure to Chinese intermediate concentration. EMA dissolution specification upgrades filter substandard competitors from European hospital tenders. For New Entrants and Emerging Players: Anchor in US homecare infusion services where post-acute networks deploy ambulatory pumps for heart failure decompensation. Preservative-free furosemide vials for subcutaneous delivery represent the most penetrable white-space segment. A direct-to-home-health-agency distribution model bypasses consolidated hospital procurement gatekeepers. For Investors and Strategic Acquirers: The market sits at a quality-upgrade phase that favors sterile formulation specialists with captive API supply and regulatory dossier depth. Long-term viability hinges on continuous manufacturing transitions and real-time release testing adoption. Acquisition targets should demonstrate FDA and EMA dual-compliance infrastructure. The signal to watch is REACH authorization timelines for residual solvent recovery systems.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA tightened dissolution specifications filter substandard generic manufacturers from European hospital access. |
| Backward Integration | Captive 4-chloro-5-sulfamoylanthranilic acid production insulates against Chinese intermediate supply disruptions. |
| Manufacturing Scale-Up | Continuous manufacturing transitions under FDA real-time release guidance compress oral tablet batch cycle times. |
| Hospital System Partnership | Direct agreements with Southwest and Midwest GPOs unbundle distributor markups and secure volume commitments. |
| Product Launch | Ready-to-use bag formulations reduce perioperative compounding labor and medication error risk in German anesthesia departments. |
Methodological Framework
Desk research of FDA bioequivalence filings, EMA regulatory dossiers, USP monograph revisions, and Indian CDSCO approval records preceded structured interviews with hospital procurement managers, sterile fill-finish plant directors, regulatory affairs leads at generic manufacturers, and cardiology formulary directors. Secondary validation drew from hospital group purchasing organization contract databases, pharmaceutical import-export customs records, and ICH Q3D implementation guidance documents. Bottom-up prescription volume modeling and top-down therapeutic class expenditure analysis provided triangulation.
Variance decomposition across dosage form, delivery mode, end-user setting, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from log-linear trend fitting to standardized prescription volumes and hospital procurement expenditure patterns. Modeled inputs included heart failure protocol adoption curves, SGLT2 inhibitor substitution rates in stable patients, and EMA dissolution specification compliance timelines.
Material uncertainties — regulatory inspection backlogs, REACH authorization delays for solvent recovery systems, and geopolitical disruptions to Chinese intermediate supply — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding cardiology society guideline revisions and hospital procurement consolidation trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Nortriptyline Hydrochloride Market
Pharmaceutical Ingredients
Saudi Arabia Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Zinc Bacitracin Market
Pharmaceutical Ingredients
Pharmaceutical Fine Chemicals Market
Pharmaceutical Ingredients
Nuclear Export Inhibitor Drugs Market
Pharmaceutical Ingredients
Synthetic Small Molecule API Market
Pharmaceutical Ingredients
Alpha Lipoic Acid API Market
Pharmaceutical Ingredients
Europe Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Oral Doxycycline Hyclate Market
Pharmaceutical Ingredients
Antibiotics API Market
Pharmaceutical Ingredients
Global Barbiturate Drugs Market
Pharmaceutical Ingredients
Antibiotics Active Pharmaceutical Ingredient (API) Market
Pharmaceutical Ingredients
Sterile Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Citicoline Market
Pharmaceutical Ingredients
Tiapride Hydrochloride API Market
Pharmaceutical Ingredients
Transdermal Drugs Market