
 Pharma Grade Synthetic Camphor Market | 2026-2036
Pharma Grade Synthetic Camphor Market Size, Share, and Industry Trends Forecast 2026-2036
Pharma Grade Synthetic Camphor Market Outlook
Contract manufacturers are redrawing procurement patterns for pharma grade synthetic camphor as branded pharmaceutical companies outsource excipient blending and tablet coating operations. Merck KGaA leverages its European pharmacopoeia certification network to supply high-purity grades to formulation labs across Germany and Switzerland. Oriental Aromatics Ltd. anchors South Asian supply through integrated turpentine processing plants in western India. Nippon Fine Chemical Co. Ltd. competes on synthetic route efficiency, operating continuous-flow hydrogenation systems that reduce batch-to-batch variability.
Pharma grade synthetic camphor denotes a bicyclic monoterpene ketone synthesized from alpha-pinene via Wagner-Meerwein rearrangement, meeting pharmacopoeial specifications of minimum 96% d-camphor content and sub-0.1% residual limonene for topical and respiratory drug applications. Powder form dominates hospital and pharmaceutical company procurement due to precise dosing in ointment compounding, while liquid formulations gain share in research laboratories requiring sterile dilutions for inhalation studies. Synthetic camphor outpaces natural grades in volume terms as Turpentine-derived supply chains achieve cost parity with sustainable forestry certification.
The US FDA enforces USP-NF monograph compliance for camphor used in over-the-counter counterirritant products, while India's CDSCO mandates BIS certification for domestic pharmaceutical excipient manufacturing and the EU's EMA requires REACH registration for imported synthetic terpenes entering European formulation facilities. These overlapping standards elevate testing costs for cross-border suppliers but create durable barriers against uncertified entrants. Stakeholders must monitor evolving pharmacopoeial harmonization talks between ICH member regulators to anticipate whether dual-certification requirements will consolidate or fragment further.
Market Dynamics
Pharmaceutical excipient procurement is consolidating around certified suppliers capable of meeting dual USP-NF and pharmacopoeia compliance, forcing mid-scale manufacturers to absorb testing costs or exit cross-border trade.
Growth Catalysts
- Regulatory harmonization pressure:The US FDA's tightened purity standards for topical analgesic excipients are elevating demand for documented synthetic camphor with sub-0.1% residual limonene certification.
- Turpentine processing efficiency:Continuous-flow hydrogenation systems are reducing batch-to-batch variability, enabling pharmaceutical companies to standardize formulation outcomes across production sites.
- Contract manufacturing expansion:Branded pharmaceutical companies are outsourcing excipient blending operations, creating dedicated procurement channels for high-purity synthetic terpenes.
Market Restraints
- Feedstock concentration:Alpha-pinene supply chains cluster in specific turpentine processing regions, exposing formulators to localized production disruptions.
- Certification cost burden:REACH registration for European entry and BIS compliance for Indian manufacturing create overlapping testing expenditures that compress margins for smaller suppliers.
- Natural camphor substitution:Sustainable forestry certification programs are reviving interest in botanical-derived alternatives for premium topical applications.
Strategic Opportunities
- Inhalation research expansion:Liquid formulation grades for sterile dilutions are gaining traction in respiratory drug development pipelines.
- Indian export channel development:Integrated turpentine-to-camphor facilities in western India offer scale advantages for serving Middle Eastern and African pharmaceutical markets.
- Pharmacopoeial convergence:ICH member regulator discussions on monograph harmonization could reduce dual-certification requirements, streamlining cross-border supplier qualification.
Industry Challenges
- Analytical chemistry talent scarcity:Specialized chromatography expertise for residual terpene quantification is concentrated among contract testing laboratories, extending validation timelines.
- Legacy equipment retrofit costs:Batch hydrogenation systems require significant capital expenditure to upgrade for continuous-flow synthetic routes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharma Grade Synthetic Camphor Market |
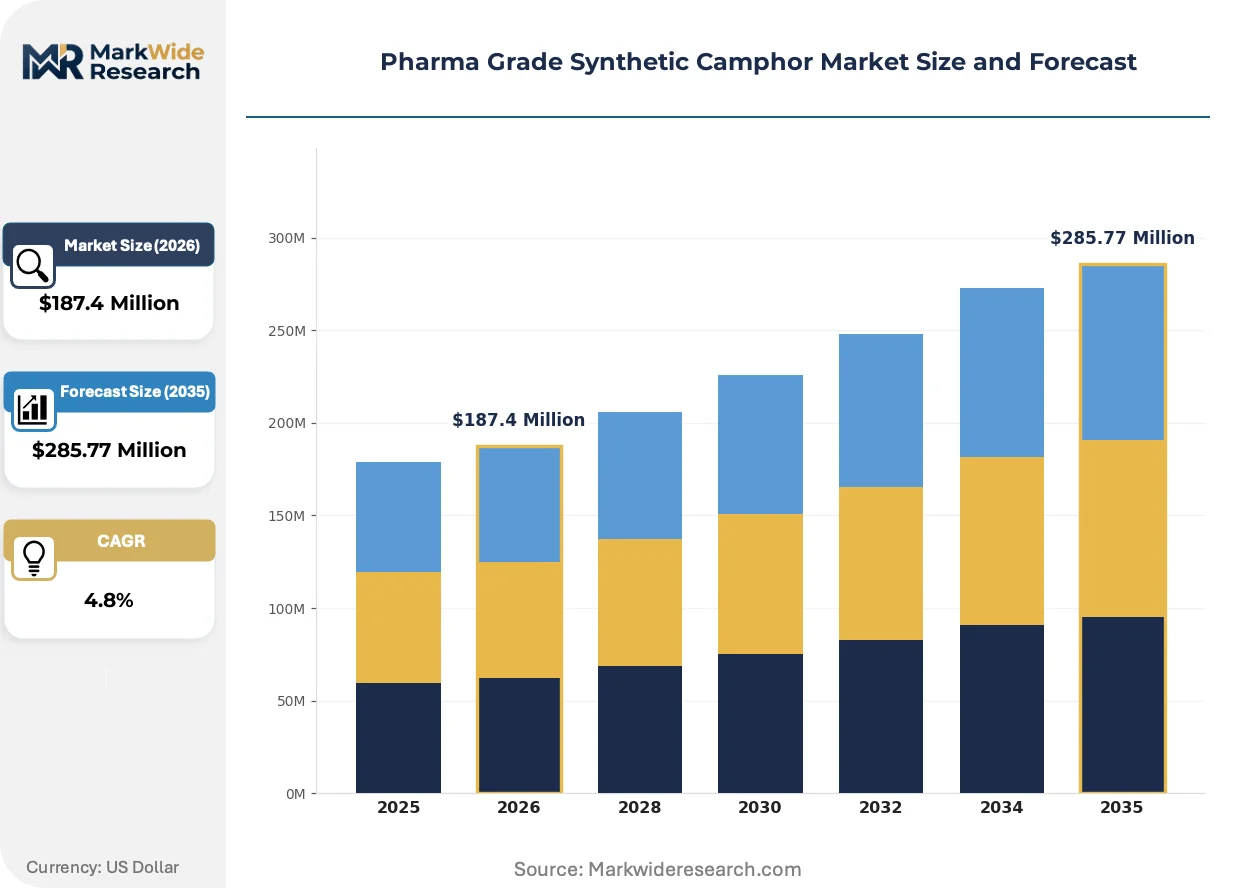
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Camphor, Synthetic Camphor, Turpentine-derived, Others Application: Pharmaceuticals, Cosmetics, Food Additives, Industrial Solvents End User: Hospitals, Pharmaceuticals Companies, Research Laboratories, Contract Manufacturers Form: Powder, Flakes, Granules, Liquid |
| Companies Covered | Nippon Fine Chemical Co. Ltd., Oriental Aromatics Ltd., Saptagir Camphor Ltd., Mangalam Organics Ltd., Merck KGaA, Kanchi Karpooram Limited, Aldon Corporation, Rochem International Inc., Spectrum Chemical Mfg. Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharma Grade Synthetic Camphor Market Strategic Shifts
Continuous processing technologies are compressing production cycles for synthetic terpenes while regulatory documentation requirements are reshaping supplier qualification protocols across pharmaceutical value chains.
Continuous-flow hydrogenation reactors are supplanting traditional batch vessels in synthetic camphor manufacturing, enabling real-time process analytical technology integration. Pharmaceutical contract manufacturers in Germany and Switzerland are prioritizing these systems for reduced solvent waste profiles. The technology is supplanting established batch-to-batch release testing, compressing quality assurance timelines from weeks to days.
REACH registration requirements for imported synthetic terpenes are tightening substance documentation obligations for European formulation facilities. The EMA's emphasis on supply chain transparency is forcing non-EU manufacturers to establish EU-based importer-of-record arrangements. Powder-grade suppliers serving topical analgesic markets are responding by consolidating certification under European pharmacopoeia standards.
Hospital procurement departments are consolidating excipient purchasing through group purchasing organizations, compressing supplier lists to pre-qualified vendors with documented pharmacopoeial compliance. This concentration is displacing spot-market purchasing for camphor used in compounding pharmacies. The shift is most visible in US health system networks where FDA enforcement of USP-NF monographs has elevated documentation requirements.
Pharma Grade Synthetic Camphor Market Segmentation
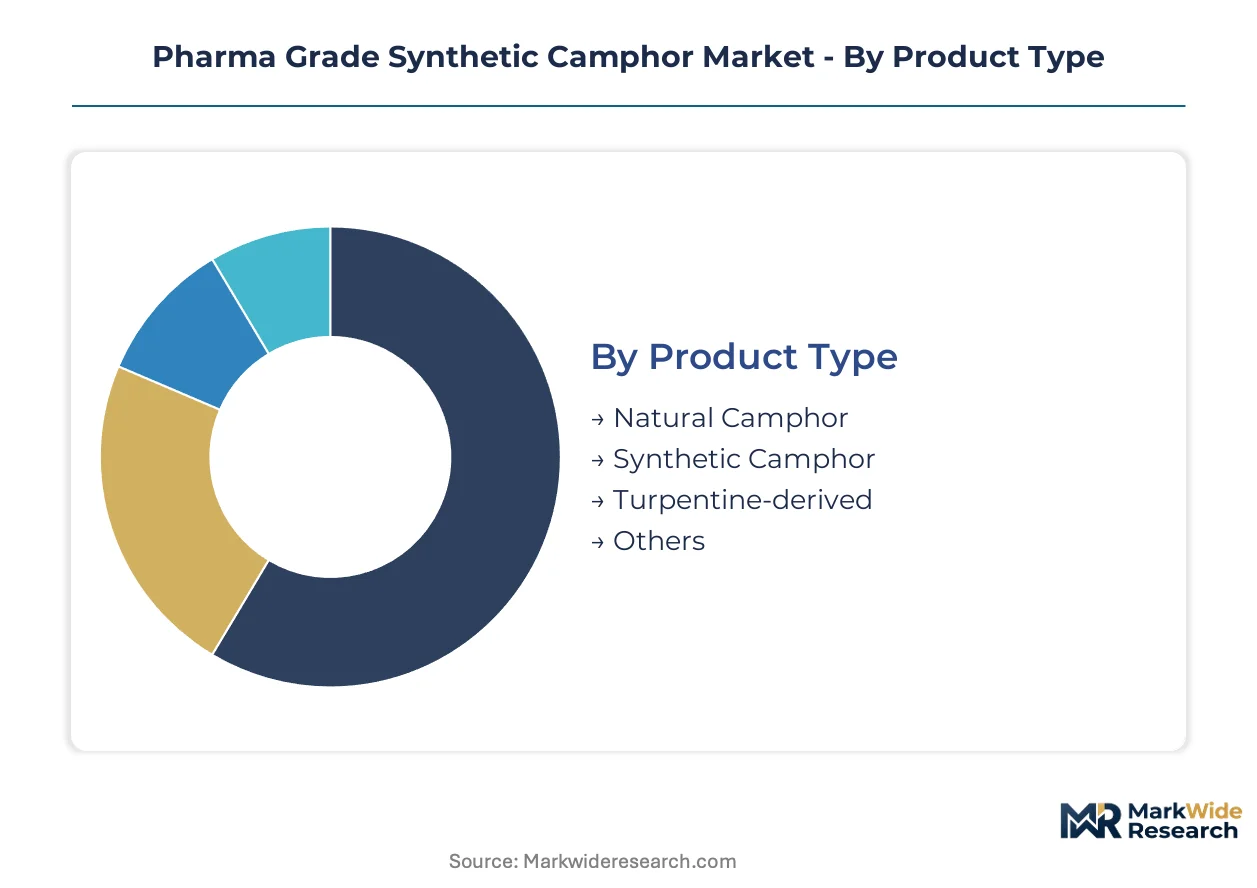
Segmentation in pharma grade synthetic camphor reveals how regulatory specifications fragment procurement channels across pharmaceutical value chains. Each dimension—product origin, application purity, end-user scale, and physical form—carries distinct certification burdens that reshape supplier qualification protocols.
Product Type:
Regulatory differentiation separates botanical-derived from synthetic grades through pharmacopoeial monograph requirements that govern excipient eligibility in FDA, EMA, and CDSCO jurisdictions.
- Synthetic Camphor:Manufactured via alpha-pinene Wagner-Meerwein rearrangement with minimum 96% d-camphor content and sub-0.1% residual limonene. US FDA tightening of USP-NF purity standards for topical analgesic formulations is elevating procurement volumes from continuous-flow hydrogenation facilities.
- Turpentine-derived:Sourced from integrated turpentine processing plants in western India, achieving cost parity with sustainable forestry certification. Mangalam Organics and Kanchi Karpooram operate large-scale conversion facilities serving domestic CDSCO-compliant and export REACH-registered markets.
- Natural Camphor:Botanical extraction from Cinnamomum camphora meeting premium topical application specifications where sustainable forestry certification programs revive interest for select cosmetic and pharmaceutical uses.
- Others:Minor synthetic routes and specialty grades including laboratory-scale custom synthesis for research applications requiring non-standard isomeric purity profiles.
Synthetic camphor handles the majority of throughput; turpentine-derived grades are expanding most quickly on share as Indian export channels mature.
Application:
Cost tier stratification aligns with regulatory scrutiny intensity, where pharmaceutical applications absorb the highest testing expenditures while industrial uses operate under lighter documentation requirements.
- Pharmaceuticals:Excipient use in topical analgesic ointments, respiratory inhalants, and tablet coatings demanding USP-NF, European Pharmacopoeia, or BIS pharmacopoeial compliance. Hospital procurement through group purchasing organizations concentrates demand on pre-qualified vendors with documented batch release protocols.
- Cosmetics:Fragrance and cooling agent applications in personal care formulations with REACH registration for European market entry and emerging clean-label preference shifts.
- Food Additives:Limited flavoring applications under FSSAI and FDA food-grade specifications with restricted concentration limits compared to pharmaceutical grades.
- Industrial Solvents:Plasticizer and cellulose nitrate solvent uses operating outside pharmacopoeial frameworks, competing primarily on volume pricing and solvent recovery efficiency.
Pharmaceutical applications command the dominant value share; cosmetics represent the steepest expansion trajectory as clean-label cooling agents displace synthetic alternatives.
End User:
Customer type determines order scale and certification depth, with pharmaceutical companies and contract manufacturers driving standardization while research laboratories sustain specialty demand.
- Pharmaceuticals Companies:Branded drug manufacturers outsourcing excipient blending operations to contract manufacturers while maintaining direct procurement of high-purity synthetic terpenes for in-house formulation development. Merck KGaA's European pharmacopoeia certification network serves this tier across Germany and Switzerland.
- Contract Manufacturers:Dedicated procurement channels for high-purity synthetic terpenes with documented pharmacopoeial compliance, consolidating purchasing through group purchasing organizations that compress supplier lists to pre-qualified vendors.
- Hospitals:Compounding pharmacy procurement shifting from spot-market purchasing to consolidated excipient purchasing through health system networks where FDA enforcement of USP-NF monographs elevates documentation requirements.
- Research Laboratories:Liquid formulation grades for sterile dilutions in respiratory drug development pipelines, requiring precise dosing flexibility and small-batch flexibility over scale economies.
Pharmaceuticals companies handle the majority of throughput; contract manufacturers are gaining share fastest as outsourcing of excipient blending accelerates.
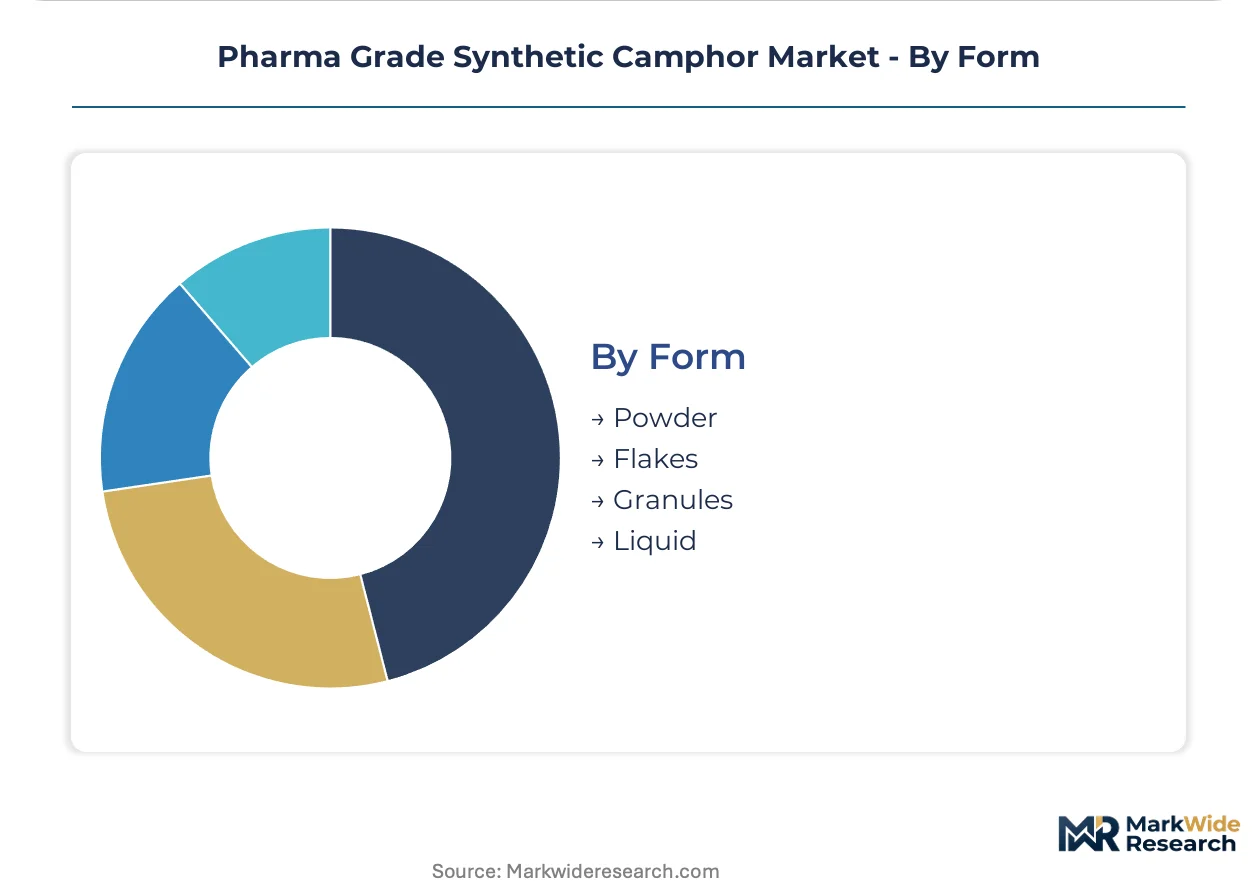
Form:
Physical state governs handling protocols and dissolution kinetics, with powder dominating precise dosing applications while liquid gains traction in sterile processing environments.
- Powder:Dominates hospital and pharmaceutical company procurement due to precise dosing in ointment compounding and tablet coating operations, with flow properties and particle size distribution critical for blending uniformity.
- Liquid:Gaining share in research laboratories requiring sterile dilutions for inhalation studies and continuous manufacturing processes where solvent-based handling reduces dust exposure and improves process analytical technology integration.
- Flakes:Intermediate form for specialized compounding applications where controlled dissolution rates and reduced static charge improve handling in humid climates.
- Granules:Agglomerated form for direct compression tablet manufacturing and reduced dust generation in high-volume pharmaceutical production environments.
Powder handles the majority of throughput; liquid is climbing the fastest on share as continuous processing technologies displace batch operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jawaharlal Nehru Port Trust in Mumbai anchors Indian synthetic camphor export capacity to Middle Eastern and African pharmaceutical markets. Rotterdam's Europoort terminal enables REACH-registered terpene flows into German and Swiss formulation facilities. The Port of Hamburg serves as the primary entry point for Asian synthetic camphor into Central European pharmacopoeia-certified supply chains.
United States
FDA enforcement of USP-NF monographs for topical analgesic excipients drives hospital procurement consolidation through group purchasing organizations. The agency's tightened purity standards elevate demand for documented sub-0.1% residual limonene certification. New Jersey and Pennsylvania host contract manufacturing clusters where pre-qualified vendors supply compounding pharmacies.
Germany
Merck KGaA's European pharmacopoeia certification network serves formulation labs across Baden-Württemberg and Bavaria. EMA requirements for REACH registration on imported synthetic terpenes force documentation upgrades at BASF Ludwigshafen and Bayer Leverkusen sites. Continuous-flow hydrogenation systems from Swiss suppliers integrate into Ruhr Valley production lines.
India
Mangalam Organics and Kanchi Karpooram operate integrated turpentine-to-camphor facilities in Gujarat and Tamil Nadu serving CDSCO-compliant domestic and export markets. BIS certification mandates compress supplier lists for pharmaceutical excipient manufacturing. Mumbai-Pune corridor contract manufacturers absorb testing costs to maintain cross-border trade eligibility.
Switzerland
Swissmedic oversight of excipient quality creates premium procurement channels for high-purity synthetic terpenes. Basel's pharmaceutical cluster demands documented pharmacopoeial compliance for topical and respiratory drug applications. Continuous manufacturing technology vendors from Zürich supply real-time process analytical systems to German contract manufacturers.
Japan
PMDA pharmacopoeial standards for camphor in over-the-counter counterirritants align with USP-NF specifications. Nippon Fine Chemical Co. Ltd. operates synthetic route efficiency systems in Osaka Prefecture. METI industrial standards support hydrogenation technology exports to Southeast Asian formulation facilities.
Pharma Grade Synthetic Camphor Market Competitive Environment
Concentration sits with integrated turpentine processors and European pharmacopoeia-certified suppliers. The vendor base separates into three tiers: large-scale Indian converters with captive alpha-pinene supply, German-Swiss specialists with dual-certification documentation capabilities, and Japanese continuous-process technology leaders. Capacity expansion and REACH registration consolidation represent the dominant competitive moves as cross-border qualification costs rise.
Within the integrated processing tier, Mangalam Organics Ltd. and Kanchi Karpooram Limited exemplify scale-driven Indian suppliers with western India turpentine conversion infrastructure. Merck KGaA occupies the European certification-specialist position, anchoring pharmacopoeia-compliant supply to German and Swiss formulation markets. Nippon Fine Chemical Co. Ltd. represents the continuous-flow technology archetype, with Japanese hydrogenation efficiency systems reducing batch-to-batch variability for respiratory and topical drug applications.
| Leading Market Players |
|---|
| Nippon Fine Chemical Co. Ltd. |
| Oriental Aromatics Ltd. |
| Saptagir Camphor Ltd. |
| Mangalam Organics Ltd. |
| Merck KGaA |
| Kanchi Karpooram Limited |
| Aldon Corporation |
| Rochem International Inc. |
| Spectrum Chemical Mfg. Corp. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Indian turpentine processors and European formulation labs lock in supply access while providing price visibility across REACH registration cycles. These contracts insulate pharmaceutical buyers from alpha-pinene feedstock volatility while compressing margins for spot-market suppliers.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade from industrial-grade procurement, with USP-NF certified batches commanding premiums over BIS-compliant domestic Indian supply. Price differentiation hinges on residual limonene certification thresholds and dual pharmacopoeia documentation depth. Cost compression in standard-grade synthetic camphor is intensifying because REACH registration fees are being amortized across smaller batch sizes. Contract manufacturers exhibit the highest price sensitivity due to group purchasing organization consolidation, while research laboratories absorb premium pricing for liquid sterile grades.
Supply Chain Analysis
India and Germany anchor pharmaceutical-grade synthetic camphor production, with Gujarat-based turpentine conversion facilities feeding Mumbai-Pune corridor contract manufacturers and Ruhr Valley hydrogenation plants supplying Swiss and German formulation labs. Feedstock supply draws from alpha-pinene distillation clusters in western India and pine chemical processing centers in Central Europe. Single-source vulnerability concentrates in turpentine supply chains exposed to monsoon-disrupted forestry operations. Distribution runs through Rotterdam's Europoort terminal for REACH-registered European entry and Jawaharlal Nehru Port Trust for Middle Eastern and African pharmaceutical markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where dual pharmacopoeia certification creates switching costs that lock pharmaceutical buyers into qualified supplier relationships. The structural moat deepens as FDA, EMA, and CDSCO documentation requirements diverge.
For Market Incumbents: Secure backward integration into alpha-pinene distillation to insulate margin structures from turpentine feedstock volatility. Prioritize continuous-flow hydrogenation retrofits that compress batch-to-batch variability and accelerate pharmacopoeial release timelines. Natural camphor substitution threats from sustainable forestry certification programs demand defensive positioning through documented synthetic route carbon footprinting. For New Entrants and Emerging Players: CDSCO fast-track certification for BIS-compliant domestic Indian manufacturing opens accessible pathways before attempting REACH-registered European entry. Target Middle Eastern and African pharmaceutical markets served through Mumbai export channels where documentation requirements remain lighter. Lead with liquid sterile formulation grades for respiratory drug development pipelines where incumbent capacity concentrates in powder production. For Investors and Strategic Acquirers: Mid-scale Indian converters with captive turpentine supply and incomplete export certification represent consolidation targets. Long-term viability frames around pharmacopoeial harmonization outcomes across the analysis window. Monitor ICH member regulator discussions on monograph convergence as the inflection signal determining whether dual-certification cost burdens consolidate or fragment further.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alpha-Pinene Distillation | Captive feedstock supply from Gujarat forestry operations insulates margin structures from monsoon volatility. |
| Continuous-Flow Hydrogenation Retrofit | Real-time process analytical technology integration compresses USP-NF batch release timelines from weeks to days. |
| Dual Pharmacopoeia Certification Investment | Simultaneous USP-NF and European Pharmacopoeia documentation unlocks German and Swiss contract manufacturing demand. |
| Liquid Sterile Grade Capacity Addition | Inhalation research expansion in respiratory drug pipelines displaces powder-dominated incumbent supply. |
| REACH Registration Consolidation | EU-based importer-of-record arrangements satisfy EMA supply chain transparency mandates for Asian manufacturers. |
Study Parameters
Desk research of pharmacopoeial monograph databases, customs trade records, and SEC filings preceded structured interviews with pharmaceutical procurement managers, regulatory affairs directors, contract manufacturing executives, and turpentine processing plant managers. Primary fieldwork validated secondary findings through bottom-up triangulation across Indian export channels and top-down reconciliation against European formulation facility demand.
Variance decomposition across product type, application purity tier, end-user scale, and physical form dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented volume-demand modeling incorporating pharmaceutical excipient outsourcing rates, respiratory drug pipeline progression, and continuous manufacturing technology adoption curves.
Underlying assumptions cover sustained FDA enforcement of USP-NF purity standards, with deviation risk concentrated in pharmacopoeial harmonization negotiations and alpha-pinene feedstock supply disruptions. Recalibration cycles align with material shifts in ICH regulatory convergence timelines and Indian forestry certification program expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Pharmaceutical Excipients for Taste Masking Market
Pharmaceutical Ingredients
Calcium Folinate for Injection Market
Pharmaceutical Ingredients
Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market
Pharmaceutical Ingredients
Asia-Pacific Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Small Molecule Drug Discovery Market
Pharmaceutical Ingredients
Pharmaceutical Grade Magnesium Hydroxide Market
Pharmaceutical Ingredients
Pharmaceutical Lactose Market
Pharmaceutical Ingredients
Encapsulated Salicylic Acid Market
Pharmaceutical Ingredients
Montelukast API Market
Pharmaceutical Ingredients
Biologic Excipients Market
Pharmaceutical Ingredients
Germany Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Albumin (As Excipient) Market
Pharmaceutical Ingredients
Zinc Bacitracin Market
Pharmaceutical Ingredients
Cyclooxygenase 2 Inhibitor Market
Pharmaceutical Ingredients
Global Dexamethasone Market
Pharmaceutical Ingredients
Pharma Grade Ibuprofen API Market