
 Moxifloxacin Hcl (CAS 186826-86-8) Market | 2026-2036
Moxifloxacin Hcl (CAS 186826-86-8) Market Size, Share, and Industry Trends Forecast 2026-2036
Moxifloxacin Hcl (CAS 186826-86-8) Market Analysis
Asset-light contract manufacturing partnerships are reshaping competitive entry in the Moxifloxacin HCl market, enabling mid-tier firms to scale without capital-intensive fermentation facilities. Pioneer Biotech leverages its integrated fermentation-to-API platform to control cost structures across bulk supply. Neuland Laboratories Ltd. anchors its position through specialized peptide and antibiotic chemistry expertise in regulated markets. Sigma-Aldrich competes via premium analytical-grade positioning for research and reference-standard applications.
Moxifloxacin hydrochloride is a fluoroquinolone antibiotic salt with molecular formula C21H24FN3O4·HCl, synthesized through multi-step organic chemistry involving quinolone core formation followed by side-chain substitution and acid salt crystallization; it functions primarily as a broad-spectrum antibacterial agent targeting DNA gyrase and topoisomerase IV in susceptible pathogens. Injectable formulations lead value generation due to higher unit economics and hospital critical-care dependence, while ophthalmic solution demand accelerates fastest behind ambulatory surgical center expansion. Therapy area segmentation shows respiratory infections occupying the mature volume base, with skin infection protocols generating concentrated margin pools in outpatient settings.
FDA batch certification requirements and EMA Good Manufacturing Practice inspections shape API sourcing decisions, compelling manufacturers to maintain dual-standard compliance for transatlantic market access. India's CDSCO and China's NMPA enforce escalating local purity specifications that filter out sub-scale producers. Stakeholders must monitor regulatory divergence between USP and EP monograph updates to avoid specification misalignment.
Market Dynamics
Injectable moxifloxacin HCl procurement is consolidating under hospital group purchasing organizations, compressing supplier margins while amplifying volume concentration among API manufacturers with dual FDA-EMA certification capabilities.
Growth Catalysts
- CDSCO purity escalation:India's tightened API specifications for fluoroquinolone salts are filtering out sub-scale producers and concentrating orders among certified fermentation specialists.
- Ambulatory surgical center expansion:Ophthalmic solution demand is accelerating as outpatient surgical volumes shift from inpatient settings across the United States and Western Europe.
- Enzymatic synthesis adoption:Biocatalytic routes for quinolone core formation are reducing solvent waste and shortening cycle times in commercial API production.
Market Restraints
- Starting material volatility:Piperazine and cyclopropylamine feedstock costs fluctuate with petrochemical pricing, squeezing margin predictability for multi-step synthesis operations.
- Zhejiang cluster concentration:Overreliance on eastern China's API manufacturing belt creates single-point vulnerability to environmental compliance shutdowns and logistics disruption.
- Fluoroquinolone resistance surveillance:WHO antimicrobial stewardship protocols are tightening hospital formularies and restricting empirical use in respiratory infections.
Strategic Opportunities
- Brazil ANVISA pathway:Underpenetrated Latin American markets present first-mover advantage for manufacturers establishing local reference-standard partnerships.
- Combination therapy protocols:Fixed-dose pairing with beta-lactamase inhibitors is emerging in complicated intra-abdominal infection guidelines.
- Continuous flow chemistry:Adoption of plug-flow reactors for nitration and cyclization steps promises yield improvements and reduced batch-to-batch variation.
Industry Challenges
- Genotoxic impurity control:N-nitrosamine and quinoline-related substance detection at parts-per-billion levels demands capital-intensive analytical infrastructure.
- Multiparametric release testing:Extended dissolution profiling and polymorph characterization are lengthening batch release timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Moxifloxacin Hcl (CAS 186826-86-8) Market |
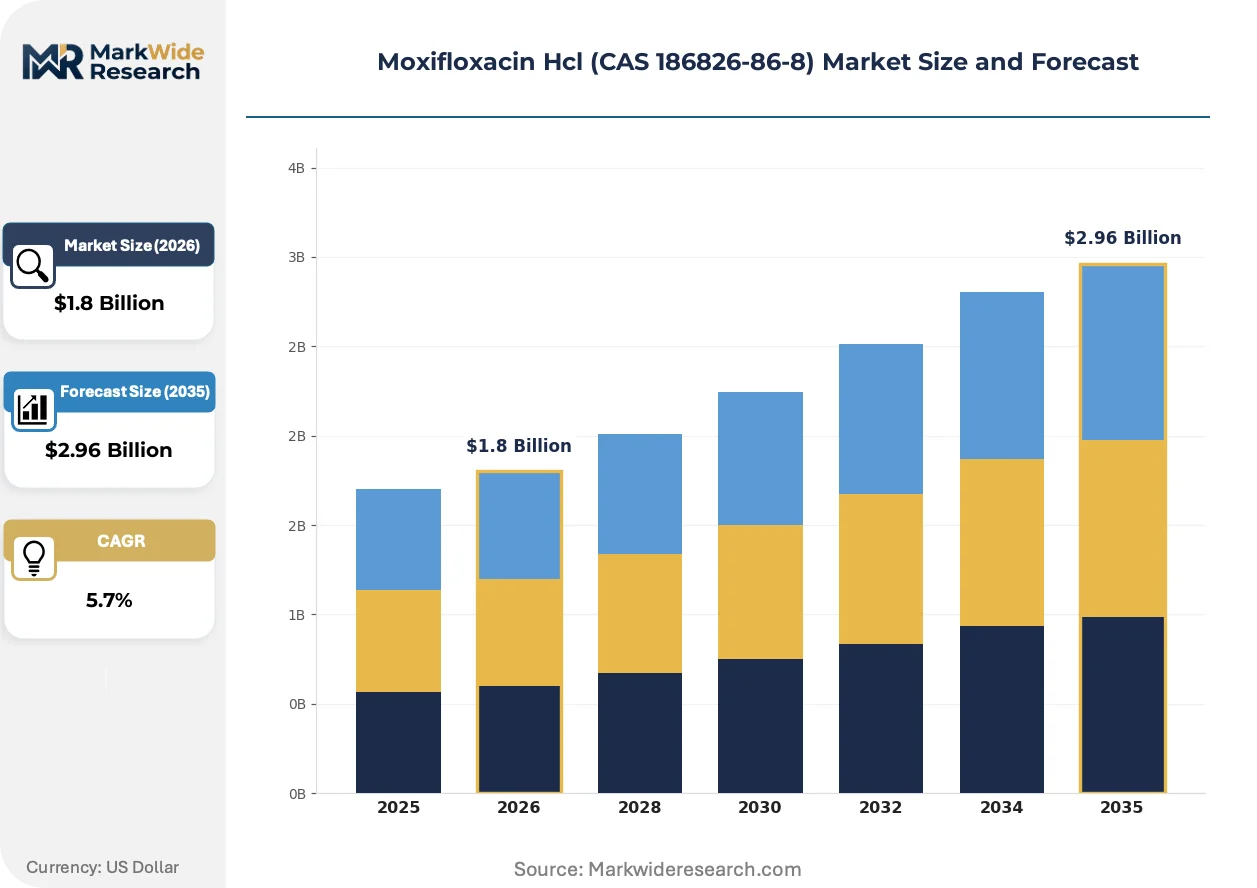
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Injectable, Ophthalmic Solution, Oral Suspension Therapy Area: Respiratory Infections, Skin Infections, Joint Infections, Gastrointestinal Infections End User: Hospitals, Pharmacies, Clinics, Homecare Distribution Channel: Direct Sales, Distributors, Retail, E-commerce |
| Companies Covered | Actavis UK, Cayman Pharmacy Groups, Pioneer Biotech, TECO land, BOC Sciences, Yutian Pharmaceutical, Nivika Chemo Pharma, Neuland Laboratories Ltd., Sigma-Aldrich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Moxifloxacin Hcl (CAS 186826-86-8) Market Emerging Trajectories
Process intensification and regulatory harmonization are compressing traditional competitive moats in moxifloxacin HCl manufacturing, rewarding agile producers with integrated quality systems.
Continuous manufacturing platforms are collapsing batch-scale economics in API synthesis. Mid-tier CMOs in India and China are retrofitting pilot plants with continuous crystallization and inline PAT sensors. This technology compression is enabling 20-30% throughput gains without greenfield fermentation investment, eroding the volume advantage of legacy batch specialists.
EMA's revised nitrosamine risk assessment guidelines are forcing retrospective validation of historical API batches. Manufacturers must resubmit dossiers with enhanced impurity fate mapping and purge factor justifications. Injectable-grade suppliers face the steepest compliance burden, with sterile formulation sites in Germany and Italy accelerating analytical method transfers.
Hospital procurement is consolidating under regional GPO frameworks in the United States, replacing fragmented purchasing with centralized tender mechanisms. This buyer concentration is privileging suppliers with 503B compounding pharmacy partnerships and just-in-time distribution networks. The shift is most visible in the southeastern US hospital systems, where IDN-owned specialty pharmacies are capturing outpatient parenteral antimicrobial therapy volumes.
Moxifloxacin Hcl (CAS 186826-86-8) Market Segmentation
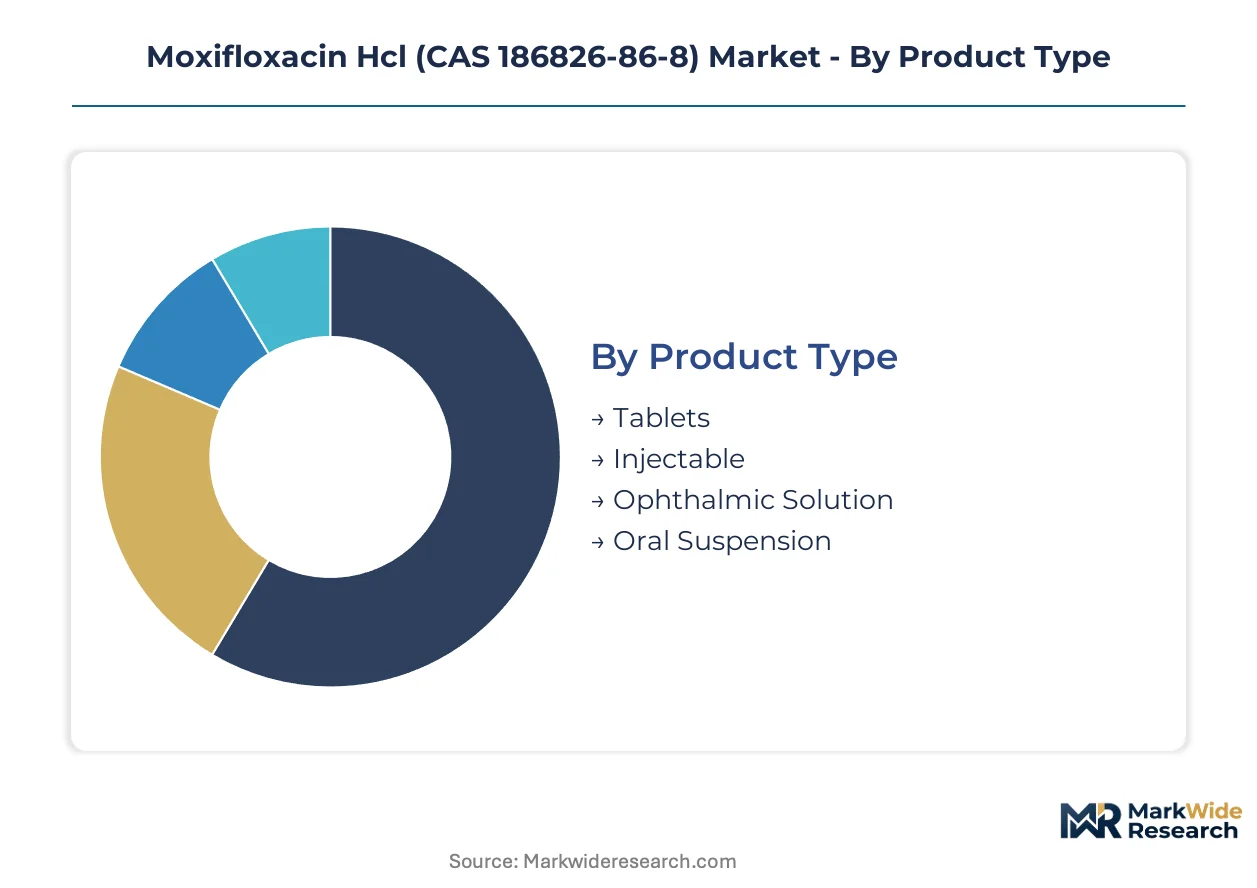
Moxifloxacin HCl procurement patterns diverge sharply across formulation types and care settings. Hospital formulary committees, retail pharmacy chains, and ambulatory surgical centers each impose distinct specification and logistics requirements that reshape supplier priorities.
Product Type:
Mature oral solid doses coexist with rapidly expanding sterile injectable and ophthalmic formats across regulated markets.
- Tablets:Oral solid dosage containing 400mg moxifloxacin base equivalent, compressed with standard excipients and film-coated for gastric protection. Outpatient respiratory infection protocols in India and China generate concentrated volume, though WHO antimicrobial stewardship guidelines are tightening empirical prescribing thresholds.
- Injectable:Sterile solution for intravenous infusion, typically 400mg/250mL in sodium chloride or dextrose vehicle, requiring aseptic manufacturing and terminal sterilization validation. Hospital critical-care dependence in the United States and Germany sustains premium positioning, with group purchasing organization consolidation amplifying volume concentration among dual-certified API suppliers.
- Ophthalmic Solution:Sterile 0.5% aqueous preparation for topical ocular administration, formulated with pH-adjusting agents and preservative systems meeting USP sterility standards. Ambulatory surgical center expansion across the United States and Western Europe accelerates demand behind cataract and refractive surgery volume shifts.
- Oral Suspension:Liquid formulation containing micronized drug dispersed in flavored aqueous vehicle, dosed by volume for pediatric or dysphagic patients. Niche positioning in homecare and pediatric clinic settings with limited API sourcing flexibility due to taste-masking complexity.
Injectable formulations handle the majority of throughput; ophthalmic solution is the fastest mover on share.
Therapy Area:
Volume concentrates in respiratory indications while margin pools shift toward skin and joint infection protocols.
- Respiratory Infections:Community-acquired pneumonia and acute bacterial sinusitis represent the established clinical application, with IDSA/ATS guidelines specifying moxifloxacin as respiratory fluoroquinolone of choice for beta-lactam allergic patients. Hospital admission criteria and CMS quality metrics in the United States constrain empirical use, redirecting volume toward culture-confirmed cases.
- Skin Infections:Complicated skin and soft tissue infections including diabetic foot infections and surgical site infections drive concentrated margin capture in outpatient parenteral antimicrobial therapy programs. Medicare reimbursement for hospital-at-home services in the United States expands eligible patient populations.
- Joint Infections:Prosthetic joint infection suppression and native septic arthritis management require prolonged parenteral courses with orthopedic surgery collaboration. Tertiary referral centers in Germany and Switzerland anchor demand through multidisciplinary infection service protocols.
- Gastrointestinal Infections:Complicated intra-abdominal infection coverage, typically in combination with anaerobic agents, occupies narrower positioning within surgical prophylaxis guidelines. EMA's restricted indication warnings have compressed European utilization compared to Asian markets.
Respiratory infections retain dominant volume contribution; skin infection applications are expanding most quickly on margin contribution.
End User:
Procurement authority fragments across institutional buyers with divergent technical specifications and compliance requirements.
- Hospitals:Integrated delivery networks and public hospital systems with centralized pharmacy and therapeutics committees, requiring FDA batch certification or EMA GMP documentation for formulary inclusion. Group purchasing organization aggregation in the United States and NHS trust procurement in the United Kingdom compress supplier margins while amplifying volume concentration.
- Pharmacies:Independent and chain retail dispensaries with stock-keeping unit breadth requirements and reverse logistics obligations. India's Jan Aushadhi generic program and China's centralized drug procurement volume-based purchasing reshape pricing structures for oral formulations.
- Clinics:Ambulatory care centers including ophthalmology practices and infectious disease infusion centers with specialty-specific formulation preferences. ASC certification standards in the United States drive ophthalmic solution specification alignment.
- Homecare:Infusion nursing services and patient self-administration programs requiring stability-validated take-home packaging and refrigeration chain integrity. Medicare home infusion therapy benefit expansion in the United States enlarges eligible service territories.
Hospitals command dominant procurement volume; homecare is climbing the fastest on patient-shift dynamics.
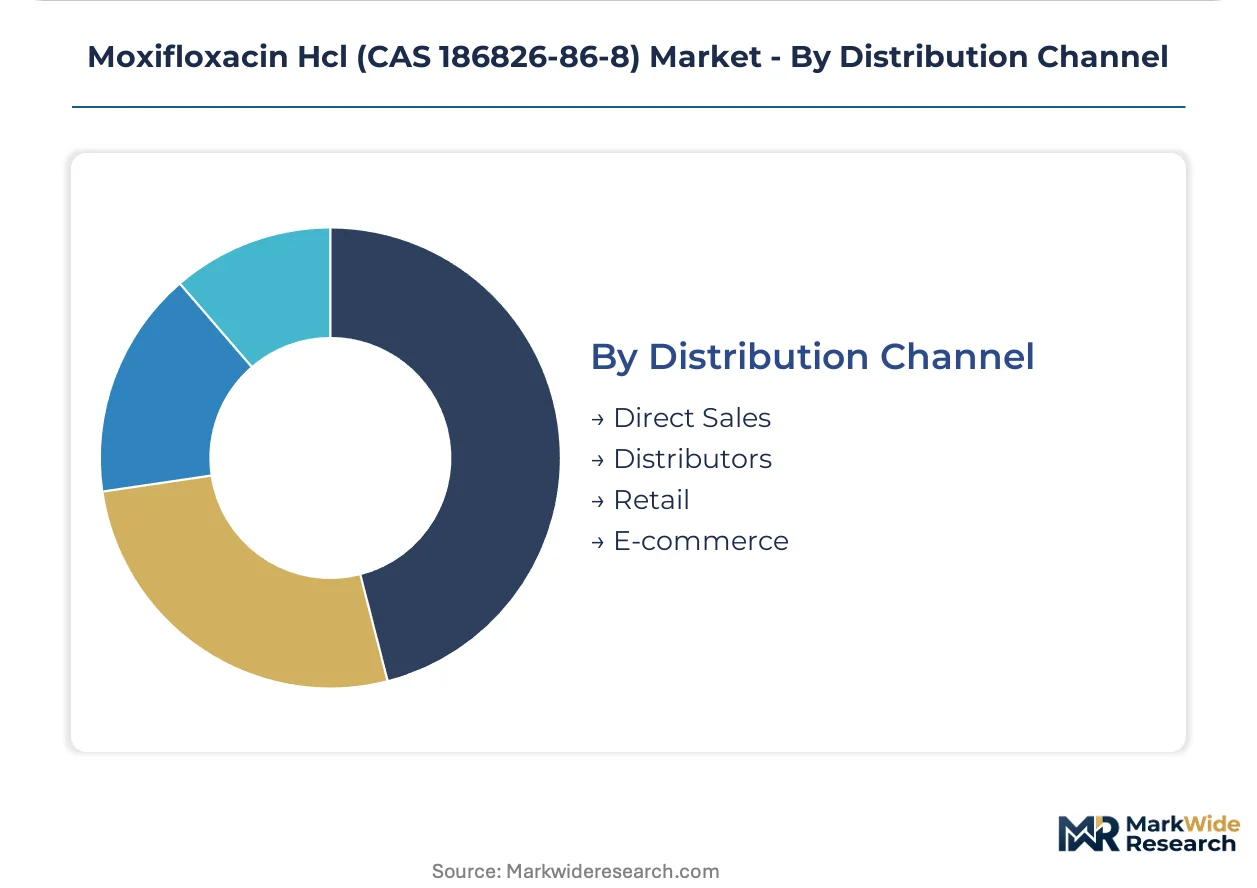
Distribution Channel:
Channel selection tracks customer scale and regulatory documentation intensity across markets.
- Direct Sales:Manufacturer-to-institution contracting for high-volume hospital systems and government tenders, eliminating intermediary margins while requiring dedicated account management and just-in-time logistics infrastructure. India's CDSCO-mandated traceability systems and China's NMPA drug coding requirements increase direct engagement complexity.
- Distributors:Wholesaler intermediaries providing inventory pooling, cold chain assurance, and credit terms for fragmented pharmacy and clinic accounts. McKesson, AmerisourceBergen, and Cardinal Health in the United States; Phoenix and Alliance Healthcare in Europe maintain category concentration.
- Retail:Brick-and-mortar pharmacy chain procurement with planogram compliance and promotional funding requirements. CVS Health, Walgreens Boots Alliance, and Rite Aid in the United States; Apollo Pharmacy and MedPlus in India structure oral formulation access.
- E-commerce:Online pharmacy platforms and B2B procurement portals with prescription verification workflows and last-mile delivery optimization. 1mg, Netmeds, and PharmEasy in India; Amazon Pharmacy and CVS.com in the United States expand share behind pandemic-accelerated digital adoption.
Distributors handle the majority of throughput; e-commerce is gaining share fastest on convenience positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for active pharmaceutical ingredients is redirecting capital toward domestic fermentation capacity, while China's NMPA accelerates environmental compliance audits across the Zhejiang API belt. Germany and the United States maintain the steepest regulatory barriers for injectable-grade certification.
United States
Hospital group purchasing organizations concentrate procurement authority under McKesson and Cardinal Health networks, compressing supplier margins while amplifying volume concentration. FDA batch certification requirements and 503B compounding pharmacy partnerships shape competitive access. The southeastern hospital systems, particularly in Florida and Georgia, anchor outpatient parenteral antimicrobial therapy expansion through IDN-owned specialty pharmacies.
Germany
EMA GMP inspections and nitrosamine risk assessment guidelines enforce the continent's most stringent API purity standards, privileging suppliers with retrospective batch validation capabilities. The Rhine-Ruhr industrial corridor hosts sterile formulation sites specializing in terminal sterilization validation for intravenous infusion products. Bavaria's tertiary referral centers drive prosthetic joint infection protocol demand through multidisciplinary infection services.
India
CDSCO purity escalation for fluoroquinolone salts filters out sub-scale producers, concentrating orders among certified fermentation specialists in Hyderabad and Ahmedabad. The Jan Aushadhi generic program and centralized drug procurement reshape oral formulation pricing structures. Maharashtra's API manufacturing clusters, particularly the Baddi-Barotiwala-Nalagarh belt, expand enzymatic synthesis adoption for quinolone core formation.
China
NMPA environmental compliance shutdowns in the Zhejiang manufacturing belt create single-point vulnerability for global supply, even as the Yangtze River Delta maintains cost advantages in multi-step organic synthesis. Dual carbon goals accelerate biocatalytic route investment to reduce solvent waste. The country's national pharmaceutical regulator enforces escalating local purity specifications that filter out non-compliant producers.
Brazil
ANVISA regulatory pathways for reference-standard partnerships remain underpenetrated, presenting first-mover positioning for manufacturers establishing local documentation capabilities. São Paulo's hospital systems and Rio de Janeiro's public health infrastructure drive concentrated demand for respiratory infection protocols. The southeastern manufacturing corridor, particularly in Minas Gerais, develops limited domestic API finishing capacity for import substitution.
Moxifloxacin Hcl (CAS 186826-86-8) Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers, with hospital GPO aggregation and research-grade distribution representing distinct control points. The vendor base organizes around three strategic archetypes: integrated fermentation-to-API platforms, specialized antibiotic chemistry houses, and premium analytical-grade suppliers. Dominant competitive moves include asset-light contract manufacturing partnerships and continuous manufacturing platform retrofits.
Among integrated fermentation specialists, Pioneer Biotech exemplifies backward integration into bulk supply control, while Neuland Laboratories Ltd. occupies a position within specialized peptide and antibiotic chemistry expertise for regulated markets. Sigma-Aldrich anchors the premium analytical-grade tier for research and reference-standard applications. These three represent the competitive spectrum from bulk API cost structures to high-margin specialty positioning.
| Leading Market Players |
|---|
| Actavis UK |
| Cayman Pharmacy Groups |
| Pioneer Biotech |
| TECO land |
| BOC Sciences |
| Yutian Pharmaceutical |
| Nivika Chemo Pharma |
| Neuland Laboratories Ltd. |
| Sigma-Aldrich |
| Others |
Supply Flow & Price Mechanics
Zhejiang cluster environmental shutdown risk compresses margin buffers across API tiers while simultaneously forcing dual-sourcing investments that reshape supplier geography. This single-point vulnerability determines both the spread between FDA-certified and uncertified material and the migration of fermentation capacity toward India and Brazil.
Pricing Analysis
Certification level (FDA-grade versus regional-standard) creates the primary spread between injectable and oral solid pricing tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by batch certification documentation and sterility validation depth. Cost compression in the economy tier is intensifying because India's Jan Aushadhi program and China's volume-based procurement reset reference prices quarterly. Hospital GPOs demonstrate lowest price sensitivity due to critical-care formulary lock-in, while independent retail pharmacies face margin erosion from e-commerce platform undercutting.
Supply Chain Analysis
Extended payment terms from 60 to 90 days among Indian CMOs are straining working capital for mid-tier fermentation specialists. API production concentrates in China, India, and Germany, with sterile finishing capacity anchored in the Rhine-Ruhr corridor and Hyderabad. Piperazine and cyclopropylamine feedstocks draw from petrochemical derivatives subject to energy price volatility. Single-source vulnerability in the Zhejiang manufacturing belt threatens global injectable supply continuity. Distribution runs through regional GPO networks in the United States and NHS trust procurement in the United Kingdom, with direct manufacturer contracting gaining share in high-volume hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Injectable moxifloxacin HCl procurement is consolidating into service-attach models where 503B compounding partnerships and just-in-time logistics command premium positioning above commodity API supply. Analytical method transfer and retrospective batch validation services are expanding faster than bulk fermentation throughput.
For Market Incumbents: Harden dual-standard compliance infrastructure to defend against enzymatic synthesis specialists capturing share through shortened cycle times. Pioneer Biotech and Neuland Laboratories Ltd. should expand sterile formulation partnerships in Germany and Italy before EMA nitrosamine guidelines tighten further. Backward integration into piperazine feedstock hedges margin exposure from petrochemical volatility. For New Entrants and Emerging Players: Brazil's ANVISA reference-standard pathway offers first-mover positioning for manufacturers establishing local documentation capabilities. Ophthalmic solution demand in ambulatory surgical centers presents the most penetrable segment given ASC certification requirements filter out incumbent bulk suppliers. Target 503B pharmacy networks in the southeastern United States with stability-validated packaging for outpatient parenteral antimicrobial therapy. For Investors and Strategic Acquirers: EMA's revised nitrosamine risk assessment guidelines reshape the acquisition landscape toward targets with retrospective batch validation capabilities and purge factor documentation. Fermentation-to-API platforms with CDSCO certification offer durable positioning across the analysis window. Monitor FDA warning letter issuance rates as the inflection indicator for supply consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Retrofit | Plug-flow reactor adoption at Indian CMOs collapses batch-scale economics without greenfield investment. |
| Dual FDA-EMA Certification Investment | Simultaneous compliance unlocks transatlantic hospital GPO access and compresses competitor field. |
| Enzymatic Synthesis Route Development | Biocatalytic quinolone core formation reduces solvent waste and shortens commercial cycle times. |
| 503B Compounding Pharmacy Partnership | IDN-owned specialty pharmacies capture outpatient parenteral antimicrobial therapy volumes in the southeastern United States. |
| Brazil ANVISA Reference-Standard Pathway | Underpenetrated Latin American markets reward early local documentation capability establishment. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA GMP inspection records, CDSCO regulatory circulars, and hospital procurement databases. Interviews with fermentation plant managers, regulatory affairs leads at API manufacturers, hospital pharmacy and therapeutics committee members, and GPO contracts managers inform supply-side and demand-side validation. Bottom-up volume modeling triangulates against top-down market sizing from customs trade data and SEC 10-K segment disclosures.
Forecast inputs include therapy area segmentation by infection type, formulation hierarchy from oral solid to sterile injectable, and end-user procurement authority distribution across hospitals, pharmacies, clinics, and homecare. Dosage form, administration route, and regional regulatory cluster dimensions structure the analytical framework. CAGRs derive from regression against historical volume trajectories and elasticity estimates from pricing event studies. NMPA environmental enforcement intensity and WHO antimicrobial stewardship protocol adoption pace serve as scenario-weighting variables.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-supported fermentation platforms or accelerated FDA generic approval timelines would shift outcomes. Macroeconomic deviation in petrochemical feedstock pricing, regulatory divergence between USP and EP monograph updates, or technological breakthrough in continuous flow chemistry scale-up would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Piperacillin Sodium API Market
Pharmaceutical Ingredients
Scopolamine Market
Pharmaceutical Ingredients
Large Molecule Drug Substance CDMO Market
Pharmaceutical Ingredients
Pharmaceutical Thermal Analysis Market
Pharmaceutical Ingredients
Flurbiprofen Market
Pharmaceutical Ingredients
Vitamins and Derivatives Market
Pharmaceutical Ingredients
Pharmaceutical Grade Magnesium Hydroxide Market
Pharmaceutical Ingredients
Growth Hormone Inhibiting Hormone Drugs Market
Pharmaceutical Ingredients
Cetrorelix Acetate API Market
Pharmaceutical Ingredients
Cox 2 Inhibitors Market
Pharmaceutical Ingredients
Amphetamine Drug Market
Pharmaceutical Ingredients
Calcium Citrate Market
Pharmaceutical Ingredients
Pharma Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market
Pharmaceutical Ingredients
Antibiotics Active Pharmaceutical Ingredient (API) Market
Pharmaceutical Ingredients
Pharmaceutical Grade Beta-Alanine Market