
 Citicoline Market | 2026-2036
Citicoline Market Size, Share, and Industry Trends Forecast 2026-2036
Citicoline Market Analysis
Pharmaceutical-grade citicoline is rotating toward higher-purity specifications as clinicians demand batch-consistent bioavailability for neuroprotective protocols. Kyowa Hakko Bio Co., Ltd. leverages its fermentation-derived manufacturing base to sustain supply security for injectable formulations. GRUPO FERRER INTERNACIONAL, S.A. anchors European hospital procurement through its established neurology portfolio. Doctor's Best, Inc. competes in direct-to-consumer channels with capsule formats targeting cognitive wellness segments.
Citicoline is a choline-containing phospholipid precursor synthesized through enzymatic phosphorylation of choline, yielding a compound that crosses the blood-brain barrier to support phosphatidylcholine synthesis and acetylcholine production. Its primary commercial purpose centers on neuroprotection and membrane repair in acute cerebrovascular events and chronic neurodegenerative conditions. The application dimension shows stroke recovery commanding the largest revenue pool while Alzheimer's Disease represents the fastest-expanding indication as biomarker-based early diagnosis spreads. Formulation technology is splitting sharply between conventional release formats dominating volume and liposomal delivery systems capturing premium pricing in research-intensive settings.
The FDA cGMP framework and the EMA's MDR pathway for neuroprotective agents are elevating documentation burdens for citicoline suppliers seeking clinical-channel access. India's CDSCO and Japan's PMDA maintain divergent bioequivalence standards that fragment registration strategies for multinational manufacturers. Stakeholders must monitor evolving pharmacovigilance requirements for nootropic compounds as regulators tighten post-market surveillance expectations.
Market Dynamics
Pharmaceutical-grade citicoline supply chains are compressing toward fermentation-derived manufacturing as batch-consistent bioavailability becomes non-negotiable for neurology clinics managing stroke recovery protocols. This concentration is forcing formulation specialists to secure captive supply agreements or risk exclusion from hospital procurement networks.
Growth Catalysts
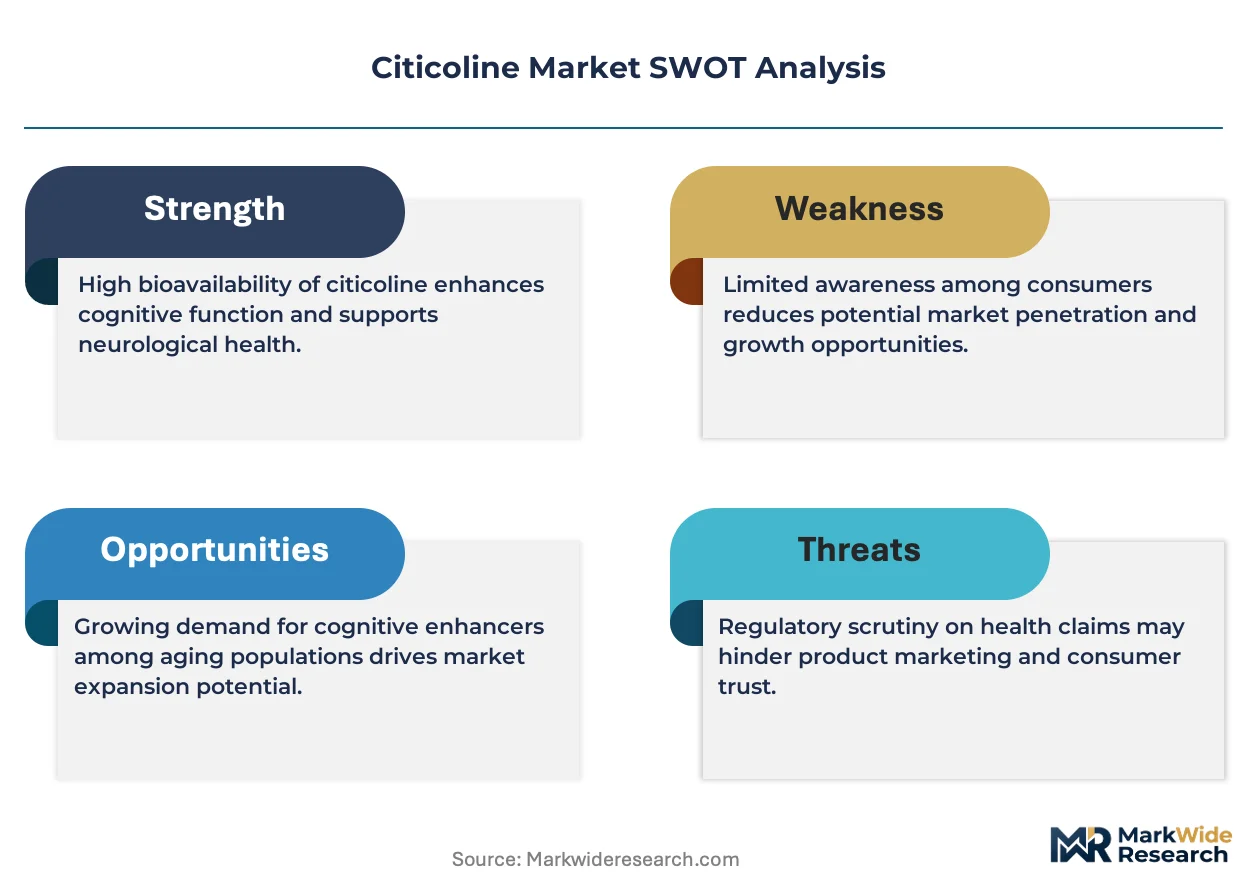
- FDA cGMP Enforcement:The FDA's tightening purity thresholds for choline-derived nootropics is accelerating quality upgrades across domestic manufacturing facilities, creating competitive separation between certified and uncertified suppliers.
- Geriatric Care Expansion:United States-based long-term care facilities are building dedicated cognitive disorder treatment wings, generating institutional demand for injectable citicoline formulations with documented neuroprotective efficacy.
- Biomarker-Based Diagnosis:Alzheimer's Disease screening protocols using cerebrospinal fluid biomarkers are expanding addressable patient populations for early-intervention citicoline therapy in neurology practices.
Market Restraints
- Choline Feedstock Volatility:Crude choline chloride prices fluctuate with agrochemical demand cycles, compressing margins for non-integrated citicoline manufacturers lacking backward integration into phospholipid precursors.
- EMA MDR Documentation Burden:The European Medicines Agency's Medical Device Regulation pathway for neuroprotective agents imposes clinical-efficacy documentation requirements that extend registration timelines by 18-24 months for new market entrants.
- Generic Piracetam Substitution:Cost-conscious hospital pharmacy committees in emerging markets continue favoring established racetam nootropics over citicoline for non-acute cognitive support, limiting volume penetration.
Strategic Opportunities
- Liposomal Delivery Systems:Nanoscale phospholipid encapsulation technology is opening premium pricing tiers in research-intensive academic medical centers seeking enhanced blood-brain barrier penetration for neurodegenerative trials.
- India CDSCO Registration:India's divergent bioequivalence standards create first-mover advantages for manufacturers establishing local fermentation capacity ahead of multinational competitors.
- Direct-to-Consumer Subscription:Telehealth-integrated cognitive wellness platforms are bypassing traditional pharmacy distribution for capsule-format citicoline, capturing lifetime value through automated replenishment models.
Industry Challenges
- Fermentation Scale-Up Expertise:Pharmaceutical-grade citicoline production requires rare microbial biochemistry specialists capable of optimizing enzymatic phosphorylation yields at commercial scale.
- Post-Market Surveillance Compliance:Evolving pharmacovigilance requirements for nootropic compounds demand dedicated adverse-event monitoring infrastructure that mid-cap suppliers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citicoline Market |
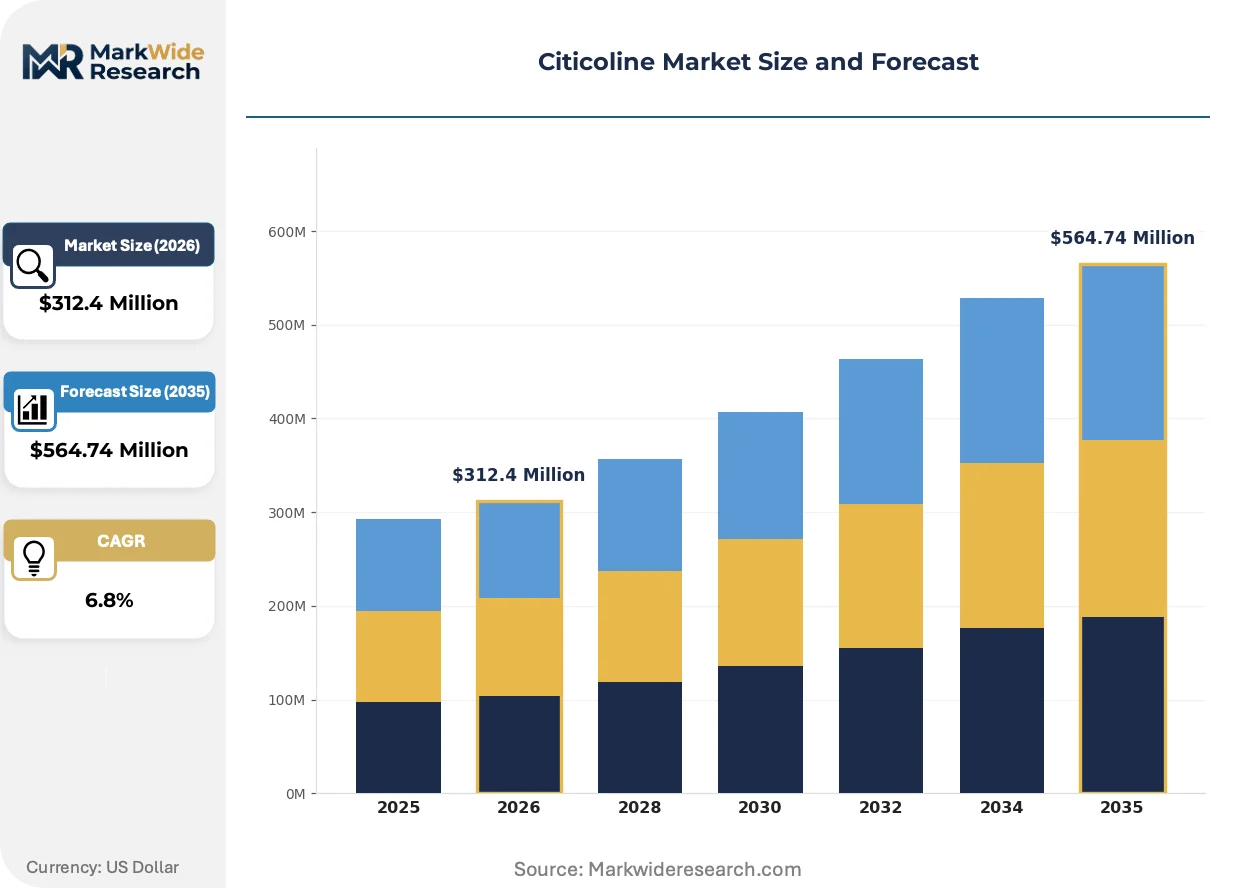
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Tablet, Liquid, Injection Application: Cognitive Disorders, Stroke Recovery, Traumatic Brain Injury, Alzheimer's Disease, Parkinson's Disease End User: Neurology Clinics, Rehabilitation Centers, Geriatric Care Facilities, Research Institutes Formulation Technology: Conventional Release, Sustained Release, Liposomal, Microencapsulation, Nanoparticle-Based |
| Companies Covered | GRUPO FERRER INTERNACIONAL, S.A., Doctor's Best, Inc., Kyowa Hakko Bio Co., Ltd., Rakshit Pharmaceuticals Limited, CTX Lifesciences, Jarrow Formulas, Inc., GNC Holdings, Inc., Union Korea Pharm, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citicoline Market Emerging Trajectories
Fermentation-derived manufacturing methods are actively displacing chemical synthesis as the dominant production paradigm, while regulatory documentation burdens and channel fragmentation are simultaneously reshaping competitive positioning across supply tiers.
Liposomal encapsulation technology is supplanting conventional immediate-release formulations in premium neuroprotective applications. Academic medical centers conducting Alzheimer's Disease trials are adopting phospholipid-encapsulated citicoline to enhance bioavailability metrics. This shift is compressing addressable margins for standard capsule manufacturers while concentrating research-channel supply relationships with fermentation-integrated specialists possessing nanoscale formulation capabilities.
The EMA's Medical Device Regulation pathway is elevating clinical-efficacy documentation requirements for neuroprotective agents seeking European hospital procurement access. Manufacturers must now submit randomized-controlled-trial data packages that previously sufficed with pharmacokinetic studies alone. German and French neurology clinics are responding by consolidating supplier relationships toward established pharmaceutical-grade producers with existing MDR-compliant dossiers.
Hospital pharmacy committees are unbundling cognitive-support procurement from bundled neurology service contracts, creating standalone tender processes for citicoline and competing nootropics. This disintermediation is compressing pricing power for traditional neurology portfolio suppliers while enabling pure-play citicoline specialists to compete on unit-economics transparency. The United States geriatric care sector exhibits this pattern most visibly, with long-term care facilities establishing independent formularies separate from acute-care hospital networks.
Citicoline Market Segmentation
Citicoline's therapeutic versatility fragments demand across five distinct formulation technologies and four clinical end-user channels. Understanding margin concentration within each dimension separates supply strategies optimized for hospital procurement from those targeting direct-to-consumer wellness platforms.
Product Type:
Margin pools concentrate in sterile injectable formats demanded by acute neurology settings, while oral solid dosage forms compete on manufacturing scale.
- Injection:Sterile parenteral citicoline commands premium positioning in stroke recovery protocols where rapid bioavailability determines clinical outcomes. United States geriatric care facilities specify this format for neuroprotective loading doses in acute cerebrovascular events.
- Capsule:Hard gelatin encapsulation dominates direct-to-consumer cognitive wellness channels with standardized dosing convenience. Telehealth-integrated subscription platforms are rotating volume toward this format as automated replenishment models capture lifetime value.
- Tablet:Compressed oral solids serve cost-sensitive institutional formularies with extended shelf stability and simplified logistics.
- Powder:Bulk active pharmaceutical ingredient supplies compounding pharmacies and research-intensive formulation development programs.
- Liquid:Oral solution formats address pediatric and dysphagia patient populations in rehabilitation center protocols.
Injection holds installed capacity. Capsule is rotating up the share rankings.
Application:
Volume distribution tracks the epidemiological burden of cerebrovascular disease, while pipeline development concentrates on neurodegenerative indications with biomarker-validated early intervention windows.
- Stroke Recovery:Acute and subacute cerebrovascular protocols represent the largest revenue concentration, with citicoline supporting membrane phospholipid resynthesis during the critical neuroplasticity window. United States neurology clinics embed this application in standardized order sets.
- Alzheimer's Disease:Early-intervention protocols using cerebrospinal fluid biomarker screening are expanding addressable populations for membrane-stabilizing therapy. Academic medical centers are gaining share fastest in this indication through trial participation requirements.
- Cognitive Disorders:Broad-spectrum mild cognitive impairment management spans geriatric care facility formularies and outpatient neurology practices.
- Traumatic Brain Injury:Military and sports medicine rehabilitation centers specify citicoline for axonal membrane repair protocols.
- Parkinson's Disease:Adjunctive dopaminergic neuron support applications remain research-phase with limited commercial penetration.
Stroke Recovery anchors current procurement volumes. Alzheimer's Disease is climbing the fastest.
End User:
Channel access requirements fragment supply relationships, with institutional credentialing demanding pharmaceutical-grade documentation and direct-to-consumer platforms prioritizing brand positioning.
- Neurology Clinics:Specialized outpatient practices manage chronic neurodegenerative conditions with prescription-grade citicoline protocols requiring batch-consistent bioavailability documentation.
- Geriatric Care Facilities:United States long-term care institutions are building dedicated cognitive disorder treatment wings with independent formularies separate from acute-care networks.
- Rehabilitation Centers:Post-acute stroke and traumatic brain injury recovery programs specify injectable formats in bundled payment arrangements.
- Research Institutes:Academic medical centers conducting Alzheimer's Disease trials drive adoption of liposomal delivery systems for enhanced blood-brain barrier penetration metrics.
Neurology Clinics maintain established purchasing relationships. Geriatric Care Facilities are gaining procurement autonomy fastest.
Formulation Technology:
Technology differentiation separates premium research-channel supply from commodity oral dosage manufacturing, with nanoscale encapsulation capturing pricing power in biomarker-driven trial settings.
- Liposomal:Phospholipid bilayer encapsulation enhances blood-brain barrier penetration for neurodegenerative research applications. Academic medical centers specify this technology for Alzheimer's Disease biomarker-validation studies.
- Conventional Release:Immediate-release oral and parenteral formats dominate volume through established manufacturing infrastructure and regulatory familiarity. Hospital pharmacy committees default to this tier for cost-containment in standard neuroprotective protocols.
- Sustained Release:Modified-release matrix systems extend dosing intervals for outpatient cognitive disorder management.
- Microencapsulation:Polymer-coated particles improve stability in combination formulations and tropical climate distribution.
- Nanoparticle-Based:Sub-100nm delivery systems target mitochondrial uptake mechanisms in preclinical neuroprotection research.
Conventional Release holds manufacturing scale. Liposomal is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation-derived citicoline production clusters in East Asia and Western Europe, with demand fragmentation pulling supply relationships toward United States geriatric care networks and Indian pharmaceutical manufacturing zones.
United States
Geriatric care facilities in Florida and Arizona are constructing dedicated cognitive disorder treatment wings with independent formularies. The FDA's cGMP enforcement tightens purity documentation for choline-derived nootropics entering institutional channels. Boston's academic medical centers drive liposomal formulation adoption for Alzheimer's Disease biomarker-validation trials.
Japan
PMDA bioequivalence standards for neuroprotective agents sustain premium positioning for domestic fermentation-derived citicoline in neurology clinics. METI's pharmaceutical manufacturing incentives support scale-up investments in Kanto region production facilities. Tokyo's specialized outpatient practices embed citicoline in standardized stroke recovery order sets.
Germany
EMA MDR documentation requirements extend registration timelines for neuroprotective agents seeking hospital procurement access. German neurology clinics consolidate supplier relationships toward established pharmaceutical-grade producers with compliant dossiers. Bavaria's research-intensive medical centers specify liposomal delivery systems for enhanced blood-brain barrier penetration studies.
India
CDSCO's divergent bioequivalence standards create first-mover advantages for manufacturers establishing local fermentation capacity ahead of multinational competitors. Maharashtra's pharmaceutical manufacturing belt attracts citicoline API production investments targeting export markets. Mumbai's contract research organizations manage pharmacovigilance infrastructure for mid-cap suppliers.
Switzerland
Swissmedic's neuroprotective agent pathway maintains rigorous clinical-efficacy documentation requirements that filter market entrants. Basel's pharmaceutical cluster hosts formulation specialists developing nanoscale encapsulation technologies. Geneva's academic hospitals participate in multinational Alzheimer's Disease trials requiring batch-consistent bioavailability metrics.
Citicoline Market Vendor Landscape
Concentration sits with fermentation-integrated specialists possessing pharmaceutical-grade documentation capabilities and hospital procurement relationships. Three tiers fragment the supply base: premium research-channel suppliers with liposomal formulation technology, mid-scale institutional suppliers serving neurology clinics, and direct-to-consumer capsule manufacturers competing on brand positioning. Competitive moves center on captive supply agreements with choline feedstock producers and technology licensing for nanoscale delivery systems.
Among Japan-based fermentation specialists, Kyowa Hakko Bio Co., Ltd. exemplifies the integrated production archetype with enzymatic phosphorylation expertise. Within the European hospital procurement tier, GRUPO FERRER INTERNACIONAL, S.A. occupies a position anchored to neurology portfolio relationships. At the direct-to-consumer vector, Doctor's Best, Inc. represents subscription-platform distribution models targeting cognitive wellness segments.
| Leading Market Players |
|---|
| GRUPO FERRER INTERNACIONAL, S.A. |
| Doctor's Best, Inc. |
| Kyowa Hakko Bio Co., Ltd. |
| Rakshit Pharmaceuticals Limited |
| CTX Lifesciences |
| Jarrow Formulas, Inc. |
| GNC Holdings, Inc. |
| Union Korea Pharm |
| Merck KGaA |
| Others |
Supply Flow & Price Mechanics
FDA cGMP certification gates both supply qualification and price differentiation simultaneously, separating pharmaceutical-grade citicoline suppliers into distinct procurement tiers based on batch-consistent bioavailability documentation. Hospital pharmacy committees in the United States pay premiums for injectable formats with verified purity thresholds, while direct-to-consumer capsule manufacturers compete on brand positioning without institutional credentialing burdens.
Pricing Analysis
FDA cGMP dictates the pricing tier structure across the citicoline market, with certified pharmaceutical-grade injectables commanding premium positioning against uncertified dietary supplement alternatives. Price differentiation rests on fermentation-derived purity grades and documented bioequivalence standards, with stroke recovery protocols in neurology clinics showing lowest price sensitivity due to clinical outcome dependencies. Pricing pressure stems from generic piracetam substitution in emerging market hospital formularies, compressing margins for non-specialized oral dosage manufacturers lacking neuroprotective efficacy dossiers.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes disrupt choline feedstock deliveries to non-integrated citicoline manufacturers, amplifying working capital requirements for spot-market raw material procurement. Geographic supply concentration centers on Japan, India, and Switzerland, where fermentation expertise and regulatory documentation capabilities cluster. Raw material dependencies draw from crude choline chloride, phospholipid precursors, and microbial bioculture stocks. Single-source vulnerability runs through captive fermentation capacity controlled by integrated specialists. Distribution runs through hospital procurement networks, direct-to-consumer subscription platforms, and research institute supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liposomal encapsulation technology disrupts conventional formulation economics, creating premium pricing tiers as academic medical centers demand enhanced blood-brain barrier penetration for Alzheimer's Disease biomarker-validation trials.
For Market Incumbents: Compound defensive positioning by securing captive supply agreements with choline feedstock producers and accelerating MDR-compliant dossier investments ahead of EMA documentation deadline compressions. Kyowa Hakko Bio's fermentation-integrated model demonstrates how backward integration into phospholipid precursors insulates margin structures from agrochemical demand cycle volatility. Priority levers include nanoscale formulation capability acquisition and geriatric care facility formulary pre-approval programs. For New Entrants and Emerging Players: CDSCO fast-track registration in India creates first-mover positioning ahead of multinational competitors establishing local fermentation capacity. Target the direct-to-consumer cognitive wellness segment through telehealth-integrated subscription platforms, where automated replenishment models capture lifetime value without hospital procurement credentialing requirements. Liposomal delivery system licensing from Swiss nanoscale encapsulation specialists accelerates research-channel access. For Investors and Strategic Acquirers: EMA MDR pathway implementation reshapes the acquisition landscape toward established pharmaceutical-grade producers with compliant neuroprotective agent dossiers. Five-to-ten-year viability favors fermentation-integrated specialists possessing enzymatic phosphorylation expertise and hospital procurement relationships. Acquisition target archetype: mid-cap manufacturers with CDSCO registration progress and liposomal formulation development partnerships. Signal to monitor: biomarker-based Alzheimer's Disease screening protocol adoption rates in United States neurology practices.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Captive enzymatic phosphorylation production secures supply security for injectable neuroprotective formulations. |
| Liposomal Formulation Licensing | Phospholipid encapsulation technology opens premium pricing tiers in academic medical center research channels. |
| CDSCO Registration Fast-Track | India's divergent bioequivalence standards create first-mover manufacturing advantages for export market access. |
| Geriatric Care Formulary Partnership | Independent long-term care facility procurement networks bypass acute-care hospital pharmacy committee gatekeeping. |
| Choline Feedstock Backward Integration | Upstream phospholipid precursor control insulates margin compression from agrochemical demand cycle volatility. |
Methodological Framework
Operator-level perspectives from neurology clinic directors, hospital pharmacy committee chairs, fermentation plant managers, and regulatory affairs specialists anchored the qualitative base for this citicoline market assessment. Primary fieldwork combined structured interviews with secondary validation against FDA cGMP inspection records, EMA MDR submission databases, CDSCO registration filings, and PMDA bioequivalence standards documentation. Bottom-up volume estimates triangulated against top-down pharmaceutical-grade production capacity assessments across Japan, India, and Western European manufacturing clusters.
Sensitivity analysis frameworks tested forecast robustness across formulation technology adoption scenarios and regulatory pathway timeline variations over the projection horizon. Segmentation modeling incorporated product type, application indication, end-user channel, and formulation technology dimensions, with Alzheimer's Disease biomarker-validation trial participation tracked as a demand inflection variable. CAGRs derived from pharmaceutical-grade volume growth trajectories in institutional channels and direct-to-consumer subscription platform expansion rates.
Underlying assumptions cover sustained FDA cGMP enforcement intensity, stable choline feedstock supply continuity, and geriatric care facility construction momentum in the United States, with deviation risk concentrated in EMA MDR documentation timeline extensions and generic piracetam substitution acceleration in emerging markets. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Antibiotics Active Pharmaceutical Ingredient (API) Market
Pharmaceutical Ingredients
Cox 2 Inhibitors Market
Pharmaceutical Ingredients
Pharma Grade Ibuprofen API Market
Pharmaceutical Ingredients
Active Ingredients Market
Pharmaceutical Ingredients
Global Tacrolimus Market
Pharmaceutical Ingredients
Penciclovir API Market
Pharmaceutical Ingredients
Kitasamycin Market
Pharmaceutical Ingredients
Global Antazoline Market
Pharmaceutical Ingredients
Chlorzoxazone Market
Pharmaceutical Ingredients
Anti-Allergic Agent Ingredients Market
Pharmaceutical Ingredients
Pharmaceutical Grade Beta-Alanine Market
Pharmaceutical Ingredients
Tranexamic Acid API Market
Pharmaceutical Ingredients
Asia-Pacific Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceutical Ingredients
Metformin Hydrochloride API Market
Pharmaceutical Ingredients
Synthetic Small Molecule API Market
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients (API) Market