
 Anti-Allergic Agent Ingredients Market | 2026-2036
Anti-Allergic Agent Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Allergic Agent Ingredients Market Insights
Project finance for dedicated API manufacturing facilities is reshaping competitive entry in the anti-allergic ingredient space. Sanofi leverages captive production of loratadine intermediates to secure supply continuity. GlaxoSmithKline plc anchors its position through backward integration into corticosteroid raw material synthesis. Novartis specializes in high-purity cetirizine base production for both proprietary and contract supply.
Anti-allergic agent ingredients comprise pharmacologically active compounds—principally H1-receptor antagonists, glucocorticoid derivatives, and leukotriene pathway modulators—synthesized to minimum purity thresholds of 99.5% and formulated for oral, parenteral, or topical drug delivery. These substances serve as the foundational inputs for prescription and over-the-counter therapeutics targeting histamine-mediated hypersensitivity responses. Antihistamines occupy the largest volume share among product types, reflecting their established efficacy profile and broad formulary inclusion across health systems. Corticosteroids command premium pricing tiers due to complex multi-step synthesis requirements and stringent impurity controls. Mast cell stabilizers represent the fastest-expanding category, driven by ophthalmic and respiratory formulation demand from pharmaceutical companies seeking alternatives to first-line antihistamine therapy.
FDA current good manufacturing practice enforcement and EMA REACH chemical safety registrations determine market access for ingredient suppliers serving regulated markets. India's CDSCO mandates site-specific manufacturing licenses for active pharmaceutical ingredients, while China's NMPA requires domestic registration of imported drug substances prior to formulation approval. Stakeholders must monitor evolving pharmacopeial monograph revisions and bioequivalence study requirements that determine which ingredient specifications qualify for commercial drug applications.
Market Dynamics
Pharmaceutical ingredient procurement is consolidating around captive manufacturing capabilities as FDA intensifies current good manufacturing practice enforcement and generic API suppliers face heightened purity threshold requirements for antihistamine and corticosteroid intermediates.
Growth Catalysts
- PLI scheme incentives:India's production-linked incentive program attracts bulk active pharmaceutical ingredient manufacturing to Hyderabad and Ahmedabad clusters, reducing import dependency for H1-receptor antagonist precursors.
- Ophthalmic formulation expansion:Mast cell stabilizer demand accelerates as pharmaceutical companies seek alternatives to first-line antihistamine therapy for allergic conjunctivitis.
- REACH chemical safety registrations:EMA compliance requirements create preferential market access for European ingredient suppliers meeting stringent impurity control standards.
Market Restraints
- Specialized solvent cost volatility:Multi-step corticosteroid synthesis depends on controlled-substance solvents subject to international scheduling restrictions and price instability.
- CDSCO site concentration:India's drug regulator mandates facility-specific manufacturing licenses that cluster production in Maharashtra and Gujarat, creating geographic supply vulnerability.
- Leukotriene pathway complexity:Synthetic routes for montelukast intermediates require chiral resolution capabilities unavailable at smaller API facilities.
Strategic Opportunities
- Brazilian generic expansion:ANVISA's accelerated approval pathways for locally manufactured antihistamines create first-mover advantage for ingredient suppliers establishing São Paulo technical partnerships.
- Continuous flow chemistry:Adoption of microreactor technology for exothermic nitration steps in cetirizine base production reduces batch cycle times and solvent waste.
- Respiratory combination therapies:Fixed-dose formulations pairing corticosteroids with long-acting beta-agonists drive demand for co-processed excipient systems.
Industry Challenges
- Analytical method transfer:Bioequivalence study requirements for ANDA submissions demand specialized impurity profiling capabilities that contract laboratories struggle to scale.
- Legacy equipment retrofitting:Stainless steel reactor fleets designed for batch antihistamine production require substantial capital expenditure to accommodate high-potency corticosteroid containment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Allergic Agent Ingredients Market |
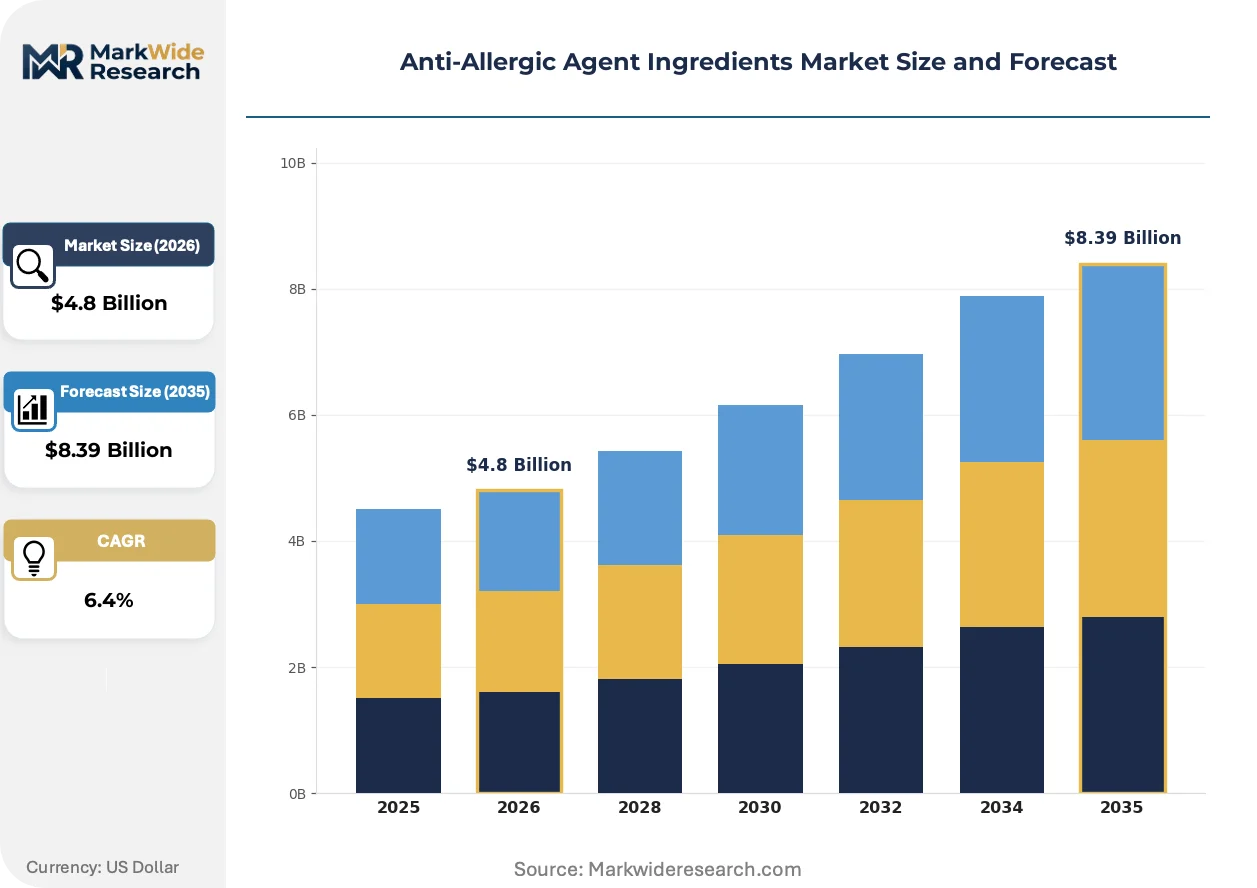
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Corticosteroids, Mast Cell Stabilizers, Leukotriene Receptor Antagonists Active Ingredient: Diphenhydramine, Loratadine, Cetirizine, Fexofenadine Formulation: Tablet, Liquid, Spray, Powder End User: Pharmaceutical Companies, Cosmetic Manufacturers, Healthcare Providers, Research Institutions |
| Companies Covered | Sanofi, GlaxoSmithKline plc, Novartis, Johnson & Johnson Services, Inc., F. Hoffmann-La Roche Ltd., STALLergenes Greer, ALK-Abelló A/S, Allergy Therapeutics, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Allergic Agent Ingredients Market Trends and Innovations
Process intensification and regulatory harmonization are compressing development timelines for anti-allergic APIs while reshaping competitive requirements for impurity specification and manufacturing scale.
Continuous manufacturing technology is migrating from pilot-scale demonstration to commercial antihistamine production. Mid-size API suppliers in India and China are retrofitting batch facilities with plug-flow reactors for loratadine intermediate synthesis. This shift is enabling real-time release testing and reducing hold times between synthesis steps.
EMA's revised nitrosamine impurity guidelines have triggered comprehensive risk assessments across all marketed antihistamine products. Pharmaceutical companies must now demonstrate absence of N-nitrosodimethylamine in cetirizine and fexofenadine batches through validated analytical methods. European formulation manufacturers are responding by demanding extended impurity data packages from ingredient suppliers.
Formulation companies are consolidating active ingredient suppliers to reduce qualification burden and audit frequency. Large generic manufacturers now maintain approved vendor lists of three or fewer API sources per therapeutic category. This concentration is most visible in the United States, where ANDA sponsors face compressed timelines for FDA pre-approval inspections and prioritize suppliers with established regulatory track records.
Anti-Allergic Agent Ingredients Market Segmentation
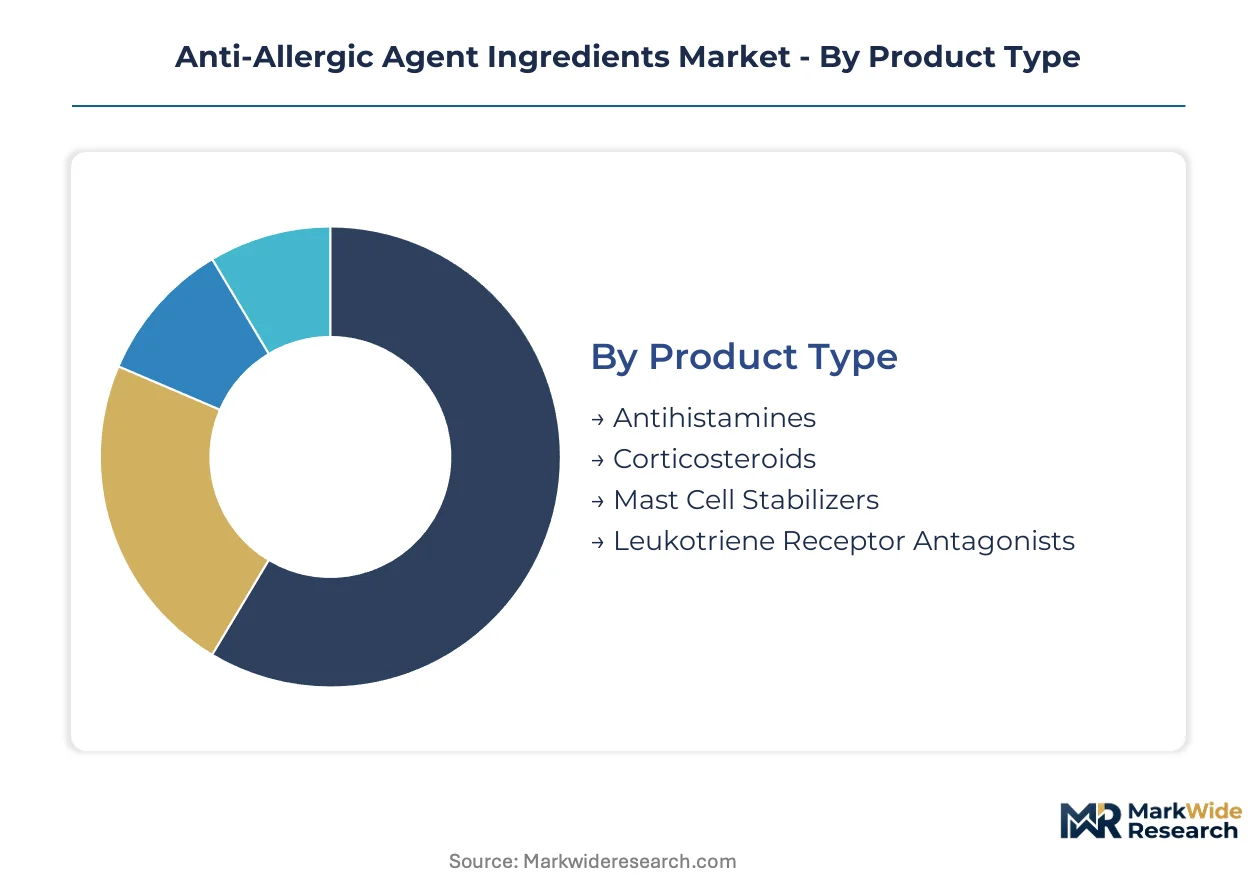
Ingredient specifications vary sharply across therapeutic applications, with purity thresholds, impurity profiles, and regulatory filing requirements determining supplier qualification. Pharmaceutical procurement teams segment active ingredients by synthesis complexity and end-use performance criteria rather than commodity characteristics alone.
Product Type:
Mature antihistamine chemistry coexists with emerging biologic pathways as formulation science advances.
- Antihistamines:H1-receptor antagonists synthesized to 99.5% minimum purity serve as the volume foundation for oral and parenteral allergy therapeutics. Procurement concentrates among Indian API manufacturers in Hyderabad and Ahmedabad clusters where CDSCO licensing and PLI scheme incentives have consolidated bulk production capacity for loratadine and cetirizine intermediates.
- Corticosteroids:Multi-step glucocorticoid derivatives demand complex chiral synthesis and stringent impurity controls that limit qualified supplier pools. European manufacturers leverage REACH-registered supply chains to meet EMA nitrosamine guideline requirements, commanding premium pricing tiers unavailable to standard antihistamine producers.
- Mast Cell Stabilizers:Cromolyn sodium and nedocromil derivatives for ophthalmic formulations.
- Leukotriene Receptor Antagonists:Montelukast and zafirlukast precursors requiring specialized chiral resolution capabilities.
Antihistamines handle the majority of throughput; mast cell stabilizers are the fastest mover on share.
Active Ingredient:
Cost tier stratification separates legacy generics from next-generation nonsedating alternatives.
- Diphenhydramine:First-generation ethanolamine derivative with established OTC distribution through mass retail channels.
- Loratadine:Second-generation piperidine antihistamine with proven cardiovascular safety profile and broad formulary inclusion.
- Cetirizine:Carboxylic acid metabolite of hydroxyzine produced through exothermic nitration steps now migrating to continuous flow microreactor platforms.
- Fexofenadine:Active metabolite of terfenadine commanding higher specification requirements for bioequivalence study submissions.
Cetirizine and loratadine dominate procurement volumes; fexofenadine exhibits the steepest expansion trajectory in prescription tier pricing.
Formulation:
Application requirements dictate physical property specifications from powder flowability to spray droplet distribution.
- Tablet:Compressed solid dosage forms requiring precise particle size distribution and excipient compatibility for high-speed rotary press operations.
- Liquid:Oral solutions and suspensions with dissolution stability requirements spanning multi-year shelf life claims.
- Spray:Nasal and ophthalmic delivery systems with critical droplet size parameters affecting mucosal deposition patterns.
- Powder:Inhalation and topical formulations demanding controlled agglomeration and moisture specifications.
Tablets retain the largest manufacturing throughput; spray formulations are climbing the fastest on share due to respiratory and ophthalmic expansion.
End User:
Customer type determines qualification burden, audit frequency, and contractual pricing structures.
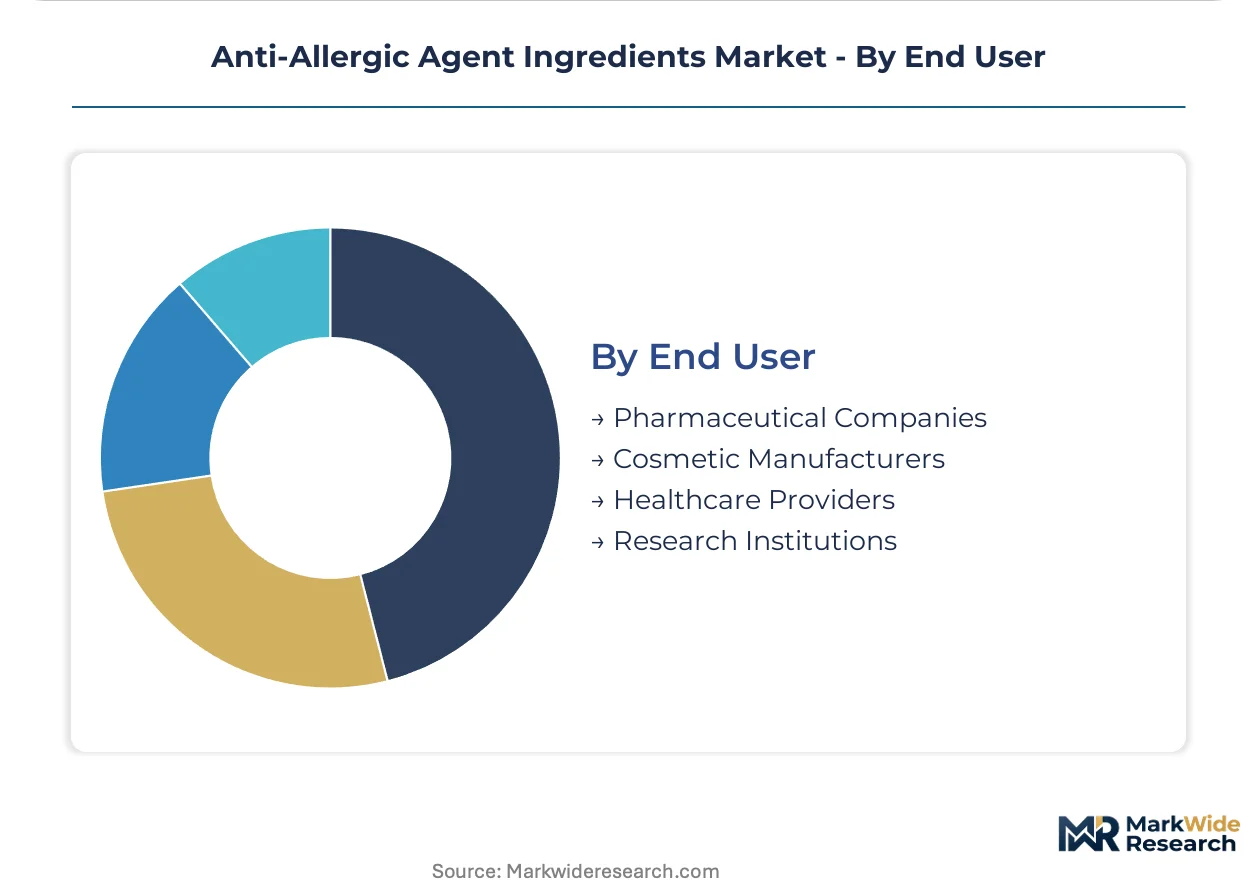
- Pharmaceutical Companies:Formulation manufacturers consolidating approved vendor lists to three or fewer API sources per therapeutic category to reduce qualification burden and FDA pre-approval inspection coordination.
- Cosmetic Manufacturers:Topical antihistamine incorporation into anti-irritant skincare formulations with lower purity thresholds than pharmaceutical applications.
- Healthcare Providers:Hospital system procurement of parenteral corticosteroid preparations for acute allergic response protocols.
- Research Institutions:Investigational compound supply for clinical trial material production and bioequivalence study requirements.
Pharmaceutical companies absorb the dominant procurement volume; cosmetic manufacturers are expanding most quickly as dermatological applications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme incentives and CDSCO licensing reforms are redrawing procurement geography for anti-allergic APIs. Regulatory pressure from FDA and EMA is forcing geographic diversification of qualified supplier bases.
United States
FDA pre-approval inspection backlogs are compressing ANDA timelines for generic antihistamine sponsors. The agency's intensified current good manufacturing practice enforcement is disqualifying overseas API suppliers from abbreviated new drug applications. New Jersey and North Carolina formulation clusters are absorbing higher qualification costs to secure domestic supply continuity.
India
Hyderabad and Ahmedabad manufacturing corridors are consolidating bulk cetirizine and loratadine intermediate production under PLI scheme subsidies. CDSCO facility inspections have accelerated since 2023, with Maharashtra and Gujarat license holders facing heightened purity threshold enforcement. The country's generic API export dominance is deepening through backward integration into H1-receptor antagonist precursors.
China
NMPA domestic registration requirements for imported drug substances are delaying European formulation approvals. Zhejiang and Jiangsu province chemical parks are retrofitting batch facilities for continuous flow microreactor platforms. The regulator's nitrosamine impurity risk assessments are forcing comprehensive revalidation of antihistamine synthesis routes.
Germany
EMA REACH chemical safety registrations are creating preferential market access for European corticosteroid ingredient suppliers. Bavaria and North Rhine-Westphalia pharmaceutical chemical clusters are leveraging stringent impurity control standards to command premium pricing tiers. ECHA's revised nitrosamine guidelines are driving extended analytical data package demands from formulation manufacturers.
Brazil
ANVISA accelerated approval pathways for locally manufactured antihistamines are attracting São Paulo technical partnerships from Indian API suppliers. The regulator's bioequivalence study requirements are narrowing qualified vendor lists for generic sponsors. Southeast region pharmaceutical manufacturing is expanding to reduce import dependency for allergic rhinitis therapeutics.
Anti-Allergic Agent Ingredients Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Consolidation is accelerating as formulation manufacturers reduce approved vendor lists to three or fewer API sources per therapeutic category. Strategic archetypes include captive vertically integrated pharmaceutical groups, independent Indian API specialists, and European REACH-registered chemical suppliers. Dominant competitive moves encompass backward integration into corticosteroid raw material synthesis and continuous flow chemistry licensing for exothermic nitration steps.
Among European-origin pharmaceutical groups, Sanofi, GlaxoSmithKline plc, and Novartis occupy positions exemplifying distinct strategic archetypes. Sanofi represents captive production specialization through in-house loratadine intermediate manufacturing. GlaxoSmithKline plc anchors the backward integration archetype with upstream control over corticosteroid synthesis pathways. Novartis sits within the high-purity contract supply tier, serving both proprietary and external formulation demand for cetirizine base production.
| Leading Market Players |
|---|
| Sanofi |
| GlaxoSmithKline plc |
| Novartis |
| Johnson & Johnson Services, Inc. |
| F. Hoffmann-La Roche Ltd. |
| STALLergenes Greer |
| ALK-Abelló A/S |
| Allergy Therapeutics |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Pricing and Supply Chain Analysis
Hyderabad and Ahmedabad manufacturing corridors concentrate bulk cetirizine and loratadine intermediate capacity, granting Indian API specialists substantial leverage over European and North American formulation manufacturers facing FDA pre-approval inspection backlogs. CDSCO licensing requirements and PLI scheme subsidies reinforce this geographic pricing power, while REACH-registered European corticosteroid suppliers command premium tiers through EMA nitrosamine compliance.
Pricing Analysis
Certification level creates the primary spread, with FDA-grade and EMA REACH-registered corticosteroid intermediates pricing at substantial premiums over standard antihistamine APIs. Three-tier pricing structure across premium, standard, and economy levels reflects synthesis complexity, chiral purity thresholds, and impurity control stringency. Cost compression in standard-grade loratadine intermediates is intensifying as Hyderabad cluster capacity expands under PLI incentives. Generic pharmaceutical manufacturers exhibit highest price sensitivity, while innovator companies prioritize supply continuity over unit economics.
Supply Chain Analysis
Specialized solvent feedstocks for corticosteroid multi-step synthesis draw from controlled-substance scheduling regimes, creating price volatility that propagates through glucocorticoid derivative supply chains. Raw material sourcing rests on piperidine precursors from India, nitration reagents from China, and chiral resolution catalysts from European specialty chemical producers. Single-source vulnerability concentrates in Maharashtra and Gujarat CDSCO-licensed facilities clustered around site-specific manufacturing mandates. Distribution runs through formulation manufacturer approved vendor lists consolidated to three or fewer API sources per therapeutic category.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as large generic pharmaceutical manufacturers reduce approved vendor lists to three or fewer API sources per therapeutic category, compressing supplier margins while elevating qualification barriers for new entrants.
For Market Incumbents: Entrench regulatory track records through accelerated FDA pre-approval inspection readiness and extended impurity data package capabilities. Deepen backward integration into H1-receptor antagonist precursors to defend against Hyderabad cluster capacity expansion. Prioritize continuous flow microreactor licensing for exothermic nitration steps to reduce batch cycle times and solvent waste exposure. For New Entrants and Emerging Players: Build out São Paulo technical partnerships to capture ANVISA accelerated approval pathway advantages for locally manufactured antihistamines. Target mast cell stabilizer ophthalmic formulations as the fastest-expanding category with lower incumbent saturation than oral antihistamines. Lead with bioequivalence study impurity profiling capabilities as a differentiated service layer. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors API specialists with demonstrated continuous manufacturing migration and established CDSCO regulatory track records. Long-term viability over the projection horizon rests on backward integration depth and EMA REACH registration breadth. Monitor FDA pre-approval inspection clearance rates as the inflection indicator for supplier qualification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Chemistry Adoption | Microreactor platforms for cetirizine nitration reduce solvent waste and enable real-time release testing at commercial scale. |
| Backward Integration into Precursors | Captive loratadine intermediate production secures supply continuity against Hyderabad cluster concentration risk. |
| EMA REACH Registration Expansion | Corticosteroid ingredient suppliers leverage stringent impurity controls to command premium pricing tiers in European markets. |
| CDSCO Facility Inspection Readiness | Accelerated licensing compliance in Maharashtra and Gujarat clusters maintains market access for Indian API exports. |
| ANVISA Technical Partnership Formation | São Paulo alliances position ingredient suppliers for accelerated generic antihistamine approval pathways in Brazil. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with API manufacturing executives, regulatory affairs directors, pharmaceutical procurement managers, and CDSCO compliance officers; and secondary validation through FDA filings, EMA REACH registrations, CDSCO facility inspection records, and PLI scheme beneficiary disclosures. Bottom-up capacity assessments across Hyderabad, Ahmedabad, Zhejiang, and Jiangsu manufacturing clusters were triangulated against top-down formulation manufacturer procurement surveys.
Forecast inputs considered product type segmentation across antihistamines, corticosteroids, mast cell stabilizers, and leukotriene receptor antagonists; formulation differentiation between tablet, liquid, spray, and powder delivery systems; and end-user stratification across pharmaceutical companies, cosmetic manufacturers, healthcare providers, and research institutions across the analysis window. CAGRs were derived from modeled volume-price interactions under varying regulatory enforcement scenarios and continuous manufacturing adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated pharmaceutical groups or state-subsidized Chinese API producers would shift outcomes beyond modeled ranges. Cross-checking against FDA ANDA approval timelines and EMA nitrosamine impurity guideline enforcement intensity is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Pharmaceutical Hot Melt Extrusion Market
Pharmaceutical Ingredients
Pharmaceutical Excipients for Taste Masking Market
Pharmaceutical Ingredients
Oral Doxycycline Hyclate Market
Pharmaceutical Ingredients
Germany Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Calcium Citrate Market
Pharmaceutical Ingredients
Global Antazoline Market
Pharmaceutical Ingredients
Pharma Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
Fosfomycin Trometamol Powder Market
Pharmaceutical Ingredients
Pharmaceutical Grade Hyaluronic Acid Market
Pharmaceutical Ingredients
Sterile Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Moxifloxacin Hcl (CAS 186826-86-8) Market
Pharmaceutical Ingredients
Glycylglycine Market
Pharmaceutical Ingredients
Small Molecule Drug Discovery Market
Pharmaceutical Ingredients
Calcium Gluconate Market
Pharmaceutical Ingredients
Chlorzoxazone Market
Pharmaceutical Ingredients
Flurbiprofen Market