
 Active Pharmaceutical Ingredient for Cancer Market | 2026-2036
Active Pharmaceutical Ingredient for Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Active Pharmaceutical Ingredient for Cancer Market Outlook
Specialty oncology clinics is unwinding the traditional hospital-centric procurement model for cancer APIs. Merck & Co., Inc. anchors its position through deep manufacturing scale in biologic active ingredients. Boehringer Ingelheim International GmbH differentiates via captive fermentation capacity for complex cytotoxic compounds. Bristol-Myers Squibb Company leads in immunotherapy API production, leveraging integrated cell-culture platforms.
Active pharmaceutical ingredient for cancer denotes the biologically active component in oncology therapeutics, synthesized through chemical synthesis, biotechnological fermentation, or semi-synthetic modification to achieve specified purity profiles and impurity thresholds. These ingredients serve as the therapeutic foundation in finished dosage forms, directly mediating cytotoxic, hormonal, targeted, or immune-modulating effects against malignant cells. Targeted therapies command premium margin pools due to patent-protected kinase inhibitors and monoclonal antibody constructs. Immunotherapies represent the fastest-expanding category, propelled by checkpoint inhibitor APIs and CAR-T cell therapy components. Cytotoxic agents retain volume leadership in generic markets, though price erosion compresses returns for commoditized platinum compounds and taxanes.
FDA oncology center guidelines, EMA GMP Annex 1 sterile manufacturing requirements, and ICH Q7 API GMP standards collectively elevate barrier-to-entry for new cancer API suppliers. Regulatory stringency around genotoxic impurity limits and containment classifications shapes capital deployment decisions for multi-purpose synthesis facilities. Stakeholders must monitor evolving biosimilar guidance and real-world evidence requirements that will determine substitution eligibility and pricing power for legacy molecules.
Market Dynamics
Oncology clinics are dismantling the hospital-centric procurement model for cancer APIs, with specialty pharmacy networks capturing distribution control and in-house compounding capabilities expanding across ambulatory care settings.
Growth Catalysts
- FDA Accelerated Approval Pathway:Compressed development timelines for oncology drugs reduce time-to-market for novel APIs, incentivizing R&D investment in breakthrough therapy candidates.
- Bioreactor Scale-Up Technologies:Single-use bioreactor systems enable flexible manufacturing of monoclonal antibody APIs, allowing contract manufacturers to serve fragmented biopharma demand without permanent infrastructure.
- Specialty Pharmacy Network Expansion:United States distribution channels concentrate procurement volume, creating dedicated API demand pools for oral oncology formulations.
Market Restraints
- Platinum Compound Price Erosion:Generic commoditization of cisplatin and carboplatin APIs compresses margins for manufacturers lacking differentiated synthesis capabilities.
- China API Concentration Risk:Bulk chemical intermediate supply concentrates in Zhejiang and Jiangsu provinces, exposing Western formulators to geopolitical supply disruptions.
- ICH Q7 GMP Compliance Burden:Stringent documentation and validation requirements for multi-purpose synthesis facilities elevate capital barriers for new market entrants.
Strategic Opportunities
- India CDMO Capacity:Contract development and manufacturing organizations in Hyderabad and Ahmedabad offer cost-competitive fermentation capacity for complex cytotoxic compounds.
- Continuous Flow Chemistry:Microreactor technology convergence with process analytical technology enables real-time quality control for high-potency API manufacturing.
- EMA PRIME Designation:Priority medicines scheme accelerates regulatory access for innovative cancer APIs targeting unmet medical needs in European markets.
Industry Challenges
- Containment Engineering Shortage:Qualified isolator and restricted access barrier system designers remain scarce, delaying facility commissioning for cytotoxic API production.
- Biosimilar Substitution Uncertainty:Evolving real-world evidence requirements from payers create pricing volatility for legacy monoclonal antibody APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Pharmaceutical Ingredient for Cancer Market |
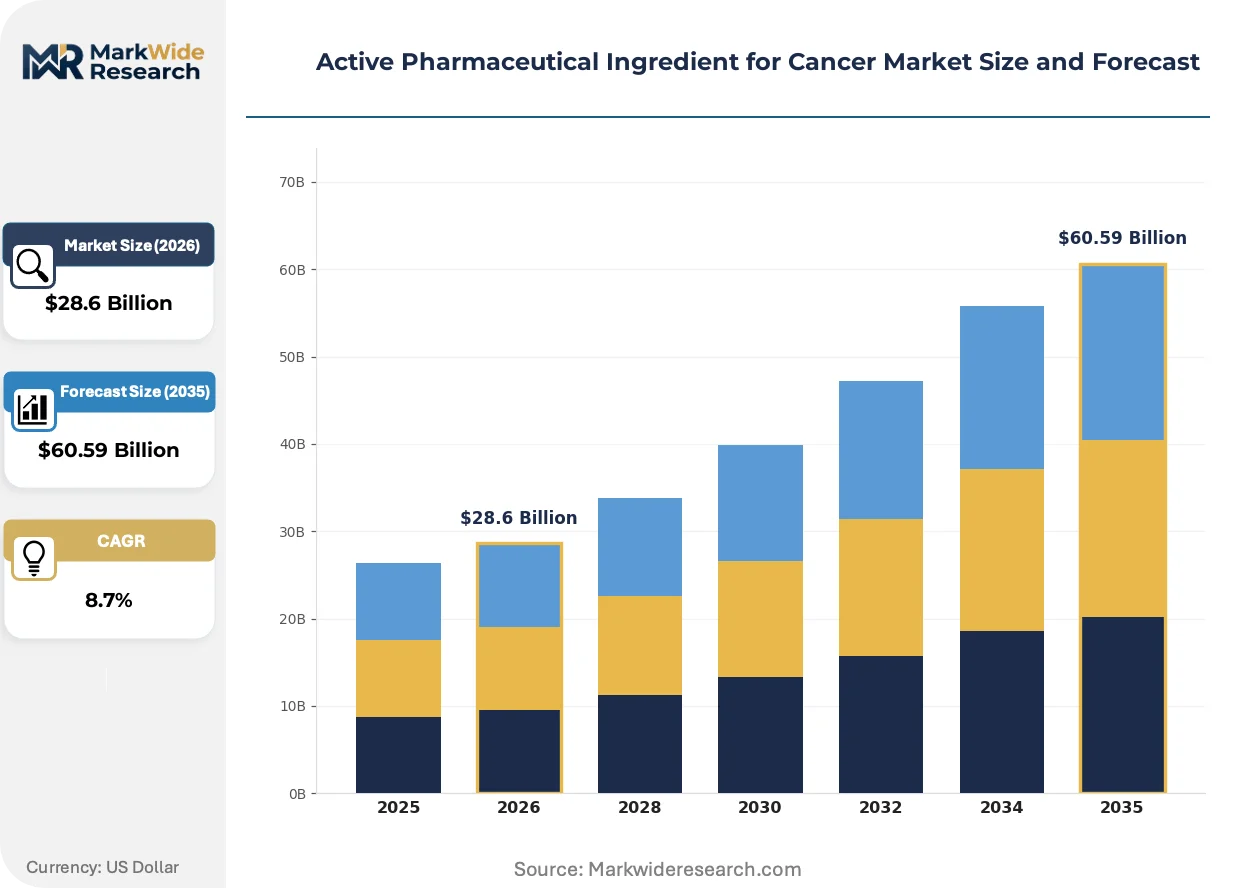
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cytotoxic Agents, Hormonal Therapies, Targeted Therapies, Immunotherapies Therapy Area: Breast Cancer, Lung Cancer, Leukemia, Colorectal Cancer Delivery Mode: Intravenous, Oral, Subcutaneous, Topical End User: Hospitals, Oncology Clinics, Research Laboratories, Pharmaceutical Companies |
| Companies Covered | AbbVie Inc, Cipla Inc, Teva Pharmaceutical Industries Ltd, Merck & Co., Inc, Boehringer Ingelheim International GmbH, Aurobindo Pharma, Sun Pharmaceutical Industries Ltd, Bristol-Myers Squibb Company, Dr. Reddy’s Laboratories Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Pharmaceutical Ingredient for Cancer Market Strategic Shifts
Manufacturing modality diversification is fragmenting competitive advantage across chemical synthesis, microbial fermentation, and mammalian cell culture, with technology selection now determining margin structure rather than scale alone.
Continuous manufacturing is supplanting batch processing for small-molecule oncology APIs. Mid-sized CDMOs in Switzerland and Germany are retrofitting legacy facilities with plug-and-play flow chemistry skids. This technology is compressing cycle times from weeks to days while reducing solvent waste and genotoxic impurity formation.
EMA GMP Annex 1 sterile manufacturing requirements are mandating isolator-based filling for parenteral oncology APIs. European formulators must validate closed-system processing or exit cytotoxic injectable markets. High-potency antibody-drug conjugate manufacturers in the Netherlands and Ireland are absorbing compliance costs through dedicated single-product facilities.
Direct-to-clinic API sourcing is eroding distributor intermediaries in United States oncology procurement. Hospital-affiliated specialty pharmacies now negotiate directly with API manufacturers for 503B compounding inputs. This channel compression concentrates buying power in integrated delivery networks across Texas, Florida, and California cancer centers.
Active Pharmaceutical Ingredient for Cancer Market Segmentation
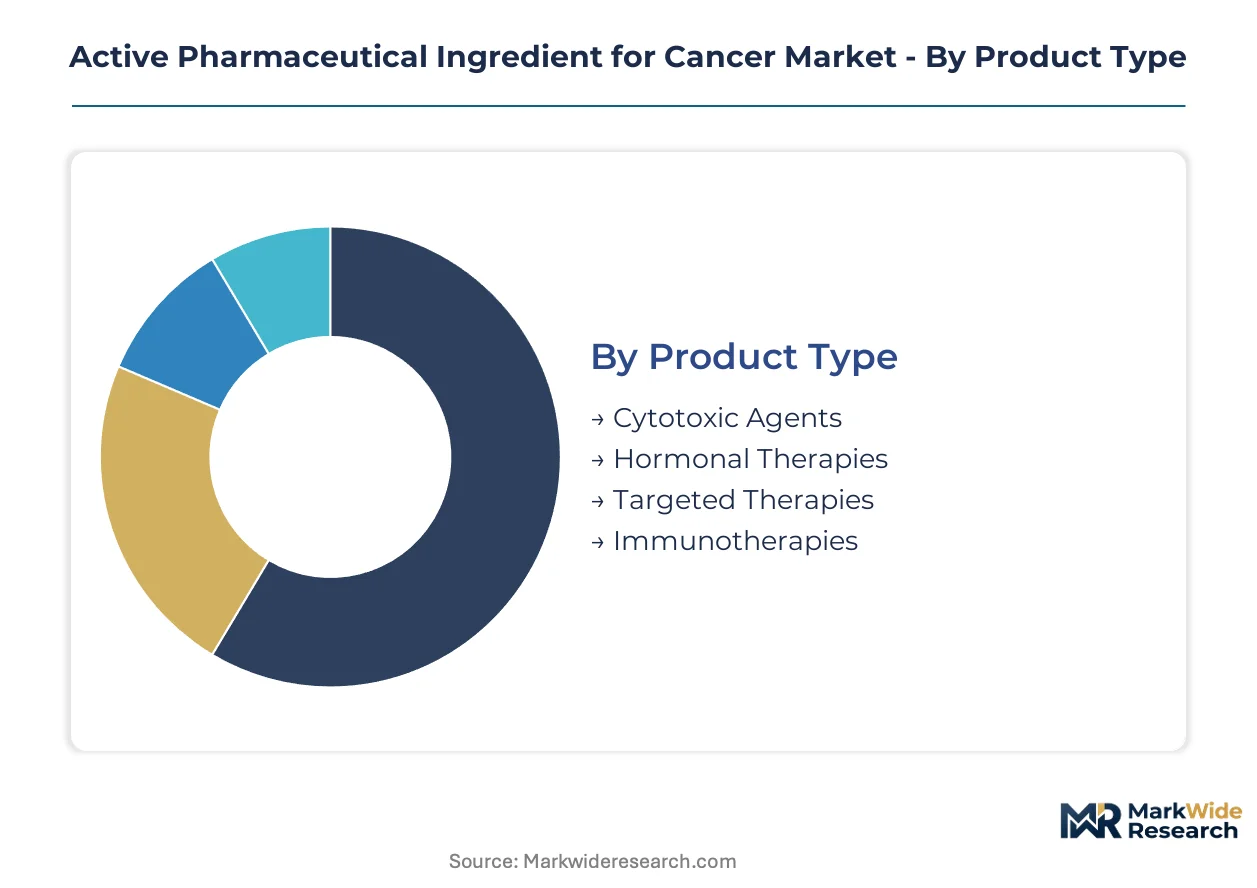
Segmentation in cancer APIs reveals how manufacturing complexity, clinical application, and distribution channel economics fragment competitive advantage. Each dimension carries distinct margin structures and regulatory burdens that shape supplier positioning.
Product Type:
Margin pools concentrate in patent-protected biologics and targeted small molecules, while commoditized cytotoxics compete on cost efficiency and captive fermentation scale.
- Targeted Therapies:Kinase inhibitors and monoclonal antibody constructs command premium pricing through validated biomarker selection. Demand clusters in United States specialty pharmacy networks where oral oncology dispensing concentrates procurement volume for BCR-ABL and EGFR inhibitors.
- Immunotherapies:Checkpoint inhibitor APIs and CAR-T cell therapy components require mammalian cell-culture platforms with integrated viral vector production. European EMA PRIME designation accelerates regulatory access for PD-1/PD-L1 programs, concentrating R&D investment in Netherlands and Ireland manufacturing clusters.
- Cytotoxic Agents:Platinum compounds and taxanes face generic price erosion across India and China bulk chemical suppliers.
- Hormonal Therapies:Aromatase inhibitors and anti-androgens serve stable maintenance protocols in breast and prostate cancer.
Targeted therapies hold installed capacity. Immunotherapies are rotating up the share rankings.
Therapy Area:
Volume distribution tracks epidemiology, but value concentration follows biomarker-driven segmentation and companion diagnostic penetration.
- Lung Cancer:EGFR, ALK, and KRAS mutation profiling fragments API demand across multiple targeted agents. United States academic medical centers drive adoption of next-generation tyrosine kinase inhibitors through tissue-agnostic trial designs.
- Breast Cancer:CDK4/6 inhibitors and HER2-directed therapies sustain multi-line treatment sequences. European formulators in Germany and Switzerland specialize in high-potency antibody-drug conjugate manufacturing for HER2-positive subsets.
- Leukemia:B-cell malignancies propel CAR-T API demand through dedicated apheresis collection networks.
- Colorectal Cancer:Anti-EGFR and anti-VEGF biologics face biosimilar substitution pressure in mature markets.
Lung cancer leads absolute volume. Breast cancer maintains the steepest expansion trajectory through targeted therapy uptake.
Delivery Mode:
Route of administration determines sterile manufacturing requirements, cold chain infrastructure, and site-of-care economics.
- Intravenous:Parenteral oncology APIs require EMA GMP Annex 1 compliant isolator-based filling, elevating capital barriers for cytotoxic injectables. Netherlands and Ireland facilities absorb compliance costs through dedicated single-product antibody-drug conjugate lines.
- Oral:Solid-dose kinase inhibitors enable specialty pharmacy distribution and 503B compounding in United States ambulatory settings. Hospital-affiliated pharmacies in Texas, Florida, and California negotiate direct API sourcing, compressing distributor margins.
- Subcutaneous:Fixed-dose combination formulations reduce infusion center burden but require high-concentration protein engineering.
- Topical:Limited to cutaneous lymphoma and palliative indications with localized cytotoxic application.
Intravenous retains infrastructure lock-in. Oral formulations are gaining share fastest through patient preference and pharmacy channel expansion.
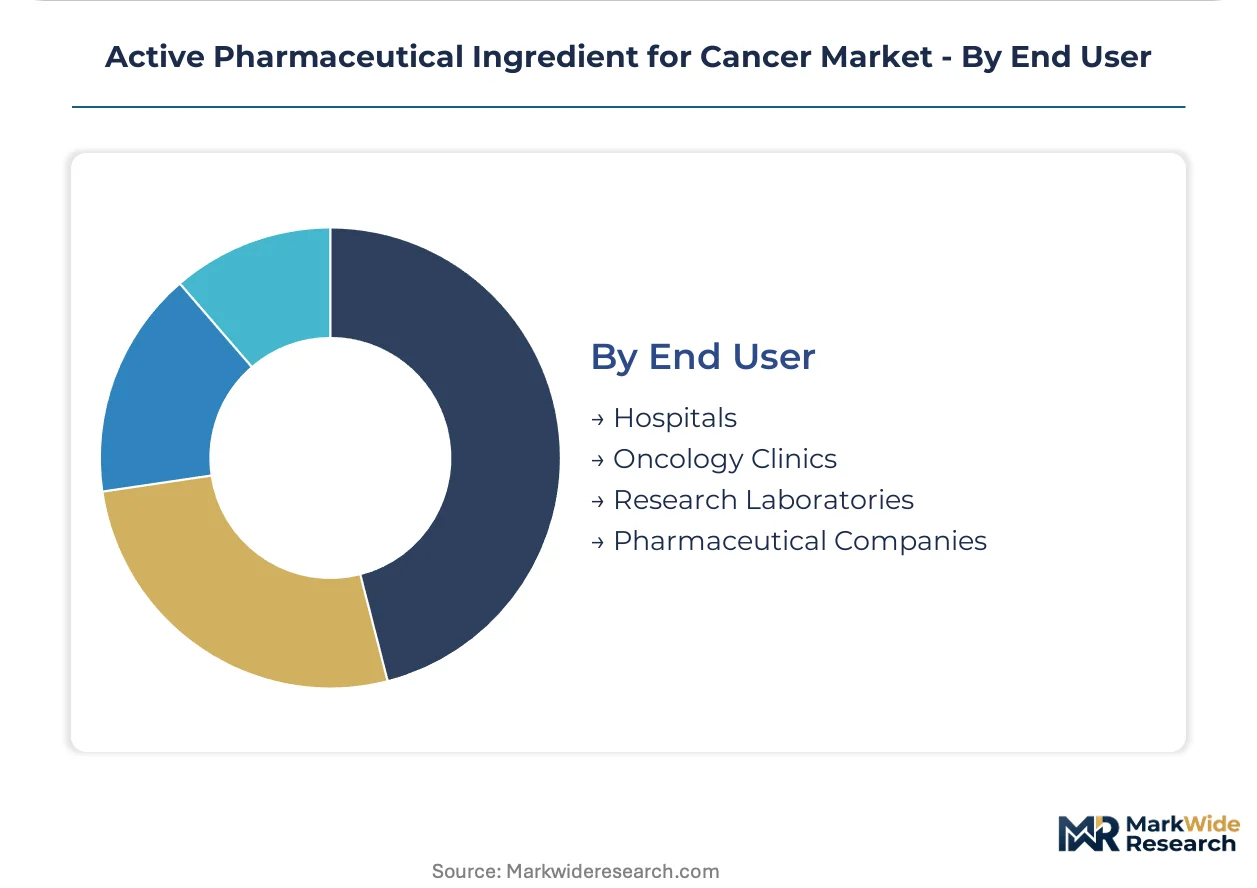
End User:
Procurement authority is shifting from centralized hospital pharmacy to distributed specialty clinic and integrated delivery network purchasing.
- Oncology Clinics:Ambulatory cancer centers expand in-house compounding capabilities for oral oncology under United States 503B regulations. Direct API sourcing from manufacturers bypasses wholesale distributors, concentrating buying power in Texas and Florida integrated delivery networks.
- Hospitals:Inpatient infusion centers retain control of parenteral biologics requiring cold chain and sterile handling. EMA GMP Annex 1 compliance costs favor established European hospital pharmacy suppliers.
- Pharmaceutical Companies:Outsourced API procurement from India CDMOs in Hyderabad and Ahmedabad leverages cost-competitive fermentation capacity for complex cytotoxics.
- Research Laboratories:Preclinical and clinical trial material supply demands flexible small-batch synthesis from contract manufacturers.
Hospitals maintain legacy volume. Oncology clinics are climbing the fastest through vertical integration into compounding and dispensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain terminals anchor European distribution for temperature-sensitive oncology APIs, while direct rail links from Basel and Frankfurt feed manufacturing clusters across the Rhine corridor.
United States
Specialty pharmacy networks in Texas and Florida concentrate procurement volume for oral oncology formulations. FDA accelerated approval pathways compress development timelines for novel cancer APIs. Houston and Dallas cancer centers expand 503B compounding capabilities, bypassing traditional wholesale distributors.
Germany
EMA GMP Annex 1 compliance costs elevate capital barriers for parenteral oncology manufacturing. The country's national pharmaceutical regulator enforces stringent isolator-based filling requirements for cytotoxic injectables. Baden-Württemberg facilities specialize in high-potency antibody-drug conjugate production for European hospital networks.
India
CDSCO oversight governs export-oriented fermentation capacity for complex cytotoxic compounds. The country's national pharmaceutical regulator aligns with ICH Q7 standards for API GMP certification. Hyderabad and Ahmedabad contract manufacturers leverage cost-competitive bioreactor scale-up for Western formulators.
Switzerland
Swissmedic prioritizes medicines scheme accelerates regulatory access for innovative kinase inhibitors. The country's national pharmaceutical regulator maintains alignment with EMA centralized procedures. Basel-area facilities integrate continuous flow chemistry for small-molecule oncology API production.
China
NMPA reforms streamline priority review for breakthrough oncology therapies. The country's national pharmaceutical regulator implements ICH-aligned technical guidelines for API quality. Zhejiang and Jiangsu provinces concentrate bulk chemical intermediate supply, exposing Western formulators to geopolitical disruption risk.
Active Pharmaceutical Ingredient for Cancer Market Competitive Environment
Concentration sits with integrated biopharma conglomerates and specialized CDMOs. The supplier base fragments across chemical synthesis, microbial fermentation, and mammalian cell-culture capabilities. Three archetypes dominate: captive manufacturers with internal demand, pure-play API specialists, and diversified contract service providers. Capacity expansion and strategic technology licensing constitute the primary competitive moves.
Among North American integrated manufacturers, AbbVie Inc and Bristol-Myers Squibb Company exemplify the captive-manufacturing archetype through internalized biologic production. Indian diversified specialists including Sun Pharmaceutical Industries Ltd and Dr. Reddy's Laboratories Ltd occupy positions bridging generic API supply and formulation integration. These entities represent contrasting scale-versus-agility positioning within the competitive matrix.
| Leading Market Players |
|---|
| AbbVie Inc |
| Cipla Inc |
| Teva Pharmaceutical Industries Ltd |
| Merck & Co., Inc |
| Boehringer Ingelheim International GmbH |
| Aurobindo Pharma |
| Sun Pharmaceutical Industries Ltd |
| Bristol-Myers Squibb Company |
| Dr. Reddy's Laboratories Ltd |
| Others |
Value Chain & Pricing Dynamics
Single-use bioreactor systems replacing stainless-steel infrastructure are simultaneously redistributing manufacturing capacity toward Switzerland and Germany while compressing per-batch economics for contract manufacturers. This substitution dynamic concentrates premium pricing power with facilities possessing validated isolator-based filling, while commoditized platinum compound APIs face margin compression from Indian and Chinese bulk suppliers.
Pricing Analysis
Volume-discount tiering structures dominate API procurement, with integrated delivery networks in Texas and Florida extracting preferential terms through direct 503B compounding agreements. Pricing stratifies across patent-protected kinase inhibitors, biosimilar monoclonal antibodies, and generic cytotoxic tiers, with FDA accelerated approval pathways sustaining premium capture for breakthrough therapy candidates. Cost compression in platinum compound APIs intensifies due to Zhejiang and Jiangsu province oversupply. Hospital-affiliated specialty pharmacies demonstrate highest price sensitivity for oral oncology formulations, while immunotherapy API buyers prioritize supply security over unit cost.
Supply Chain Analysis
Inventory lead times for mammalian cell-culture platforms stretch across multi-week viral vector production cycles, tethering checkpoint inhibitor API availability to bioreactor scheduling constraints. Manufacturing concentrates in Switzerland for continuous flow chemistry, India for fermentation-based cytotoxics, and China for bulk chemical intermediates. Key inputs include recombinant protein media, specialized containment equipment, and genotoxic-grade solvents. Single-source vulnerability permeates Zhejiang province intermediate supply. Distribution runs through Rotterdam cold-chain terminals for European parenteral formulations and direct-to-clinic channels for United States oral oncology APIs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty pharmacy network consolidation across Texas, Florida, and California cancer centers is shifting procurement leverage toward ambulatory buyers and compressing distributor margins throughout the oncology API channel.
For Market Incumbents: Fortify isolator-based filling capabilities against EMA GMP Annex 1 compliance deadlines while deepening backward integration into captive fermentation capacity for complex cytotoxic compounds. Merck & Co., Inc. and Bristol-Myers Squibb Company exemplify defensive positioning through biologic manufacturing scale. Containment engineering scarcity threatens facility commissioning timelines. Priority investment areas include single-use bioreactor scale-up and dedicated antibody-drug conjugate lines in Netherlands and Ireland clusters. For New Entrants and Emerging Players: FDA Breakthrough Therapy designation fast-tracks offer regulatory acceleration into checkpoint inhibitor API segments where incumbent capacity constraints create white-space opportunity. Hyderabad and Ahmedabad CDMOs demonstrate penetrable entry points through cost-competitive fermentation scale-up. Target oral oncology formulation supply to United States specialty pharmacy networks bypassing wholesale distribution. Go-to-market positioning should emphasize 503B compounding input partnerships with integrated delivery networks. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale CDMOs possessing validated continuous flow chemistry platforms and EMA-compliant sterile manufacturing infrastructure. Long-term viability across the projection horizon hinges on regulatory alignment with evolving biosimilar substitution frameworks and real-world evidence requirements. Acquisition target archetype: Swiss or German facilities with isolator-based filling capabilities and existing biopharma relationships. Signal to watch: FDA oncology center guidance revisions affecting accelerated approval confirmatory trial requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Single-use bioreactor deployment in Basel-area facilities compresses monoclonal antibody API cycle times. |
| Regulatory Approval Pathway | EMA PRIME designation accelerates European market access for PD-1/PD-L1 checkpoint inhibitor programs. |
| Backward Integration | Captive fermentation capacity insulates Boehringer Ingelheim from Zhejiang intermediate supply disruptions. |
| Long-term Supply Agreement | Direct API sourcing contracts with Texas integrated delivery networks bypass wholesale distributor margins. |
| Licensing Agreement | Technology licensing for continuous flow chemistry enables mid-sized CDMOs to serve fragmented biopharma demand. |
Study Parameters
Operator-level perspectives from regulatory affairs leads, hospital procurement managers, CDMO manufacturing executives, and payer access specialists anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up facility capacity assessments and top-down epidemiology-driven demand modeling enabled triangulation across the analysis window.
Sensitivity analysis frameworks tested alternative scenarios around biosimilar substitution velocity and geopolitical supply disruption severity. Segmentation dimensions modeled include therapy area, manufacturing modality, delivery mode, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to baseline capacity and demand estimates. Industry-specific forecast inputs encompassed EMA GMP Annex 1 compliance cost absorption rates and 503B compounding volume trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained FDA accelerated approval pathway utilization and stable China-India intermediate trade flows; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Large Molecule Drug Substance CDMO Market
Pharmaceutical Ingredients
Global Tacrolimus Market
Pharmaceutical Ingredients
Pharmaceutical Desiccants Market
Pharmaceutical Ingredients
Glycylglycine Market
Pharmaceutical Ingredients
Celecoxib API Market
Pharmaceutical Ingredients
Calcium Gluconate Market
Pharmaceutical Ingredients
Pharmaceutical Hot Melt Extrusion Market
Pharmaceutical Ingredients
Calcium Citrate Market
Pharmaceutical Ingredients
Ferrous Succinate Market
Pharmaceutical Ingredients
Pharmaceutical Grade Sodium Carbonate Market
Pharmaceutical Ingredients
Moxifloxacin Hcl (CAS 186826-86-8) Market
Pharmaceutical Ingredients
Pharmaceuticals Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
Oral Doxycycline Hyclate Market
Pharmaceutical Ingredients
Sulphonamides Market
Pharmaceutical Ingredients
Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market
Pharmaceutical Ingredients
North America Active Pharmaceutical Ingredients Market