
 Lidocaine Hydrochloride Market | 2026-2036
Lidocaine Hydrochloride Market Size, Share, and Industry Trends Forecast 2026-2036
Lidocaine Hydrochloride Market Analysis
Buyer concentration among hospital systems is hardening as integrated delivery networks in the United States negotiate multi-year supply agreements for injectable lidocaine. Pfizer Inc. leverages its vertically integrated active pharmaceutical ingredient operations to secure long-term contracts with these consolidated purchasers. Fresenius Kabi anchors its position through dedicated manufacturing lines for parenteral anesthetics serving European and North American acute care facilities. Teva Pharmaceutical Industries Ltd. competes aggressively on price in the generic injectable segment while sustaining compliance with stringent FDA current good manufacturing practice requirements.
Lidocaine hydrochloride is the water-soluble salt form of lidocaine base, typically formulated at concentrations ranging from 0.5% to 2% for injection and 2% to 5% for topical preparations, functioning as an amide-type local anesthetic that blocks sodium ion channels in neuronal membranes to prevent nerve impulse transmission. Injectable formulations dominate hospital procurement due to their irreplaceable role in surgical infiltration and nerve block procedures, while patch-based delivery systems represent the fastest-expanding segment as chronic pain management shifts toward outpatient settings. The cream and gel categories occupy stable positions in dermatology and minor procedure applications where lower potency and reduced systemic absorption are clinically preferred.
FDA oversight of generic injectable anesthetics enforces bioequivalence and sterility standards that limit market entry to manufacturers with validated aseptic processing capabilities. EMA's Good Manufacturing Practice guidelines for active substances, combined with REACH requirements for chemical intermediates, shape the European competitive landscape by raising compliance costs for API suppliers. The WHO Essential Medicines List designation for lidocaine injectable solutions sustains procurement priority in public health systems across multiple geographies. Stakeholders must monitor evolving pharmacovigilance requirements for local anesthetic systemic toxicity reporting as regulatory agencies intensify post-market surveillance obligations.
Market Dynamics
Hospital procurement consolidation across the United States, Germany, and Japan is compressing supplier margins while amplifying volume concentration around manufacturers with validated aseptic processing capabilities and backward integration into active pharmaceutical ingredient production.
Growth Catalysts
- Ambulatory Surgery Center Expansion:Outpatient facilities in the United States are expanding their purchasing power for injectable anesthetics, creating dedicated supply channels separate from traditional hospital procurement.
- EMA Pharmacovigilance Tightening:The European Medicines Agency's intensified purity standards for local anesthetics is disqualifying marginal suppliers and concentrating volume among qualified manufacturers.
- WHO Essential Medicines List:Lidocaine injectable solutions maintain procurement priority in public health systems across multiple geographies, insulating demand from budget volatility.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient production for lidocaine base concentrates among Chinese and Indian manufacturers, exposing formulators to geopolitical and logistics disruptions.
- FDA Bioequivalence Barriers:The Food and Drug Administration's sterility and bioequivalence requirements for generic injectables limit market entry to manufacturers with capital-intensive aseptic processing infrastructure.
- Topical Anesthetic Substitution:Liposomal formulations and alternative amide-type compounds compete for dermatology and minor procedure applications where systemic absorption concerns predominate.
Strategic Opportunities
- Patch-Based Chronic Pain Management:Transdermal delivery systems represent underpenetrated white space as pain management migrates from inpatient to outpatient settings in Japan and the United States.
- REACH Compliance Differentiation:European chemical registration requirements create competitive moats for manufacturers with documented supply chain transparency and intermediate substance controls.
- Integrated Delivery Network Contracts:Multi-year supply agreements with consolidated United States hospital systems offer volume predictability and formulary lock-in for qualified suppliers.
Industry Challenges
- Aseptic Processing Talent Scarcity:Validated cleanroom operators and sterile manufacturing engineers command premium compensation, constraining capacity expansion timelines for injectable formulators.
- Pharmacovigilance Reporting Burden:Post-market surveillance obligations for local anesthetic systemic toxicity require dedicated adverse event infrastructure that smaller generic manufacturers struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lidocaine Hydrochloride Market |
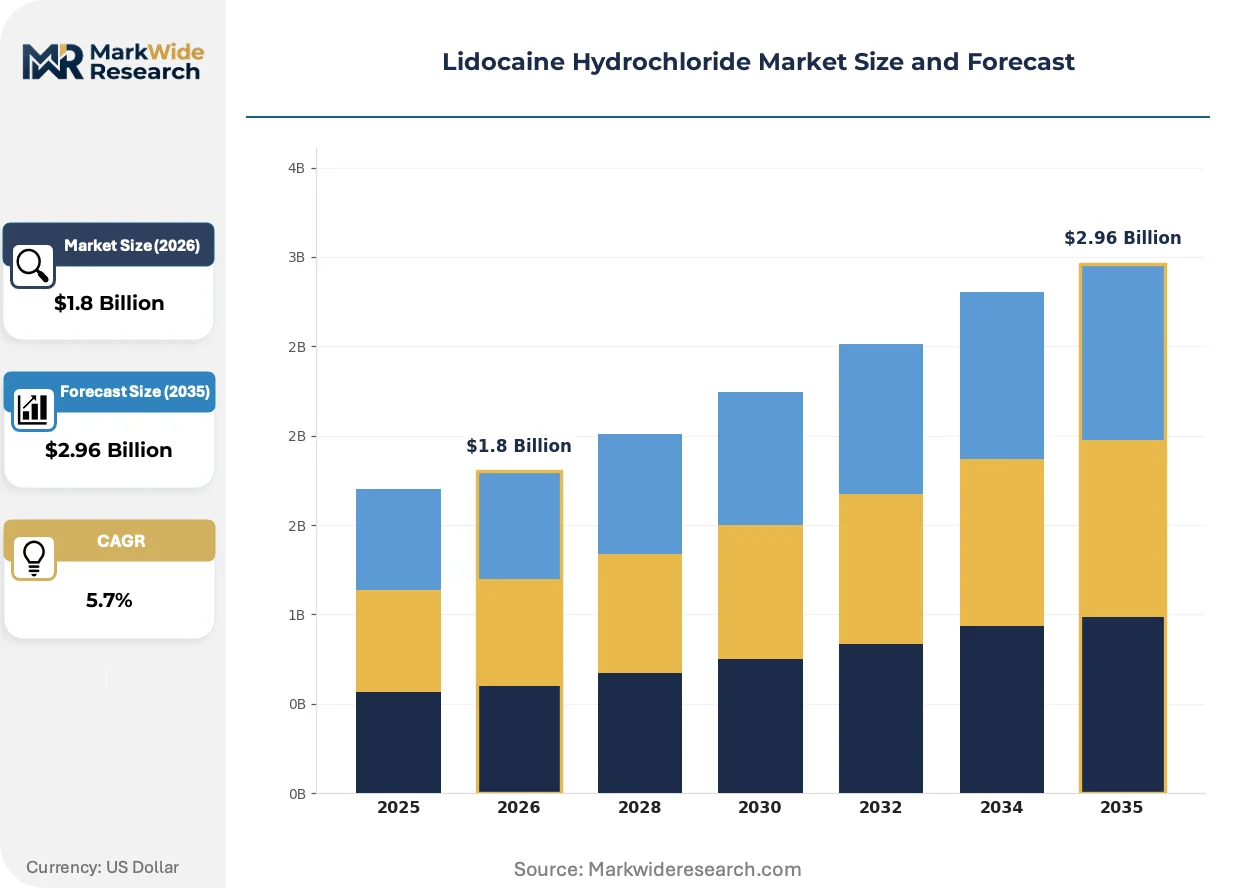
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Cream, Gel, Patch End User: Hospitals, Clinics, Ambulatory Surgery Centers, Home Care Application: Local Anesthesia, Pain Management, Surgical Procedures, Diagnostic Procedures Delivery Mode: Topical, Infiltration, Nerve Block, Intravenous |
| Companies Covered | Pfizer Inc., Merck KGaA, Teva Pharmaceutical Industries Ltd., Fresenius Kabi, Amneal Pharmaceuticals Inc., Amphastar Pharmaceuticals Inc., Hikma Pharmaceuticals, AstraZeneca, Endo International plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lidocaine Hydrochloride Market Emerging Trajectories
Formulation science and delivery mechanism innovation are reshaping competitive positioning in lidocaine hydrochloride, with particular momentum in non-injectable modalities and regulatory compliance automation.
Microsphere encapsulation technology is integrating controlled-release capabilities into topical and transdermal lidocaine formulations, enabling sustained plasma concentrations without repeated dosing. Dermatology clinics and chronic pain management centers in Germany and Japan are adopting these platforms for post-operative and neuropathic pain protocols. The technology is integrating premium pricing power into segments previously commoditized by generic cream and gel competition.
REACH registration requirements for chemical intermediates are forcing API suppliers to reconstruct documentation trails for lidocaine base precursors and manufacturing byproducts. European formulators now demand certified supply chain transparency as a qualification threshold, compressing the vendor base to manufacturers with established European Chemicals Agency compliance infrastructure. German acute care facilities have accelerated supplier audits to verify intermediate substance controls ahead of registration deadlines.
Consolidated purchasing by United States integrated delivery networks is compressing supplier margins while demanding guaranteed supply continuity and formulary exclusivity. Multi-year agreements with penalty clauses for stockouts are displacing spot-market transactions and distributor-mediated procurement. The tightest contract terms appear in Southeastern and Midwestern hospital systems where network consolidation has advanced furthest.
Lidocaine Hydrochloride Market Segmentation
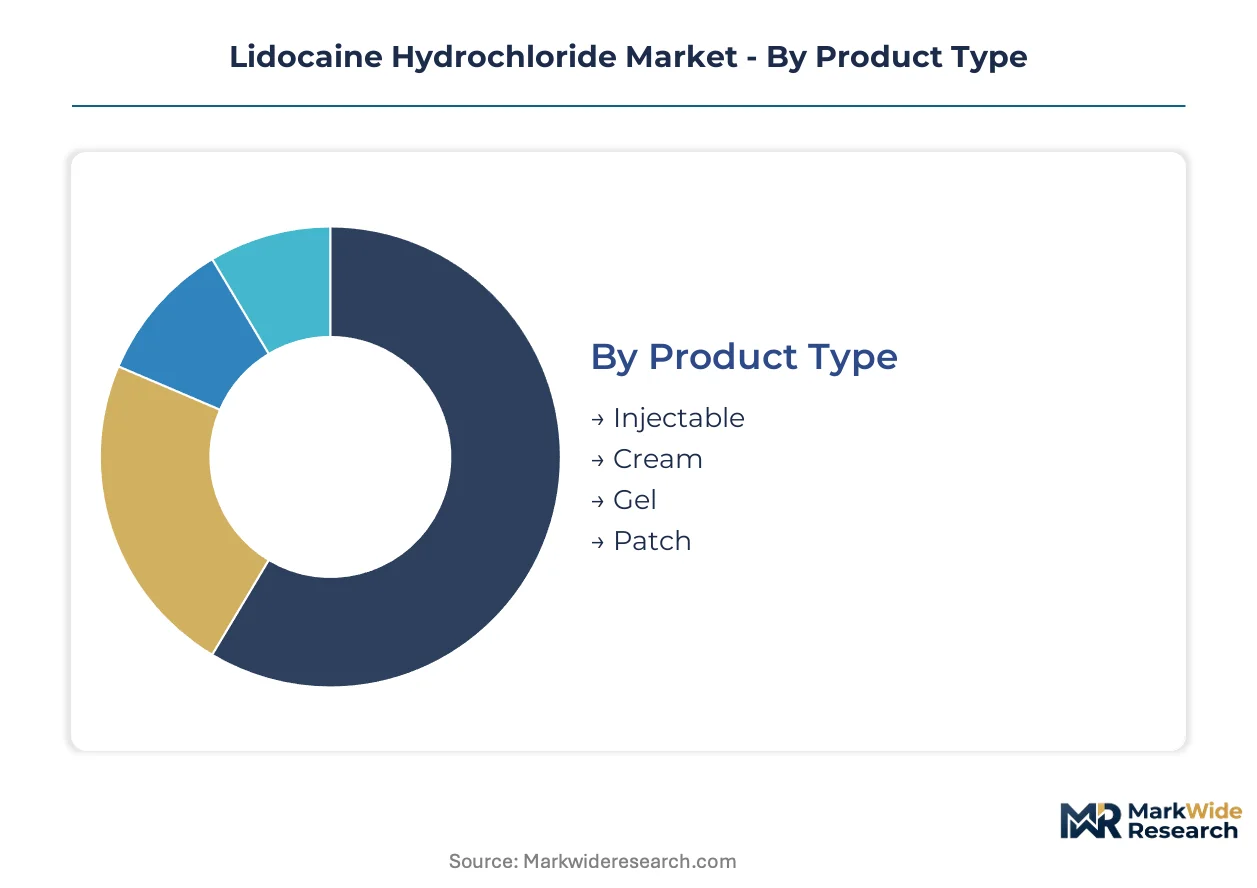
Segmentation in lidocaine hydrochloride reveals how formulation modality and care setting interact to determine procurement patterns. Injectable formulations anchor hospital formularies while patch-based systems unlock outpatient expansion. Understanding these divides exposes where supplier capabilities must align with specific clinical workflows and regulatory pathways.
Product Type:
Standalone formulations command premium positioning through dedicated manufacturing infrastructure, while embedded delivery systems integrate lidocaine into broader therapeutic platforms.
- Injectable:Sterile aqueous solutions at 0.5% to 2% concentration formulated for parenteral administration. Hospital systems in the United States concentrate procurement around multi-source generic injectables as integrated delivery networks consolidate formularies. FDA sterility requirements and bioequivalence validation limit supplier qualification to manufacturers with validated aseptic processing lines.
- Patch:Transdermal systems delivering sustained lidocaine release through adhesive matrix technology. Demand in Japan and the United States is climbing fastest as chronic pain management migrates from inpatient to outpatient settings, with pain management centers adopting these platforms for neuropathic protocols. Premium pricing power emerges in segments previously commoditized by topical competition.
- Cream:Semisolid emulsions at 2% to 5% concentration for dermatological and minor procedural applications. Lower systemic absorption profiles suit ambulatory clinic preferences where rapid onset is secondary to safety margins.
- Gel:Viscous aqueous preparations combining lidocaine with lubricating agents for mucosal and catheterization procedures. Stable demand persists in urology and emergency medicine departments requiring controlled application viscosity.
Volume placements concentrate in Injectable; the faster expansion belongs to Patch.
End User:
Cost tier stratification separates capital-intensive acute care facilities from distributed outpatient settings with lighter infrastructure requirements.
- Hospitals:Comprehensive acute care institutions performing surgical infiltration, nerve block, and critical care procedures. Procurement in Germany and Japan hardens around backward-integrated suppliers capable of multi-year supply agreements with penalty clauses for stockout events. Formulary consolidation compresses vendor panels to manufacturers with captive API production.
- Ambulatory Surgery Centers:Dedicated outpatient facilities performing same-day surgical procedures. Purchasing power in the United States is expanding fastest as these centers establish supply channels separate from traditional hospital procurement, demanding guaranteed supply continuity at compressed margins.
- Clinics:Primary and specialty care settings managing minor procedures and diagnostic interventions. Dermatology and pain management clinics in Germany adopt microsphere-encapsulated topical formulations for sustained-release protocols.
- Home Care:Patient-directed administration settings for chronic pain management and post-operative recovery. Patch-based systems enable this segment's expansion through reduced clinical supervision requirements.
Revenue concentration sits with Hospitals; Ambulatory Surgery Centers are gaining share fastest.
Application:
Application segmentation tracks how clinical purpose shapes dosing precision requirements and regulatory scrutiny intensity.
- Local Anesthesia:Regional nerve block and tissue infiltration for operative pain prevention. Surgical departments in United States hospital systems anchor demand through irreplaceable use in operative protocols.
- Pain Management:Chronic and acute pain treatment across inpatient and outpatient settings. Neuropathic pain protocols in Japan drive adoption of sustained-release transdermal systems.
- Surgical Procedures:Perioperative anesthesia for invasive interventions. Requirements for rapid onset and predictable duration favor injectable formulations with documented pharmacokinetic profiles.
- Diagnostic Procedures:Anesthesia for biopsy, endoscopy, and imaging-guided interventions. Lower volume requirements suit clinic and ambulatory settings where procedure throughput is constrained.
Procedure volume concentrates in Surgical Procedures; Pain Management shows the steepest expansion trajectory.
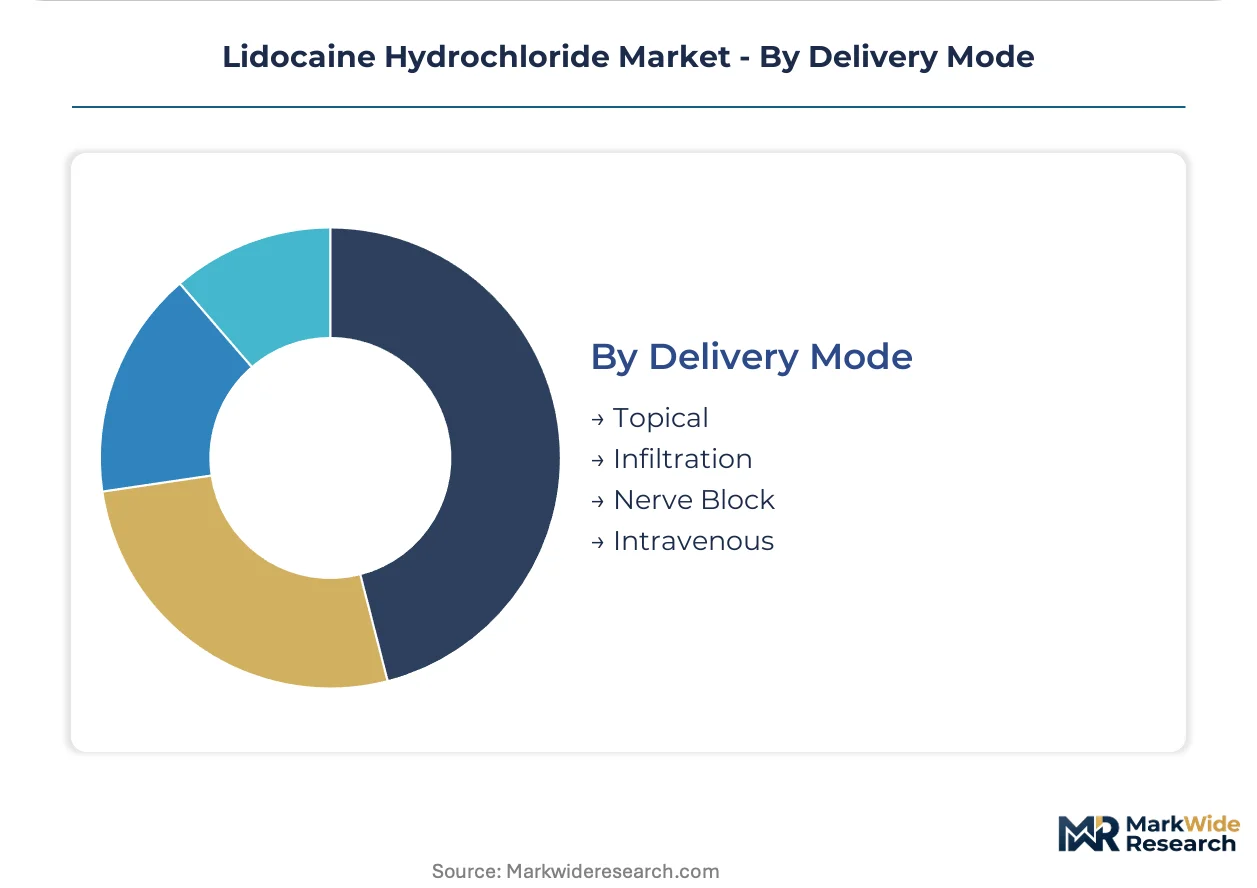
Delivery Mode:
Delivery modality determines the technical barrier to entry, with invasive routes demanding validated aseptic capabilities that exclude marginal manufacturers.
- Infiltration:Direct injection into tissue planes for localized anesthesia. Operating rooms across United States integrated delivery networks standardize on this modality for wound closure and superficial procedures.
- Nerve Block:Perineural injection targeting specific neural pathways for regional anesthesia. Anesthesiology departments require precise concentration control and documented sensory distribution outcomes.
- Intravenous:Systemic administration for antiarrhythmic indications and procedural sedation. ICU and emergency medicine settings in Germany maintain stocked formularies for cardiac stabilization protocols.
- Topical:Surface application to intact or disrupted skin and mucous membranes. Dermatology clinics favor this route where systemic absorption minimization is clinically preferred.
Infiltration captures the largest procedure volume; Nerve Block is climbing fastest as regional anesthesia protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consolidation concentrates demand in the United States, Germany, and Japan, where integrated delivery networks and acute care systems anchor volume placement for injectable formulations.
United States
Ambulatory surgery centers in Texas and Florida are expanding dedicated supply channels separate from traditional hospital procurement, demanding guaranteed supply continuity. FDA bioequivalence and sterility requirements for generic injectables limit supplier qualification to manufacturers with validated aseptic processing capabilities. Southeastern and Midwestern hospital systems have advanced network consolidation furthest, compressing vendor panels through multi-year agreements with stockout penalty clauses.
Germany
Acute care facilities in Bavaria and North Rhine-Westphalia harden procurement around backward-integrated suppliers capable of multi-year supply agreements. EMA Good Manufacturing Practice guidelines for active substances, combined with REACH requirements for chemical intermediates, raise compliance costs and reshape supplier qualification protocols. German dermatology clinics in Baden-Württemberg accelerate adoption of microsphere-encapsulated topical formulations for sustained-release pain protocols.
Japan
Pain management centers in Tokyo and Osaka drive fastest-expanding demand for patch-based transdermal systems as chronic care migrates from inpatient to outpatient settings. PMDA pharmacovigilance requirements for local anesthetics intensify post-market surveillance obligations for systemic toxicity reporting. The Kanto region anchors manufacturing concentration for transdermal delivery technology serving domestic and export markets.
India
Active pharmaceutical ingredient production for lidocaine base concentrates among manufacturers in Gujarat and Maharashtra, exposing formulators to logistics disruptions. CDSCO oversight of injectable anesthetics enforces sterility standards that limit market entry to facilities with validated aseptic processing infrastructure. Hyderabad and Ahmedabad clusters specialize in intermediate substance production for export to European and North American formulators.
China
API manufacturing clusters in Jiangsu and Zhejiang provinces supply precursor chemicals and lidocaine base to global formulators. NMPA registration requirements for sterile injectables align with international standards, enabling qualified manufacturers to serve export markets. The Yangtze River Delta concentrates finished formulation capacity for domestic hospital procurement and regional export.
Lidocaine Hydrochloride Market Vendor Landscape
United States and European producers anchor one tier; Indian and Chinese specialists hold upstream positions in active pharmaceutical ingredient supply. The market structures around three tiers: multinational pharmaceutical corporations with captive API production, regional generic injectable specialists with validated aseptic lines, and API-focused manufacturers supplying intermediate substances. Strategic moves concentrate on backward integration into API production and multi-year supply agreements with consolidated hospital systems.
Within the multinational tier, Pfizer Inc. and Fresenius Kabi occupy positions defined by vertically integrated operations and dedicated manufacturing infrastructure. Teva Pharmaceutical Industries Ltd. exemplifies the generic injectable specialist archetype, competing on price while sustaining compliance with stringent regulatory requirements. These three companies represent the competitive anchors around which supplier consolidation and procurement concentration are reshaping market access.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck KGaA |
| Teva Pharmaceutical Industries Ltd. |
| Fresenius Kabi |
| Amneal Pharmaceuticals Inc. |
| Amphastar Pharmaceuticals Inc. |
| Hikma Pharmaceuticals |
| AstraZeneca |
| Endo International plc |
| Others |
Supply Flow & Price Mechanics
Ethylene and diethylamine feedstock indices cascade through lidocaine base synthesis into three-tier pricing stratification across injectable, patch, and topical segments. Hospital procurement consolidation in the United States and Germany translates volume concentration into margin compression for formulators lacking backward integration into active pharmaceutical ingredient production.
Pricing Analysis
Volume-margin splits separate multi-year hospital contracts from spot-market transactions. Three-tier pricing structure across premium, standard, and economy levels reflects FDA certification tiers, aseptic processing validation status, and geographic delivery cost differentials. Pricing pressure stems from integrated delivery network formulary consolidation demanding guaranteed supply continuity at compressed terms. Ambulatory surgery centers exhibit highest price sensitivity; German acute care facilities with captive API suppliers demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements from United States and German hospital systems mandate multi-supplier qualification for lidocaine base and intermediate substances. API production concentrates in India, China, and select European facilities. Formulators draw from diethylamine, xylene, and chloroacetyl chloride precursors. Single-source vulnerability persists in Chinese intermediate supply. Distribution runs through direct manufacturer-to-hospital agreements displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation functions as a consolidation play, with FDA aseptic processing requirements forcing subscale generic manufacturers toward exit or acquisition.
For Market Incumbents: Anchor formulary position through captive API production and dedicated manufacturing lines for parenteral anesthetics. Defend against patch-based chronic pain substitution by securing pain management center contracts with sustained-release microsphere formulations. Prioritize REACH documentation infrastructure as European qualification threshold. For New Entrants and Emerging Players: Begin with transdermal delivery technology for outpatient pain management in Japan and United States ambulatory settings. Target clinic-tier dermatology and home care segments where regulatory barriers remain lower than hospital injectable qualification. Pursue white-label manufacturing partnerships with established API suppliers to bypass capital-intensive aseptic infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale injectable specialists with validated cleanroom operations in India and Eastern Europe. Long-term viability hinges on backward integration completion and multi-year contract visibility with consolidated health systems. Monitor PMDA and FDA pharmacovigilance enforcement intensity as inflection signal for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Production | Captive lidocaine base supply secures margin protection against Chinese intermediate price volatility. |
| Multi-Year Hospital System Contracts | Integrated delivery network agreements in the United States provide volume predictability and formulary lock-in. |
| Transdermal Delivery Technology Investment | Patch-based systems capture outpatient chronic pain migration in Japan and United States markets. |
| REACH Compliance Infrastructure | European Chemicals Agency documentation creates competitive moats disqualifying marginal API suppliers. |
| Aseptic Processing Capacity Expansion | FDA-validated sterile manufacturing lines enable qualification for consolidated hospital procurement. |
Methodological Framework
FDA filings, EMA regulatory submissions, and hospital procurement databases formed the secondary backbone of this analysis. Primary interviews with formulary directors, hospital procurement managers, regulatory affairs leads, and API manufacturing executives combined with bottom-up and top-down triangulation to validate volume and value estimates across formulation modalities and care settings.
Bottom-up modeling of injectable, patch, cream, and gel segments by end user and application intersected with top-down macroeconomic and demographic calibration across the projection horizon. Segmentation dimensions included product type, delivery mode, care setting, and regional regulatory cluster. CAGRs derived from procedure volume trajectories, ambulatory surgery center expansion rates, and chronic pain prevalence patterns.
Underlying measurement precision varies by segment; hospital injectable procurement carries tighter precision than emerging patch-based home care adoption. Forecasts reflect assumptions regarding regulatory enforcement continuity, API supply chain stability, and hospital consolidation pace. Deviation in FDA pharmacovigilance stringency or Chinese intermediate export restrictions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
United States Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Growth Hormone Inhibiting Hormone Drugs Market
Pharmaceutical Ingredients
Saudi Arabia Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Asia-Pacific Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Global Small Molecule API Market
Pharmaceutical Ingredients
Nuclear Export Inhibitor Drugs Market
Pharmaceutical Ingredients
MEK Inhibitors Market
Pharmaceutical Ingredients
Diclofenac Sodium API Market
Pharmaceutical Ingredients
Citicoline Market
Pharmaceutical Ingredients
Pharmaceutical Grade Hyaluronic Acid Market
Pharmaceutical Ingredients
Quinoline Market
Pharmaceutical Ingredients
Flurbiprofen Market
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients CDMO Market
Pharmaceutical Ingredients
Global Ibuprofen Market
Pharmaceutical Ingredients
Acetaminophen API Market
Pharmaceutical Ingredients
Global Tizanidine Market