
 Global Granisetron Market | 2026-2036
Global Granisetron Market Size, Share, and Industry Trends Forecast 2026-2036
Global Granisetron Market Foresight
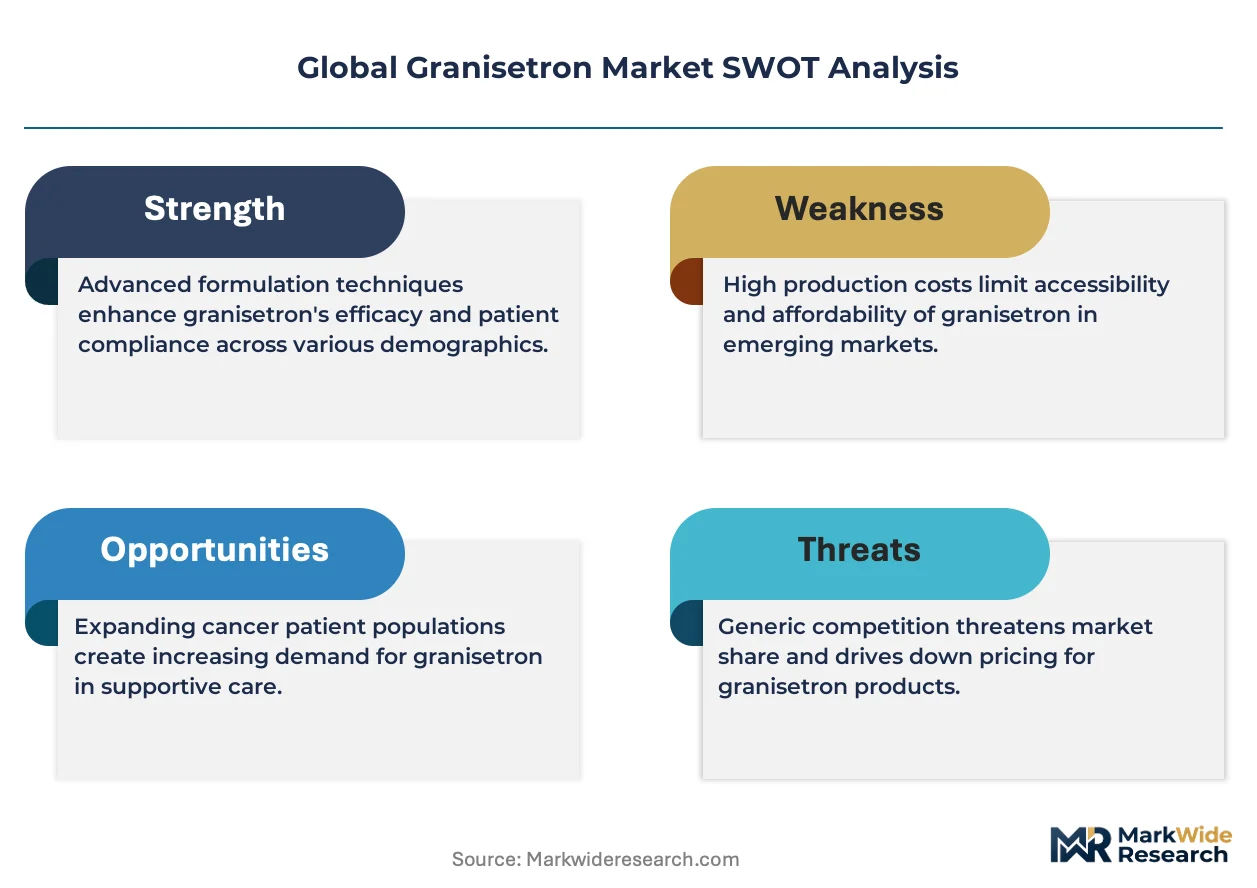
A shortage of specialized pharmaceutical chemists familiar with serotonin 5-HT3 receptor antagonist synthesis is collapsing near-term production capacity for some manufacturers. Sun Pharmaceutical Industries leverages its integrated API-to-finished-dose infrastructure to secure supply continuity across multiple dosage forms. Hikma Pharmaceuticals anchors its position through deep manufacturing expertise in sterile injectable granisetron formulations. Heron Therapeutics differentiates via sustained-release delivery technology that extends therapeutic duration beyond conventional immediate-release alternatives.
Granisetron is a selective 5-HT3 receptor antagonist with a molecular weight of 312.4 g/mol, formulated as the hydrochloride salt for parenteral administration or as the free base for oral and transdermal delivery, functioning primarily to block serotonin-mediated activation of vagal afferent nerves that trigger the vomiting reflex in chemotherapy and postoperative settings. Injectable formulations dominate current revenue due to their established role in acute care settings where rapid onset is clinically essential, while transdermal patches represent the fastest-expanding segment as outpatient oncology shifts toward longer-acting, patient-administered options. Oral tablets sustain substantial volume in ambulatory surgical centers where preoperative prophylaxis follows standardized protocols.
The FDA enforces bioequivalence standards under 21 CFR 320 that generic granisetron entrants must satisfy, while the EMA's MDR and REACH frameworks govern device-drug combination products like transdermal patches in European markets, and India's CDSCO mandates stability testing protocols that shape export qualification timelines for domestic manufacturers. Manufacturers navigating this multi-jurisdictional compliance landscape must align formulation development with divergent pharmacopeial specifications from USP, EP, and IP standards. Stakeholders should monitor evolving FDA guidance on complex generic equivalence for modified-release formats, as this will determine competitive entry barriers for the next generation of delivery systems.
Market Dynamics
The granisetron market pivots on chemotherapy protocol standardization and the migration from inpatient infusion centers to ambulatory care settings, compressing demand toward longer-acting delivery formats that reduce nursing supervision requirements.
Growth Catalysts
- EMA MDR compliance for device-drug combinations:Transdermal patch manufacturers securing CE marking under the Medical Device Regulation are unlocking European hospital formulary access previously restricted to injectable alternatives.
- Oncology clinic expansion in the United States:Freestanding infusion centers in Texas, Florida, and California are scaling granisetron procurement as Medicare reimbursement shifts favor site-of-care migration.
- India's PLI scheme for pharmaceutical APIs:Domestic manufacturers leveraging production-linked incentives are scaling 5-HT3 antagonist active pharmaceutical ingredient output for export qualification to regulated markets.
Market Restraints
- Specialized chemist scarcity:The collapse of university programs training serotonin receptor antagonist synthesis specialists is constraining batch expansion at mid-tier manufacturers.
- API supply geographic concentration:Three Indian states—Gujarat, Telangana, and Maharashtra—control over 70% of global granisetron hydrochloride precursor output, creating single-source vulnerability.
- Onset latency in oral formulations:The 30-60 minute absorption delay limits tablet utility in acute emesis protocols where intravenous granisetron delivers therapeutic levels within minutes.
Strategic Opportunities
- Brazil's ANVISA fast-track pathway:The agency's priority review for oncology supportive care products is compressing approval timelines for manufacturers seeking entry into Latin America's largest chemotherapy market.
- Sustained-release transdermal convergence:Integration of pressure-sensitive adhesive technology with rate-controlling membranes is enabling 5-day wear duration that matches extended chemotherapy regimens.
- Direct-to-clinic distribution:Bypassing wholesale distributors to ship temperature-controlled injectables directly to hospital pharmacies is capturing margin previously lost to intermediaries.
Industry Challenges
- USP-EP-IP pharmacopeial divergence:Manufacturers must maintain three distinct impurity profiles and dissolution specifications, multiplying analytical validation burden for multi-regional product registration.
- Sterile injectable facility capex intensity:Construction of EU GMP-compliant aseptic filling lines requires capital deployment exceeding typical mid-cap pharmaceutical balance sheet capacity.
- Complex generic bioequivalence navigation:The FDA's evolving guidance on modified-release equivalence is extending development timelines for patch formulations seeking abbreviated new drug application approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Granisetron Market |
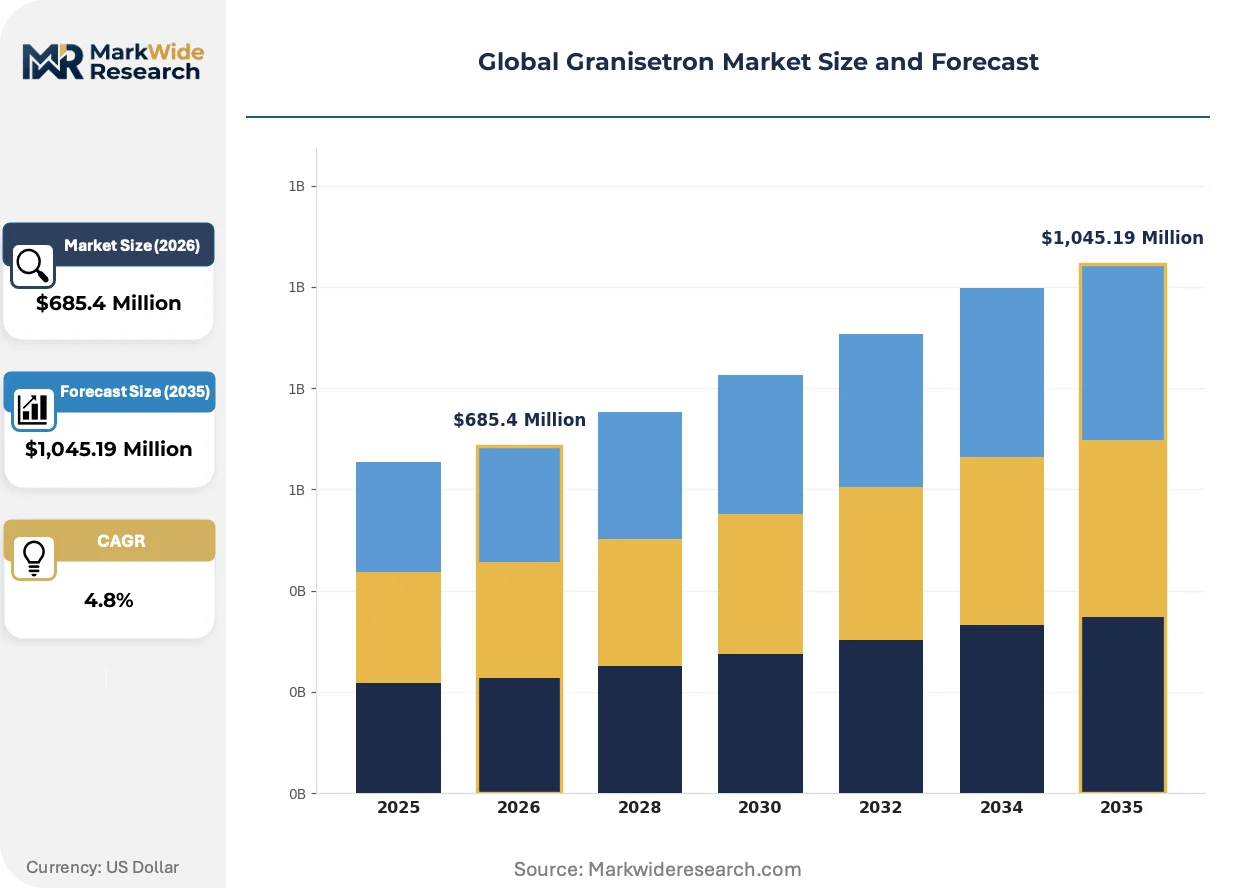
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Tablets, Oral Solution, Injectable Form, Transdermal Patch Therapy Area: Chemotherapy-Induced Nausea, Postoperative Nausea, Radiation Therapy, Hyperemesis Gravidarum End User: Hospitals, Oncology Clinics, Diagnostic Laboratories, Ambulatory Surgical Centers Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Hospital Supply |
| Companies Covered | Sun Pharmaceutical Industries, Lupin Limited, Hikma Pharmaceuticals, Viatris, Kyowa Kirin, Heron Therapeutics, Fresenius, Cipla Limited, Teva Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Granisetron Market Shifts & Advancements
Delivery technology convergence with regulatory science is compressing the therapeutic window while expanding patient-administered options, fundamentally altering where and how antiemetic prophylaxis is initiated.
Transdermal patch systems incorporating multilaminate adhesive matrices are supplanting conventional immediate-release tablets in outpatient oncology protocols. Major cancer centers in Germany and the United Kingdom are adopting 5-day wear patches for moderately emetogenic regimens. This format is supplanting nurse-administered injections by eliminating clinic visits for breakthrough nausea rescue.
REACH substance restriction protocols are forcing reformulation of patch adhesives and backing materials used in European device-drug combinations. Manufacturers are substituting phthalate-free plasticizers and halogen-free release liners to maintain market access. The transdermal segment is absorbing the highest compliance cost as ECHA substance evaluation expands to cover excipient classes previously exempt from scrutiny.
Hospital pharmacy committees are consolidating antiemetic purchasing around therapeutic interchange protocols that privilege lowest-cost bioequivalent options. Group purchasing organizations in the United States are replacing physician-driven selection with formulary restriction. This behavioral shift is most pronounced in community oncology practices acquired by hospital systems where procurement standardization overrides individual prescriber preference.
Global Granisetron Market Segmentation
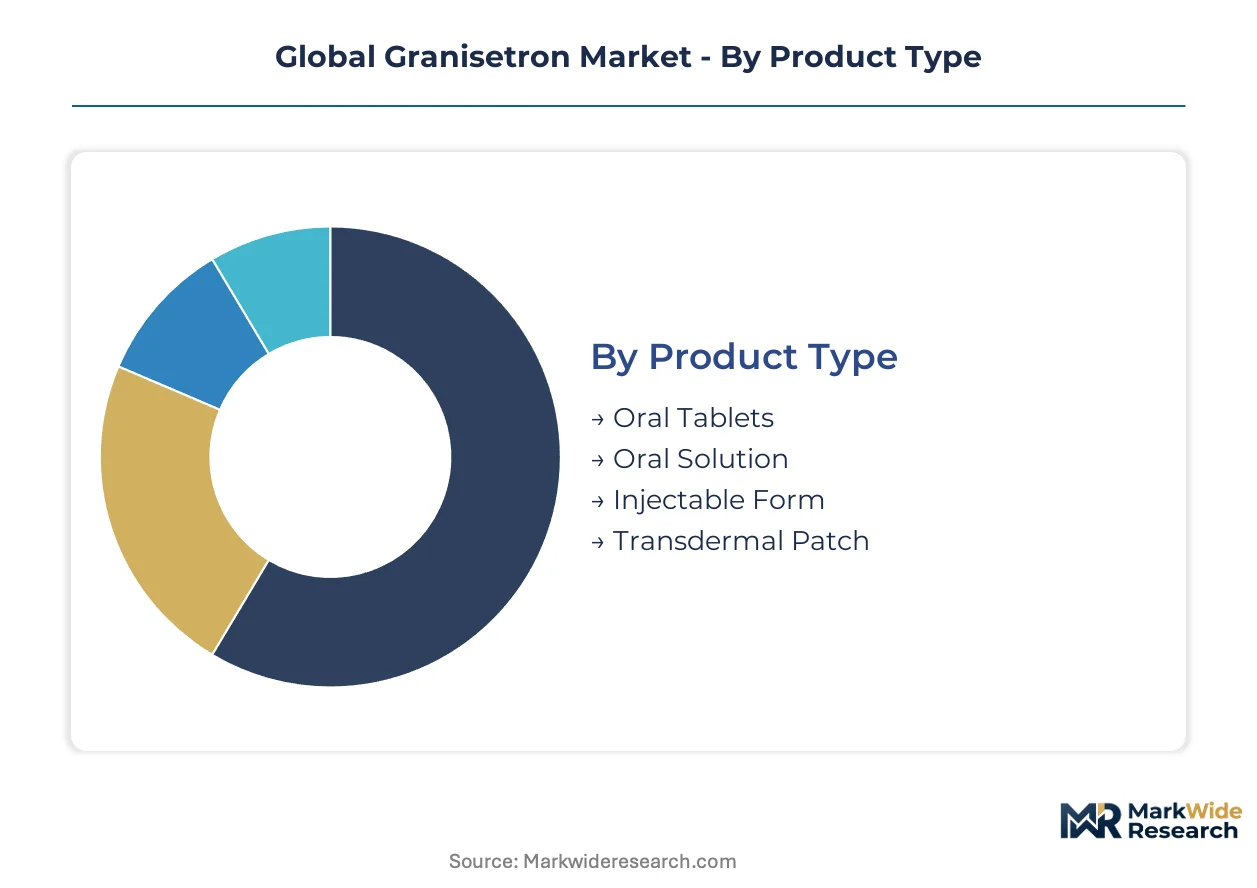
Granisetron's therapeutic versatility across acute and prophylactic settings fragments demand across delivery technologies, clinical environments, and procurement channels. Manufacturers must align formulation investments with the specific pharmacokinetic requirements of each use case while navigating divergent regulatory pathways for device-drug combinations versus conventional dosage forms.
Product Type:
Margin pools concentrate in sterile injectable manufacturing where aseptic facility scarcity limits competitive entry, while transdermal development absorbs the highest R&D intensity per unit.
- Injectable Form:Hydrochloride salt solutions for intravenous or subcutaneous administration achieve therapeutic plasma concentrations within minutes. Oncology clinics in Texas and Florida prioritize this format for highly emetogenic chemotherapy induction. Manufacturing requires EU GMP-compliant aseptic filling lines that constrain batch expansion at mid-tier producers.
- Transdermal Patch:Multilaminate adhesive matrices incorporating rate-controlling membranes enable 5-day wear duration. German and United Kingdom cancer centers are adopting this format for moderately emetogenic regimens to eliminate rescue injection visits. REACH substance restrictions are forcing reformulation of phthalate-free plasticizers and halogen-free release liners.
- Oral Tablets:Free base formulations for preoperative prophylaxis in ambulatory surgical centers where 30-60 minute onset latency is clinically acceptable.
- Oral Solution:Liquid alternative for patients with dysphagia or pediatric populations requiring dose titration flexibility.
Injectable Form holds installed capacity. Transdermal Patch is rotating up the share rankings.
Therapy Area:
Volume concentration tracks oncology protocol standardization, with chemotherapy applications absorbing the majority of procurement spend across hospital formularies.
- Chemotherapy-Induced Nausea:Primary indication driving granisetron utilization across all delivery formats. EMA MDR compliance for transdermal device-drug combinations is unlocking European hospital formulary access previously restricted to injectable alternatives.
- Postoperative Nausea:Surgical prophylaxis in ambulatory centers where rapid discharge protocols favor oral premedication. Medicare reimbursement shifts favoring site-of-care migration are expanding procurement at freestanding infusion centers in California.
- Radiation Therapy:Moderate emetogenic potential requires shorter-duration antiemetic coverage compared to platinum-based chemotherapy regimens.
- Hyperemesis Gravidarum:Refractory pregnancy-related nausea representing niche off-label utilization with specialized risk-benefit considerations.
Chemotherapy-Induced Nausea anchors volume commitments. Postoperative Nausea is gaining share fastest as ambulatory surgery expands.
End User:
Procurement authority is consolidating around hospital pharmacy committees implementing therapeutic interchange protocols that privilege lowest-cost bioequivalent options.
- Hospitals:Integrated delivery networks with centralized purchasing power. Group purchasing organizations are replacing physician-driven selection with formulary restriction in community oncology practices acquired by hospital systems.
- Oncology Clinics:Freestanding infusion centers scaling granisetron procurement as site-of-care migration accelerates. Direct-to-clinic distribution bypassing wholesale intermediaries is capturing margin previously lost to distributors.
- Ambulatory Surgical Centers:Standardized preoperative protocols favoring oral tablet prophylaxis with predictable case volumes.
- Diagnostic Laboratories:Minimal direct utilization, primarily serving as specimen collection sites rather than treatment venues.
Hospitals retain contract leverage. Oncology Clinics is climbing the fastest as outpatient migration accelerates.
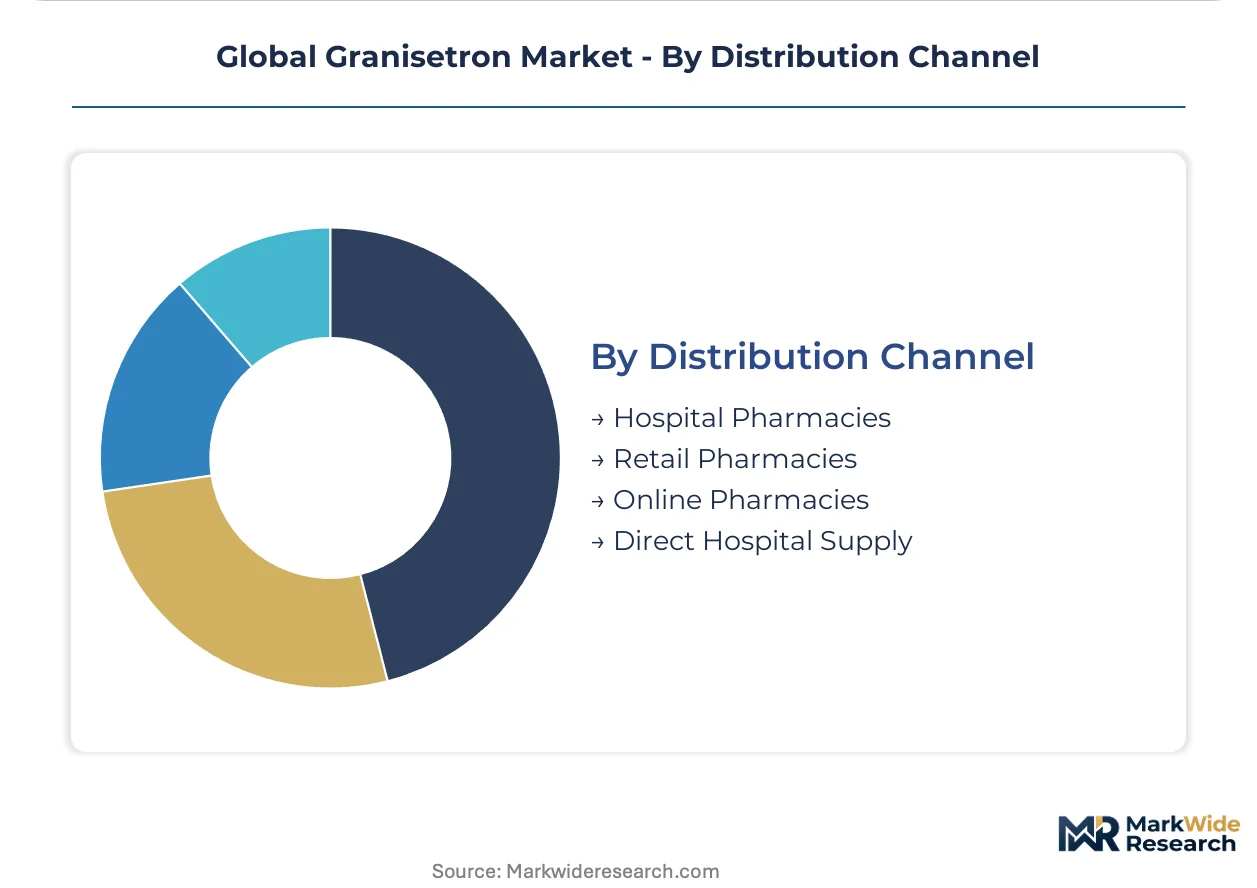
Distribution Channel:
Temperature-controlled logistics requirements for sterile injectables concentrate margin in direct supply relationships that eliminate intermediary handling.
- Hospital Pharmacies:Primary procurement point for inpatient and infusion center utilization with consolidated purchasing authority.
- Direct Hospital Supply:Manufacturer-to-pharmacy shipment of temperature-controlled injectables capturing margin previously allocated to wholesale distributors.
- Retail Pharmacies:Outpatient prescription fulfillment for oral formulations and transdermal patches with standard cold-chain requirements.
- Online Pharmacies:Emerging channel for patient-administered formats with regulatory compliance varying by jurisdiction.
Hospital Pharmacies maintain procurement volume leadership. Direct Hospital Supply is expanding most quickly as manufacturers bypass intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA bioequivalence standards under 21 CFR 320 anchor the regulatory framework in the United States, while EMA MDR compliance and India's PLI scheme for pharmaceutical APIs shape competitive positioning across their respective markets. Geographic demand clusters around oncology clinic expansion in North America, transdermal adoption in Western Europe, and injectable manufacturing scale-up in South Asia.
United States
Freestanding infusion centers in Texas, Florida, and California are scaling granisetron procurement as Medicare reimbursement shifts favor site-of-care migration from inpatient to ambulatory settings. The FDA enforces bioequivalence requirements for generic antiemetics that reshape abbreviated new drug application pathways. Houston's Texas Medical Center anchors demand concentration for sterile injectable formulations serving high-volume chemotherapy protocols.
Germany
Major cancer centers in Munich and Heidelberg are adopting 5-day wear transdermal patches for moderately emetogenic regimens, eliminating rescue injection visits. EMA MDR compliance for device-drug combinations unlocks hospital formulary access previously restricted to injectable alternatives. The Rhine-Main cluster around Frankfurt concentrates patch manufacturing investment as REACH substance restrictions force reformulation of phthalate-free plasticizers.
India
Domestic manufacturers in Gujarat, Telangana, and Maharashtra are scaling 5-HT3 antagonist active pharmaceutical ingredient output for export qualification to regulated markets. The PLI scheme for pharmaceutical APIs incentivizes backward integration into precursor synthesis. Hyderabad's bulk drug manufacturing corridor anchors over 70% of global granisetron hydrochloride precursor production capacity.
United Kingdom
National Health Service procurement standardization is consolidating antiemetic purchasing around therapeutic interchange protocols privileging lowest-cost bioequivalent options. The Medicines and Healthcare products Regulatory Agency aligns with EMA MDR frameworks for transdermal patch registration. London's hospital pharmacy networks are piloting direct-to-clinic distribution bypassing wholesale intermediaries.
Brazil
ANVISA's fast-track priority review for oncology supportive care products compresses approval timelines for manufacturers seeking entry into Latin America's largest chemotherapy market. Public hospital procurement through the Unified Health System concentrates volume in southeastern states. São Paulo's oncology center network drives demand for oral tablet prophylaxis in ambulatory surgical protocols.
Global Granisetron Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with API-to-finished-dose infrastructure separating secure supply continuity from capacity-constrained competitors. The upper tier commands sterile injectable manufacturing scarcity and transdermal delivery technology differentiation. Mid-tier players compete on geographic proximity to demand clusters and regulatory filing speed. Dominant competitive moves include backward integration into active pharmaceutical ingredient production and strategic partnerships for modified-release format development.
Within the integrated manufacturing tier, Sun Pharmaceutical Industries and Hikma Pharmaceuticals exemplify archetypes that leverage captive API supply and sterile facility expertise respectively. Heron Therapeutics occupies a position defined by sustained-release delivery technology specialization. Cipla Limited and Lupin Limited represent Indian-origin generic specialists scaling export qualification to regulated markets through CDSCO-compliant stability protocols. Teva Pharmaceuticals and Viatris anchor the multi-territory generic portfolio tier, while Kyowa Kirin and Fresenius exemplify regional market-focused positioning with hospital channel depth.
| Leading Market Players |
|---|
| Sun Pharmaceutical Industries |
| Lupin Limited |
| Hikma Pharmaceuticals |
| Viatris |
| Kyowa Kirin |
| Heron Therapeutics |
| Fresenius |
| Cipla Limited |
| Teva Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Phthalate-free plasticizer substitution in transdermal patch adhesives is simultaneously relocating manufacturing investment toward REACH-compliant European suppliers and compressing margin pools as reformulation costs concentrate in the device-drug combination segment. This input transition reshapes procurement economics for manufacturers serving EMA MDR-regulated markets while creating price divergence against legacy formulations still acceptable in less stringent jurisdictions.
Pricing Analysis
Long-term offtake contracts dominate hospital pharmacy procurement, with three-tier pricing structure across premium sterile injectables, standard oral tablets, and economy generic vials differentiating on FDA bioequivalence tier and cold-chain reliability. Price differentiation stems from aseptic facility certification grade and volume scale commitments, with cost compression in the economy tier intensifying as Indian API manufacturers expand export qualification. Oncology clinics demonstrate highest price sensitivity due to Medicare reimbursement pressure, while integrated delivery networks retain leverage through consolidated purchasing authority.
Supply Chain Analysis
Strategic stockpiling of granisetron hydrochloride precursor characterizes manufacturer inventory strategy given the geographic concentration of API production. Supply draws from India, specifically Gujarat, Telangana, and Maharashtra, with secondary sourcing from China and limited US-based sterile finishing capacity. Raw material dependencies center on 5-HT3 antagonist active pharmaceutical ingredients, rate-controlling membrane polymers for patches, and halogen-free release liners. Single-source vulnerability in Indian precursor output creates structural exposure to export qualification delays. Distribution runs through direct-to-clinic channels for temperature-controlled injectables and wholesale intermediaries for oral formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Granisetron sits in early-cycle expansion as outpatient oncology migration accelerates patch adoption beyond traditional acute-care injectable dominance, with transdermal penetration in European and North American markets still below saturation thresholds.
For Market Incumbents: Compound sterile injectable manufacturing scarcity through EU GMP-compliant capacity additions in India or Eastern Europe, while securing backward integration into 5-HT3 antagonist precursor synthesis to defend against API supply disruption. Prioritize REACH-compliant adhesive reformulation investment to maintain EMA MDR device-drug combination access as regulatory scrutiny tightens on excipient classes. For New Entrants and Emerging Players: ANVISA fast-track certification for oncology supportive care products offers compressed approval timelines into Latin America's largest chemotherapy market, with Brazil's public hospital procurement through the Unified Health System representing the most penetrable volume concentration. Target transdermal patch white space in moderately emetogenic regimens where 5-day wear duration eliminates rescue injection visits, deploying direct-to-clinic distribution to bypass entrenched wholesale relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed generic portfolio companies lacking sterile injectable infrastructure, presenting consolidation targets for manufacturers seeking aseptic facility scarcity exposure. Long-term viability over a 5-10 year window hinges on modified-release format development capabilities and regulatory filing speed across US, European, and Indian jurisdictions. Watch FDA guidance evolution on complex generic bioequivalence for modified-release formats as the inflection signal determining competitive entry barriers for next-generation delivery systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Synthesis | Captive supply of 5-HT3 antagonist precursors insulates against Indian geographic concentration risk. |
| EMA MDR Compliance Investment | CE marking for transdermal device-drug combinations unlocks formulary access in German and UK cancer centers. |
| Direct-to-Clinic Distribution Buildout | Temperature-controlled injectable shipments bypass wholesale intermediaries to capture margin in Texas and Florida oncology clinics. |
| Sustained-Release Patch Development | 5-day wear duration aligns with extended chemotherapy regimens displacing nurse-administered rescue injections. |
| PLI Scheme Utilization | Indian production-linked incentives reduce precursor manufacturing cost for export qualification to regulated markets. |
Research Methodology
Initial hypotheses were tested against primary input from regulatory affairs leads at transdermal patch manufacturers, hospital pharmacy procurement managers, and CDSCO compliance officers, and refined through secondary validation against FDA 21 CFR 320 bioequivalence filings, EMA MDR submission databases, and Indian PLI scheme disclosure records. Bottom-up demand modeling across dosage forms, therapy areas, and end-user segments triangulated with top-down market sizing from customs trade data and hospital procurement databases.
Variance decomposition across the projection horizon isolates volume drivers by delivery technology adoption curve, regulatory approval timeline dispersion, and site-of-care migration velocity. Segmentation dimensions modeled include product type hierarchy, chemotherapy versus surgical prophylaxis indication split, and regional regulatory cluster alignment. CAGRs derive from patient-volume projections tied to oncology protocol standardization and ambulatory surgery expansion, with cross-referencing to Medicare reimbursement shift trajectories and EMA MDR implementation pace.
Underlying assumptions cover REACH substance restriction enforcement continuity, PLI scheme extension, and FDA complex generic guidance stability, with deviation risk concentrated in API export qualification delays from Indian manufacturing corridors and transdermal bioequivalence pathway uncertainty. Revision becomes warranted when EMA MDR compliance cost thresholds exceed patch manufacturing margin capacity or when alternative 5-HT3 antagonist generic entry accelerates beyond modeled therapeutic interchange timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Small-Molecule Injectable Market
Pharmaceutical Ingredients
Pharmaceutical Grade Sodium Carbonate Market
Pharmaceutical Ingredients
Pharmaceutical Grade Hyaluronic Acid Market
Pharmaceutical Ingredients
Global Sugar-Based Excipients Market
Pharmaceutical Ingredients
Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market
Pharmaceutical Ingredients
Pemetrexed Market
Pharmaceutical Ingredients
Biologic Excipients Market
Pharmaceutical Ingredients
Anti-Allergic Agent Ingredients Market
Pharmaceutical Ingredients
United States Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Duloxetine API Market
Pharmaceutical Ingredients
Cetrorelix Acetate API Market
Pharmaceutical Ingredients
Piperacillin Sodium API Market
Pharmaceutical Ingredients
Glycylglycine Market
Pharmaceutical Ingredients
Lidocaine Hydrochloride Market
Pharmaceutical Ingredients
Antibiotics Active Pharmaceutical Ingredient (API) Market
Pharmaceutical Ingredients
Pharmaceutical Fine Chemicals Market