
 Global Aluminum Hydroxide Market | 2026-2036
Global Aluminum Hydroxide Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aluminum Hydroxide Market Foresight
A widening capital-intensity gap between integrated refiners and specialty chemical producers is redrawing competitive boundaries in aluminum hydroxide supply. Almatis leverages its captive alumina refining network to sustain cost leadership across high-purity grades. Huber Engineered Materials differentiates through advanced precipitation technologies that command premium positioning in pharmaceutical and electronics applications. Nabaltec AG anchors its European operations with dedicated flame retardant compounding capabilities, competing on specification breadth rather than volume scale.
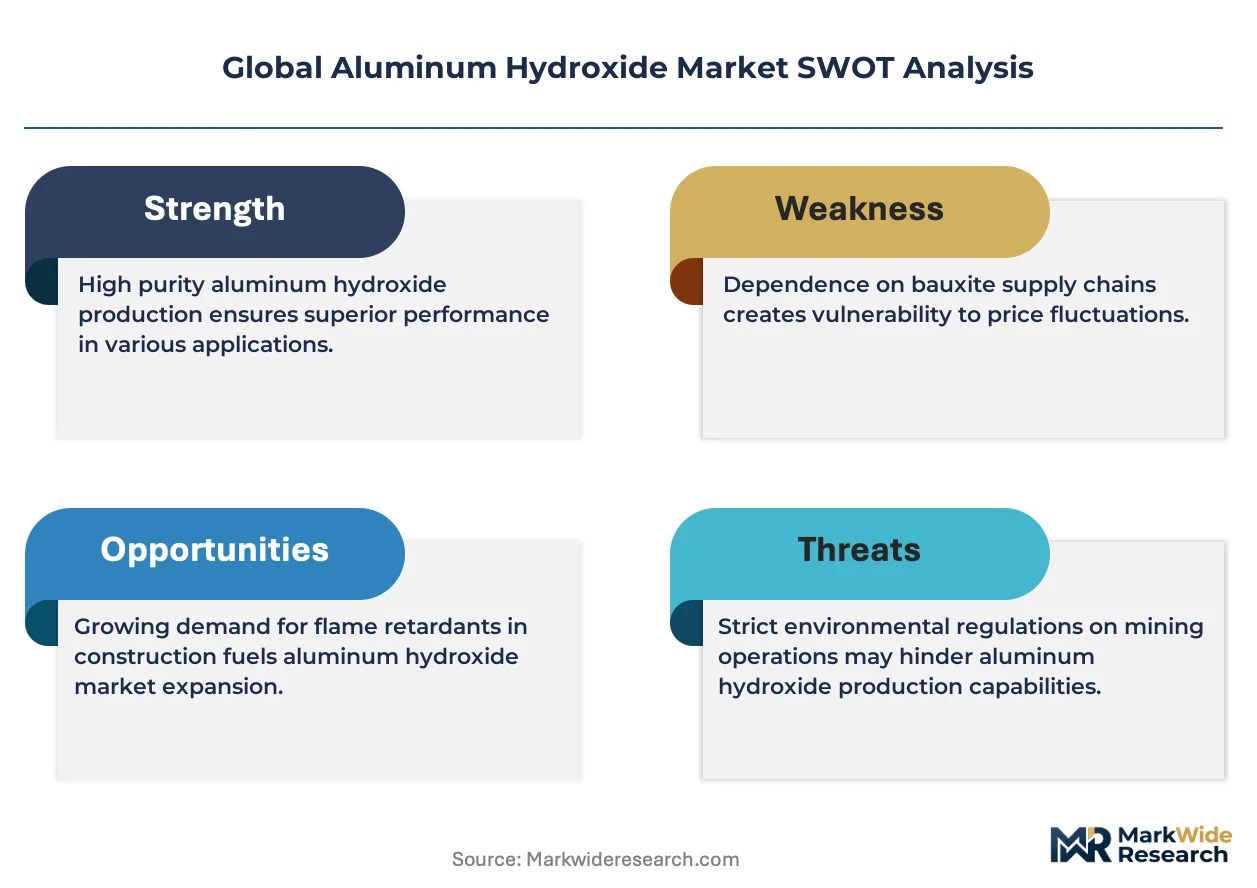
Aluminum hydroxide, chemically Al(OH)3 with typical purity thresholds spanning 99.0% to 99.9% depending on precipitation and calcination protocols, functions primarily as a halogen-free flame retardant filler, pH buffering agent, and active pharmaceutical ingredient precursor. Pharmaceutical-grade material commands the tightest specification windows and associated margin pools, while medium-grade output serves as the volume backbone for construction and paper applications. Flame retardant demand in wire and cable compounds is expanding fastest, though water treatment procurement remains structurally price-sensitive and fragmented across municipal buyers.
REACH registration requirements and the EU F-Gas Regulation are elevating environmental compliance costs for European producers, while China's GB standards and MEE enforcement are tightening effluent controls around alumina refining corridors. The FDA's ICH Q3D guidelines on elemental impurities are reshaping pharmaceutical-grade certification protocols for suppliers targeting U.S. drug manufacturers. Stakeholders must weigh regulatory divergence against regional demand concentration when configuring capacity investments and qualification strategies.
Market Dynamics
Flame retardant specification tightening across wire and cable applications is restructuring procurement priorities, with buyers now requiring halogen-free fillers that meet simultaneous thermal performance and toxicity thresholds. This regulatory compression is forcing reformulation investments across compounders serving construction and electronics verticals.
Growth Catalysts
- REACH F-Gas Regulation:European environmental mandates are accelerating substitution away from brominated flame retardants toward aluminum hydroxide in electrical insulation compounds.
- Wire and cable compounding:Infrastructure electrification projects in China and India are pulling medium-grade material into high-volume jacketing applications.
- GB standards enforcement:China's Ministry of Ecology and Environment is tightening effluent controls around alumina refining corridors, consolidating supply among compliant producers.
Market Restraints
- Caustic soda volatility:Bayer process input costs fluctuate with energy-intensive chlor-alkali production economics, compressing margins for non-integrated precipitators.
- Guangxi and Shandong concentration:Chinese smelter-grade alumina overcapacity creates sporadic dump pricing that disrupts specialty chemical pricing discipline.
- Surface area limitations:Standard precipitation protocols cap specific surface area below what certain high-performance thermoset applications require.
Strategic Opportunities
- India construction chemicals:Underpenetrated fireproofing coatings sector offers white space for precipitated grades with controlled particle size distribution.
- Electric vehicle battery enclosures:Thermal runaway protection requirements are opening specification windows for nano-precipitated variants in composite housings.
- US FDA ICH Q3D alignment:Elemental impurity guideline harmonization creates qualification pathways for pharmaceutical-grade suppliers targeting ANDA filers.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA drug master file preparation and ICH Q3D validation protocols extend qualification cycles to 18-24 months.
- Continuous precipitation engineering:Capex requirements for controlled crystal growth systems exceed mid-tier chemical processors' balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aluminum Hydroxide Market |
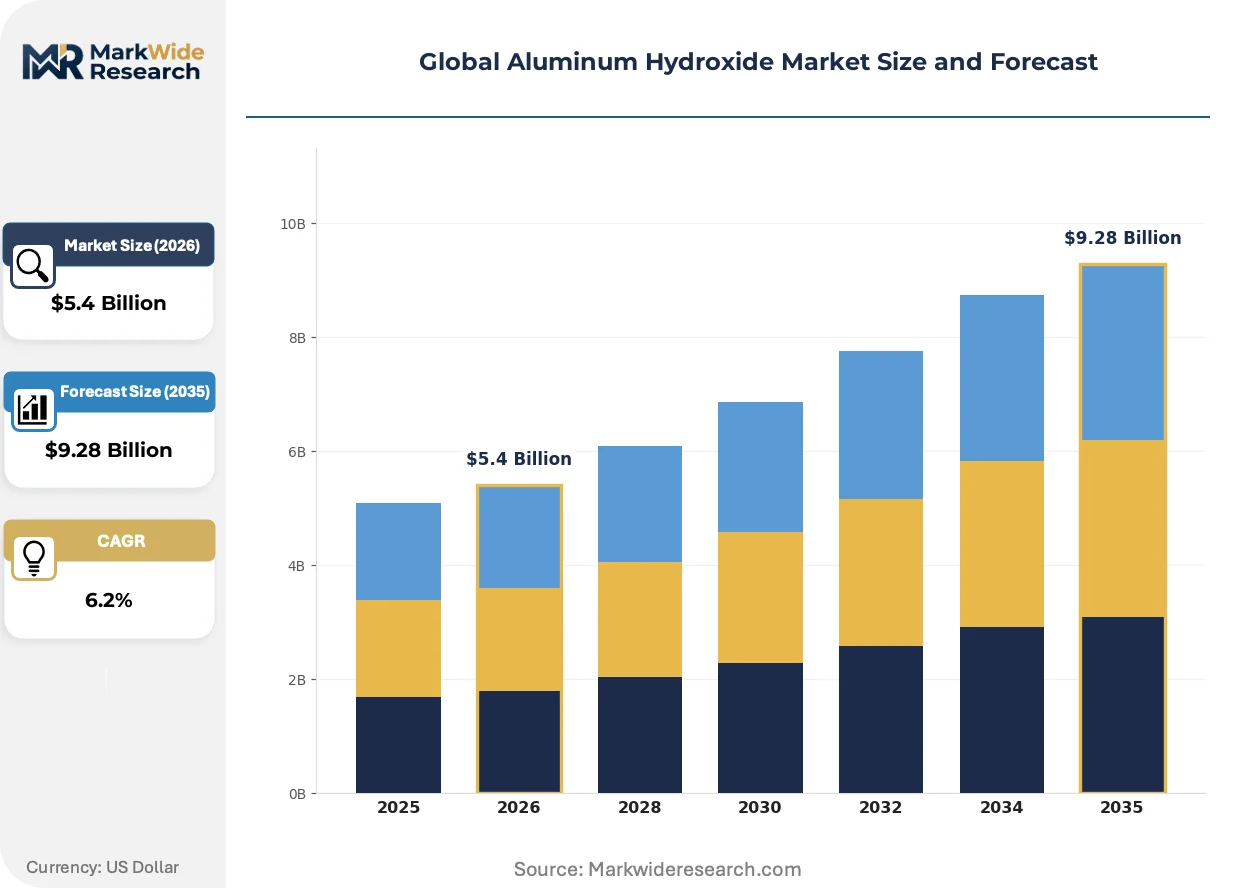
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Grade, Medium-Grade, Low-Grade, Pharmaceutical-Grade Application: Flame Retardants, Fillers, Antacids, Water Treatment, Paper Coating End User Industry: Chemicals, Pharmaceuticals, Construction Materials, Water Purification, Paper Manufacturing Packaging Type: Bagged, Bulk, Drum, Super Sack, Loose |
| Companies Covered | Almatis, Huber Engineered Materials, Aluminum Corporation of China Limited, Sumitomo Chemical Co. Ltd., Alteo, Nabaltec AG, Sibelco, Showa Denko K.K., Alcoa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aluminum Hydroxide Market Shifts & Advancements
Surface modification chemistry and particle engineering are redefining performance benchmarks across flame retardant and pharmaceutical applications, with functionalization now separating commodity from premium positioning.
Nano-precipitated aluminum hydroxide with silane surface treatment is displacing conventional ground-grade material in high-voltage cable compounds. European wire manufacturers are adopting these grades to meet CPR Class B2ca smoke density requirements. The technology is displacing legacy ATH loadings above 60% by weight while maintaining equivalent flame suppression.
REACH registration dossier updates and the EU F-Gas Regulation are elevating environmental compliance costs for European producers. Industrial consequence includes accelerated plant closures among non-integrated precipitators unable to absorb toxicity testing expenditures. Wire and cable compounders in Germany and Poland are responding by dual-sourcing from Middle Eastern refiners with captive ATH streams.
Specification-driven procurement is compressing supplier qualification cycles from multi-year frameworks to annual re-tendering with embedded performance guarantees. Distributor relationships are being disintermediated by direct technical service engagements between precipitators and compounders. This pattern is most visible in China's electronics manufacturing clusters around Shenzhen and Dongguan.
Global Aluminum Hydroxide Market Segmentation
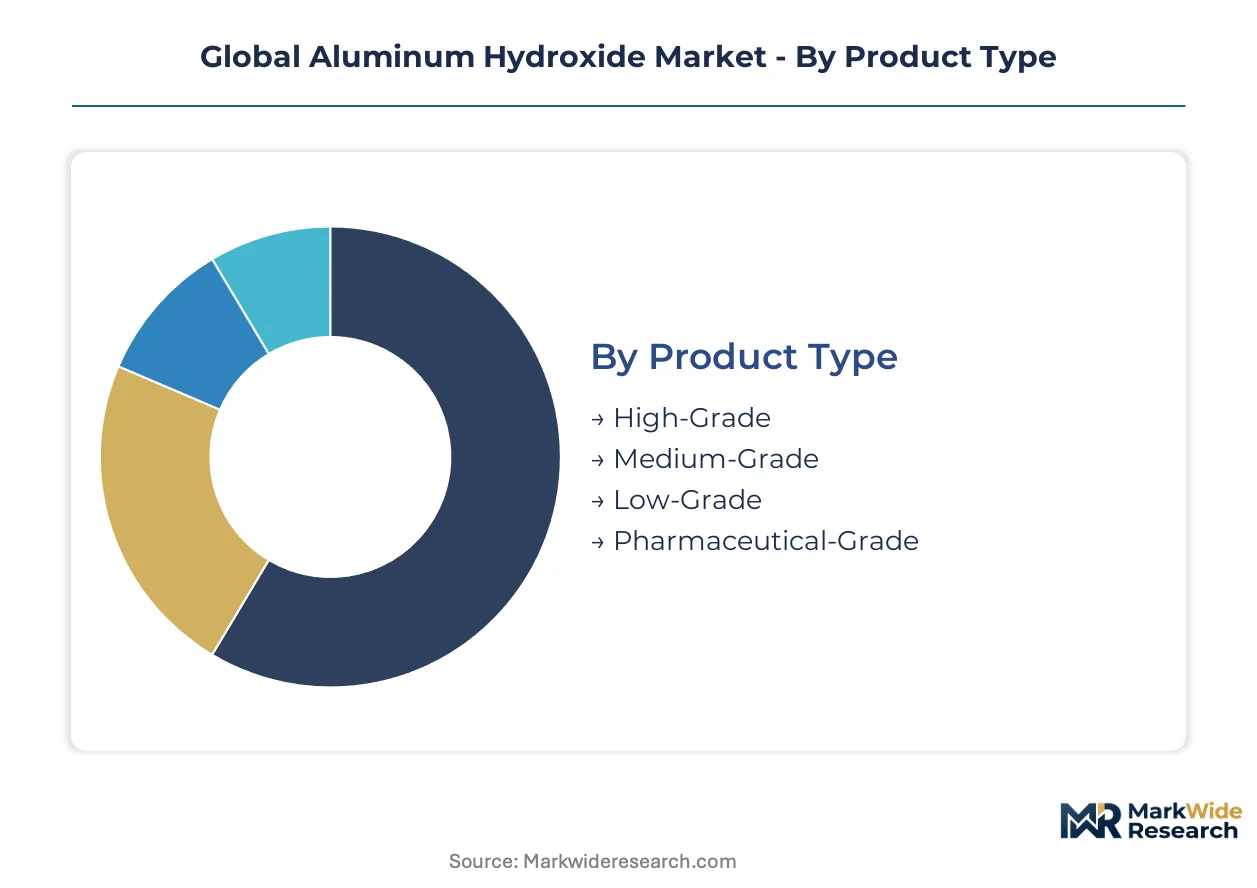
Segmentation in aluminum hydroxide separates specification-driven premium tiers from commodity volume plays. Pharmaceutical and flame retardant grades operate under divergent regulatory regimes and margin structures, while packaging and application choices reflect downstream handling economics and purity requirements.
Product Type:
Substitute pressure from precipitated calcium carbonate and magnesium hydroxide intensifies at the lower purity tiers, forcing grade-specific defensive positioning.
- High-Grade:Material meeting 99.5-99.9% purity thresholds through controlled precipitation and calcination protocols. Electronics manufacturers in Germany and Japan specify these grades for high-voltage cable compounds where thermal stability and low ionic contamination are non-negotiable.
- Pharmaceutical-Grade:Tightest specification windows with elemental impurity controls aligned to FDA ICH Q3D and EMA guidelines. Antacid manufacturers in the United States and India require dedicated drug master file documentation, creating 18-24 month qualification barriers that protect incumbent suppliers.
- Medium-Grade:Volume backbone for construction materials and paper applications, typically 99.0-99.5% purity.
- Low-Grade:Ground material serving price-sensitive water treatment and industrial filler markets with minimal surface area requirements.
Medium-grade retains volume leadership; pharmaceutical-grade holds the steepest expansion curve.
Application:
Cost tier stratification separates specification-captive applications from commodity procurement where price sensitivity dominates supplier selection.
- Flame Retardants:Halogen-free filler demand in wire and cable compounds is restructuring procurement priorities across European and Chinese manufacturing clusters. CPR Class B2ca smoke density requirements in Germany and Poland are accelerating substitution away from brominated alternatives.
- Antacids:Active pharmaceutical ingredient precursor subject to FDA and CDSCO certification protocols. Formulation stability and taste masking requirements favor precipitated grades with controlled particle morphology over ground alternatives.
- Fillers:Extender applications in plastics and rubber where surface area and oil absorption specifications determine suitability.
- Water Treatment:Municipal and industrial buyers prioritize unit dosing economics over performance differentiation, fragmenting supply across regional distributors.
- Paper Coating:Brightness and opacity specifications in printing paper applications, competing against kaolin and calcium carbonate alternatives.
Flame retardant applications command premium positioning; antacids are climbing the fastest on regulatory tailwinds.
End User Industry:
Customer type concentration creates divergent service intensity requirements, with pharmaceutical and chemical processors demanding technical support that commodity buyers reject.
- Chemicals:Compounders serving wire and cable, plastics, and rubber markets require consistent lot-to-lot surface area and particle size distribution for automated feeding systems.
- Pharmaceuticals:ANDA filers and contract manufacturers in the United States and India drive qualification-driven procurement with embedded audit requirements and supply continuity guarantees.
- Construction Materials:Fireproofing coatings and insulation board manufacturers in India and Southeast Asia represent underpenetrated white space for precipitated grades with controlled particle size distribution.
- Water Purification:Municipal treatment plants and industrial processors operate on annual tender cycles with minimal technical specification differentiation.
- Paper Manufacturing:Integrated mills and specialty paper producers balance brightness requirements against kaolin and calcium carbonate substitution economics.
Construction materials retain volume leadership; pharmaceuticals hold the steepest expansion curve.
Packaging Type:
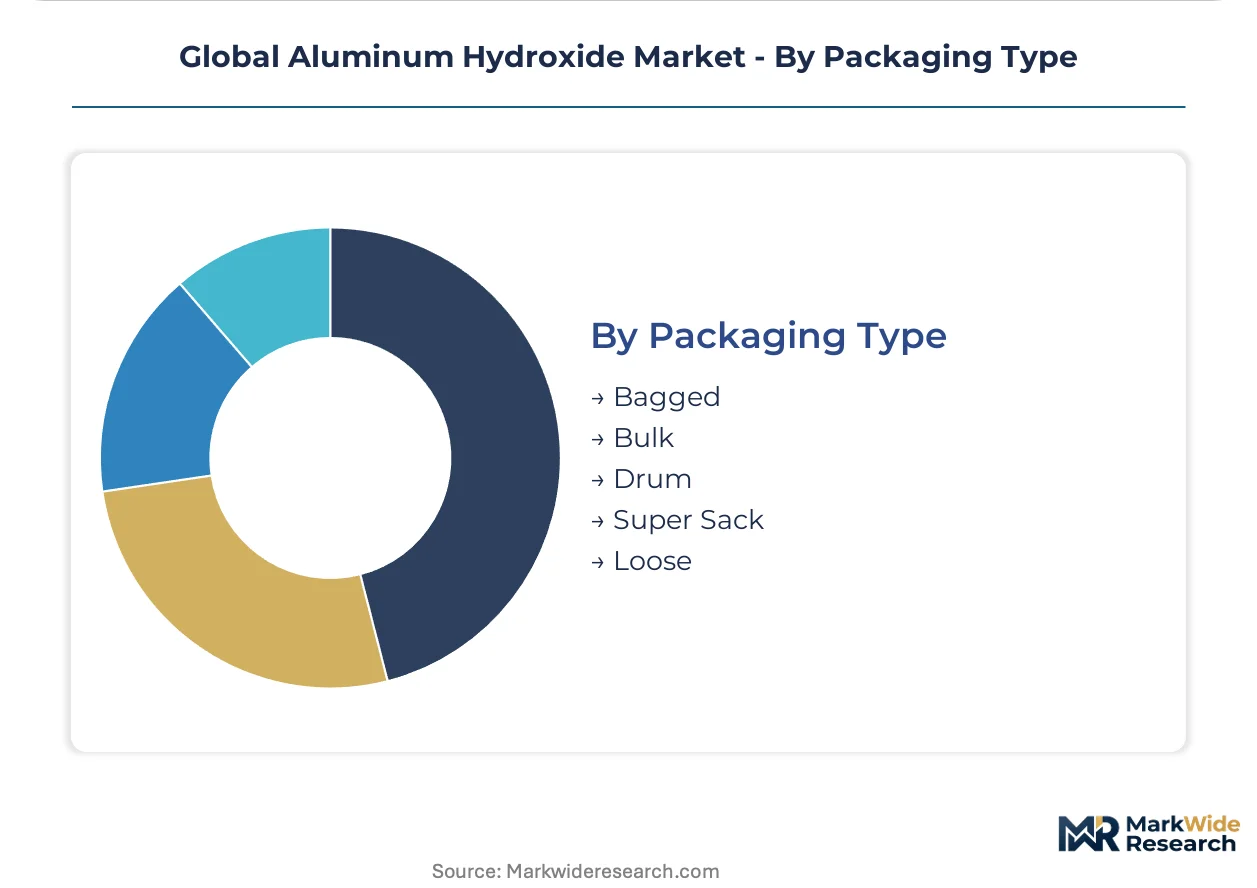
Supply concentration in alumina refining corridors shapes packaging economics, with bulk and super sack formats dominating high-volume offtake from integrated producers.
- Bulk:Tanker and pneumatic trailer delivery for high-volume flame retardant compounders and paper mills with dedicated unloading infrastructure.
- Super Sack:Intermediate bulk containers serving mid-volume chemical processors requiring forklift handling without dedicated silo systems.
- Bagged:25-50 kg multi-wall paper or polyethylene bags for pharmaceutical and specialty chemical buyers with batch-scale processing.
- Drum:Fiber or steel drums for pharmaceutical-grade material requiring contamination protection and lot traceability.
- Loose:Railcar and barge shipments from refining corridors to downstream compounding facilities with captive handling systems.
Bulk formats retain volume leadership; super sack configurations are gaining share fastest on flexibility advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry separates Chinese integrated refiners from European specialty precipitators, with the former capturing volume economics and the latter defending specification premiums. Regulatory divergence across REACH, EPA, and GB standards is fragmenting procurement strategies by geography. Construction and electronics clusters in Asia-Pacific pull medium-grade material, while pharmaceutical-grade demand concentrates in Germany, the United States, and Japan.
China
Construction materials and electronics manufacturing in Guangxi and Shandong corridors drive bulk consumption of medium and high-grade variants. MEE enforcement of GB standards tightens effluent controls around alumina refining, consolidating supply among compliant producers. Shenzhen and Dongguan electronics clusters specification-drive procurement with annual re-tendering and embedded performance guarantees.
Germany
Wire and cable compounders serving infrastructure electrification pull nano-precipitated grades for CPR Class B2ca smoke density compliance. REACH F-Gas Regulation accelerates substitution from brominated flame retardants toward aluminum hydroxide in electrical insulation. Industrial concentration around Cologne and Leverkusen supports dual-sourcing strategies from Middle Eastern refiners with captive ATH streams.
United States
Antacid manufacturers and ANDA filers drive pharmaceutical-grade demand subject to FDA ICH Q3D elemental impurity protocols. EPA standards for flame retardant applications tighten purity benchmarks, extending qualification cycles. Gulf Coast chemical processors balance caustic soda input volatility against specialty chemical margin pools.
India
Underpenetrated fireproofing coatings and construction chemicals sectors offer white space for precipitated grades with controlled particle size distribution. CDSCO certification requirements for pharmaceutical applications create parallel qualification pathways to FDA protocols. Maharashtra and Gujarat industrial corridors concentrate bulk chemical processing capacity.
Japan
Electronics manufacturers specify high-purity grades for high-voltage cable compounds where thermal stability and low ionic contamination are non-negotiable. METI industrial standards shape procurement frameworks for flame retardant applications. Osaka and Nagoya industrial clusters anchor specialty chemical demand for nano-precipitated variants.
Global Aluminum Hydroxide Market Competitive Landscape
Concentration sits with integrated alumina refiners and specialty precipitators occupying distinct margin tiers. The vendor base separates into three strategic archetypes: captive refiners leveraging upstream bauxite-alumina integration, precipitation specialists commanding premium positioning through particle engineering, and regional compounders serving construction and paper volume segments. Dominant competitive moves include backward integration into alumina refining and technology licensing for controlled crystal growth systems.
Among German-based specialty chemical producers, Nabaltec AG exemplifies the flame retardant compounding archetype. Almatis occupies a position within the integrated refiner tier, while Huber Engineered Materials represents the advanced precipitation technology vector. These three anchors illustrate how geographic origin and corporate structure map to divergent competitive strategies across specification-captive versus volume-driven market segments.
| Leading Market Players |
|---|
| Almatis |
| Huber Engineered Materials |
| Aluminum Corporation of China Limited |
| Sumitomo Chemical Co. Ltd. |
| Alteo |
| Nabaltec AG |
| Sibelco |
| Showa Denko K.K. |
| Alcoa Corporation |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day qualification cycles for pharmaceutical-grade material concentrate pricing power among incumbent precipitators with validated drug master files, while caustic soda cost pass-through mechanisms in non-integrated operations compress margins at the commodity end. This lead-time asymmetry separates specification-captive premiums from volume-driven spot markets across Chinese refining corridors and European specialty chemical clusters.
Pricing Analysis
The customization-premium spread between configured-to-order nano-precipitated grades and standard ground material spans three distinct certification tiers. Contract-based long-term offtake agreements dominate pharmaceutical and high-voltage cable segments, while commodity spot trading governs water treatment procurement. Price differentiation rests on FDA ICH Q3D validation status and REACH registration completeness. Cost compression in medium-grade construction applications is intensifying because Chinese smelter-grade alumina overcapacity periodically floods adjacent specialty chemical channels. Municipal water treatment buyers exhibit highest price sensitivity; antacid manufacturers demonstrate lowest sensitivity due to eighteen-to-twenty-four-month supplier switching costs.
Supply Chain Analysis
Container availability constraints on Middle East-to-Europe trade lanes have elevated inbound logistics costs for German and Polish compounders dual-sourcing from non-integrated precipitators. Supply concentrates in China, Germany, and the United States, with captive alumina refining in Shandong and Guangxi corridors feeding downstream precipitation operations. Raw material dependencies center on bauxite ore quality, caustic soda pricing, and natural gas for calcination energy. Single-source vulnerability around pharmaceutical-grade validation protocols creates qualification bottlenecks that resist rapid supplier substitution. Distribution runs through direct technical service engagements between precipitators and compounders, bypassing traditional distributor relationships in Shenzhen and Dongguan electronics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flame retardant specification tightening across wire and cable applications signals early-cycle expansion, with infrastructure electrification in China and India pulling medium-grade material into high-volume jacketing applications faster than incumbent capacity can qualify replacement grades.
For Market Incumbents: Fortify qualification moats by accelerating FDA drug master file updates for ICH Q3D elemental impurity protocols before ANDA filers consolidate supplier panels. Deepen upstream control over alumina refining capacity in Shandong or Leverkusen corridors to absorb caustic soda volatility that threatens non-integrated precipitators. Magnesium hydroxide substitution in lower-purity construction tiers represents the most pressing substitute technology threat; counter with nano-precipitated surface area advantages in CPR Class B2ca applications. For New Entrants and Emerging Players: Differentiate on particle engineering capabilities for electric vehicle battery enclosure thermal runaway protection, where nano-precipitated variants with silane surface treatment command specification premiums absent from commodity flame retardant markets. Target India's underpenetrated fireproofing coatings sector through precipitated grades with controlled particle size distribution that construction chemical formulators cannot source from integrated refiners. Pursue technical partnership pathways with Maharashtra and Gujarat industrial corridor compounders rather than direct qualification against entrenched pharmaceutical-grade incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with captive ATH streams but neglected precipitation technology portfolios, particularly European operations facing REACH F-Gas Regulation compliance cost absorption challenges. Five-to-ten-year viability favors specialists with validated pharmaceutical-grade certification pipelines over volume-commodity positions exposed to Chinese dump pricing. Monitor CDSCO alignment with FDA ICH Q3D protocols as the critical inflection signal for Indian pharmaceutical-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Refining | Captive bauxite-to-ATH control insulates margin pools from chlor-alkali caustic soda volatility. |
| Nano-Precipitation Capacity Expansion | Silane surface treatment capabilities unlock CPR Class B2ca smoke density compliance premiums in German cable compounds. |
| Pharmaceutical-Grade Certification Investment | FDA drug master file validation creates eighteen-to-twenty-four-month switching costs protecting incumbent antacid supply positions. |
| Regional Compounding Joint Venture | Localized precipitation in Maharashtra corridors reduces logistics exposure for Indian construction chemical penetration. |
| REACH Registration Dossier Update | Toxicity testing expenditure absorption consolidates supply among compliant European producers as MEE enforcement tightens. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at precipitation facilities, procurement leads at wire and cable compounders, and technical R&D directors at pharmaceutical formulators; and secondary validation through customs and trade data, SEC 10-K filings of integrated alumina producers, and ECHA REACH registration dossiers. Bottom-up triangulation across grade-specific production volumes and top-down cross-check against end-use consumption patterns anchored market sizing integrity.
Across the analysis window, forecasts modeled grade tier stratification, end-use industry concentration, packaging format economics, and regional regulatory cluster divergence. CAGRs derived from weighted capacity expansion pipelines, substitution elasticity estimates for brominated flame retardants, and pharmaceutical qualification cycle duration assumptions. Specific inputs included MEE enforcement trajectory for GB standards compliance and infrastructure electrification capex commitments in India and China.
The analysis sits within stated boundaries; outcomes outside sustained REACH F-Gas Regulation enforcement, continued Chinese construction materials demand, or stable FDA ICH Q3D protocol adherence would require recalibration. Forecasts reflect documented assumptions regarding caustic soda pricing corridors and bauxite ore quality availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
3-Fluoro-5-Nitrotoluene Market
Chemicals
United States Construction Chemicals Market
Chemicals
Canada Methanol Market
Chemicals
Tributyl Phosphate Market
Chemicals
Global E Series Glycol Ether Market
Chemicals
Isopropanolamine Market
Chemicals
Aluminium Chloride Market
Chemicals
Anticoagulant Rodenticides Market
Chemicals
Piroctone Olamine Market
Chemicals
Photographic Chemicals Market
Chemicals
Global Hydrogen Fluoride Market
Chemicals
India Ethoxylates Market
Chemicals
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market
Chemicals
Nonaisoprenol Market
Chemicals
Cumene Hydroperoxide Market
Chemicals
China Inorganic Iodide Market