
 North America Pharmaceutical Plastic Packaging Market | 2026-2036
North America Pharmaceutical Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pharmaceutical Plastic Packaging Market Insights
Biologics manufacturers are redrawing procurement priorities across the North America pharmaceutical plastic packaging landscape as temperature-sensitive therapies multiply. Amcor PLC leverages its multilayer blow-molding infrastructure to dominate high-barrier bottles for parenteral applications. Berry Global Group Inc. anchors North American supply through its extensive thermoforming footprint for blister and clamshell formats. West Pharmaceutical Services Inc. differentiates via integrated delivery systems that combine elastomeric closure technology with precision-molded plastic components.
Pharmaceutical plastic packaging encompasses polymer-based containment and delivery systems engineered to meet USP Class VI biocompatibility, moisture vapor transmission rates below specified thresholds, and particulate contamination limits measured per ASTM standards. These structures protect drug stability from manufacturing through patient administration while enabling automated filling lines and child-resistant functionality. Bottles retain the largest volume share across oral solid dosage applications, though blisters gain ground in adherence packaging for chronic disease management. Polypropylene leads material selection for autoclave-compatible containers, while PET displaces PVC in blister formats as healthcare systems prioritize halogen-free alternatives.
FDA enforces Current Good Manufacturing Practice regulations that dictate validation protocols for plastic packaging used in drug applications, while USP chapters set physicochemical and biological reactivity testing benchmarks for extractables and leachables. Health Canada and PMRA align with ICH guidelines for container closure integrity, creating cross-border compliance obligations for suppliers serving integrated North American supply chains. Stakeholders must monitor evolving EPR legislation in multiple Canadian provinces and pending state-level packaging waste mandates across the United States that threaten to impose material recovery requirements on pharmaceutical-grade plastics.
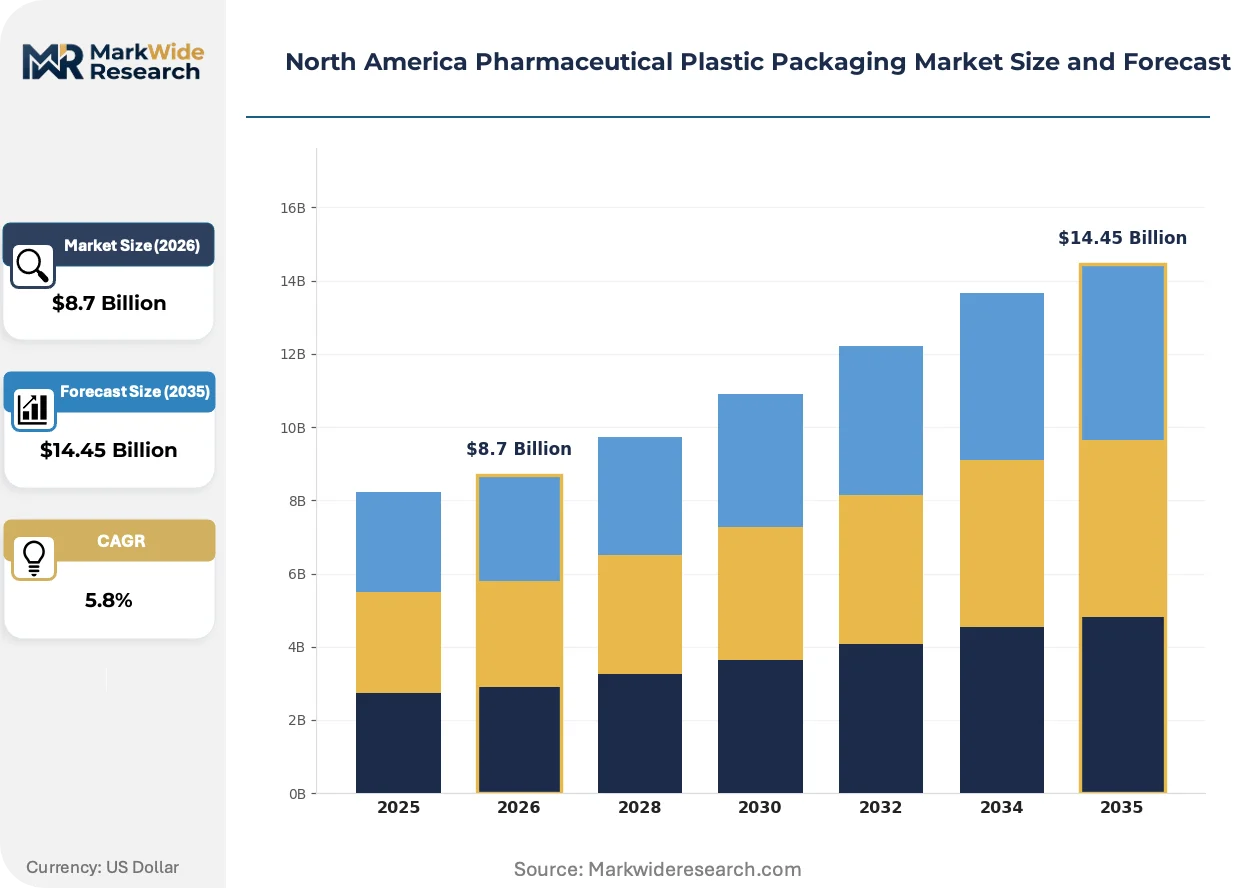
Market Dynamics
Contract manufacturing organizations are consolidating fill-finish procurement around barrier-grade plastic containment systems, compressing supplier qualification timelines and elevating technical specification thresholds across the value chain.
Growth Catalysts
- FDA serialization mandates:Track-and-trace requirements for pharmaceutical packaging are accelerating capital deployment into integrated labeling and verification systems across United States manufacturing facilities.
- Biologics cold-chain expansion:Temperature-sensitive therapies are multiplying demand for multilayer structures with validated thermal protection profiles in parenteral applications.
- Halogen-free material transition:Healthcare systems are prioritizing PET displacement of PVC in blister formats, creating specification pull-through from hospital procurement networks.
Market Restraints
- Resin cost volatility:Polypropylene and PET feedstock prices fluctuate with crude oil derivatives, compressing margin predictability for converters serving long-term pharmaceutical contracts.
- Supplier concentration risk:Northeast United States manufacturing clusters around Boston and New Jersey create geographic vulnerability to regional logistics disruptions or weather events.
- Extractables testing burden:USP chapters governing physicochemical and biological reactivity testing extend qualification timelines for new material introductions.
Strategic Opportunities
- Canadian EPR alignment:Extended producer responsibility legislation across multiple provinces will reward early movers in pharmaceutical-grade plastic recovery infrastructure.
- Adherence packaging formats:Blister and clamshell structures for chronic disease management represent underpenetrated volume relative to oral solid dosage bottles.
- Elastomeric-plastic integration:Convergence of precision-molded plastic components with closure technology opens integrated delivery system architectures.
Industry Challenges
- Container closure integrity certification:USP standards validation protocols demand specialized metrology capabilities that strain mid-tier converter technical resources.
- Cross-border compliance synchronization:Health Canada and PMRA alignment with ICH guidelines creates documentation complexity for suppliers serving integrated United States-Canada supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pharmaceutical Plastic Packaging Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Bottles, Blisters, Bags, Capsules Material: Polyethylene, Polypropylene, PVC, PET End User: Pharmaceutical Companies, Contract Manufacturers, Distributors, Retailers Application: Injectables, Oral Medications, Topicals, Vaccines |
| Companies Covered | Amcor PLC, Berry Global Group Inc., Gerresheimer AG, AptarGroup Inc., West Pharmaceutical Services Inc., Tekni-Plex Inc., Drug Plastics & Glass Company Inc., Alpha Packaging Inc., Pretium Packaging LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pharmaceutical Plastic Packaging Market Trends and Innovations
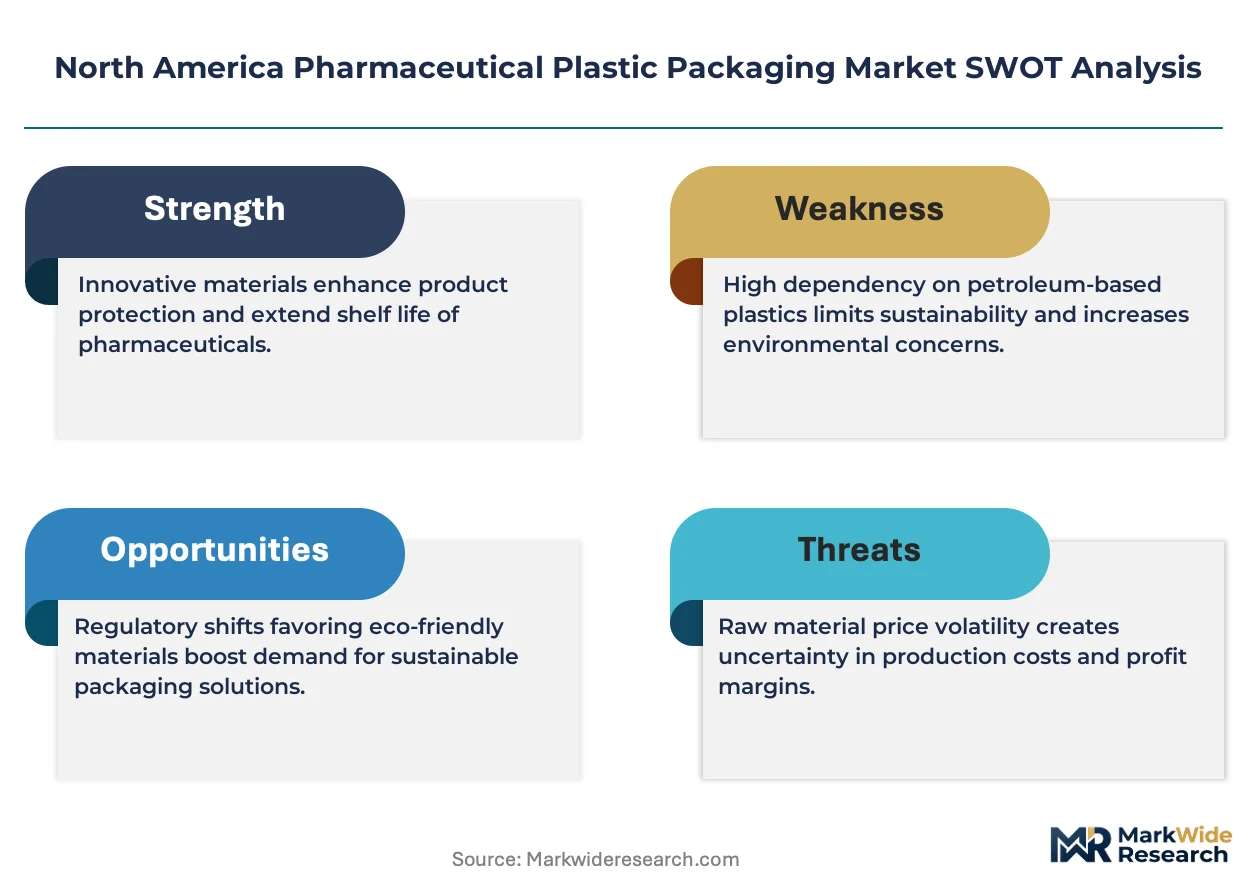
Multilayer co-extrusion and advanced barrier coatings are redefining performance benchmarks for moisture-sensitive formulations, while regulatory pressure on material transparency accelerates substitution cycles across primary packaging categories.
Cyclic olefin polymers are supplanting traditional thermoplastics in high-purity parenteral applications due to superior extractables profiles and glass-like clarity. Biologics manufacturers are adopting these materials at accelerated qualification paces to meet USP Class VI biocompatibility thresholds. This transition is compressing incumbent resin suppliers' pricing power in premium containment segments.
Health Canada and PMRA container closure integrity guidelines are tightening validation documentation requirements for cross-border pharmaceutical shipments. Manufacturers must now demonstrate equivalent testing protocols across United States and Canadian regulatory submissions. Parenteral packaging suppliers serving integrated North American supply chains are responding by harmonizing quality management systems to dual-jurisdiction standards.
Hospital and pharmacy buying consortia are consolidating procurement decisions around pre-qualified supplier lists with demonstrated serialization readiness. Traditional distributor-centric purchasing is yielding to direct manufacturer relationships with integrated service agreements. This pattern concentrates most visibly in the Northeast United States, where pharmaceutical manufacturing density enables consolidated logistics and technical service bundling.
North America Pharmaceutical Plastic Packaging Market Segmentation
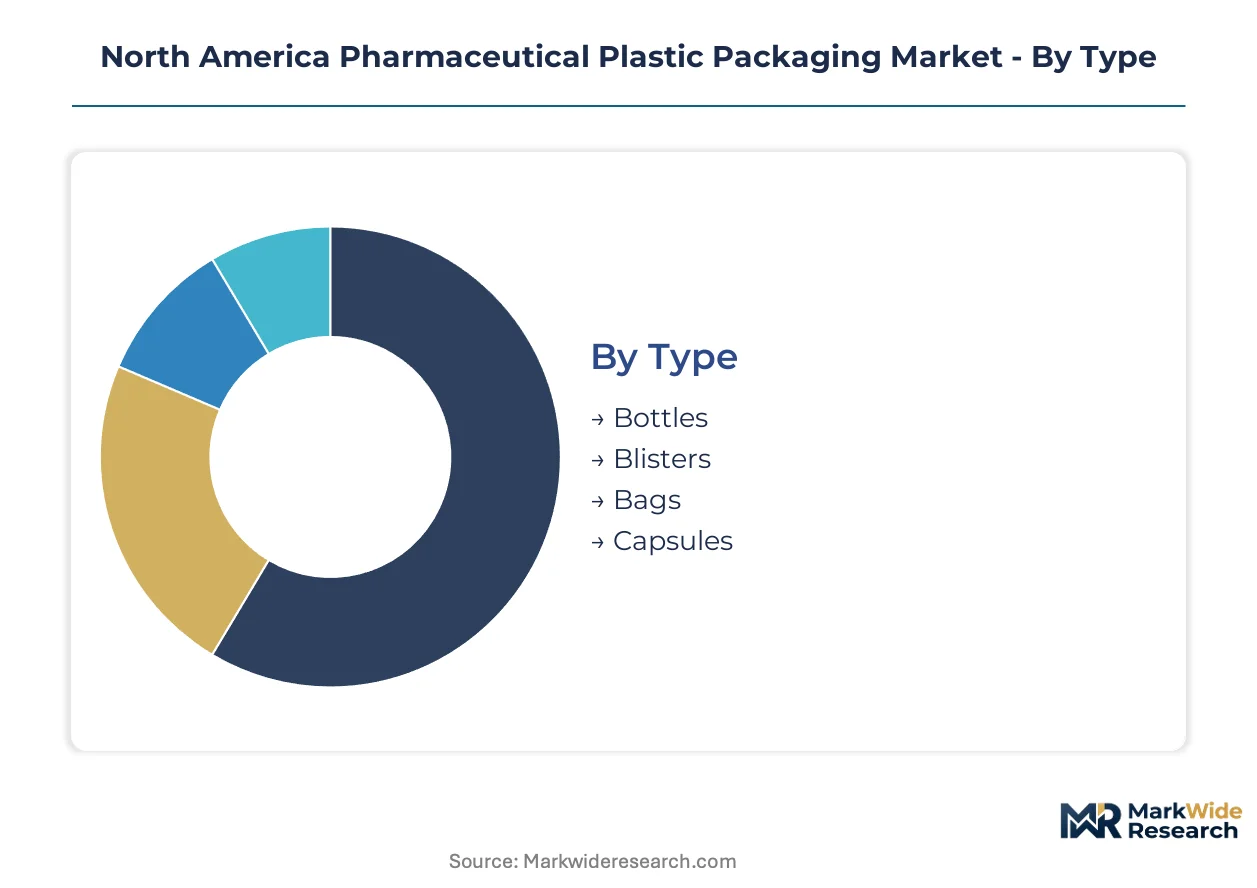
Segmentation in pharmaceutical plastic packaging reveals how specification requirements diverge across containment formats, polymer chemistries, and end-user procurement patterns. Each dimension carries distinct qualification burdens and margin structures that reshape supplier competitive positioning.
Type:
Bottles face intensifying substitution pressure from adherence-focused blister formats as chronic disease protocols multiply, while bags confront competition from pre-filled syringe systems in parenteral delivery.
- Bottles:HDPE and PET multilayer structures dominate oral solid dosage containment with validated moisture vapor transmission barriers. Northeast United States pharmaceutical clusters around Boston and New Jersey sustain dense supplier networks for high-volume bottle procurement. Bottles anchor the volume base while blisters gain share at the steepest rate.
- Blisters:Thermoformed PVC and PET laminates with push-through or peelable lidding enable unit-dose adherence packaging for hypertension and diabetes therapies. Hospital buying consortia in the United States are consolidating procurement around halogen-free PET specifications, displacing incumbent PVC volumes.
- Bags:IV solution and parenteral nutrition containers utilize multilayer films with ethylene vinyl acetate tie layers for flex crack resistance. Contract manufacturers are compressing supplier qualification timelines for barrier-grade bag systems as outsourcing accelerates.
- Capsules:Two-piece hard gelatin shells with polymer-based banding or HPMC vegetarian alternatives serve powder and granule formulations. Health Canada container closure integrity guidelines are tightening validation documentation for capsule shipments across United States-Canada supply chains.
Bottles retain procurement volume leadership though blisters climb fastest as adherence protocols expand.
Material:
Cost tier stratification separates commodity resins from specialty polymers, with qualification timelines and testing burdens scaling directly with purity specifications.
- Polyethylene:HDPE delivers chemical resistance and autoclave compatibility for oral solid dosage bottles across United States manufacturing facilities. FDA serialization mandates are accelerating capital deployment into integrated labeling systems for PE-based containment.
- Polypropylene:Clarified and nucleated PP grades offer glass-like transparency with superior drop resistance for parenteral vials and syringe components. Cyclic olefin polymers are supplanting traditional thermoplastics in high-purity applications due to superior extractables profiles, compressing incumbent PP pricing power in premium segments.
- PVC:Rigid and plasticized vinyl formulations persist in blister lidding and IV bag applications despite halogen-free transition pressures. Healthcare systems in the United States are prioritizing PET displacement of PVC, creating specification pull-through from hospital procurement networks.
- PET:Biaxially oriented and blow-molded grades deliver oxygen and moisture barriers for pharmaceutical bottles and blister webs. Resin cost volatility with crude oil derivatives compresses margin predictability for converters serving long-term PET contracts.
Polyethylene and polypropylene dominate procurement tonnage while cyclic olefin specialty grades expand most quickly in parenteral applications.
End User:
Customer type determines specification authority, with direct manufacturers wielding formulation-specific requirements that distributors and retailers cannot modify.
- Pharmaceutical Companies:Branded and generic drug manufacturers dictate primary packaging specifications tied to stability data and regulatory submissions. USP chapters governing extractables and leachables extend qualification timelines for new material introductions at innovator firms.
- Contract Manufacturers:Fill-finish and packaging service providers consolidate procurement around pre-qualified supplier lists with demonstrated serialization readiness. CMOs are expanding barrier-grade plastic containment procurement as outsourcing of parenteral operations accelerates.
- Distributors:Wholesale and specialty pharmacy networks influence secondary packaging configurations for cold-chain integrity and track-and-trace compliance. Northeast United States distribution hubs face geographic vulnerability to regional logistics disruptions.
- Retailers:Chain pharmacies and buying consortia drive child-resistant and senior-friendly compliance packaging specifications for over-the-counter portfolios. Direct manufacturer relationships with integrated service agreements are displacing traditional distributor-centric purchasing.
Pharmaceutical companies anchor specification authority while contract manufacturers drive the steepest procurement volume expansion.
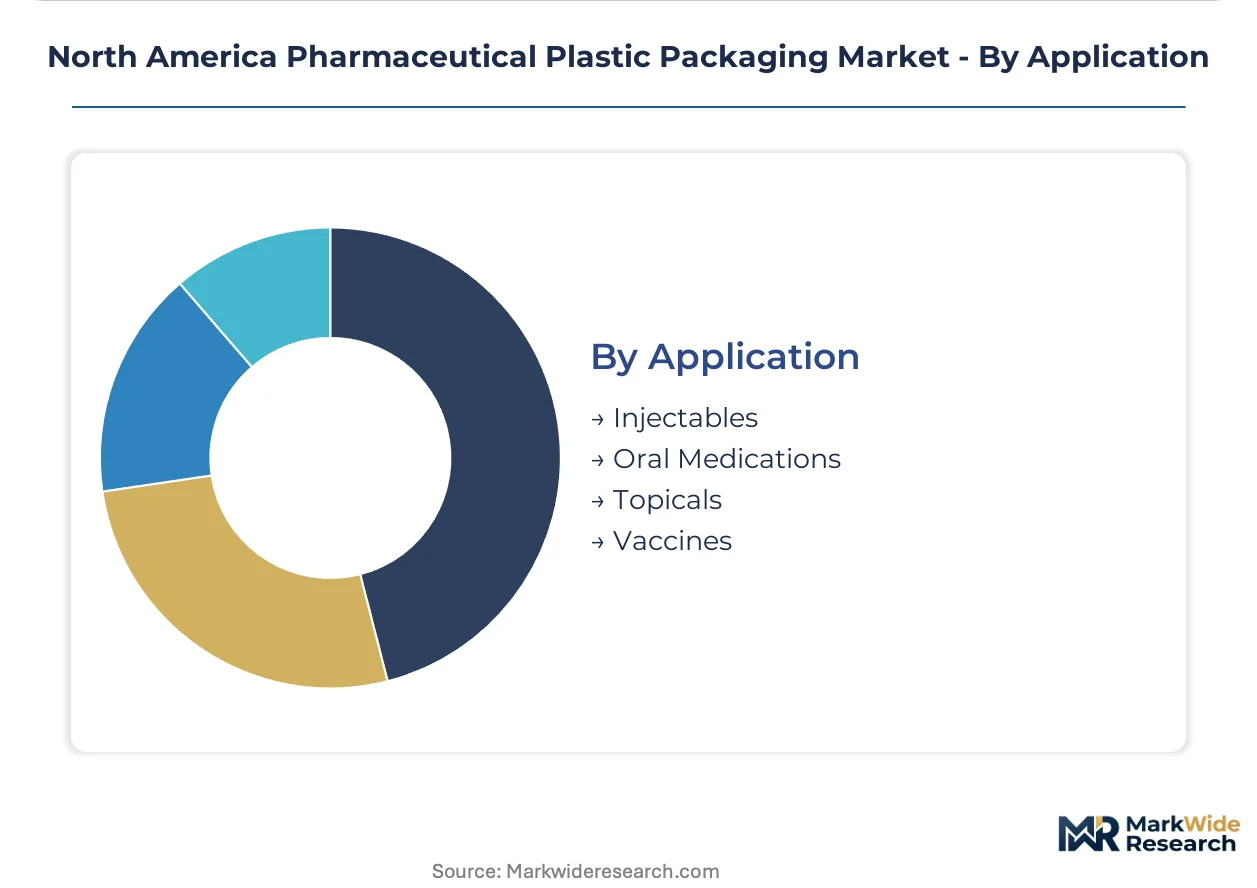
Application:
Volume concentration varies sharply by therapeutic category, with injectables and oral medications commanding divergent barrier and sterility requirements.
- Injectables:Parenteral solutions, suspensions, and lyophilized powders demand USP Class VI biocompatibility and particulate contamination limits per ASTM standards. Biologics cold-chain expansion is multiplying demand for multilayer structures with validated thermal protection profiles.
- Oral Medications:Tablets, capsules, and liquids in bottle and blister formats constitute the largest volume segment across chronic disease management protocols. Adherence packaging formats for hypertension and diabetes represent underpenetrated volume relative to traditional bottle configurations.
- Topicals:Creams, ointments, and transdermal patches utilize barrier tubes and laminated pouches with validated drug compatibility profiles. FDA Current Good Manufacturing Practice regulations dictate validation protocols for plastic packaging in topical drug applications.
- Vaccines:Temperature-sensitive biological products require multilayer vials, pre-filled syringes, and novel delivery systems with demonstrated container closure integrity. Health Canada and PMRA alignment with ICH guidelines creates cross-border compliance obligations for vaccine packaging suppliers.
Oral medications anchor the volume base while vaccines gain share at the steepest rate as temperature-sensitive biological therapies multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical procurement authority concentrates in contract manufacturing organizations and branded drug manufacturers with direct specification control, creating geographic clustering around FDA-registered production facilities and Health Canada-aligned distribution networks.
United States
Biologics cold-chain expansion and FDA serialization mandates drive multilayer barrier system procurement. FDA Current Good Manufacturing Practice regulations enforce validation protocols for plastic packaging extractables and leachables. Pharmaceutical manufacturing clusters around Boston and New Jersey sustain dense supplier networks for high-volume bottle and blister procurement.
Canada
Health Canada and PMRA alignment with ICH guidelines creates cross-border compliance obligations for integrated United States-Canada supply chains. Extended producer responsibility legislation across multiple provinces imposes material recovery requirements on pharmaceutical-grade plastics. Ontario and Quebec host the primary pharmaceutical distribution infrastructure serving national cold-chain networks.
Mexico
Nearshoring of pharmaceutical fill-finish operations accelerates demand for barrier-grade plastic containment systems. COFEPRIS regulatory harmonization with FDA standards reduces dual-qualification burdens for exporters serving United States markets. The Mexico City Metro and Bajío Region concentrate contract manufacturing facilities serving North American distribution networks.
North America Pharmaceutical Plastic Packaging Market Competitive Landscape
Player mix skews toward integrated packaging specialists with multilayer blow-molding and thermoforming capabilities. The vendor base stratifies across three tiers: multinational converters with pharmaceutical-dedicated divisions, mid-tier regional specialists with FDA-registered facilities, and niche providers focused on elastomeric-plastic integration. Dominant competitive moves include backward integration into resin compounding and strategic partnerships with contract manufacturing organizations for co-development of delivery systems.
Within the integrated packaging tier, Amcor PLC and Berry Global Group Inc. exemplify scale-driven converters with pharmaceutical-dedicated infrastructure. West Pharmaceutical Services Inc. occupies a distinct position combining elastomeric closure technology with precision-molded plastic components. These three entities represent the archetype spectrum spanning pure-play packaging through integrated delivery system architectures.
| Leading Market Players |
|---|
| Amcor PLC |
| Berry Global Group Inc. |
| Gerresheimer AG |
| AptarGroup Inc. |
| West Pharmaceutical Services Inc. |
| Tekni-Plex Inc. |
| Drug Plastics & Glass Company Inc. |
| Alpha Packaging Inc. |
| Pretium Packaging LLC |
| Others |
Pricing and Supply Chain Analysis
Multilayer blow-molding capacity utilization above eighty-five percent in the Northeast United States sustains pricing power for barrier-grade pharmaceutical bottles while compressing margin buffers for mid-tier converters serving generic drug manufacturers. Scale concentration around Boston and New Jersey pharmaceutical clusters elevates cost-plus contract floors, with resin indexation clauses passing polypropylene and PET volatility directly to buyers.
Pricing Analysis
Cost-plus contracts with quarterly resin indexation to crude oil derivatives dominate long-term pharmaceutical packaging agreements in North America. Price differentiation separates USP Class VI-certified multilayer structures from commodity-grade alternatives, with serialization-ready formats commanding additional premiums. Pricing pressure stems from contract manufacturing organizations consolidating procurement around pre-qualified supplier lists, squeezing mid-tier converters. Generic drug manufacturers exhibit highest price sensitivity, while biologics innovators prioritize extractables profiles over unit cost.
Supply Chain Analysis
Port of Newark and Port of Boston chokepoints underwrite continental distribution efficiency for pharmaceutical-grade plastic containment systems. Resin supply draws from Gulf Coast petrochemical complexes in the United States, with specialty cyclic olefin polymer imports from Japan and Germany supplementing domestic capacity. Single-source vulnerability concentrates in FDA-registered multilayer film extrusion assets. Distribution runs through integrated logistics networks serving contract manufacturing clusters in Massachusetts, New Jersey, and Puerto Rico.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contract manufacturing organization consolidation is shifting procurement leverage toward fewer, larger buyers with pre-qualified supplier mandates and integrated service bundling requirements.
For Market Incumbents: Consolidate barrier-grade resin compounding capabilities through backward integration to defend margin position against cyclic olefin polymer substitution. Lock in serialization-ready capacity additions in Puerto Rico to preempt regional logistics disruption exposure. Prioritize USP Class VI certification maintenance as regulatory documentation requirements tighten across Health Canada and FDA jurisdictions. For New Entrants and Emerging Players: Lead with halogen-free PET blister formats targeting hospital buying consortia in the United States Midwest, where PVC displacement lags coastal adoption curves. Penetrate Mexican nearshoring corridors through COFEPRIS-aligned quality systems serving United States contract manufacturers. Position around adherence packaging for diabetes and hypertension protocols, the fastest-expanding volume segment relative to incumbent bottle configurations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors elastomeric-plastic integration specialists with precision-molding capabilities and established CMO relationships. Long-term viability hinges on pharmaceutical serialization infrastructure ownership and cold-chain validation expertise. Monitor Health Canada EPR enforcement intensity as the inflection signal for pharmaceutical-grade plastic recovery infrastructure valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captures margin from polypropylene and PET volatility while securing USP Class VI supply continuity. |
| Serialization Infrastructure Deployment | Meets FDA track-and-trace mandates and qualifies suppliers for hospital buying consortia pre-approved lists. |
| Halogen-Free PET Blister Expansion | Aligns with United States hospital procurement specifications displacing incumbent PVC volumes. |
| Cold-Chain Validation Capability Buildout | Supports biologics manufacturers' thermal protection requirements for parenteral multilayer structures. |
| Cross-Border Quality System Harmonization | Reduces documentation burden for suppliers serving integrated United States-Canada supply chains under ICH guidelines. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 483 inspection observations, USP chapter documentation, and Health Canada guidance documents. Interviews with pharmaceutical packaging procurement directors, contract manufacturing quality leads, and resin compounding technical managers informed specification requirement validation. Secondary sources include customs import records for cyclic olefin polymers, SEC filings from publicly traded converters, and GPO contract award databases. Bottom-up volume estimates from individual facility capacities triangulate against top-down pharmaceutical production data.
Segmentation dimensions modeled encompass containment format, polymer chemistry, end-user procurement archetype, and therapeutic application across the projection horizon. CAGRs derive from elasticity-adjusted demand functions incorporating resin price sensitivity and regulatory compliance cost trajectories. Forecast inputs include pharmaceutical outsourcing penetration rates, biologics cold-chain expansion curves, and EPR implementation schedules across Canadian provinces.
Forecasts assume regulatory continuity in FDA Current Good Manufacturing Practice enforcement and Health Canada ICH alignment; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as extended producer responsibility legislation evolves and serialization mandate deadlines approach.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
North America Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Topical Drugs Packaging Market
Pharmaceutical Packaging
Pharmaceutical Packaging Market
Pharmaceutical Packaging
Intravenous Packaging Market
Pharmaceutical Packaging
Serum Bottles Market
Pharmaceutical Packaging
United States Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Cartoning Machines for Pharmaceutical Industry Market
Pharmaceutical Packaging
Injection Bottles Market
Pharmaceutical Packaging
Philippines Pharmaceutical Packaging Market
Pharmaceutical Packaging
Oral Dose Packaging Market
Pharmaceutical Packaging
Pharmaceutical Ampoules Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Dispensing Pharmacy Packaging Machine Market
Pharmaceutical Packaging
Vaccine Shippers Market
Pharmaceutical Packaging
Medical Flexible Packaging Market