
 US Clinical Trial Packaging Market | 2026-2036
US Clinical Trial Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
US Clinical Trial Packaging Market Insights
The FDA's Drug Supply Chain Security Act is consolidating demand for serialized, traceable packaging across Phase III and commercial-transition trials. Catalent, Inc. leverages its integrated clinical supply network to anchor multi-protocol programs. PCI Pharma Services competes through specialized cold-chain infrastructure for cell and gene therapies. Almac Group differentiates via just-in-time labeling and global distribution reach.
Clinical trial packaging encompasses the design, manufacture, and labeling of primary and secondary containers that protect investigational medicinal products from moisture, oxygen, and light while enabling accurate patient dosing and regulatory traceability. Blister packs dominate oral solid dose trials due to compliance-assuring calendarized formats. Injectable delivery modes are expanding fastest as monoclonal antibody and mRNA protocols multiply, with vial and pre-filled syringe formats capturing premium margin pools. Pouch formats sustain growth in early-phase adaptive trials requiring flexible dosing schemes.
FDA regulations, ICH Q1A stability guidelines, and USP <661> container qualification standards collectively govern material selection, labeling content, and distribution documentation. These frameworks elevate barrier performance requirements and compel sponsors to validate packaging under actual stress conditions rather than accelerated models alone. Stakeholders must monitor how the FDA's evolving quality metrics guidance reshapes supplier qualification protocols and audit frequencies.
Market Dynamics
FDA serialization mandates under the Drug Supply Chain Security Act are compressing supplier qualification timelines while elevating barrier performance standards for investigational packaging. Cold-chain biologics expansion is simultaneously reshaping material specifications across Phase III and commercial-transition trials.
Growth Catalysts
- Biologics Proliferation:Monoclonal antibody and mRNA protocols are multiplying demand for vial and pre-filled syringe formats with validated thermal protection. Cell and gene therapy sponsors now specify packaging systems capable of maintaining cryogenic conditions through last-mile distribution.
- FDA DSCSA Compliance:The agency's traceability mandates are consolidating demand for serialized, electronically readable packaging across commercial-transition trials. Sponsors must validate unit-level tracking before product enters the dispensing chain.
- Oncology Trial Density:Massachusetts and New Jersey biopharma clusters are anchoring multi-site protocols requiring just-in-time labeling and adaptive dosing flexibility. Calendarized blister formats with compliance-assuring features capture preference in these patient populations.
Market Restraints
- Specialized Material Costs:Cold-chain-qualified films and desiccant systems command premium multiples over standard pharmaceutical-grade substrates. Input volatility in fluoropolymer and cyclic olefin polymer supply channels compresses margin predictability for packaging converters.
- Supplier Concentration:Northeast corridor demand clusters create geographic supply risk when qualified vendors face capacity constraints. Single-source dependencies for validated barrier laminates expose sponsors to qualification timeline extensions.
- Validation Burden:USP container qualification standards require real-time stability data under actual stress conditions rather than accelerated aging models alone. This technical limitation extends development cycles for novel packaging formats.
Strategic Opportunities
- Decentralized Trial Models:Direct-to-patient distribution channels are opening white space for packaging systems integrating temperature logging and patient-facing instructions. Logistics providers in Texas and Florida are piloting last-mile configurations bypassing traditional site-based dispensing.
- Adaptive Protocol Design:Early-phase sponsors in California are specifying pouch formats with variable dosing schemes and rapid label turnaround. This emerging application rewards converters with digital printing and on-demand finishing capabilities.
- Quality Metrics Guidance:FDA's evolving supplier qualification protocols create regulatory tailwind for packaging vendors with documented continuous process verification. Audit frequency reductions for qualified suppliers incentivize capability investments.
Industry Challenges
- Cold-Chain Expertise Scarcity:Qualified engineers capable of validating thermal packaging for cell therapies remain concentrated among a limited pool of specialized service providers. This talent gap extends recruitment timelines for expansion programs.
- Serialization Integration:Legacy enterprise systems at mid-size sponsors require substantial reconfiguration to accommodate line-level aggregation and verification routing. Capex intensity for compliant infrastructure strains budget allocations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Clinical Trial Packaging Market |
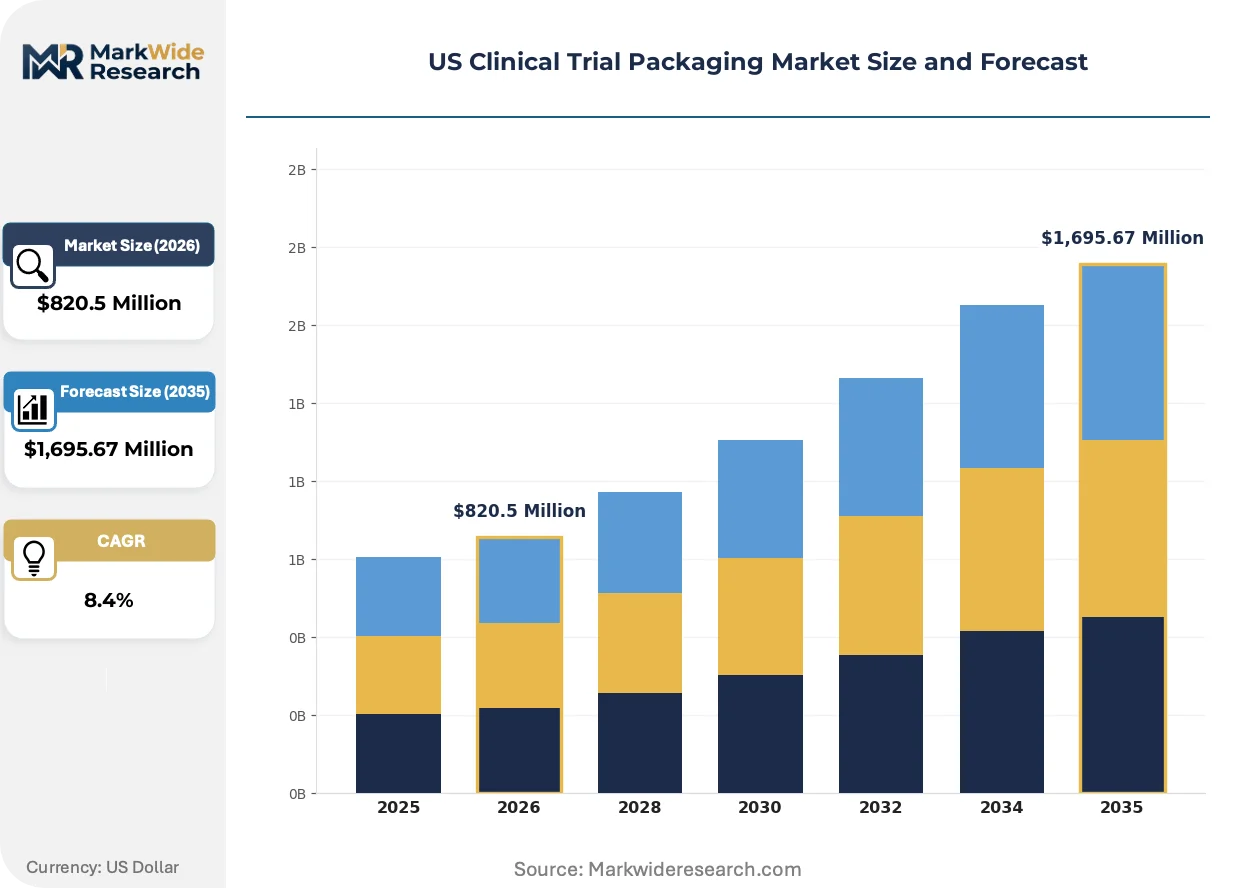
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,695.67 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Blister Packs, Bottles, Vials, Pouches Delivery Mode: Oral, Injectable, Transdermal, Intravenous End User: Pharmaceutical Companies, Contract Research Organizations, Hospitals, Clinics Regulatory Compliance: FDA Regulations, ICH Guidelines, EMA Standards, ISO Certifications |
| Companies Covered | Catalent, Inc., PCI Pharma Services, Almac Group, Fisher Clinical Services (Thermo Fisher Scientific), Parexel International, Sharp Services, LLC, Piramal Pharma Solutions, WestRock Company, Amcor plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Clinical Trial Packaging Market Trends and Innovations
Digital integration and material science advances are compressing development timelines while elevating patient safety assurances. Regulatory traceability requirements and biologics expansion are jointly reshaping competitive capability requirements.
Smart packaging incorporating printed electronics and near-field communication tags is consolidating control over chain-of-custody documentation. Phase III sponsors in the Northeast corridor are specifying these formats for high-value oncology assets. The technology is consolidating audit trail integrity while reducing manual reconciliation labor in site dispensing operations.
FDA's Drug Supply Chain Security Act implementation timeline is accelerating serialization infrastructure deployment across commercial-transition packaging lines. The regulation mandates unit-level traceability with electronic data exchange between supply chain nodes. Injectable delivery formats for biologics are most affected, with sponsors in New Jersey and Massachusetts prioritizing aggregation-capable systems ahead of enforcement deadlines.
Patient-centric trial designs are compressing traditional site-centric procurement patterns. Direct-to-patient distribution models are displacing investigator-site bulk shipments for certain therapeutic categories. California and Texas sponsors are most visible in this behavioral shift, specifying packaging with integrated patient instructions and return logistics capabilities.
US Clinical Trial Packaging Market Segmentation
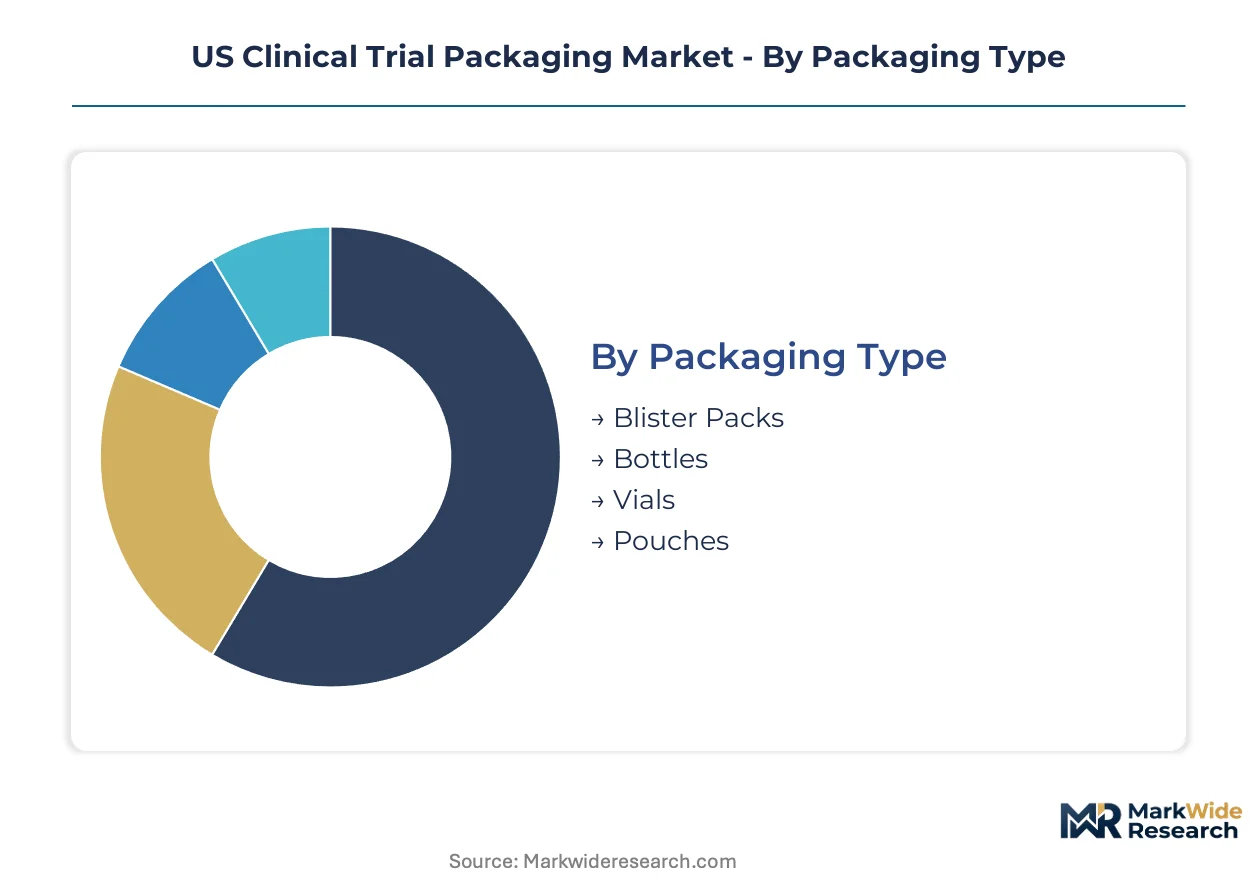
Packaging format selection in US clinical trials hinges on stability requirements, dosing complexity, and regulatory traceability mandates. Each segmentation dimension reveals distinct procurement patterns across Phase I through commercial-transition protocols.
Packaging Type:
Volume concentration sits with high-throughput oral solid formats, while premium margins attach to specialized cold-chain configurations.
- Blister Packs:Calendarized cavity configurations with aluminum-barrier lidding dominate oral solid dose trials requiring compliance tracking. Massachusetts and New Jersey sponsors specify these formats for oncology protocols with complex titration schedules.
- Vials:Borosilicate and cyclic olefin polymer containers with validated seal integrity capture demand from monoclonal antibody and mRNA trials. Cryogenic-compatible formats are expanding most quickly in cell and gene therapy distribution.
- Bottles:Standard pharmaceutical-grade HDPE and PET containers serve bulk investigational supplies with desiccant integration.
- Pouches:Flexible multi-layer laminates enable adaptive dosing schemes in early-phase California trials with rapid label turnaround requirements.
Mature deployment sits with blister packs. Newer deployment is concentrated in vials.
Delivery Mode:
Application urgency separates chronic condition formats from acute intervention packaging with accelerated stability demands.
- Injectable:Pre-filled syringes and cartridge systems with validated needle safety mechanisms command premium specification from biologics sponsors. New Jersey biopharma clusters anchor multi-protocol demand for aggregation-capable serialization.
- Oral:Solid dose and liquid formulations in compliance-assuring configurations sustain the largest procurement volumes across Phase III trials.
- Intravenous:Flexible bag and glass container formats with validated port configurations serve hospital-based infusion protocols.
- Transdermal:Adhesive patch systems with controlled release membranes address pain management and hormone therapy trials.
Established infrastructure supports oral delivery. Capacity expansion is concentrating in injectable formats.
End User:
Customer scale determines packaging customization depth, from standardized bulk supply to patient-specific kit assembly.
- Pharmaceutical Companies:Large sponsors with integrated supply chains specify validated barrier systems with global distribution documentation. Internal packaging operations in Massachusetts and New Jersey maintain captive label printing and serialization infrastructure.
- Contract Research Organizations:Multi-protocol service providers demand flexible formats with rapid protocol-switching capabilities and just-in-time labeling.
- Hospitals:Academic medical centers with investigator-initiated trials procure smaller batch sizes with site-specific dispensing configurations.
- Clinics:Community-based research sites favor simplified kit formats with integrated patient instructions and return logistics.
Procurement sophistication peaks with pharmaceutical companies. Operational flexibility is paramount for contract research organizations.
Regulatory Compliance:
Certification tier separates domestic-only supply from globally qualified packaging with multi-agency validation.
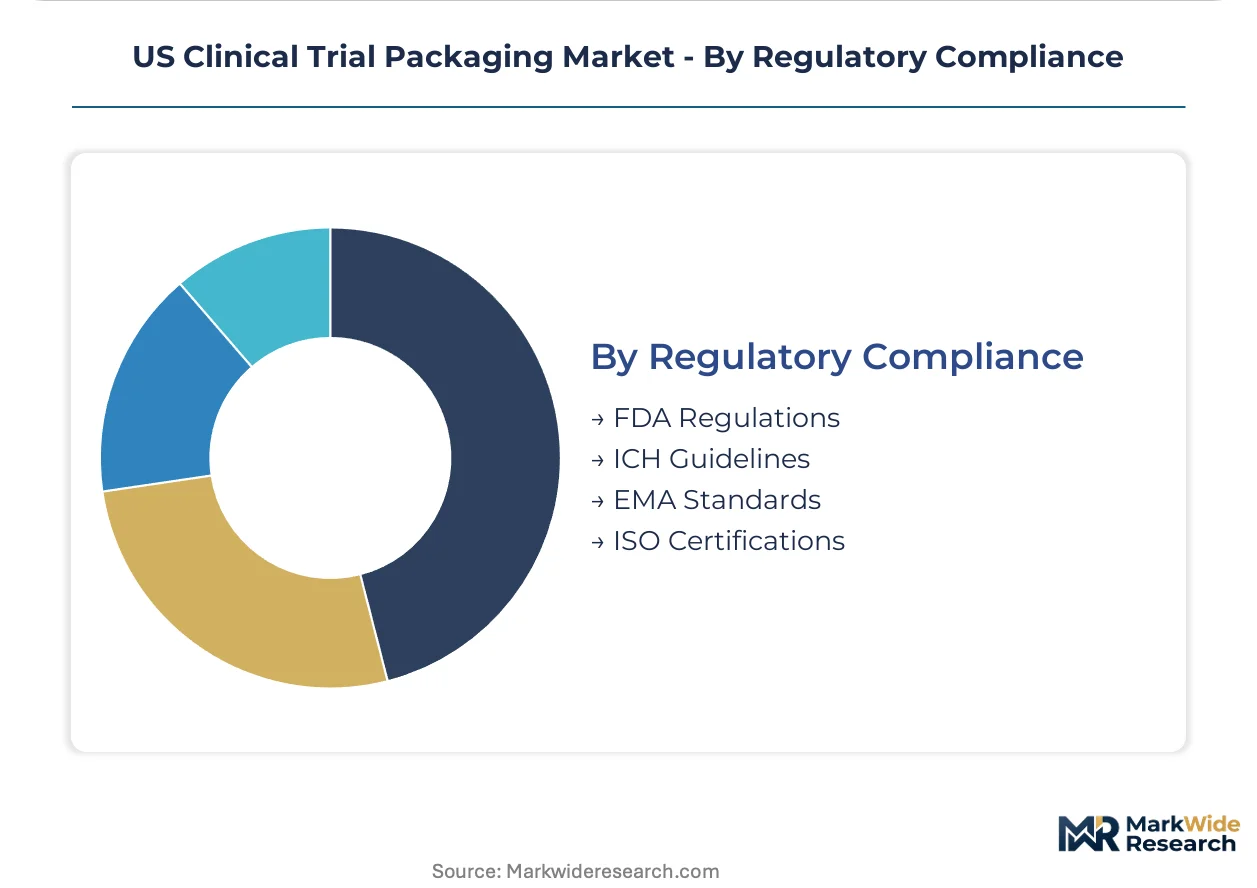
- FDA Regulations:DSCSA serialization mandates and USP container qualification standards govern all US-distributed investigational products. Unit-level traceability with electronic data exchange is mandatory for commercial-transition trials.
- ICH Guidelines:Q1A stability protocols and Q3D elemental impurity standards enable concurrent trial registration across multiple jurisdictions.
- EMA Standards:European Medicines Agency requirements for investigational medicinal product dossiers facilitate parallel EU trial initiation from US packaging facilities.
- ISO Certifications:ISO 15378 pharmaceutical packaging materials and ISO 13485 medical device quality management systems support supplier qualification across sponsor audit programs.
Baseline compliance rests with FDA regulations. Multi-jurisdictional deployment requires ICH guideline alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Boston corridor anchors US clinical trial packaging demand through its density of biopharma headquarters and contract research operations. Massachusetts hosts the highest concentration of oncology and rare disease protocol sponsors, while New Jersey's pharmaceutical manufacturing belt drives commercial-transition packaging volumes. FDA serialization mandates and cold-chain biologics expansion are reshaping regional supplier requirements across three distinct sub-regions.
Northeast Corridor
Massachusetts and New Jersey biopharma clusters generate concentrated demand for serialized, cold-chain-qualified packaging systems. FDA Drug Supply Chain Security Act compliance deadlines are compressing supplier qualification timelines across Phase III and commercial-transition trials. Cambridge and Princeton anchor multi-protocol programs requiring just-in-time labeling and adaptive dosing flexibility.
Mid-Atlantic Region
Pennsylvania and Maryland academic medical centers sustain investigator-initiated trial packaging procurement with site-specific dispensing configurations. NIH funding patterns influence early-phase protocol density across Baltimore and Philadelphia research hubs. Regional CROs specify flexible formats with rapid protocol-switching capabilities for multi-site oncology studies.
Southeast Region
Florida and Georgia logistics providers are piloting direct-to-patient distribution channels with integrated temperature logging and return logistics capabilities. Decentralized trial models are opening white space for patient-facing packaging configurations bypassing traditional site-based dispensing. Atlanta and Miami distribution nodes serve emerging cell therapy sponsors with cryogenic last-mile requirements.
West Coast
California sponsors in the San Francisco Bay Area and San Diego biotech corridor specify pouch formats with variable dosing schemes and rapid label turnaround. Early-phase adaptive protocols reward converters with digital printing and on-demand finishing capabilities. State-level biosafety regulations complement FDA requirements for gene therapy packaging validation.
Southwest Region
Texas emerging as a secondary logistics hub for temperature-sensitive biologics distribution to Latin American trial sites. Dallas and Houston facilities are expanding cold-chain capacity to capture overflow demand from Northeast corridor constraints. State economic development incentives are attracting packaging converters seeking geographic diversification from single-source dependencies.
US Clinical Trial Packaging Market Competitive Landscape
The competitive structure tilts toward integrated service providers with captive clinical supply networks. Three tiers have crystallized: global CDMOs with end-to-end packaging-through-distribution capabilities, specialized cold-chain service providers with validated thermal infrastructure, and regional converters focused on rapid-turnaround labeling and kit assembly. Consolidation pressure intensifies as FDA serialization mandates elevate capital requirements for compliant infrastructure. Strategic partnerships between packaging specialists and logistics providers are displacing arm's-length supplier relationships in commercial-transition trials.
Within the integrated service tier, Catalent, Inc. and PCI Pharma Services exemplify archetypes combining packaging operations with global distribution reach. Almac Group occupies a position emphasizing just-in-time labeling capabilities and multi-jurisdictional regulatory support. These three anchors represent distinct competitive vectors: scale-driven network density, specialized cold-chain infrastructure, and operational flexibility for adaptive protocol designs.
| Leading Market Players |
|---|
| Catalent, Inc. |
| PCI Pharma Services |
| Almac Group |
| Fisher Clinical Services (Thermo Fisher Scientific) |
| Parexel International |
| Sharp Services, LLC |
| Piramal Pharma Solutions |
| WestRock Company |
| Amcor plc |
| Others |
Pricing and Supply Chain Analysis
Fluoropolymer resin price indices cascade through the US clinical trial packaging supply chain into three distinct pricing tiers, compressing margins for converters while elevating qualification premiums for DSCSA-compliant serialization infrastructure. Cold-chain biologics expansion concentrates procurement power among sponsors with validated thermal packaging requirements, forcing mid-tier suppliers toward commodity oral-solid formats or specialized service differentiation.
Pricing Analysis
Yield-guaranteed throughput pricing anchors premium tiers for serialization-capable packaging lines serving Phase III and commercial-transition trials. Price differentiation separates FDA-validated barrier laminates from standard pharmaceutical-grade substrates, with volume scale and cryogenic qualification level as secondary tiering factors. Pricing pressure stems from raw material volatility in cyclic olefin polymer channels, compressing converter margins on fixed-price contracts. Small CROs exhibit highest price sensitivity, while large pharmaceutical sponsors prioritize compliance assurance over unit cost.
Supply Chain Analysis
Direct-to-site distribution channels handle bulk investigational supplies for traditional trial models, while direct-to-patient logistics providers in Texas and Florida pilot last-mile configurations with integrated temperature logging. Geographic supply concentration draws from domestic fluoropolymer producers in the Gulf Coast region, German specialty film manufacturers, and Japanese cyclic olefin polymer suppliers. Raw material dependencies rest on aluminum-barrier lidding substrates, desiccant systems, and printed electronics for smart packaging integration. Single-source vulnerability for validated barrier laminates exposes sponsors to qualification timeline extensions when Northeast corridor capacity constraints emerge.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US clinical trial packaging market functions as a cost-of-compliance narrative where FDA Drug Supply Chain Security Act mandates erect substantial barrier-to-entry moats. Serialization infrastructure investments and validated cold-chain capabilities now separate viable competitors from margin-challenged converters.
For Market Incumbents: Extend qualification protocol depth to capture commercial-transition trial volumes ahead of DSCSA enforcement deadlines. Incumbents should consolidate backward integration into captive label printing and serialization infrastructure to defend against specialized cold-chain entrants. Capacity addition in Texas and Florida logistics corridors addresses geographic concentration risk while serving decentralized trial expansion. Certification investment in ISO 15378 pharmaceutical packaging materials standards reinforces audit-ready positioning for sponsor qualification programs.
For New Entrants and Emerging Players: The mid-tier pricing gap between premium serialization-capable providers and economy oral-solid converters creates entry space for digital-native converters with rapid-turnaround pouch capabilities. California early-phase adaptive trials represent the most penetrable segment, with sponsors specifying variable dosing schemes and on-demand label turnaround. Direct-to-patient packaging configurations with integrated patient instructions and return logistics offer a differentiated go-to-market angle bypassing traditional site-centric procurement.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized cold-chain service providers with validated cryogenic infrastructure in the Southeast corridor over commodity oral-solid converters facing margin compression. Long-term viability across the projection horizon hinges on DSCSA compliance capability and biologics protocol exposure. The inflection signal to monitor is FDA quality metrics guidance implementation, which will accelerate supplier consolidation by reducing audit frequency for qualified vendors while elevating compliance costs for marginal players.
| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Infrastructure Deployment | FDA DSCSA compliance mandates unit-level traceability with electronic data exchange between supply chain nodes. |
| Cold-Chain Capacity Expansion | Cell and gene therapy sponsors specify cryogenic-compatible packaging systems through last-mile distribution. |
| Direct-to-Patient Distribution Pilot | Texas and Florida logistics providers bypass traditional site-based dispensing with integrated temperature logging. |
| Digital Printing Capability Investment | California adaptive trials reward converters with on-demand finishing for variable dosing pouch formats. |
| Regulatory Certification Program | ISO 15378 pharmaceutical packaging materials qualification supports sponsor audit program compliance. |
Research Methodology
Multi-period observation of FDA filing patterns, ClinicalTrials.gov enrollment trajectories, and sponsor packaging procurement disclosures anchored the trend analysis, supplemented by interviews with regulatory affairs leads at contract research organizations, clinical supply chain directors at pharmaceutical sponsors, and procurement managers at integrated CDMOs. Secondary validation drew from FDA DSCSA guidance documents, USP container qualification standards, SEC 10-K filings of publicly traded packaging service providers, and trade data on fluoropolymer and cyclic olefin polymer imports. Bottom-up protocol-level demand modeling triangulated against top-down market sizing from packaging converter capacity disclosures.
The input-output matrix framed demand projections across packaging type, delivery mode, end user scale, and regulatory compliance tier, with treatment complexity and biologics share as cross-cutting dimensions. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs included sponsor pipeline composition by therapeutic area, DSCSA implementation timeline assumptions, and cold-chain infrastructure buildout trajectories across regional logistics hubs.
Inputs from FDA regulatory filings and sponsor public disclosures were available through the study window; gaps in privately held CRO procurement data introduce uncertainty bands around early-phase adaptive trial packaging estimates. Forecasts reflect documented assumptions regarding DSCSA enforcement consistency and biologics pipeline conversion rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Prescription Pharmacy Bags Market
Pharmaceutical Packaging
Pharmaceutical Secondary Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Vials Market
Pharmaceutical Packaging
Temperature Controlled Pharmaceutical Containers Market
Pharmaceutical Packaging
Pharmaceutical Packaging Market
Pharmaceutical Packaging
Oral Dose Packaging Market
Pharmaceutical Packaging
Topical Drugs Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Clinical Trial Packaging Market
Pharmaceutical Packaging
Saudi Arabia Pharmaceutical Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Vials Market
Pharmaceutical Packaging
Nasal Spray Packaging Market
Pharmaceutical Packaging
Global Ampoules Packaging Market
Pharmaceutical Packaging
United States Ampoules Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Contract Packaging Market