
 Temperature Controlled Pharmaceutical Containers Market | 2026-2036
Temperature Controlled Pharmaceutical Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Temperature Controlled Pharmaceutical Containers Market Outlook
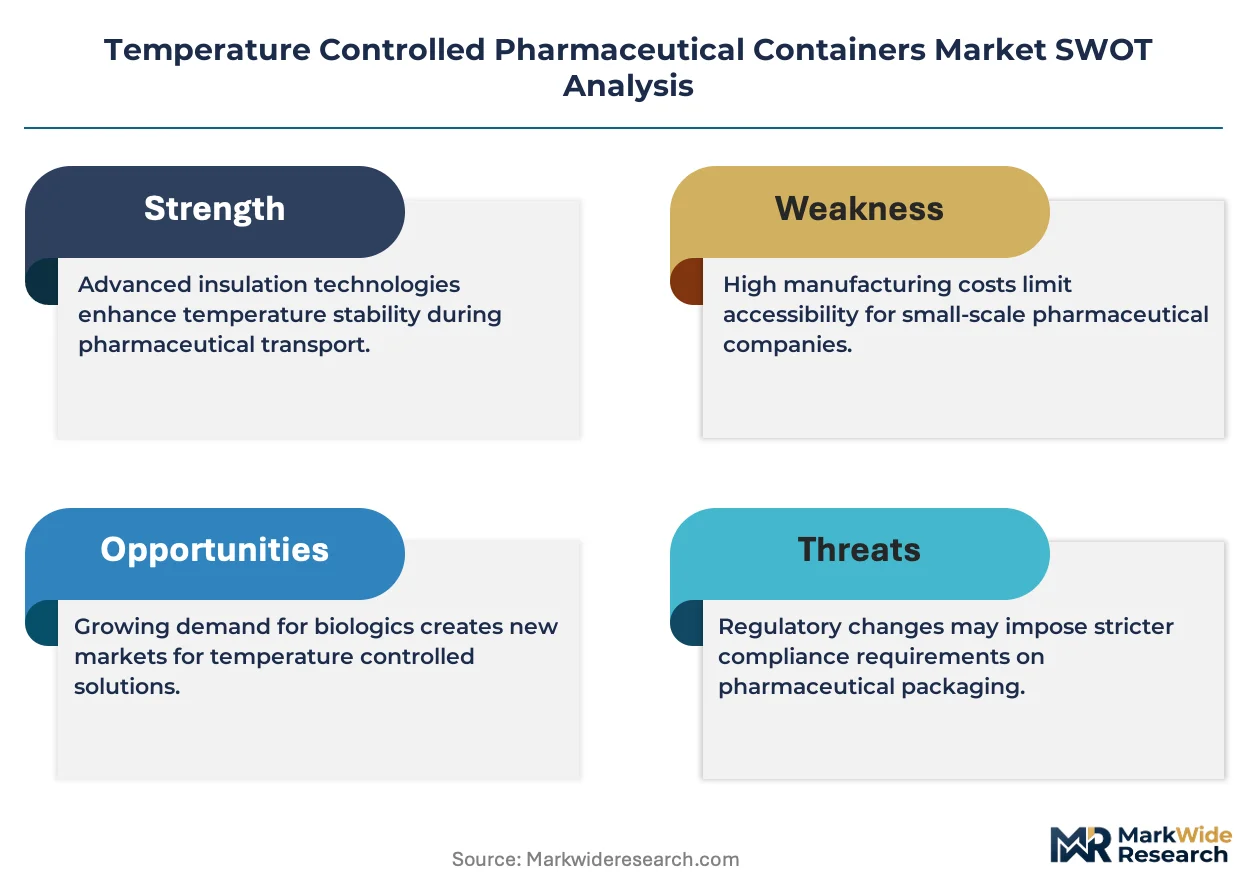
Germany is rewriting the competitive map for temperature controlled pharmaceutical containers through expanded vacuum-insulated panel production and specialized cold chain infrastructure. Pelican BioThermal leverages its North American manufacturing footprint to sustain leadership in reusable active container systems. Va-Q-Tec AG anchors European supply with its core vacuum insulation technology, while Cold Chain Technologies competes through specialized phase-change material formulations for ultra-cold payloads.
Temperature controlled pharmaceutical containers are engineered thermal enclosures utilizing vacuum insulation panels, phase-change materials, or active compressor systems to maintain precise thermal bands between ultra-cold and ambient conditions during transit and storage. These systems incorporate validated temperature monitoring, redundant sealing, and impact-resistant shells to protect biologics, vaccines, and cell therapies from thermal excursions that compromise efficacy. Active containers command premium positioning due to their compressor-based precision, while cooler boxes occupy the high-volume segment driven by generic pharmaceutical distribution. Ultra-cold temperature range applications represent the fastest-expanding category, propelled by cell and gene therapy logistics requirements.
FDA cold chain validation requirements and EU GDP guidelines shape product design by mandating documented temperature integrity across distribution lanes, while IATA CEIV Pharma certification gates market access for air freight handlers. The EU F-Gas Regulation and evolving EPA refrigerant standards are forcing material transitions in active container compressor systems. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance-driven supply fragmentation.
Market Dynamics
mRNA therapy pipelines are forcing container manufacturers to engineer ultra-cold systems below minus 70 degrees Celsius, compressing development cycles and reshaping supplier qualification criteria across biologics logistics.
Growth Catalysts
- EU GDP Guidelines:Strengthened validation requirements for cross-border pharmaceutical shipments are mandating redundant temperature monitoring and documented chain-of-custody protocols, expanding addressable market for certified container providers.
- Cell Therapy Logistics:Autologous CAR-T manufacturing requires patient-specific cryogenic transport from apheresis centers to processing facilities and back, generating dedicated demand for validated ultra-cold shippers with GPS tracking.
- Vacuum Insulation Panel Production:German manufacturing clusters are scaling VIP output for pharmaceutical-grade thermal protection, reducing container weight and extending passive temperature hold times without compressor systems.
Market Restraints
- Refrigerant Input Volatility:Active compressor systems depend on hydrofluorocarbon blends whose supply faces disruption under EU F-Gas Regulation phase-down schedules, compressing margins for container lessors.
- Phase-Change Material Supply Concentration:Specialized PCM formulations for ultra-cold applications source from limited North American and European chemical processors, creating single-source vulnerability for container assemblers.
- Technical Limitation at Extreme Duration:Passive systems cannot maintain minus 80 degrees Celsius beyond 120 hours without dry ice replenishment, restricting their deployment for intercontinental cell therapy shipments.
Strategic Opportunities
- India Biologics Manufacturing:CDMO investments in Hyderabad and Bangalore are building cold chain infrastructure for export-oriented biosimilar production, opening demand for IATA CEIV Pharma-certified active containers.
- Reusable Container Leasing Models:Pharma manufacturers are transitioning from purchase to per-shipment rental for temperature-controlled packaging, enabling service revenue streams and asset utilization optimization.
- WHO PQS Prequalification:Vaccine procurement programs are mandating WHO Performance Quality and Safety certification for cold chain equipment, creating a regulatory pathway for container vendors into Gavi and UNICEF supply chains.
Industry Challenges
- Thermal Validation Engineering Talent:Container manufacturers face scarcity of engineers capable of executing IQ/OQ/PQ protocols for pharmaceutical clients, extending sales cycles and inflating compensation costs.
- Legacy ERP Integration:Real-time temperature data streams from IoT-enabled containers require API connectivity with customer warehouse management systems, generating implementation friction and customization demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temperature Controlled Pharmaceutical Containers Market |
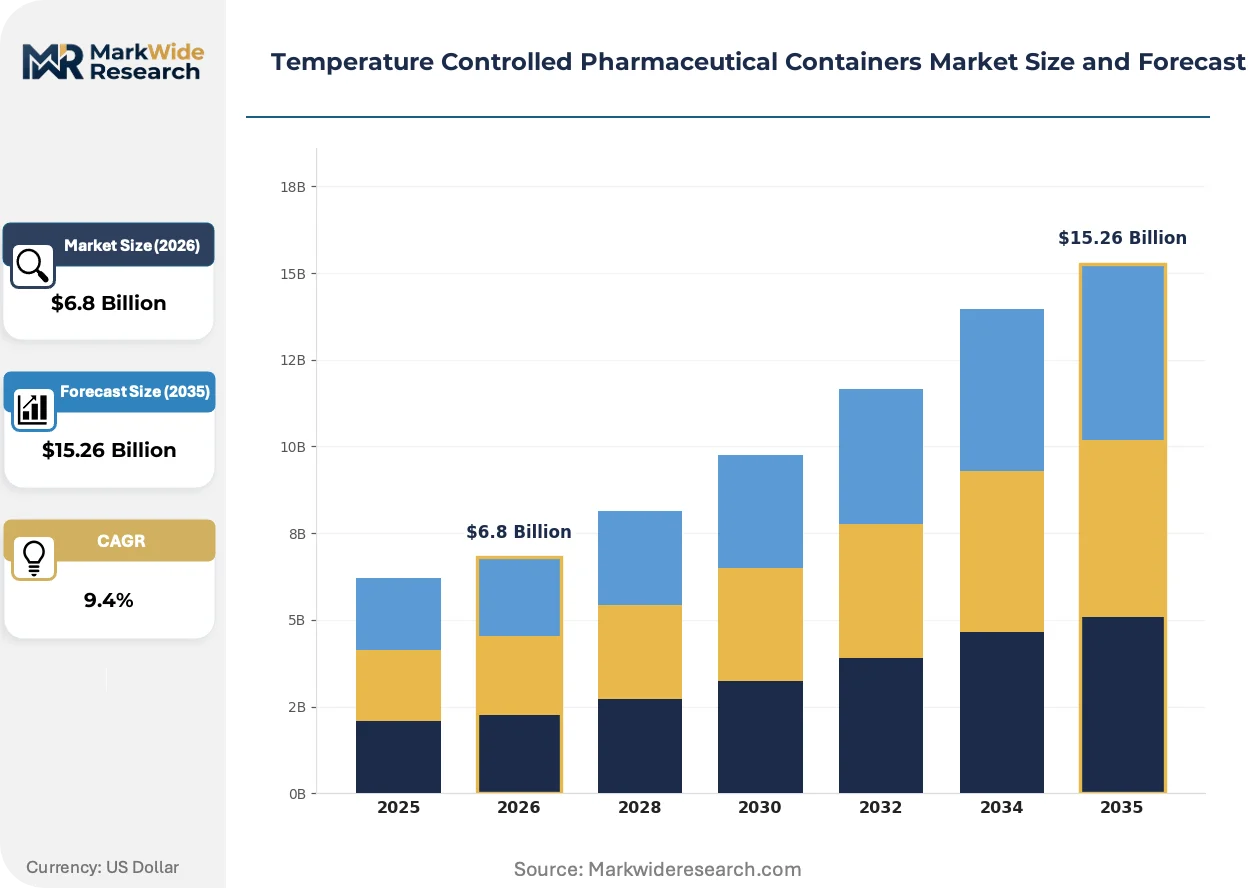
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cooler Boxes, Refrigerated Trucks, Temperature-Controlled Pallets, Active Containers End User: Pharmaceutical Companies, Biotech Firms, Contract Logistics, Hospitals Temperature Range: Frozen, Cold Chain, Ambient, Ultra-Cold Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Sonoco Products Company, Cold Chain Technologies, Pelican BioThermal, Va-Q-Tec AG, Softbox, Sofrigam, Envirotainer, Cryopak, Intelsius, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temperature Controlled Pharmaceutical Containers Market Strategic Shifts
Container architecture is bifurcating between lightweight passive systems for high-volume generics and precision active compressor units for personalized therapies, with material science and digital integration as the decisive competitive axes.
Solid-state battery technology is migrating from consumer electronics into active thermal containers, replacing lithium-ion packs with safer, denser energy storage that extends compressor runtime without hazardous material shipping restrictions. Gene therapy developers are piloting these systems for last-mile delivery to infusion centers. The technology is migrating from niche oncology applications toward broader biologics distribution, compressing the performance gap between passive and active thermal protection.
EPA refrigerant standards are tightening allowable global warming potential thresholds for compressor-based systems, forcing redesign of active container cooling circuits toward hydrofluoroolefin alternatives or transcritical CO2 architectures. Container OEMs are requalifying entire product lines under accelerated timelines. Ultra-cold product categories face the steepest compliance burden, with European manufacturers responding faster than North American counterparts due to prior EU F-Gas Regulation alignment.
Pharmaceutical buyers are consolidating vendor relationships from multi-source procurement toward single-platform partnerships that bundle containers, monitoring software, and reverse logistics. This compression is displacing spot-market container rentals with multi-year service contracts tied to therapy launch timelines. The shift is most visible in cell therapy verticals, where manufacturers prioritize supply security over unit cost minimization.
Temperature Controlled Pharmaceutical Containers Market Segmentation
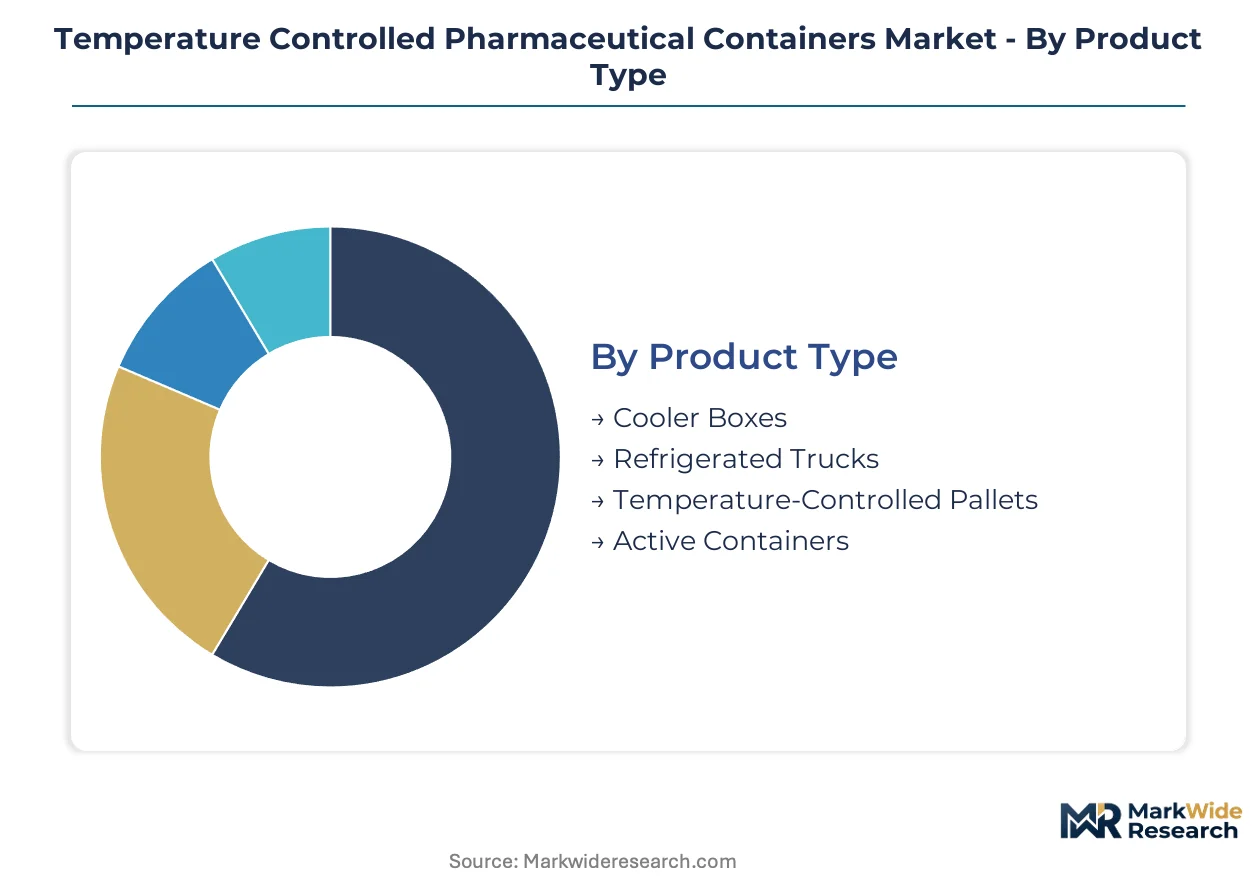
Segmentation in temperature controlled pharmaceutical containers reveals how thermal performance requirements, custody complexity, and distribution economics partition demand across distinct equipment categories and customer workflows.
Product Type:
Use-case spectrum spans lightweight passive protection for routine generics through precision active systems for personalized therapies.
- Cooler Boxes:Passive thermal enclosures utilizing phase-change materials or vacuum insulation panels for short-duration protection. Generic pharmaceutical distribution in Germany and contract logistics networks in India concentrate procurement volumes.
- Active Containers:Compressor-driven systems with redundant power and real-time telemetry for precise thermal band maintenance. Autologous CAR-T logistics and mRNA therapy distribution are forcing engineering cycles below minus 70 degrees Celsius.
- Refrigerated Trucks:Fleet-based mobile cold storage for high-volume lane hauls between manufacturing plants and distribution centers.
- Temperature-Controlled Pallets:Unit-load thermal protection for bulk biologics shipments requiring pallet-level integrity without individual container investment.
Established volume favors cooler boxes; emerging adoption favors active containers.
End User:
Customer type determines custody chain complexity and validation burden.
- Pharmaceutical Companies:In-house logistics operations for proprietary therapies with stringent FDA and EMA validation requirements. Multinational manufacturers in Switzerland and the United States are consolidating vendor relationships toward single-platform partnerships.
- Biotech Firms:Emerging therapy developers lacking captive cold chain infrastructure. Cell and gene therapy startups in Boston and Basel are driving per-shipment rental models for ultra-cold shippers.
- Contract Logistics:Third-party cold chain operators seeking IATA CEIV Pharma certification for air freight handling.
- Hospitals:Last-mile receiving points with limited on-site thermal storage capacity for direct-to-patient therapies.
Pharmaceutical companies dominate capital procurement; biotech firms are expanding fastest in rental uptake.
Temperature Range:
Margin structure tightens as thermal bands descend below standard cold chain thresholds.
- Ultra-Cold:Cryogenic systems maintaining below minus 70 degrees Celsius for mRNA and cell therapy payloads. Dry ice replenishment constraints and solid-state battery migration are reshaping competitive dynamics.
- Cold Chain:Standard two to eight degrees Celsius protection for insulin, vaccines, and biologics. EU GDP guidelines and FDA validation requirements mandate redundant monitoring across this band.
- Frozen:Minus 20 to minus 30 degrees Celsius for certain biologics and plasma derivatives.
- Ambient:Controlled room temperature protection for heat-sensitive generics requiring 15 to 25 degrees Celsius stability.
Cold chain captures the volume base; ultra-cold is climbing the fastest in revenue contribution.
Distribution Channel:
Supply concentration varies by procurement scale and relationship intensity.
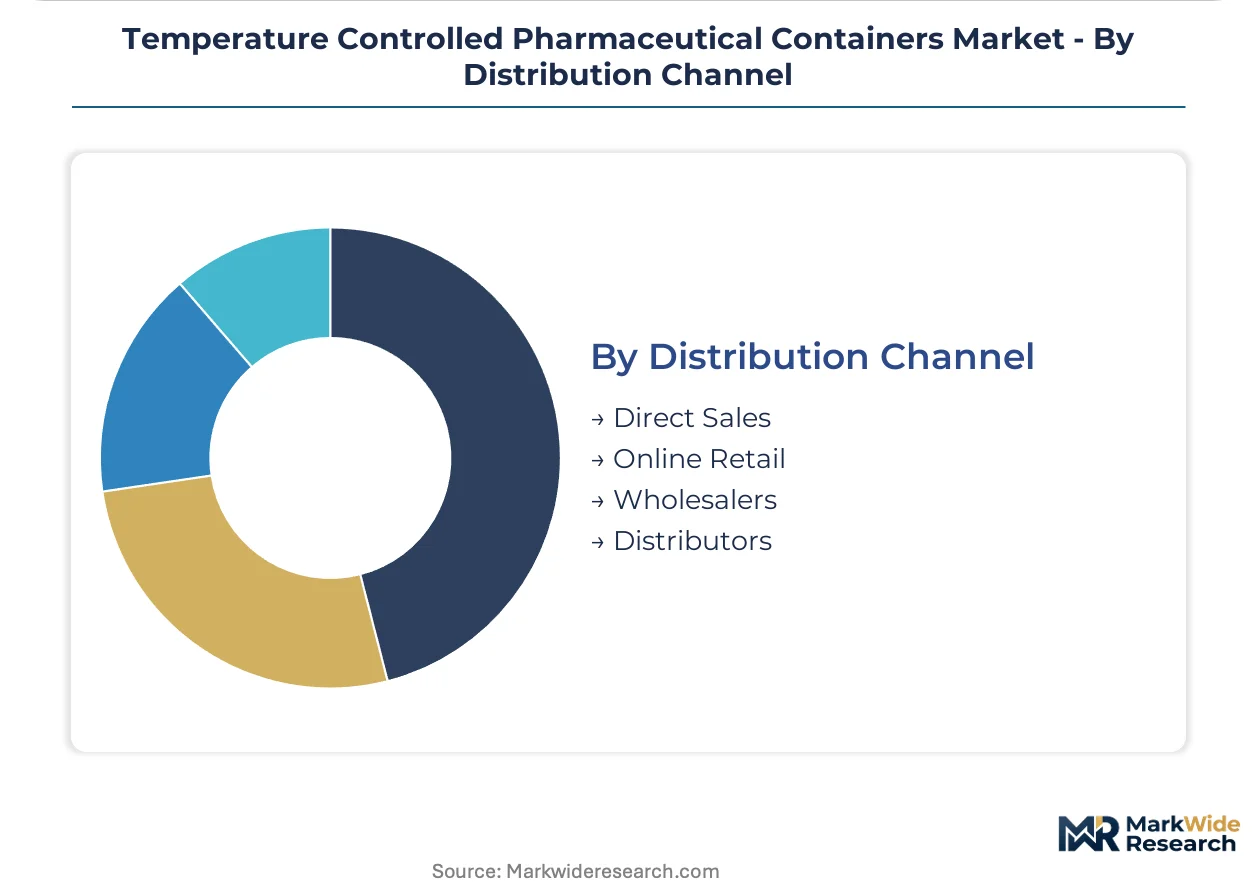
- Direct Sales:Manufacturer-to-end-user contracts for customized container fleets with embedded telemetry. Major biologics manufacturers in Germany and the United States are negotiating multi-year service agreements tied to therapy launch timelines.
- Distributors:Regional stocking intermediaries for standardized cooler box and pallet procurement. Indian pharmaceutical clusters in Hyderabad and Bangalore access cold chain equipment through specialized medical supply distributors.
- Wholesalers:Volume aggregators serving mid-tier pharmaceutical manufacturers with limited procurement sophistication.
- Online Retail:Spot-market procurement for emergency replenishment and small-volume buyers.
Direct sales anchor strategic accounts; distributors are gaining share fastest in emerging manufacturing geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cold chain validation requirements anchor North American demand, while EU GDP guidelines and tightening refrigerant standards reshape European procurement patterns across biologics distribution networks.
United States
mRNA therapy commercialization and autologous CAR-T manufacturing are driving ultra-cold container demand. FDA validation requirements for cross-border shipments mandate redundant temperature monitoring and documented chain-of-custody protocols. Greater Boston hosts concentrated biotech logistics operations requiring specialized cryogenic transport infrastructure.
Germany
Vacuum-insulated panel production clusters and specialized pharmaceutical logistics hubs anchor European cold chain distribution. EU F-Gas Regulation phase-down schedules are forcing material transitions in active container compressor systems. Va-Q-Tec AG and supporting manufacturing networks in Bavaria and Hesse supply thermal protection technology across the continent.
India
CDMO investments in Hyderabad and Bangalore are building export-oriented biosimilar production capacity requiring IATA CEIV Pharma-certified cold chain equipment. CDSCO regulations align with international GDP standards for temperature-sensitive pharmaceutical exports. Telangana and Karnataka pharmaceutical clusters are procuring active thermal containers for intercontinental distribution lanes.
Switzerland
Multinational biologics manufacturers are consolidating vendor relationships toward single-platform partnerships with embedded telemetry and reverse logistics. Swissmedic requirements for temperature integrity documentation exceed baseline EU standards. Basel-area pharmaceutical headquarters negotiate multi-year service agreements tied to therapy launch timelines.
Japan
Cell therapy logistics and precision medicine distribution are expanding demand for validated ultra-cold shippers with GPS tracking capabilities. PMDA cold chain guidelines mandate documented thermal performance for regenerative medicine shipments. Kanto region biotech clusters require specialized containers for patient-specific cryogenic transport between apheresis centers and processing facilities.
Temperature Controlled Pharmaceutical Containers Market Competitive Environment
Specialized thermal packaging developers and diversified packaging conglomerates split the market along the axis of therapy-specific engineering versus volume manufacturing scale. The vendor base concentrates among European vacuum insulation specialists, North American active system engineers, and diversified industrial packaging groups with pharmaceutical divisions. Two strategic archetypes dominate: precision-engineered active container specialists serving personalized therapy logistics, and high-volume passive system manufacturers supplying generic pharmaceutical distribution. Competitive moves center on solid-state battery integration for extended compressor runtime and reusable container leasing models replacing capital purchase.
Among German-based thermal technology developers, Va-Q-Tec AG exemplifies the vacuum insulation specialist archetype through its core panel technology supply to container assemblers. Pelican BioThermal and Cold Chain Technologies occupy positions within the active system engineering tier, representing North American precision thermal management capabilities. Sonoco Products Company sits within the diversified packaging conglomerate structure, leveraging broad manufacturing infrastructure across multiple industrial segments.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Cold Chain Technologies |
| Pelican BioThermal |
| Va-Q-Tec AG |
| Softbox |
| Sofrigam |
| Envirotainer |
| Cryopak |
| Intelsius |
| Others |
Value Chain & Pricing Dynamics
Vacuum insulation panel production concentrates in German manufacturing clusters around Bavaria and Hesse, anchoring margin capture for passive container tiers while active compressor systems face cost pressure from refrigerant phase-down schedules under EU F-Gas Regulation. This upstream concentration shapes downstream pricing power, with VIP-based cooler boxes commanding stable premiums against volatile active system margins.
Pricing Analysis
Geographic price spreads widen between North American active container leases and European passive system procurement, reflecting divergent regulatory compliance burdens. Three-tier pricing structure across certified premium, standard GDP-compliant, and economy generic levels segments buyer tiers. FDA and EMA validation requirements drive premium tier pricing, while Indian CDMO procurement concentrates price sensitivity in economy segments. Cost compression in active compressor tiers is intensifying because solid-state battery migration demands requalification investment.
Supply Chain Analysis
Contract manufacturing for active compressor assemblies concentrates among specialized German and North American thermal engineering firms with IATA CEIV Pharma certification. Geographic supply concentration spans Germany for vacuum insulation panels, the United States for solid-state battery integration, and India for assembly scale-up. Raw material dependencies include phase-change material formulations, hydrofluoroolefin refrigerant alternatives, and aerospace-grade aluminum shells. Single-source vulnerability in specialized PCM chemical processing creates supply chain risk. Distribution runs through direct manufacturer-to-pharma contracts for active systems and regional medical supply distributors for passive cooler boxes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against reusable container leasing models that displace capital purchase patterns among biotech firms and mid-tier pharmaceutical manufacturers.
For Market Incumbents: Entrench position through backward integration into solid-state battery supply chains and captive vacuum insulation panel production in German manufacturing clusters. Certification investment for WHO PQS prequalification gates access to Gavi and UNICEF procurement channels, defending against emerging Asian container assemblers. Channel control through embedded telemetry APIs strengthens multi-year service contract renewals. For New Entrants and Emerging Players: Mid-market biotech firms in Boston and Basel lacking captive cold chain infrastructure represent the most penetrable entry point for per-shipment rental models. Indian CDMO clusters in Hyderabad and Bangalore offer white-space demand for IATA CEIV Pharma-certified active containers at price points below established German and North American suppliers. Go-to-market execution through specialized medical supply distributors accelerates procurement access. For Investors and Strategic Acquirers: Capital is best deployed toward precision-engineered active container specialists with solid-state battery integration capabilities and established IQ/OQ/PQ validation protocols. Long-term viability across the analysis window hinges on regulatory alignment with evolving EPA refrigerant standards and EU F-Gas Regulation phase-downs. The signal to watch is consolidation velocity among biotech firms toward single-platform vendor partnerships, indicating which container providers secure embedded multi-year revenue streams.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Battery Integration | Extends active container runtime beyond lithium-ion limitations for ultra-cold gene therapy logistics. |
| WHO PQS Prequalification | Unlocks Gavi and UNICEF vaccine procurement channels for emerging market expansion. |
| Reusable Container Leasing Models | Captures service revenue streams as biotech firms abandon capital purchase patterns. |
| Backward Integration into VIP Production | Secures supply of vacuum insulation panels from German manufacturing clusters. |
| API Telemetry Integration | Enables real-time temperature data streams into customer warehouse management systems. |
Study Parameters
A standing panel of cold chain logistics directors, pharmaceutical procurement managers, regulatory affairs leads, and biotech supply chain executives provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 483 inspection observations, EMA GDP guidance documents, IATA CEIV Pharma certification registries, and customs trade data for thermal container imports. Bottom-up shipment volume modeling triangulated against top-down therapy pipeline capacity forecasts.
Scenario-bracketing framed low-base-high projections across the modeling period without discrete year anchoring. Segmentation dimensions included product type (active versus passive thermal protection), temperature range tier, end-user category (pharmaceutical manufacturer versus biotech firm versus contract logistics), and regional regulatory cluster. CAGRs were derived from therapy launch timeline alignment with container fleet deployment patterns, incorporating mRNA pipeline expansion and cell therapy site authorization trajectories as industry-specific forecast inputs.
Practitioners should monitor refrigerant regulatory divergence between EPA standards and EU F-Gas Regulation phase-down schedules for early signals of compliance-driven supply fragmentation. Forecasts reflect assumptions regarding solid-state battery cost curves and WHO PQS certification velocity. Quarterly review of biotech financing rounds and CDMO capacity announcements is advised to detect inflection in per-shipment rental model adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Vials Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Materials Market
Pharmaceutical Packaging
Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Global Vaccine Storage and Packaging Market
Pharmaceutical Packaging
Philippines Pharmaceutical Packaging Market
Pharmaceutical Packaging
Saudi Arabia Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Packaging Equipment Market
Pharmaceutical Packaging
Advanced Empty Capsule Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Pharmaceutical Packaging Market
Pharmaceutical Packaging
Dispensing Pharmacy Packaging Machine Market
Pharmaceutical Packaging
Medical Flexible Packaging Market
Pharmaceutical Packaging
Injectable Drug Packaging Market
Pharmaceutical Packaging
Pharma Trays Market
Pharmaceutical Packaging
Pharma Packaging Films Market