
 Pharmaceutical Plastic Pots Market | 2026-2036
Pharmaceutical Plastic Pots Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Plastic Pots Market Analytics
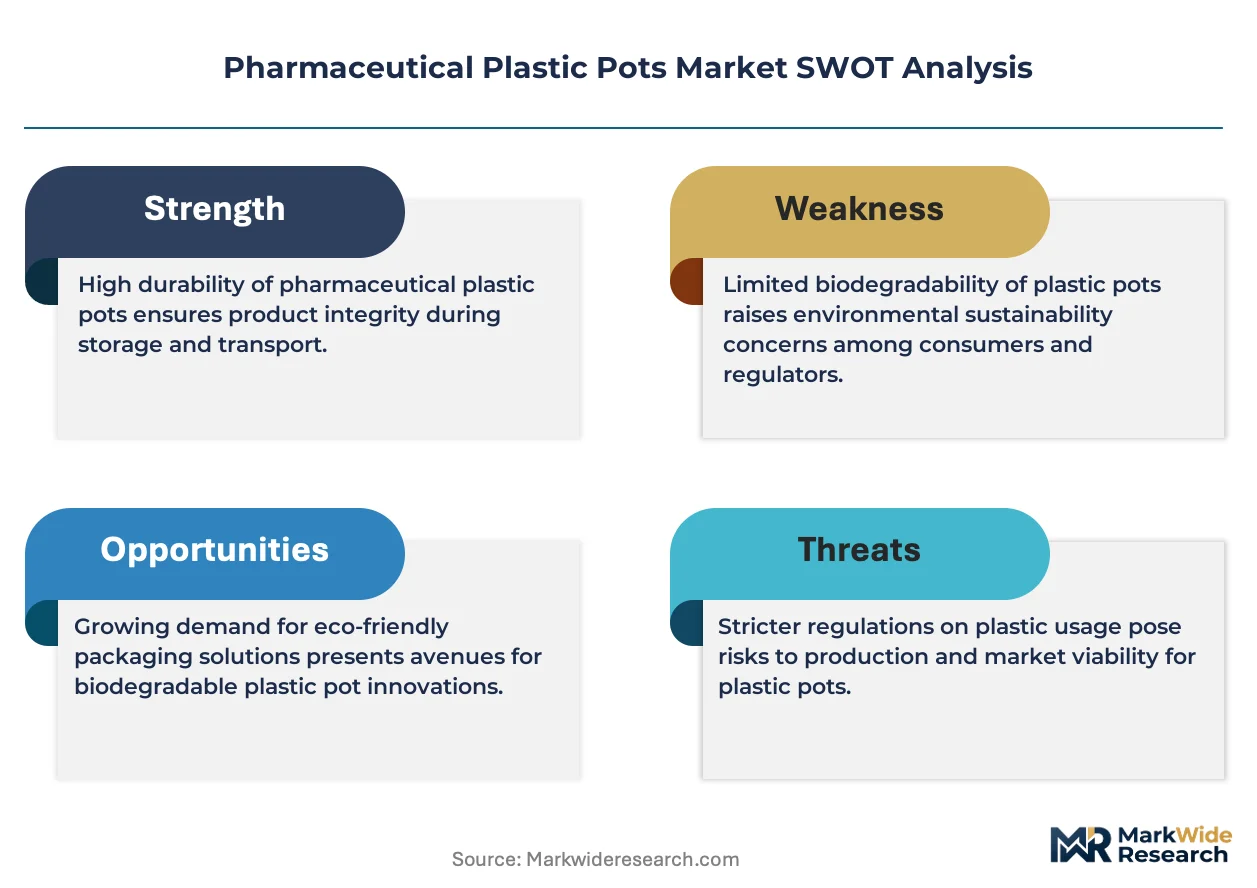
Pharmaceutical-grade barrier specifications is redrawing competitive boundaries across the plastic pots sector. Gerresheimer AG leverages its glass-to-plastic conversion expertise to anchor high-barrier polymer solutions for moisture-sensitive formulations. Berry Global Inc. sustains manufacturing scale across multiple FDA-registered facilities, competing on volume flexibility for large pharmaceutical contract packagers.
Pharmaceutical plastic pots are injection-molded or blow-molded polymer containers engineered to meet USP Class VI and EP 3.1 material standards, designed for tablet, capsule, and powder storage with functional requirements including child-resistant closures, desiccant integration, and tamper-evident seals. Polypropylene dominates material selection due to its chemical inertness and autoclave compatibility, while PET is gaining ground in transparent display applications where moisture barrier enhancement justifies premium positioning. Injection molding occupies the largest share of production output, though blow molding is expanding fastest in liquid and semi-solid pharmaceutical formats where dimensional consistency and neck-finish precision command higher margins.
FDA cGMP guidelines and EMA Annex 1 sterile manufacturing requirements shape container closure integrity testing protocols, directly influencing pot design validation cycles and supplier qualification timelines. ISO 15378 and USP <661> standards govern extractables and leachables thresholds, filtering out non-compliant converters from approved vendor lists. Stakeholders must monitor evolving state-level pharmaceutical packaging regulations in India and China, where national pharmacopoeia harmonization with ICH Q3D elemental impurity guidelines is accelerating supplier consolidation.
Market Dynamics
Contract packaging providers are consolidating procurement around serialization-ready containers as FDA and EMA track-and-trace mandates harden compliance thresholds for primary pharmaceutical packaging.
Growth Catalysts
- Oral solid dose volume expansion:Chronic disease prevalence is elevating tablet and capsule production runs, pulling demand for high-volume plastic pot supply chains anchored in India and China.
- EMA serialization deadlines:European traceability mandates are forcing wholesale packaging upgrades, creating replacement demand for tamper-evident and aggregation-capable container designs.
- Desiccant-integrated molding:In-mold desiccant technologies are eliminating secondary sachet insertion steps, cutting total cost of ownership for moisture-sensitive formulations.
Market Restraints
- Polypropylene resin volatility:Feedstock price swings tied to naphtha and propylene supply disruptions compress converter margins and complicate long-term contract pricing.
- Single-source FDA-registered tooling:Precision mold fabrication concentrates among a handful of European and North American suppliers, extending qualification timelines for new market entrants.
- Glass persistence in high-barrier segments:Cyclic olefin polymer and multilayer plastic solutions remain cost-disadvantaged against borosilicate glass for oxygen-sensitive biologics.
Strategic Opportunities
- India PLI scheme leverage:Government production-linked incentives for active pharmaceutical ingredient and formulation manufacturing are expanding domestic packaging demand in Maharashtra and Gujarat clusters.
- Connected packaging integration:Near-field communication and QR-code embedding technologies are enabling direct-to-patient engagement and cold-chain verification services.
- Semi-solid format migration:Topical cream and ointment brands are shifting from aluminum tubes to wide-mouth polypropylene pots, opening blow-molding capacity expansion.
Industry Challenges
- USP <661> extractables validation:Accelerated aging studies and leachables profiling are extending new product introduction cycles by six to twelve months.
- Serialization equipment retrofitting:Legacy injection-molding lines require substantial capital redeployment to accommodate vision systems and aggregation hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Plastic Pots Market |
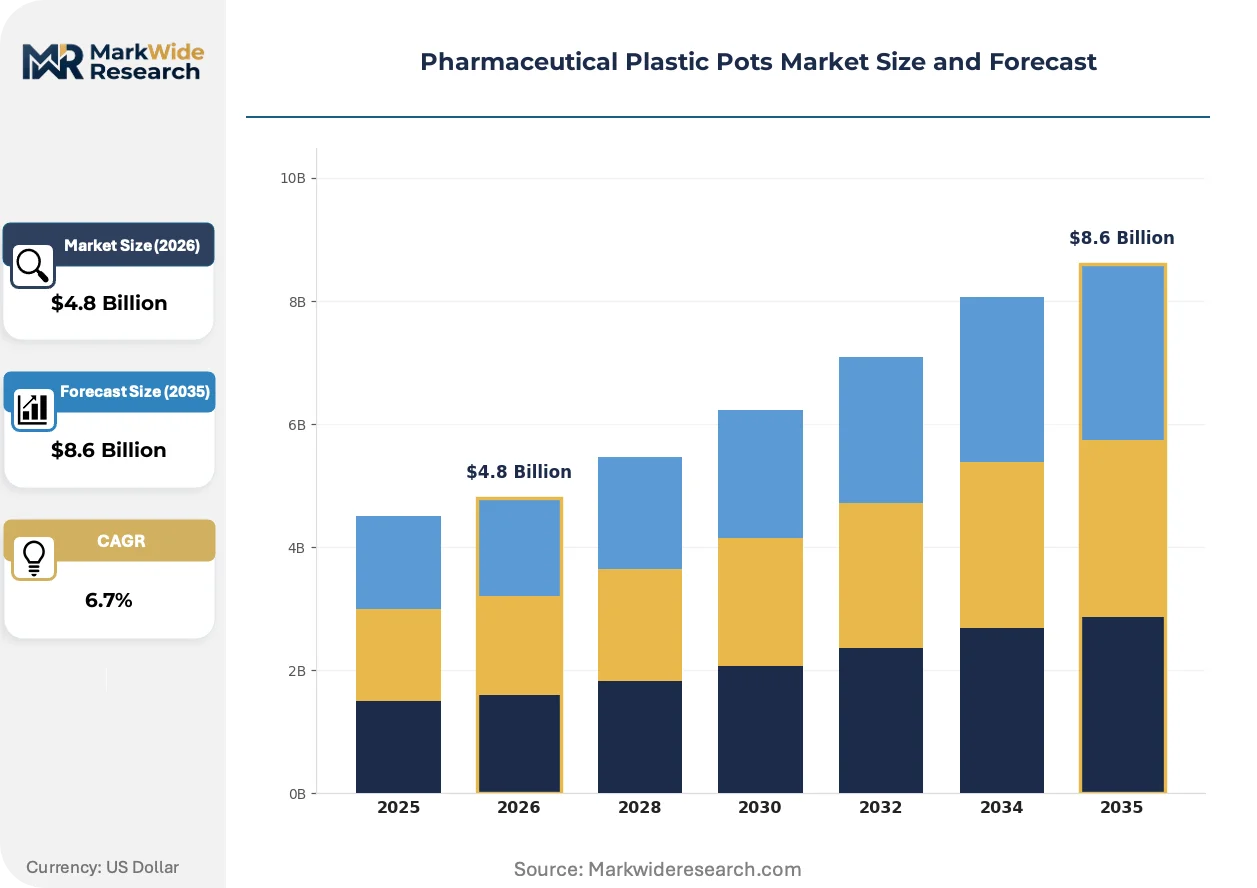
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molding, Blow Molding, Thermoforming, Extrusion Material: Polypropylene, Polyethylene, Polystyrene, PET End User: Pharmaceutical Manufacturers, Biotechnology Firms, Research Laboratories, Contract Packaging Size: Small, Medium, Large, Extra Large |
| Companies Covered | Amcor plc, Gerresheimer AG, AptarGroup, Inc., O.Berk Company, Alpha Packaging, Berry Global Inc., Comar, CKS Packaging, Drug Plastics Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Plastic Pots Market Evolving Landscape
Material science and regulatory engineering are converging to redefine barrier performance standards, with moisture vapor transmission rate specifications tightening across oral solid dose categories.
Multilayer co-injection barrier technology is bifurcating the high-performance segment from commodity polypropylene supply. Niche oncology and hormone therapy packagers are specifying ethylene vinyl alcohol and cyclic olefin copolymer interlayers at triple the unit cost of standard pots. This capability split is compressing margin pools for undifferentiated converters while anchoring premium positioning for integrated barrier specialists.
EMA Annex 1 sterile manufacturing revisions are mandating container closure integrity testing protocols that exceed historical USP <1207> guidance. Blow-fill-seal and form-fill-seal integrators must now validate seal strength distributions against statistically rigorous sampling plans. Parenteral packaging lines in Ireland and Germany are absorbing the bulk of compliance investment, with CDSCO in India signaling harmonization within eighteen months.
Direct purchasing from converter to pharmaceutical manufacturer is displacing traditional distribution intermediaries for high-volume oral solid dose programs. Tier-one contract packagers in North America are qualifying second-source molders to compress switching costs and secure capacity commitments. This channel compression is most visible among generic drug manufacturers facing formulary pricing pressure, who are consolidating supplier panels from twelve vendors to three.
Pharmaceutical Plastic Pots Market Segmentation
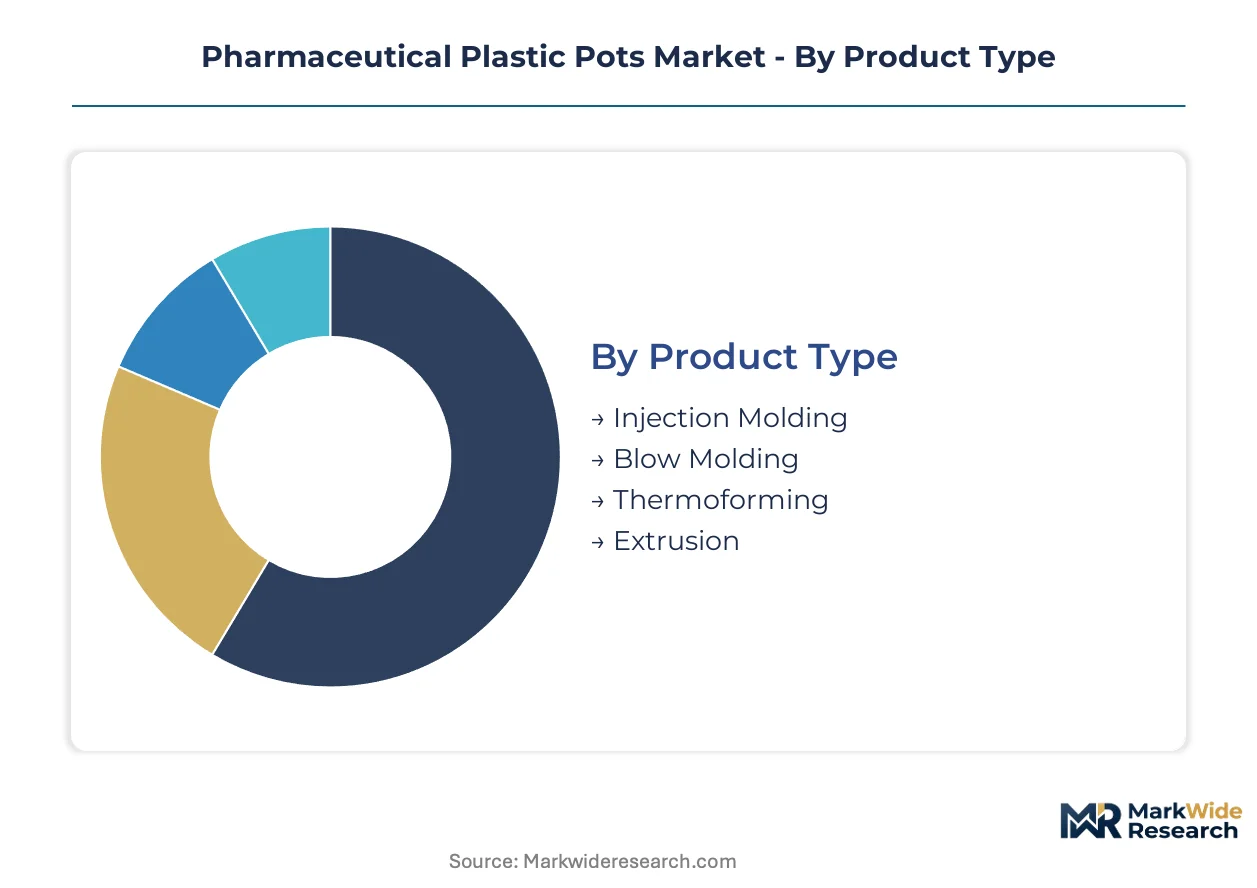
Segmentation in pharmaceutical plastic pots reveals how manufacturing technology, material science, and end-user requirements channel demand through distinct procurement pathways. Each dimension carries implications for regulatory qualification timelines, tooling investment, and margin capture.
Product Type:
Channel flow splits sharply: injection molding serves high-volume oral solid dose programs through direct converter-to-manufacturer contracts, while blow molding and thermoforming route through specialized contract packagers serving semi-solid and liquid formats.
- Injection Molding:High-pressure polymer injection into precision steel tooling yields dimensional repeatability critical for child-resistant closure engagement. Demand concentrates among generic pharmaceutical manufacturers in India and North America where FDA-registered facilities require validated mold cavitation for serialization-ready output.
- Blow Molding:Extrusion or injection blow processes form hollow containers with controlled wall thickness for moisture barrier performance. Expansion concentrates in topical cream and ointment segments where wide-mouth polypropylene pots displace aluminum tubes, particularly among European dermatology brands.
- Thermoforming:Sheet-fed vacuum and pressure forming produces shallow trays and blister-compatible pot formats. Contract packaging providers in Germany and Switzerland specify thermoformed solutions for clinical trial kits requiring rapid format changeovers.
- Extrusion:Continuous profile extrusion with secondary cutting and sealing generates low-cost cylindrical containers for powder and granule storage. Indian formulation manufacturers source extruded pots for government tender programs where unit cost dominates specification.
Injection molding dominates installed base. Blow molding is where expansion concentrates.
Material:
Cost tier stratification separates commodity polymers from barrier-enhanced formulations, with procurement patterns tracking end-use sensitivity to moisture and oxygen ingress.
- Polypropylene:Isotactic polypropylene homopolymer and random copolymer grades deliver chemical inertness, autoclave compatibility, and USP Class VI compliance. Pharmaceutical manufacturers in Maharashtra and Gujarat clusters specify polypropylene for high-volume tablet programs under India's PLI scheme incentives.
- PET:Polyethylene terephthalate offers optical clarity for product visibility and tamper-evident shrink-band compatibility. Blow-molded PET pots gain share in retail pharmacy display applications where moisture barrier enhancement justifies premium positioning over polypropylene.
- Polyethylene:HDPE and LDPE grades provide flexibility and impact resistance for cold-chain distribution. Biotechnology firms specify polyethylene for temperature-sensitive biologic adjunct packaging.
- Polystyrene:Crystal and high-impact polystyrene enable thin-wall molding for cost-sensitive diagnostic reagent containers. Research laboratories source polystyrene pots for non-sterile compound storage where barrier requirements are minimal.
Polypropylene anchors volume procurement. PET is climbing the fastest on barrier-performance premiums.
End User:
Customer-type segmentation determines validation depth, with direct pharmaceutical manufacturers requiring full extractables profiles and contract packagers accepting converter-generated stability data.
- Pharmaceutical Manufacturers:Integrated formulation and packaging operations demand lot-level traceability, mold cavity identification, and direct EPCIS serialization integration. Tier-one manufacturers in the United States and Germany consolidate supplier panels to three qualified converters.
- Contract Packaging:Third-party packagers serving multiple pharmaceutical clients require format flexibility and rapid tooling changeover. Indian contract packaging hubs in Hyderabad and Ahmedabad scale procurement of child-resistant and tamper-evident designs as oral solid dose volumes rise.
- Biotechnology Firms:Cell therapy and biologic developers specify cyclic olefin polymer and multilayer barrier pots for oxygen-sensitive formulations. EMA Annex 1 sterile manufacturing requirements drive container closure integrity testing investment.
- Research Laboratories:Preclinical and clinical trial material packaging prioritizes small-lot availability and rapid prototyping. Academic and CRO facilities source non-validated pots for investigational compound storage.
Pharmaceutical manufacturers command the largest procurement volumes. Contract packaging is gaining share fastest on outsourcing trends.
Size:
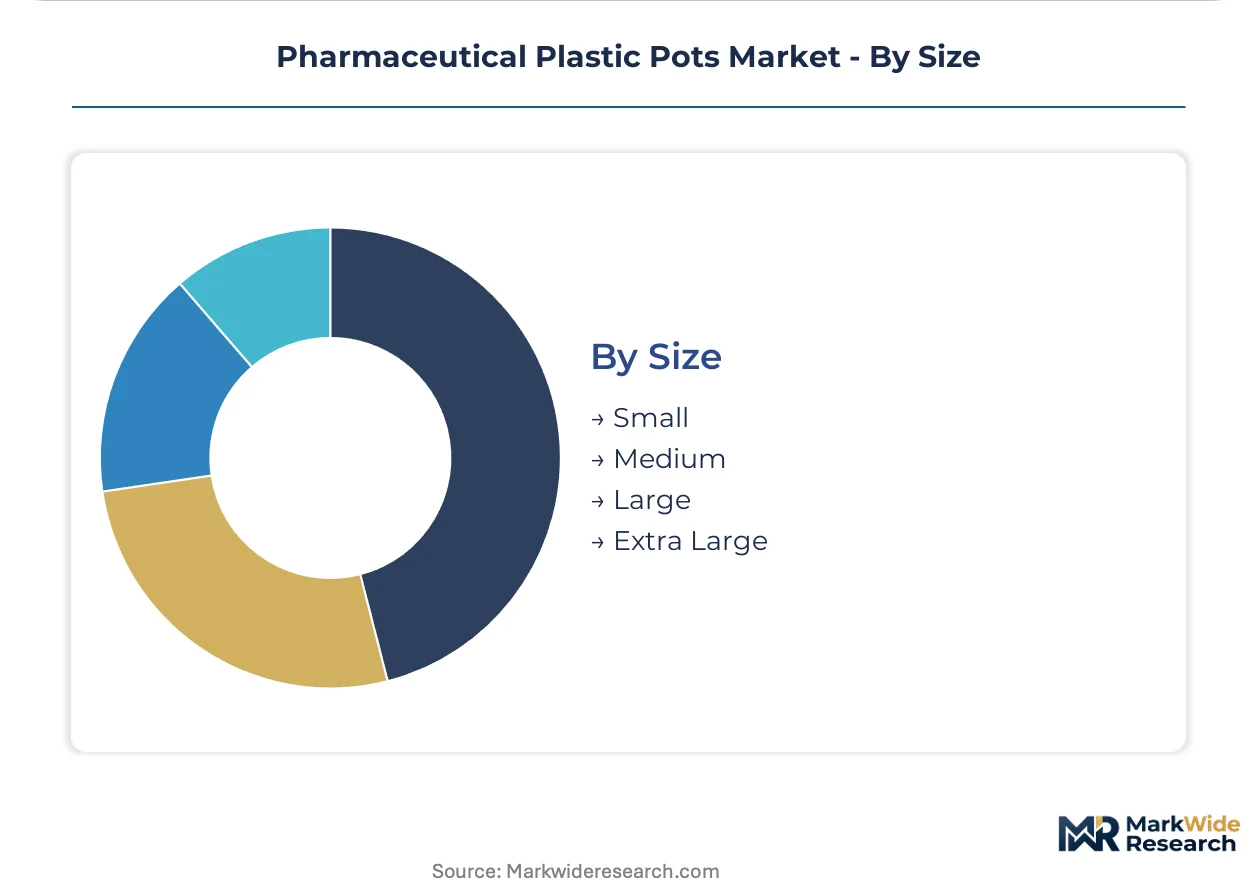
Volume-to-value ratios invert across size categories, with small pots carrying per-unit premiums for precision dosing and extra-large formats competing on throughput efficiency.
- Small:10-30 milliliter capacities serve unit-dose and sample packaging for clinical trials and physician samples. High cavity-count molds and automated vision inspection systems concentrate in Swiss and German converter facilities.
- Medium:50-150 milliliter capacities dominate chronic disease tablet and capsule programs. Indian generic manufacturers specify medium pots for 30-count and 90-count fills targeting US formulary contracts.
- Large:200-500 milliliter capacities support hospital and institutional packaging for high-volume antibiotic and analgesic formulations. Blow molding capacity for large pots expands in China to serve domestic hospital procurement.
- Extra Large:750 milliliter and above capacities address bulk powder and granule storage for compounding pharmacies and veterinary applications. Limited converter availability concentrates supply among North American specialists.
Medium sizes dominate current procurement. Small formats are expanding most quickly on clinical trial outsourcing growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in pharmaceutical plastic pots reveal concentrated supply from injection-molding specialists in Germany and India serving formulation manufacturers across North America and Europe. Trade flows track regulatory qualification timelines, with FDA-registered converters commanding freight premiums for serialized container shipments.
United States
Generic drug manufacturers in New Jersey and Pennsylvania drive procurement of child-resistant polypropylene pots for 90-count chronic disease formulations. FDA cGMP guidelines mandate container closure integrity testing that extends supplier qualification cycles. Indianapolis hosts contract packaging hubs scaling serialization-ready capacity for track-and-trace compliance.
Germany
EMA serialization deadlines are forcing wholesale packaging upgrades among Rhine-Main pharmaceutical manufacturers. EMA Annex 1 sterile manufacturing revisions mandate statistically rigorous seal strength validation. Heidelberg and Mannheim clusters concentrate blow-fill-seal integrators serving parenteral packaging lines.
India
Domestic formulation manufacturing and PLI scheme incentives are expanding local packaging demand in Maharashtra and Gujarat. CDSCO signals harmonization with ICH Q3D elemental impurity guidelines within eighteen months. Hyderabad and Ahmedabad contract packaging hubs scale procurement of tamper-evident designs as oral solid dose volumes rise.
China
Hospital procurement expansion for large-format antibiotic containers is driving blow-molding capacity investment. NMPA pharmacopoeia updates are accelerating supplier consolidation around extractables-compliant converters. Yangtze River Delta manufacturing zones concentrate extrusion specialists serving government tender programs.
Switzerland
Swissmedic oversight of clinical trial material packaging prioritizes small-lot precision dosing pots with rapid format changeover. Basel-area biotechnology firms specify cyclic olefin polymer barriers for oxygen-sensitive biologics. Swiss converter facilities maintain high cavity-count molds with automated vision inspection for 10-30 milliliter clinical sample formats.
Pharmaceutical Plastic Pots Market Competitive Landscape
Listed leaders compete with private specialists across regulatory qualification depth, with publicly traded packaging conglomerates leveraging FDA-registered facility networks against nimble private molders serving regional pharmaceutical clusters. Market structure tilts toward consolidation at the premium barrier tier while commodity polypropylene supply fragments across mid-scale Indian and Chinese converters. Three archetypes dominate: integrated barrier specialists commanding triple-unit-cost premiums, volume-scale injection molders competing on cavitation flexibility, and regional contract packaging affiliates capturing local regulatory proximity. Competitive moves center on second-source qualification partnerships and in-mold desiccant technology licensing.
Among Germany-based specialists, Gerresheimer AG occupies a position exemplifying glass-to-plastic conversion expertise for moisture-sensitive formulations. Berry Global Inc. anchors the North American volume-flexibility tier with manufacturing scale across multiple FDA-registered facilities. Amcor plc represents the integrated multinational archetype with converter-to-manufacturer direct purchasing relationships spanning serialized container programs.
| Leading Market Players |
|---|
| Amcor plc |
| Gerresheimer AG |
| AptarGroup, Inc. |
| O.Berk Company |
| Alpha Packaging |
| Berry Global Inc. |
| Comar |
| CKS Packaging |
| Drug Plastics Group |
| Others |
Value Network & Pricing Analysis
FDA cGMP and EMA Annex 1 sterile manufacturing requirements gate both supplier qualification timelines and price differentiation simultaneously, compressing margin pools for non-compliant converters while anchoring premium positioning for validated molders with serialization-ready capacity.
Pricing Analysis
Pharmaceutical manufacturers anchor contract-based long-term offtake pricing for injection-molded polypropylene pots, with price differentiation tracking FDA registration tier and mold cavitation scale. Three-tier pricing structure across premium barrier-enhanced, standard USP Class VI compliant, and economy extruded formats separates multilayer co-injection specialists from commodity converters. Cost compression in the economy tier is intensifying because Indian government tender programs prioritize unit cost over validation depth. Generic drug manufacturers in North America exhibit highest price sensitivity, while biotechnology firms sourcing cyclic olefin polymer barriers demonstrate lowest sensitivity due to oxygen-ingress specifications.
Supply Chain Analysis
Single-source FDA-registered tooling in Germany and Switzerland underwrites supply security for precision mold fabrication, extending qualification timelines for new market entrants. Raw material supply draws from propylene feedstock concentrations in the US Gulf Coast, Middle Eastern naphtha crackers, and Indian petrochemical complexes. Distribution runs through direct converter-to-manufacturer channels for high-volume oral solid dose programs, displacing traditional pharmaceutical packaging distributors. Tariff exposure on precision steel tooling imports from European suppliers poses structural risk for North American generic manufacturers consolidating supplier panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical plastic pots demand is recovering cyclically as oral solid dose production runs expand with chronic disease prevalence, pulling capacity utilization rates upward across FDA-registered molding facilities.
For Market Incumbents: Secure second-source qualification partnerships with Indian contract packaging hubs in Hyderabad and Ahmedabad to defend against emerging regional converter competition. Invest in in-mold desiccant technology licensing to differentiate from commodity polypropylene suppliers facing margin compression. Capacity addition in Maharashtra and Gujarat clusters anchors proximity to PLI scheme formulation manufacturing expansion. For New Entrants and Emerging Players: Lead with small-format clinical trial packaging for Swiss and German biotechnology firms, where rapid format changeover capabilities and high cavity-count molds penetrate fastest. Target research laboratory segments with non-validated polystyrene pots for preclinical compound storage, where regulatory qualification barriers are lowest. Partner with academic CRO facilities for investigational material packaging contracts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multilayer barrier technology segments, favoring acquisition targets with integrated co-injection capabilities and existing EMA serialization compliance. Focus on mid-scale European specialists with glass-to-plastic conversion expertise and established pharmaceutical manufacturer direct purchasing relationships. Monitor CDSCO harmonization signals with ICH Q3D guidelines as inflection indicator for Indian supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| In-Mold Desiccant Technology Licensing | Eliminates secondary sachet insertion for moisture-sensitive formulations at Gerresheimer and Berry Global scale. |
| Second-Source Qualification Partnerships | Compresses switching costs for generic manufacturers consolidating supplier panels from twelve vendors to three. |
| PLI Scheme Proximity Expansion | Positions capacity within Maharashtra and Gujarat clusters capturing government-backed formulation manufacturing growth. |
| Serialization Equipment Retrofitting | Enables EPCIS integration for FDA track-and-trace compliance at Indianapolis contract packaging hubs. |
| Multilayer Barrier R&D Investment | Develops ethylene vinyl alcohol interlayers for oncology and hormone therapy packagers at triple-unit-cost premiums. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 483 inspection observations, EMA marketing authorization submissions, and USP <661> extractables guidance documents, combining interviews with pharmaceutical packaging procurement directors, contract packaging operations managers, and regulatory affairs leads with customs trade data and SEC 10-K filings from listed packaging conglomerates. Bottom-up triangulation across injection molding capacity utilization rates and top-down validation against oral solid dose production forecasts anchor quantitative outputs.
Segmentation dimensions modeled span manufacturing technology, material grade tier, end-user type, and size category across the analysis window, with CAGRs derived from curve-fitting historical procurement volumes against projected formulation manufacturing expansion. Forecast inputs incorporate PLI scheme incentive disbursement trajectories and CDSCO harmonization timelines with ICH Q3D elemental impurity guidelines.
Forecasts assume regulatory continuity in FDA cGMP and EMA Annex 1 sterile manufacturing regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as polypropylene resin volatility and single-source tooling concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
China Pharmaceutical Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Materials Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Recycled Prescription Bag Market
Pharmaceutical Packaging
Vaccine Shippers Market
Pharmaceutical Packaging
Tablet Bottle Market
Pharmaceutical Packaging
Clinical Trial Packaging Market
Pharmaceutical Packaging
Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment Market
Pharmaceutical Packaging
Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Pharmacy Repackaging Systems Market
Pharmaceutical Packaging
Pharma Packaging Films Market
Pharmaceutical Packaging
Plastic Pharma Tray Market
Pharmaceutical Packaging
Global Parenteral Packaging Market
Pharmaceutical Packaging
APAC Pharmaceutical Packaging Market