
 Reefer Container for Pharmaceutical Market | 2026-2036
Reefer Container for Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Reefer Container for Pharmaceutical Market Analytics
Asian container manufacturing is shifting toward pharmaceutical-grade certification as quality thresholds harden. A.P. Moller - Maersk leverages its integrated logistics network to control end-to-end temperature integrity across trade lanes. Carrier Transicold anchors the equipment supply layer through deep specialization in precision cooling systems. Thermo King competes on energy efficiency metrics that directly reduce landed cost per shipment for drug distributors.
A reefer container for pharmaceutical use is an insulated shipping unit equipped with active refrigeration or advanced phase-change materials to maintain temperatures between minus 80 degrees Celsius and plus 25 degrees Celsius, protecting biologics, vaccines, and cell therapies from thermal degradation during multimodal transport. The product type dimension shows containers commanding the core volume base while modular units capture the fastest expansion as pharmaceutical companies seek flexible capacity for clinical trial material. Temperature range segmentation reveals controlled-environment units carrying the deepest margin pools due to validation complexity and regulatory audit requirements.
FDA enforcement of the Drug Supply Chain Security Act elevates documentation burdens for all inbound pharmaceutical shipments to United States ports. The EU's Good Distribution Practice guidelines mandate continuous temperature monitoring with alarm protocols, forcing equipment upgrades across European trade lanes. Stakeholders must monitor evolving pharmacopeial standards in major import markets to anticipate retrofit cycles and compliance-driven replacement demand.
Market Dynamics
Biologics manufacturers are consolidating cold-chain procurement around end-to-end temperature integrity guarantees, forcing equipment suppliers to absorb validation liability and integrate real-time monitoring as standard rather than premium features.
Growth Catalysts
- EU Good Distribution Practice:Continuous temperature monitoring mandates across European trade lanes accelerate equipment replacement cycles and retrofit demand for existing container fleets.
- mRNA vaccine platforms:Ultra-low temperature requirements for lipid nanoparticle formulations expand the addressable market for minus 80 degrees Celsius capable units beyond traditional biologics.
- Cell therapy commercialization:Chimeric antigen receptor T-cell therapies require cryogenic chain-of-custody protocols that standard cold-chain infrastructure cannot satisfy.
Market Restraints
- Specialized compressor supply:Precision cooling system manufacturing concentrates among a limited set of European and Japanese component suppliers, creating input bottlenecks during demand surges.
- Validation cost inflation:FDA Drug Supply Chain Security Act documentation requirements add non-recurring engineering costs that disproportionately burden smaller pharmaceutical distributors.
- Phase-change material limitations:Current salt-hydrate and paraffin formulations lack the thermal stability duration required for extended ocean freight without active refrigeration backup.
Strategic Opportunities
- Indian pharmaceutical exports:CDSCO alignment with WHO prequalification standards positions Indian generic injectable manufacturers as volume buyers of certified reefer capacity.
- Gene therapy logistics:Adeno-associated virus vector shipments require controlled-rate freezing capabilities that most existing container fleets lack, creating premium service tiers.
- Blockchain documentation:Immutable temperature records integrated with customs clearance systems reduce port dwell time and insurance premiums for high-value biologics shipments.
Industry Challenges
- Calibration technician scarcity:Qualified personnel for IQ/OQ/PQ validation protocols command wage premiums that erode service margin at third-party logistics providers.
- Legacy fleet retrofit complexity:Older container architectures cannot accommodate the sensor density and connectivity modules required for real-time GDP compliance without structural reinforcement.
- Cross-border protocol harmonization:Divergent national pharmacopeial standards between FDA, EMA, and PMDA jurisdictions force redundant testing and documentation for multi-market product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reefer Container for Pharmaceutical Market |
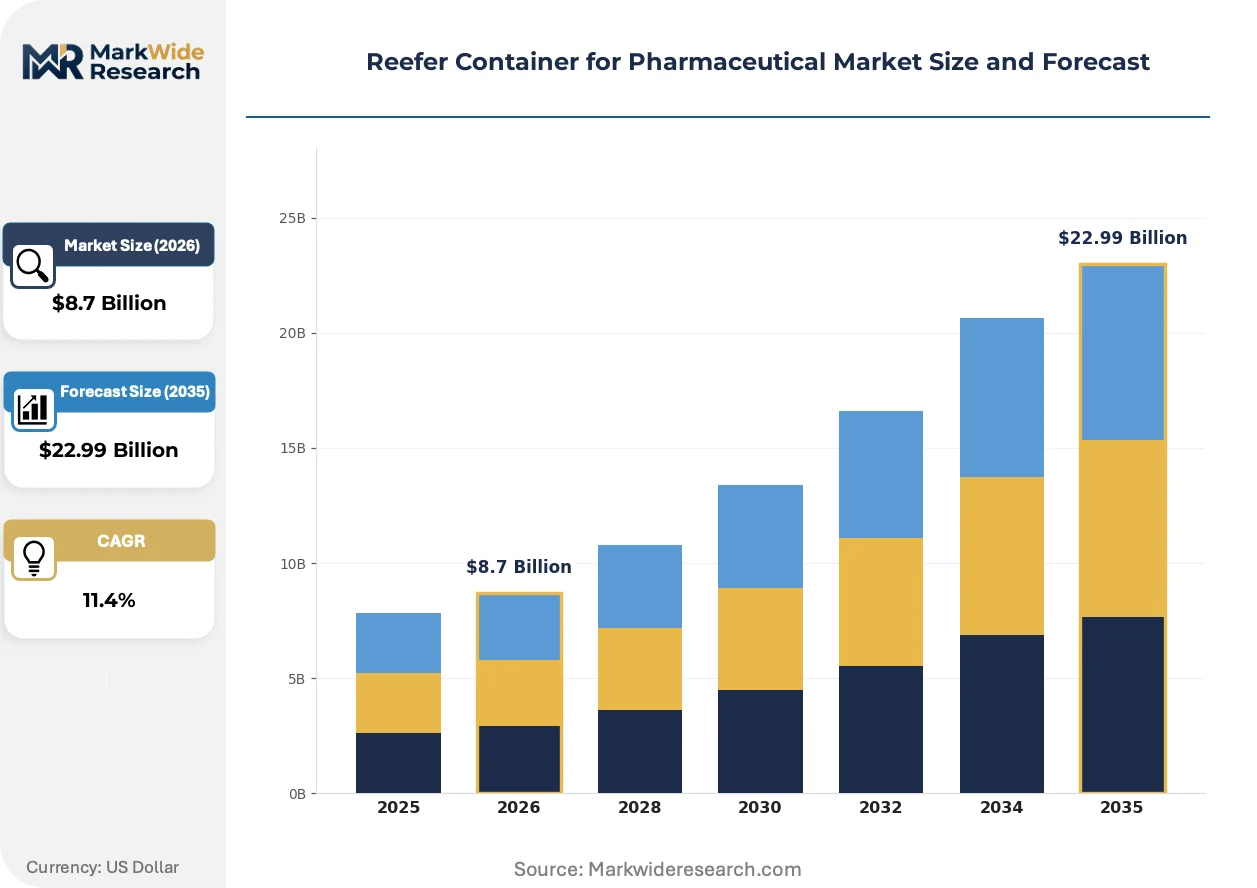
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containers, Pallets, Modular Units, Totes End User: Pharmaceutical Companies, Distributors, Hospitals, Clinics Temperature Range: Chilled, Ambient, Frozen, Controlled Material: Plastic, Composite, Steel, Aluminum |
| Companies Covered | A.P. Moller - Maersk, CMA CGM Group, MSC Mediterranean Shipping Company, COSCO SHIPPING, Evergreen Marine Corporation, Hapag-Lloyd AG, Carrier Transicold, Thermo King, Klinge Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reefer Container for Pharmaceutical Market Evolving Landscape
Active thermal management systems are converging with digital traceability platforms to create closed-loop cold-chain ecosystems where equipment performance data directly feeds regulatory audit trails.
Advanced phase-change material composites incorporating graphene-enhanced thermal conductivity are unifying passive and active cooling approaches into hybrid containers that maintain temperature setpoints for 240 hours without external power. Gene therapy developers are specifying these units for clinical trial material shipments to remote investigator sites. The technology is unifying previously separate procurement categories of passive shippers and active reefers into single-platform decisions.
EU F-Gas Regulation restrictions on hydrofluorocarbon refrigerants are forcing equipment redesigns toward natural refrigerant alternatives with lower global warming potential. Container manufacturers must recertify cooling systems under new environmental performance thresholds. European trade lanes show the fastest adoption of CO2-based transcritical refrigeration systems as fleet replacement accelerates ahead of 2030 phase-down targets.
Pharmaceutical distributors are consolidating vendor relationships around integrated logistics providers that bundle equipment, monitoring, and customs brokerage into single-contract arrangements. This procurement consolidation displaces fragmented spot-market container leasing for high-value biologics. German pharmaceutical corridors around Frankfurt demonstrate the most advanced buyer concentration, with three major distributors controlling the majority of certified reefer capacity in the region.
Reefer Container for Pharmaceutical Market Segmentation
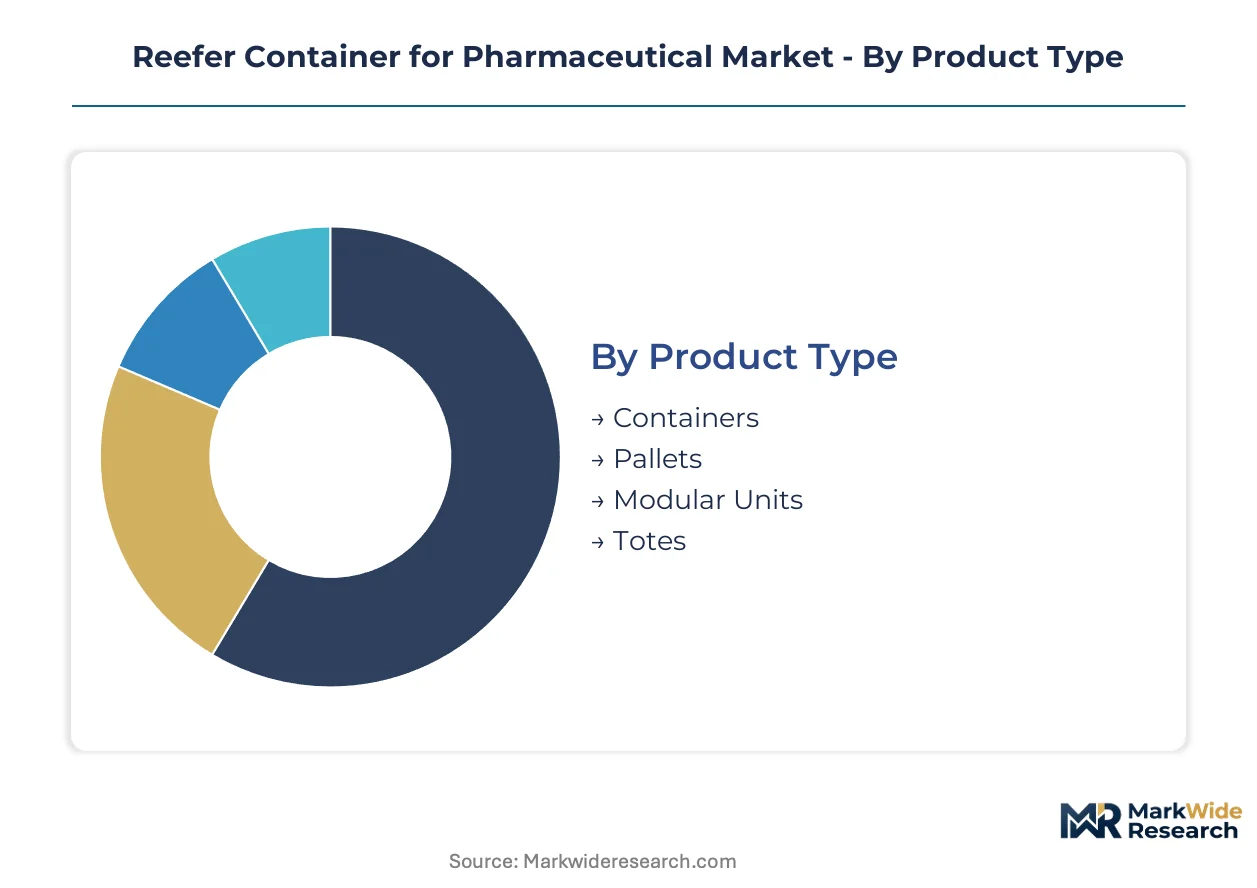
Pharmaceutical cold-chain procurement divides sharply between asset-heavy container ownership and flexible pallet-based models. Each segment carries distinct validation burdens, capital intensity profiles, and regulatory documentation requirements that shape supplier relationships.
Product Type:
Buyers differentiate primarily by shipment scale and frequency of need, with high-volume manufacturers favoring owned assets while clinical trial operators prioritize rental flexibility.
- Containers:Standardized 20-foot and 40-foot insulated units with integrated refrigeration systems form the backbone of intermodal pharmaceutical transport. Biologics manufacturers in Germany's Frankfurt corridor deploy these for recurring high-volume lanes where amortization justifies capital deployment against per-shipment leasing costs.
- Modular Units:Configurable cold-chain compartments adapt to varying payload dimensions without full container commitment. Gene therapy developers specify these for investigator-site shipments where batch sizes fluctuate and rapid reconfiguration outweighs unit cost premiums.
- Pallets:Single-use or limited-reuse passive thermal platforms protect palletized pharmaceutical cargo within standard dry containers. Generic injectable exporters from India leverage these for cost-sensitive volume lanes where GDP compliance must balance against freight economics.
- Totes:Hand-portable insulated containers serve last-mile distribution from airport cargo terminals to hospital pharmacies. Cell therapy logistics providers specify these for cryogenic chain-of-custody handoffs where payload value exceeds equipment cost by orders of magnitude.
Containers lead volumes today; modular units are gaining share fastest.
End User:
Procurement sophistication varies dramatically across buyer types, with large pharmaceutical companies demanding end-to-end temperature integrity guarantees that smaller clinical sites cannot specify.
- Pharmaceutical Companies:Originators and generic manufacturers with internal cold-chain engineering teams specify equipment performance parameters directly. mRNA vaccine producers negotiate validation liability transfer to equipment suppliers as contract standard.
- Distributors:Third-party logistics providers aggregate demand across multiple pharmaceutical clients and standardize on interoperable container fleets. German pharmaceutical corridors demonstrate the most advanced distributor consolidation, with regional players controlling certified reefer capacity through long-term equipment leases.
- Hospitals:Receiving institutions specify inbound container requirements for direct-to-site deliveries of temperature-sensitive therapeutics. Academic medical centers with cell therapy programs impose cryogenic handling protocols that exceed standard hospital pharmacy capabilities.
- Clinics:Outpatient and specialty care sites represent fragmented demand with limited cold-chain infrastructure. Remote investigator sites for decentralized clinical trials drive demand for extended-duration passive thermal protection where active refrigeration is unavailable.
Pharmaceutical companies dominate current procurement; distributors are climbing the fastest as outsourcing accelerates.
Temperature Range:
Validation complexity and regulatory audit intensity escalate nonlinearly as temperature setpoints deviate from ambient, creating steep margin differentiation across thermal categories.
- Controlled:Tight-tolerance environments between 2°C and 8°C protect the majority of small-molecule and protein-based pharmaceuticals. This segment carries the deepest margin pools due to GDP-mandated continuous monitoring and alarm protocol requirements.
- Frozen:Minus 20°C to minus 40°C setpoints serve vaccine bulk storage and certain biologic intermediates. Lipid nanoparticle formulations for mRNA platforms have expanded frozen infrastructure demand beyond traditional biologics applications.
- Chilled:8°C to 15°C bands accommodate less temperature-sensitive pharmaceuticals and certain diagnostic reagents. This segment faces commoditization pressure as passive phase-change materials encroach on active refrigeration economics.
- Ambient:15°C to 25°C controlled environments protect heat-sensitive pharmaceuticals in tropical trade lanes. WHO prequalification standards for generic medicines drive certification requirements even for this nominally permissive range.
Controlled-environment units command the highest margins today; frozen-capable systems show steepest expansion trajectory.
Material:
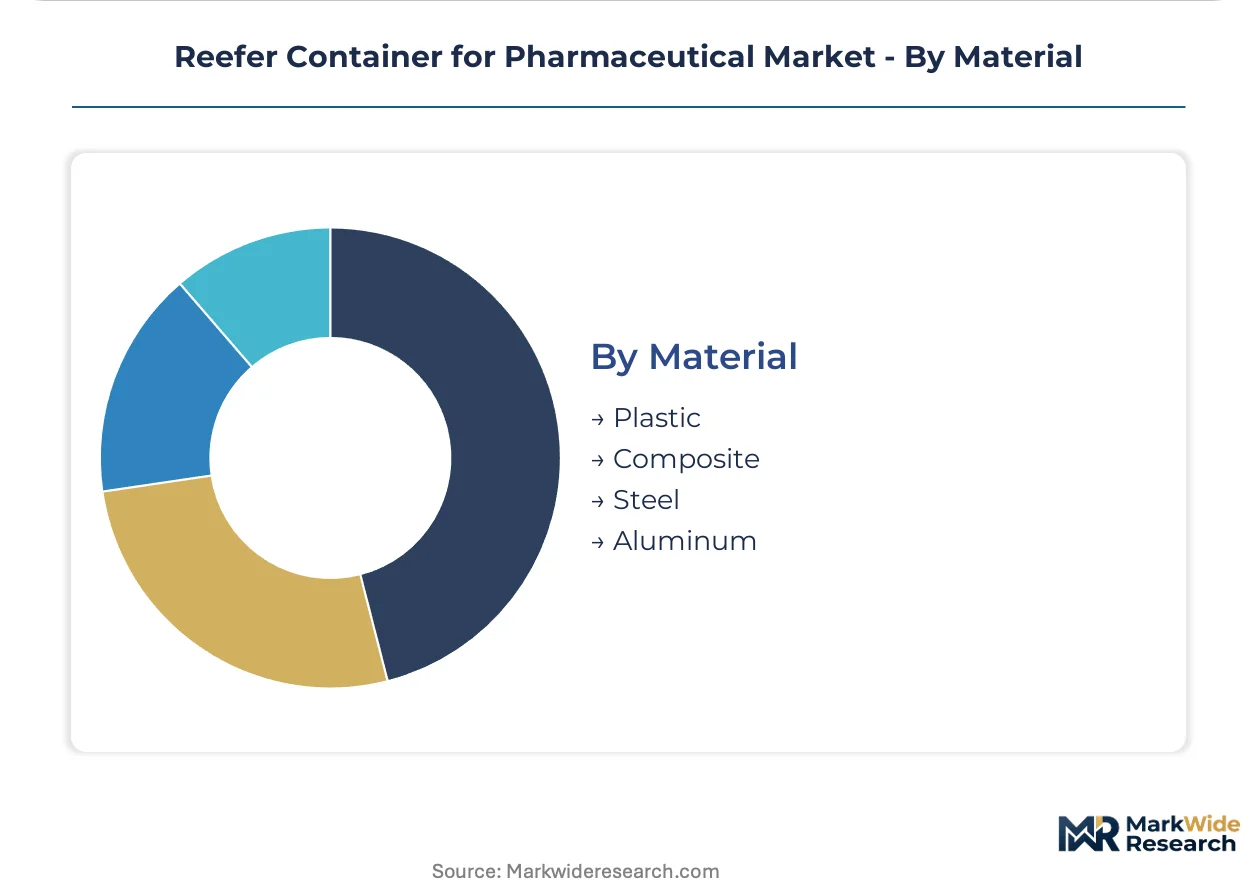
Weight, thermal conductivity, and recyclability tradeoffs drive material selection, with sustainability pressures from EU F-Gas Regulation extending into container construction choices.
- Composite:Fiber-reinforced polymer constructions optimize strength-to-weight ratios for air freight applications. These materials enable sensor integration and connectivity modules that GDP compliance demands.
- Plastic:Rotationally molded polyethylene dominates single-use and limited-reuse tote and pallet segments. Cost sensitivity in Indian pharmaceutical exports sustains demand despite recyclability limitations.
- Steel:Corrosion-resistant alloys provide structural durability for long-haul ocean freight containers. Legacy fleet architectures rely on steel reinforcement that complicates retrofit for real-time monitoring density.
- Aluminum:Lightweight metal constructions reduce tare weight for air cargo applications where payload optimization directly reduces landed cost. Premium biologics shipments absorb material cost premiums for weight savings.
Composites lead technology investment today; aluminum is expanding most quickly in air freight lanes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pharmaceutical corridor around Frankfurt commands deeper reefer container penetration than India's emerging generic injectable export hubs, though both markets face divergent regulatory compliance timelines.
United States
FDA enforcement of the Drug Supply Chain Security Act elevates documentation burdens for inbound pharmaceutical shipments at major ports. The agency mandates serialization and track-and-trace protocols that force equipment upgrades across container fleets. Boston's biotech cluster drives demand for cryogenic-capable units as cell therapy developers commercialize CAR-T platforms.
Germany
The EU's Good Distribution Practice guidelines mandate continuous temperature monitoring with alarm protocols across European trade lanes. The F-Gas Regulation accelerates fleet replacement toward CO2-based transcritical refrigeration systems ahead of 2030 phase-down targets. The Frankfurt-Ludwigshafen pharmaceutical corridor concentrates certified reefer capacity among three major distributors controlling regional cold-chain infrastructure.
India
CDSCO alignment with WHO prequalification standards positions Indian generic injectable manufacturers as volume buyers of certified reefer capacity. The country's pharmaceutical exports to regulated markets demand GDP-compliant documentation that domestic logistics providers are racing to meet. Maharashtra's API-to-formulation manufacturing belt around Mumbai and Pune anchors outbound cold-chain investment.
Japan
PMDA pharmacopeial standards for biologics distribution enforce stringent validation protocols that exceed baseline international requirements. METI industrial policy supports domestic reefer manufacturing capacity to reduce import dependence for precision cooling components. The Kansai region's pharmaceutical production cluster around Osaka drives demand for modular cold-chain units adaptable to clinical trial material shipments.
China
NMPA biologics licensing reforms accelerate domestic cold-chain infrastructure buildout for gene therapy and mRNA vaccine production. The country's dual carbon goals pressure equipment suppliers toward natural refrigerant alternatives in new container designs. The Yangtze River Delta biopharmaceutical manufacturing zone around Shanghai concentrates demand for ultra-low temperature storage and transport capabilities.
Reefer Container for Pharmaceutical Market Competitive Landscape
European equipment specialists anchor one tier; Asian integrated logistics providers hold the service-integrated segment. The market structures around three distinct competitive layers: precision cooling system fabricators, container manufacturing operations, and end-to-end logistics operators bundling equipment with monitoring and customs services. Strategic differentiation concentrates on validation liability absorption, real-time temperature traceability integration, and natural refrigerant compliance ahead of environmental regulatory deadlines. Consolidation pressures favor operators with captive equipment supply and multi-modal network density.
Among integrated logistics providers, A.P. Moller - Maersk exemplifies the end-to-end temperature integrity model, while Carrier Transicold and Thermo King occupy foundational positions in precision cooling system supply. These three names represent the archetypal split between service integration and equipment specialization that defines competitive positioning across pharmaceutical cold-chain procurement.
| Leading Market Players |
|---|
| A.P. Moller - Maersk |
| CMA CGM Group |
| MSC Mediterranean Shipping Company |
| COSCO SHIPPING |
| Evergreen Marine Corporation |
| Hapag-Lloyd AG |
| Carrier Transicold |
| Thermo King |
| Klinge Corporation |
| Others |
Value Network & Pricing Analysis
Integrated logistics providers rolled up through private-equity consolidation now control certified reefer capacity across Germany's Frankfurt-Ludwigshafen corridor, translating fleet concentration into pricing discipline that smaller pharmaceutical distributors cannot match.
Pricing Analysis
Capacity additions in China's Yangtze River Delta biopharmaceutical zone are reshaping price floors for standard controlled-environment units. Three-tier pricing structure across GDP-validated premium, ISO-standard mid-tier, and economy pallet-based segments separates validation liability absorption from basic equipment rental. Cost compression in the mid-tier is intensifying because Indian generic injectable exporters negotiate volume offtakes that undercut European fleet rates. Clinical trial operators show least price sensitivity due to payload value concentration, while commodity vaccine shippers drive hardest bargain on per-lane economics.
Supply Chain Analysis
Freight cost volatility on Asia-Europe lanes feeds directly into landed equipment pricing for pharmaceutical distributors. Precision cooling component manufacturing centers on Germany, Japan, and South Korea, with compressor supply resting on a limited supplier base. Steel and aluminum hull fabrication draws from Chinese and South Korean shipyards. Single-source vulnerability in specialized compressor supply creates bottleneck risk during demand surges. Distribution runs through integrated logistics providers bundling equipment, monitoring, and customs brokerage into single-contract arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in pharmaceutical cold-chain equipment hinges on premium-tier shift toward ultra-low temperature gene therapy logistics, where validation complexity supports pricing power unavailable in commoditized standard cold-chain segments.
For Market Incumbents: Acquire modular cold-chain unit specialists serving decentralized clinical trial networks. Backward integration into precision cooling compressor supply insulates against input bottlenecks from Japanese and European component suppliers. Lock in long-term validation liability transfer contracts with mRNA vaccine producers before generic competition erodes premium tiers.
For New Entrants and Emerging Players: Launch via blockchain-integrated temperature documentation platforms targeting Indian generic injectable exporters racing to meet WHO prequalification standards. Penetrate the cryogenic chain-of-custody gap for cell therapy investigator sites in secondary cities lacking active refrigeration infrastructure. Position around calibration technician scarcity by building IQ/OQ/PQ validation service capabilities as differentiated attachment.
For Investors and Strategic Acquirers: Valuations sit cheapest among equipment-specialist fabricators without captive logistics networks, where technology differentiation is underpriced against integrated provider multiples. Five-to-ten year viability favors operators with natural refrigerant compliance locked in ahead of EU F-Gas Regulation deadlines. Watch CDSCO enforcement timelines in India as inflection signal for certified capacity demand surge.
| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Fleet Conversion | CO2-based transcritical systems satisfy EU F-Gas Regulation ahead of 2030 phase-down targets. |
| Blockchain Temperature Documentation Integration | Immutable records reduce port dwell time and insurance premiums for high-value biologics shipments. |
| Calibration Technician Training Programs | IQ/OQ/PQ validation capability scarcity commands wage premiums that erode third-party logistics margins. |
| Modular Unit Configuration Platforms | Gene therapy developers specify rapid-reconfiguration compartments for fluctuating clinical trial batch sizes. |
| Ultra-Low Temperature Validation Partnerships | Minus 80 degrees Celsius capable units expand addressable market beyond traditional biologics into mRNA platforms. |
Research Methodology
Multiple input streams — structured interviews with cold-chain engineering directors, regulatory affairs leads at biologics manufacturers, and third-party logistics procurement managers — were reconciled against customs trade data, FDA DSCSA enforcement records, EMA GDP inspection reports, and container fleet utilization disclosures. Bottom-up equipment deployment estimates triangulated with top-down pharmaceutical export value flows.
Segment-level projections across product type, temperature range, end-user category, and material composition were modeled throughout the forecast period. CAGRs derived from equipment replacement cycle analysis, regulatory retrofit demand timing, and biologics pipeline commercialization schedules. Gene therapy logistics requirements and mRNA vaccine platform expansion served as primary demand-side inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated EU F-Gas Regulation enforcement or sudden compressor supply disruption. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Europe Pharmaceutical Glass Packaging Market
Pharmaceutical Packaging
North America Ampoules Packaging Market
Pharmaceutical Packaging
Parenteral Drugs Packaging Market
Pharmaceutical Packaging
Tablets and Capsules Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
United States Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Serum Bottles Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Pharmaceutical Printed Cartons Market
Pharmaceutical Packaging
Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment Market
Pharmaceutical Packaging
Global Ampoules Packaging Market
Pharmaceutical Packaging
Global Pharmaceutical Processing Seals Market
Pharmaceutical Packaging
North America Pharmaceutical Vials Market
Pharmaceutical Packaging
Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Global Parenteral Packaging Market
Pharmaceutical Packaging
Injection Bottles Market